
 Variable Displacement Compressor Market | 2026-2036
Variable Displacement Compressor Market Size, Share, and Industry Trends Forecast 2026-2036
Variable Displacement Compressor Market Analytics
Chinese compressor foundries is repositioning output toward variable-speed scroll architectures for EV battery cooling. Denso Corporation leverages its Toyota supply heritage to dominate Japanese OEM thermal contracts. MAHLE anchors European aftermarket distribution through its Stuttgart engineering base. Hanon Systems competes in Korean and North American electric vehicle programs with dedicated HVAC module integration.
A variable displacement compressor modulates refrigerant mass flow without cycling the clutch, using swash-plate angle adjustment or scroll orbit variation to match cooling load from partial to full capacity. Scroll compressors with electronic control sustain the fastest expansion as precision thermal management becomes critical for lithium-ion battery packs in electric vehicles. Mechanical control reciprocating units still occupy substantial replacement demand in legacy commercial refrigeration, though margin pools are shifting toward hybrid control systems that bridge cost and efficiency requirements.
EPA SNAP regulations restrict high-GWP refrigerants in US automotive and stationary applications, forcing compressor redesigns for lower-charge systems. EU F-Gas Regulation and CE marking under the Machinery Directive shape product standards and market access for European suppliers. China's GB standards and MIIT efficiency mandates drive domestic certification requirements. Stakeholders must monitor refrigerant chemistry transitions and electric vehicle platform thermal architectures to align R&D commitments with emerging compliance thresholds.
Market Dynamics
Electric vehicle thermal architectures are forcing compressor suppliers to abandon fixed-displacement designs in favor of continuously variable refrigerant modulation systems that protect lithium-ion battery packs from thermal runaway.
Growth Catalysts
- EPA refrigerant phase-down mandates:US automotive OEMs must adopt lower-GWP refrigerants requiring compressor redesigns that favor variable-capacity modulation over clutch cycling.
- China's dual carbon goals:MIIT efficiency mandates accelerate domestic EV adoption, creating concentrated demand for precision thermal management in battery cooling loops.
- Scroll orbit variation technology:Electronic control systems enable real-time capacity matching that extends compressor life and reduces energy consumption in hybrid vehicle HVAC modules.
Market Restraints
- Copper and rare-earth magnet costs:Permanent magnet motors in electronically controlled units face input price volatility that compresses margin pools for mid-tier suppliers.
- East Asian foundry concentration:Precision casting capacity for swash-plate housings clusters in Chinese manufacturing zones, creating geographic supply risk for European and North American assemblers.
- Mechanical control legacy compatibility:Commercial refrigeration replacement demand sustains reciprocating compressor volumes that cannibalize R&D investment toward electronic variable-speed platforms.
Strategic Opportunities
- Indian EV manufacturing scale-up:PLI scheme incentives for domestic automotive production create virgin demand for locally sourced variable-displacement thermal modules.
- EU F-Gas Regulation tightening:Lower charge requirements for R-1234yf systems favor compact variable-displacement designs that minimize refrigerant inventory.
- Vehicle-to-grid thermal preconditioning:Bidirectional power flows enable compressor operation during charging cycles, expanding addressable duty cycles beyond traditional engine-driven architectures.
Industry Challenges
- Embedded software certification:ISO 26262 functional safety validation for compressor motor controllers extends development timelines and requires specialized automotive electronics talent.
- Legacy HVAC module retrofit complexity:Aftermarket installers face integration friction when mating electronic variable-speed units to mechanical control refrigerant circuits designed for clutch cycling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Variable Displacement Compressor Market |
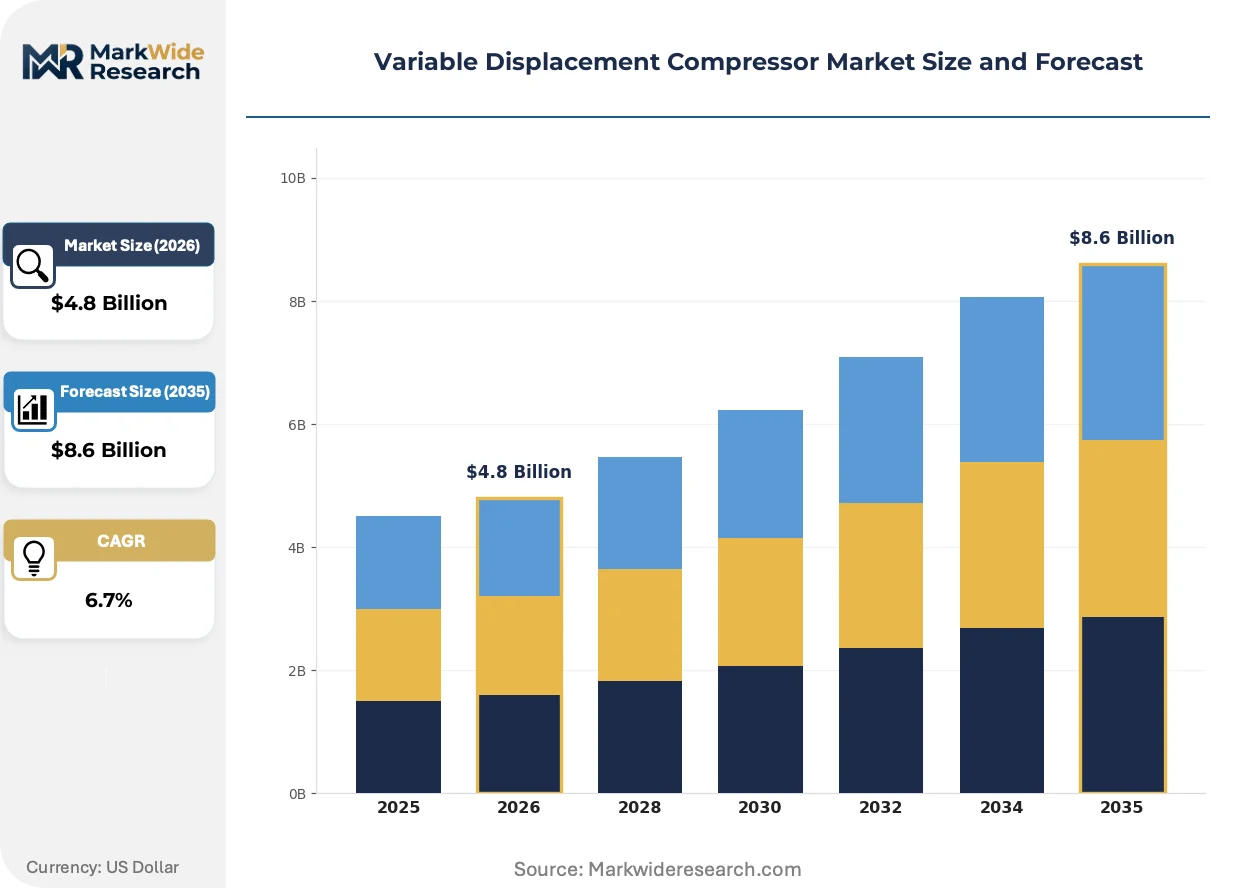
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Scroll, Rotary, Reciprocating, Centrifugal Application: HVAC, Refrigeration, Automotive, Industrial End User: Commercial, Residential, Transportation, Manufacturing Technology: Electronic Control, Mechanical Control, Hybrid Control, Variable Speed |
| Companies Covered | Denso Corporation, Toyota Industries, Mitsubishi Heavy Industries, SANDEN, Hanon Systems, Subros, MAHLE, Automotive Thermal Systems, Nissens, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Variable Displacement Compressor Market Evolving Landscape
Refrigerant chemistry transitions and electrified powertrains are compressing development cycles, forcing compressor architectures to evolve from mechanical modulation toward software-defined thermal capacity.
Variable-speed scroll compressors with integrated inverters are integrating permanent magnet synchronous motors that enable 10:1 turndown ratios for battery cooling precision. Korean and Chinese EV platforms are adopting these units fastest, displacing belt-driven swash-plate designs in 400V and 800V electrical architectures. The technology is integrating thermal management with battery management systems, collapsing the boundary between HVAC and powertrain cooling loops.
EU F-Gas Regulation and its delegated acts are mandating refrigerant charge limits that favor compact, leak-tight compressor housings with integrated sensors. European OEMs are responding with aluminum die-cast scroll housings that reduce mass and internal volume. Stationary heat pump applications are absorbing these automotive-derived designs, creating cross-sector technology transfer.
Fleet operators and leasing companies are consolidating procurement authority for thermal service contracts, unbundling compressor replacement from full HVAC system overhauls. Independent service networks in Germany and the US are capturing this disaggregated spend through predictive maintenance platforms that monitor compressor vibration signatures. The pattern is most visible in commercial vehicle segments where uptime guarantees dominate total cost of ownership calculations.
Variable Displacement Compressor Market Segmentation
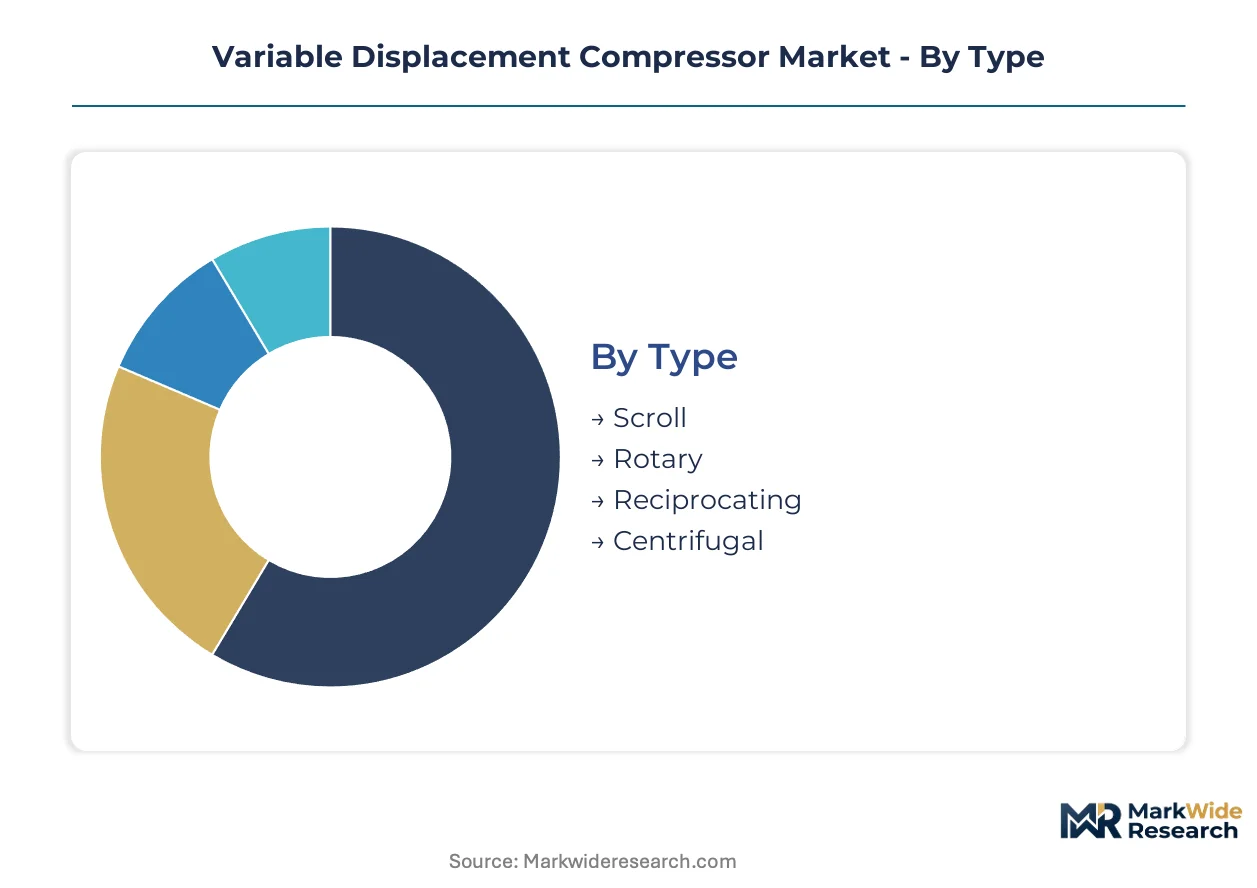
Variable displacement compressor architectures fragment across thermal load requirements and system integration depth. Discrete compressor categories serve standalone commercial refrigeration cabinets versus embedded automotive HVAC modules, with technology selection driven by duty cycle precision and refrigerant charge constraints.
Type:
Scroll compressors integrate most deeply into embedded thermal management systems, while reciprocating and centrifugal architectures retain standalone deployment patterns.
- Scroll:Orbiting scroll pairs create continuous refrigerant compression with 10:1 turndown ratios for precision capacity matching. Demand concentrates in Korean and Chinese EV battery cooling loops where MIIT efficiency mandates accelerate electronic control adoption.
- Rotary:Vane-based displacement modulation suits compact residential heat pumps with moderate capacity variation requirements. European OEMs favor these units for R-1234yf systems under tightening EU F-Gas Regulation charge limits.
- Reciprocating:Piston-driven swash-plate angle adjustment dominates legacy commercial vehicle HVAC retrofits.
- Centrifugal:High-volume refrigerant handling serves industrial process cooling with constant-speed auxiliary modulation.
Volume placements concentrate in Reciprocating; the faster expansion belongs to Scroll.
Application:
Application selection tracks refrigerant inventory scale and thermal response latency requirements across stationary versus mobile platforms.
- HVAC:Building climate control demands capacity modulation across partial-load operating hours. Chinese construction markets absorb variable-speed scroll units for district cooling integration under dual carbon goals.
- Refrigeration:Cold chain integrity requires compressor cycling avoidance to maintain precise evaporator temperatures. Indian food processing corridors drive mechanical control hybrid adoption where grid stability concerns limit full electronic deployment.
- Automotive:Belt-driven and electrically powered units serve passenger vehicle cabin and battery thermal management.
- Industrial:Process cooling loops tolerate fixed-speed staging with variable displacement as trim capacity.
Refrigeration claims the deepest installed base; Automotive climbs the fastest on EV platform proliferation.
End User:
End user economics separate capital-intensive manufacturing installations from operating-expense-driven service sector procurement.
- Commercial:Retail and hospitality operators prioritize energy cost reduction through variable-speed modulation. US supermarket chains retrofit R-404A systems with lower-charge electronic control compressors ahead of EPA SNAP phase-down deadlines.
- Residential:Homeowners accept premium pricing for noise reduction and efficiency gains in heat pump conversions. Japanese residential markets absorb inverter-driven scroll units with METI efficiency labeling driving replacement cycles.
- Transportation:Fleet operators demand uptime-optimized thermal modules with predictive maintenance integration.
- Manufacturing:Process industries specify heavy-duty centrifugal and reciprocating platforms for continuous operation.
Commercial segment generates the highest unit volumes; Transportation is gaining share fastest on electrification mandates.
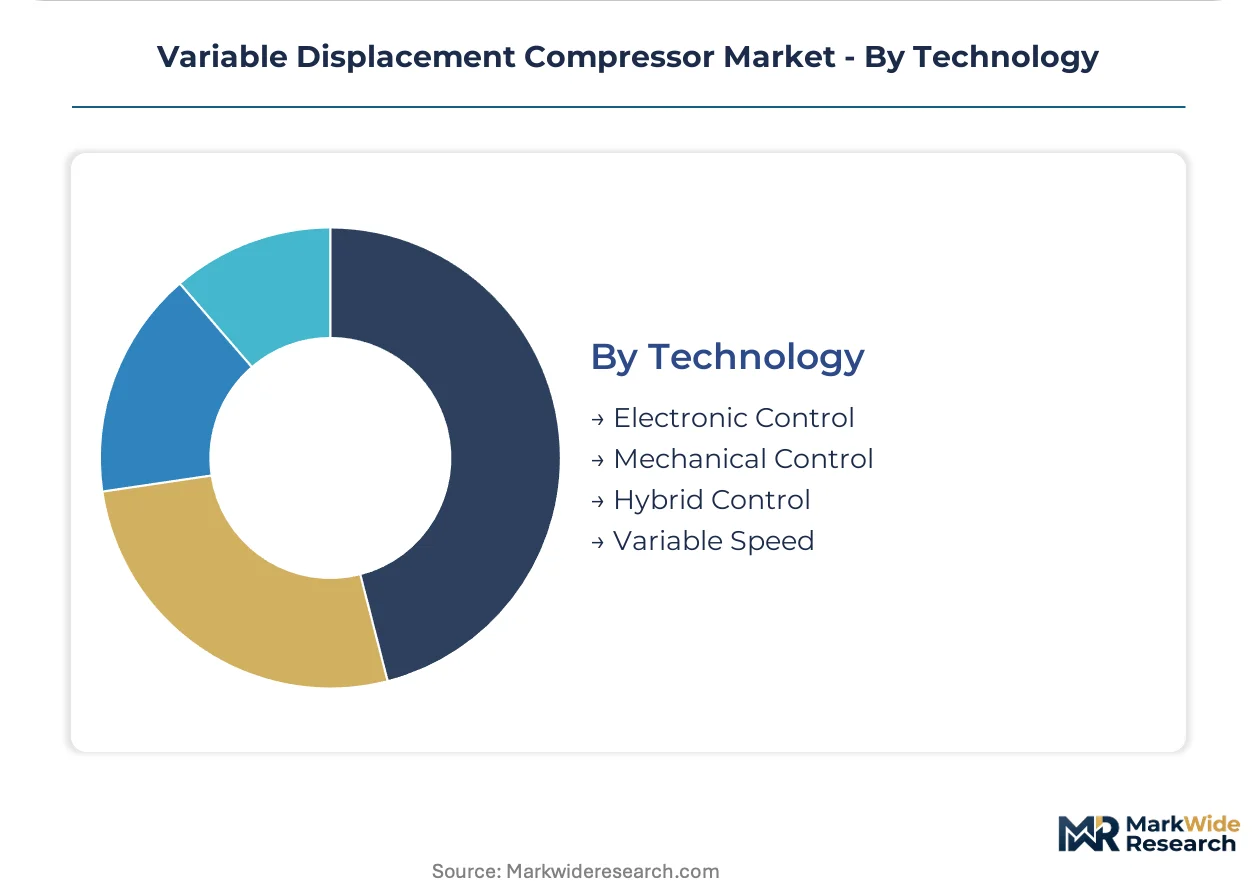
Technology:
Technology tiers reflect control system sophistication and motor drive architecture investment levels.
- Electronic Control:Integrated inverters and permanent magnet synchronous motors enable real-time capacity matching through software-defined refrigerant flow. Chinese EV manufacturers specify these systems for 800V architectures where battery thermal precision prevents runaway conditions.
- Mechanical Control:Pneumatic or hydraulic swash-plate angle modulation operates without electrical complexity. Legacy commercial refrigeration in India and Southeast Asia sustains demand where capital constraints limit inverter adoption.
- Hybrid Control:Electromechanical actuators bridge cost and precision requirements for mid-tier HVAC retrofits.
- Variable Speed:Frequency modulation of fixed-displacement compressors provides partial-load efficiency without full variable displacement mechanics.
Mechanical Control retains the broadest installed footprint; Electronic Control shows the steepest expansion trajectory on automotive electrification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper foundries in Jiangsu Province supply precision castings that anchor East Asian compressor manufacturing. German aluminum die-casting clusters feed European scroll housing demand. Japanese rare-earth magnet processors enable permanent motor supply chains for electronic control units.
China
MIIT efficiency mandates accelerate EV thermal module procurement across domestic OEM platforms. GB standards certification requirements filter supplier access to battery cooling contracts. Precision casting corridors in Ningbo and Taizhou concentrate swash-plate housing output for export markets.
Germany
EU F-Gas Regulation delegated acts force refrigerant charge reductions in automotive HVAC redesigns. Stuttgart engineering bases anchor MAHLE aftermarket distribution across European borders. Bavarian aluminum foundries supply compact scroll housings for R-1234yf systems.
United States
EPA SNAP phase-down deadlines drive supermarket retrofit demand for lower-charge electronic compressors. IRA clean energy incentives accelerate heat pump deployment in residential construction. Michigan automotive supplier parks integrate variable-speed units into EV platform thermal loops.
Japan
METI efficiency labeling sustains replacement cycles for inverter-driven residential heat pumps. Toyota supply heritage concentrates thermal contract access around Denso Corporation. Nagoya-area manufacturing clusters produce scroll orbit variation systems for hybrid vehicle programs.
India
PLI scheme automotive incentives create virgin demand for locally sourced variable-displacement modules. BIS certification requirements shape domestic supplier qualification protocols. Chennai and Pune manufacturing corridors attract Korean and Japanese compressor assembly investments.
Variable Displacement Compressor Market Competitive Landscape
Global majors compete with regional champions across thermal module integration depth and electronic control sophistication. The vendor base stratifies between full-system HVAC integrators and discrete compressor specialists. Three archetypes dominate: Japanese keiretsu-affiliated suppliers leveraging OEM heritage, Korean chaebol-linked firms capturing EV platform share, and European engineering houses anchoring aftermarket distribution. Competitive moves concentrate on capacity co-location with battery cell factories and software certification partnerships for ISO 26262 compliance.
Within the keiretsu-affiliated tier, Denso Corporation and Toyota Industries exemplify supply chain integration advantages. Among Korean system integrators, Hanon Systems occupies a position bridging HVAC module assembly and compressor supply. MAHLE anchors the European aftermarket vector through Stuttgart-based engineering services.
| Leading Market Players |
|---|
| Denso Corporation |
| Toyota Industries |
| Mitsubishi Heavy Industries |
| SANDEN |
| Hanon Systems |
| Subros |
| MAHLE |
| Automotive Thermal Systems |
| Nissens |
| Others |
Value Network & Pricing Analysis
Copper futures volatility on the London Metal Exchange cascades through variable displacement compressor manufacturing, amplifying cost differentials between electronic control units with permanent magnet motors and mechanical control alternatives. This raw material exposure stratifies pricing tiers across automotive OEM contracts, aftermarket replacement channels, and commercial refrigeration retrofit segments.
Pricing Analysis
Warranty bundling separates premium electronic control compressors with integrated predictive maintenance from unbundled mechanical units sold through independent distributors. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 26262 certification status, permanent magnet motor efficiency grades, and geographic proximity to East Asian foundry clusters. Pricing pressure stems from rare-earth magnet cost volatility pressuring mid-tier supplier margins. Fleet operators and commercial HVAC contractors exhibit highest price sensitivity, while automotive OEMs prioritize thermal precision over unit cost.
Supply Chain Analysis
Precision casting workforce availability in Ningbo and Taizhou corridors anchors global swash-plate housing output, while German aluminum die-casting clusters around Stuttgart serve European scroll compressor demand. Supply chains draw from copper cathode shipments through Shanghai Futures Exchange contracts, rare-earth magnet processing in Jiangxi Province, and aluminum billet sourcing from Bavarian smelters. Single-source vulnerability concentrates in Chinese permanent magnet supply chains feeding electronic control motor production. Distribution runs through Tier 1 HVAC module integrators for automotive OEM channels and independent aftermarket networks for commercial refrigeration replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation tightening constructs a cost-of-compliance moat that favors incumbent suppliers with existing CE marking infrastructure and refrigerant charge optimization capabilities, raising barriers for unqualified entrants.
For Market Incumbents: Extend software certification partnerships to accelerate ISO 26262 functional safety validation for compressor motor controllers, countering emerging Korean and Chinese electronics specialists. Deepen captive supply of rare-earth magnet processing through joint ventures with Jiangxi-based processors, insulating margin pools from commodity volatility. Anchor aftermarket channel control through predictive maintenance platform integration with European fleet operators.
For New Entrants and Emerging Players: Launch via dedicated EV thermal module assembly partnerships with Indian OEMs qualifying under PLI scheme incentives, exploiting virgin demand in Chennai and Pune manufacturing corridors. Target commercial refrigeration retrofit segments in Southeast Asia where mechanical control hybrid systems bridge capital constraints and efficiency mandates. Prioritize BIS certification investment to unlock domestic supplier status for Indian automotive contracts.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier electronic control specialists with stranded R&D in 400V automotive architectures during 800V platform transitions. Long-term viability hinges on software-defined thermal capacity integration with battery management systems. Monitor MIIT efficiency mandate acceleration and EPA refrigerant phase-down enforcement velocity as inflection indicators for capacity expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 26262 Certification Investment | Functional safety validation unlocks automotive OEM electronic control contracts against unqualified competitors. |
| Rare-Earth Magnet Supply Agreement | Long-term offtake with Jiangxi processors secures permanent motor cost stability for electronic variable-speed platforms. |
| Predictive Maintenance Platform Integration | Vibration signature monitoring captures fleet operator thermal service contracts unbundled from full HVAC overhauls. |
| 800V Architecture R&D Pivot | High-voltage electronic control development aligns with Korean and Chinese EV platform proliferation trajectories. |
| Indian PLI Scheme Qualification | Domestic assembly certification accesses virgin EV thermal module demand from Chennai and Pune OEM corridors. |
Research Methodology
Multi-period observation of refrigerant chemistry transitions, MIIT efficiency mandate implementation, and EPA SNAP enforcement patterns anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement officers, OEM platform thermal engineers, aftermarket distribution heads, and commercial fleet maintenance directors. Secondary validation drew from EPA regulatory filings, EU F-Gas Regulation delegated acts, China GB standards documentation, and automotive production databases. Bottom-up segmentation modeling triangulated against top-down macroeconomic demand indicators.
Input-output matrices mapped compressor type, control technology, and application segments across the projection horizon, with propulsion architecture and regional regulatory framework as cross-cutting dimensions. CAGRs derived from segment-level demand elasticity modeling against EV platform thermal management intensity curves and refrigerant charge constraint trajectories. Forecast inputs incorporated battery cooling loop precision requirements and rare-earth magnet price elasticity assumptions.
Refrigerant chemistry acceleration beyond modeled timelines, permanent magnet supply disruption, and EV platform thermal architecture standardization are the dominant revision risks to projection outputs. Forecasts embed assumptions around regulatory enforcement consistency and battery cell factory co-location patterns. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Haptic Accelerator Pedal Market
Powertrain
Exhaust Flexible Couplings Market
Powertrain
CNG Powertrain Market
Powertrain
Automotive Drivetrain Market
Powertrain
EV Powertrain-in-the-Loop (P-HIL) Test Benches Market
Powertrain
Automotive Thrust Washer Market
Powertrain
Gasoline Direct Injection (GDI) System Market
Powertrain
Fuel Injection Systems Market
Powertrain
Motor Vehicle Carburetors Market
Powertrain
Automotive Driveline Market
Powertrain
Torque Limiter Market
Powertrain
Automotive Fuel Feed Pumps Market
Powertrain
Europe Turbocharger Market
Powertrain
Drivetrain Vibration and Condition Monitoring Sensor Systems Market
Powertrain
Automotive Brake Booster Market
Powertrain
Dual Clutch Transmission (DCT) Market