
 Automotive Carburetor Market | 2026-2036
Automotive Carburetor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Carburetor Market Outlook
Aftermarket maintenance and rebuild services is hardening as the primary revenue layer for carburetor suppliers as new-vehicle installations decline. Holley Performance Products dominates the North American racing and classic vehicle restoration channel with specialized high-performance units. Mikuni Corporation anchors Asian motorcycle supply through manufacturing scale in Thailand and Indonesia. Keihin Group leverages its historic OEM relationships to sustain aftermarket parts distribution.
An automotive carburetor is a mechanical device that blends air and fuel in precise ratios for internal combustion engines, typically featuring venturi tubes, throttle plates, and adjustable jets calibrated to engine displacement and operating conditions. Down draft configurations occupy the largest volume share in passenger vehicle applications due to simpler intake manifold integration and gravity-assisted fuel flow. Motorcycle applications represent the most resilient demand segment as emerging market commuters prioritize repairable mechanical fuel systems over complex electronic alternatives. Aluminum material grades lead production volumes for cast carburetor bodies, though zinc alloys persist in cost-optimized small-engine variants.
The US EPA and California Air Resources Board tighten evaporative emission standards that restrict carburetor applicability in on-road vehicles, while India's BIS and Thailand's Industrial Standards Institute maintain certification pathways for two-wheeler mechanical fuel systems. China's MIIT fuel consumption regulations accelerate displacement of carburetors by electronic fuel injection in domestic passenger vehicle production. Stakeholders must monitor regulatory phase-out timelines against aftermarket inventory cycles and emerging market replacement demand.
Market Dynamics
The automotive carburetor market confronts a fundamental structural compression as electronic fuel injection systems capture new-vehicle assembly lines, forcing suppliers to pivot toward aftermarket rebuild services and emerging market two-wheeler production where mechanical simplicity retains cost advantages.
Growth Catalysts
- India's BIS emission norms:India's Bureau of Indian Standards maintains certification pathways for calibrated mechanical fuel systems in two-wheeler commuter segments, sustaining baseline manufacturing demand.
- Southeast Asian motorcycle assembly:Indonesian and Thai domestic plants serving regional export markets continue sourcing carburetors for cost-sensitive models targeting emerging economy consumers.
- Classic vehicle restoration:North American collector and racing communities generate resilient aftermarket demand for period-correct fuel system components and performance-tuned units.
Market Restraints
- EPA evaporative emission standards:The US Environmental Protection Agency's tightening on-road vehicle standards structurally restrict carburetor applicability in passenger vehicle and light truck categories.
- Aluminum ingot price volatility:Primary aluminum cost fluctuations compress margin structures for cast carburetor body manufacturers dependent on gravity-fed die-casting processes.
- Electronic fuel injection substitution:Port and direct injection systems displace mechanical fuel metering in all but the most price-sensitive engine displacement categories.
Strategic Opportunities
- African two-wheeler assembly:Underpenetrated motorcycle manufacturing clusters in Nigeria and Kenya present white-space demand for simple, field-repairable fuel systems.
- Small-engine outdoor power equipment:Lawnmower and generator manufacturers in cost-optimized segments retain specification tolerance for zinc-alloy carburetor variants.
- Thailand's Industrial Standards Institute certification:TISI compliance pathways for two-wheeler mechanical systems create regulatory tailwind for suppliers maintaining Thai manufacturing presence.
Industry Challenges
- Precision machining workforce scarcity:Venturi tube calibration and jet drilling operations require skilled machinist competencies that are aging out of the workforce without replacement pipelines.
- Legacy OEM parts rationalization:Original equipment manufacturers are accelerating end-of-life inventory discontinuation, compressing aftermarket parts availability windows for older vehicle platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Carburetor Market |
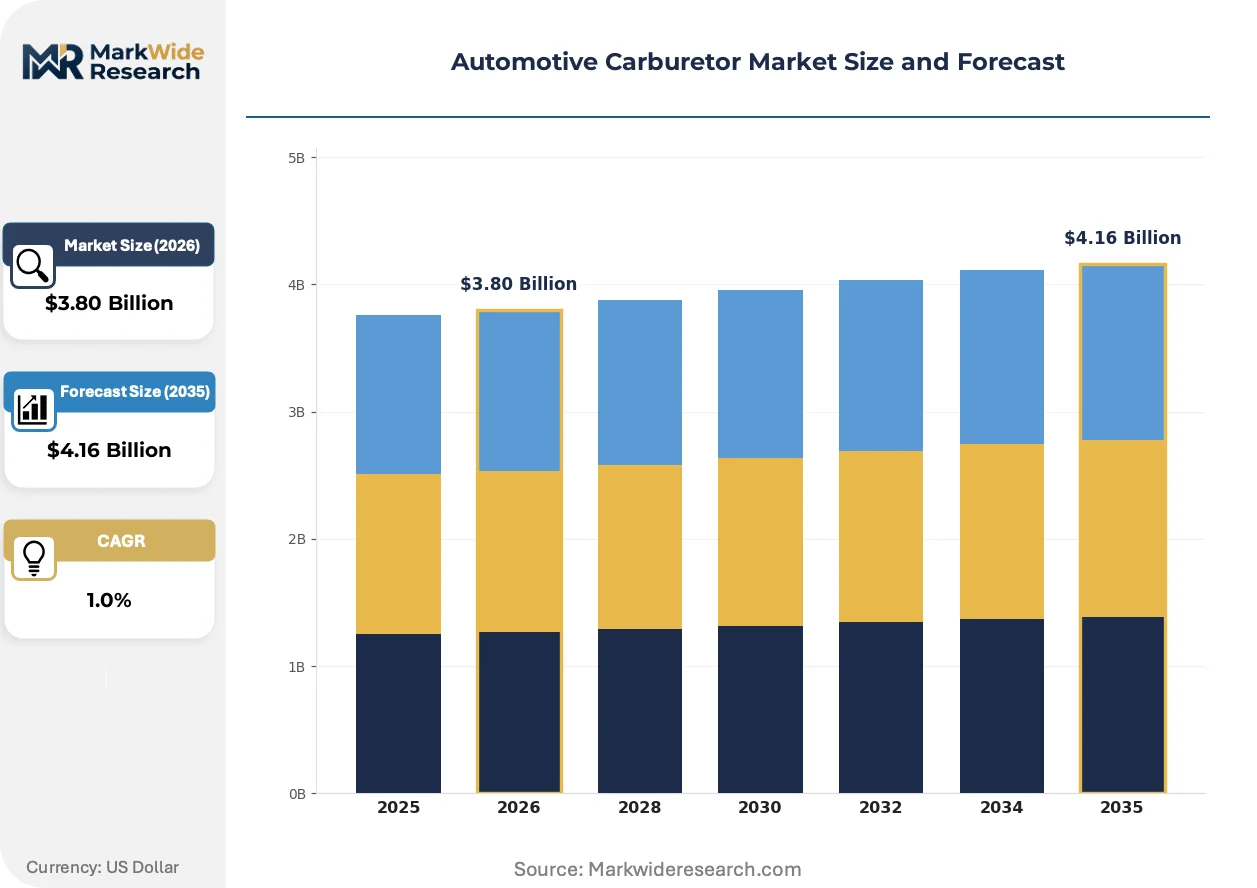
| Market Size in 2026 | $3.80 Billion |
| Market Size in 2035 | $4.16 Billion |
| CAGR (2026 – 2036) | 1.0% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Side Draft, Down Draft, Up Draft, Constant Vacuum Material: Aluminum, Plastic, Zinc, Cast Iron Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Racing Vehicles End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Parts Distributors |
| Companies Covered | Zama Group, Holley Performance Products, Keihin Group, Fuding Huayi, Edelbrock, Mikuni Corporation, Dell'Orto, Ruixing, Walbro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Carburetor Market Strategic Shifts
Carburetor technology evolution now concentrates on manufacturing process automation and quality control systems that preserve mechanical precision at declining production volumes, rather than fundamental design innovation.
Computer-numerical-control machining is automating venturi boring and throttle shaft drilling operations that historically required manual lathe work. Indonesian and Thai suppliers are adopting these systems to maintain tolerance consistency across shrinking batch sizes. This automation is compressing the viable minimum order quantity for custom-calibrated carburetor variants.
China's MIIT fuel consumption regulations are accelerating displacement of carburetors by electronic fuel injection in domestic passenger vehicle production. The Ministry of Industry and Information Technology's corporate average fuel economy mandates penalize mechanical fuel metering inefficiencies. Domestic Chinese OEMs are responding by eliminating carburetor options from entire vehicle lineups.
Aftermarket distributors are consolidating inventory positions around fast-moving rebuild kits rather than complete carburetor assemblies. North American jobber networks now prioritize diaphragm, needle, and gasket assortments over finished units. This pattern is most visible in US classic vehicle restoration channels where enthusiasts prefer component-level refurbishment.
Automotive Carburetor Market Segmentation
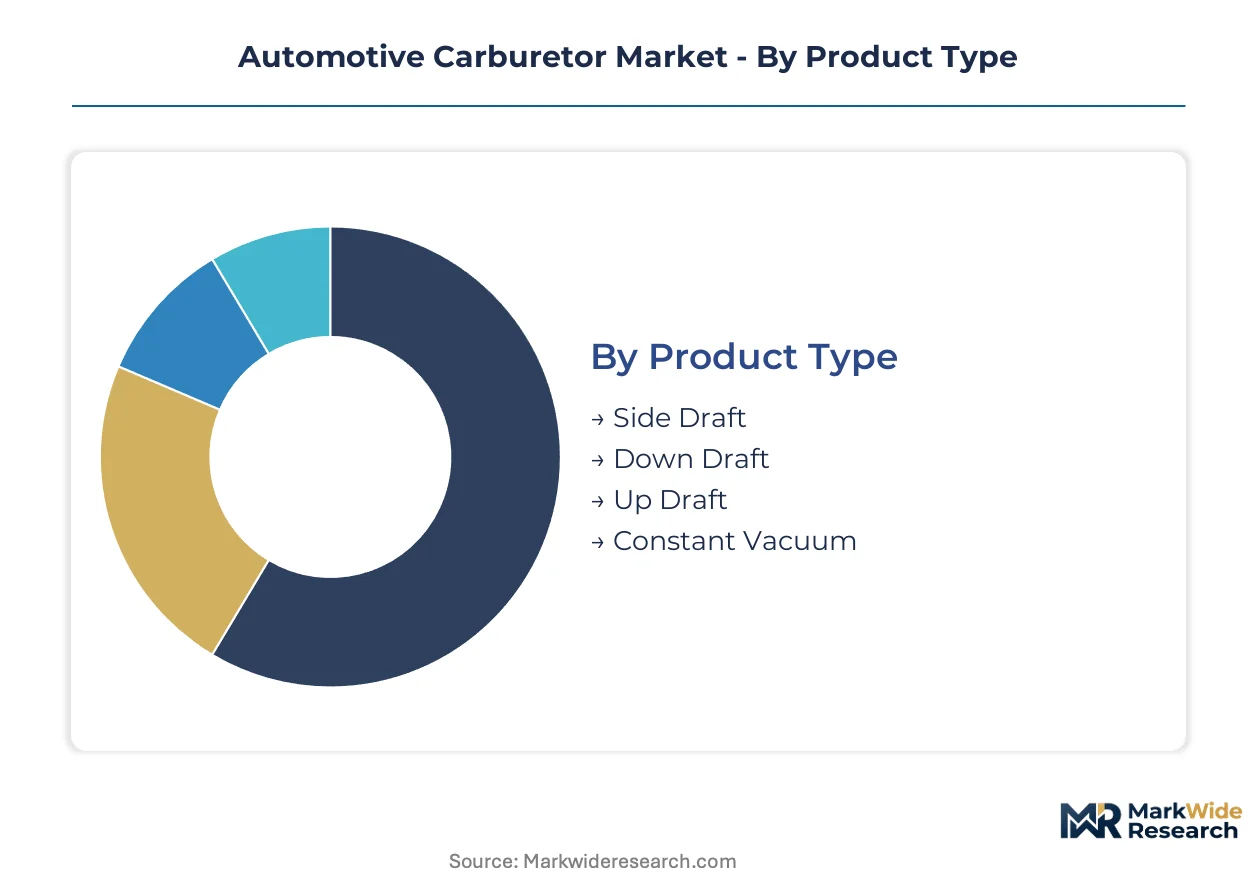
Carburetor segmentation reveals how mechanical fuel systems fragment across diverging demand pools. Product configuration and material selection now map directly to regulatory tolerance zones and repair economics rather than performance optimization.
Product Type:
Down draft configurations dominate assembly volumes while side draft units command premium positioning in specialized applications.
- Down Draft:Gravity-assisted fuel flow simplifies intake manifold integration in passenger vehicle architectures. Demand concentrates in Southeast Asian motorcycle plants serving Indonesian and Thai domestic assembly where cost-sensitive engineering prioritizes manufacturing simplicity over fuel efficiency optimization.
- Side Draft:Horizontal venturi orientation enables compact engine bay packaging for performance-tuned applications. Classic vehicle restoration channels in the United States sustain resilient aftermarket demand as collectors prioritize period-correct fuel system authenticity over modern alternatives.
- Up Draft:Vertical air intake direction suits small-engine outdoor power equipment where space constraints dominate design decisions. Lawnmower and generator manufacturers specify these units for cost-optimized displacement categories.
- Constant Vacuum:Variable venturi design maintains consistent air-fuel ratios across RPM ranges. Motorcycle OEMs in India specify these for BIS-certified two-wheeler commuter segments requiring calibrated mechanical fuel systems.
Today's leader: Down Draft. Tomorrow's challenger: Constant Vacuum.
Material:
Aluminum grades anchor production economics while zinc alloys defend niche cost positions in small-engine supply chains.
- Aluminum:Die-cast aluminum bodies deliver thermal conductivity and machinability for precision venturi boring. Thai and Indonesian suppliers rely on gravity-fed die-casting processes serving regional motorcycle assembly clusters where batch consistency determines OEM qualification.
- Zinc:Lower melting point alloys enable thinner wall sections in cost-optimized small-engine variants. Outdoor power equipment manufacturers in China specify zinc carburetors for lawnmower and generator applications where unit economics override durability requirements.
- Plastic:Polymer housings reduce weight in specialized racing applications where every gram affects competitive performance. North American racing channels source these for sanctioned competition categories with strict displacement rules.
- Cast Iron:Dense ferrous construction survives extreme thermal cycling in vintage heavy-duty applications. Restoration specialists specify cast iron for pre-1970s commercial vehicle rebuilds requiring metallurgical authenticity.
Aluminum retains volume leadership. Zinc defends cost-driven niches against polymer substitution.
Application:
Motorcycle assembly sustains manufacturing demand while passenger vehicle applications retreat to aftermarket rebuild services.
- Motorcycles:Two-wheeler commuter segments in India and Southeast Asia prioritize field-repairable mechanical systems over electronic fuel injection. Indonesian domestic plants serving regional export markets specify carburetors for displacement categories under 150cc where cost sensitivity dominates consumer purchasing decisions.
- Racing Vehicles:Sanctioned competition categories mandate mechanical fuel metering for technical parity. US-based racing parts distributors stock performance-tuned variants with adjustable jetting for track-specific calibration.
- Passenger Vehicles:New-vehicle installations have collapsed under EPA evaporative emission standards. Aftermarket rebuild services now constitute the primary revenue layer for suppliers serving classic vehicle restoration channels.
- Commercial Vehicles:Heavy-duty trucking eliminated carburetors decades ago. Limited demand persists in vintage bus and truck restoration where historical accuracy commands premium pricing.
Motorcycles anchor current production. Racing vehicles offer the steepest expansion trajectory in aftermarket value per unit.
End User:
Aftermarket suppliers capture margin expansion as OEMs accelerate parts rationalization and inventory discontinuation.
- Aftermarket Suppliers:Rebuild kit distributors consolidate inventory around diaphragm, needle, and gasket assortments rather than complete assemblies. North American jobber networks prioritize component-level refurbishment for classic vehicle enthusiasts.
- OEMs:Original equipment manufacturers maintain limited specification tolerance only in emerging market two-wheeler segments. Indian and Thai motorcycle OEMs represent the final manufacturing demand concentration for new carburetor procurement.
- Vehicle Assemblers:Contract assembly plants in Indonesia and Nigeria source carburetors for knock-down kit production serving domestic markets with minimal emission enforcement.
- Parts Distributors:Wholesale distributors buffer inventory cycles against regulatory phase-out timelines. Regional distributors in Africa stock field-repairable units for informal repair networks lacking electronic diagnostic capability.
Aftermarket Suppliers lead revenue capture. Vehicle Assemblers in underpenetrated African markets present white-space expansion potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India sustains carburetor manufacturing demand through BIS-certified two-wheeler production, while Indonesia anchors Southeast Asian assembly volume for regional motorcycle exports. These markets diverge in regulatory tolerance, with India maintaining mechanical fuel system pathways as China accelerates electronic fuel injection displacement.
India
Two-wheeler commuter segments drive carburetor procurement as field-repairable mechanical systems dominate price-sensitive rural markets. The Bureau of Indian Standards certifies calibrated fuel systems under BIS emission norms for displacement categories under 150cc. Manufacturing clusters in Tamil Nadu and Maharashtra supply domestic OEMs and aftermarket rebuild networks across South Asia.
Indonesia
Domestic motorcycle assembly plants source carburetors for cost-optimized models targeting emerging economy consumers throughout ASEAN. The Ministry of Industry's localization incentives sustain component manufacturing in Bekasi and Karawang industrial zones. Thai border logistics corridors facilitate cross-border kit assembly serving Philippines and Vietnam markets.
Thailand
The Industrial Standards Institute maintains TISI certification pathways for two-wheeler mechanical fuel systems, preserving supplier qualification routes. Rayong and Chonburi provinces concentrate die-casting operations serving regional OEM procurement. Japanese-affiliated suppliers leverage Thai manufacturing scale for ASEAN export fulfillment.
China
MIIT fuel consumption regulations penalize mechanical fuel metering inefficiencies, accelerating carburetor displacement in domestic passenger vehicle production. Chongqing and Zhejiang motorcycle manufacturers retain limited specification tolerance for export-oriented small-displacement models. Domestic OEMs have eliminated carburetor options from entire vehicle lineups under corporate average fuel economy mandates.
United States
Classic vehicle restoration and sanctioned racing categories sustain aftermarket demand for period-correct fuel system components. The EPA's evaporative emission standards structurally restrict new-vehicle carburetor applicability, concentrating revenue in rebuild services. Holley Performance Products anchors the North American high-performance channel through specialized racing and restoration distribution.
Automotive Carburetor Market Competitive Environment
Top-tier vendors anchor the premium aftermarket channel, while mid-scale fabricators serve emerging market OEM procurement. The supplier base fragments across geographic specialization rather than consolidated global platforms. Three archetypes dominate: performance-tuned specialists serving racing restoration, high-volume Asian manufacturers supplying motorcycle OEMs, and diversified component houses maintaining legacy parts distribution. Competitive positioning depends on regulatory compliance maintenance and precision machining workforce retention rather than capacity expansion.
Within the Asian manufacturing tier, Mikuni Corporation and Keihin Group exemplify scale-driven suppliers serving Indonesian and Thai motorcycle assembly clusters. Holley Performance Products occupies the premium-tier position in North American racing and classic vehicle channels. Zama Group represents the diversified component archetype with cross-segment small-engine supply capabilities. These anchors illustrate how competitive positioning maps to regulatory tolerance zones and end-use specialization rather than integrated global scale.
| Leading Market Players |
|---|
| Zama Group |
| Holley Performance Products |
| Keihin Group |
| Fuding Huayi |
| Edelbrock |
| Mikuni Corporation |
| Dell'Orto |
| Ruixing |
| Walbro |
| Others |
Value Chain & Pricing Dynamics
China's MIIT fuel consumption regulations gate both qualified supply and premium-tier pricing access, as OEMs eliminate carburetor options from entire vehicle lineups and suppliers must maintain TISI or BIS certification pathways to command pricing power in residual demand pools.
Pricing Analysis
Capacity additions in Thailand and Indonesia are reshaping price floors for aluminum die-cast carburetor bodies serving regional motorcycle assembly. Three-tier pricing structure across premium racing variants, standard OEM-calibrated units, and economy small-engine grades separates performance-tuned restoration channels from cost-optimized commuter segments. Cost compression in zinc-alloy small-engine supply is intensifying because Chinese lawnmower manufacturers prioritize unit economics over durability specifications. Aftermarket rebuild kit distributors exhibit highest price sensitivity, while North American racing channels absorb premium pricing for period-correct authenticity.
Supply Chain Analysis
Dual-sourcing requirements from Japanese-affiliated motorcycle OEMs mandate multi-supplier qualification across Thai and Indonesian die-casting operations. Primary supply concentrates in Thailand, Indonesia, and India, with secondary finishing in China for export-oriented small-displacement models. Raw material dependencies center on primary aluminum ingots, zinc alloys for cost-optimized variants, and precision-machined brass jet components. Single-source vulnerability persists in venturi calibration equipment where CNC machining expertise is aging out without replacement pipelines. Distribution runs through regional OEM procurement offices and consolidated North American jobber networks prioritizing component-level inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as demand concentrates in premium restoration and certified OEM supply where mechanical precision and regulatory compliance separate viable suppliers from commodity competitors.
For Market Incumbents: Deepen backward integration into precision CNC machining capabilities to offset workforce scarcity in venturi calibration operations. Secure TISI and BIS certification maintenance as defensive moats against regulatory phase-out timelines. Control aftermarket channel inventory positions to buffer against legacy OEM parts rationalization accelerating end-of-life discontinuation.
For New Entrants and Emerging Players: Automated quality control systems for small-batch custom calibration present a technology-first wedge into North American racing and classic vehicle restoration channels. Target underpenetrated African motorcycle assembly clusters in Nigeria and Kenya where field-repairable mechanical systems dominate over electronic alternatives. Pursue knock-down kit supplier relationships with vehicle assemblers lacking electronic diagnostic infrastructure.
For Investors and Strategic Acquirers: Roll-up economics work for diversified component houses with cross-segment small-engine capabilities because aftermarket parts rationalization creates captive demand consolidation opportunities. Five-to-ten year viability hinges on emerging market two-wheeler production sustainability against electronic fuel substitution pressure. Watch India's BIS emission norm revision timelines as the critical inflection signal for residual manufacturing demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into CNC Machining | Precision automation offsets aging venturi calibration workforce scarcity in Thai and Indonesian plants. |
| Dual Certification Maintenance (TISI/BIS) | Regulatory compliance pathways preserve OEM qualification routes as emission standards tighten. |
| Aftermarket Channel Consolidation | Rebuild kit distributor relationships buffer revenue against new-vehicle installation collapse. |
| African Assembly Footprint Expansion | Nigerian and Kenyan knock-down kit production accesses white-space demand for repairable fuel systems. |
| Component-Level Inventory Pivot | Diaphragm and gasket assortment focus aligns with North American jobber network consolidation patterns. |
Study Parameters
Multiple input streams — primary interviews with carburetor manufacturing executives, aftermarket distribution managers, and motorcycle OEM procurement leads; secondary validation through MIIT regulatory filings, BIS certification databases, and ASEAN automotive production statistics; plus customs trade data for aluminum and zinc alloy flows — were reconciled through bottom-up and top-down triangulation across the analysis window.
Data-stream reconciliation applied vehicle class, propulsion architecture, and regional production cluster segmentation dimensions throughout the forecast period. CAGRs were derived from production volume trajectories weighted against regulatory phase-out timelines and aftermarket inventory cycle patterns. Industry-specific forecast inputs incorporated EPA evaporative emission standard enforcement schedules and India's BIS two-wheeler certification pathway stability.
The model holds under stable emerging market two-wheeler demand and gradual electronic fuel injection substitution; deviation in India's BIS norm revision timing or China's MIIT mandate acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Torque Converter Market
Powertrain
Transmission Oil Pumps Market
Powertrain
Global Automotive Clutch Pedals Market
Powertrain
Clutch Market
Powertrain
India Automotive Engine Oils Market
Powertrain
Global Automotive Electric Drivetrain System Market
Powertrain
Global Automotive Transmission Engineering Services Outsourcing Market
Powertrain
Automotive Performance Tuning Market
Powertrain
Tachometer Market
Powertrain
Automotive Crankshaft Sensor Market
Powertrain
Asia-Pacific Automotive Engine Oils Market
Powertrain
Global Industrial Turbocharger Market
Powertrain
Europe Hill-Start Assist System Market
Powertrain
South Africa Automotive Engine Oils Market
Powertrain
Turbine Housing for Automobile Market
Powertrain
Reciprocating Engine Market