
 Europe Automotive Start-Stop Battery Market | 2026-2036
Europe Automotive Start-Stop Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Start-Stop Battery Market Analysis
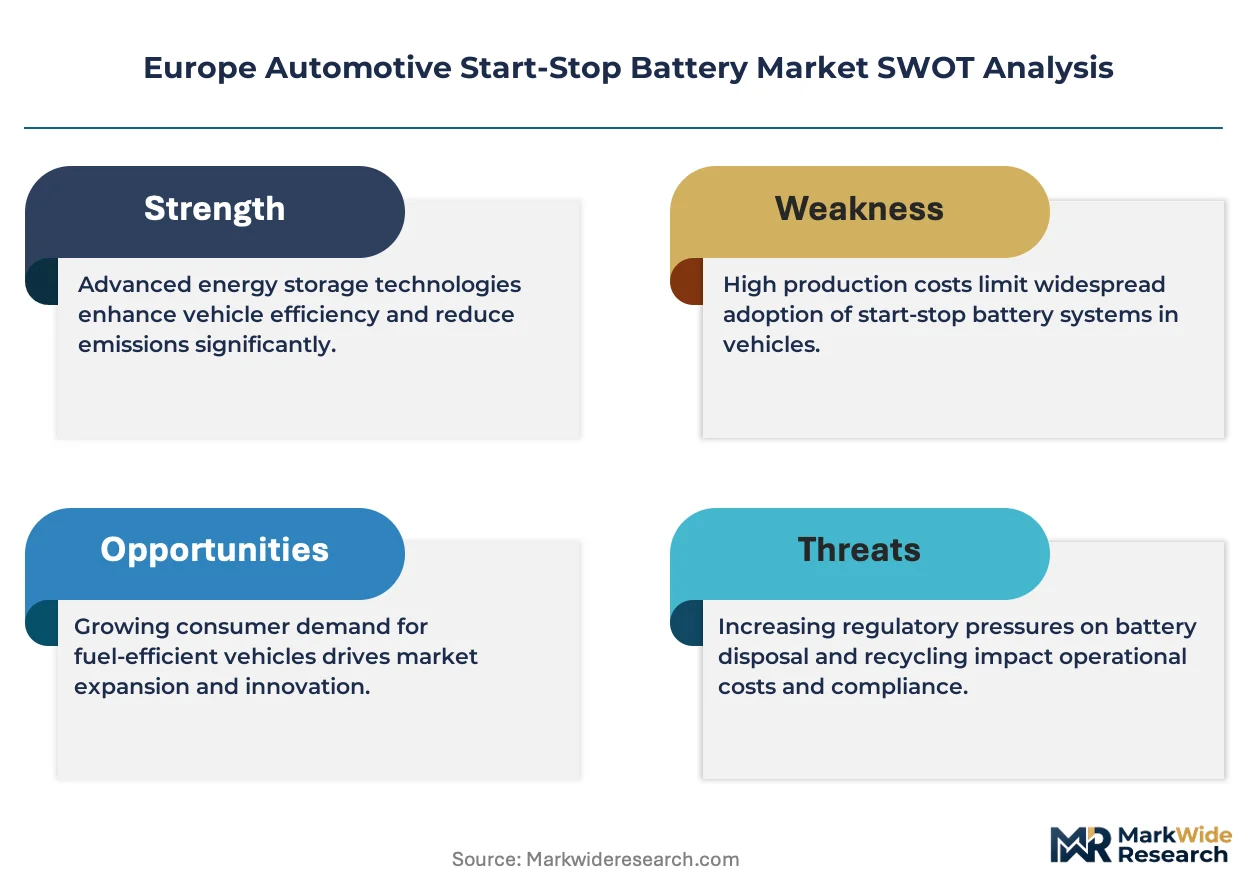
The capital-intensity divergence between absorbed glass mat specialists and conventional flooded battery producers is rotating competitive advantage toward manufacturers with dedicated AGM casting and formation lines. VARTA leverages its German manufacturing base to sustain premium positioning in OEM start-stop fitments. Banner Batteries anchors central European aftermarket distribution through Austrian production and regional logistics hubs. Clarios competes across both technology tiers with integrated recycling operations that lower lead input costs.
Europe Automotive Start-Stop Battery refers to rechargeable energy storage devices engineered for frequent shallow-depth cycling, typically employing absorbent glass mat or enhanced flooded lead-acid construction with calcium-tin alloy grids to withstand 200,000-plus engine restarts across a five-to-seven-year service life. The primary commercial purpose is enabling internal combustion engines to shut down at idle and restart instantly, reducing urban fuel consumption and tailpipe emissions in congested European driving conditions. Lead-Acid variants occupy the volume tier due to established recycling infrastructure and cost parity with conventional batteries, while Lithium-Ion chemistries capture margin pools in 48-volt mild-hybrid architectures where energy density and charge acceptance rates justify premium positioning. Passenger Vehicles dominate installation volumes as OEMs embed start-stop as standard equipment across B-segment and above nameplates to comply with fleet-average CO2 regulations.
EU Green Deal mandates and the F-Gas Regulation shape product standards by accelerating 48-volt system adoption that demands enhanced battery durability, while ECHA oversight of lead substance restrictions influences recycling compliance costs and manufacturing site licensing across member states. CE marking requirements enforce electromagnetic compatibility and safety testing protocols that differentiate qualified suppliers from gray-market imports. Stakeholders must monitor pending Battery Regulation delegated acts on carbon footprint declarations and recycled content quotas, as these will reshape sourcing strategies and qualification timelines for OEM supply contracts.
Market Dynamics
EU Green Deal mandates are compressing fleet-average CO2 limits faster than powertrain electrification can scale, forcing OEMs to embed start-stop systems across internal combustion lineups as a compliance bridge technology. This regulatory pressure is restructuring battery procurement specifications toward enhanced cycling durability and faster charge acceptance rates.
Growth Catalysts
- EU Green Deal Fleet Mandates:Binding CO2 reduction targets for passenger vehicle fleets are mandating idle-stop functionality as standard equipment across B-segment and above nameplates, creating embedded demand for absorbent glass mat and enhanced flooded battery technologies.
- 48-Volt Mild-Hybrid Architectures:Powertrain electrification at the 48-volt tier is expanding start-stop system duty cycles from simple idle-stop to sailing, boosting, and recuperation functions that require batteries with 200,000-plus restart tolerance.
- Aging Vehicle Parc Turnover:Germany, France, and Italy collectively concentrate replacement demand as vehicles aged eight to twelve years upgrade from conventional flooded batteries to start-stop-compatible chemistries during scheduled maintenance cycles.
Market Restraints
- Lead Price Volatility:Raw material input costs for lead-acid battery production fluctuate with London Metal Exchange pricing and secondary lead availability, compressing margin stability for producers without integrated recycling operations.
- Technology Transition Friction:Absorbent glass mat manufacturing requires dedicated casting and formation lines with higher capital intensity than conventional flooded battery production, creating supply bottlenecks during demand surges.
- Lithium-Ion Substitution Threat:48-volt system designers are evaluating lithium-ion alternatives for premium mild-hybrid applications where energy density and charge acceptance advantages justify cost premiums over lead-acid solutions.
Strategic Opportunities
- Eastern European Aftermarket Expansion:Poland, Czech Republic, and Hungary present underpenetrated replacement demand as vehicle ownership rates mature and independent repair networks upgrade diagnostic capabilities for start-stop battery installation.
- Battery Regulation Delegated Acts:Pending EU carbon footprint declarations and recycled content quotas will reshape qualification timelines for OEM supply contracts, favoring producers with established circular economy infrastructure.
- Smart Battery Sensor Integration:Convergence of battery management electronics with state-of-charge algorithms is enabling predictive maintenance services that extend service life and create recurring revenue streams for distributors.
Industry Challenges
- AGM Formation Skill Scarcity:Specialized electrochemical engineering expertise for absorbent glass mat plate formation and acid saturation control remains concentrated among legacy producers, constraining capacity expansion timelines.
- CE Marking Compliance Compression:Electromagnetic compatibility and safety testing protocols for start-stop batteries require third-party certification cycles that lag behind OEM platform launch schedules, creating supply qualification bottlenecks.
- Reverse Logistics Complexity:Core return management for lead-acid batteries involves hazardous material handling regulations that vary across member states, fragmenting collection network economics and compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Start-Stop Battery Market |
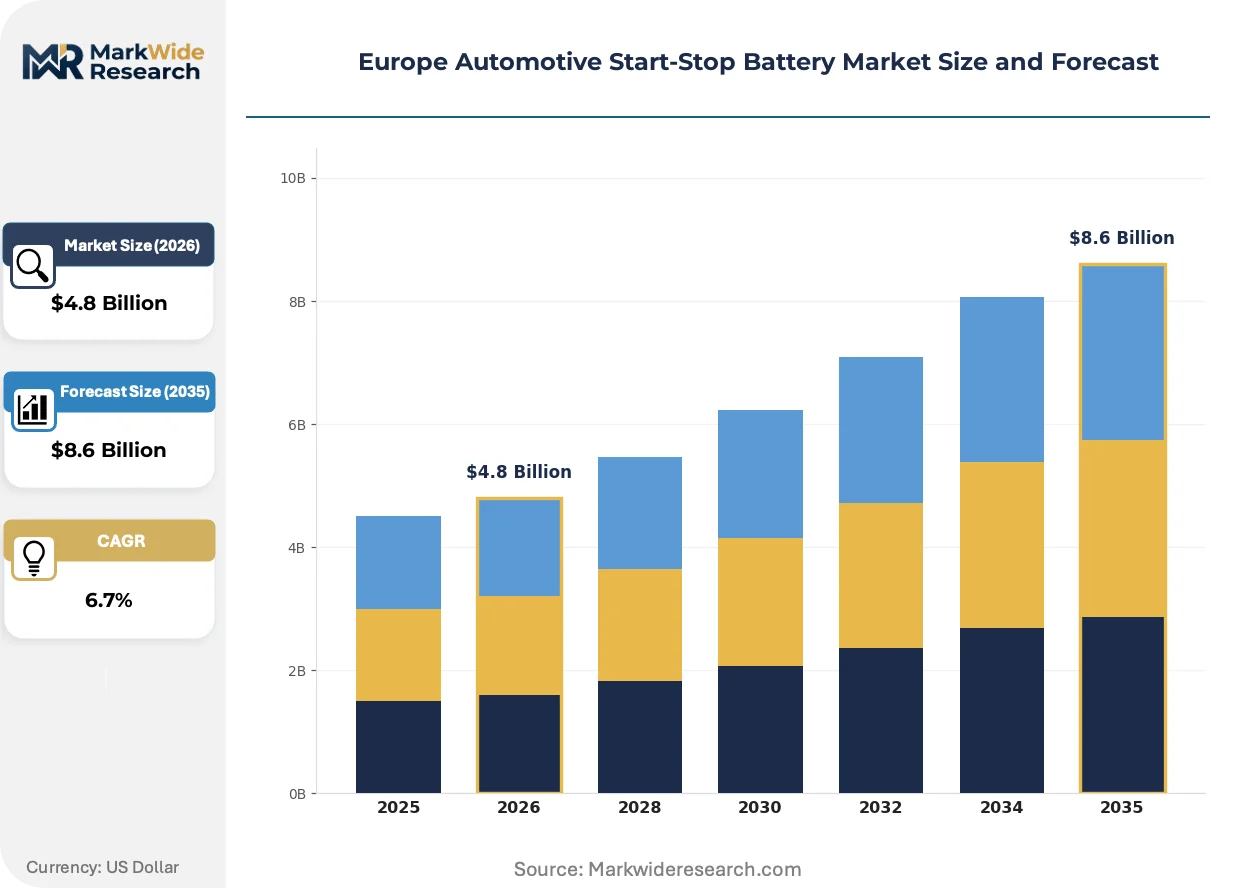
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Acid, Lithium-Ion, Nickel-Metal Hydride, Advanced Lead-Acid End User: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Hybrid Vehicles Technology: Micro-Hybrid, Full Hybrid, Plug-In Hybrid, Start-Stop Technology Installation Type: Original Equipment Manufacturers, Aftermarket Installations, Retrofitting, Fleet Installations |
| Companies Covered | East Penn Manufacturing Company, Banner Batteries, Clarios, Continental AG, VARTA, GS Yuasa International, EnerSys, FIAMM, Exide Industries, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Start-Stop Battery Market Emerging Trajectories
Active materials engineering and system-level integration are compressing battery form factors while expanding functional envelopes. Three developments are restructuring competitive positioning.
Silicon-doped negative active material is miniaturizing plate thickness while maintaining cranking power density. OEMs are specifying these formulations for under-hood packaging constraints in downsized engine bays. The technology is miniaturizing battery footprints to half the volume of conventional designs without sacrificing cold-cranking amperage ratings.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant system electrification that couples with 48-volt architectures. This industrial consequence is expanding start-stop battery duty cycles into thermal management functions. Passenger vehicle segments in Germany and France are responding with enhanced battery thermal packaging to sustain performance across wider operating temperature ranges.
Fleet operators are unbundling battery replacement from scheduled maintenance contracts and negotiating direct procurement with distributors. Independent repair networks are displacing authorized dealer channels for out-of-warranty start-stop battery installation. This behavioral shift is most visible in Italy's fragmented aftermarket where price transparency platforms are aggregating demand and compressing distributor margins.
Europe Automotive Start-Stop Battery Market Segmentation
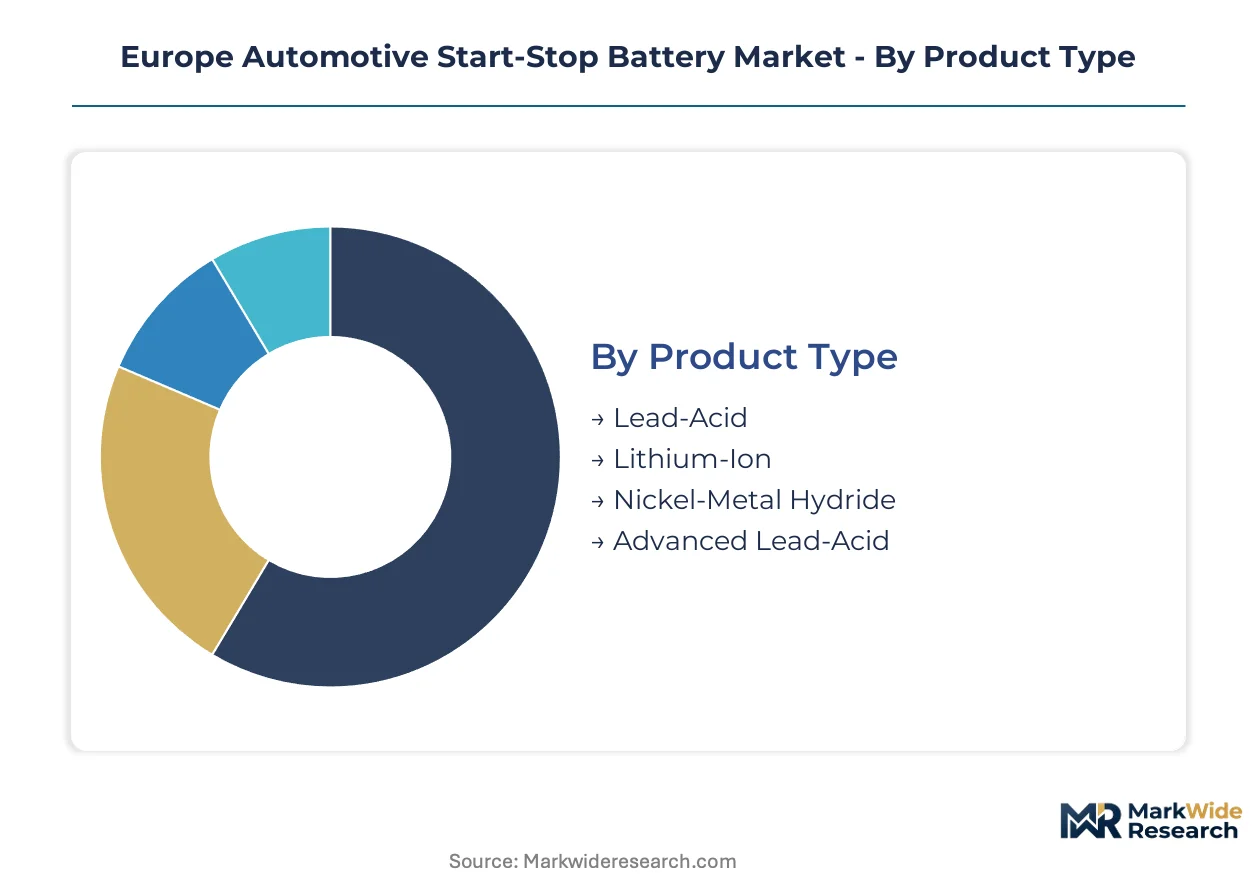
Technology heterogeneity across European powertrain electrification tiers creates distinct battery procurement specifications. Start-stop system designers match chemistry and construction to duty cycle severity, thermal packaging constraints, and OEM platform cost targets.
Product Type:
Lead-acid chemistries dominate domestic European production volumes, while lithium-ion sourcing concentrates on Asian cell imports for premium 48-volt architectures.
- Lead-Acid:Absorbent glass mat and enhanced flooded constructions withstand 200,000-plus engine restarts across five-to-seven-year service lives. German OEMs specify AGM formulations for B-segment and above idle-stop systems to meet EU Green Deal fleet CO2 mandates.
- Lithium-Ion:Higher energy density and charge acceptance rates justify cost premiums in 48-volt mild-hybrid sailing and boosting functions. French premium vehicle platforms are adopting lithium-ion starter batteries for under-hood packaging miniaturization.
- Nickel-Metal Hydride:Mature recycling pathways and thermal stability sustain niche deployment in legacy full-hybrid powertrains.
- Advanced Lead-Acid:Silicon-doped negative active materials compress plate thickness while maintaining cold-cranking amperage ratings for downsized engine bays.
Lead-Acid holds the largest share; momentum sits with Lithium-Ion.
End User:
Passenger vehicle OEMs embed start-stop as standard equipment to compress fleet-average emissions, while commercial fleet operators drive aftermarket replacement velocity through scheduled maintenance contracts.
- Passenger Vehicles:B-segment and above nameplates integrate idle-stop functionality as baseline equipment under EU Green Deal binding CO2 reduction targets. Italian and Spanish vehicle parc turnover accelerates replacement demand for start-stop-compatible batteries.
- Commercial Vehicles:Urban delivery van platforms in Germany and France deploy enhanced cycling durability for high-frequency stop-and-go duty cycles. Fleet procurement contracts unbundle battery replacement from dealer service packages.
- Electric Vehicles:Auxiliary 12-volt systems require deep-cycle tolerance for HVAC and control electronics when traction batteries are disconnected.
- Hybrid Vehicles:Dual battery architectures separate high-voltage traction and 12-volt start-stop functions, demanding specialized formation protocols.
Passenger Vehicles anchor volume concentration; Commercial Vehicles are climbing the fastest on fleet electrification timelines.
Technology:
Micro-hybrid configurations represent the volume tier, while plug-in hybrid architectures impose the most severe cycling demands on battery durability.
- Micro-Hybrid:Simple idle-stop functionality operates on 12-volt electrical architectures with conventional AGM or enhanced flooded batteries. Polish and Czech vehicle assembly plants source these batteries from central European suppliers to minimize logistics costs.
- Full Hybrid:Sustained electric-only propulsion intervals require batteries with enhanced thermal packaging for wider operating temperature ranges.
- Plug-In Hybrid:Extended electric range and frequent engine restart cycles impose the highest durability specifications on start-stop battery subsystems.
- Start-Stop Technology:Standalone idle-stop systems without electric boost capability represent the entry-tier compliance solution for mass-market nameplates.
Micro-Hybrid commands installed base; Plug-In Hybrid shows steepest expansion trajectory on EU fleet mandate pressure.
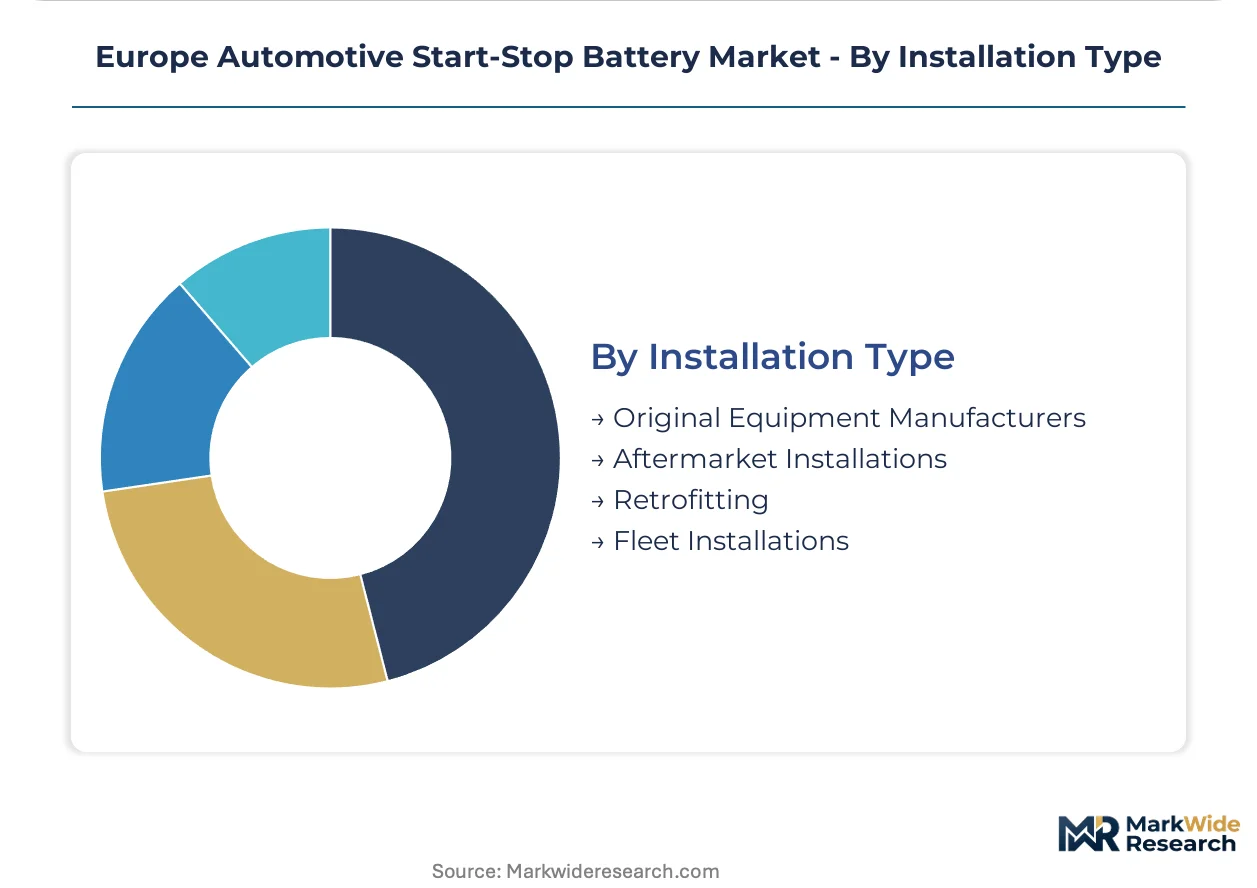
Installation Type:
OEM fitments concentrate in German, French, and Italian assembly plants, while aftermarket channels fragment across independent repair networks with varying diagnostic capabilities.
- Original Equipment Manufacturers:Tier-1 battery suppliers qualify through electromagnetic compatibility and safety testing protocols for CE marking. VARTA and Clarios anchor OEM supply contracts with integrated recycling operations that lower lead input costs.
- Aftermarket Installations:Independent repair networks in Italy and Spain displace authorized dealers for out-of-warranty battery replacement. Price transparency platforms aggregate demand and compress distributor margins.
- Retrofitting:Aging vehicle parc upgrades from conventional flooded to start-stop-compatible chemistries during scheduled maintenance cycles.
- Fleet Installations:Direct procurement negotiations between logistics operators and distributors bypass traditional wholesale channels for volume battery replacement.
Original Equipment Manufacturers retain value concentration; Aftermarket Installations gain share fastest on vehicle parc maturity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Replacement demand elasticity varies sharply across European markets. German fleet operators prioritize OEM-certified AGM formulations regardless of price premiums, while Italian independent workshops drive aggressive aftermarket price competition for compatible flooded alternatives.
Germany
KBA vehicle registration data shows the steepest parc aging in Bavaria and Baden-Württemberg, where eight-to-twelve-year-old vehicles dominate replacement cycles. EU Green Deal fleet mandates force domestic OEMs to embed start-stop across B-segment nameplates, tightening AGM specification standards. Stuttgart and Ingolstadt assembly corridors source batteries from suppliers with integrated recycling operations to satisfy ECHA lead substance compliance.
France
Renault and Stellantis production lines in Hauts-de-France and Île-de-France specify enhanced cycling durability for urban delivery van platforms. ANSM oversight of workplace chemical exposure influences formation plant licensing in northern industrial zones. Lyon and Grenoble engineering clusters develop 48-volt thermal packaging solutions for wider operating temperature ranges.
Italy
Fragmented independent repair networks in Lombardy and Emilia-Romagna displace authorized dealers for out-of-warranty battery installation. Price transparency platforms aggregate demand from aging vehicle parc in Turin and Milan metropolitan belts. ECHA REACH compliance costs fragment collection network economics for core return management.
United Kingdom
Post-Brexit regulatory divergence complicates CE marking reciprocity for battery imports into Midlands assembly plants. London congestion charging accelerates mild-hybrid adoption among fleet operators, expanding duty cycles beyond simple idle-stop. Birmingham and Coventry supplier parks adapt formation lines to dual certification requirements.
Poland
Underpenetrated replacement demand in Silesia and Greater Poland provinces attracts distributor expansion as vehicle ownership rates mature. Czech and Slovak assembly plants source batteries from central European logistics hubs to minimize inbound freight costs. Warsaw-based independent networks upgrade diagnostic capabilities for start-stop system installation.
Europe Automotive Start-Stop Battery Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the European supply base. The market structure concentrates around legacy producers with dedicated AGM formation assets and integrated recycling operations, while Asian cell imports compete on lithium-ion energy density metrics. Three archetypes dominate: German-Austrian specialists with captive lead supply chains, integrated global suppliers with circular economy infrastructure, and Asian battery groups leveraging cell cost advantages. Capacity expansion and strategic partnerships constitute the primary competitive vectors as OEMs dual-source to mitigate qualification bottlenecks.
Within the European specialist tier, VARTA and Banner Batteries anchor premium OEM fitment positions through regional manufacturing proximity. Clarios occupies a position bridging technology tiers with integrated recycling operations that lower lead input cost volatility. These three exemplify the capital-intensity divergence separating AGM specialists from conventional flooded producers, with each representing distinct approaches to ECHA compliance and circular economy infrastructure deployment.
| Leading Market Players |
|---|
| East Penn Manufacturing Company |
| Banner Batteries |
| Clarios |
| Continental AG |
| VARTA |
| GS Yuasa International |
| EnerSys |
| FIAMM |
| Exide Industries |
| Others |
Supply Flow & Price Mechanics
CE marking requirements and ECHA lead substance oversight gate both supplier qualification timelines and price differentiation across OEM and aftermarket tiers. Battery producers face dual pressure: electromagnetic compatibility testing cycles compress margin recovery periods, while integrated recycling investments create cost advantages that translate into pricing power against non-compliant imports.
Pricing Analysis
Aftermarket service contracts and extended warranty programs drive lifetime value concentration for distributors serving fleet operators. Three-tier pricing structure across premium AGM, standard enhanced flooded, and economy flooded levels segments buyer archetypes by certification tolerance. Cost compression in the economy tier is intensifying because Polish and Czech independent workshops aggregate demand through price transparency platforms. Fleet procurement managers show lowest price sensitivity, prioritizing OEM-certified formulations and predictive maintenance integration over unit cost.
Supply Chain Analysis
Inbound freight costs from Asian lithium-ion cell suppliers face volatility through Rotterdam port congestion and container availability constraints on the Asia-Europe trade lane. European lead-acid production draws from German, Austrian, and Italian formation plant networks, with secondary lead supply anchored in domestic recycling infrastructure. Raw material dependencies center on lead ingot, battery-grade acid, and AGM separator matting. Single-source vulnerability concentrates in specialized AGM plate formation equipment. Distribution runs through regional logistics hubs serving OEM assembly corridors and independent aftermarket networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized electrochemical engineering expertise for AGM plate formation remains concentrated among legacy producers, constraining capacity expansion and creating acquisition premiums for qualified assets. This capability scarcity favors incumbents with captive formation lines and disadvantages entrants lacking proven saturation control protocols.
For Market Incumbents: Secure backward integration into secondary lead supply to buffer London Metal Exchange price volatility and lock in ECHA compliance cost advantages. Expand AGM formation capacity in German and Austrian industrial corridors before Battery Regulation delegated acts tighten carbon footprint qualification timelines. Clarios and VARTA demonstrate this positioning through integrated recycling operations that lower input cost exposure. For New Entrants and Emerging Players: Lead with smart battery sensor integration and predictive maintenance software to bypass capital-intensive formation asset requirements. Eastern European aftermarket channels in Poland, Czech Republic, and Hungary present the most penetrable geography, with vehicle ownership maturation outpacing diagnostic capability installation. Partner with price transparency platforms to aggregate fragmented independent workshop demand and compress incumbent distributor margins. For Investors and Strategic Acquirers: Battery Regulation delegated acts on carbon footprint declarations and recycled content quotas reshape the acquisition landscape toward producers with established circular economy infrastructure. Five-to-ten-year viability favors integrated specialists with captive lead supply chains over pure-play lithium-ion assemblers dependent on Asian cell imports. Monitor ECHA enforcement patterns on lead substance restrictions as the signal for compliance cost inflection and qualification timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| AGM Formation Capacity Expansion | Qualifies suppliers for EU Green Deal fleet mandate volumes from German OEMs. |
| Integrated Recycling Operations | Lowers lead input cost volatility and satisfies ECHA substance compliance requirements. |
| Smart Battery Sensor Integration | Enables predictive maintenance services that extend service life for fleet operators. |
| Eastern European Distribution Buildout | Captures underpenetrated replacement demand in Poland and Czech Republic markets. |
| Battery Regulation Compliance Investment | Positions producers for delegated acts on carbon footprint and recycled content quotas. |
Methodological Framework
Cross-validation between OEM procurement data and aftermarket distributor transaction records anchors the qualitative findings on technology substitution patterns. Primary interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributor operations heads, and fleet maintenance directors combined with secondary validation from vehicle production databases, KBA registration statistics, IHS Markit parc data, and ECHA regulatory filings. Bottom-up segment sizing and top-down market triangulation reconcile volume estimates across the analysis window.
Sensitivity analysis on lead price volatility, 48-volt adoption curves, and Battery Regulation implementation timelines tests forecast robustness. The analytical framework models vehicle class, propulsion architecture, battery chemistry tier, installation channel, and regional production cluster dimensions across the projection horizon. CAGRs derive from segment-level growth rate reconciliation with macroeconomic automotive demand indicators and OEM platform launch schedules. Industry-specific inputs include EU fleet CO2 mandate compliance trajectories and AGM formation capacity utilization rates.
Forecasts assume regulatory continuity in EU Green Deal mandates, ECHA REACH enforcement, and Battery Regulation delegated acts; material policy shifts would require re-modeling. Lead price volatility, lithium-ion cost parity breakthroughs, or CE marking reciprocity disruptions represent specific risk factors that could revise trajectory assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Battery Recycling
ASEAN Electric Vehicle Battery Anode Market
Transportation Battery Recycling
Europe Train Battery Market
Transportation Battery Recycling
EV Battery Recycling Services Market
Transportation Battery Recycling
Automobile Storage Battery Market
Transportation Battery Recycling
China Transportation Battery Recycling Market
Transportation Battery Recycling
Automotive Battery Recycling Market
Transportation Battery Recycling
South Korea Transportation Battery Recycling Market
Transportation Battery Recycling
Two-Wheeler Battery Market
Transportation Battery Recycling
Transportation Battery Market
Transportation Battery Recycling
Transportation Battery Recycling Market
Transportation Battery Recycling
Asia-Pacific Transportation Battery Recycling Market
Transportation Battery Recycling
Automotive Energy Recovery System Market