
 Vehicle Power Tailgate System Market | 2026-2036
Vehicle Power Tailgate System Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Power Tailgate System Market Insights
China's expanding automotive component manufacturing corridor is reshaping supply dynamics for power tailgate electromechanical systems. Robert Bosch GmbH leverages its integrated sensor-actuator platforms to dominate premium OEM channels across European and Asian markets. Johnson Electric Holdings Limited anchors its competitive position through specialized DC motor production for hands-free liftgate mechanisms. Huf Hülsbeck & Fürst GmbH & Co. KG differentiates via proprietary electronic latching systems that comply with evolving crash-safety protocols.
A vehicle power tailgate system comprises electromechanical actuators, control modules, and sensor arrays that automate rear cargo access through motorized hinge and strut mechanisms, typically operating at 12V vehicle electrical architecture with torque ratings between 400 and 600 Nm for mid-size SUV applications. Its primary purpose is to eliminate manual lifting while integrating obstacle detection and programmable height stops for user convenience and loading bay compatibility. Electric tailgate configurations now capture the dominant share of OEM fitments as hands-free operation becomes standard on mid-range crossovers, while hydraulic variants retain niche positions in commercial van upfit segments where load-bearing capacity exceeds electromechanical limits. Smart sensor integration represents the fastest-growing technology dimension, with capacitive foot-activation and radar-based proximity detection commanding premium positioning in feature hierarchies.
NHTSA Federal Motor Vehicle Safety Standards and Euro NCAP pedestrian protection protocols jointly mandate anti-entrapment responsiveness and pinch-force thresholds below 100 N across power-operated closure systems. China's MIIT automotive technical regulations and GB standards for electromagnetic compatibility add compliance layers for imported electromechanical assemblies. ISO 26262 functional safety requirements and IEC electromagnetic immunity standards further condition product development cycles for control module suppliers. Stakeholders must monitor how software-defined vehicle architectures redistribute control logic between tailgate ECUs and centralized domain controllers, as this shift threatens standalone component margins while opening subscription-based feature monetization pathways.
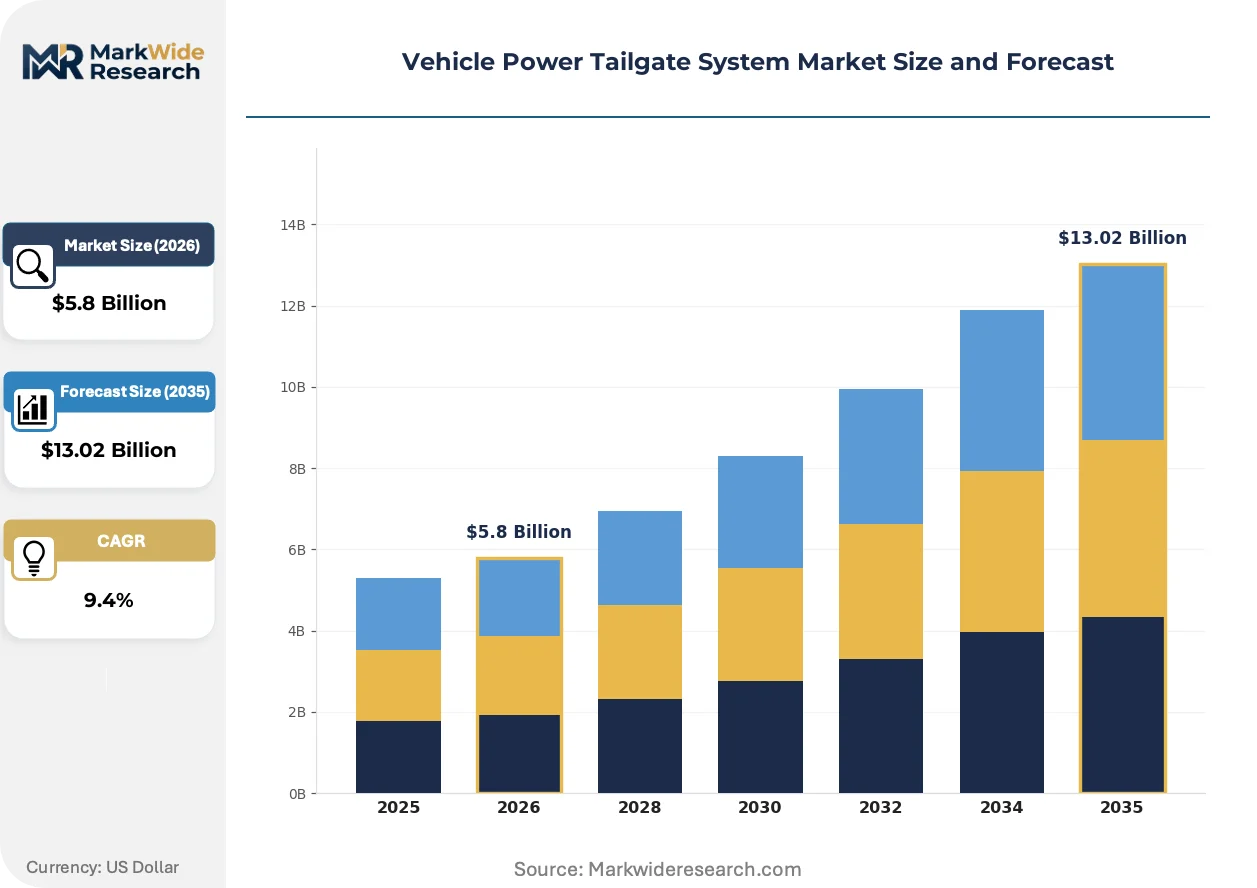
Market Dynamics
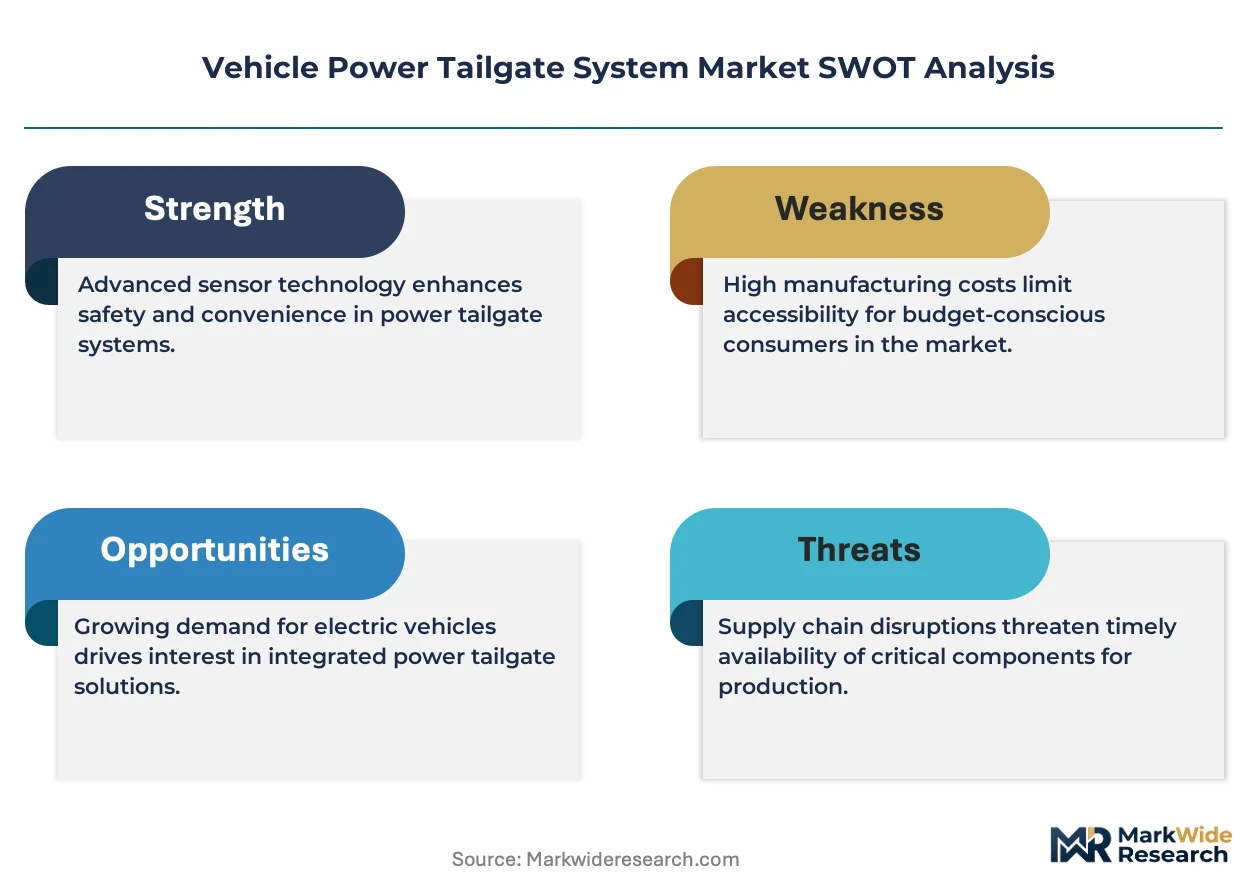
Software-defined vehicle architectures are redistributing control logic from standalone tailgate ECUs toward centralized domain controllers, compressing component margins while forcing suppliers to develop firmware monetization capabilities.
Growth Catalysts
- Hands-Free Activation Mandates:NHTSA pedestrian safety protocols now require anti-entrapment responsiveness below 100 N pinch-force thresholds, compelling OEM integration of capacitive foot-activation and radar-based proximity detection across mid-range crossover platforms.
- Electromechanical Strut Advancement:DC motor torque density improvements to 600 Nm ratings enable electromechanical systems to displace hydraulic variants in light-commercial applications previously reserved for load-bearing hydraulic mechanisms.
- Stuttgart-Munich Supplier Cluster:Premium OEM sourcing concentration around specialized Tier-1 mechatronic assembly facilities accelerates R&D cycle compression and just-in-sequence delivery capabilities for luxury SUV programs.
Market Restraints
- Rare Earth Magnet Volatility:Neodymium and dysprosium price fluctuations in DC motor permanent magnets create input cost instability for electromechanical actuator manufacturers serving volume crossover segments.
- Control Module Margin Compression:Centralized vehicle compute architectures threaten standalone tailgate ECU pricing power as domain controllers absorb sensor fusion and motor drive functions.
- Hydraulic Load-Bearing Limits:Electromechanical torque ceilings below 800 Nm preserve hydraulic dominance in commercial van upfit segments requiring sustained cargo bay load capacity.
Strategic Opportunities
- Subscription Feature Monetization:Over-the-air activation of programmable height memory and gesture customization creates recurring revenue streams as firmware-defined functionality decouples from hardware bill-of-materials.
- India PLI Scheme Alignment:Automotive component manufacturing incentives under India's production-linked incentive scheme attract electromechanical assembly investment for export-oriented supply to ASEAN markets.
- Radar-Capacitive Sensor Fusion:Convergence of millimeter-wave proximity detection with capacitive foot-activation enables all-weather hands-free operation previously compromised by rain and snow interference.
Industry Challenges
- ISO 26262 Functional Safety Certification:ASIL-D compliance timelines for anti-pinch algorithms extend product development cycles 8-14 months, straining supplier engineering bandwidth.
- Legacy Vehicle Electrical Architecture Integration:12V power distribution limitations in older platforms constrain smart sensor deployment without costly harness redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Power Tailgate System Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $13.02 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Tailgate, Hydraulic Tailgate, Manual Tailgate, Automatic Tailgate End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: Smart Sensors, Power-Assist Systems, Remote Control, Safety Mechanisms Feature: Hands-Free Operation, Adjustable Height, Anti-Pinch Technology, Integrated Lighting |
| Companies Covered | Aisin Seiki Co. Ltd., Johnson Electric Holdings Limited, Robert Bosch GmbH, ZF Friedrichshafen AG, Huf Hülsbeck & Fürst GmbH & Co. KG, Continental AG, Brose Fahrzeugteile SE & Co. KG, Stabilus GmbH, Magna International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Power Tailgate System Market Trends and Innovations
Capacitive and radar-based sensing modalities are displacing simple switch mechanisms as primary human-machine interfaces, while centralized compute architectures rewrite component supplier value capture models.
Smart sensor integration is digitizing tailgate operation from mechanical actuation toward software-defined experience layers. Capacitive foot-activation modules with programmable sensitivity thresholds now ship standard on mid-range crossovers from Volkswagen, Hyundai, and Ford. This digitization compresses hardware differentiation cycles and shifts competitive advantage toward firmware update velocity and feature subscription architecture.
Euro NCAP pedestrian protection protocols now mandate anti-entrapment force limits and obstacle detection responsiveness across all power-operated closure systems. The industrial consequence accelerates sensor fusion requirements and elevates functional safety certification to ASIL-D thresholds. European premium OEMs and their Stuttgart-based Tier-1 suppliers absorb the highest compliance burden, passing costs through platform-shared module designs.
Fleet procurement of commercial vans now specifies hands-free liftgate functionality as standard equipment, compressing the technology diffusion cycle from luxury passenger vehicles toward vocational applications. Upfitters and fleet management companies displace traditional dealer channel distribution for this segment. Germany and the United States exhibit the most pronounced fleet specification pressure, driven by last-mile delivery operator ergonomics mandates.
Vehicle Power Tailgate System Market Segmentation
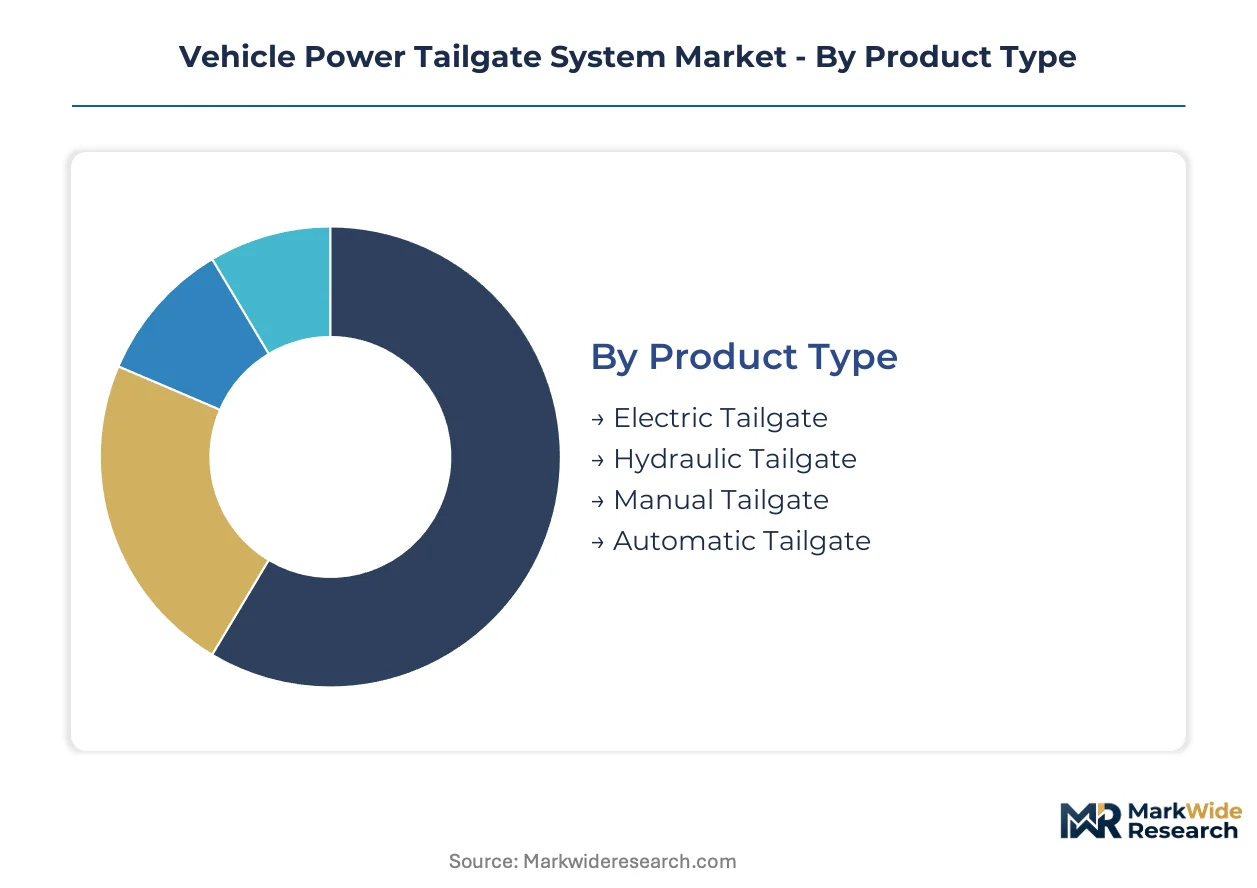
Power tailgate system segmentation reveals how component complexity and integration depth vary across vehicle platforms and supply tiers. Understanding these divisions exposes where margin pools concentrate and which technology trajectories reshape competitive positioning.
Product Type:
After-sales service intensity diverges sharply across product categories, with electromechanical systems demanding specialized diagnostic tooling and hydraulic variants requiring fluid maintenance protocols.
- Electric Tailgate:DC motor-driven strut assemblies operating at 12V architecture with 400-600 Nm torque ratings dominate mid-size SUV fitments. Demand concentrates in Germany's Stuttgart-Munich corridor where premium OEMs source mechatronic assemblies from specialized Tier-1 clusters.
- Hydraulic Tailgate:Load-bearing piston mechanisms sustain sustained cargo bay capacity exceeding 800 Nm for commercial van upfit segments. Fleet procurement specifications in Germany and the United States preserve hydraulic dominance where electromechanical torque ceilings fall short.
- Manual Tailgate:Counterbalanced hinge systems with gas spring assist retain economy vehicle positions where power operation remains optional.
- Automatic Tailgate:Integrated motor-strut combinations with programmable height memory span premium and mid-range crossover platforms.
Electric tailgate holds the largest share; momentum sits with automatic tailgate configurations as hands-free operation becomes standard equipment.
End User:
Cost tier stratification separates captive OEM supply relationships from independent aftermarket channels, with Tier-1 suppliers capturing the highest value-added positions.
- OEMs:Original equipment manufacturers specify integrated tailgate modules during platform development, locking in multi-year supply agreements with mechatronic specialists. Volkswagen, Hyundai, and Ford now ship capacitive foot-activation standard on mid-range crossovers.
- Tier-1 Suppliers:Specialized assembly facilities around Stuttgart and Munich compress R&D cycles and deliver just-in-sequence capabilities for luxury SUV programs.
- Aftermarket Providers:Retrofit kit distributors serve aging vehicle populations and commercial fleet extensions outside factory warranty coverage.
- Vehicle Assemblers:Contract manufacturing operations integrate power tailgate modules during final assembly without direct component sourcing authority.
OEMs hold the largest share; momentum sits with Tier-1 suppliers as centralized domain controllers force firmware monetization capabilities.
Technology:
Application-specific technology deployment separates convenience-oriented passenger vehicles from safety-critical commercial implementations.
- Smart Sensors:Capacitive foot-activation and radar-based proximity detection modules enable all-weather hands-free operation. NHTSA pedestrian safety protocols now mandate anti-entrapment responsiveness below 100 N pinch-force thresholds, compelling sensor fusion integration.
- Safety Mechanisms:Anti-pinch algorithms with ASIL-D functional safety certification extend product development cycles 8-14 months. Euro NCAP protocols elevate compliance burdens for European premium OEMs and their Tier-1 partners.
- Power-Assist Systems:Motorized hinge and strut mechanisms automate rear cargo access through electromechanical actuation.
- Remote Control:Key fob and smartphone-activated tailgate operation extends convenience functionality across vehicle classes.
Smart sensors hold the largest share; momentum sits with safety mechanisms as ISO 26262 certification becomes mandatory.
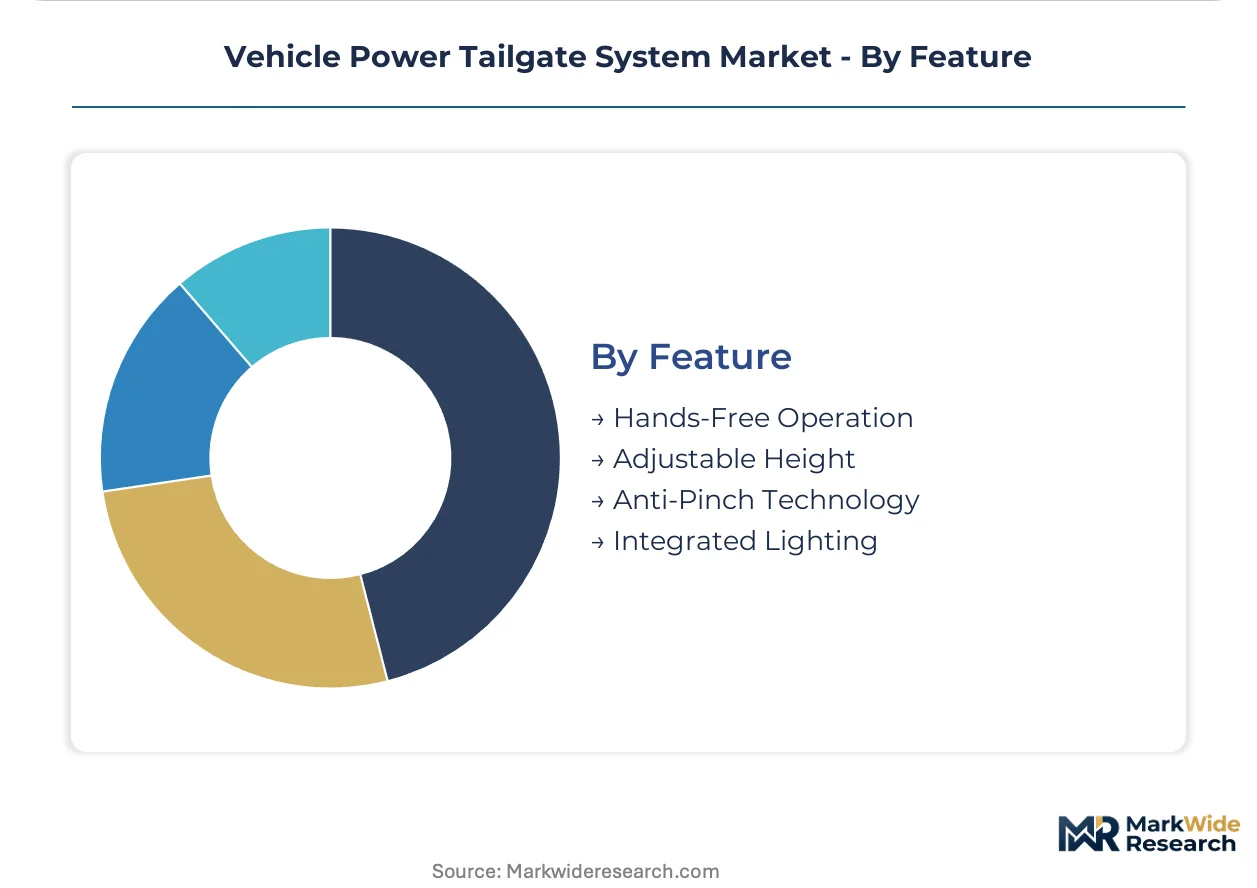
Feature:
Customer type preferences stratify feature hierarchies, with fleet operators prioritizing ergonomic loading solutions and retail buyers emphasizing convenience personalization.
- Hands-Free Operation:Capacitive foot-activation with programmable sensitivity thresholds now ships standard on mid-range crossovers. Radar-capacitive sensor fusion enables all-weather performance previously compromised by precipitation interference.
- Anti-Pinch Technology:Force-limiting algorithms and obstacle detection modules comply with NHTSA and Euro NCAP entrapment protection mandates. ASIL-D certification timelines strain supplier engineering bandwidth.
- Adjustable Height:Programmable memory stops accommodate loading bay compatibility and user stature variations.
- Integrated Lighting:LED cargo bay illumination merges with tailgate control modules for unified electrical architecture.
Hands-free operation holds the largest share; momentum sits with anti-pinch technology as regulatory mandates tighten force thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mechatronic assembly specialists cluster around Stuttgart and Munich in Germany, while China's expanding automotive corridor reshapes electromechanical sourcing patterns. Premium OEM procurement concentrates in Western Europe, with regulatory mandates from NHTSA and Euro NCAP accelerating sensor integration requirements.
United States
Fleet procurement from last-mile delivery operators drives hands-free liftgate specifications as standard equipment. NHTSA pedestrian safety protocols mandate anti-entrapment responsiveness below 100 N pinch-force thresholds. The Southeast manufacturing corridor, spanning Tennessee and South Carolina, hosts final assembly operations for mid-range crossover platforms.
Germany
Premium SUV and crossover platforms anchor OEM demand for sophisticated tailgate assemblies. Euro NCAP protocols elevate functional safety certification to ASIL-D thresholds for anti-pinch algorithms. The Stuttgart-Munich supplier cluster compresses R&D cycles and delivers just-in-sequence capabilities for luxury vehicle programs.
China
Expanding automotive component manufacturing corridors reshape supply dynamics for electromechanical systems. MIIT automotive technical regulations and GB standards for electromagnetic compatibility add compliance layers for imported assemblies. Yangtze River Delta production hubs scale DC motor manufacturing for regional OEM fitments.
Japan
Domestic OEMs integrate capacitive foot-activation modules across mid-range crossover lineups. METI industrial policy supports electromechanical component R&D through targeted manufacturing incentives. Kanto region engineering centers develop radar-based proximity detection for all-weather operation.
India
Automotive component manufacturing incentives under the PLI scheme attract electromechanical assembly investment for export-oriented supply. BIS technical standards condition product certification timelines for imported control modules. Tamil Nadu and Maharashtra production corridors scale assembly operations for ASEAN market distribution.
Vehicle Power Tailgate System Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in motor and sensor supply. The vendor base organizes around three archetypes: diversified automotive suppliers with integrated mechatronic portfolios, specialized actuator manufacturers with torque density expertise, and electronic latching specialists with proprietary safety algorithms. Competitive moves concentrate on firmware monetization capabilities and strategic partnerships with domain controller suppliers.
Within the diversified supplier tier, Robert Bosch GmbH and Continental AG represent platform integrators with sensor-actuator breadth, while Johnson Electric Holdings Limited exemplifies the specialized motor manufacturer archetype. Huf Hülsbeck & Fürst GmbH & Co. KG occupies a position among electronic latching specialists. These companies anchor competitive positioning across European and Asian OEM channels without dominating any single technology vector.
| Leading Market Players |
|---|
| Aisin Seiki Co. Ltd. |
| Johnson Electric Holdings Limited |
| Robert Bosch GmbH |
| ZF Friedrichshafen AG |
| Huf Hülsbeck & Fürst GmbH & Co. KG |
| Continental AG |
| Brose Fahrzeugteile SE & Co. KG |
| Stabilus GmbH |
| Magna International Inc. |
| Others |
Pricing and Supply Chain Analysis
Stuttgart-Munich Tier-1 clusters anchor global capacity for sophisticated mechatronic tailgate assemblies, translating concentrated R&D proximity into premium pricing power for ASIL-D certified modules serving luxury SUV programs.
Pricing Analysis
NHTSA and Euro NCAP pedestrian safety protocols dictate the pricing tier structure across the Vehicle Power Tailgate System Market. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified anti-pinch systems from basic motor-strut configurations and unbranded aftermarket retrofit kits. Pricing pressure stems from centralized domain controller architectures absorbing standalone ECU functionality and compressing component margins. Fleet procurement operators exhibit highest price sensitivity due to volume scale requirements, while premium OEMs prioritize certification grade and just-in-sequence delivery reliability over unit cost.
Supply Chain Analysis
Neodymium and dysprosium permanent magnets for DC motor torque density improvements draw from China, with secondary processing concentration in Japan and Germany. Electromechanical actuator manufacturers rest on rare earth magnet feedstocks, specialized PCB assemblies for control modules, and injection-molded polymer housings. Single-source vulnerability in rare earth magnet refining creates supply chain risk exposure for volume crossover segment suppliers. Distribution runs through captive OEM supply agreements with multi-year platform lock-ins, supplemented by aftermarket retrofit channels serving aging vehicle populations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined vehicle architectures fragment competitive positioning by redistributing control logic toward centralized domain controllers, creating white-space opportunities for firmware monetization specialists and sensor fusion providers.
For Market Incumbents: Pre-empt margin compression from domain controller consolidation by developing subscription-based feature activation capabilities and deepening captive supply relationships with premium OEM platform engineering teams. Secure backward integration into rare earth magnet sourcing to offset input cost volatility threatening electromechanical actuator profitability.
For New Entrants and Emerging Players: India's Tamil Nadu and Maharashtra production corridors offer underpenetrated manufacturing capacity for export-oriented electromechanical assembly serving ASEAN markets. Target commercial van upfit segments where hydraulic torque requirements preserve niche demand outside electromechanical dominance. Pursue PLI scheme alignment as the primary go-to-market angle for cost-competitive DC motor production.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified automotive suppliers seeking to divest non-core mechatronic portfolios amid software-defined vehicle transition pressures. Long-term viability centers on firmware monetization capabilities and domain controller partnership access rather than hardware scale alone. Watch for consolidation signals among Stuttgart-Munich Tier-1 clusters as R&D cycle compression intensifies.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Actuator Platform Integration | Robert Bosch GmbH leverages unified hardware-software stacks to dominate premium OEM channels across European markets. |
| Rare Earth Magnet Backward Integration | Johnson Electric Holdings Limited secures captive magnet supply to stabilize DC motor production costs for hands-free liftgate mechanisms. |
| ASIL-D Certification Investment | Huf Hülsbeck & Fürst GmbH & Co. KG extends electronic latching development cycles to meet Euro NCAP functional safety mandates. |
| India PLI Scheme Manufacturing Footprint | Electromechanical assembly investment in Tamil Nadu corridors targets export-oriented supply to ASEAN crossover platforms. |
| Radar-Capacitive Sensor Fusion Partnership | Millimeter-wave proximity detection convergence enables all-weather hands-free operation for mid-range crossover specifications. |
Research Methodology
Cross-validation between OEM platform engineering disclosures and Tier-1 supplier procurement patterns anchors the qualitative findings in this study. Primary interviews with vehicle platform engineers, Tier-1 procurement directors, aftermarket distribution managers, and mechatronic R&D specialists combined with secondary validation from NHTSA regulatory filings, Euro NCAP test protocols, vehicle production databases, and IHS Markit registration data. Bottom-up component demand modeling and top-down vehicle production triangulation ensure segmentation integrity across the analysis window.
Calibration against historical fitment rates and technology diffusion curves shapes the analytical framework. Segmentation dimensions span vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster throughout the forecast period. CAGRs derive from fitted technology adoption curves and platform lifecycle replacement patterns. Industry-specific forecast inputs include hands-free activation mandate compliance timelines and rare earth magnet price trajectory assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by diversified automotive suppliers or sudden domain controller architecture shifts would shift outcomes. Cross-checking against vehicle platform engineering roadmaps and regulatory enforcement schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
South Korea Automotive Engine Oils Market
Powertrain
Automotive Torque Vectoring System Market
Powertrain
Russia Electro Hydraulic Power Steering Market
Powertrain
Automotive Transmission System Market
Powertrain
Automotive Power Modules Market
Powertrain
Automotive Clutch Slave Cylinder Market
Powertrain
Transmission Shift Actuator Market
Powertrain
Europe Turbocharger Market
Powertrain
Tuning Box Market
Powertrain
Asia Pacific Electrically Powered Hydraulic Steering Market
Powertrain
Motor Vehicle Carburetors Market
Powertrain
Automotive Intermediate Shaft Market
Powertrain
Europe Internal Combustion Engines Market
Powertrain
Middle East and Africa Internal Combustion Engines Market
Powertrain
Automotive Vacuum Brake Booster Market
Powertrain
Automotive Counter Shaft Market