
 Automotive Structural Steel Market | 2026-2036
Automotive Structural Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Structural Steel Market Outlook
Electric vehicle OEMs is redrawing procurement priorities across the automotive structural steel value chain, shifting volume toward lightweight, high-strength grades that preserve range without compromising safety architecture. ArcelorMittal leverages its integrated R&D platform to develop tailored press-hardening solutions for battery enclosure applications. POSCO sustains dominant supply relationships with Korean and Japanese automakers through captive hot-rolled capacity and proprietary high-tensile formulations. Tata Steel anchors South Asian demand with localized production of cold-rolled structural grades serving both domestic OEMs and export-oriented tier-1 suppliers.
Automotive structural steel encompasses carbon and alloy steel grades engineered to absorb impact energy, maintain dimensional stability under dynamic loading, and enable complex forming operations, typically achieving tensile strengths from 300 MPa to over 1,500 MPa in advanced variants. Hot rolled steel occupies the highest volume share in chassis and underbody applications where surface finish tolerance is secondary to yield strength and cost efficiency. Dual phase steel represents the fastest-expanding product category as OEMs deploy it in B-pillar reinforcements and roof rails to meet stringent side-impact requirements without adding mass. Cold rolled steel commands premium positioning in visible body panels and closure assemblies where surface quality and precise gauge control determine downstream paint and assembly outcomes.
The EPA and NHTSA in the United States enforce fleet-wide fuel economy and crash safety standards that directly dictate minimum steel strength requirements and gauge thickness trade-offs in vehicle architecture. The EU Green Deal and REACH frameworks from ECHA impose carbon intensity disclosures and restricted substance protocols that reshape mill-level process investments and scrap recycling mandates across European supply chains. Stakeholders must monitor evolving battery platform architectures and corresponding structural load-path redesigns to anticipate which steel grades will capture the next wave of OEM specification lock-ins.
Market Dynamics
Electric vehicle platform architectures are forcing a wholesale recalibration of structural steel specifications, as battery mass penalties compel OEMs to extract weight savings from body-in-white assemblies without degrading crash performance.
Growth Catalysts
- EU Green Deal carbon intensity mandates:Steel mills across Germany, France, and Italy are accelerating electric arc furnace investments to supply automakers with verified low-carbon structural grades.
- Dual phase steel adoption:OEMs in the United States and China are specifying DP980 and DP1180 grades for B-pillar and roof rail reinforcements to meet side-impact protocols.
- Press-hardening process maturation:Tier-1 stampers in Mexico and Eastern Europe are installing new hot-forming lines to localize supply of 1500 MPa-class components.
Market Restraints
- Iron ore and scrap price volatility:Input cost swings of 30-40 percent within single quarters compress mill margins and destabilize contract pricing.
- Supply concentration in East Asian flat-rolled capacity:Over 60 percent of global automotive-grade hot-rolled coil originates from integrated mills in China, South Korea, and Japan.
- Aluminum extrusion substitution:Battery enclosure manufacturers are specifying 6xxx-series aluminum for floor pans and cross-members to achieve 40 percent mass reduction versus steel equivalents.
Strategic Opportunities
- India domestic production localization:PLI scheme incentives for specialty steel are attracting greenfield investments in cold-rolling and continuous annealing capacity.
- Third-generation advanced high-strength steel:TWIP and Q&P grades with 20-30 percent improved formability are opening applications in complex-draw closure panels previously reserved for aluminum.
- Direct-reduced iron and hydrogen-reduced steel:Swedish and German pilot projects are validating near-zero-emission production routes for premium automotive contracts.
Industry Challenges
- Hot-forming die engineering talent scarcity:The specialized thermomechanical simulation and tribology expertise required for press-hardening tool design concentrates in a handful of German and Japanese engineering consultancies.
- Multi-material joining certification:OEM weld-bond specifications for steel-to-aluminum and steel-to-composite interfaces demand extended validation cycles that delay platform launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Structural Steel Market |
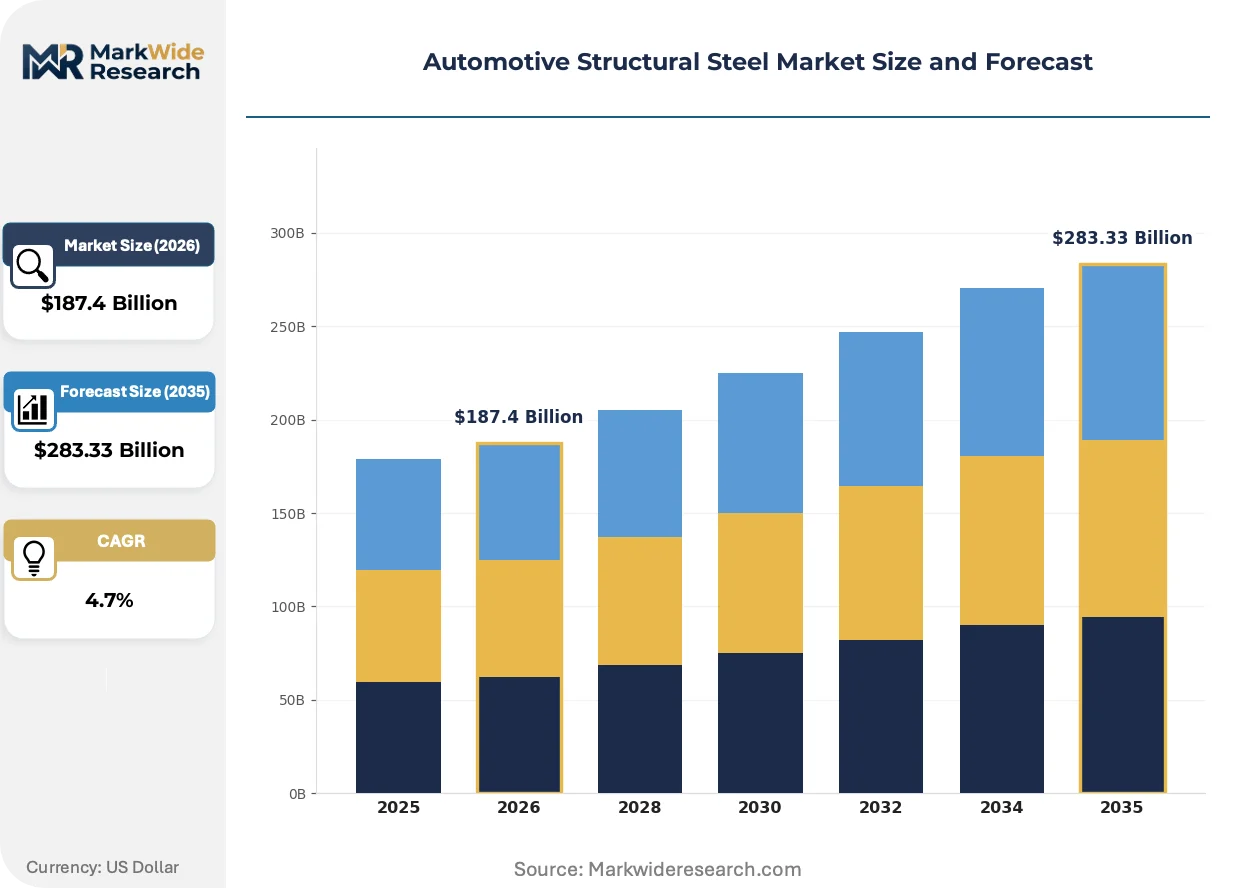
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $283.33 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Rolled Steel, Cold Rolled Steel, High Strength Steel, Dual Phase Steel Application: Body Structure, Chassis, Suspension, Reinforcement End User: Automakers, Tier-1 Suppliers, Aftermarket Providers, OEMs Technology: Welding, Stamping, Casting, Machining |
| Companies Covered | ArcelorMittal, POSCO, Nippon Steel Corporation, thyssenkrupp AG, Tata Steel, United States Steel Corporation, Hyundai Steel, JSW Steel Limited, BAOSTEEL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Structural Steel Market Strategic Shifts
Material-process combinations are evolving faster than specification standards can codify them, creating temporary competitive windows for early movers in next-generation forming technologies and low-carbon metallurgy.
Third-generation advanced high-strength steel with twinning-induced plasticity is supplanting first-generation dual phase grades in door ring and A-pillar applications. European and Korean OEMs have locked in TWIP specifications for 2027-2028 platform cycles. The shift is compressing demand for conventional high-strength low-alloy grades above 500 MPa.
REACH Annex XIV authorization requirements for nickel and chromium compounds are forcing European mills to reformulate surface treatment chemistries in galvanizing lines. The regulatory pressure has triggered a wave of zinc-magnesium coating substitutions that alter corrosion warranty calculations. German automakers are now requiring full material disclosure down to 0.1 percent concentration thresholds for all structural steel purchases.
Direct mill-to-OEM contracting is eroding the traditional distributor tier for high-volume structural grades. Tier-1 stampers in the US Midwest and China's Yangtze River Delta are establishing consignment inventory arrangements that transfer working capital burden upstream. The disintermediation is most pronounced in just-in-sequence supply for electric vehicle skateboard platforms where coil-to-blank lead times compress below 72 hours.
Automotive Structural Steel Market Segmentation
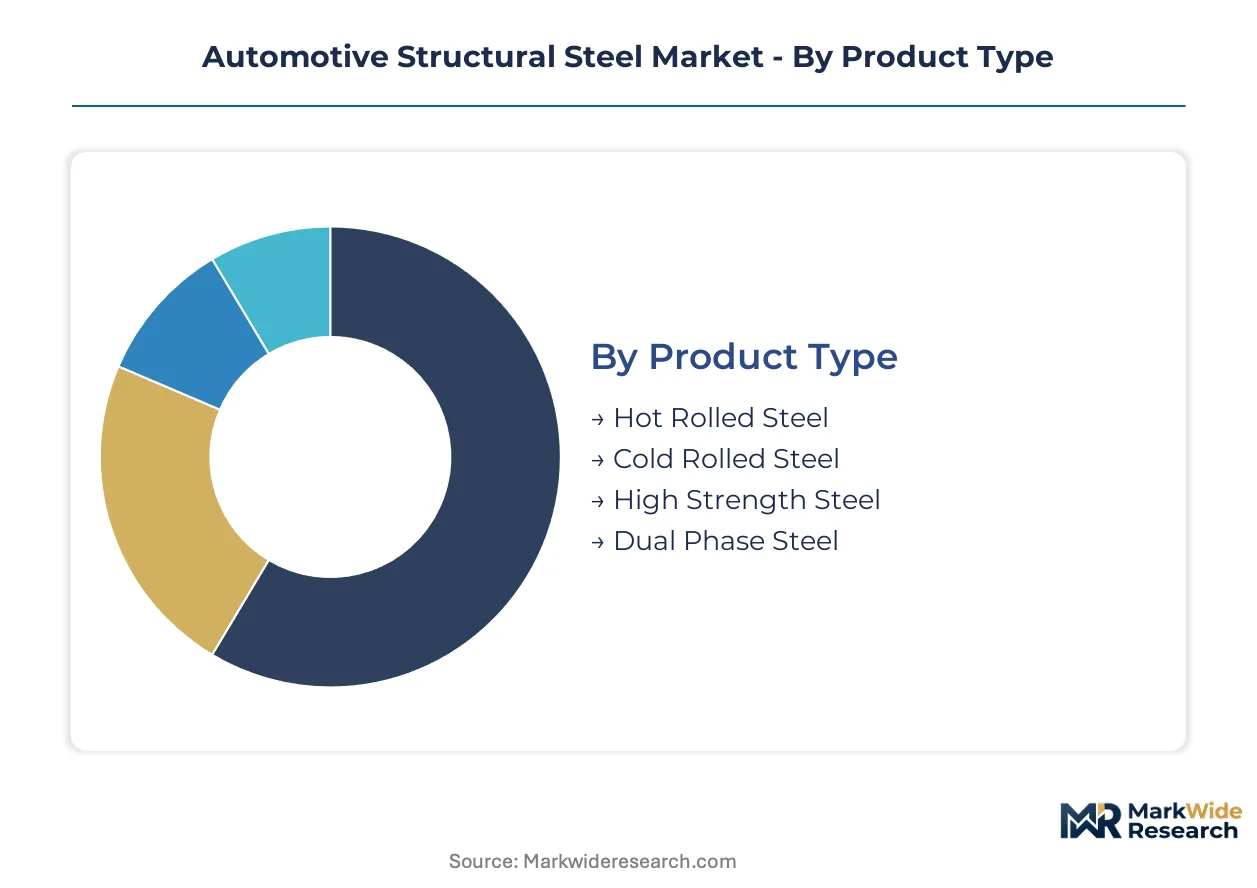
Automotive structural steel segmentation reveals how material specifications cascade through distinct value pools. Product grades, application requirements, and manufacturing technologies each concentrate margin in different supply chain tiers, forcing suppliers to choose where technical differentiation commands premium pricing.
Product Type:
Margin pools concentrate most heavily in advanced high-strength grades where metallurgical R&D creates specification lock-ins with OEM engineering teams.
- Hot Rolled Steel:Manufactured above recrystallization temperature with scale-oxidized surfaces and dimensional tolerances suited to structural members hidden from view. Demand concentrates in chassis rails and underbody cross-members for commercial vehicles across the US Midwest and China's Yangtze River Delta, where cost-per-kilogram dominates procurement criteria.
- Cold Rolled Steel:Processed below recrystallization temperature to deliver superior surface finish, tight gauge control, and enhanced formability for exposed body panels. German and Japanese automakers specify cold-rolled grades for hoods, doors, and fenders where paint adhesion and dent resistance determine warranty exposure.
- High Strength Steel:Alloy formulations achieving 500-800 MPa tensile strength through controlled rolling and microalloying additions. Serves crash management systems and seat structures where energy absorption must balance against gauge thickness penalties.
- Dual Phase Steel:Martensitic islands dispersed in ferritic matrices deliver exceptional work-hardening rates for complex stampings. Korean OEMs specify DP980 and DP1180 grades for B-pillar reinforcements meeting side-impact protocols without mass penalties.
The dominant share belongs to Hot Rolled Steel, while Dual Phase Steel is closing the gap fastest.
Application:
Application segmentation tracks how structural load-path redesign for electric vehicle platforms is reallocating volume across vehicle zones.
- Body Structure:Encompasses unibody rails, pillars, roof bows, and floor pans forming the primary occupant safety cell. Chinese joint ventures and European premium OEMs are localizing press-hardened steel supply for body structures to offset battery mass while preserving five-star crash ratings.
- Chassis:Frame rails, subframes, and cradles carrying powertrain and suspension loads. Mexican stampers serving Detroit Three automakers dominate chassis component supply through integrated hot-forming and welding operations.
- Suspension:Control arms, links, and knuckles requiring fatigue resistance under cyclic loading. Demand clusters with German and Japanese tier-1 suppliers holding proprietary heat-treatment qualifications.
- Reinforcement:Bumper beams, door beams, and roof rail inserts providing localized crash protection. Specified increasingly in 1500 MPa press-hardened grades as OEMs pursue weight-optimized safety architectures.
Body Structure commands the largest volume position, though Reinforcement applications are expanding most quickly as crash standards tighten.
End User:
End user segmentation exposes divergent procurement patterns between integrated OEM engineering teams and specialized tier-1 stampers.
- Automakers:Integrated vehicle manufacturers with direct mill relationships for high-volume structural grades. Volkswagen, Toyota, and BYD negotiate annual contracts with ArcelorMittal and POSCO for specified coil dimensions and metallurgical properties.
- Tier-1 Suppliers:Specialized stampers and assembly houses converting steel coil into welded subassemblies. Canadian and Thai tier-1 operations are installing continuous annealing lines to capture value-added processing previously performed at mills.
- Aftermarket Providers:Distributors and remanufacturers serving collision repair and vehicle modification markets. Fragmented across regional distributors with limited specification influence.
- OEMs:Original equipment manufacturers with captive stamping capacity for proprietary vehicle architectures. Tesla and Rivier maintain direct mill contracts for battery enclosure steel to protect intellectual property around structural integration.
Automakers retain the dominant procurement position, while Tier-1 Suppliers are capturing share fastest through just-in-sequence integration.
Technology:
Technology segmentation maps how process capabilities determine which suppliers qualify for platform-specific contracts.
- Welding:Resistance spot, laser, and arc processes joining stamped components into structural assemblies. German and Japanese equipment suppliers dominate laser welding system supply for aluminum-steel mixed joints.
- Stamping:Mechanical and hydraulic press operations forming flat coil into three-dimensional structural members. Mexican and Eastern European stampers are adding hot-forming capacity to localize 1500 MPa component supply.
- Casting:Liquid metal solidification producing complex geometries impractical to stamp. Limited to suspension nodes and engine cradle attachments where topology optimization demands irregular shapes.
- Machining:Material removal processes finishing cast or forged blanks to precise tolerances. Concentrated in powertrain-adjacent structural interfaces requiring dimensional accuracy beyond stamping capabilities.
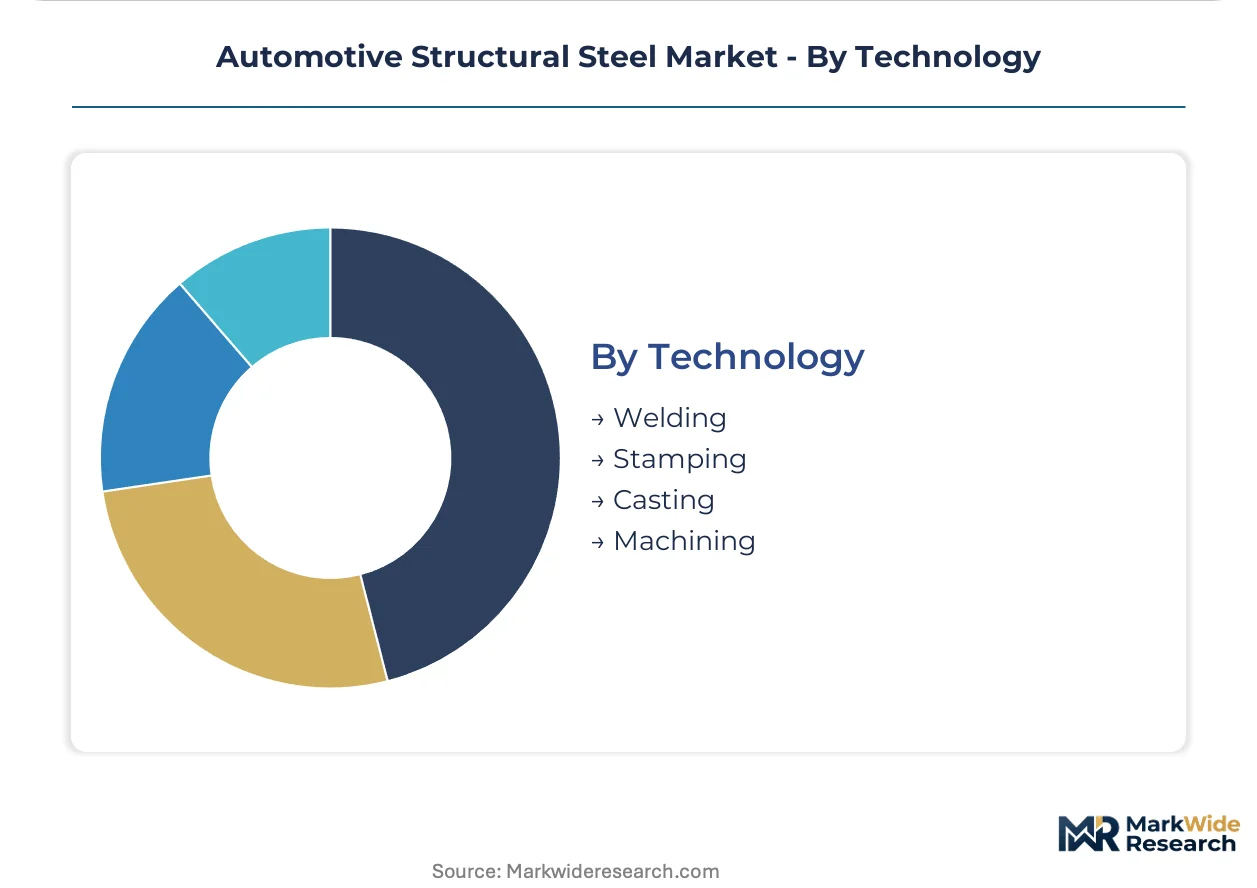
Stamping holds the dominant technology position, while Welding is gaining share fastest as multi-material joining complexity increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated mills in China, South Korea, and Japan command over sixty percent of global automotive-grade hot-rolled coil capacity. This concentration shapes procurement patterns across every major vehicle-producing region.
China
Domestic automakers and joint ventures are localizing structural steel supply chains to reduce import dependency. The MIIT enforces GB standards for vehicle safety that mandate specific high-strength grades in passenger car architectures. The Yangtze River Delta hosts the densest cluster of cold-rolling and continuous annealing lines serving BYD and SAIC Motor.
United States
Detroit Three automakers negotiate annual contracts with integrated producers for specified coil dimensions and metallurgical properties. The EPA and NHTSA enforce fleet-wide fuel economy and crash safety standards that dictate minimum steel strength requirements. Mexican stampers in Nuevo León and the Bajío Region are adding hot-forming capacity to localize 1500 MPa component supply.
Germany
Premium OEMs specify cold-rolled grades for exposed body panels where paint adhesion determines warranty exposure. The EU Green Deal and REACH frameworks impose carbon intensity disclosures that reshape mill-level process investments. The Ruhr industrial corridor and Bavarian automotive clusters anchor demand for press-hardened steel in electric vehicle platforms.
India
Domestic production localization is accelerating under PLI scheme incentives for specialty steel capacity. The BIS certifies automotive steel grades that align with global crashworthiness protocols. Gujarat and Maharashtra are attracting greenfield investments in cold-rolling and continuous annealing lines to serve Maruti Suzuki and Tata Motors.
South Korea
Hyundai Motor and Kia maintain captive supply relationships through proprietary high-tensile formulations. The MFDS does not regulate automotive materials directly, but export requirements to the US and EU drive compliance investments. The Busan-Ulsan industrial belt concentrates hot-rolled capacity serving both domestic OEMs and Japanese automakers.
Automotive Structural Steel Market Competitive Environment
Concentration sits with integrated steel producers possessing captive R&D platforms and hot-rolled capacity. The market structure favors scale-driven players with backward integration into iron ore and metallurgical coal. Two strategic archetypes dominate: diversified global miners with steel divisions, and regional specialists with automotive-certified mills. Competitive moves center on electric arc furnace investments for low-carbon grades and hot-forming line partnerships with tier-1 stampers.
Among diversified global producers, ArcelorMittal and POSCO exemplify the integrated archetype with captive R&D platforms. Tata Steel occupies a position as the dominant South Asian supplier with localized production of cold-rolled structural grades. These three anchors demonstrate how metallurgical specification lock-ins with OEM engineering teams create defensive competitive positions.
| Leading Market Players |
|---|
| ArcelorMittal |
| POSCO |
| Nippon Steel Corporation |
| thyssenkrupp AG |
| Tata Steel |
| United States Steel Corporation |
| Hyundai Steel |
| JSW Steel Limited |
| BAOSTEEL |
| Others |
Value Chain & Pricing Dynamics
Mill-level capacity utilization above 85 percent in integrated Chinese and South Korean plants anchors price floors for automotive-grade hot-rolled coil, concentrating bargaining power among a handful of coastal producers while forcing tier-1 stampers to absorb working capital burdens through consignment arrangements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates OEM-direct contracts from distributor spot purchases and scrap-fed mini-mill supply. Price differentiation hinges on metallurgical certification grade and annual volume commitments above 50,000 tonnes. Cost compression in cold-rolled and advanced high-strength grades is intensifying because electric vehicle OEMs are consolidating specification lists to reduce qualification overhead. Tier-1 stampers serving just-in-sequence programs exhibit highest price sensitivity, while premium German and Japanese automakers prioritize performance guarantees over per-kilogram savings.
Supply Chain Analysis
Strait of Malacca transit underwrites raw material flows for over half of global automotive structural steel output, exposing mills to bunker fuel volatility and port congestion cascades. Supply concentrates in China, South Korea, and Japan for hot-rolled coil, while Germany and Mexico anchor cold-rolling and hot-forming capacity. The chain draws from iron ore, metallurgical coal, and zinc coating inputs. Single-source vulnerability concentrates in East Asian flat-rolled capacity. Distribution runs through direct mill-to-OEM contracts and tier-1 stamper consignment inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation among electric vehicle OEMs into fewer global platform architectures is shifting procurement leverage toward buyers capable of locking in multi-year metallurgical specifications across entire vehicle programs.
For Market Incumbents: Fortify specification lock-ins with OEM engineering teams by deepening captive R&D in third-generation advanced high-strength steel grades. Invest in continuous annealing capacity in India and Mexico to defend against emerging low-cost entrants. Aluminum extrusion substitution for battery enclosures represents the most acute substitution threat requiring metallurgical response. For New Entrants and Emerging Players: Certification fast-track through BIS automotive grade approval in India opens white-space access to Maruti Suzuki and Tata Motors supply chains. Target the reinforcement application segment where 1500 MPa press-hardened steel demand outpaces qualified local supply. Pursue toll-processing partnerships with established cold-rollers to bypass capital-intensive mill construction. For Investors and Strategic Acquirers: Tier-1 stampers with hot-forming line installations and OEM weld-bond qualifications represent the most defensible acquisition archetype for exposure to electric vehicle platform volumes. Long-term viability rests on proximity to battery assembly hubs and capability to serve multi-material joining specifications. Monitor hydrogen-reduced steel pilot project validation as the inflection signal for carbon intensity premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Arc Furnace Conversion | Swedish and German mills validate near-zero-emission routes for EU Green Deal compliance. |
| Hot-Forming Line Partnership | Mexican stampers in Nuevo León localize 1500 MPa component supply for Detroit Three platforms. |
| Third-Generation AHSS R&D Lock-in | TWIP and Q&P grade specifications for 2027-2028 platform cycles compress competitor access. |
| Direct Mill-to-OEM Contracting | Consignment inventory arrangements transfer working capital burden upstream to integrated producers. |
| Multi-Material Joining Certification | German equipment suppliers dominate laser welding systems for aluminum-steel mixed joints. |
Study Parameters
Initial hypotheses were tested against primary input from OEM platform engineers, tier-1 supplier procurement directors, and hot-forming line operators and refined through secondary validation against customs trade data, SEC filings from integrated steel producers, vehicle production databases, and IHS Markit registration data. Bottom-up coil consumption estimates triangulated with top-down steel intensity per vehicle class projections.
Variance decomposition across the projection horizon isolates volume drivers by propulsion architecture, content per vehicle, and regional production cluster shifts. CAGRs were derived from segment-level growth rate reconciliation with macro steel demand forecasts. Industry-specific inputs include battery platform architecture roadmaps and crashworthiness standard evolution timelines.
Decision-makers should treat outputs as directional under assumptions of sustained electric vehicle penetration and stable iron ore supply; material deviation in scrap-fed mini-mill cost competitiveness or aluminum substitution rates would warrant model refresh. Practitioners should keep alternative scenarios live as EU carbon border adjustment mechanisms and hydrogen-reduced steel cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Fuel Tank Covers Market
Automotive Interior & Exterior
Automotive Dashboard Market
Automotive Interior & Exterior
Automotive Airbag Fabric Market
Automotive Interior & Exterior
Bumper Sticker Market
Automotive Interior & Exterior
Automotive Decorative Exterior Trim Market
Automotive Interior & Exterior
Door Panel Market
Automotive Interior & Exterior
Automotive Digital Rear View Mirror Market
Automotive Interior & Exterior
Automotive Solar Film Market
Automotive Interior & Exterior
Europe Automotive Wrap Films Market
Automotive Interior & Exterior
China Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Clear Coat Paint Market
Automotive Interior & Exterior
Automotive Climate Control Market
Automotive Interior & Exterior
Automotive Roof Liners Market
Automotive Interior & Exterior
Two Wheeler Backrest Market
Automotive Interior & Exterior
Automotive Headlamp Reflector Market
Automotive Interior & Exterior
Automotive Upholstery Market