
 Automotive Camless Engine Market | 2026-2036
Automotive Camless Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Camless Engine Market Analysis
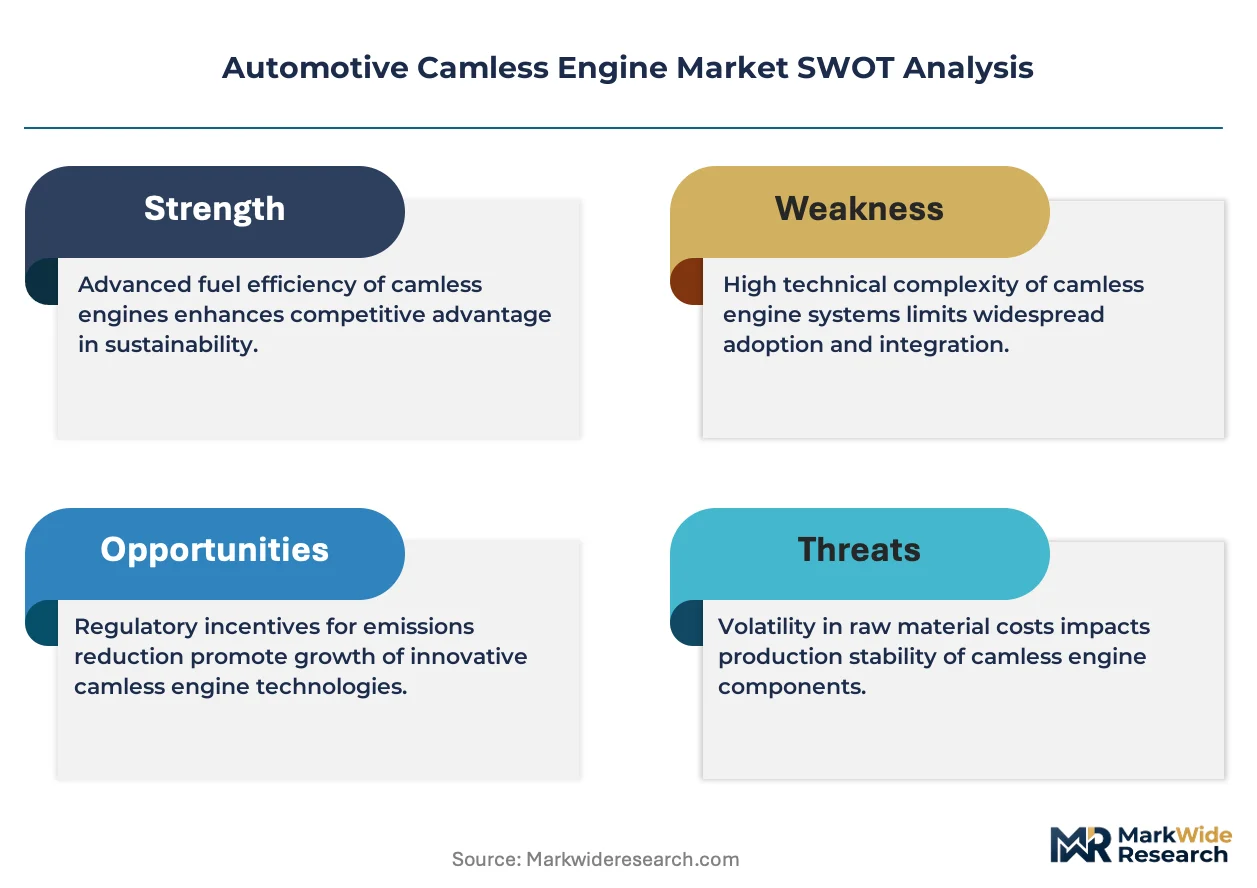
Asset-light engineering partnerships and project-based R&D financing are reshaping competitive entry in camless engine development. Freevalve AB leverages its electromagnetic valve architecture to sustain technology leadership in compact powertrain applications. BorgWarner Inc. anchors North American supply relationships through its extensive actuator manufacturing footprint. Camcon Auto Ltd. specializes in precision control systems that differentiate its offering for high-performance automotive segments.
An automotive camless engine replaces conventional camshaft-driven valve trains with electronically controlled actuators that manage intake and exhaust valve timing independently, typically achieving valve response times under 3 milliseconds and enabling cylinder-specific optimization. The primary purpose is to maximize thermal efficiency and reduce parasitic losses across varying load conditions. Electromagnetic valves and linear actuators lead current product configurations, while control units capture expanding margin pools as software-defined calibration becomes central to performance differentiation. Hybrid Solutions within the technology dimension represent the fastest-growing category, combining electronic precision with mechanical redundancy to meet OEM reliability thresholds.
The EPA and NHTSA coordinate fuel economy and safety compliance that directly shapes camless engine validation requirements in the United States, while EMA and REACH frameworks in Europe govern emissions testing and material substance restrictions for valvetrain components. These regulatory layers create compliance costs that favor suppliers with established certification pathways. Stakeholders must monitor how emissions rule evolution affects R&D allocation between camless combustion architectures and full electrification programs.
Market Dynamics
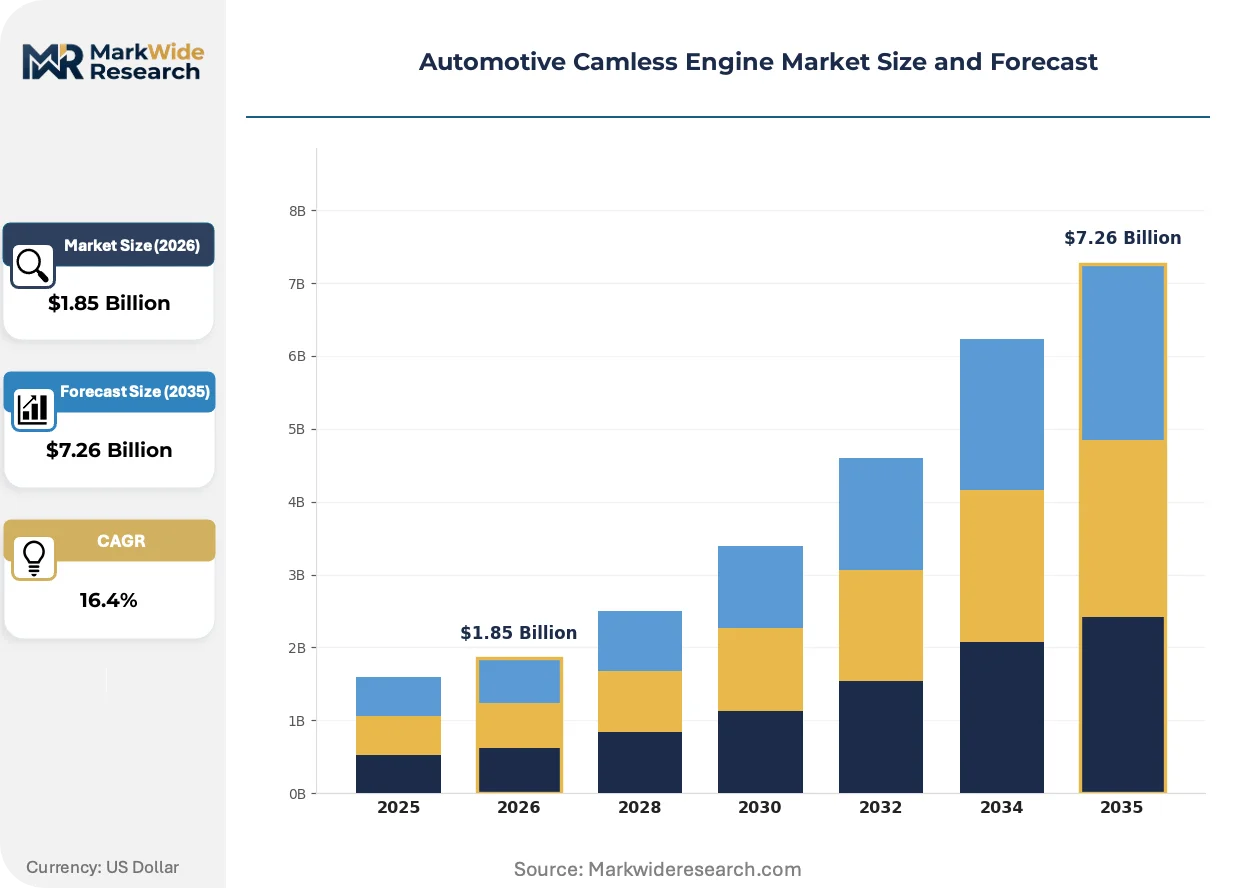
The automotive camless engine market is undergoing structural transformation as EPA Corporate Average Fuel Economy standards and Euro 7 emissions rules force OEMs to extract maximum thermal efficiency from remaining combustion architectures before electrification timelines mature.
Growth Catalysts
- EPA CAFE Standards:Stringent fleet-wide fuel economy mandates in the United States compel manufacturers to adopt variable valve timing technologies that eliminate camshaft parasitic losses.
- Germany Powertrain Clusters:Concentrated R&D infrastructure around Stuttgart and Munich accelerates prototype-to-production cycles for electromagnetic valvetrain systems.
- Hybrid Solutions Technology:Configurations combining electronic precision with mechanical redundancy address OEM reliability thresholds while preserving efficiency gains.
Market Restraints
- Rare Earth Magnet Costs:Neodymium and dysprosium price volatility in electromagnetic actuator supply chains compresses component margins unpredictably.
- Control Unit Complexity:Real-time cylinder-specific optimization demands processing power that strains thermal management in compact engine bays.
- Electrification Substitution:Battery-electric powertrain investments by major OEMs divert engineering resources from advanced combustion development programs.
Strategic Opportunities
- Japan Performance Segment:Motorsport-derived camless architectures offer technology transfer pathways into premium street vehicle applications.
- Software-Defined Calibration:Over-the-air valve timing updates create recurring revenue streams and decouple hardware from performance versioning.
- India Two-Wheeler Market:Cost-optimized electromagnetic valve systems address fuel efficiency mandates in high-volume motorcycle and scooter production.
Industry Challenges
- Embedded Systems Talent Scarcity:Shortage of engineers proficient in real-time control algorithms for sub-millisecond valve actuation limits development velocity.
- EPA/NHTSA Validation Timelines:Extended certification cycles for novel valvetrain architectures delay platform integration and revenue recognition.
- Legacy ECU Integration:Backward compatibility requirements with existing engine management systems constrain architectural freedom in retrofit applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Camless Engine Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Linear Actuators, Electromagnetic Valves, Hydraulic Systems, Control Units End User: OEMs, Aftermarket Providers, Fleet Operators, Research Institutions Application: Passenger Vehicles, Commercial Vehicles, Off-Road Vehicles, High-Performance Cars Technology: Mechanical Systems, Electronic Control, Hybrid Solutions, Fuel Efficiency Technologies |
| Companies Covered | BorgWarner Inc., Freevalve AB, Camcon Auto Ltd., Linamar Corp., Musashi Seimitsu Industry Co. Ltd., ElringKlinger AG, NEMAK SAB de CV, thyssenkrupp AG, Schaeffler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Camless Engine Market Emerging Trajectories
Digital twin technology is virtualizing camless engine development workflows, compressing validation cycles and enabling predictive calibration before physical prototyping begins.
Electromagnetic valve actuation is virtualizing traditional camshaft hardware stacks by replacing mechanical timing mechanisms with software-controlled magnetic force fields. Tier 1 suppliers are embedding these systems into 48V mild-hybrid architectures at accelerated development cadences. This virtualization is compressing the boundary between powertrain hardware and software-defined vehicle platforms.
Euro 7 emissions rules are tightening particulate and nitrogen oxide limits for internal combustion engines through 2025 implementation timelines. OEMs must demonstrate real-world driving emissions compliance that variable valve timing can address through precise charge control. German and Japanese manufacturers are prioritizing camless architectures in premium segments where pricing absorbs technology premiums.
Fleet procurement departments are consolidating supplier relationships around full valvetrain system integrators rather than discrete component vendors. Powertrain engineering divisions now demand turnkey electromagnetic actuator and control unit packages with guaranteed emissions compliance. This concentration is most pronounced in United States-based OEMs facing simultaneous EPA and CARB certification requirements.
Automotive Camless Engine Market Segmentation
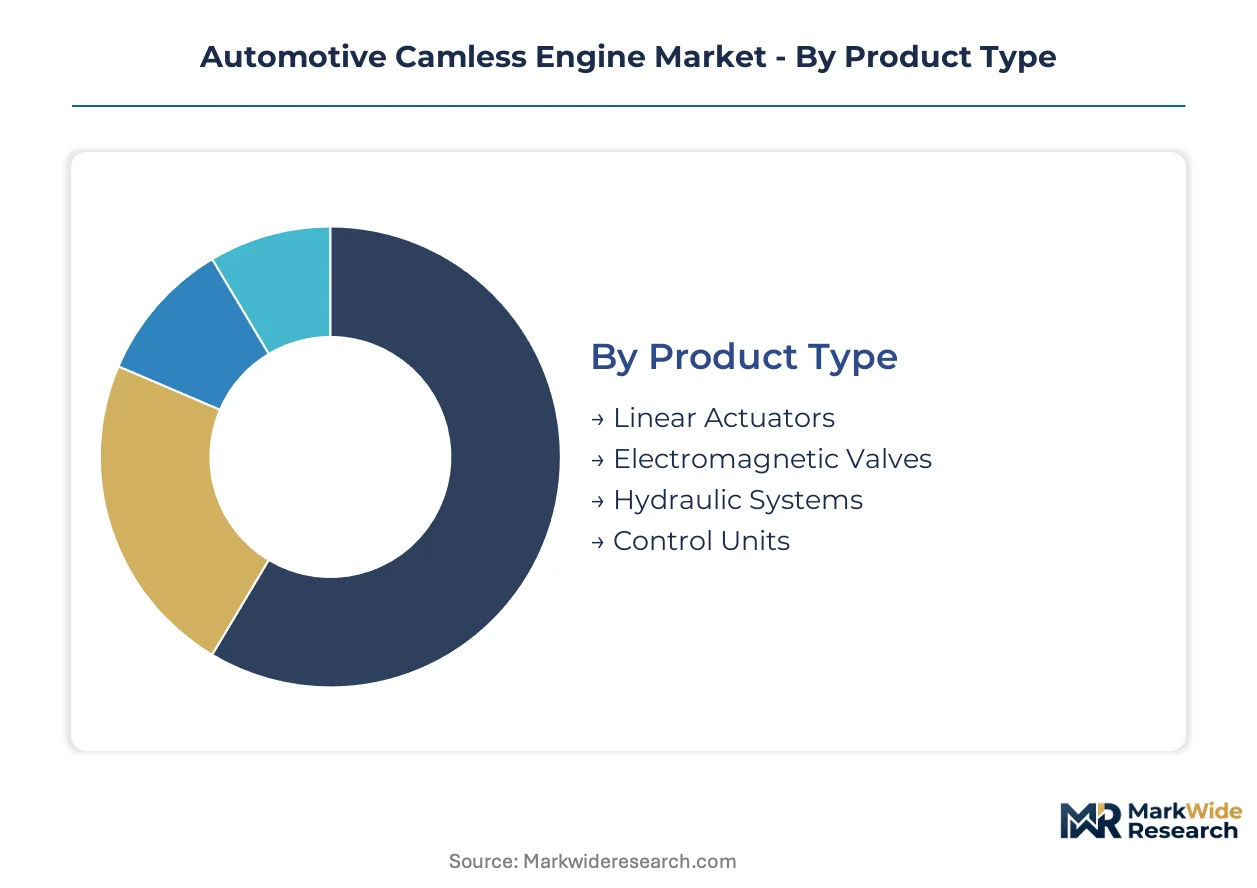
Camless engine segmentation reflects competing priorities across hardware precision, software control, and application-specific reliability requirements. Product architecture choices determine margin capture, while end-user concentration shapes procurement patterns and technology roadmaps.
Product Type:
Cost tier differentiation separates commodity actuator hardware from high-margin control electronics and integrated system packages.
- Linear Actuators:Electromechanical devices convert electrical signals into precise linear valve displacement with sub-millimeter accuracy. Demand clusters in German premium passenger vehicle programs where thermal efficiency targets justify component premiums. Rare earth magnet supply volatility constrains cost predictability.
- Control Units:Embedded computing platforms execute real-time cylinder-specific valve timing algorithms under extreme thermal and vibration loads. Japanese OEM procurement concentrates here as software-defined calibration becomes the primary performance differentiator. Processing power requirements strain thermal management in compact engine bays.
- Electromagnetic Valves:Direct-acting solenoid valves eliminate mechanical linkages through magnetic force fields.
- Hydraulic Systems:Fluid-pressure actuation provides mechanical redundancy for reliability-critical applications.
Control Units command the established base. The steepest expansion runs through Hybrid Solutions integration across multiple product categories.
End User:
Application context determines procurement sophistication, with volume scale and technical specification intensity varying sharply across customer types.
- OEMs:Original equipment manufacturers specify integrated valvetrain systems with guaranteed emissions compliance and multi-platform scalability. Procurement concentrates among Germany, Japan, and United States-based powertrain engineering divisions facing simultaneous EPA CAFE and Euro 7 certification requirements. Fleet-wide fuel economy mandates compress supplier qualification timelines.
- Fleet Operators:Commercial vehicle and rental fleet managers demand retrofit compatibility with existing engine management architectures. United States long-haul trucking segments prioritize total cost of ownership calculations over upfront technology premiums. Extended EPA/NHTSA validation cycles delay platform integration.
- Aftermarket Providers:Independent service networks and performance tuners supply replacement components and upgrade kits.
- Research Institutions:University and national laboratory programs advance fundamental actuator physics and control algorithms.
OEMs command the established base. The steepest expansion runs through Fleet Operators as total cost of ownership transparency improves.
Application:
Volume scale and performance specification intensity create distinct market tiers with diverging technology requirements and margin profiles.
- Passenger Vehicles:High-volume automotive platforms demand cost-optimized electromagnetic valve systems with proven reliability across temperature and duty cycles. German and Japanese manufacturers prioritize camless architectures in premium segments where pricing absorbs technology premiums. Euro 7 particulate and nitrogen oxide limits mandate precise charge control.
- High-Performance Cars:Motorsport-derived applications exploit sub-millisecond valve response times for cylinder-specific optimization and transient power delivery. Japan performance segments offer technology transfer pathways into premium street vehicle applications. Engineering talent scarcity for real-time control algorithms constrains development velocity.
- Commercial Vehicles:Heavy-duty trucking and logistics fleets prioritize durability and service interval extension.
- Off-Road Vehicles:Construction, agriculture, and mining equipment operates under extreme environmental contamination and vibration conditions.
Passenger Vehicles command the established base. The steepest expansion runs through High-Performance Cars as motorsport technology transfer accelerates.
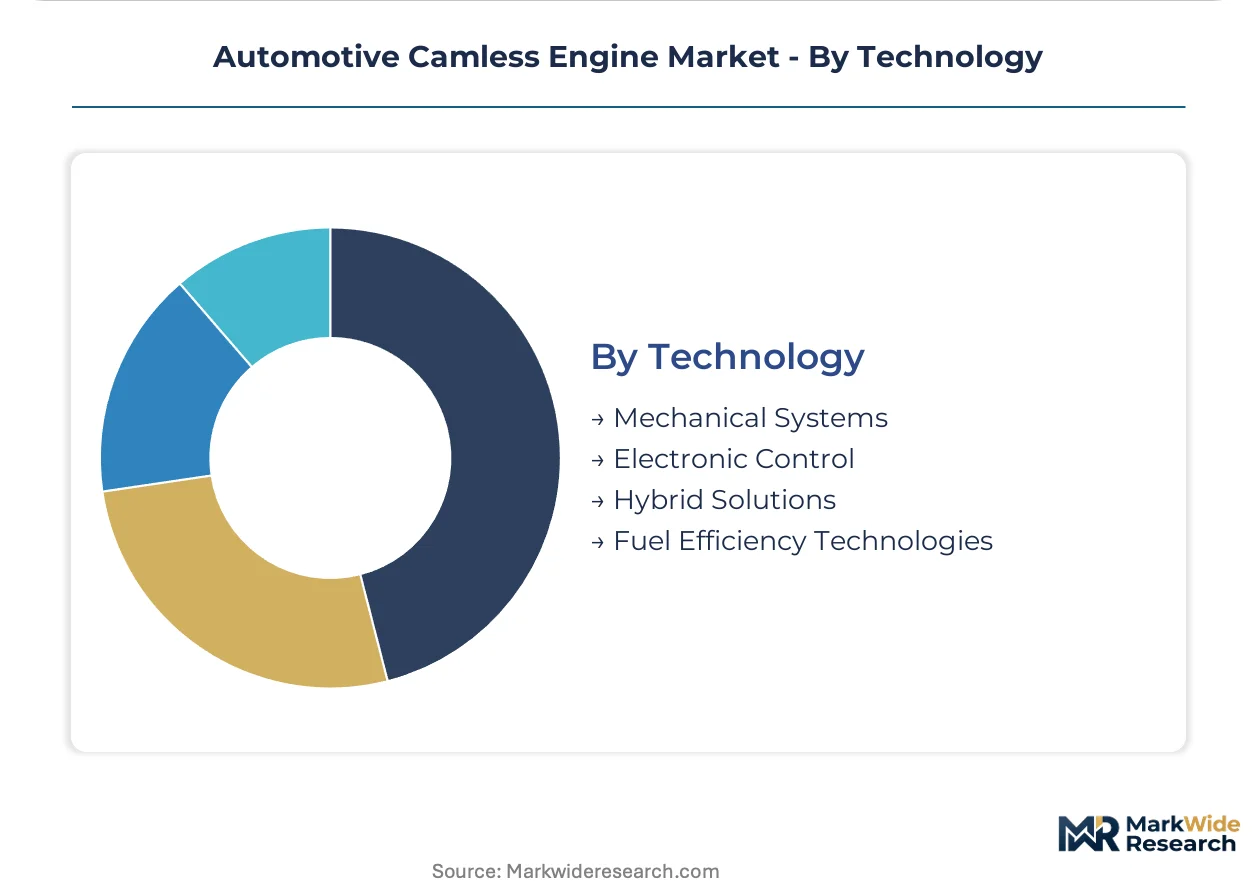
Technology:
Maturity stage and integration complexity determine competitive entry barriers and supplier margin capture across architectural approaches.
- Hybrid Solutions:Configurations combine electronic precision with mechanical redundancy to meet OEM reliability thresholds while preserving efficiency gains. Freevalve AB and BorgWarner anchor development through electromagnetic valve architectures and actuator manufacturing scale. This category captures expanding margin pools as software-defined calibration becomes central to performance differentiation.
- Electronic Control:Fully software-defined valve timing eliminates mechanical backup systems for maximum thermal efficiency. Real-time cylinder-specific optimization demands processing power that strains thermal management in compact engine bays. Over-the-air valve timing updates create recurring revenue streams.
- Mechanical Systems:Cam-based architectures with electromechanical enhancement retain established supply chain relationships.
- Fuel Efficiency Technologies:Ancillary systems including thermal management and friction reduction complement core valvetrain function.
Mechanical Systems command the established base. The steepest expansion runs through Hybrid Solutions as reliability thresholds and efficiency targets converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in camless engine components reflect concentrated engineering capability in developed automotive clusters. Import dependence for rare earth magnets and electromagnetic actuators shapes procurement strategies across manufacturing regions.
United States
EPA CAFE standards and NHTSA safety compliance drive OEM validation investments. The Inflation Reduction Act provisions support domestic manufacturing reshoring for powertrain components. Detroit-area engineering centers coordinate prototype testing for electromagnetic valvetrain integration.
Germany
Premium passenger vehicle programs absorb technology premiums for thermal efficiency gains. KBA certification requirements and Euro 7 emissions rules compress supplier qualification timelines. Stuttgart and Munich powertrain clusters accelerate electromagnetic actuator development cycles.
Japan
Motorsport-derived architectures enable technology transfer into street vehicle applications. METI industrial policy supports next-generation combustion efficiency research programs. Nagoya and Tokyo metropolitan areas concentrate control systems engineering talent.
China
Domestic OEMs pursue fuel efficiency gains amid dual carbon policy implementation. MIIT standards govern new energy vehicle classifications affecting hybrid powertrain investments. Yangtze River Delta manufacturing bases expand electromagnetic component production capacity.
India
Two-wheeler fuel efficiency mandates create volume opportunities for cost-optimized valve systems. BIS certification requirements standardize component specifications for domestic assembly. Tamil Nadu and Maharashtra automotive corridors attract tier-1 actuator supplier investments.
Automotive Camless Engine Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying precision actuators and control modules. The vendor base organizes around three functional layers: electromagnetic architecture developers, precision manufacturing specialists, and full-system integrators. Strategic archetypes include technology originators with patent portfolios, scale manufacturers with automotive supply relationships, and hybrid solution providers bridging mechanical and electronic domains. Competitive moves concentrate on engineering partnerships for R&D financing and geographic expansion into high-volume motorcycle markets.
Among electromagnetic architecture specialists, Freevalve AB exemplifies the technology originator archetype through its valve control system focus. BorgWarner Inc. occupies a position as a scale-integrated manufacturer with established North American supply relationships. Camcon Auto Ltd. represents the precision control segment serving performance-oriented applications. These three entities anchor distinct competitive vectors within the broader valvetrain ecosystem.
| Leading Market Players |
|---|
| BorgWarner Inc. |
| Freevalve AB |
| Camcon Auto Ltd. |
| Linamar Corp. |
| Musashi Seimitsu Industry Co. Ltd. |
| ElringKlinger AG |
| NEMAK SAB de CV |
| thyssenkrupp AG |
| Schaeffler |
| Others |
Supply Flow & Price Mechanics
Overcapacity in electromagnetic actuator manufacturing across China is compressing supplier margins while simultaneously intensifying price competition for German and Japanese OEM procurement contracts. This utilization dynamic forces component vendors to absorb rare earth magnet cost volatility rather than pass through increases, reshaping contractual risk allocation across the valvetrain ecosystem.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock in volume commitments against price stability guarantees. Price differentiation rests on certification grade—EPA and Euro 7 compliance tiers command substantial premiums over baseline configurations—and vertical integration depth of the supplier. Cost compression in commodity actuator hardware is intensifying because Chinese manufacturing expansion outpaces demand absorption, while fleet operators exhibit highest price sensitivity due to total cost of ownership scrutiny.
Supply Chain Analysis
Export control regimes limiting electromagnetic actuator technology transfers constrain supply chain reconfiguration options for Western OEMs. Manufacturing concentrates in China, Germany, and Japan, with rare earth magnet feedstocks drawing from Chinese processing dominance and Australian mining outputs. Single-source vulnerability in neodymium supply chains represents the dominant structural risk. Distribution runs through Tier 1 system integrators rather than discrete component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive moat built on regulatory entrenchment—EPA CAFE and Euro 7 certification pathways create switching costs that lock OEMs into validated supplier relationships across multi-year platform cycles.
For Market Incumbents: Pre-empt emerging entrant challenges by deepening backward integration into rare earth magnet supply chains and accelerating embedded systems talent acquisition in Stuttgart and Nagoya engineering clusters. Electrification substitution threats demand defensive patent portfolio expansion around hybrid electromagnetic-mechanical architectures. For New Entrants and Emerging Players: India's two-wheeler fuel efficiency mandates represent the most penetrable entry point for cost-optimized electromagnetic valve systems lacking premium passenger vehicle certification overhead. Fleet operator retrofit demand in United States long-haul trucking offers secondary white-space with lower regulatory barriers. A go-to-market partnership with established Tier 1 distributors bypasses direct OEM qualification timelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across control unit software development as real-time processing requirements strain thermal management engineering. Long-term viability favors platform-integrator archetypes with embedded EPA and KBA certification pathways over pure component suppliers. The signal to watch is OEM R&D allocation shifts between camless combustion and full electrification programs.| Strategic Initiative | Industry Significance |
|---|---|
| Electromagnetic Architecture Patent Expansion | Freevalve AB's valve control IP creates defensive barriers against actuator commoditization. |
| 48V Mild-Hybrid Platform Integration | BorgWarner's actuator manufacturing scale enables rapid embedding into electrified powertrains. |
| Software-Defined Calibration Capability | Over-the-air valve timing updates transform hardware margins into recurring revenue streams. |
| Rare Earth Magnet Supply Security | Backward integration into neodymium processing hedges against Chinese export restriction risks. |
| India Two-Wheeler Market Localization | Tamil Nadu manufacturing corridors attract cost-optimized actuator production for BIS certification. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and embedded systems R&D directors; and secondary validation through EPA certification databases, KBA type-approval records, IHS Markit vehicle production data, and SEC filings from listed automotive component suppliers. Bottom-up segment sizing triangulated against top-down macroeconomic anchors across the analysis window.
Forecast inputs span vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs were derived from regression analysis against historical EPA CAFE compliance cost curves and Euro 7 implementation timelines. Industry-specific inputs include rare earth magnet price volatility indices and OEM electrification program announcements.
Stress conditions across neodymium supply disruption severity, EPA rule acceleration scenarios, and embedded systems talent availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory implementation pacing and OEM platform cycle timing. Material shifts in electrification substitution velocity or export control regime expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Engine Market
Powertrain
Automotive Tuner Market
Powertrain
Automotive Fuel Injector Market
Powertrain
Automotive Engine Air Filter Market
Powertrain
Sway Bar Bushing Market
Powertrain
Colombia Automotive Engine Oils Market
Powertrain
Automotive Variable Discharge Oil Pump Market
Powertrain
United Kingdom Automotive Engine Oils Market
Powertrain
Transmission Oil Pumps Market
Powertrain
Drive Shaft Market
Powertrain
Global Automotive Engine Pulley Market
Powertrain
Diesel Engine Management System Market
Powertrain
Brazil Automotive Engine Oils Market
Powertrain
Gas Engine Market
Powertrain
Asia Pacific Electrically Powered Hydraulic Steering Market
Powertrain
Canada Automotive Engine Oils Market