

EV Powertrain-in-the-Loop (P-HIL) Test Benches Market Size, Share, and Industry Trends Forecast 2026-2036
EV Powertrain-in-the-Loop (P-HIL) Test Benches Market Insights
The performance gap between premium multi-physics P-HIL platforms and entry-level single-axis rigs is hardening into a durable market split. AVL dominates high-fidelity powertrain integration with proprietary toolchain control. dSPACE sustains its position through deep backward integration into real-time computing hardware. Typhoon HIL specializes in FPGA-based electrical emulation for inverter-focused test cells.
EV Powertrain-in-the-Loop test benches combine real-time simulators with physical electric motors, inverters, and battery interfaces to validate control algorithms under dynamic load conditions, typically operating at sub-millisecond simulation step sizes to preserve numerical stability during switching events. Their primary purpose is to de-risk powertrain integration before prototype vehicle assembly, cutting months from development schedules. Component Type segmentation shows inverter and battery management system emulation commanding the deepest margin pools due to silicon carbide transition complexity. Technology segmentation reveals digital twin overlay adoption outpacing standalone hardware-in-the-loop configurations, as OEMs seek to bridge virtual and physical validation environments.
NHTSA crashworthiness and EPA emissions compliance timelines in the United States, combined with EU Green Deal vehicle CO₂ targets enforced through the European Commission, are mandating earlier powertrain lock points that compress validation windows. China's MIIT NEV credit system and GB/T standards for electric vehicle safety further tighten certification requirements. Stakeholders must weigh captive P-HIL investment against third-party testing access as platform refresh cycles accelerate and regulatory divergence between major automotive markets widens.
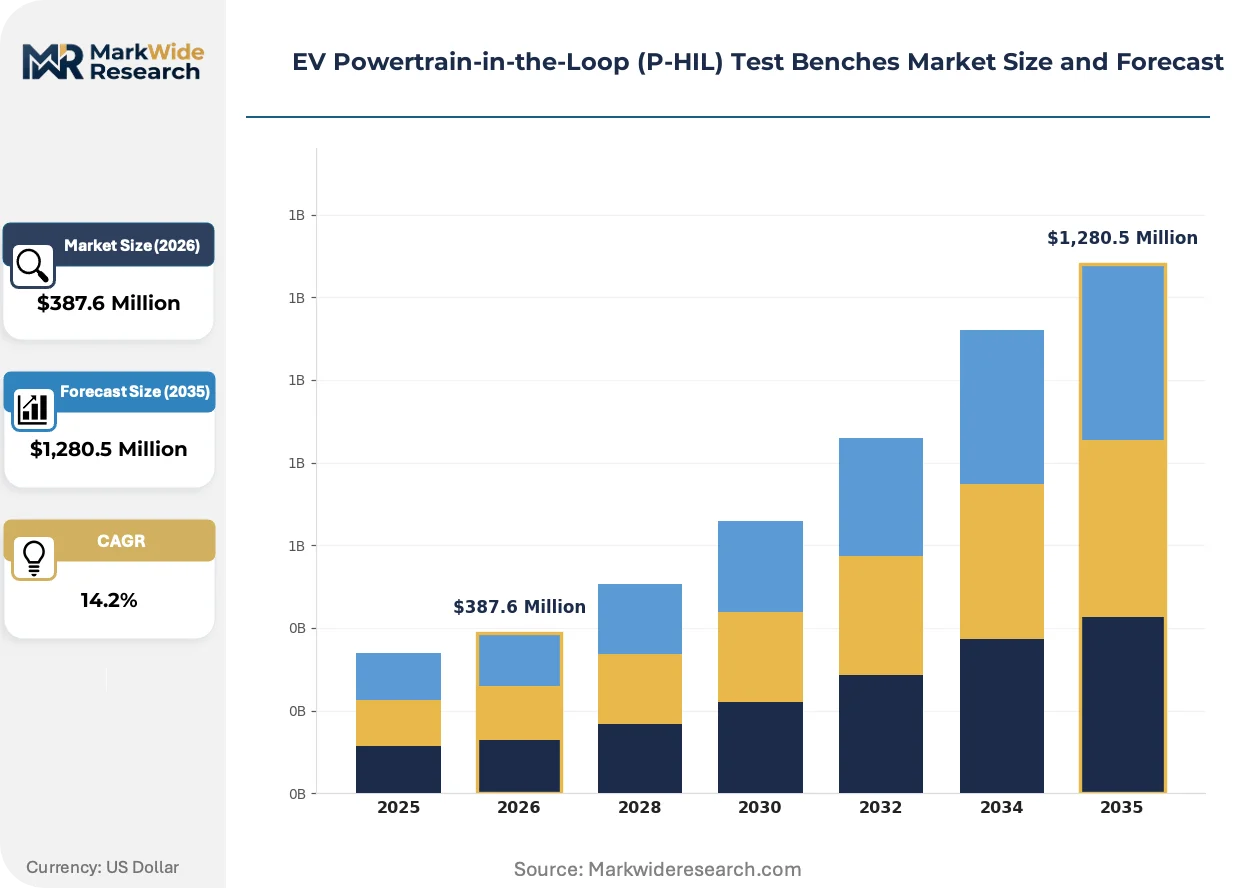
Market Dynamics
The transition to silicon carbide power electronics is compressing validation cycles, forcing test bench architectures to accommodate faster switching frequencies and thermal transients that legacy rigs cannot replicate.
Growth Catalysts
- EU Green Deal CO₂ targets:The European Commission's vehicle emissions mandates are accelerating powertrain lock points, requiring earlier hardware validation and expanded P-HIL throughput.
- Silicon carbide inverter proliferation:Wide-bandgap semiconductor adoption in traction inverters demands sub-microsecond simulation step sizes that only FPGA-based P-HIL platforms can deliver.
- Stuttgart-Munich engineering corridor:Germany's concentrated OEM and tier-one R&D footprint generates dense demand for high-fidelity powertrain integration test cells.
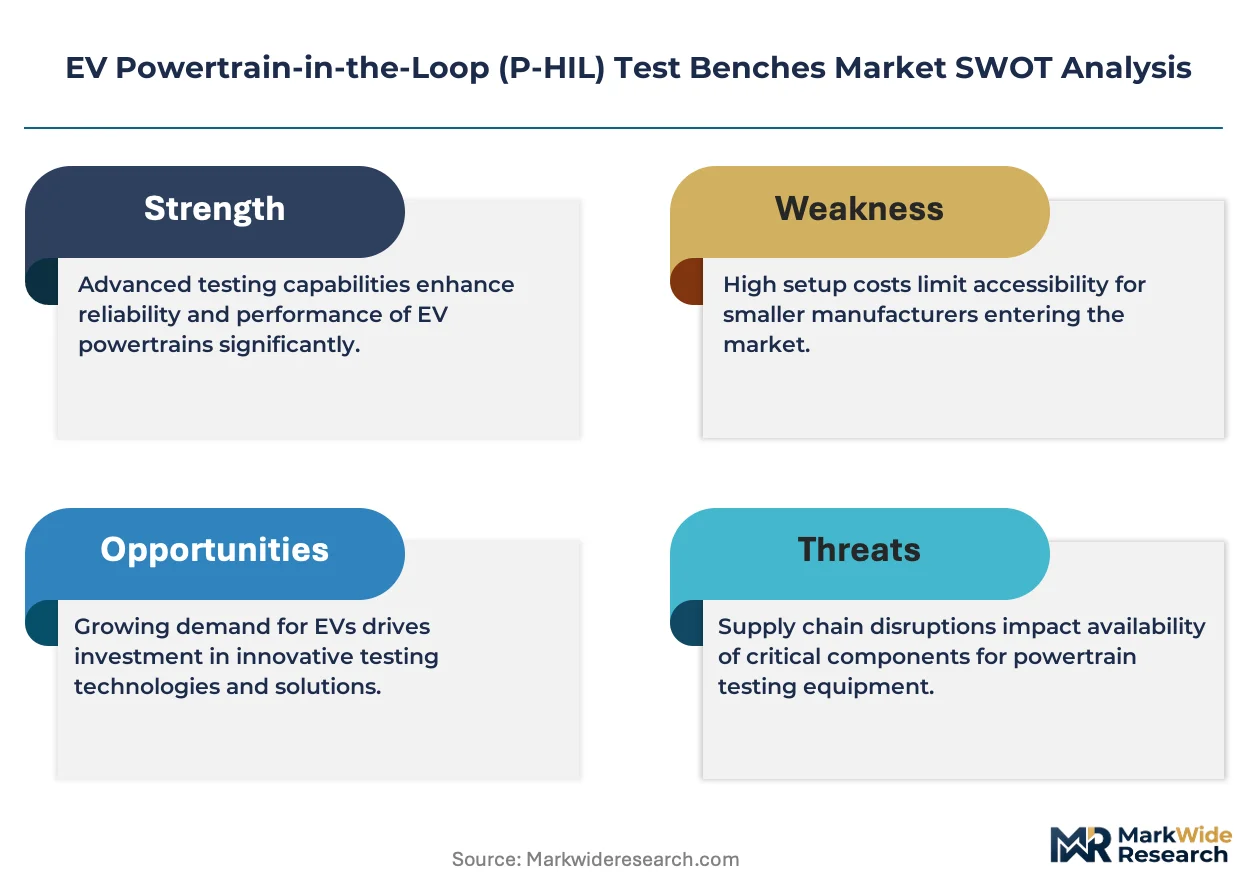
Market Restraints
- FPGA hardware cost concentration:Real-time computing substrates and high-bandwidth signal conditioning modules account for disproportionate platform capex, limiting mid-tier lab expansion.
- Specialized engineering talent scarcity:The intersection of power electronics, control theory, and real-time simulation expertise concentrates in a narrow geographic and institutional pool.
- Legacy dyno infrastructure lock-in:Existing mechanical test cell investments create switching costs that delay P-HIL adoption at smaller powertrain suppliers.
Strategic Opportunities
- India PLI scheme for automotive:Production-linked incentives for advanced automotive technology manufacturing are attracting powertrain engineering investment and creating greenfield P-HIL demand.
- Digital twin overlay convergence:The integration of virtual powertrain models with physical test benches enables continuous validation loops that compress development timelines.
- Second-life battery emulation:Circular economy regulations in the EU are creating new test requirements for degraded battery pack integration in stationary and mobility applications.
Industry Challenges
- Multi-physics calibration complexity:Synchronizing electrical, thermal, and mechanical domain models requires specialized expertise that outstrips current workforce supply.
- GB/T 18384 safety certification timelines:China's electric vehicle safety standards mandate specific test protocols that demand dedicated P-HIL configurations, stretching validation resource allocation.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EV Powertrain-in-the-Loop (P-HIL) Test Benches Market Trends and Innovations
Test methodology is bifurcating between full-vehicle digital twins and hardware-intensive powertrain cells, with automation bridging the validation gap between virtual design and physical commissioning.
AI-assisted test sequence generation is automating the creation of boundary-condition scenarios for inverter thermal stress and battery aging profiles. Tier-one suppliers in Germany and Japan are deploying these tools to reduce calibration engineer hours by half on new platform introductions. The technology is automating the transition from manual drive-cycle scripting to autonomous exploration of failure modes.
The EU AI Act's risk classification framework is extending to autonomous vehicle validation tools, requiring documented traceability for simulation-based safety claims. P-HIL platforms must now embed audit trails for every test parameter variation. Powertrain divisions with heavy European sales exposure are retrofitting data governance layers into existing test infrastructure.
Consolidated validation procurement is displacing distributed R&D purchasing as OEMs centralize P-HIL access under single engineering services contracts. The shift concentrates vendor relationships and favors platform providers with multi-site service capabilities. This pattern is most pronounced among German OEMs restructuring after platform consolidation announcements.
EV Powertrain-in-the-Loop (P-HIL) Test Benches Market Segmentation
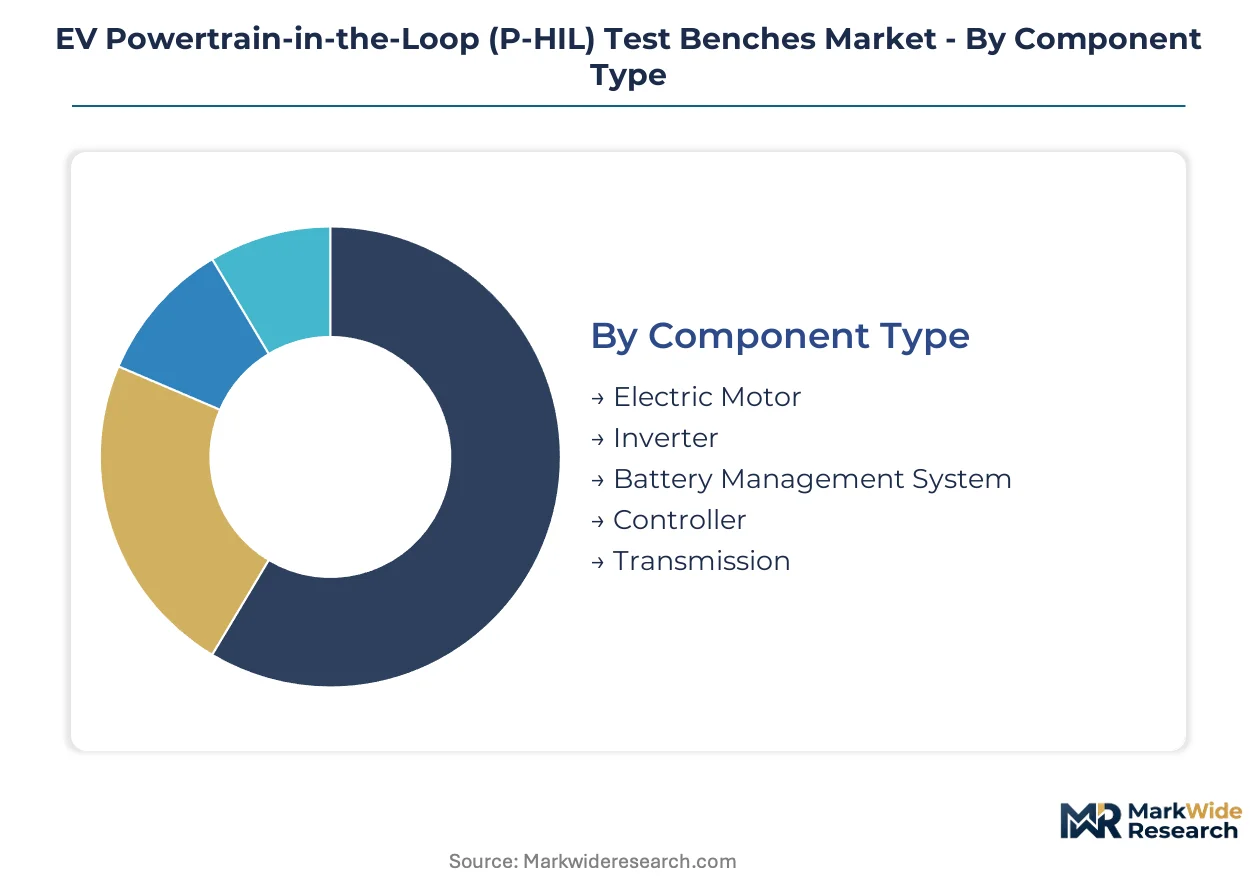
P-HIL test bench procurement varies sharply by validation objective, with component-focused buyers prioritizing electrical fidelity while system integrators demand multi-physics synchronization. Segment boundaries are hardening as silicon carbide adoption and digital twin convergence create divergent capability requirements across buyer types.
Component Type:
Capital allocation follows the thermal and switching complexity of each powertrain element, with wide-bandgap transitions driving differential investment intensity.
- Inverter:FPGA-based emulation platforms replicate sub-microsecond switching transients from silicon carbide and gallium nitride power stages. German OEM validation labs in Stuttgart command the deepest rig configurations for 800V architectures, driven by EU Green Deal CO₂ compliance deadlines compressing powertrain lock points.
- Battery Management System:Cell-level emulation hardware simulates electrochemical impedance and thermal runaway propagation across degraded pack states. China's MIIT GB/T 18384 safety mandates are forcing dedicated BMS-HIL cell investments at domestic NEV engineering centers, stretching validation resource allocation.
- Electric Motor:Dynamometer-coupled rigs test field-oriented control algorithms under magnetic saturation and thermal derating conditions.
- Controller:Rapid prototyping platforms host auto-generated code before silicon commitment, concentrating at tier-one supplier R&D sites.
- Transmission:Mechanical-electric co-simulation cells validate gear mesh dynamics and lubrication thermal management for multi-speed e-axles.
Inverter test cells lead on scale; battery management system rigs lead on momentum.
Technology:
Architecture selection hinges on the trade-off between model fidelity and hardware latency, with hybrid configurations gaining favor among platform integrators.
- Digital Twin:Virtual powertrain overlays synchronize with physical test benches through real-time data pipelines, enabling continuous validation loops. German and Japanese tier-one suppliers deploy these configurations to halve calibration engineer hours on new platform introductions, driven by automation of boundary-condition scenario generation.
- Real-Time Simulation:Sub-millisecond step-size computing substrates preserve numerical stability during inverter switching events and battery transient response. China's NEV engineering corridors demand these platforms for GB/T standards compliance, with MIIT dual carbon goals forcing compressed electrification timelines.
- Hardware Integration:Signal conditioning and power interface modules bridge simulated and physical domains.
- Software-in-the-Loop:Pre-silicon algorithm validation runs on host PCs without real-time constraints.
- Rapid Control Prototyping:Auto-code generation targets deploy directly to production-intent ECU hardware.
Real-time simulation dominates installed base; digital twin configurations are climbing the fastest.
Application:
Test scope determines rig complexity, with full-vehicle integration demanding synchronized multi-component cells that command premium pricing.
- Vehicle Development:Full powertrain integration cells combine motor, inverter, battery, and transmission emulation under unified load profiles. Stuttgart-Munich engineering corridor OEMs concentrate demand here, restructuring after platform consolidation announcements toward centralized validation procurement.
- Component Validation:Isolated test benches verify individual element performance against specification before system integration. India's PLI scheme for automotive is attracting greenfield powertrain engineering investment, creating new demand for entry-to-mid-tier validation capacity.
- System Diagnostics:Fault injection and failure mode exploration rigs isolate root causes in field-returned hardware.
- Performance Testing:Drive-cycle replication cells measure efficiency maps and thermal limits across operating envelopes.
- Reliability Assessment:Accelerated aging protocols stress powertrain durability before warranty commitment.
Vehicle development commands the deepest rig investments; component validation shows the steepest expansion trajectory.
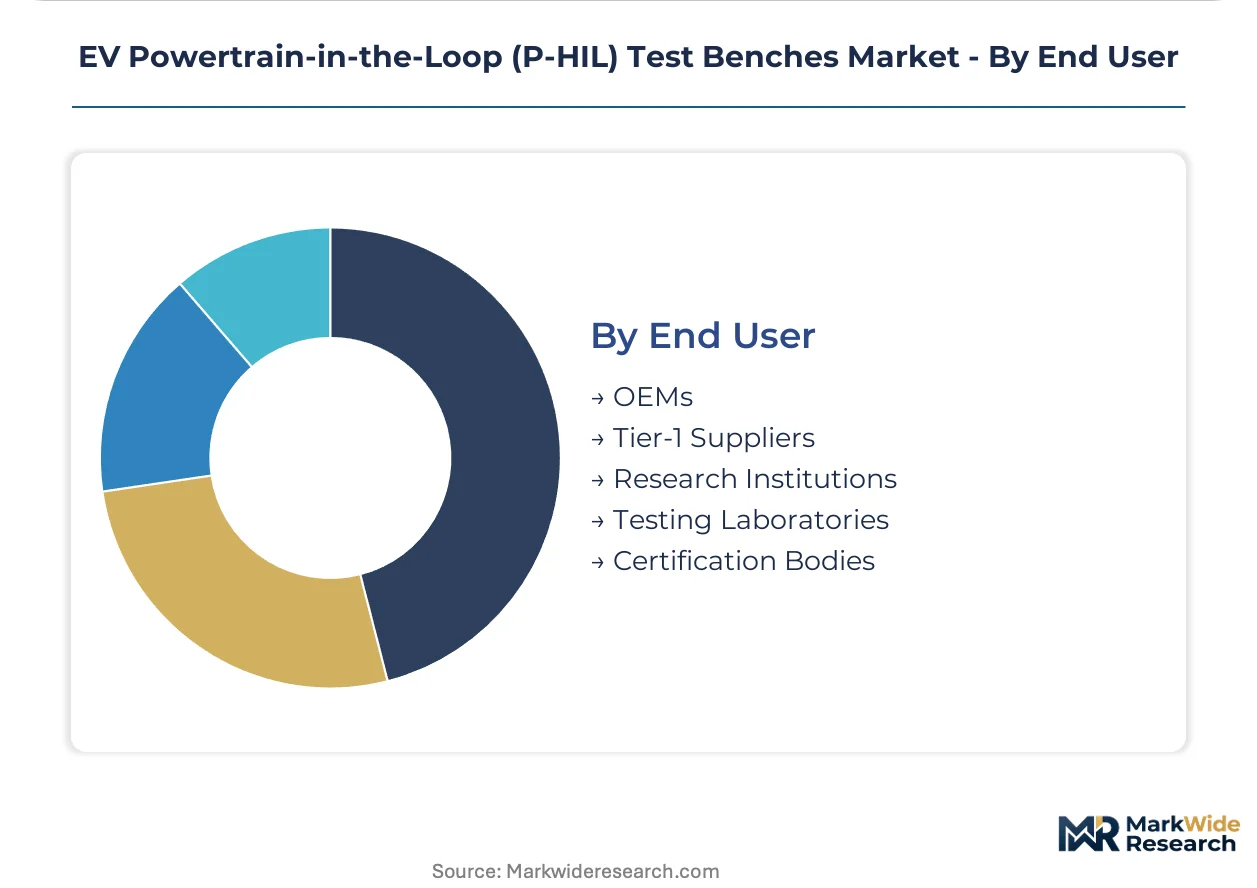
End User:
Procurement authority concentrates with scale, though certification body mandates are fragmenting buyer concentration.
- OEMs:Captive validation labs maintain multi-site P-HIL networks for platform development and supplier qualification. German OEMs are consolidating distributed R&D purchasing under single engineering services contracts, favoring vendors with multi-site service capabilities.
- Tier-1 Suppliers:Independent validation capacity supports simultaneous program execution for multiple OEM customers. Japan's automotive supplier base concentrates FPGA-based inverter test expertise, with METI technology roadmaps guiding wide-bandgap semiconductor adoption.
- Research Institutions:Academic and national laboratory access supports pre-competitive technology development.
- Testing Laboratories:Third-party validation services offer P-HIL access without captive capital commitment.
- Certification Bodies:EU AI Act traceability requirements and NHTSA crashworthiness protocols mandate documented test parameter audit trails.
OEMs lead on scale; tier-1 suppliers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Power electronics and real-time simulation expertise clusters in Germany's automotive engineering corridor, China's NEV manufacturing belts, and Japan's precision control technology hubs, with emerging capacity forming in India's automotive corridors and the US electrification corridors.
Germany
Stuttgart and Munich host the densest concentration of OEM validation labs and tier-one powertrain engineering centers. EU Green Deal CO₂ targets enforced by the European Commission compress powertrain lock points, forcing earlier hardware validation. Baden-Württemberg's engineering corridor generates concentrated demand for 800V silicon carbide inverter test cells.
China
MIIT dual carbon goals and NEV credit mandates are compressing electrification timelines across domestic automakers. GB/T 18384 safety standards mandate specific test protocols for battery management systems. Shanghai and Shenzhen engineering corridors are scaling dedicated BMS-HIL cell investments to meet certification requirements.
Japan
METI technology roadmaps guide wide-bandgap semiconductor adoption across automotive suppliers. The country's automotive supplier base concentrates FPGA-based inverter test expertise. Nagoya and Tokyo corridors maintain deep backward integration into real-time computing hardware for powertrain control development.
United States
NHTSA crashworthiness and EPA emissions compliance timelines mandate earlier powertrain integration validation. The Southeast and Midwest automotive corridors are attracting greenfield electrification investment. Michigan and California engineering clusters are scaling P-HIL capacity to compress EV development cycles.
India
PLI scheme production-linked incentives for advanced automotive technology manufacturing attract powertrain engineering investment. The country's national automotive regulator mandates alignment with evolving electrification standards. Tamil Nadu and Maharashtra automotive corridors are creating greenfield demand for entry-to-mid-tier validation capacity.
EV Powertrain-in-the-Loop (P-HIL) Test Benches Market Competitive Landscape
Top-tier vendors anchor high-fidelity multi-physics integration, while mid-tier specialists occupy electrical emulation niches and entry-level providers serve component validation needs. The vendor base stratifies around FPGA-based real-time computing control, proprietary toolchain ecosystems, and signal conditioning hardware differentiation. Dominant competitive moves include geographic expansion into NEV engineering corridors and technology licensing partnerships to access silicon carbide validation expertise.
Within the premium-tier vector, AVL and dSPACE occupy positions exemplifying deep toolchain control and real-time computing hardware integration respectively. Typhoon HIL represents the FPGA-based electrical emulation archetype specializing in inverter-focused test configurations. These three anchors illustrate the market's structural split between full powertrain integration platforms and component-specific emulation specialists.
| Leading Market Players |
|---|
| AVL |
| dSPACE |
| HORIBA |
| National Instruments |
| OPAL-RT Technologies |
| IPG Automotive |
| Speedgoat |
| Keysight Technologies |
| Typhoon HIL |
| Others |
Pricing and Supply Chain Analysis
FPGA firmware engineers clustered in Germany's Stuttgart-Munich corridor command wage premiums that compress mid-tier vendor margins and widen spreads between premium multi-physics platforms and entry-level single-axis rigs.
Pricing Analysis
Bundled engineering-services contracts now dominate procurement for German OEMs, while unbundled hardware-only transactions persist among India's emerging tier-one suppliers. Three-tier pricing structure across premium, standard, and economy levels separates AVL-grade full powertrain integration from Typhoon HIL's inverter-specialist configurations and entry-level battery emulation cells. Price differentiation hinges on silicon carbide switching fidelity and EU AI Act traceability certification. Pricing pressure stems from China's MIIT-mandated BMS-HIL capacity buildouts flooding mid-market supply. Tier-one suppliers exhibit highest price sensitivity; captive OEM labs show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Xilinx-AMD and Intel-Altera for high-bandwidth FPGA substrates that anchor sub-microsecond simulation step sizes. Manufacturing concentrates in Taiwan, the United States, and Germany. Raw material dependencies include gallium nitride wafers, high-frequency magnetic cores, and precision signal conditioning modules. Tariff exposure on Chinese-sourced rare-earth magnetics for motor emulation rigs threatens cost structures. Distribution runs through direct vendor-engineering relationships for premium tiers; regional systems integrators handle mid-market fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EU Green Deal CO₂ targets and China's MIIT dual carbon goals forcing simultaneous compliance investments across multiple jurisdictions.
For Market Incumbents: Extend toolchain control into digital twin overlay convergence to defend against FPGA-based specialists encroaching on system integration. Deepen backward integration into real-time computing hardware to capture margin pools silicon carbide validation demands. AVL and dSPACE must consolidate multi-site service capabilities before German OEM procurement centralization locks out fragmented vendors. For New Entrants and Emerging Players: The 40-60% price-point gap between dSPACE premium platforms and unbranded Chinese BMS-HIL cells opens entry corridors for mid-tier FPGA emulation specialists. Target India's PLI-scheme automotive corridors for greenfield validation capacity where incumbent presence remains thin. Lead with silicon carbide inverter test expertise as the wedge capability; bundle rapid deployment engineering to differentiate from established vendor lead times. For Investors and Strategic Acquirers: Tier-one automotive suppliers with heavy European sales exposure are the most active acquirer in this space, seeking digital twin capabilities to compress calibration timelines. Long-term viability favors vendors controlling proprietary real-time computing substrates rather than software-only overlay plays. Watch for GB/T 18384 safety certification timeline extensions as the demand inflection signal; delays would stretch Chinese OEM validation budgets and trigger consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Validation Partnership | Secures FPGA expertise for 800V inverter test cells ahead of EU CO₂ lock points. |
| Digital Twin Overlay Acquisition | Bridges virtual-physical validation loops that German tier-ones deploy to halve calibration hours. |
| Multi-Site Engineering Services Contract | Captures centralized procurement restructuring among Stuttgart-Munich OEM validation labs. |
| GB/T 18384 Certification Pathway Investment | Unlocks dedicated BMS-HIL demand from China's MIIT-mandated NEV engineering centers. |
| India PLI Corridor Manufacturing Footprint | Positions for greenfield powertrain engineering investment in Tamil Nadu and Maharashtra clusters. |
Research Methodology
Coverage spans Germany, China, Japan, the United States, and India, with primary inputs from each market's automotive engineering corridor. The study combines structured interviews with OEM platform engineers, tier-one supplier procurement leads, FPGA firmware specialists, and test cell integration contractors with secondary validation from MIIT regulatory filings, EU Green Deal implementation documents, SEC 10-K disclosures from listed automation vendors, and vehicle production databases tracking NEV platform introductions. Bottom-up rig deployment counts triangulate against top-down validation spending estimates from automotive R&D surveys.
Granularity-level framing models component type at the test-cell configuration level, technology at the simulation architecture level, and application at the validation scope level across the analysis window. Segmentation dimensions include inverter versus battery management system versus electric motor emulation, digital twin overlay versus real-time simulation versus hardware integration, and vehicle development versus component validation versus system diagnostics. CAGRs derive from rig installation run rates, OEM powertrain lock point schedules, and silicon carbide adoption curves. Industry-specific inputs include MIIT NEV credit system compliance deadlines and EU AI Act traceability requirement phase-ins.
The model assumes a particular technology adoption path; alternative pathways for wide-bandgap semiconductor transition timing would alter the outlook. Forecasts reflect assumptions about regulatory enforcement consistency, FPGA substrate supply continuity, and workforce availability for multi-physics calibration expertise. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.