
 Torque Converter Market | 2026-2036
Torque Converter Market Size, Share, and Industry Trends Forecast 2026-2036
Torque Converter Market Intelligence
The US EPA's Phase 3 greenhouse gas standards for heavy-duty vehicles is shifting procurement patterns across North American torque converter supply chains. BorgWarner Inc. leverages its lock-up clutch technology leadership to sustain premium positioning in commercial vehicle programs. ZF Friedrichshafen AG anchors European demand through integrated transmission-torque converter modules for premium truck platforms.
A torque converter is a fluid coupling that transfers rotating power from an internal combustion engine to a rotating driven load, using a pump impeller, turbine runner, and stator assembly within a sealed housing filled with transmission fluid; its stall torque ratio and K-factor determine launch performance and towing capability in automatic transmissions. Lock-up torque converters command the dominant share of value as fleet operators prioritize highway fuel economy, while electro-hydraulic technology variants represent the fastest-expanding segment as hybrid powertrains proliferate. Single-stage architectures remain the volume mainstay in cost-sensitive emerging markets where agricultural machinery and entry commercial vehicles predominate.
Federal emissions enforcement in the US, the EU Green Deal's transport decarbonization pathway, and China's MIIT fuel consumption limits for passenger vehicles collectively mandate higher mechanical efficiency across automatic transmission architectures. The EPA and NHTSA coordinate testing protocols that directly influence torque converter lock-up calibration requirements and supplier certification burdens. Stakeholders must monitor regulatory divergence between US and EU test cycles, as divergent efficiency metrics will force parallel product development tracks and complicate platform standardization strategies.
Market Dynamics
Lock-up clutch calibration requirements under tightening fuel efficiency mandates are forcing transmission suppliers to redesign hydraulic circuits and control strategies across all vehicle weight classes.
Growth Catalysts
- EPA Phase 3 standards:Heavy-duty fleet operators in the United States face compliance deadlines that accelerate lock-up torque converter retrofits and new equipment procurement.
- China MIIT passenger vehicle limits:Domestic automakers expand dual-clutch and CVT integration with optimized torque converter modules to meet corporate average fuel consumption targets.
- Electro-hydraulic actuation:Hybrid powertrain architectures demand faster lock-up engagement cycles, creating specification pull for electronically controlled converter variants.
Market Restraints
- Specialized steel alloying inputs:Hardened pump impeller stampings depend on controlled-carbon steel grades subject to volatile scrap metal and ferroalloy pricing.
- Tianjin-Shanghai corridor concentration:Transmission assembly plants cluster within 200 kilometers of these port cities, exposing supply chains to single-region logistics disruptions.
- Dual mass flywheel substitution:Manual transmission holdouts in European light commercial segments bypass torque converters entirely through clutch-based driveline designs.
Strategic Opportunities
- India BIS efficiency tier compliance:Light commercial vehicle fleets face escalating procurement requirements for lock-up converters as the Bureau of Indian Standards tightens test-cycle stringency.
- Agricultural machinery electrification:Tractor and harvester OEMs explore torque converter-hybrid integration for field-load variability management.
- Aftermarket remanufacturing channels:Independent distributors build certified rebuild programs for out-of-warranty commercial vehicle converters.
Industry Challenges
- Lock-up clutch friction material formulation:Suppliers struggle to balance engagement smoothness against thermal durability under high-torque diesel applications.
- Cross-cycle calibration complexity:Engineering teams must harmonize converter behavior across divergent EPA and EU test protocols without hardware duplication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Torque Converter Market |
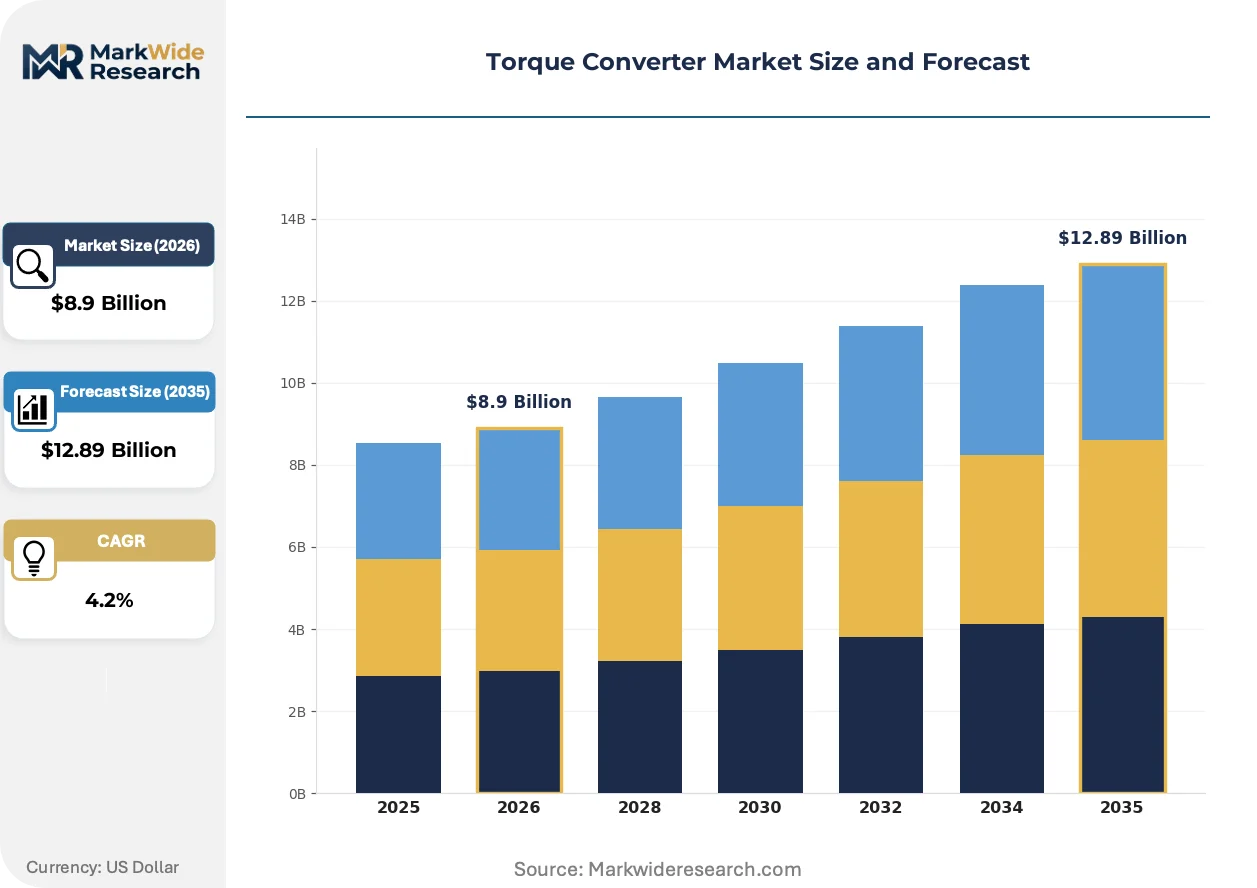
| Market Size in 2026 | $8.9 Billion |
| Market Size in 2035 | $12.89 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Stage, Two Stage, Three Stage, Lock-up Torque Converter Technology: Hydraulic, Mechanical, Electrical, Electro-Hydraulic, Pneumatic Application: Commercial Vehicles, Construction Equipment, Agricultural Machinery, Marine Vessels, Rail Transport End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Equipment Dealers |
| Companies Covered | Aisin Corporation, ZF Friedrichshafen AG, BorgWarner Inc., Schaeffler AG, Valeo SA, Continental AG, Voith GmbH & Co. KGaA, Allison Transmission, EXEDY Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Torque Converter Market Strategic Shifts & Innovations
Fluid dynamics simulation and electrified actuation are compressing development cycles while regulatory test-cycle divergence forces parallel engineering tracks.
Multi-plate lock-up clutch architectures are converging with electro-hydraulic control systems to enable millisecond engagement precision. Hybrid truck and bus manufacturers in Germany and Japan specify these modules for seamless engine-start transitions. The technology is converging with transmission control unit software stacks, collapsing the historical separation between mechanical and electronic development teams.
EU Green Deal transport decarbonization pathways mandate mechanical efficiency gains that exceed what conventional fluid coupling physics can deliver. The European Commission's 2030 CO2 reduction targets for heavy-duty vehicles force converter suppliers to prioritize lock-up duty cycle extension over stall ratio optimization. Premium truck platforms in Scandinavia and the Benelux now specify continuous lock-up operation above 35 km/h, compressing hydraulic slippage windows to regulatory minimums.
Fleet procurement departments are consolidating supplier relationships around integrated transmission-converter module vendors. Independent torque converter specialists face displacement as commercial vehicle OEMs award sole-source contracts for complete powertrain packages. This concentration is most visible in North American Class 8 truck segments, where vertically integrated powertrain divisions now specify proprietary converter designs unavailable to aftermarket channels.
Torque Converter Market Segmentation
Torque converter procurement splits sharply between cost-driven volume segments and efficiency-focused premium tiers. Technology selection and application requirements determine supplier margins more than raw production scale.
Product Type:
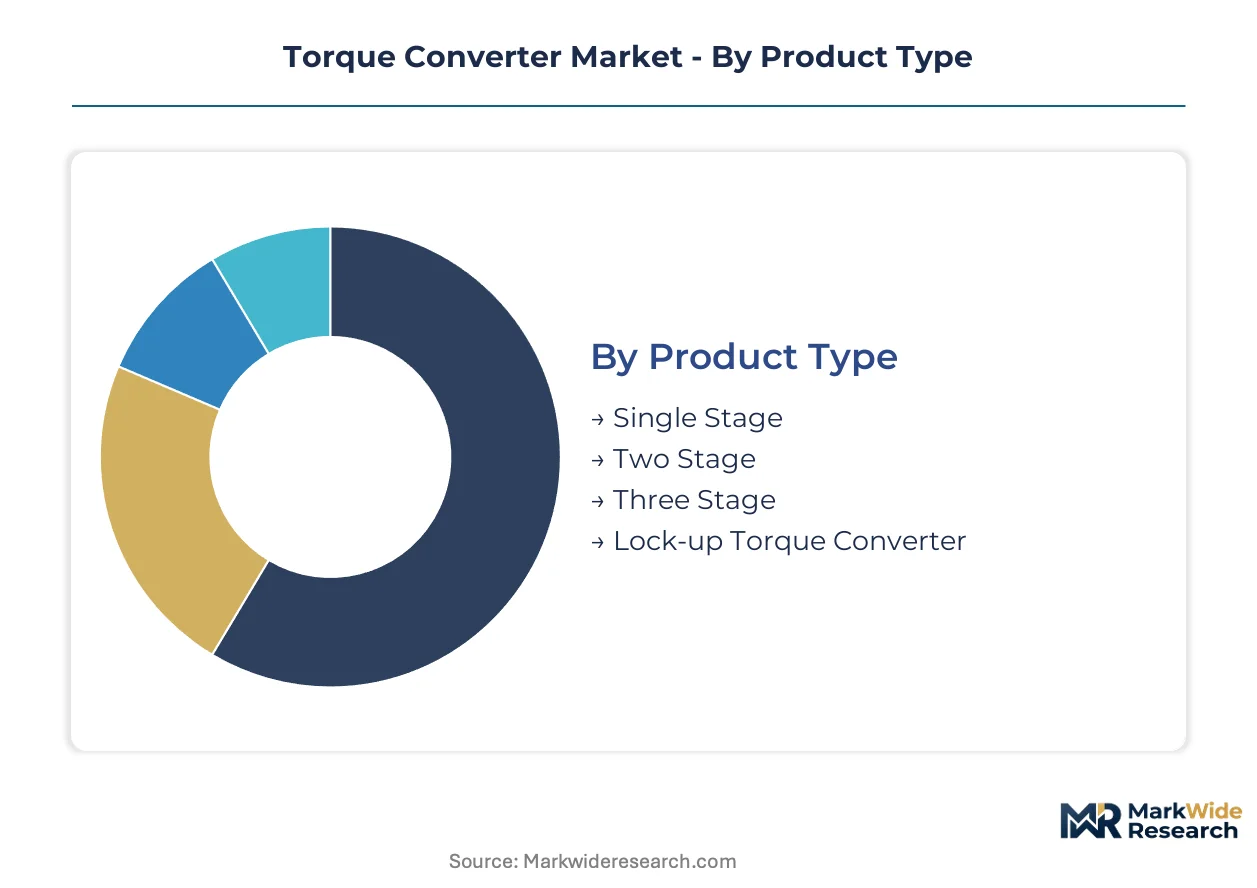
Volume concentrates in single-stage architectures while premium value migrates toward lock-up variants with integrated clutch mechanisms.
- Single Stage:Simple pump-turbine-stator geometry dominates agricultural tractors and entry commercial vehicles across India and Southeast Asia. Cost-sensitive fleet operators in these markets prioritize purchase price over highway fuel economy, sustaining demand despite inferior thermal efficiency.
- Lock-up Torque Converter:Mechanical clutch bypass eliminates hydraulic slippage during steady-state operation, delivering compliance with EPA Phase 3 and EU Green Deal efficiency mandates. North American Class 8 truck specifications now require continuous lock-up capability above 35 km/h, compressing fluid coupling windows to regulatory minimums.
- Two Stage:Dual turbine configurations serve medium-duty delivery trucks requiring balanced launch torque and cruising efficiency.
- Three Stage:Complex multi-element designs persist in specialized mining haulers and oversized construction equipment where stall ratio customization outweighs packaging constraints.
Mature deployment sits with single-stage converters. Newer deployment is concentrated in lock-up architectures.
Technology:
Actuation method determines calibration precision and integration depth with hybrid powertrain control systems.
- Electro-Hydraulic:Solenoid-controlled valve bodies enable millisecond lock-up engagement synchronized with engine restart events in hybrid buses and trucks. German and Japanese manufacturers specify these modules for seamless transition between electric and combustion modes, collapsing historical separation between mechanical and electronic engineering teams.
- Hydraulic:Conventional governor-pressure control remains the volume foundation in price-sensitive emerging markets where transmission fluid quality and maintenance infrastructure limit electronic system reliability.
- Mechanical:Centrifugal and throttle-valve actuation persists in legacy agricultural equipment with minimal electronic content.
- Electrical:Fully electric actuation without hydraulic intermediaries is gaining traction in battery-electric commercial vehicle prototypes requiring simplified thermal management.
- Pneumatic:Compressed-air control systems survive in specialized rail and marine applications where hydraulic fluid contamination risks exceed electronic complexity tolerance.
Proven reliability sits with hydraulic control. Steepest expansion trajectory belongs to electro-hydraulic integration.
Application:
Load variability and duty cycle intensity dictate converter sizing and thermal management requirements across equipment categories.
- Commercial Vehicles:Highway trucking fleets in the United States drive specification for extended lock-up duty cycles under EPA compliance pressure. Urban delivery operators in European cities prioritize stop-start durability over cruising efficiency.
- Agricultural Machinery:Field-load variability in tractors and harvesters creates demand for torque converter-hybrid integration, with OEMs exploring electro-hydraulic modules to manage PTO engagement shocks.
- Construction Equipment:Excavator and loader manufacturers in China's eastern manufacturing corridor specify heavy-duty single-stage units for intermittent high-torque demands.
- Marine Vessels:Naval architects specify multi-stage converters for tugs and offshore supply vessels requiring precise bollard pull control.
- Rail Transport:Locomotive rebuild programs in India and Russia sustain demand for pneumatically governed units in legacy diesel-electric platforms.
Standardized volume sits with commercial vehicles. Technical differentiation concentrates in agricultural and marine segments.
End User:
Channel structure determines warranty liability and aftermarket access, with integrated powertrain suppliers displacing independent specialists.
- OEMs:Vertically integrated transmission divisions at major truck manufacturers now specify proprietary converter designs unavailable to external channels, consolidating procurement around complete powertrain packages.
- Aftermarket Suppliers:Independent distributors build certified remanufacturing programs for out-of-warranty commercial vehicle converters, competing on core exchange economics rather than new unit pricing.
- Vehicle Assemblers:Contract manufacturers and kit builders in emerging markets source open-catalogue converters without transmission integration support.
- Equipment Dealers:Agricultural and construction machinery distribution networks provide field service and fluid replacement, capturing recurring revenue from installed base maintenance.
Direct procurement sits with OEM captive supply. Channel expansion is concentrated in aftermarket remanufacturing networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in China's eastern manufacturing corridor while consumption splits across heavy-duty fleet replacement cycles in North America, regulatory compliance drives in Europe, and commercial vehicle expansion in India.
United States
Class 8 truck fleets accelerate lock-up torque converter procurement ahead of EPA Phase 3 compliance deadlines. The EPA and NHTSA coordinate testing protocols that directly influence lock-up calibration requirements. Detroit and Columbus anchor transmission assembly operations where vertically integrated powertrain divisions specify proprietary converter designs.
China
Domestic automakers expand dual-clutch and CVT integration with optimized torque converter modules to meet MIIT corporate average fuel consumption targets. The Ministry of Industry and Information Technology tightens enforcement through GB standards certification. Shanghai and Tianjin host transmission assembly plants within a 200-kilometer corridor that processes the majority of regional converter demand.
Germany
Premium truck manufacturers specify electro-hydraulic modules for seamless engine-start transitions in hybrid bus and truck platforms. The EU Green Deal's transport decarbonization pathway mandates mechanical efficiency gains exceeding conventional fluid coupling physics. Stuttgart and Friedrichshafen anchor integrated transmission-converter development where mechanical and electronic engineering teams have collapsed historical separation.
India
Light commercial vehicle fleets face escalating procurement requirements for lock-up converters as BIS tightens fuel efficiency test-cycle stringency. The Bureau of Indian Standards enforces tiered compliance schedules that accelerate fleet retrofit decisions. Pune and Chennai host agricultural machinery and entry commercial vehicle assembly where single-stage architectures retain cost-sensitive volume dominance.
Japan
Hybrid powertrain architects demand faster lock-up engagement cycles, creating specification pull for electronically controlled converter variants. METI coordinates industrial policy supporting electrified actuation technology development. Toyota City and Nagoya anchor transmission control unit software integration where converter behavior converges with powertrain management systems.
Torque Converter Market Key Industry Players
The competitive structure tilts toward integrated transmission-converter module vendors displacing independent specialists. Vertically integrated powertrain divisions at major truck manufacturers consolidate procurement around complete packages, compressing aftermarket access. Three archetypes dominate: captive transmission divisions with proprietary converter designs, independent hydraulic component specialists, and electro-hydraulic technology integrators serving hybrid architectures. Capacity expansion in China's eastern corridor and strategic partnerships for software stack integration represent the dominant competitive moves.
Among German-based integrated suppliers, ZF Friedrichshafen AG and Schaeffler AG occupy positions exemplifying the captive transmission division archetype, while Voith GmbH & Co. KGaA represents the electro-hydraulic integration specialist tier. Aisin Corporation anchors Japanese-origin supply for hybrid powertrain applications. These entities sit within a structure where fleet procurement departments consolidate relationships around module vendors capable of delivering complete powertrain packages rather than discrete converter components.
| Leading Market Players |
|---|
| Aisin Corporation |
| ZF Friedrichshafen AG |
| BorgWarner Inc. |
| Schaeffler AG |
| Valeo SA |
| Continental AG |
| Voith GmbH & Co. KGaA |
| Allison Transmission |
| EXEDY Corporation |
| Others |
Cost & Logistics Intelligence
Family-owned mid-cap specialists across Germany and Japan anchor converter supply, their conservative balance sheets limiting capacity expansion despite lock-up demand surges from EPA and EU Green Deal compliance deadlines. This ownership pattern concentrates pricing power with integrated transmission divisions while squeezing independent hydraulic component vendors on margin.
Pricing Analysis
Margin tightening in lock-up converter tiers reflects dual-mass flywheel substitution pressure in European light commercial segments and electro-hydraulic R&D amortization. Three-tier pricing structure across premium, standard, and economy levels separates ZF and BorgWarner integrated modules from Aisin hybrid-optimized variants and Chinese single-stage volume producers. Certification grade differentiation intensifies as EPA Phase 3 and MIIT GB standards enforcement raises compliance costs. Fleet procurement departments at North American Class 8 operators exhibit lowest price sensitivity, prioritizing fuel economy gains over unit cost.
Supply Chain Analysis
Hardened pump impeller stampings rest on controlled-carbon steel grades from Japanese and South Korean specialty mills, with secondary forging capacity concentrated in China's eastern manufacturing corridor. Input dependencies span ferroalloy pricing volatility, precision stamping dies, and transmission fluid formulation IP. Single-region logistics exposure through the Tianjin-Shanghai corridor creates vulnerability to port congestion and regional lockdowns. Distribution runs through vertically integrated OEM captive supply chains, compressing aftermarket access for independent rebuild specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Powertrain divisions pursue backward integration into proprietary converter designs to lock fleet procurement departments into sole-source powertrain packages.
For Market Incumbents: Lock in fleet procurement relationships through integrated transmission-converter module contracts that exclude aftermarket channel access. Expand electro-hydraulic calibration capacity in Stuttgart and Nagoya to capture hybrid bus and truck specifications from German and Japanese OEMs. Dual-mass flywheel substitution in European light commercial segments threatens single-stage volume; respond with lock-up retrofit programs for existing fleet installed base.
For New Entrants and Emerging Players: E-commerce aftermarket channels offer the most penetrable route for independent remanufacturing specialists seeking core exchange economics against OEM captive supply. Target India's BIS tier compliance acceleration as light commercial vehicle fleets face escalating retrofit requirements. Agricultural machinery electrification creates white-space for torque converter-hybrid integration modules managing PTO engagement shocks.
For Investors and Strategic Acquirers: Distressed-cycle entries favor electro-hydraulic technology integrators with software stack capabilities in Japan and Germany. Long-term viability hinges on convergence with transmission control unit architectures and millisecond lock-up precision for hybrid powertrains. Monitor EPA Phase 3 enforcement velocity and EU Green Deal heavy-duty CO2 reduction trajectory as inflection signals for lock-up duty cycle extension demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Proprietary Converter Design | Vertically integrated powertrain divisions at Detroit and Columbus anchor sole-source fleet contracts. |
| Electro-Hydraulic Actuation Scale-Up | Stuttgart and Friedrichshafen development centers collapse mechanical-electronic engineering separation for hybrid platforms. |
| Aftermarket Remanufacturing Certification | Independent distributors build core exchange economics competing against OEM captive supply channels. |
| Software Stack Integration Partnership | Toyota City and Nagoya transmission control unit convergence enables millisecond lock-up synchronization. |
| Geographic Manufacturing Footprint Expansion | Pune and Chennai assembly addresses India BIS efficiency tier compliance acceleration. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across transmission control unit software engineers, OEM platform procurement managers, fleet maintenance directors, and aftermarket distribution channel heads. EPA Phase 3 rulemaking dockets, MIIT GB standard certification databases, EU Green Deal transport decarbonization impact assessments, and BIS efficiency tier compliance schedules provided regulatory validation. Bottom-up unit shipment modeling triangulated against top-down value estimates from integrated powertrain division revenue disclosures.
Product type, technology actuation method, application segment, and end-user channel were modeled at country-level granularity across the analysis window. CAGRs derived from regression against historical fleet replacement cycles and regulatory compliance deadline clustering. Lock-up duty cycle extension rates, electro-hydraulic module penetration in hybrid architectures, and single-stage volume retention in agricultural machinery informed segment-specific trajectory assumptions.
The model holds under steady regulatory enforcement timelines; deviation in EPA Phase 3 delay litigation, EU Green Deal ambition recalibration, or China MIIT enforcement intensity would shift fleet procurement acceleration patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Transmission Fluid Market
Powertrain
Automotive Camshaft Market
Powertrain
South America Automotive Market
Powertrain
Diesel Engine Market
Powertrain
Europe Electrically Powered Hydraulic Steering Market
Powertrain
Engine Flush Market
Powertrain
Tuning Box Market
Powertrain
Automotive Clutch Actuator Market
Powertrain
United Kingdom Automotive Engine Oils Market
Powertrain
Automatic Transmission Market
Powertrain
Automotive Intermediate Shaft Market
Powertrain
Electric Vehicle Powertrain Market
Powertrain
EGR and Emissions Control Actuator Systems Market
Powertrain
Clutch Market
Powertrain
Automotive Performance Tuning Market
Powertrain
Global Automotive Electric Drivetrain System Market