
 Automotive Variable Discharge Oil Pump Market | 2026-2036
Automotive Variable Discharge Oil Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Variable Discharge Oil Pump Market Analysis
Asset-light manufacturing partnerships and third-party pump leasing arrangements is fragmenting competitive control across the supply base. Delphi Automotive LLP leverages captive forging operations to sustain cost discipline on precision gear sets. Aisin World Corp. anchors its position through integrated casting-to-assembly lines serving Toyota and Lexus powertrain programs. NIDEC GPM GmbH specializes in compact vane pump architectures for European passenger vehicle platforms.
An automotive variable discharge oil pump modulates lubricant flow rate in response to real-time engine speed, temperature, and load conditions, typically achieving pressure ranges of 2–6 bar through solenoid-controlled displacement mechanisms. The device reduces parasitic engine losses by supplying only the required oil volume rather than fixed full-flow circulation. Gear pumps occupy the dominant share in mechanical actuation systems for light-duty applications, while electromechanical technology leads growth trajectories as 48-volt mild-hybrid architectures proliferate. Vane pumps retain margin concentration in heavy commercial vehicle segments where durability under sustained high-load operation commands premium positioning.
The EPA Corporate Average Fuel Economy program and the European Commission's Euro 7 emission framework mandate measurable reductions in engine friction losses, directly accelerating OEM specification of variable discharge architectures. China's Ministry of Industry and Information Technology enforces dual carbon goals that pressure domestic vehicle assemblers toward electrified thermal management including variable oil flow systems. Stakeholders must monitor regulatory calibration timelines across the United States, Europe, and China to align R&D pipelines with compliance windows.
Market Dynamics
Electromechanical actuation architectures are compressing mechanical pump margins as 48-volt mild-hybrid platforms mandate real-time flow modulation. OEM procurement committees in Germany, Japan, and the United States now specify solenoid-controlled displacement as baseline for new powertrain programs.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:Mandated friction-loss reductions force Detroit Three automakers to specify variable discharge units across light-truck and passenger car portfolios.
- Electromechanical solenoid control:Precision pressure modulation between 2–6 bar enables thermal management integration with engine control modules.
- China's dual carbon goals:MIIT enforcement pressures domestic assemblers toward electrified oil flow systems in volume passenger vehicle segments.
Market Restraints
- Precision forging cost volatility:Specialized steel alloys for gear sets face input price pressure from energy-intensive European foundry operations.
- Electronics supply concentration:Solenoid driver modules depend on concentrated Southeast Asian semiconductor packaging capacity.
- Mechanical pump substitution ceiling:Fixed-displacement architectures retain cost advantage in emerging-market commercial vehicle segments.
Strategic Opportunities
- Indian passenger vehicle electrification:BIS certification pathways for 48-volt systems create first-mover positioning for variable pump suppliers.
- Battery thermal management convergence:Integration of oil flow control with electric vehicle battery conditioning loops opens adjacent specification channels.
- Third-party pump leasing:Asset-light service models penetrate commercial fleet operators seeking operational expenditure flexibility.
Industry Challenges
- Mechatronics skill scarcity:Cross-functional engineering talent spanning hydraulics, electronics, and embedded software commands premium compensation.
- Euro 7 calibration timelines:Compressed validation windows strain test cell availability and regulatory submission sequencing.
- Legacy engine control integration:Backward compatibility with existing ECU architectures extends development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Variable Discharge Oil Pump Market |
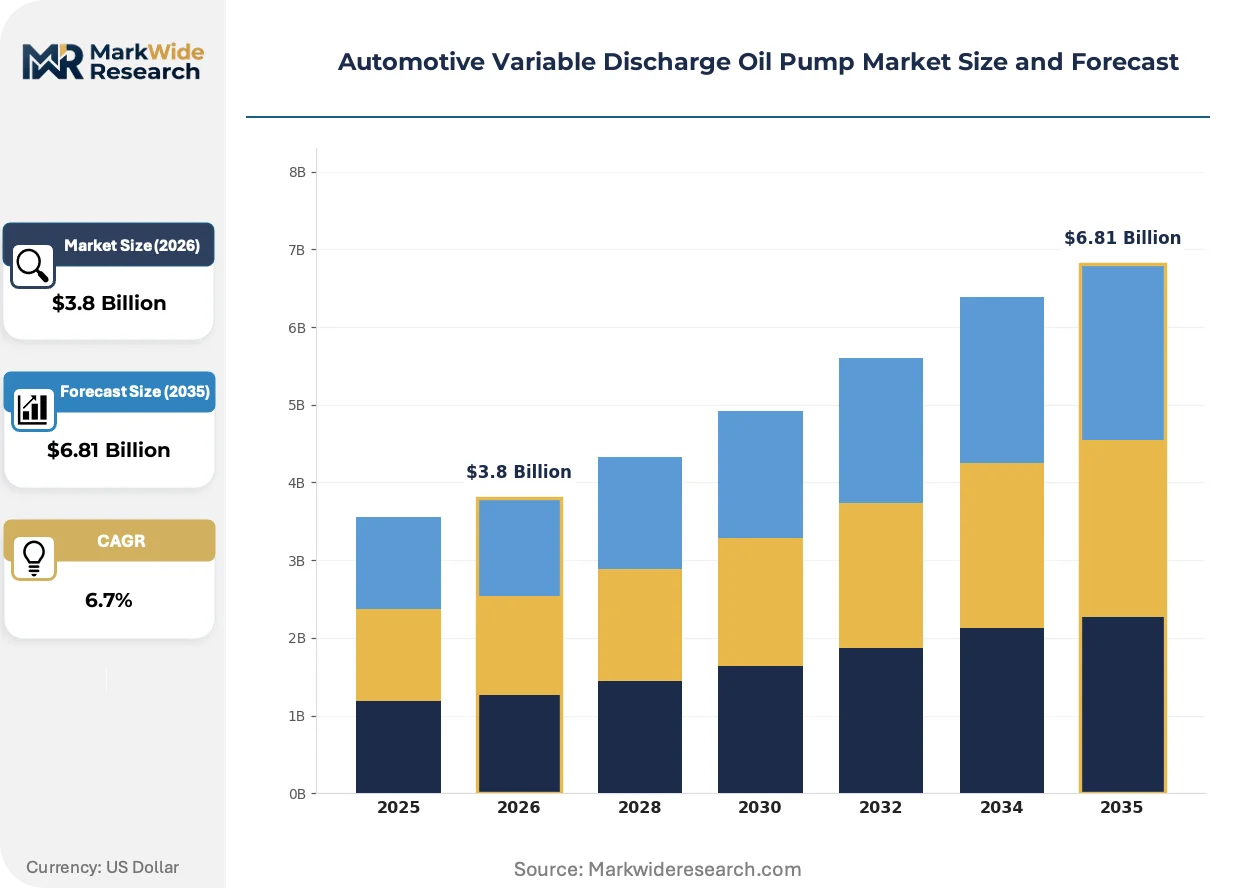
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gear Pumps, Vane Pumps, Screw Pumps, Centrifugal Pumps End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Technology: Electromechanical, Mechanical, Hydraulic, Pneumatic Application: Passenger Vehicles, Commercial Vehicles, Motorcycles, Heavy Machinery |
| Companies Covered | Delphi Automotive LLP, SHW Group, Aisin World Corp., Hitachi Astemo, NIDEC GPM GmbH, Denso Corporation, Magna International, Continental AG, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Variable Discharge Oil Pump Market Emerging Trajectories
Real-time sensor fusion and edge computing are redefining pump control architectures. Electrification mandates across multiple geographies accelerate specification of intelligent flow modulation systems.
Electromechanical vane pumps with integrated pressure transducers enable closed-loop flow control independent of engine speed. Passenger vehicle OEMs in Germany and Japan are specifying these architectures for 48-volt mild-hybrid platforms. Fixed-gear mechanical pumps is rendering obsolete in light-duty applications where fuel economy certification depends on parasitic loss minimization.
Euro 7 emission limits impose measurable engine friction reduction targets with 2025 enforcement windows. European Commission calibration requirements compress supplier development cycles and elevate validation documentation standards. Electromechanical variable discharge units capture specification share in compact passenger vehicles where thermal management integration determines compliance margins.
Powertrain procurement committees now require pump suppliers to assume lifecycle thermal performance accountability. Traditional component supply contracts yield to outcome-based service agreements with guaranteed efficiency thresholds. This shift concentrates most visibly in German premium passenger vehicle programs where OEMs transfer operational risk downstream.
Automotive Variable Discharge Oil Pump Market Segmentation
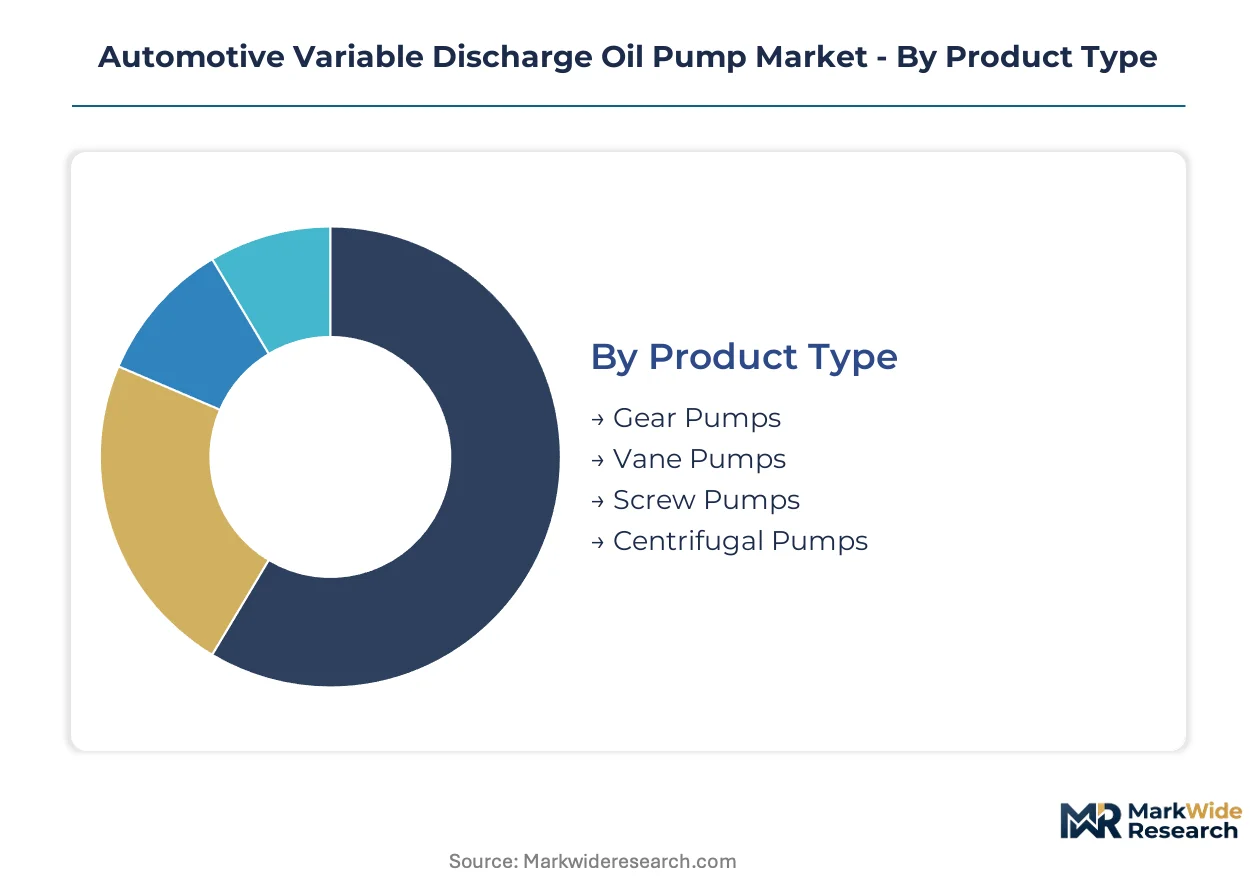
Segmentation in the automotive variable discharge oil pump market reveals how technical specifications, procurement channels, and actuation architectures diverge across vehicle platforms. Understanding these divides exposes where margin concentrates and which technology transitions command capital allocation priority.
Product Type:
Product architecture determines parasitic loss profiles, forging precision requirements, and thermal integration complexity across light-duty and heavy-duty applications.
- Gear Pumps:Meshing precision gear sets deliver consistent volumetric efficiency across 2–6 bar pressure ranges with minimal slip at high RPM. Passenger vehicle OEMs in Germany and Japan specify these for 48-volt mild-hybrid platforms where cost discipline meets friction-loss mandates.
- Vane Pumps:Sliding vanes within an eccentric rotor housing accommodate variable displacement through solenoid-controlled cam ring positioning. Heavy commercial vehicle segments in the United States retain this architecture for sustained high-load durability where thermal stress exceeds gear pump tolerance limits.
- Screw Pumps:Intermeshing helical rotors generate pulse-free flow ideal for precision bearing lubrication in high-performance powertrains. Premium German passenger vehicle programs specify these for turbocharger oil circuits demanding minimal pressure fluctuation.
- Centrifugal Pumps:Impeller-driven flow modulation eliminates mechanical contact wear, suiting auxiliary cooling loops in battery thermal management systems. Emerging electric vehicle architectures in China integrate these for coolant-oil heat exchanger circuits.
The dominant share belongs to gear pumps, while vane pumps are closing the gap fastest in commercial vehicle electrification.
End User:
Procurement authority determines contract structure, validation burden, and lifecycle accountability allocation across the supply base.
- OEMs:Direct specification power allows Volkswagen, Toyota, and General Motors to mandate electromechanical architectures and assume thermal performance accountability through outcome-based service agreements.
- Tier-1 Suppliers:Delphi Automotive LLP and Aisin World Corp. integrate casting-to-assembly lines to capture margin through captive forging operations and design-for-manufacturing authority.
- Aftermarket Providers:Independent distributors serve legacy fleet operators with mechanical pump replacements where fixed-displacement units retain cost advantage in aging commercial vehicle pools.
- Vehicle Assemblers:Contract manufacturers in China and India procure variable discharge units through MIIT and BIS certification pathways, transferring compliance risk upstream to component suppliers.
OEMs command specification authority, yet Tier-1 suppliers are expanding fastest through integrated manufacturing investments.
Technology:
Actuation mechanism separates legacy mechanical systems from electrified architectures demanded by emission compliance timelines.
- Electromechanical:Solenoid-controlled displacement mechanisms enable real-time flow modulation through engine control module integration, achieving pressure precision within 0.3 bar variance. This architecture captures specification share across German and Japanese passenger vehicle 48-volt platforms.
- Mechanical:Spring-loaded pressure relief valves and fixed cam ring geometries deliver baseline lubrication without electronic complexity. Emerging-market commercial vehicle segments in India and Brazil retain this technology where electrification infrastructure remains underdeveloped.
- Hydraulic:Pilot-operated control circuits modulate displacement through engine oil pressure feedback, bridging mechanical reliability with limited variable output capability. Heavy machinery applications in the United States specify these for hydraulic system integration.
- Pneumatic:Compressed air actuation serves niche auxiliary pump applications in commercial vehicle pneumatic brake system integration, though displacement precision lags electromechanical alternatives.
Electromechanical systems hold the dominant position, while hydraulic technology maintains residual share in heavy machinery integration.
Application:
Vehicle platform characteristics dictate thermal load profiles, duty cycle severity, and integration complexity for pump specification.
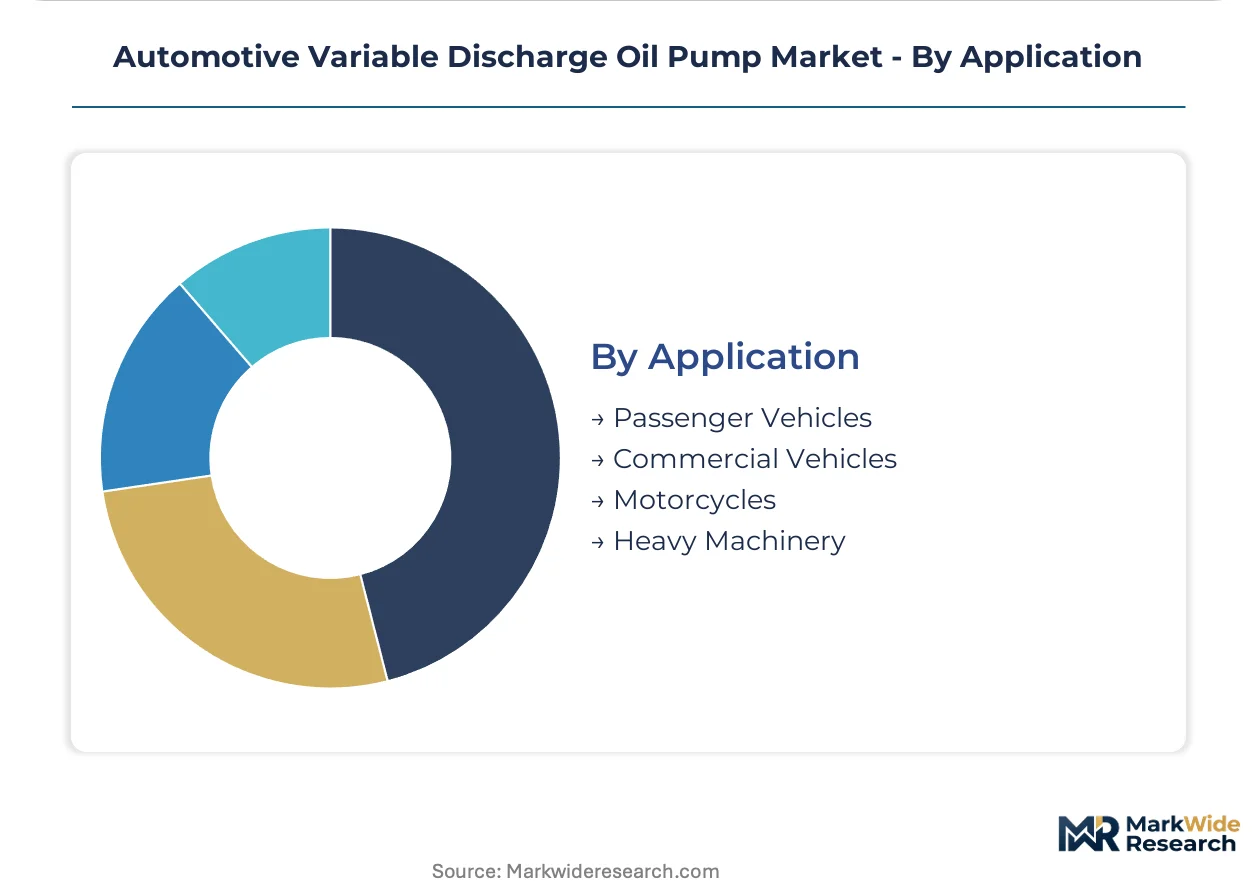
- Passenger Vehicles:Compact engine bays and aggressive fuel economy certification requirements prioritize minimal parasitic loss through intelligent flow modulation. Euro 7 calibration windows compress supplier development cycles for German and Japanese OEMs.
- Commercial Vehicles:Sustained high-load operation and extended service intervals demand vane pump durability and serviceable component architectures. EPA Corporate Average Fuel Economy standards now extend to light-truck portfolios, accelerating variable discharge adoption.
- Motorcycles:Space-constrained crankcase integration favors compact gear pump designs with integrated pressure regulation. Japanese manufacturers lead specification for high-displacement touring and adventure bike segments.
- Heavy Machinery:Construction and agricultural equipment combines severe contamination exposure with intermittent high-load cycles, requiring hardened pump housings and filtration-integrated suction circuits.
Passenger vehicles generate dominant volume, yet commercial vehicles are expanding most quickly under tightening EPA fuel economy mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in precision-forged pump components concentrate between German, Japanese, and Chinese manufacturing clusters, with intra-regional supply chains dominating high-value electromechanical assemblies. The United States maintains a structural deficit in precision gear set forging, sourcing specialized alloys from European foundries while exporting finished pump modules to Canadian and Mexican vehicle assembly plants.
United States
Detroit Three automakers drive procurement volume for light-truck variable discharge units under EPA Corporate Average Fuel Economy mandates. The EPA enforcement timeline compresses supplier validation cycles for 2025-2026 model year powertrains. Michigan and Ohio host concentrated pump module assembly operations serving Midwest transmission plants.
Germany
Premium passenger vehicle OEMs in Bavaria and Baden-Württemberg specify electromechanical architectures for 48-volt mild-hybrid platforms. The European Commission's Euro 7 emission framework imposes measurable engine friction reduction targets with 2025 calibration windows. Stuttgart and Ingolstadt anchor integrated powertrain development clusters where pump suppliers co-locate thermal engineering teams.
China
Domestic vehicle assemblers accelerate variable oil flow system procurement under MIIT dual carbon goal enforcement. The Ministry of Industry and Information Technology certification pathways pressure suppliers toward electrified thermal management integration. Yangtze River Delta manufacturing corridors concentrate casting-to-assembly operations for volume passenger vehicle programs.
Japan
Toyota and Honda procurement committees mandate solenoid-controlled displacement as baseline for new powertrain architectures. METI energy efficiency standards reinforce thermal management integration requirements across compact vehicle segments. Aichi Prefecture maintains captive supply relationships with integrated casting and forging operations.
Automotive Variable Discharge Oil Pump Market Vendor Landscape
On the supply side, the industry is consolidating around three distinct capability tiers: integrated powertrain specialists, electromechanical component pure-plays, and captive forging operations serving single OEM relationships. Strategic archetypes include backward-integrated casting-to-assembly houses, precision gear set forgers, and mechatronics integrators bridging hydraulic and electronic domains. Dominant competitive moves center on captive forging investments to secure alloy supply and outcome-based service contracts transferring lifecycle thermal performance accountability downstream.
Within the integrated powertrain tier, Aisin World Corp. and Delphi Automotive LLP exemplify archetypes combining captive manufacturing with design-for-manufacturing authority. NIDEC GPM GmbH occupies a specialized position in compact vane pump architectures. These three entities anchor distinct strategic vectors: Toyota-Lexus captive supply, Detroit Three cost discipline, and European passenger vehicle platform specialization.
| Leading Market Players |
|---|
| Delphi Automotive LLP |
| SHW Group |
| Aisin World Corp. |
| Hitachi Astemo |
| NIDEC GPM GmbH |
| Denso Corporation |
| Magna International |
| Continental AG |
| Robert Bosch GmbH |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Southeast Asian semiconductor packaging capacity for solenoid driver modules compresses margin structures across electromechanical pump tiers while simultaneously forcing buyers toward dual-source qualification programs. This chokepoint simultaneously widens pricing spreads between premium validated suppliers and economy-tier mechanical alternatives and reshapes procurement committee sourcing mandates toward geographic diversification.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure with volume-scale and certification-grade drivers separating Tier 1 validated suppliers from aftermarket mechanical alternatives. Pricing stratifies across premium electromechanical architectures, standard hydraulic bridging technologies, and economy fixed-displacement units. Cost compression in the economy tier is intensifying because emerging-market commercial vehicle assemblers prioritize first-cost over lifecycle efficiency. Fleet operators exhibit highest price sensitivity, while German premium passenger vehicle OEMs demonstrate lowest sensitivity due to outcome-based thermal performance accountability transfers.
Supply Chain Analysis
Extended payment terms from German and Japanese OEM procurement committees strain working capital for precision forging operations in China and India. Geographic supply concentration centers on Germany for specialized alloy gear sets, China for casting-to-assembly integration, and Japan for captive Toyota-Lexus supply relationships. Raw material dependencies draw from high-grade steel alloys, rare-earth magnet components for solenoid actuators, and precision-machined aluminum housings. Tariff exposure on European specialty steel imports into North American assembly plants constitutes the dominant structural risk. Distribution runs through Tier 1 module suppliers co-located with Midwest and Yangtze River Delta transmission plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across the supplier base creates multiple entry points as 48-volt mild-hybrid platform proliferation fragments procurement authority between legacy mechanical specialists and electromechanical integrators. The shift toward outcome-based service contracts with guaranteed efficiency thresholds enables niche positioning for thermal performance accountability specialists.
For Market Incumbents: Build captive forging moats through backward integration into European specialty alloy supply and Aichi Prefecture-style captive casting operations. Incumbent suppliers should secure dual-source semiconductor packaging relationships to neutralize Southeast Asian concentration risk. Add thermal engineering co-location capacity in Stuttgart and Ingolstadt to defend against platform engineering staff poaching by emerging mechatronics integrators. For New Entrants and Emerging Players: Pursue BIS certification pathways for 48-volt electromechanical architectures in Indian passenger vehicle electrification, the most penetrable geography given nascent supplier relationships and compressed regulatory windows. Target battery thermal management convergence applications where oil flow control integration with electric vehicle conditioning loops remains underspecified. Lead with software-defined pump control modules as the go-to-market angle, offering edge computing architectures that legacy hydraulic suppliers cannot replicate. For Investors and Strategic Acquirers: Euro 7 calibration timelines reshapes the acquisition landscape by compressing validation windows and elevating regulatory documentation standards that only established suppliers can satisfy. Long-term viability over the projection horizon favors precision gear set forgers with existing EPA and MIIT certification pathways. Watch for MIIT enforcement intensity on dual carbon goals as the signal indicating when Chinese domestic assembler procurement shifts decisively toward electromechanical architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Forging Investment | Secures alloy supply discipline for precision gear sets serving Detroit Three programs. |
| Electromechanical Platform Standardization | Enables solenoid-controlled displacement baseline specification across Toyota and Lexus powertrains. |
| Battery Thermal Management Integration | Opens adjacent specification channels in Chinese electric vehicle coolant-oil heat exchanger circuits. |
| Outcome-Based Service Contracting | Transfers lifecycle thermal performance accountability from German OEMs to downstream suppliers. |
| 48-Volt System Certification | Creates first-mover positioning through BIS pathways in Indian passenger vehicle electrification. |
Methodological Framework
A standing panel of OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distribution heads, and thermal management R&D directors provided ongoing calibration across primary fieldwork phases. Secondary validation drew from EPA enforcement documentation, MIIT certification filings, European Commission Euro 7 calibration timelines, vehicle production databases, and IHS Markit registration data. Bottom-up segment sizing triangulated against top-down powertrain production forecasts to ensure consistency across the analysis window.
Scenario-bracketing framed the analytical approach with low, base, and high cases reflecting differential MIIT enforcement intensity and EPA Corporate Average Fuel Economy compliance trajectory variation. Segmentation dimensions modeled encompass product architecture, actuation technology, vehicle application, end-user procurement authority, and regional production cluster. CAGRs were derived from fitted growth curves anchored to named regulatory milestone enforcement windows and validated against historical penetration patterns in comparable thermal management component markets.
Macroeconomic conditions sit as an overlay; deviation in specialty steel alloy pricing, semiconductor packaging capacity utilization, or euro-dollar exchange rate volatility would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory calibration timelines and OEM platform engineering resource allocation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
UAE Automotive Engine Oils Market
Powertrain
Automotive Engine Degreasers Market
Powertrain
Global Powertrain Market
Powertrain
North America Electrically Powered Hydraulic Steering Market
Powertrain
Transmission Sales Market
Powertrain
Automotive Vacuum Brake Booster Market
Powertrain
Automotive Clutch Slave Cylinder Market
Powertrain
Advanced Gear Shifter System Market
Powertrain
Truck Auxiliary Power Units Market
Powertrain
Automotive Fuel Pulsation Damper Market
Powertrain
Automotive Coil Spring Market
Powertrain
Emission Control Catalyst for Small Engines Market
Powertrain
Automotive Power Distribution Block Market
Powertrain
Global Automotive Clutch Market
Powertrain
Synchronizer for Dual-Clutch Transmissions (DCT) Market
Powertrain
United States Automotive Engine Oils Market