
 Automotive Air Intake Manifold Market | 2026-2036
Automotive Air Intake Manifold Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Air Intake Manifold Market Analysis
IATF 16949 qualification is unwinding the supplier base, filtering out uncertified tier-two manufacturers across North America and Europe. MANN+HUMMEL leverages in-house filtration expertise to bundle air intake modules with integrated sensors, capturing higher value per engine bay. Toyota Boshoku anchors its position through captive supply to Toyota Motor's hybrid platforms, while MAHLE GmbH competes across aluminum and composite manifold variants with foundry-to-assembly integration.
An automotive air intake manifold is a plenum chamber that distributes combustion air to engine cylinders, typically molded from glass-reinforced polyamide or cast from aluminum alloy to withstand temperatures exceeding 130°C and pressure pulsations across thousands of thermal cycles. Its primary function is to optimize air-fuel mixture uniformity, directly influencing engine efficiency, emissions output, and throttle response. Plastic manifolds lead volume in gasoline applications due to weight savings and acoustic damping, while aluminum retains structural dominance in diesel and performance segments where boost pressures exceed plastic fatigue limits. Hybrid engine types represent the fastest-growing category as electrified powertrains require compact, thermally isolated intake architectures distinct from conventional ICE layouts.
EPA tailpipe standards and the EU Green Deal's 55% CO2 reduction mandate for passenger vehicles are forcing manifold redesigns toward thinner-wall composites and integrated charge-air cooling, with both frameworks penalizing excess engine mass. China's MIIT enforces corporate average fuel consumption limits that push domestic OEMs toward plastic manifolds in sub-2.0L turbocharged engines. Stakeholders must monitor how Euro 7's expanded cold-start emission testing windows reshape thermal management requirements and whether that shifts procurement preference back toward aluminum or toward next-generation polymer formulations.
Market Dynamics
Hybrid powertrain proliferation is forcing intake manifold architectures toward compact, thermally isolated designs that diverge from conventional ICE layouts, compressing development cycles and rewiring supplier-OEM relationships across the value chain.
Growth Catalysts
- EPA Tier 3 particulate thresholds:Tightening NOx and particulate limits are mandating lighter manifold designs with improved thermal efficiency, accelerating composite adoption in North American passenger vehicle programs.
- China MIIT fuel consumption mandates:Corporate average fuel economy rules are pushing domestic OEMs toward plastic manifolds in sub-2.0L turbocharged gasoline engines, localizing supply chains around glass-reinforced polyamide formulations.
- Hybrid engine thermal isolation requirements:Electrified powertrains demand distinct intake architectures with reduced heat soak, creating specialized procurement categories separate from conventional ICE sourcing.
Market Restraints
- Glass fiber and polyamide resin volatility:Raw material price swings for composite feedstocks compress margin buffers for tier-two molders lacking long-term supply agreements.
- Aluminum foundry concentration in Germany and China:Structural dependence on cast aluminum capacity in specific geographies creates supply vulnerability when boost-pressure diesel applications require metal durability beyond polymer fatigue limits.
- Euro 7 cold-start testing expansion:Extended emission measurement windows are forcing costly thermal management redesigns, extending validation timelines and freezing procurement decisions until compliance pathways clarify.
Strategic Opportunities
- Integrated sensor modules:Convergence of air intake and filtration functions with pressure and temperature sensing creates higher-value bundled offerings, displacing discrete component sourcing.
- India PLI scheme for auto components:Production-linked incentives for advanced automotive parts are attracting composite manifold investment as domestic OEMs expand hybrid and small-displacement turbo engine lines.
- Charge-air cooling integration:Embedded intercooler architectures within polymer manifolds represent an unpenetrated design space for next-generation downsized turbocharged engines.
Industry Challenges
- IATF 16949 certification timelines:Quality management system qualification requirements are filtering out uncertified suppliers, constraining available manufacturing capacity during platform ramp-ups.
- Multi-material bonding expertise:Hybrid aluminum-composite manifold assemblies require specialized joining processes that outpace current workforce skill availability in traditional metalworking regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Air Intake Manifold Market |
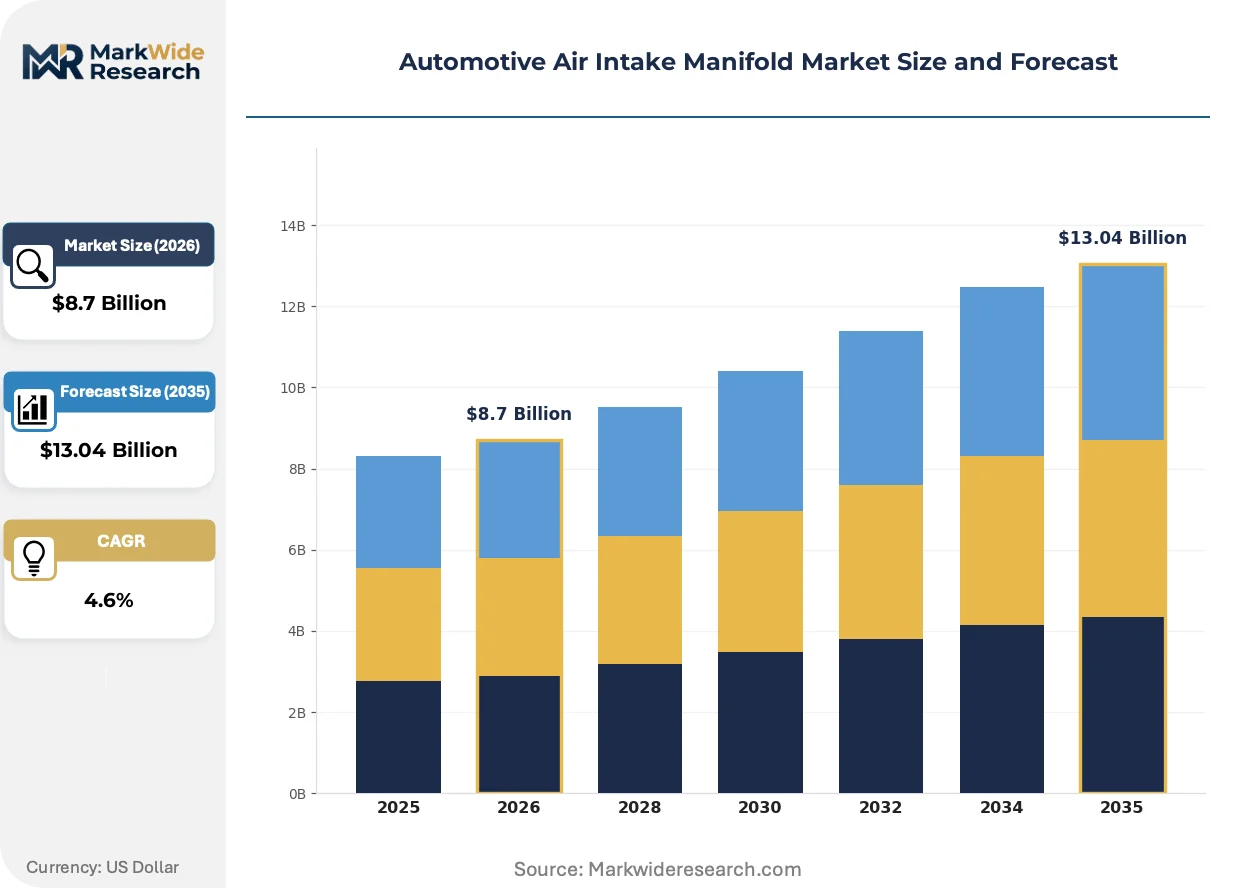
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Aluminum, Composite, Magnesium Engine Type: Gasoline, Diesel, Hybrid, Electric Vehicle Type: SUV, Sedan, Truck, Van Manufacturing Process: Injection Molding, Casting, Machining, 3D Printing |
| Companies Covered | Aisin Seiki, Marelli, MANN+HUMMEL, Continental Aktiengesellschaft, Toyota Boshoku, MAHLE GmbH, Roechling, Robert Bosch GmbH, Sogefi SpA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Air Intake Manifold Market Emerging Trajectories
Active material substitution and embedded intelligence are converging to redefine manifold value propositions, shifting competition from commodity molding toward integrated thermal-fluid systems engineering.
Glass-reinforced polyamide with 35-50% fiber loading is supplanting cast aluminum in gasoline turbo applications up to 1.8 bar boost pressure. Tier-one suppliers are accelerating composite adoption in C-segment passenger cars where weight reduction targets exceed 25% versus metal equivalents. This material transition is compressing foundry capacity utilization in traditional aluminum supply basins while expanding in-house compounding investments among resin processors.
The EU Green Deal's 55% CO2 reduction mandate for passenger vehicles is forcing manifold wall-thinning and integrated charge-air cooling architectures. OEM engineering teams are redesigning plenum chambers to reduce thermal mass and improve transient response during cold-start emission windows. European premium passenger vehicle platforms are most affected, with procurement specifications now penalizing excess engine bay mass through total cost of ownership models.
Sensor-integrated intake modules are consolidating discrete component sourcing into single-source system contracts. Tier-one filtration specialists are capturing manifold procurement decisions through bundled air management offerings that include pressure, temperature, and humidity sensing. This consolidation pattern is most visible in Japanese and Korean OEM supply chains, where keiretsu relationships favor captive system suppliers over independent molders.
Automotive Air Intake Manifold Market Segmentation
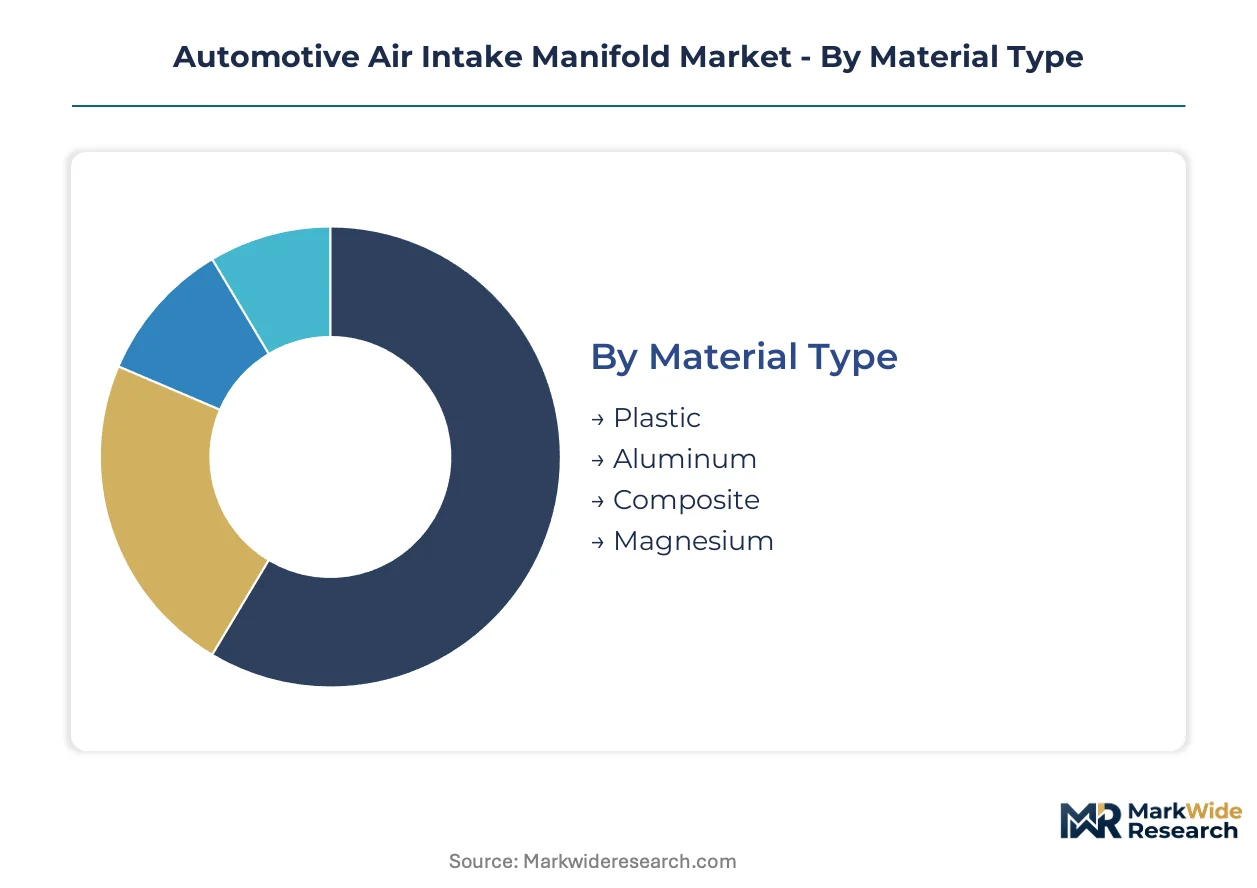
Intake manifold procurement channels diverge sharply by material and engine architecture, with OEM direct sourcing dominating aluminum programs while tier-one system suppliers control plastic manifold distribution. Understanding these channel dynamics reveals where margin pools concentrate and which segments offer supplier entry points.
Material Type:
Channel mix varies by material: plastic manifolds flow predominantly through tier-one system suppliers with in-house compounding, while aluminum programs favor direct OEM-foundry relationships with machining subcontractors.
- Plastic:Glass-reinforced polyamide formulations withstand temperatures exceeding 130°C while delivering 25% weight reduction versus metal equivalents. Demand concentrates in China's sub-2.0L turbocharged gasoline engines where MIIT fuel consumption mandates push domestic OEMs toward localized composite supply chains.
- Aluminum:Cast aluminum alloys retain structural dominance in diesel and high-boost applications where pressure pulsations exceed polymer fatigue limits. Foundry capacity concentrates in Germany and China, creating geographic supply vulnerability when procurement timelines compress.
- Composite:Hybrid material stacks combining polymer cores with metal flanges address thermal isolation requirements in electrified powertrains.
- Magnesium:Lightweight castings occupy niche performance segments where mass reduction justifies premium material costs.
By volume, plastic leads. By growth pace, composite is climbing the fastest.
Engine Type:
Application requirements dictate procurement patterns: gasoline programs favor standardized plastic architectures, while hybrid and diesel engines demand specialized thermal management designs with extended validation cycles.
- Gasoline:Downsized turbocharged engines drive standardized plastic manifold platforms with integrated charge-air cooling. Volume procurement concentrates in C-segment passenger vehicles where OEMs prioritize cost efficiency over thermal customization.
- Hybrid:Electrified powertrains require compact, thermally isolated intake architectures distinct from conventional ICE layouts. Toyota Boshoku and captive suppliers capture this segment through platform-specific development partnerships.
- Diesel:Boost pressures above 2.0 bar mandate aluminum or cast iron construction with enhanced fatigue resistance.
- Electric:Battery electric vehicles eliminate traditional intake manifolds, though range-extender hybrids retain compact plenum requirements.
Gasoline commands absolute volume. Hybrid platforms are expanding most quickly as electrification penetrates mainstream vehicle classes.
Vehicle Type:
Customer type segmentation reveals divergent cost structures: fleet procurement for trucks and vans prioritizes durability and service intervals, while retail-driven SUV and sedan segments emphasize NVH performance and weight reduction.
- SUV:Mid-size and full-size utility vehicles balance towing capacity requirements with fuel economy targets, driving mixed material strategies. North American OEMs specify aluminum for turbocharged V6 applications while adopting plastic for base four-cylinder variants.
- Sedan:Passenger car programs emphasize acoustic damping and packaging efficiency in crowded engine bays. European premium sedans under EU Green Deal CO2 mandates are thinning manifold walls and integrating sensors to reduce total engine bay mass.
- Truck:Commercial and heavy-duty applications prioritize thermal durability over weight savings.
- Van:Fleet-operated light commercial vehicles favor serviceable designs with extended replacement intervals.
Sedan applications retain volume leadership. SUV segments are gaining share fastest as consumer preference shifts toward utility vehicle architectures.
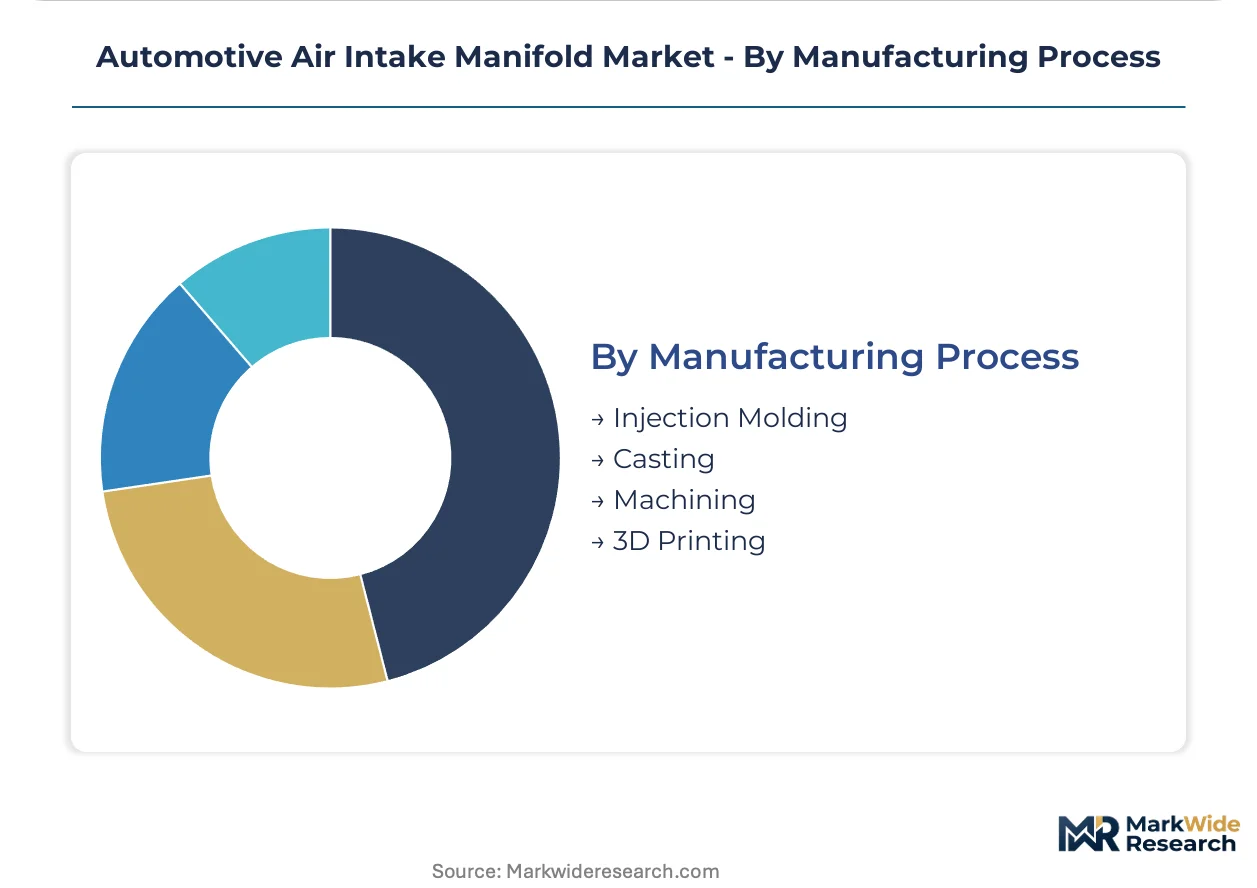
Manufacturing Process:
Margin structure varies by process maturity: injection molding offers scale economies for plastic platforms, while casting and machining retain cost advantages in lower-volume aluminum applications.
- Injection Molding:High-pressure molding of glass-reinforced polyamide enables complex internal geometries with integrated mounting features. Tooling investments favor programs exceeding 100,000 units annually, concentrating production among tier-one suppliers with captive compounding operations.
- Casting:Gravity and low-pressure aluminum casting dominates diesel and performance gasoline applications. German and Chinese foundries anchor supply, with IATF 16949 certification filtering out uncertified tier-two capacity.
- Machining:CNC finishing of cast blanks addresses tight tolerance requirements for sealing surfaces and sensor bores.
- 3D Printing:Additive manufacturing enables rapid prototyping and low-volume tooling for hybrid architecture development.
Injection molding leads by unit volume. 3D printing is expanding most quickly from prototyping into bridge production for hybrid powertrain development programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Passenger vehicle OEMs in China, Germany, and the United States drive procurement volumes for intake manifold systems, with each market imposing distinct regulatory pressures on material selection and thermal management architecture.
China
Domestic automakers including BYD and Geely are scaling hybrid powertrain production lines, creating specialized demand for compact, thermally isolated intake designs. MIIT corporate average fuel consumption mandates push OEMs toward glass-reinforced polyamide manifolds in sub-2.0L turbocharged engines. Yangtze River Delta manufacturing clusters around Shanghai are localizing plastic manifold supply chains to reduce import dependency.
Germany
Premium passenger vehicle platforms from BMW and Mercedes-Benz require thinner-wall composite manifolds with integrated charge-air cooling to meet EU Green Deal CO2 reduction targets. KBA enforcement of Euro 7 pre-certification timelines is extending validation cycles for new manifold architectures. Bavarian and Baden-Württemberg engineering centers are redesigning plenum chambers to reduce thermal mass and improve cold-start emission performance.
United States
Detroit Three OEMs are balancing aluminum and composite strategies across SUV and light truck segments, with turbocharged V6 applications retaining metal construction. EPA Tier 3 particulate and NOx thresholds are accelerating composite adoption in passenger car programs. Southeast manufacturing corridors in Tennessee and South Carolina are attracting tier-one injection molding investments to serve regional assembly plants.
Japan
Keiretsu supply relationships favor captive system suppliers over independent molders, concentrating procurement decisions within Toyota, Honda, and Nissan affiliate networks. METI carbon neutrality roadmaps are pushing electrified powertrain architectures that require distinct intake designs. Kanto region engineering centers around Tokyo are developing sensor-integrated intake modules that consolidate air management functions.
India
Domestic OEMs including Tata Motors and Mahindra are expanding hybrid and small-displacement turbo engine lines, creating procurement opportunities for composite manifold suppliers. PLI scheme production-linked incentives for advanced automotive components are attracting foreign direct investment in injection molding capacity. Tamil Nadu and Gujarat automotive clusters are emerging as preferred locations for tier-one manifold manufacturing.
Automotive Air Intake Manifold Market Vendor Landscape
Player mix skews toward tier-one system suppliers with in-house compounding and captive OEM relationships, creating a tiered structure where IATF 16949 certification filters out uncertified molders. Three archetypes dominate: filtration specialists bundling air intake with sensor modules, captive suppliers serving single OEM hybrid platforms, and foundry-integrated metalworkers competing across aluminum variants. Competitive moves concentrate on M&A to secure compounding capabilities and strategic partnerships to embed charge-air cooling into polymer architectures.
Among Japanese keiretsu-affiliated suppliers, Toyota Boshoku and Aisin Seiki exemplify the captive-platform archetype through their integration with Toyota Motor's hybrid powertrain development. Continental Aktiengesellschaft and MANN+HUMMEL occupy positions within the European filtration-specialist tier, leveraging air management expertise to capture higher-value system contracts. These named entities represent how geographic origin and corporate structure shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| Aisin Seiki |
| Marelli |
| MANN+HUMMEL |
| Continental Aktiengesellschaft |
| Toyota Boshoku |
| MAHLE GmbH |
| Roechling |
| Robert Bosch GmbH |
| Sogefi SpA |
| Others |
Supply Flow & Price Mechanics
IATF 16949 certification gates both supplier qualification and price differentiation simultaneously, filtering uncertified tier-two molders from premium procurement tiers while compressing margin buffers for non-compliant manufacturers across North America and Europe. This quality regime bifurcates the supply base into certified system suppliers commanding value-added bundling premiums and uncertified competitors trapped in spot-market aluminum casting.
Pricing Analysis
Cost-plus contracts with polyamide resin indexation dominate procurement for glass-reinforced plastic manifolds, insulating tier-one molders from raw material volatility while exposing tier-two suppliers to margin compression. Price differentiation separates IATF-certified system suppliers with integrated sensor modules from commodity aluminum foundries, with certification grade and volume scale as primary tiering mechanisms. Pricing pressure stems from glass fiber and resin volatility compressing buffers for non-integrated molders. Fleet procurement for commercial vans exhibits highest price sensitivity, while European premium sedan programs under EU Green Deal mandates show lowest sensitivity to engine bay mass-reduction premiums.
Supply Chain Analysis
Just-in-time delivery preferences among Japanese keiretsu-affiliated OEMs contrast with strategic stockpiling of aluminum castings by German premium manufacturers buffering against foundry concentration risk. Supply concentrates in China for plastic manifold injection molding, Germany for aluminum casting expertise, and Japan for captive hybrid platform supply. Raw material dependencies center on glass-reinforced polyamide formulations, aluminum alloy feedstock, and specialized sensor components. Single-source vulnerability in Yangtze River Delta compounding operations creates geographic concentration risk. Distribution runs through tier-one system suppliers with in-house filtration and sensing capabilities, displacing discrete component sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as battery electric vehicles eliminate traditional intake manifolds entirely, forcing manifold specialists to capture range-extender hybrid and thermal management diversification opportunities before electrification erodes addressable market scope.
For Market Incumbents: Shield core gasoline turbo programs through backward integration into polyamide compounding operations, securing resin supply against price volatility while building captive capacity for integrated charge-air cooling architectures. Defend against aluminum foundry competition by embedding pressure and temperature sensing into bundled air management modules, displacing discrete component sourcing with higher-value system contracts. For New Entrants and Emerging Players: Aftermarket service intervals for fleet-operated commercial vans represent an under-served layer where incumbents lack dedicated distribution infrastructure, creating white-space for independent molders with extended replacement interval guarantees. Target India's Tamil Nadu and Gujarat automotive clusters where PLI scheme incentives reduce capital barriers for injection molding investment, entering through hybrid powertrain development partnerships with domestic OEMs expanding small-displacement turbo lines. For Investors and Strategic Acquirers: Euro 7 cold-start testing expansion reshapes the acquisition landscape toward suppliers with proven thermal management redesign capabilities and extended validation cycle experience. Long-term viability hinges on exposure to hybrid architectures rather than pure ICE dependence, favoring targets with platform-specific development partnerships. Acquisition focus should center on tier-one system suppliers with in-house compounding and sensor integration expertise. The signal to watch is Euro 7 pre-certification timeline clarity, which will unfreeze procurement decisions and reveal which thermal management architectures secure platform wins.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyamide Compounding | Captive resin supply insulates margin buffers from glass fiber price volatility affecting tier-two molders. |
| Sensor-Integrated Module Development | Bundled air management offerings with pressure and temperature sensing displace discrete component sourcing. |
| Charge-Air Cooling Architecture Integration | Embedded intercooler designs within polymer manifolds penetrate unoccupied design space for downsized turbo engines. |
| Hybrid Platform Captive Supply Partnerships | Toyota Boshoku's keiretsu model demonstrates how electrified powertrain specialization locks out independent competitors. |
| India PLI Scheme Manufacturing Localization | Tamil Nadu injection molding investments capture procurement from Tata Motors and Mahindra hybrid expansion programs. |
Methodological Framework
A standing panel of OEM platform engineers, tier-one supplier procurement directors, aluminum foundry operations managers, and aftermarket distribution specialists provided ongoing calibration across primary interview rounds. Secondary validation drew from vehicle production databases, IHS Markit registration data, EPA Tier 3 and Euro 7 regulatory filings, and MIIT corporate average fuel consumption compliance records. Bottom-up unit demand modeling triangulated against top-down OEM procurement budget analysis.
Consistency checks validated volume and value outputs against external automotive component production benchmarks and regional assembly plant capacity utilization disclosures across the projection horizon. Segmentation dimensions modeled include material type, engine architecture, vehicle class, manufacturing process, and regional production cluster. CAGRs were derived from trend extrapolation of platform-level content per vehicle and electrification penetration assumptions, with hybrid powertrain thermal isolation requirements and emissions testing expansion as key forecast inputs.
Underlying assumptions cover regulatory compliance timeline adherence, raw material supply continuity, and OEM platform development cycle stability, with deviation risk concentrated in Euro 7 pre-certification delays and polyamide resin price volatility. Forecasts reflect these assumptions with acknowledged sensitivity to electrification pace and hybrid architecture standardization. Revision becomes warranted when battery electric vehicle penetration crosses thresholds that materially compress range-extender hybrid retention rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Ignition Box Market
Automotive Components
Automotive Fuel Injection System Market
Automotive Components
Automotive Metal Market
Automotive Components
Egypt Commercial Vehicles Lubricants Market
Automotive Components
Global Automotive Aluminum Market
Automotive Components
Africa and Middle East Automotive Actuators Market
Automotive Components
Asia-Pacific Heat Shrink Tubing for Automotive Market
Automotive Components
India Automotive Stamping Market
Automotive Components
Automotive Spark Plugs and Glow Plugs Market
Automotive Components
Automotive Retarders Market
Automotive Components
Automotive Steering Column Market
Automotive Components
Automotive Active Bonnet Market
Automotive Components
Automotive Exhaust Components Aftermarket Market
Automotive Components
Europe Automotive Pneumatic Actuators Market
Automotive Components
Alloys for Automotive Market
Automotive Components
Automotive Connecting Rod Bearing Market