
 Freeze Dried Dog Food Market | 2026-2036
Freeze Dried Dog Food Market Size, Share, and Industry Trends Forecast 2026-2036
Freeze Dried Dog Food Market Intelligence
Canadian production expansion is reconfiguring the North American supply chain for freeze-dried ingredients. Stella & Chewy's leverages its strong brand presence in the pet specialty channel. Primal Pet Foods competes by specializing in raw, ancestral diet formulations. The entry of large CPG firms like Mars introduces significant scale and distribution advantages to the category.
Freeze-dried dog food is a pet food category where moisture is removed via lyophilization, preserving raw ingredients' nutritional integrity without chemical preservatives. Its primary purpose is to provide a nutrient-dense, shelf-stable alternative to raw diets. Within product types, Complete Meals are displacing Treats as the primary format for daily feeding. Novel protein sources like lamb and venison represent the fastest-growing segment, commanding higher price points than chicken or beef.
Regulatory oversight from bodies like the FDA in the United States and the EFSA in Europe dictates permissible ingredients and marketing claims. These agencies' standards for pathogen control and labeling accuracy directly influence product formulation and market access. Future market leadership will depend on a manufacturer's ability to secure and validate its supply chain for high-quality, novel proteins.
Market Dynamics
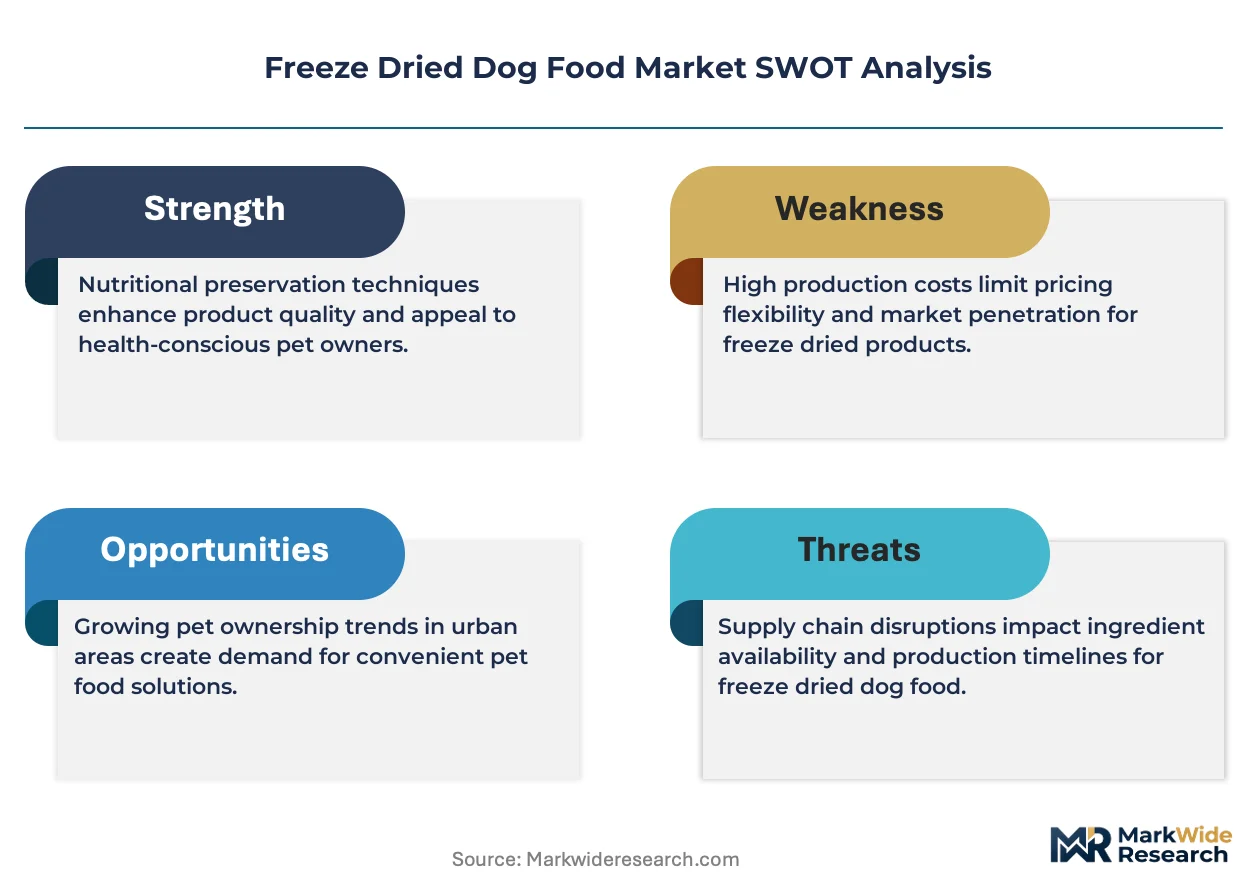
The market's central dynamic is the tension between rising consumer demand for human-grade, novel protein ingredients and the inherently high production costs of lyophilization, which limits price accessibility for the mass market.
Growth Catalysts
- Pet Humanization:The perception of pets as family members drives spending on premium foods mirroring human dietary trends like grain-free and high-protein formulations.
- Regulatory Clarity:Stricter FDA labeling mandates on ingredient sourcing and nutritional claims build consumer confidence, justifying premium price points for verified products.
- Novel Protein Availability:The introduction of proteins like venison and rabbit creates high-margin product lines for dogs with common food sensitivities.
Market Restraints
- High Production Cost:The energy-intensive lyophilization process requires expensive equipment, resulting in a retail price that is prohibitive for many consumers.
- Supply Chain Bottlenecks:Securing a consistent supply of pathogen-free novel proteins like venison presents a major bottleneck, limiting production scalability for manufacturers.
- Competition from Substitutes:The category faces intense price competition from established, lower-cost formats like extruded kibble and canned wet food.
Strategic Opportunities
- Geographic Expansion:Markets with high pet spending but low freeze-dried penetration, including Japan and Germany, offer significant growth avenues for new entrants.
- Functional Formulations:Products fortified with ingredients like probiotics or glucosamine to target specific health needs, such as joint support, can command higher prices.
- Direct-to-Consumer Channels:Subscription e-commerce bypasses retail intermediaries, enabling brands to build customer loyalty and improve margin capture on sales.
Industry Challenges
- Consumer Education on Value:A key challenge is educating consumers on the nutritional benefits of lyophilization to justify the significant price premium over kibble.
- Pathogen Risk Management:Maintaining strict pathogen control for raw ingredients to meet FDA food safety standards is a major operational and financial burden for producers.
- Production Scaling Hurdles:The capital-intensive nature of freeze-drying equipment makes it difficult to scale manufacturing capacity quickly to meet demand surges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Freeze Dried Dog Food Market |
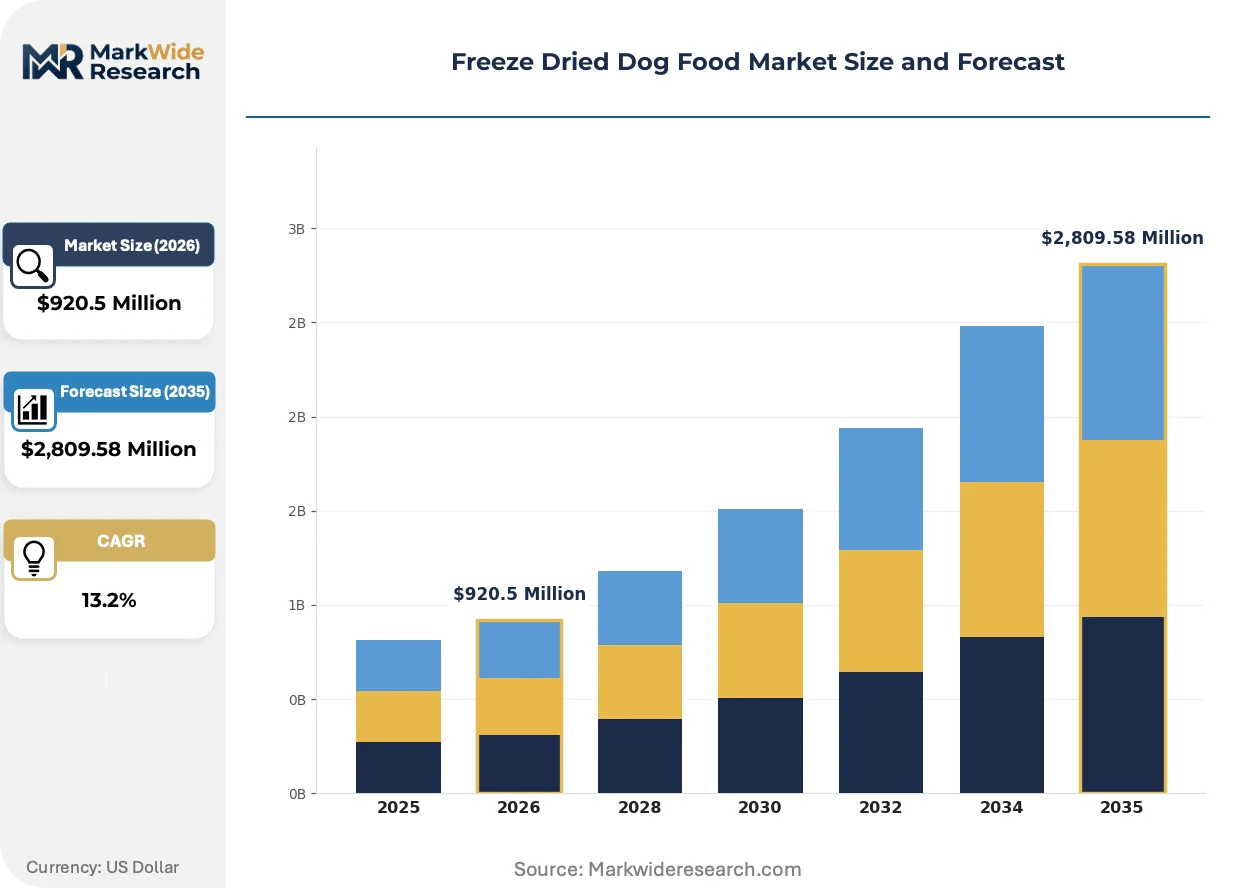
| Market Size in 2026 | $920.5 Million |
| Market Size in 2035 | $2,809.58 Million |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Complete Meals, Treats, Supplements, Raw Blend Protein Source: Chicken, Beef, Fish, Lamb, Turkey, Venison Formulation: Grain-Free, Organic, High Protein, Limited Ingredient, Low Fat Distribution Channel: Pet Specialty Stores, Veterinary Clinics, Online Retailers, Grocery Stores |
| Companies Covered | Stella & Chewy's, Primal Pet Foods, Mars, Northwest Naturals, Merrick, Vital Essentials, Instinct, Open Farm, Dr. Harvey's, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Freeze Dried Dog Food Market Strategic Shifts & Innovations
The evolution of the freeze-dried dog food category is defined by a convergence of food safety technologies and demand for nutritional transparency. This pushes manufacturers to validate ingredient integrity from the farm to the final product.
High-Pressure Processing (HPP) is a non-thermal pasteurization method used to neutralize pathogens in raw meat while preserving its nutritional profile. Premium and raw-focused brands are adopting HPP to enhance food safety without resorting to heat or chemical preservatives. This technology is collapsing the perceived safety gap between conventional heat-treated kibble and raw-ingredient freeze-dried foods.
The European Food Safety Authority (EFSA) is applying stricter scrutiny to novel ingredients and health claims in pet food. This forces manufacturers to provide extensive safety and efficacy data for functional additives like botanicals or specific probiotic strains. The novel protein segment is most affected, as producers must validate sourcing to gain market access in the EU.
A notable behavioral shift is the move from one-time purchases in pet specialty stores to automated orders via direct-to-consumer (DTC) subscription websites. This model disintermediates traditional distributors and allows brands to capture valuable first-party data on consumer preferences. This trend is most pronounced among urban pet owners in North America and Western Europe.
Freeze Dried Dog Food Market Segmentation
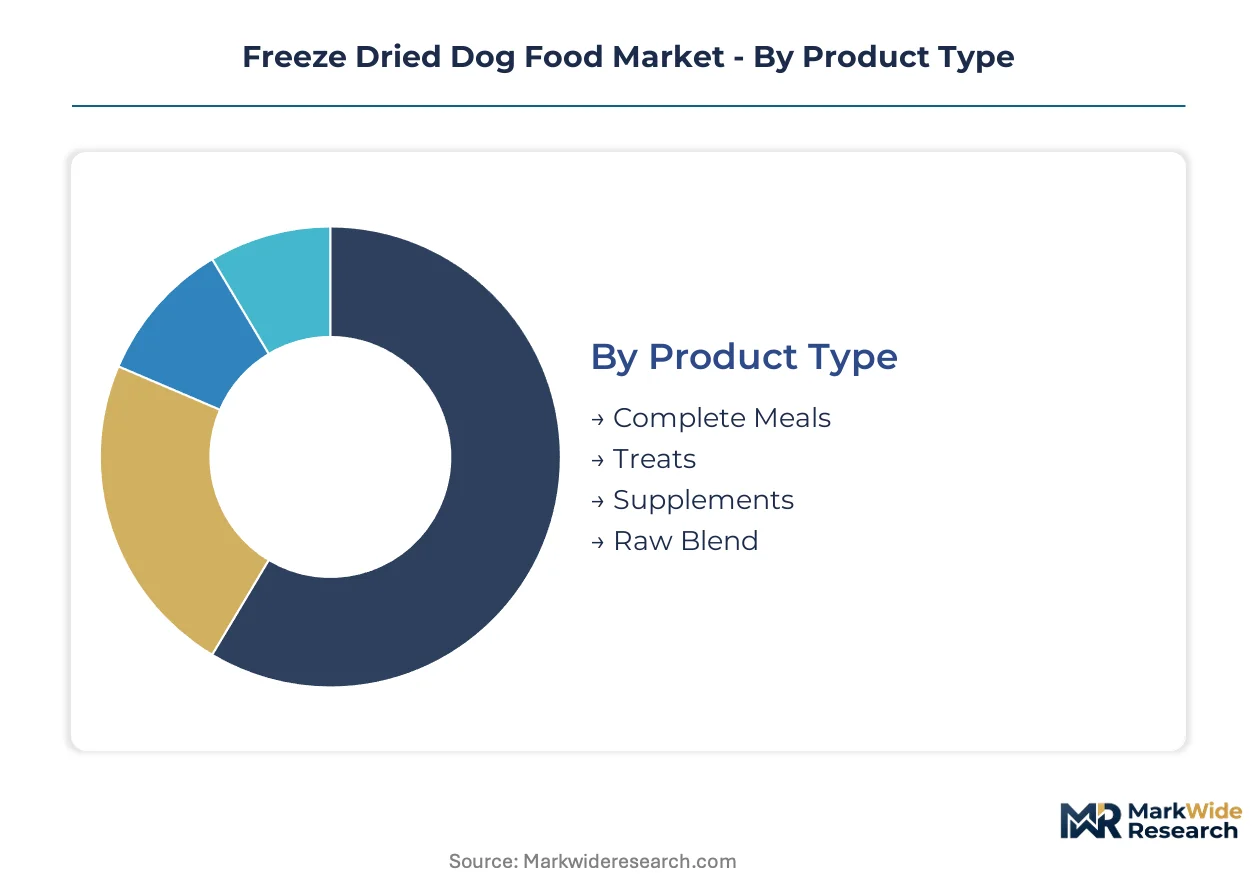
The segmentation of the freeze-dried dog food market provides a granular understanding of product offerings and consumer preferences. Analyzing these distinct categories helps identify specific growth pockets and areas of product innovation within the premium pet food sector.
Product Type:
The application of freeze-dried dog food extends across various formats, each serving distinct pet owner needs.
- Complete Meals:These formulations provide a nutritionally balanced diet intended for daily feeding, often displacing traditional kibble or wet food. Demand for Complete Meals concentrates in urban areas where pet owners prioritize convenience and nutrient density for their dogs.
- Treats:Freeze-dried treats serve as supplementary rewards or training aids, offering a palatable, nutrient-rich option for occasional consumption.
- Supplements:These products target specific health concerns, delivering concentrated nutrients or functional ingredients to complement a dog's regular diet.
- Raw Blend:Raw Blend products combine freeze-dried raw ingredients with other components, providing a convenient way for owners to incorporate raw nutrition without full preparation. This segment appeals to consumers seeking the benefits of raw feeding with enhanced safety and shelf stability.
Complete Meals holds installed capacity. Raw Blend is rotating up the share rankings.
Protein Source:
Customer preference for specific protein types heavily influences purchasing decisions within the freeze-dried dog food sector.
- Chicken:Chicken remains a foundational protein source due to its widespread availability and general palatability for most dogs.
- Beef:Beef provides a rich protein option, widely accepted and often used in various freeze-dried formulations.
- Fish:Fish-based freeze-dried foods offer novel protein options rich in omega-3 fatty acids, catering to dogs with sensitivities or requiring skin and coat support. Demand for fish proteins is particularly strong in coastal regions where pet owners seek sustainable and unique dietary choices.
- Lamb:Lamb is a popular hypoallergenic protein choice for dogs with common food sensitivities to more traditional meat sources.
- Turkey:Turkey offers a lean protein alternative, often chosen for its digestibility and as a rotational protein in dog diets.
- Venison:Venison represents a premium, novel protein source, highly sought after for dogs with severe allergies or specific dietary requirements. This segment commands higher price points, particularly in the United States, driven by pet humanization trends.
Traditional proteins like Chicken and Beef maintain market presence. Novel protein sources like Venison and Fish are expanding most quickly.
Formulation:
Margin profiles for freeze-dried dog food vary significantly based on the specific formulation and ingredient claims.
- Grain-Free:Grain-Free formulations exclude common grains, aligning with ancestral diet philosophies and addressing common pet sensitivities. This segment sees high demand from pet owners in North America who prioritize human-grade ingredient standards.
- Organic:Organic formulations emphasize ingredients grown without pesticides or synthetic fertilizers, appealing to environmentally conscious consumers.
- High Protein:High Protein formulations cater to the natural carnivorous diet of dogs, supporting muscle development and energy levels. This segment is a core offering for brands emphasizing raw and ancestral feeding principles.
- Limited Ingredient:Limited Ingredient diets feature a minimal number of components, simplifying ingredient lists for dogs with sensitive digestive systems or allergies.
- Low Fat:Low Fat options are designed for dogs requiring weight management or those with specific health conditions that necessitate a reduced fat intake.
Grain-Free formulations attract a broad consumer base. Organic and Limited Ingredient options are climbing the fastest in niche segments.
Distribution Channel:
The customer type and their purchasing habits dictate the most effective distribution channels for freeze-dried dog food products.
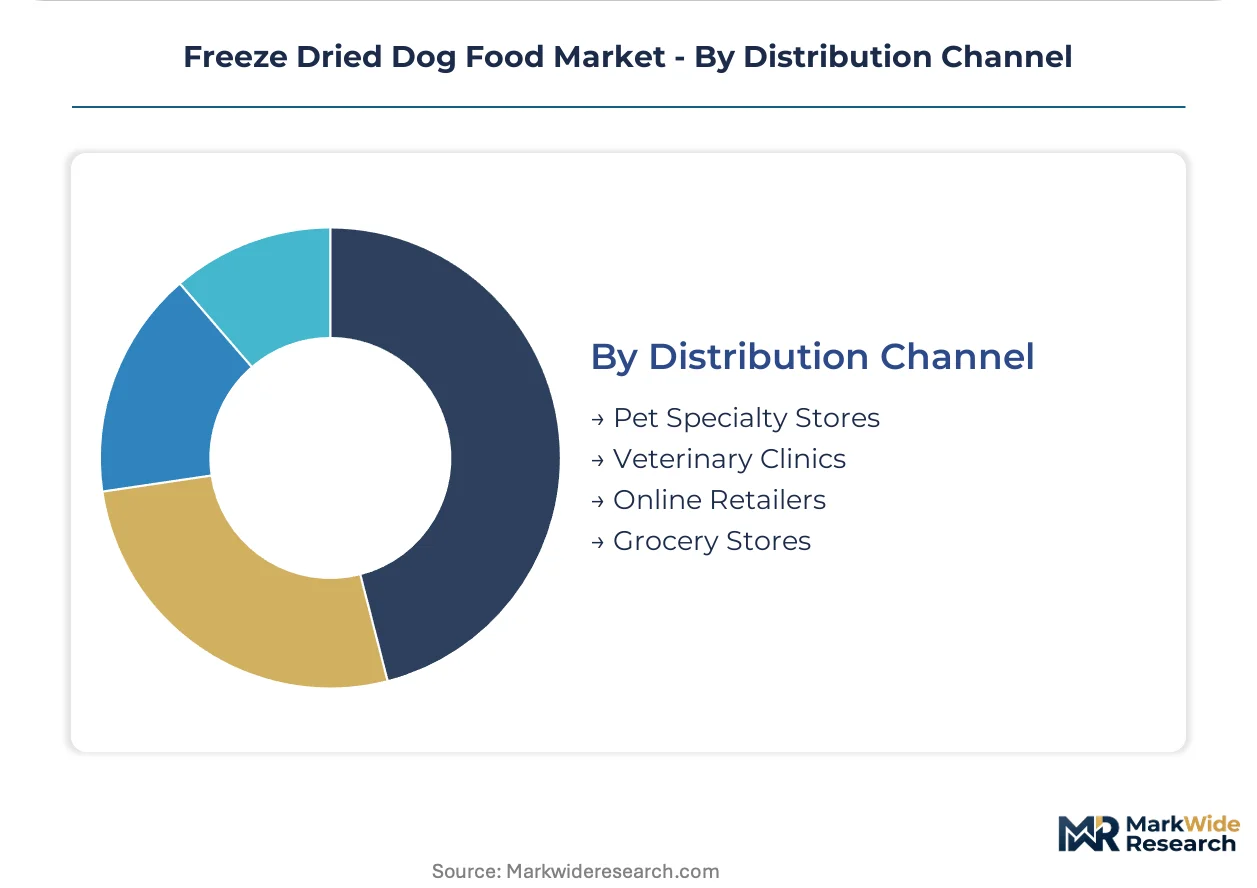
- Pet Specialty Stores:These stores offer a curated selection of premium pet products, providing expert advice and a personalized shopping experience for discerning pet owners. Pet Specialty Stores remain critical for product discovery and brand building for new freeze-dried brands.
- Veterinary Clinics:Veterinary clinics distribute specialized or therapeutic freeze-dried diets, often recommended by veterinarians for specific health conditions.
- Online Retailers:Online platforms provide unparalleled convenience, broad product selection, and often competitive pricing, facilitating subscription models for recurring purchases. This channel is experiencing significant growth, particularly among younger, tech-savvy pet owners in Western Europe.
- Grocery Stores:Grocery stores offer accessibility and convenience for mass-market consumers, although their freeze-dried product selection often remains limited compared to other channels.
Online Retailers are increasingly capturing market share due to convenience. Pet Specialty Stores continue to serve a discerning customer base seeking expert guidance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA in the United States anchors regulatory oversight for the freeze-dried dog food market, ensuring product safety and ingredient integrity. This regulatory clarity supports consumer confidence in premium offerings. High demand for these specialized pet foods concentrates significantly across North America.
United States
Pet humanization trends drive strong demand for human-grade, grain-free formulations in the United States. FDA labeling mandates on ingredient sourcing build consumer trust, justifying higher price points for verified products. Pet food innovation clusters in California, where brands develop novel protein options and functional ingredients.
Germany
German pet owners increasingly seek high-protein and functional formulations for their dogs, reflecting European pet spending habits. The EFSA applies stricter scrutiny to novel ingredients and health claims in pet food, impacting market access. Munich and surrounding regions host a concentration of specialized pet food manufacturers, driving product diversification.
Japan
Japan represents a significant growth avenue due to high pet spending and relatively low freeze-dried food penetration. METI standards for food safety and quality influence product development and market entry for international brands. The Tokyo metropolitan area serves as a key hub for pet product retail and distribution, facilitating premium brand visibility.
Canada
Canadian production expansion is reconfiguring the North American supply chain for freeze-dried ingredients, enhancing regional availability. Health Canada provides regulatory oversight for pet food safety and nutritional adequacy, guiding manufacturer practices. Ontario features a growing cluster of pet food manufacturing facilities, supporting export capabilities across the continent.
Freeze Dried Dog Food Market Key Industry Players
Premium specialists and large consumer packaged goods (CPG) firms currently split the freeze-dried dog food market. The market structure exhibits a tiered approach, with specialized brands focusing on niche formulations and quality ingredients. Large CPG firms leverage extensive distribution networks and economies of scale. Strategic moves include geographic expansion into underpenetrated markets and the development of direct-to-consumer sales channels.
Within the premium specialist tier, Stella & Chewy's exemplifies strong brand presence across pet specialty channels. Primal Pet Foods occupies a position among raw-focused specialists, emphasizing ancestral diet formulations. Large CPG firms like Mars anchor the market with significant scale and distribution advantages, introducing broader accessibility. These entities collectively highlight the market's differentiation based on product philosophy and reach. Their strategies often involve expanding product portfolios to capture diverse consumer preferences.
| Leading Market Players |
|---|
| Stella & Chewy's |
| Primal Pet Foods |
| Mars |
| Northwest Naturals |
| Merrick |
| Vital Essentials |
| Instinct |
| Open Farm |
| Dr. Harvey's |
| Others |
Cost & Logistics Intelligence
Canadian production capacity expansion is reconfiguring North American supply, influencing ingredient availability and manufacturer pricing strategies across the continent. This shift impacts supplier behavior and price posture for freeze-dried dog food ingredients.
Pricing Analysis
Geographic price spreads for freeze-dried dog food reflect regional demand and ingredient sourcing costs. The dominant pricing model incorporates premium-mid-economy differentiation, with higher prices for novel protein complete meals and lower prices for traditional protein treats. Price differentiation drivers include human-grade ingredient certification and brand premium. Pricing softness stems from intense competition from established, lower-cost substitutes like kibble. Mass-market consumers exhibit high price sensitivity, while pet owners seeking novel proteins for allergies show lower sensitivity.
Supply Chain Analysis
Upstream feedstock for freeze-dried dog food primarily sources raw ingredients from North America and Europe, with Canada emerging as a key supplier for freeze-dried components. Raw material dependencies center on pathogen-free novel proteins like venison and rabbit, alongside traditional chicken and beef. Supply chain bottlenecks present a structural risk, particularly for securing consistent volumes of novel proteins. Distribution runs through online retailers and pet specialty stores, with grocery channels holding limited freeze-dried product selection.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a high-growth disruption, driven by the technological inflection of High-Pressure Processing (HPP) enhancing food safety for raw ingredients.
For Market Incumbents:Build robust supply chain resilience through strategic partnerships with novel protein suppliers. Expand production capacity for lyophilization to meet growing demand, mitigating reliance on external contract manufacturers. Invest in HPP technology to enhance pathogen control, addressing a key consumer safety concern and a threat from regulatory scrutiny. Leverage existing brand presence in pet specialty channels to introduce functional formulations, capturing a larger share of premium spending against emerging entrants.
For New Entrants and Emerging Players:Pursue niche geographic expansion into underpenetrated markets like Japan, leveraging a unique value proposition. Target the novel protein segment with specialized formulations, focusing on dogs with specific dietary needs or allergies. Develop direct-to-consumer subscription models to build customer loyalty and capture valuable first-party data. A penetrable segment exists within functional formulations, offering products fortified with probiotics or joint support ingredients, providing a clear go-to-market angle.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting upwards across the freeze-dried production segment, driven by equipment and specialized ingredient sourcing. Long-term viability rests on securing consistent, high-quality novel protein supply chains. Acquisition targets should include vertically integrated specialists with strong brand recognition in the premium segment or those possessing advanced pathogen control technologies like HPP. The signal to watch is the growth rate of direct-to-consumer subscription enrollments, indicating sustained consumer adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Secure Novel Protein Supply Agreements | Ensures consistent access to high-demand ingredients, stabilizing production. |
| Invest in High-Pressure Processing (HPP) | Enhances food safety for raw ingredients, boosting consumer confidence. |
| Expand Direct-to-Consumer (DTC) Channels | Fosters customer loyalty and improves margin capture through direct sales. |
| Develop Functional Freeze-Dried Formulations | Addresses specific pet health needs, commanding higher price points. |
| Geographic Market Entry in Asia-Pacific | Captures growth in underpenetrated regions with rising pet spending. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade association reports, and company investor disclosures. Primary interviews engaged pet food manufacturers, ingredient suppliers, veterinarians, and pet specialty retailers. This involved a rigorous process of bottom-up data collection and top-down market sizing, triangulating insights from diverse industry perspectives.
Forecast inputs considered include pet humanization trends, novel protein availability, and regulatory landscape shifts across the analysis window. The analytical framework modeled segmentation dimensions such as product type, protein source, formulation, and distribution channel, alongside regional demand patterns. Compound Annual Growth Rates (CAGRs) were derived by projecting market evolution based on these identified drivers and constraints.
Sensitivities concentrate around raw material cost fluctuations and evolving regulatory standards for pet food safety. Forecasts reflect assumptions regarding consumer preferences and technological adoption rates within the market. Cross-checking against established pet industry market intelligence is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Japan Pet Clothing Market
Pet Care Products
Smart Pet Supply Market
Pet Care Products
US Pet Food Market
Pet Care Products
Dog Collars Market
Pet Care Products
Dog Float Market
Pet Care Products
Pet Bathing Supplies Market
Pet Care Products
Pet Car Seat Market
Pet Care Products
Asia Pacific Dog Food Market
Pet Care Products
GCC Dog Food Market
Pet Care Products
Cat Litter Product Market
Pet Care Products
Dog Seat Belt Market
Pet Care Products
Pet Food Pulverizer Market
Pet Care Products
Smart Cat Eye Market
Pet Care Products
Automatic and Smart Pet Feeder Market
Pet Care Products
South America Pet Food Market
Pet Care Products
Global Pet Carriers Market