
 Asia Pacific Dog Food Market | 2026-2036
Asia Pacific Dog Food Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Dog Food Market Insights
Premium grain-free and functional ingredient tiers is unwinding across the Asia Pacific dog food landscape as owners trade up from basic kibble. Mars Incorporated leverages its Royal Canin veterinary channel to anchor the therapeutic nutrition segment across Japan and Australia. Nestle Purina competes through Purina Pro Plan formulations that sustain science-backed positioning in South Korea's pet specialty stores. Unicharm Corporation dominates the Japanese mass market through its Aiken Genki brand, which controls shelf space in convenience retail formats.
Asia Pacific dog food encompasses nutritionally complete and complementary formulations manufactured through extrusion, retorting, or cold-pressing processes, with macronutrient profiles calibrated to canine life-stage requirements and species-appropriate digestibility coefficients. Dry food occupies the largest volume share due to shelf stability advantages in tropical climates and price accessibility across emerging Southeast Asian markets. Wet food generates disproportionate margin pools in Japan and South Korea where humanization trends elevate palatability premiums. Online retailers represent the fastest-growing sales channel as platform ecosystems in China and India collapse distribution layers between manufacturers and pet owners.
Japan's Ministry of Agriculture, Forestry and Fisheries enforces feed safety standards that shape import requirements and domestic manufacturing protocols, while China's SAMR and NMPA coordinate GB standard updates for pet feed hygiene and labeling transparency. Australia's Department of Agriculture, Fisheries and Forestry administers biosecurity rules that constrain ingredient sourcing flexibility for local producers. Stakeholders must monitor regulatory divergence between harmonized ASEAN frameworks and country-specific compliance layers as formulation investments compound across the region.
Market Dynamics
Urbanization across China, India, and Southeast Asia is compressing pet ownership timelines and elevating nutritional sophistication faster than domestic supply chains can adapt, forcing formulation investments to outpace manufacturing capacity expansion.
Growth Catalysts
- Japan's FOSHU-inspired pet food standards:These regulations create a certification pathway for functional nutrition claims, rewarding manufacturers who invest in clinical validation and premium positioning.
- Extrusion technology advancement:Cold-pressing and low-temperature processing methods preserve heat-sensitive bioactives, enabling therapeutic-grade formulations that command shelf space in veterinary channels.
- Metropolitan corridor concentration:Demand clusters in Shanghai, Mumbai, Bangkok, and Jakarta generate sufficient volume density to justify dedicated distribution infrastructure and localized production facilities.
Market Restraints
- Animal protein input volatility:Fishmeal and poultry by-product prices fluctuate with aquaculture harvest cycles and avian influenza outbreaks, compressing margin predictability for mid-tier producers.
- Import dependency for premix vitamins:Concentrated vitamin and mineral blends sourced from European and North American suppliers create foreign exchange exposure and biosecurity clearance delays.
- GB standard transition friction:China's evolving pet feed hygiene and labeling requirements impose reformulation costs and inventory obsolescence risks during compliance windows.
Strategic Opportunities
- Vietnam and Philippines underpenetration:These markets exhibit low commercial pet food conversion rates among traditional feeding households, presenting first-mover advantages for affordable complete nutrition formats.
- Subscription direct-to-home models:Platform ecosystems in India and Indonesia enable recurring revenue capture and consumption data accumulation that offline retail cannot replicate.
- Dual carbon goal alignment:China's MEE incentives for low-carbon manufacturing favor producers investing in renewable energy procurement and packaging lightweighting.
Industry Challenges
- Veterinary nutritionist scarcity:Qualified formulators capable of designing life-stage specific and therapeutic diets remain concentrated in Japan and Australia, constraining R&D velocity elsewhere.
- Multi-jurisdiction label compliance:Divergent ASEAN national requirements versus harmonized frameworks force SKU proliferation and inventory fragmentation across Southeast Asian operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Dog Food Market |
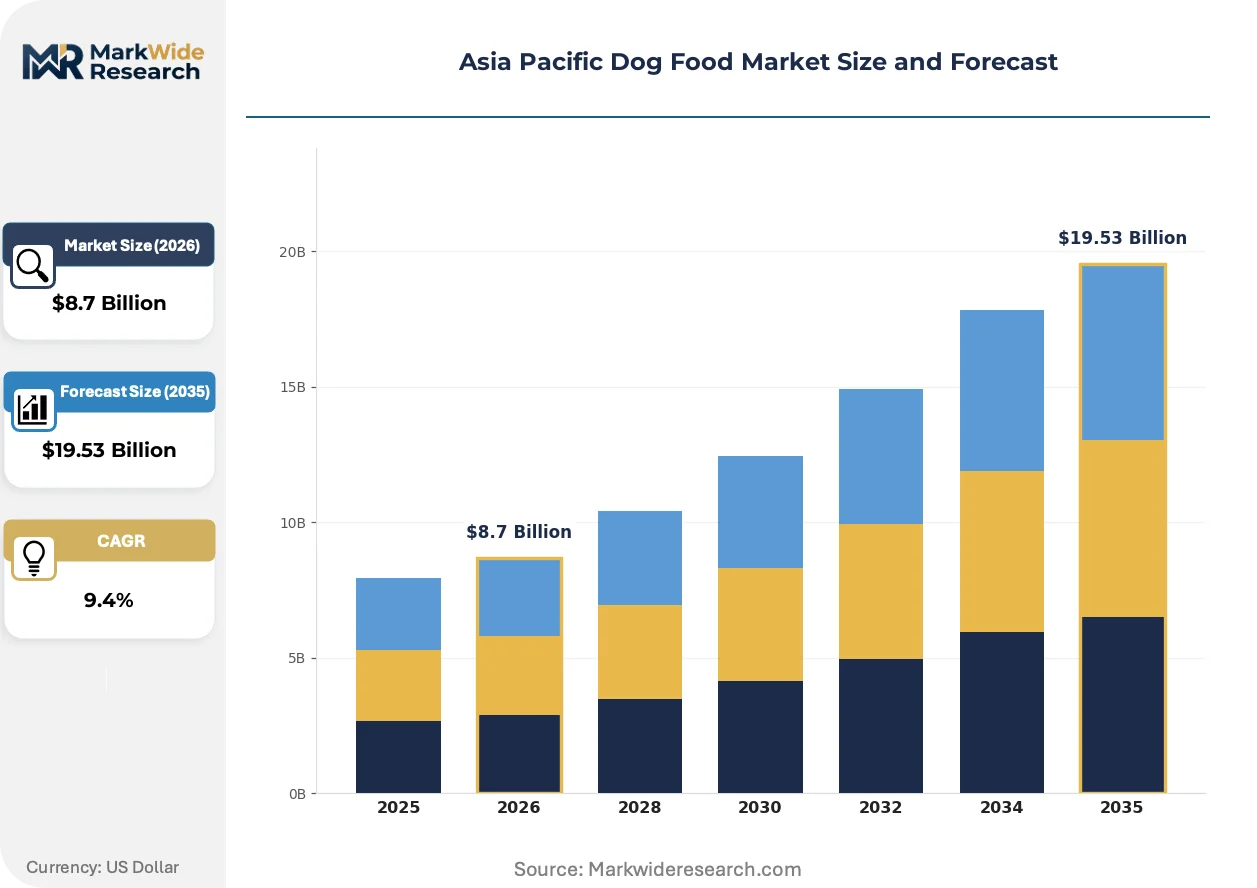
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Snacks, Treats Packaging Type: Bag, Can, Box, Pouch Sales Channel: Supermarkets, Pet Stores, Online Retailers, Wholesale Customer Type: Pet Owners, Pet Lovers, Animal Shelters, Breeders |
| Companies Covered | Mars Incorporated, Nestle (Purina), Colgate-Palmolive Company (Hill's Pet Nutrition), General Mills Inc., Archer Daniels Midland (ADM), Unicharm Corporation, Perfect Companion Group, Jeil Feed, DoggyMan H.A. Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Dog Food Market Trends and Innovations
Cold-processing technologies, regulatory certification layering, and platform-mediated distribution are restructuring how nutritional value is created, verified, and delivered to pet owners across the region.
High-pressure processing and freeze-drying technologies are fragmenting the traditional extrusion-dominated manufacturing landscape. Premium and super-premium brands in South Korea and Japan are adopting these methods to preserve enzymatic activity in functional ingredients. The capital intensity of these systems is compressing the viable producer base toward scaled specialists with veterinary channel access.
China's SAMR and NMPA coordination on GB standard updates is tightening hygiene and traceability mandates for pet feed manufacturing. Domestic producers face facility upgrade requirements that favor centralized, automated plants over distributed operations. Importers must navigate dual compliance layers for products entering both mainland China and Hong Kong regulatory zones.
Pet specialty stores and veterinary clinics are losing share to integrated e-commerce ecosystems that collapse distribution layers. Platform algorithms in China and India now surface personalized nutrition recommendations based on breed, age, and health condition data. This behavioral shift is most visible among millennial pet owners in tier-one Chinese cities who prioritize convenience and subscription pricing over tactile retail evaluation.
Asia Pacific Dog Food Market Segmentation
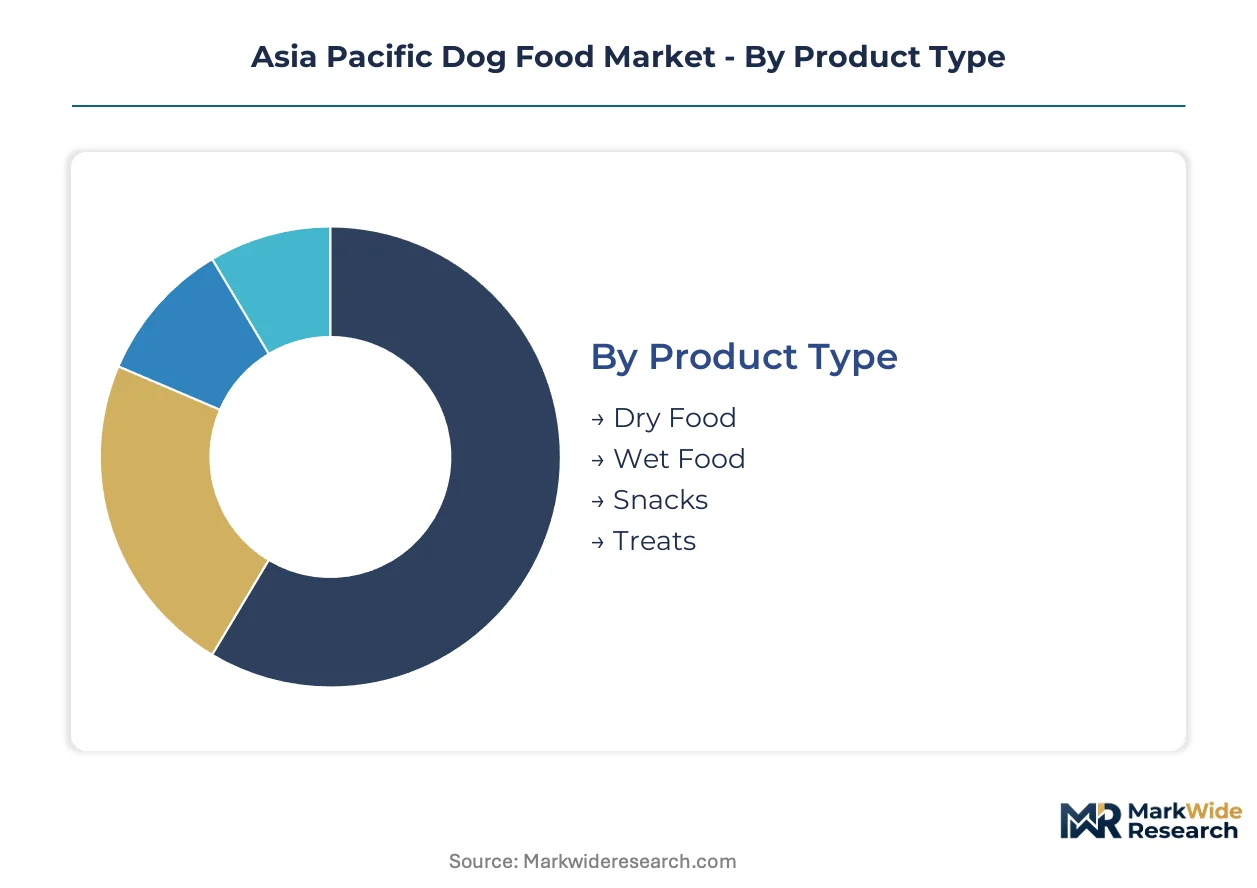
Segmentation in Asia Pacific dog food reveals how tropical climate constraints, platform-mediated distribution, and regulatory divergence create distinct competitive arenas. Manufacturers must align formulation investments, packaging specifications, and channel economics to specific buyer clusters across China's tier-one cities, Japan's veterinary networks, and Southeast Asia's emerging conversion zones.
Product Type:
Substitution pressure runs strongest against basic nutrition formats as owners trade up toward functional and experiential feeding options.
- Dry Food:Extruded kibble formulations deliver shelf-stable macronutrient density calibrated for tropical storage conditions. Demand concentrates in India's metropolitan corridors and Southeast Asian urban clusters where price accessibility and bulk purchasing dominate household procurement patterns.
- Wet Food:Retorted or cold-filled formulations achieve higher moisture content and palatability premiums through emulsion technology and gravy suspensions. Japan and South Korea absorb disproportionate volumes as humanization trends elevate sensory experience over cost efficiency.
- Snacks:Complementary nutrition formats including dental chews and functional biscuits occupy impulse purchase occasions in convenience retail.
- Treats:High-reward training formats and indulgence-positioned products command premium pricing in pet specialty channels.
Dry food retains volume leadership; wet food holds the steepest expansion curve.
Packaging Type:
Cost tier stratification separates premium convenience formats from economy bulk options across the region's divergent retail infrastructures.
- Bag:Multi-layer laminated structures with oxygen barrier properties protect extruded kibble from humidity degradation. China's tier-one cities and Bangkok generate concentrated demand for resealable stand-up pouches that extend shelf life in high-moisture climates.
- Can:Metal retort containers enable wet food sterilization and extended ambient stability without refrigeration dependency. Japan's convenience retail formats and Australia's veterinary channels absorb significant volume for single-serve therapeutic portions.
- Box:Corrugated secondary packaging supports bulk distribution economics for multi-unit dry food purchases.
- Pouch:Flexible film structures with spout fitments reduce material intensity and shipping cube versus rigid alternatives.
Bags retain volume leadership; pouches hold the steepest expansion curve.
Sales Channel:
Application-based channel selection reflects where owners seek validation versus convenience across the ownership lifecycle.
- Supermarkets:Mass-market retail formats stock mid-tier complete nutrition brands with promotional pricing cycles. India's organized retail expansion and Indonesia's modern trade corridors concentrate volume for household staple purchases.
- Pet Stores:Specialty retail environments provide tactile evaluation and staff consultation for breed-specific formulation selection. South Korea's pet specialty chains and Japan's home center formats sustain premium positioning through curated assortment.
- Online Retailers:Platform ecosystems collapse distribution layers and enable subscription-based replenishment with consumption data capture.
- Wholesale:Bulk procurement channels serve multi-pet households, breeding operations, and institutional buyers with pallet-scale logistics.
Supermarkets retain volume leadership; online retailers hold the steepest expansion curve.
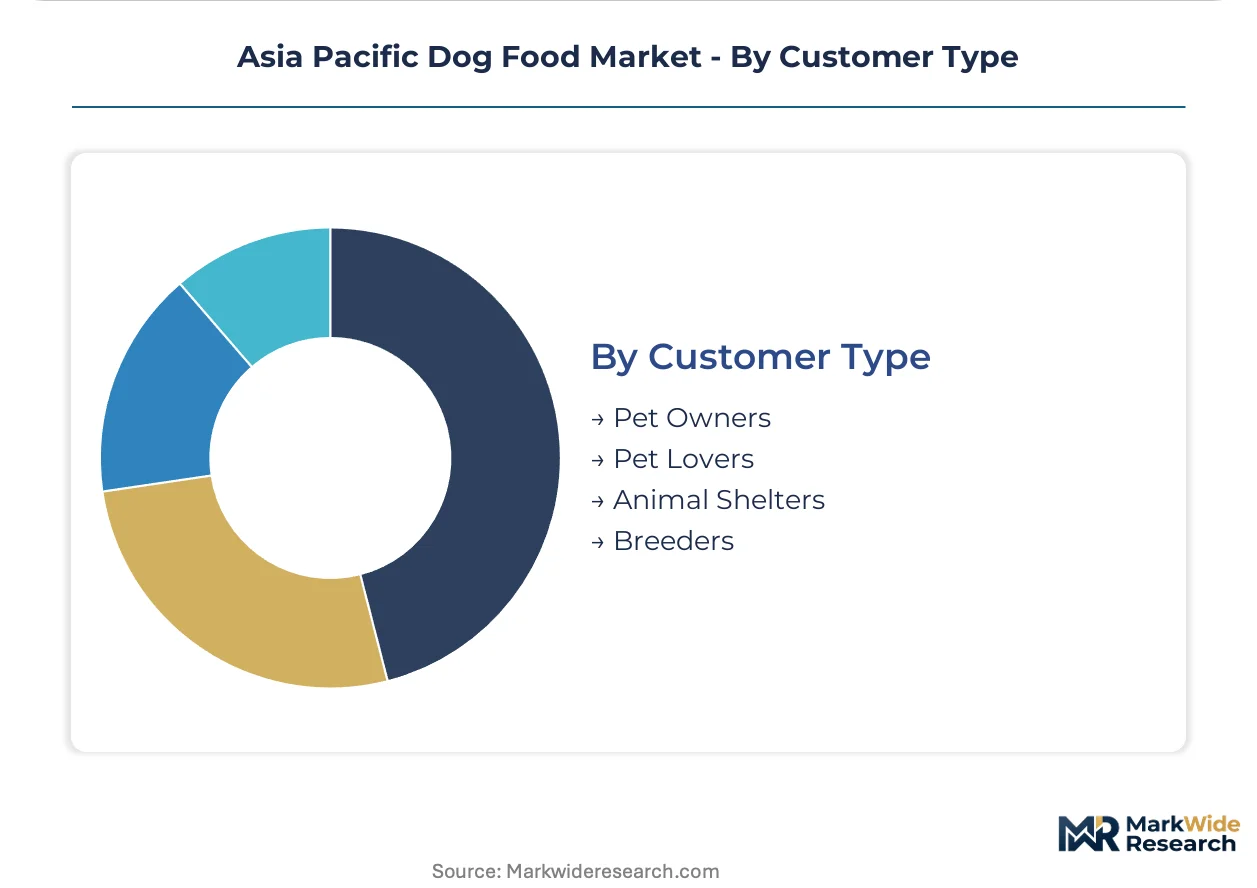
Customer Type:
Volume concentration varies sharply between commercial breeding operations and individual companion animal households.
- Pet Owners:Individual companion animal households purchasing complete nutrition for daily feeding requirements. China's tier-one cities and Mumbai generate dense demand clusters where premiumization trends elevate functional ingredient expectations.
- Pet Lovers:Enthusiast segment pursuing experiential and indulgence-positioned products beyond basic nutritional adequacy. Tokyo and Seoul concentrate this segment through high-frequency treat and snack purchasing.
- Animal Shelters:Institutional buyers procuring economy-tier complete nutrition at volume scale with cost optimization priorities.
- Breeders:Commercial operations requiring life-stage specific formulations for reproductive health and puppy development.
Pet owners retain volume leadership; pet lovers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Thailand, Australia, and eastern China where feed-grade ingredient processing and extrusion infrastructure overlap with export-oriented logistics. Veterinary nutrition expertise concentrates in Japan and Australia, creating R&D capability gaps elsewhere that importers fill through branded finished goods.
China
Shanghai, Beijing, and Guangzhou concentrate demand for functional and premium formulations as urban pet owners trade up from table scraps and homemade diets. SAMR and NMPA coordination on GB standard updates tightens hygiene and labeling mandates, forcing facility upgrades toward centralized automated plants. Yangtze River Delta manufacturing clusters supply tier-one cities while navigating dual compliance layers for mainland and Hong Kong regulatory zones.
Japan
Tokyo, Osaka, and Nagoya generate dense demand for therapeutic and life-stage specific nutrition through veterinary and pet specialty channels. METI-aligned FOSHU-inspired standards create certification pathways for functional claims, rewarding clinical validation investments. Kanto region production facilities serve both domestic retail and premium export positioning across Southeast Asia.
India
Mumbai, Delhi-NCR, and Bangalore concentrate emerging demand as metropolitan pet ownership timelines compress and nutritional sophistication rises faster than domestic supply adaptation. FSSAI feed safety frameworks remain less prescriptive than East Asian counterparts, creating import dependency for premix vitamins and specialized formulations. Western India manufacturing corridors expand extrusion capacity to serve organized retail expansion in tier-one cities.
South Korea
Seoul Capital Area absorbs disproportionate wet food and premium treat volumes as humanization trends elevate palatability premiums over cost efficiency. MFDS enforcement of feed safety and import inspection protocols shapes ingredient sourcing flexibility for local blenders. Busan-Ulsan industrial zones support retort manufacturing for export-oriented pet food processors.
Australia
Sydney and Melbourne concentrate demand for grain-free and functional ingredient tiers as pet owners prioritize species-appropriate nutrition claims. The Department of Agriculture, Fisheries and Forestry administers biosecurity rules that constrain ingredient sourcing flexibility, favoring domestic protein inputs over imported alternatives. Victorian manufacturing hubs supply both domestic retail and export positioning into Southeast Asian premium channels.
Asia Pacific Dog Food Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Asia Pacific dog food landscape. Multinational packaged goods conglomerates with veterinary channel access anchor the premium and therapeutic segments, while regional feed specialists and private label manufacturers capture volume in emerging market conversion zones. Three archetypes dominate: science-backed therapeutic nutrition specialists, mass-market brand owners with convenience retail penetration, and platform-native direct-to-consumer challengers. Competitive moves concentrate on M&A for veterinary network access and strategic partnerships with e-commerce platforms for distribution layer collapse.
Within the multinational conglomerate tier, Mars Incorporated and Nestlé Purina occupy positions that exemplify science-backed positioning through veterinary and specialty retail channels. Unicharm Corporation anchors the Japanese mass-market segment through convenience retail format dominance. These three entities represent contrasting geographic and channel strategies rather than direct head-to-head competition, with each anchoring distinct national and positioning territories.
| Leading Market Players |
|---|
| Mars Incorporated |
| Nestle (Purina) |
| Colgate-Palmolive Company (Hill's Pet Nutrition) |
| General Mills Inc. |
| Archer Daniels Midland (ADM) |
| Unicharm Corporation |
| Perfect Companion Group |
| Jeil Feed |
| DoggyMan H.A. Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
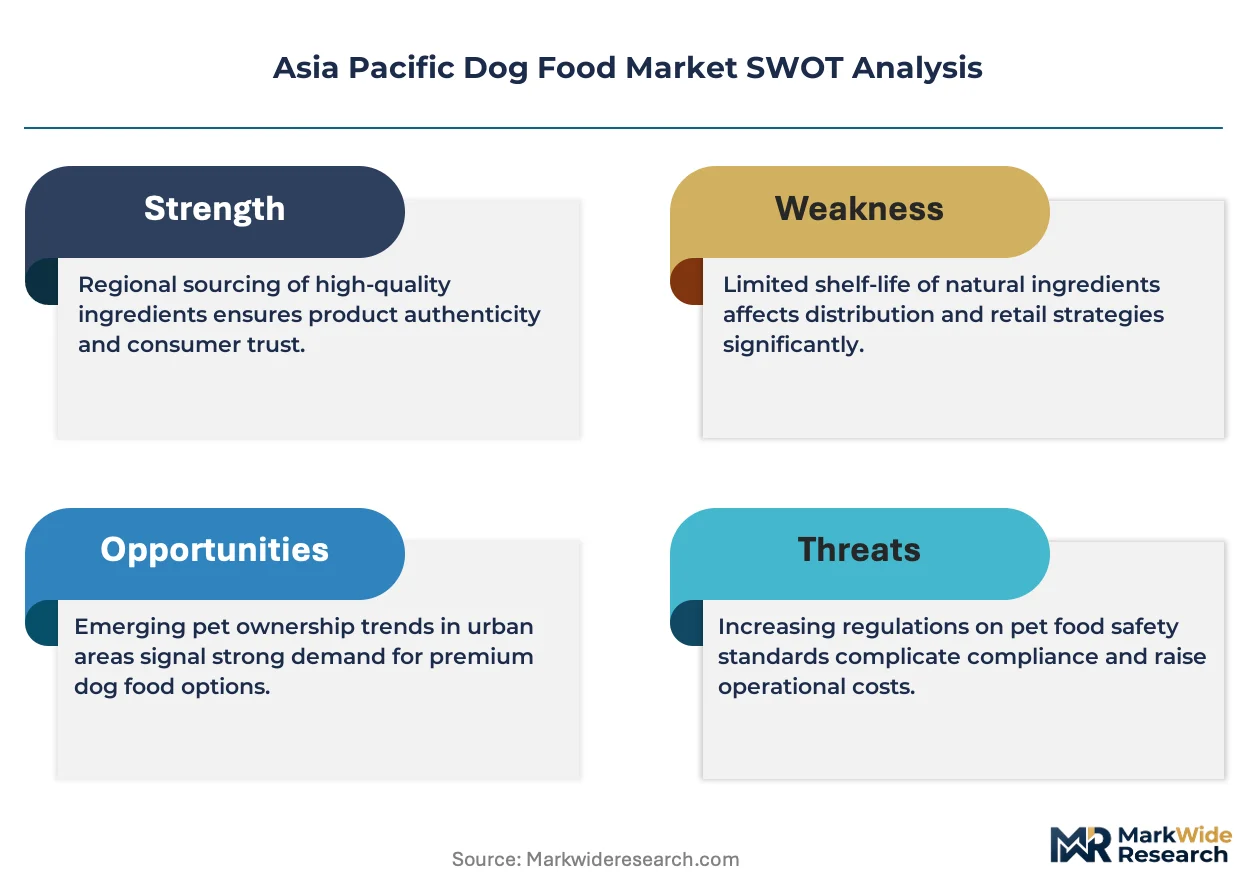
Fishmeal substitution for poultry by-product meal across Southeast Asian formulations simultaneously redraws procurement geography toward Peruvian anchovy fisheries and compresses margin pools for mid-tier producers locked into volatile avian protein contracts. This input swap forces manufacturers to rebuild hedging strategies around marine commodity cycles rather than domestic livestock economics.
Pricing Analysis
Japan's FOSHU-inspired pet food standards dictate the pricing tier structure by mandating clinical validation investments that separate certified functional nutrition from basic adequacy claims. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and veterinary channel access, with premium tiers absorbing disproportionate margin capture. Cost compression in economy segments intensifies because domestic feed grain prices fluctuate with import dependency. Price sensitivity concentrates among multi-pet households in India's metropolitan corridors, while therapeutic nutrition buyers in Tokyo and Seoul exhibit minimal elasticity.
Supply Chain Analysis
Strategic stockpiling of fishmeal and poultry by-product inputs dominates inventory strategy over just-in-time preferences, as tropical climate storage risks and harvest cycle volatility favor forward coverage. Supply concentrates in Thailand, Australia, and eastern China where extrusion infrastructure overlaps with export logistics. Raw material flows draw from Peruvian fishmeal operations, domestic Chinese grain processors, and Australian meat rendering facilities. Single-source vulnerability runs through vitamin premix channels tethered to European suppliers. Distribution runs through platform ecosystems in China and India that collapse traditional wholesale layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as platform-mediated distribution fragments buyer access and creates niche positioning space for formulation specialists outside multinational conglomerate channels. Urban pet owner premiumization across tier-one cities generates micro-segments underserved by mass-market portfolios.
For Market Incumbents: Compound veterinary network density through exclusive formulation partnerships with university teaching hospitals in Japan and Australia. Acquire cold-pressing manufacturing assets in South Korea to preempt therapeutic nutrition capacity constraints. Defend against platform-native challengers by embedding subscription replenishment APIs within Tmall and Shopee storefronts.
For New Entrants and Emerging Players: China's GB standard fast-track for imported pet feed creates entry pathway for clinically validated functional formats without domestic facility investment. Vietnam and Philippines conversion zones offer white-space for affordable complete nutrition targeting traditional feeding households. Indonesia's platform ecosystem enables direct-to-home subscription models with minimal offline retail fixed costs.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional feed specialists in Thailand and western India lacking veterinary channel access. Five-to-ten year viability hinges on therapeutic nutrition capability buildout versus commodity volume exposure. Acquisition target archetype: mid-cap extrusion operators with dormant cold-processing retrofit potential. Watch for MFDS and SAMR enforcement intensity as inflection signal for compliance cost barriers.
| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Partnership | Secures therapeutic nutrition shelf space against Mars and Nestlé dominance in Japan's clinic networks. |
| Cold-Processing Retrofit | Enables functional ingredient preservation that commands FOSHU-aligned premium positioning in South Korea. |
| Platform API Integration | Embeds replenishment algorithms within Alibaba and Shopee ecosystems for recurring revenue capture. |
| GB Standard Pre-Certification | Accelerates mainland China entry by front-loading SAMR hygiene documentation before facility investment. |
| Premix Vitamin Backward Integration | Reduces foreign exchange exposure and biosecurity clearance delays from European supplier dependency. |
Research Methodology
A standing panel of veterinary nutritionists, pet specialty retail buyers, platform ecosystem managers, and feed manufacturing operations directors provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation against NMPA GB standard filings, MFDS import inspection records, customs trade data, and SEC 10-K disclosures from multinational packaged goods conglomerates. Bottom-up facility capacity assessments and top-down consumption surveys underwent iterative triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated product type, packaging format, sales channel, and customer archetype dimensions alongside regulatory compliance tier as an industry-specific stratifier. CAGRs derived from annualized growth rate interpolation between base and terminal year estimates, with feed ingredient price indices and urban pet ownership penetration curves as forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained platform ecosystem expansion or GB standard enforcement continuity would require recalibration. Forecasts reflect documented assumptions about veterinary channel access stability and tropical climate storage cost trajectories. Revision becomes warranted when fishmeal price volatility or avian influenza outbreak frequency crosses historical threshold bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Calming Products Market
Pet Care Products
UTI Cat Food Market
Pet Care Products
Pet Care Market
Pet Care Products
Pet Selfie Tools Market
Pet Care Products
Dog Perfume Market
Pet Care Products
Pet Stairs Market
Pet Care Products
China Pet Boarding Market
Pet Care Products
Indonesia Pet Care Market
Pet Care Products
Pet Daycare Market
Pet Care Products
Asia Pacific Pet Diet Market
Pet Care Products
Dog Bed Covers Market
Pet Care Products
Organic Dog Food Market
Pet Care Products
Pet Shampoo Market
Pet Care Products
Dog Clothing and Accessories Market
Pet Care Products
Organic and Natural Dog Foods Market
Pet Care Products
Plant-Based Pet Food Market