
 Global Probiotic Cosmetic Products Market | 2026-2036
Global Probiotic Cosmetic Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Probiotic Cosmetic Products Market Intelligence
The prestige-seeking homecare consumer is collapsing the salon-dependent distribution model that once dominated probiotic skincare. TULA Life leverages physician-backed positioning and clean-ingredient transparency to anchor its direct-to-consumer channel. Eminence Organic Skincare sustains farm-to-face sourcing narratives that differentiate its biodynamic probiotic lines. L'Oréal S.A. dominates mass-market access through pharmacy and department store networks across France, Brazil, and the United States.
Probiotic cosmetic products incorporate live or lysed beneficial bacteria, fermented extracts, and postbiotic metabolites into topical formulations designed to modulate skin microbiome balance and strengthen barrier function. Manufacturing requires cold-chain preservation or microencapsulation to maintain strain viability through shelf life, with pH buffering critical to prevent formula degradation. Facial creams and serums command premium positioning due to concentrated active delivery systems and higher per-unit margins. The sensitive skin care application segment expands fastest as dermatology clinics validate microbiome-supporting protocols for rosacea and eczema patients. Online retail channels capture growing share as tele-dermatology and influencer education reduce reliance on in-person sampling.
The FDA oversees cosmetic safety under the Federal Food, Drug, and Cosmetic Act while lacking pre-market approval authority for probiotic topical claims, creating uncertainty around structure-function positioning. The EU Cosmetics Regulation mandates safety assessments through ECHA-notified bodies and restricts live microorganism claims without substantiated dossiers. South Korea's MFDS and China's NMPA impose distinct strain-registration requirements that fragment global formulation strategies. Stakeholders must monitor evolving microbiome-specific regulatory categories across the United States, European Union, and East Asia to anticipate compliance-driven reformulation cycles and claim-adjustment costs.
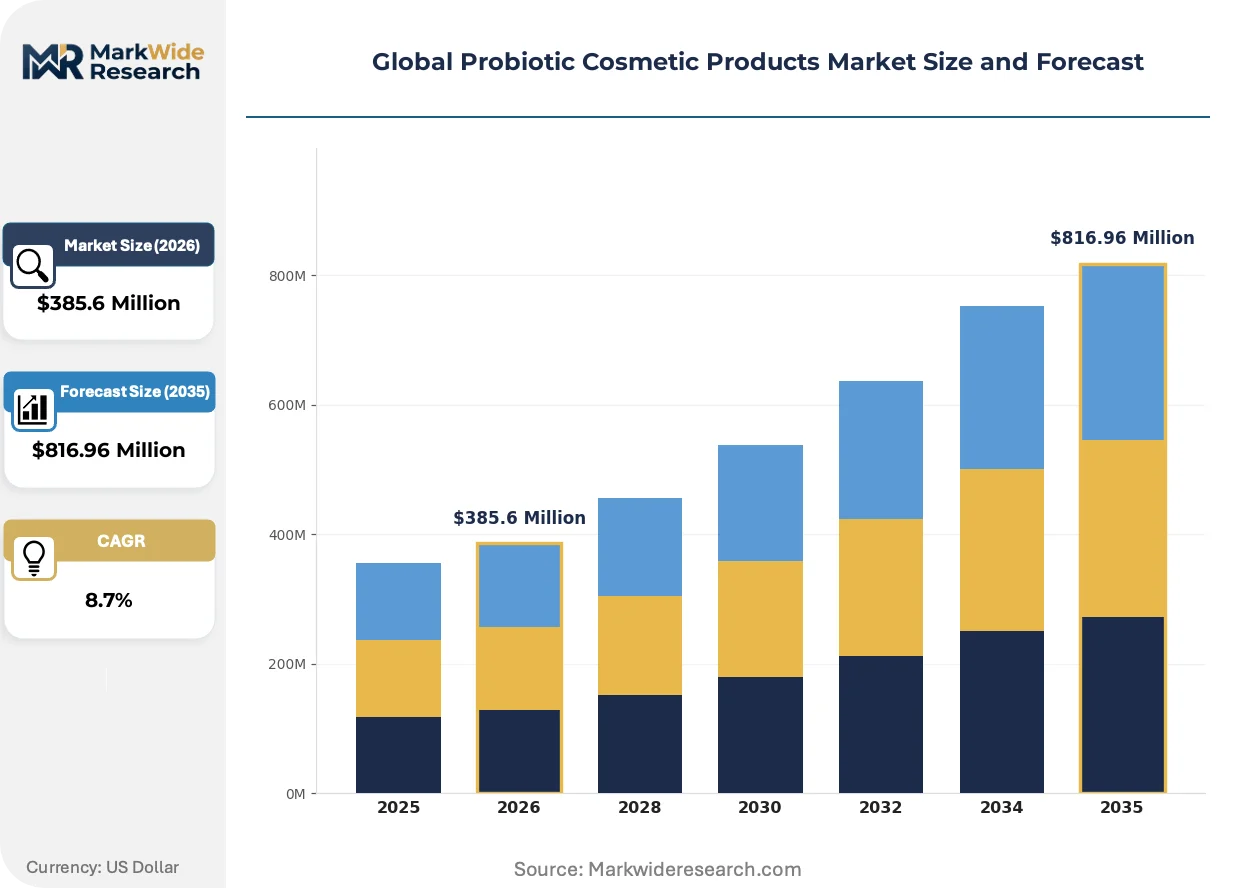
Market Dynamics
Tele-dermatology platforms and influencer-led education are collapsing the in-person sampling dependency that once anchored probiotic skincare distribution, forcing brands to rebuild trust architectures through digital channels and cold-chain logistics guarantees.
Growth Catalysts
- EU Cosmetics Regulation safety dossiers:Harmonized ECHA-notified body assessments reduce fragmentation for cross-border launches, accelerating multi-country rollouts for substantiated microbiome claims.
- Sensitive skin care protocols:Dermatology clinics in France and the United States validate postbiotic metabolites for rosacea and eczema management, creating clinical credibility that transfers to retail.
- Direct-to-consumer cold-chain infrastructure:Refrigerated last-mile networks in China and South Korea enable live strain viability guarantees that mass-market pharmacy channels cannot match.
Market Restraints
- Strain-specific registration requirements:China's NMPA and South Korea's MFDS impose divergent live microorganism dossiers, fragmenting global formulation strategies and duplicating compliance costs.
- Lyophilization and microencapsulation input concentration:Three suppliers control pharmaceutical-grade trehalose and cryoprotectant supply, creating vulnerability to price volatility and allocation constraints.
- Shelf-life technical ceiling:Current pH buffering systems degrade postbiotic activity above 18 months, limiting distribution radius for premium live formulations.
Strategic Opportunities
- Brazil's ANVISA regulatory pathway:Emerging microbiome-friendly certification frameworks in Latin America's largest market offer first-mover positioning before standards mature.
- Scalp and hair microbiome applications:Undeveloped adjacencies in trichology clinics and salon channels extend probiotic positioning beyond facial skincare saturation.
- Subscription-based replenishment models:Cold-chain logistics integration with tele-dermatology platforms creates recurring revenue structures that bypass traditional retail margin stacking.
Industry Challenges
- Microbiome assay standardization:Lack of ISO-validated skin sampling protocols forces brands to fund proprietary clinical studies, inflating substantiation budgets and delaying launch timelines.
- Cross-functional talent scarcity:Formulation chemists with simultaneous expertise in strain viability preservation and cosmetic sensory engineering command premium compensation that mid-scale players cannot absorb.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Probiotic Cosmetic Products Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $816.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Facial Creams, Body Lotions, Cleansers, Serums, Masks Application: Anti-Aging, Skin Brightening, Moisturizing, Acne Treatment, Sensitive Skin Care End User: Dermatology Clinics, Salons, Homecare Consumers, Wellness Centers, Spas Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Direct Sales, Department Stores |
| Companies Covered | TULA Life, Eminence Organic Skincare, L'Oréal S.A., Glowbiotics, Aurelia Skincare, Estée Lauder Companies, Esse Skincare, LaFlore Probiotic Skincare, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Probiotic Cosmetic Products Market Strategic Shifts & Innovations
Biotechnology advances and regulatory category creation are converging to redefine how probiotic cosmetic products demonstrate efficacy, manufacture at scale, and reach consumers through channels that bypass traditional retail gatekeepers.
Lyophilized live strain formats with pharmaceutical-grade cryoprotection are supplanting traditional fermented extract bases in premium facial serums. Dermatology-backed brands in the United States and France are adopting these formats to support structure-function claims that fermented extracts cannot substantiate. The shift is compressing margins for conventional postbiotic suppliers while rewarding vertically integrated strain developers with captive bioprocessing capabilities.
Japan's PMDA and South Korea's MFDS are developing distinct microbiome-specific cosmetic categories that diverge from EU and US frameworks. These regulatory innovations force multinational formulators to maintain parallel dossier systems and strain banks. Sensitive skin care lines targeting atopic dermatitis patients face the steepest compliance burden as they seek dual positioning between cosmetic and quasi-drug classifications.
Consumer verification behaviors now prioritize third-party microbiome-friendly certifications over brand-owned clean beauty claims. Specialty retailers in France and the United States are responding by demanding independent assay documentation before shelf placement. This certification-driven preference shift most visibly concentrates among millennial and Gen Z purchasers in urban China, where domestic influencers amplify foreign standard credibility.
Global Probiotic Cosmetic Products Market Segmentation
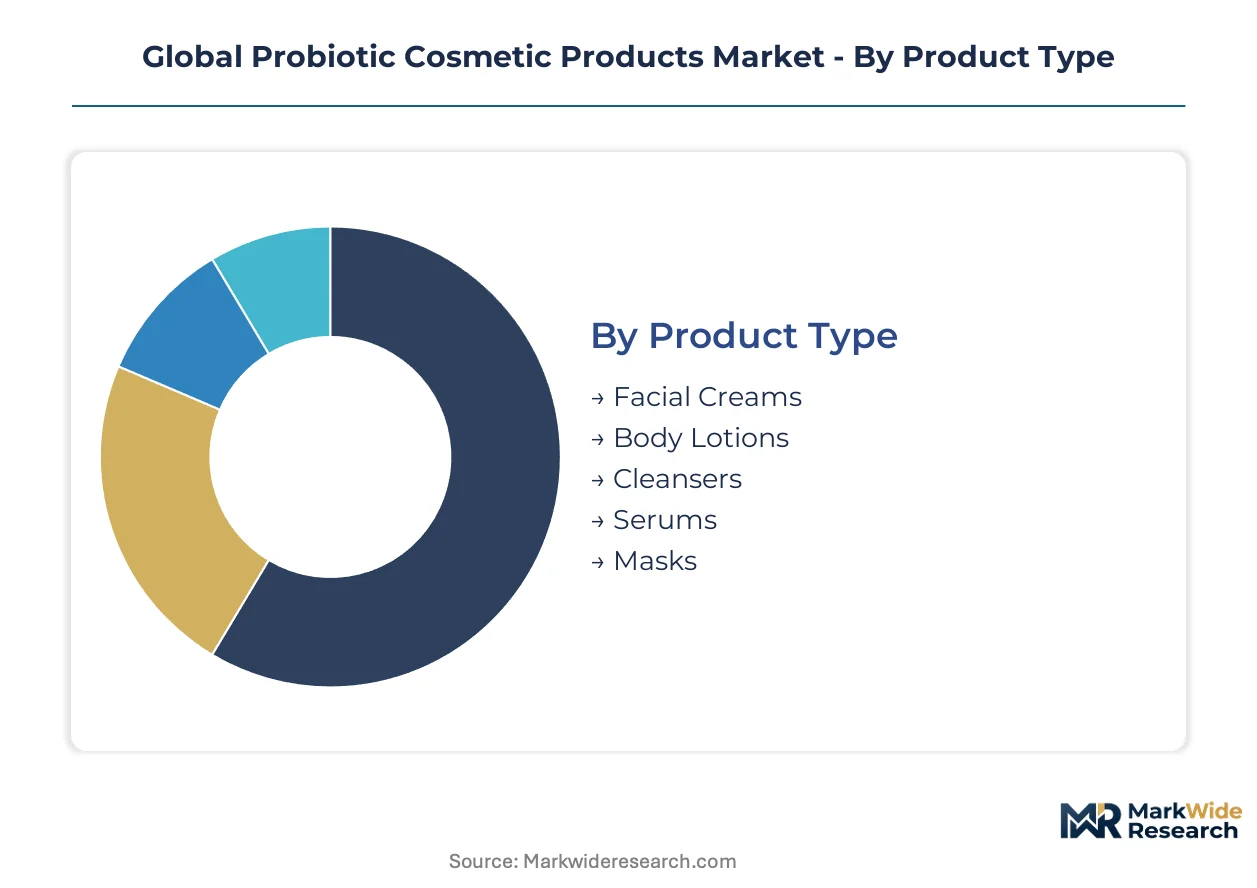
Probiotic cosmetic formulations fragment across multiple demand dimensions that determine pricing architecture, regulatory pathway, and cold-chain logistics requirements. Understanding these segment boundaries reveals where microbiome-friendly certifications command premium positioning versus mass-market penetration.
Product Type:
Geographic demand concentration varies sharply by format, with serums and masks dominating export-led premium channels while creams and lotions anchor domestic mass-market shelves.
- Facial Creams:pH-buffered emulsion bases incorporate lysed bacterial extracts and postbiotic metabolites for barrier repair. Demand concentrates in France and the United States where pharmacy networks validate dermatological positioning, though live strain viability remains limited to shorter shelf-life formats.
- Serums:Concentrated aqueous delivery systems enable higher active loading of live or lyophilized strains with pharmaceutical-grade cryoprotection. South Korea's direct-to-consumer cold-chain infrastructure supports the steepest volume expansion for refrigerated serum subscriptions targeting sensitive skin protocols.
- Body Lotions:Lower concentration postbiotic formulations dominate mass-market access in Brazil and Mexico through pharmacy and supermarket channels.
- Cleansers:Rinse-off formats favor fermented extract bases over live strains due to formulation stability constraints and shorter skin contact time.
- Masks:Sheet and rinse-off formats in China and Japan leverage microbiome-friendly certification premiums for weekly treatment positioning.
Facial creams command the established base. The steepest expansion runs through serums.
Application:
Cost tier stratification separates clinical-grade positioning from accessible wellness claims, with prescription-adjacent protocols justifying threefold price multiples over general brightening or moisturizing lines.
- Sensitive Skin Care:Dermatology clinics in France and the United States validate postbiotic metabolites for rosacea and eczema management, creating clinical credibility that transfers to retail at premium price points. Regulatory substantiation costs limit participation to well-capitalized formulators with captive clinical study capabilities.
- Anti-Aging:Collagen-support claims through microbiome modulation attract the highest per-unit margins in China's urban millennial segment, where influencer amplification of foreign certification standards drives purchase decisions.
- Moisturizing:Entry-level positioning dominates volume in Brazil and India through pharmacy and general trade channels with minimal strain-specific claims.
- Skin Brightening:Postbiotic tyrosinase inhibition narratives concentrate in East Asian markets with distinct regulatory pathways from Western pigmentation positioning.
- Acne Treatment:Strain-specific Cutibacterium acnes competitive exclusion claims require clinical dossiers that only South Korea and United States dermatology-backed brands currently substantiate.
Sensitive skin care anchors premium pricing power. Anti-aging applications are climbing the fastest in value terms.
End User:
Channel control and customer acquisition economics diverge sharply between institutional procurement and direct-to-consumer subscription models.
- Homecare Consumers:Subscription replenishment with cold-chain guarantees now captures the dominant revenue share in China and South Korea, displacing traditional department store sampling dependency.
- Dermatology Clinics:Institutional procurement in France and the United States requires ISO-validated assay documentation and strain-specific dossiers that filter supplier bases to vertically integrated bioprocessors.
- Salons:Farm-to-face sourcing narratives sustain positioning for biodynamic probiotic lines in European professional channels.
- Spas:Treatment-room application favors single-use live strain formats with immediate activation protocols.
- Wellness Centers:Holistic positioning bridges cosmetic and supplement categories with looser regulatory scrutiny in select Latin American markets.
Homecare consumers command the established base. Dermatology clinics represent the steepest expansion trajectory for substantiated live strain formats.
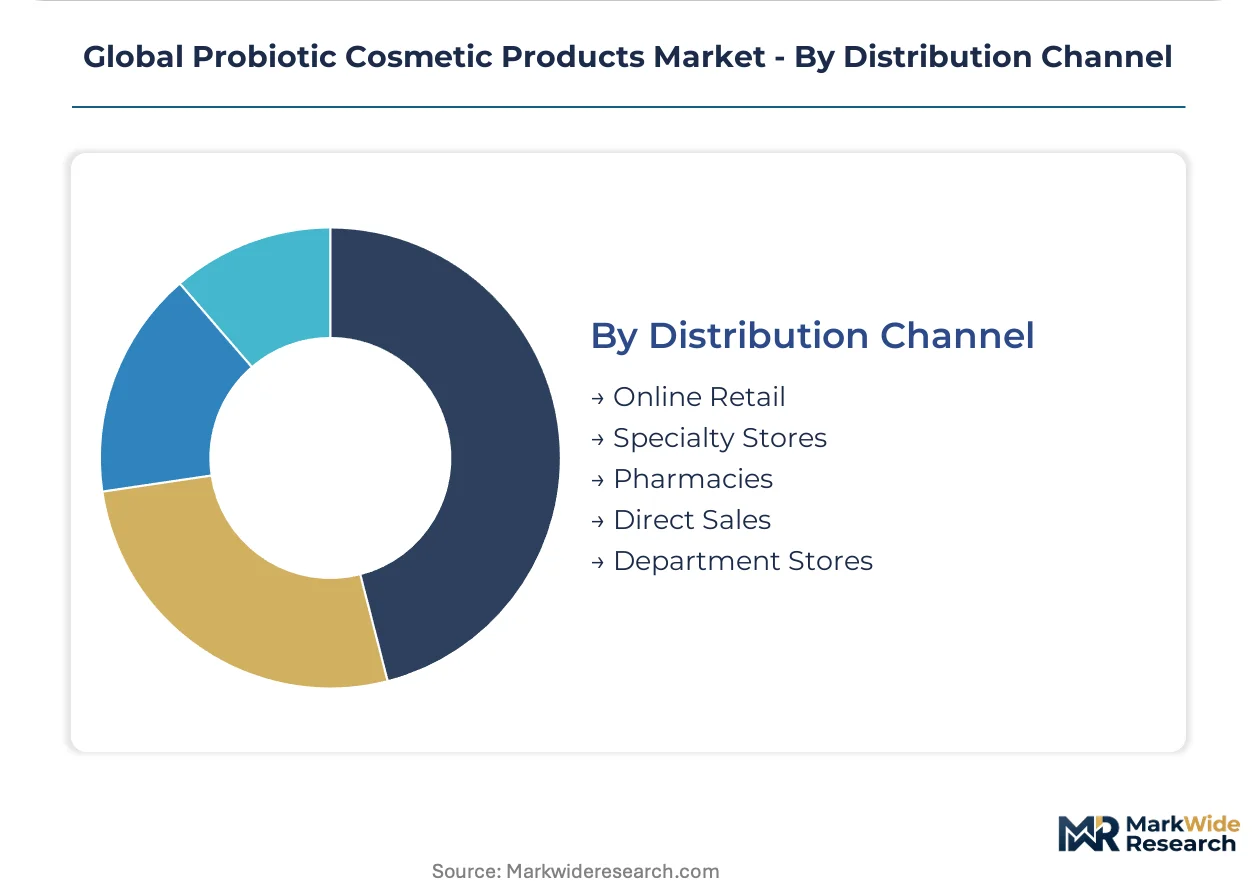
Distribution Channel:
Logistics infrastructure investment determines which channels can support live strain viability guarantees versus postbiotic-only distribution.
- Online Retail:Tele-dermatology platform integration and influencer-led education collapse traditional sampling requirements, enabling refrigerated last-mile networks in China and South Korea to guarantee strain viability through delivery.
- Specialty Stores:Independent assay documentation demands from French and United States retailers filter shelf access to certified microbiome-friendly lines with substantiated dossiers.
- Pharmacies:Mass-market access in Brazil and France supports postbiotic extracts without live strain cold-chain requirements.
- Direct Sales:Consultant-led education sustains premium positioning in markets with underdeveloped digital infrastructure.
- Department Stores:Collapsing relevance for probiotic skincare as millennials and Gen Z abandon traditional beauty counters for digital discovery.
Online retail commands the established base. Specialty stores are gaining share fastest through certification-driven curation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai Yangshan deep-water port anchors Asia-Pacific cold-chain logistics for live strain cosmetic ingredients, enabling refrigerated container throughput that underwrites South Korea's direct-to-consumer serum subscriptions and China's cross-border e-commerce fulfillment.
United States
Dermatology clinic procurement and tele-dermatology platform integration drive institutional and homecare demand simultaneously. FDA oversight under the Federal Food, Drug, and Cosmetic Act maintains pre-market approval gaps for probiotic topical claims, creating regulatory uncertainty that favors substantiated postbiotic formulations. California's biotech corridor concentrates strain development facilities serving prestige skincare brands with clinical study capabilities.
China
Urban millennial consumers in Shanghai and Beijing prioritize third-party microbiome-friendly certifications amplified through domestic influencer channels. NMPA strain-specific registration requirements impose dossier duplication costs that filter supplier bases to well-capitalized formulators. The Yangtze River Delta hosts cold-chain logistics networks enabling refrigerated last-mile delivery for live strain viability guarantees.
South Korea
Direct-to-consumer subscription models with integrated cold-chain infrastructure capture dominant revenue share among skincare-conscious Gen Z purchasers. MFDS microbiome-specific cosmetic category development diverges from EU and US frameworks, forcing parallel dossier maintenance. Seoul Capital Area biotech clusters specialize in lyophilized strain formats with pharmaceutical-grade cryoprotection for premium serum export.
France
Pharmacy network validation of dermatological positioning sustains premium pricing for barrier-repair facial creams. EU Cosmetics Regulation safety assessments through ECHA-notified bodies reduce cross-border launch fragmentation for substantiated microbiome claims. Paris and Lyon concentrate formulation R&D facilities serving both domestic prestige lines and export-oriented biodynamic probiotic brands.
Brazil
Mass-market pharmacy and supermarket channels distribute lower-concentration postbiotic body lotions to price-sensitive consumers in São Paulo and Rio de Janeiro. ANVISA emerging microbiome-friendly certification frameworks offer first-mover positioning before standards mature. Southeast industrial zones host contract manufacturers adapting European fermentation extract processes for tropical climate stability requirements.
Global Probiotic Cosmetic Products Market Key Industry Players
Listed leaders compete with private specialists across capital access and agility dimensions, producing a tiered structure where multinational consumer goods conglomerates anchor mass-market pharmacy distribution while physician-backed private brands capture direct-to-consumer premium positioning. Three archetypes dominate: vertically integrated bioprocessors with captive strain banks, dermatology clinic-validated prestige formulators, and farm-to-face sourcing narrative specialists. Competitive moves concentrate on cold-chain logistics partnerships and microbiome-friendly certification acquisition.
Within the dermatology-validated tier, TULA Life and Glowbiotics exemplify physician-backed positioning architectures that leverage clean-ingredient transparency to anchor subscription revenue models. Eminence Organic Skincare occupies a distinct sourcing narrative position, representing the biodynamic probiotic line archetype sustained through farm-to-face storytelling. L'Oréal S.A. anchors the listed conglomerate tier, exemplifying mass-market access scale through pharmacy and department store network dominance across multiple continents.
| Leading Market Players |
|---|
| TULA Life |
| Eminence Organic Skincare |
| L'Oréal S.A. |
| Glowbiotics |
| Aurelia Skincare |
| Estée Lauder Companies |
| Esse Skincare |
| LaFlore Probiotic Skincare |
| Unilever |
| Others |
Cost & Logistics Intelligence
Pharmaceutical-grade cryoprotectant production scale in South Korea and Japan establishes minimum viable batch economics that filter supplier bases and set price floors for live strain formats. Cold-chain infrastructure investment thresholds concentrate viable manufacturing among vertically integrated bioprocessors, compressing margins for contract formulators lacking captive strain banks.
Pricing Analysis
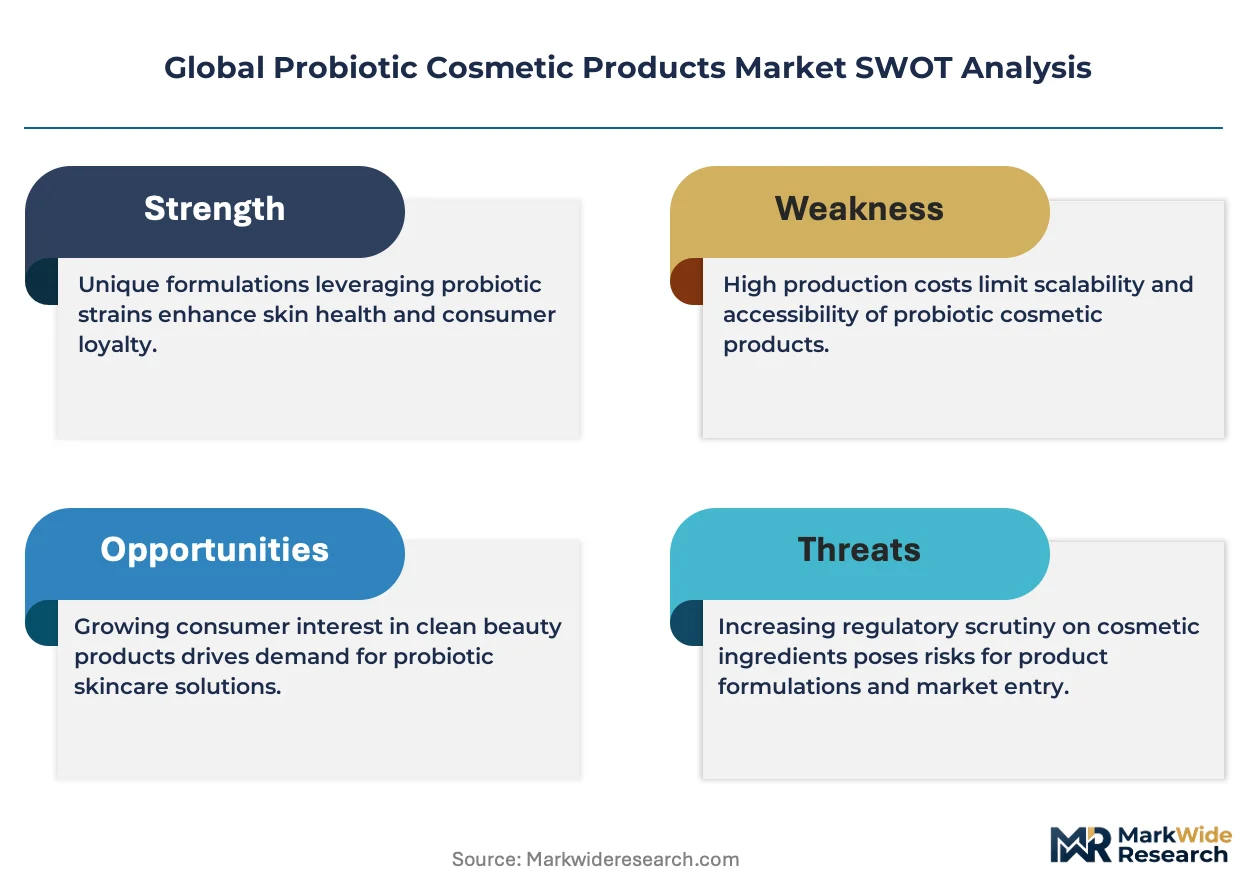
Volume-discount tiering structures separate dermatology clinic procurement contracts from direct-to-consumer subscription pricing. Three-tier pricing stratifies across lyophilized live strain serums, postbiotic extract creams, and fermented cleanser bases, with certification grade and cold-chain guarantee as primary differentiation drivers. Pricing pressure stems from lyophilization input concentration among three dominant trehalose suppliers. Homecare consumers exhibit highest price sensitivity; dermatology clinics accept premium positioning for ISO-validated assay documentation.
Supply Chain Analysis
Strait of Malacca transit routes anchor refrigerated container flows for live strain ingredients moving from South Korean biotech clusters to Chinese cross-border e-commerce fulfillment centers. Manufacturing concentration in France, South Korea, and the United States draws from pharmaceutical-grade trehalose, cryoprotectant polymers, and pH buffering systems. Single-source vulnerability in cryoprotectant supply creates allocation risk during demand surges. Distribution runs through direct-to-consumer cold-chain networks in China and South Korea, pharmacy channels in France and Brazil, and specialty retailers demanding independent certification documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as the primary defensive moat, with strain-specific dossier requirements creating switching costs that lock institutional buyers into validated supplier relationships.
For Market Incumbents: Secure ECHA-notified body assessments and MFDS parallel dossiers before emerging certification frameworks mature in Brazil and other Latin American markets. Expand cold-chain logistics partnerships in China's Yangtze River Delta to defend against direct-to-consumer entrants lacking refrigerated last-mile infrastructure. Prioritize captive bioprocessing capabilities to reduce trehalose supplier concentration risk.
For New Entrants and Emerging Players: Anchor in scalp and hair microbiome applications where trichology clinic validation remains undeveloped and salon channel saturation is lowest. Target Brazil's ANVISA emerging certification pathway for first-mover positioning before standards crystallize. Build subscription-based replenishment models with tele-dermatology platform integration to bypass traditional retail margin stacking.
For Investors and Strategic Acquirers: Physician-backed prestige formulators with clinical study capabilities and clean-ingredient transparency positioning represent the most defensible acquisition archetype. Long-term viability hinges on regulatory substantiation depth rather than brand marketing spend. Watch for MFDS and PMDA microbiome-specific category finalization as inflection signals for compliance-driven consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Microbiome-Friendly Certification Acquisition | Independent assay documentation from ECHA-notified bodies unlocks specialty retailer shelf placement in France and the United States. |
| Cold-Chain Logistics Integration | Refrigerated last-mile partnerships in South Korea and China enable live strain viability guarantees that mass-market channels cannot replicate. |
| Vertical Strain Bank Development | Captive bioprocessing capabilities reduce pharmaceutical-grade cryoprotectant supplier concentration and buffer allocation volatility. |
| Tele-Dermatology Platform Partnership | Subscription replenishment models through digital health channels collapse traditional department store sampling dependency. |
| Scalp Microbiome Line Extension | Trichology clinic validation creates undeveloped adjacency beyond facial skincare saturation. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA cosmetic safety guidance, EU Cosmetics Regulation ECHA dossiers, and MFDS strain registration requirements. Interviews with formulation chemists, dermatology clinic procurement managers, cold-chain logistics operators, and specialty retailer category buyers combined with customs trade data and bioprocessing equipment shipment records. Bottom-up strain volume estimates and top-down channel revenue analysis triangulate market sizing.
Segmentation dimensions modeled include product format, application indication, end-user archetype, and distribution channel across the projection horizon. CAGRs derive from growth driver elasticity analysis against regulatory pathway timelines and cold-chain infrastructure buildout rates. Forecast inputs incorporate microbiome assay standardization progress and tele-dermatology platform penetration curves.
Material uncertainties — NMPA strain-specific registration shifts, cryoprotectant supply allocation disruptions, and ISO-validated skin sampling protocol adoption — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory harmonization trajectories and cold-chain cost compression curves. Practitioners should keep alternative scenarios live as ANVISA certification framework evolution and PMDA category divergence progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Luxury Beauty Devices Market
Beauty & Personal Care
Global Cosmetics Market
Beauty & Personal Care
Hair Conditioner Market
Beauty & Personal Care
Beauty Devices Market
Beauty & Personal Care
South America Hair Styling Products Market
Beauty & Personal Care
Middle East and Africa Hair Conditioner Market
Beauty & Personal Care
Global and North America Organic and Natural Feminine Care Market
Beauty & Personal Care
Electric Nail Files Market
Beauty & Personal Care
US Sexual Wellness Market
Beauty & Personal Care
Facial Epilator Market
Beauty & Personal Care
Brazil Beauty and Personal Care Products Market
Beauty & Personal Care
Saudi Arabia Eyelash Serum Market
Beauty & Personal Care
Global Organic Personal Care Products Market
Beauty & Personal Care
Eyelash Curler Market
Beauty & Personal Care
Plant-Based Skincare Products Market
Beauty & Personal Care
Global Bath Salts Market