
 GCC Dog Food Market | 2026-2036
GCC Dog Food Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Dog Food Market Intelligence
Affluent urban households is reorganizing demand patterns across the GCC dog food sector, displacing traditional mass-market buyers as the primary volume engine. Mars Petcare leverages its multi-brand portfolio to dominate shelf space across Saudi Arabian hypermarkets. Nestlé Purina PetCare anchors its position through specialized veterinary diet formulations that command premium positioning. Hill's Pet Nutrition differentiates via science-backed clinical nutrition channels tied to veterinary clinics.
Dog food encompasses commercially manufactured nutritional products formulated from proteins, fats, carbohydrates, vitamins, and minerals to meet canine dietary requirements, typically processed through extrusion for dry formats or retort sterilization for wet formats to ensure shelf stability and digestibility. Dry food occupies the largest volume share due to cost efficiency and storage convenience across Gulf climates, while grain-free ingredient formulations capture the fastest value growth as pet owners prioritize digestive sensitivity and allergen avoidance. Wet food in pouch packaging concentrates margin pools through portion-controlled premium positioning targeting small-breed ownership.
SFDA labeling mandates and UAE Ministry of Climate Change and Environment import protocols shape product registration timelines and ingredient sourcing transparency across Gulf markets. GCC Standardization Organization (GSO) pet food safety standards further harmonize manufacturing benchmarks for cross-border trade. Stakeholders must monitor evolving veterinary endorsement requirements and cold-chain infrastructure gaps affecting raw food segment viability.
Market Dynamics
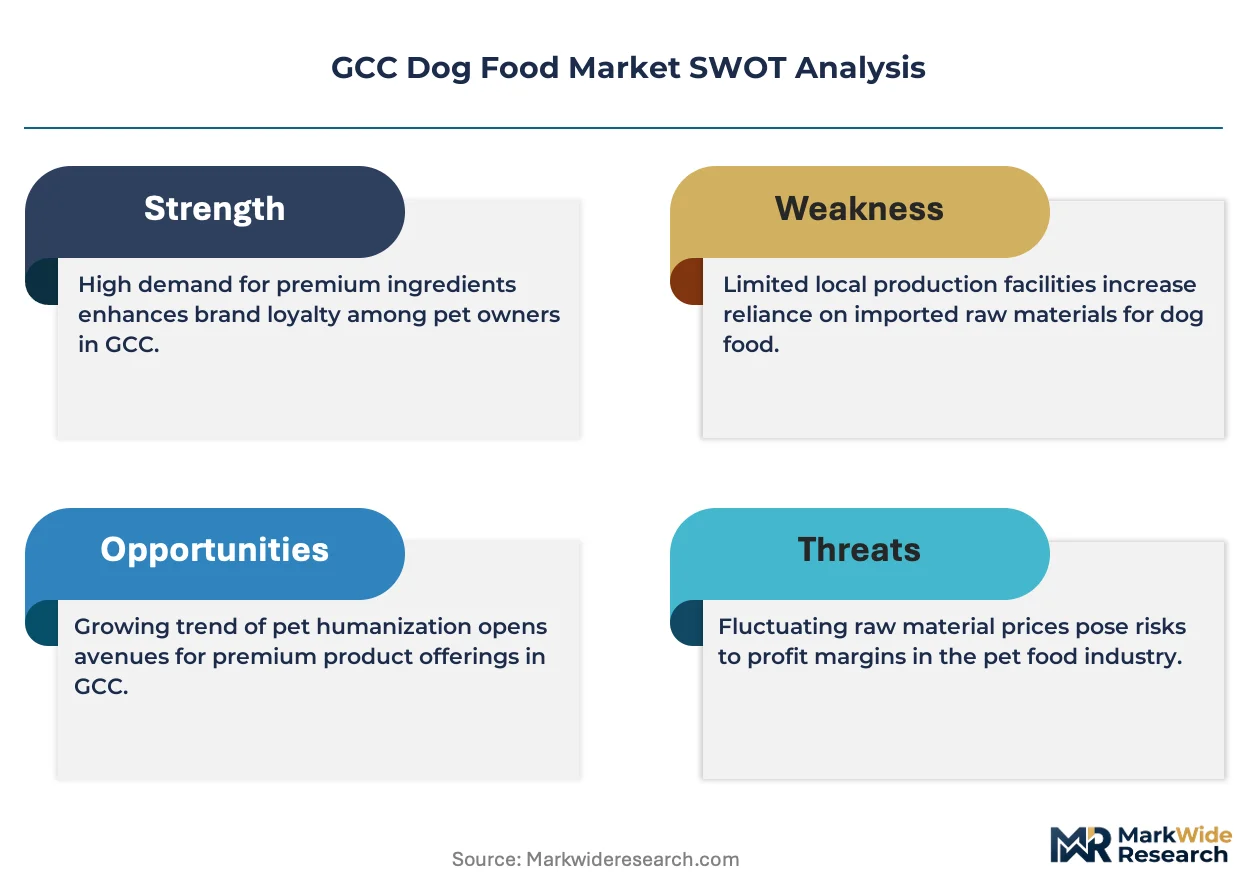
Pet humanization among affluent Gulf households is compressing traditional mass-market demand and elevating premium clinical nutrition formats. This structural force is redistributing value pools toward veterinary-anchored distribution channels and specialized ingredient sourcing.
Growth Catalysts
- SFDA Labeling Mandates:Saudi Food and Drug Authority disclosure requirements on ingredient provenance and nutritional adequacy are accelerating transparency investments by importers. This regulatory pressure is filtering substandard suppliers and consolidating shelf access for compliant brands.
- Expatriate Household Concentration:High-income foreign residents in Dubai and Abu Dhabi are driving demand for grain-free and limited-ingredient formulations. Their purchasing power sustains premium pricing tiers unavailable to mass-market segments.
- Veterinary Channel Integration:Science-backed clinical diets distributed through private veterinary clinics are capturing margin-rich repeat purchases. This channel shift locks in prescription-level loyalty beyond conventional retail.
Market Restraints
- Import Dependency:Domestic manufacturing capacity across Saudi Arabia, UAE, and Qatar remains negligible. Reliance on European and North American suppliers exposes distributors to currency volatility and shipping cost spikes.
- Raw Material Concentration:High-quality animal protein sourcing concentrates in specialized rendering facilities with limited Gulf presence. This bottleneck constrains local formulation flexibility and extends lead times.
- GSO Harmonization Friction:GCC Standardization Organization pet food safety benchmarks create registration delays for products crossing member-state borders. Divergent national interpretations of shared standards fragment compliance workflows.
Strategic Opportunities
- Kuwait Penetration Gap:Per-capita pet ownership rates in Kuwait lag UAE benchmarks by substantial margins. Early entrants establishing veterinary partnerships there can preempt competitive positioning before market maturation.
- Cold-Chain Infrastructure Gaps:Raw and fresh-frozen dog food segments remain underdeveloped due to temperature-controlled logistics deficiencies. Investors in specialized last-mile refrigeration can capture first-mover premiums in this whitespace.
- MOHAP Veterinary Endorsement Pathway:UAE Ministry of Health and Prevention protocols for clinical diet certification create regulatory tailwinds for science-formulated products. Brands securing these endorsements gain preferential clinic access.
Industry Challenges
- Specialized Nutrition Expertise Scarcity:Qualified veterinary nutritionists and formulation scientists remain concentrated in Western markets. Gulf-based manufacturers face recruitment friction and compensation premiums for this talent pool.
- Product Registration Timeline Compression:SFDA and MOHAP approval cycles for novel ingredients or therapeutic claims extend 12-18 months. These durations strain working capital and delay revenue recognition for innovation pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Dog Food Market |
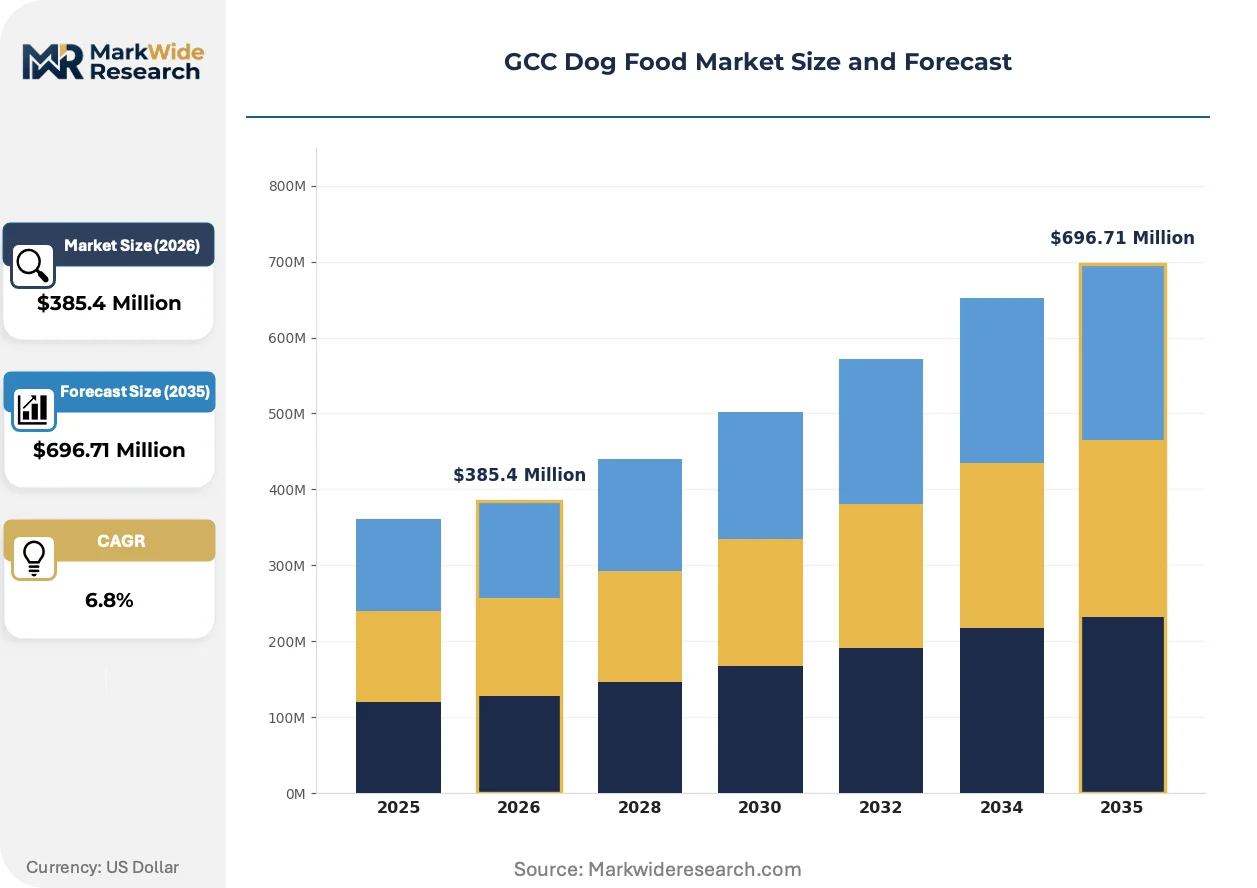
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Raw Food Ingredient Type: Meat-Based, Grain-Free, Organic, Vegetarian Packaging Type: Bags, Cans, Pouches, Tubs Distribution Channel: Online Retail, Pet Stores, Supermarkets, Specialty Stores |
| Companies Covered | Mars Petcare, Nestlé Purina PetCare, Hill's Pet Nutrition, Del Monte Foods, Blue Buffalo Pet Products, Petto Club, Raseen, Bayt Al Aleefa, PURINA Arabia, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Dog Food Market Strategic Shifts & Innovations
Novel protein sources and precision fermentation technologies are actively restructuring ingredient supply economics. These advances are enabling allergen avoidance at scale while compressing reliance on conventional livestock rendering.
Precision fermentation of single-cell proteins is decomposing traditional poultry and fish meal dependencies in premium formulations. Saudi Arabian and Emirati importers are piloting these ingredients for small-breed specialized diets. This biotechnology is decomposing cost structures that previously locked grain-free positioning at luxury price points.
SFDA's phased implementation of digital traceability requirements for imported pet food is tightening documentation burdens on suppliers. Manufacturers must now provide batch-level ingredient origin records and third-party laboratory verification. Wet food and raw formats face the steepest compliance adjustments due to shorter shelf lives and temperature sensitivity.
Subscription-based replenishment models are displacing conventional hypermarket purchasing among urban professional households. Dubai-based pet tech platforms are capturing recurring revenue through algorithmic portion sizing and automated delivery scheduling. This behavioral shift concentrates customer lifetime value with digital-native distributors and erodes traditional retail foot traffic.
GCC Dog Food Market Segmentation
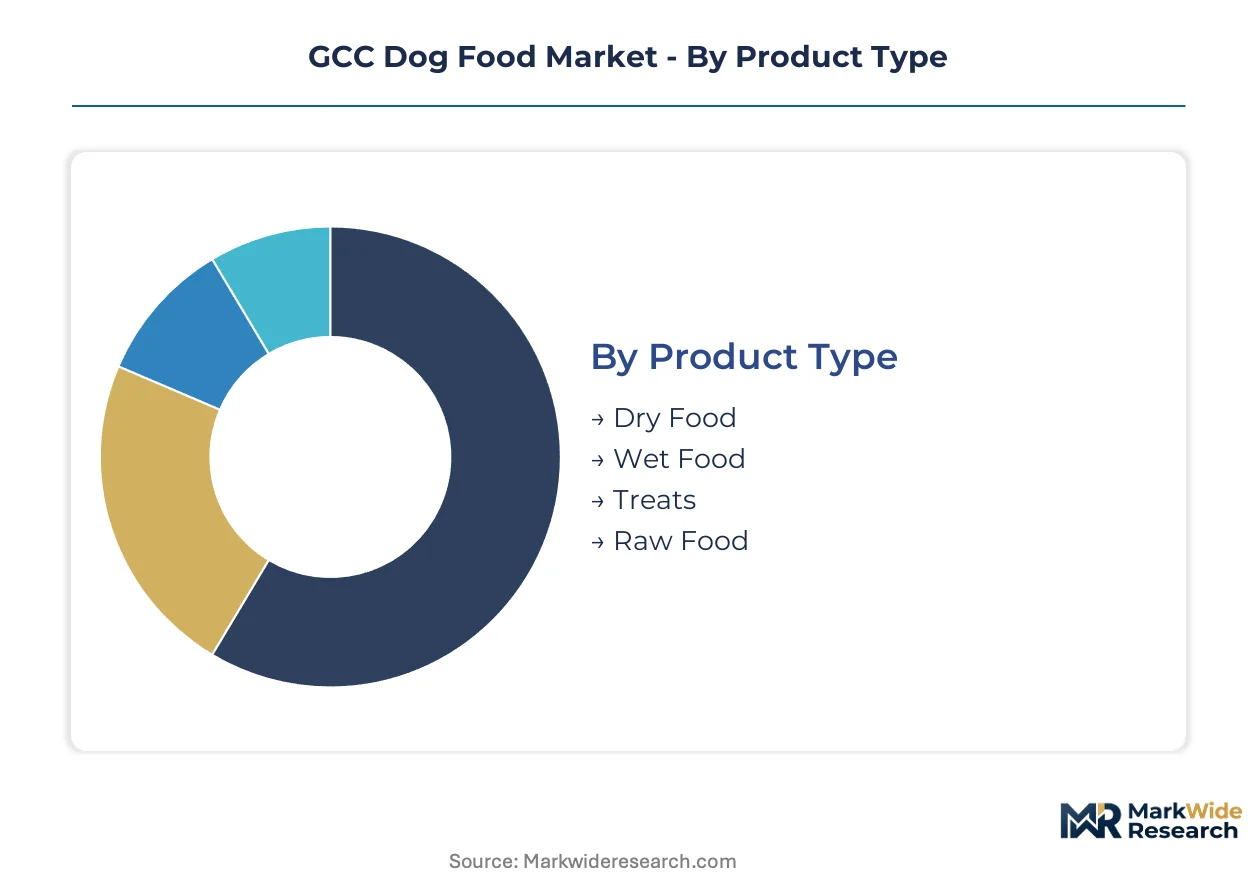
Segmentation in the GCC dog food market reveals how Gulf-specific consumption patterns diverge from Western benchmarks. Climate constraints, import dependency, and expatriate household concentration reshape which product formats and channels capture disproportionate value.
Product Type:
Dry food formats dominate Saudi Arabian hypermarket shelves due to ambient storage tolerance, while wet and raw segments concentrate in UAE veterinary clinics and premium pet boutiques.
- Dry Food:Extruded kibble formulations deliver shelf stability exceeding 18 months under Gulf heat and humidity. Saudi Arabian distributors favor 15-20kg bulk bags for cost-conscious households in Riyadh and Jeddah, though SFDA labeling mandates now require nutritional adequacy statements on every package.
- Wet Food:Retort-sterilized pouches and cans target small-breed owners in Dubai Marina and Abu Dhabi's Al Reem Island, where portion control and palatability command premium positioning. Moisture content above 75% addresses hydration concerns in air-conditioned indoor environments.
- Treats:Functional dental chews and training rewards concentrate in UAE pet specialty retail, with grain-free variants gaining traction among allergen-aware expatriate owners.
- Raw Food:Frozen and freeze-dried formats remain nascent across the Gulf due to cold-chain infrastructure gaps, though Dubai-based subscription services are piloting direct-to-consumer frozen distribution.
Dry food commands the established base. The steepest expansion runs through wet food pouches targeting urban professional households.
Ingredient Type:
Cost tiers stratify sharply across the Gulf, with meat-based formulations anchoring mass-market positioning while grain-free and organic segments extract premiums from high-income expatriate enclaves.
- Meat-Based:Conventional poultry and fish meal formulations supply volume-driven segments across Saudi Arabia's mass retail channel, constrained by rendering facility bottlenecks that extend European import lead times.
- Grain-Free:Potato and legume-substituted recipes target digestive sensitivity concerns among Golden Retriever and French Bulldog owners in Dubai's Jumeirah district, with limited-ingredient positioning justifying 40-60% price premiums over conventional equivalents.
- Organic:Certified ingredient sourcing remains sparse across GCC suppliers, though UAE Ministry of Climate Change and Environment import protocols for organic claims are tightening third-party verification requirements.
- Vegetarian:Plant-protein formulations capture niche positioning among ethically motivated owners in Doha's Education City expatriate community, with pea and lentil protein concentrates substituting animal-derived inputs.
Meat-based formulations anchor volume. Grain-free positioning captures the fastest margin expansion.
Packaging Type:
Volume applications favor bulk formats for multi-dog Saudi households, while single-serve pouches concentrate margin in UAE small-breed ownership.
- Bags:Multi-layer polymer and paper laminate sacks dominate dry food distribution across Saudi hypermarkets, with 10-20kg sizes optimizing per-kilogram economics for large-breed owners in Riyadh's suburban compounds.
- Cans:Steel and aluminum containers retain wet food shelf stability for 24-36 months, though shipping weight penalties disadvantage this format versus flexible alternatives in import-dependent Gulf markets.
- Pouches:Retortable flexible packaging captures premium wet food positioning in UAE pet boutiques, with 85-100g single-serve formats aligning with Chihuahua and Pomeranian portion requirements.
- Tubs:Polypropylene containers with resealable lids target fresh and refrigerated segments, though limited cold-chain penetration restricts this format's Gulf distribution footprint.
Bags sustain the volume core. Pouch formats are climbing the fastest in value terms.
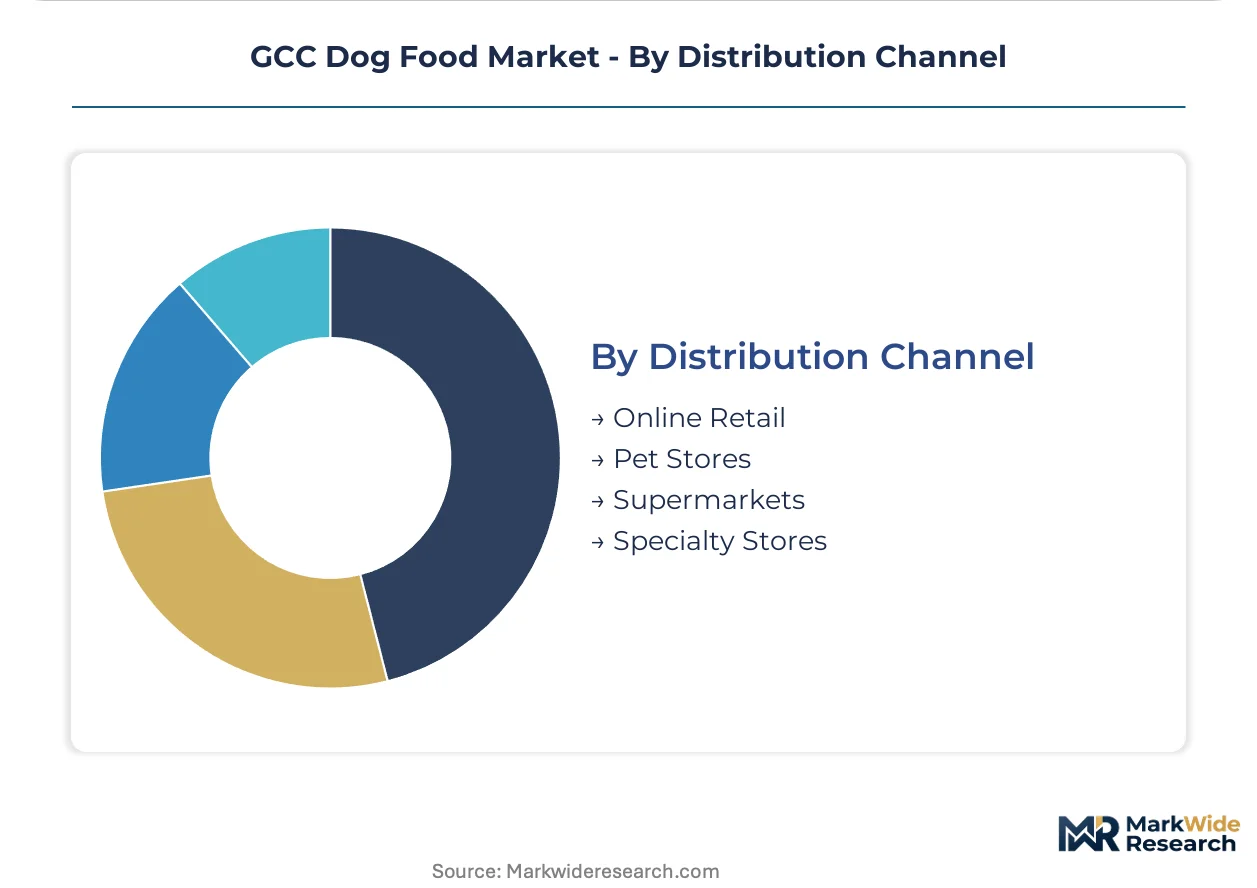
Distribution Channel:
Customer type fragmentation separates subscription-driven urban professionals from conventional retail-dependent mass-market buyers across Dubai and Riyadh.
- Online Retail:Dubai-based pet tech platforms deploy algorithmic replenishment for grain-free and veterinary diet subscriptions, capturing recurring revenue through automated delivery scheduling that erodes hypermarket foot traffic.
- Pet Stores:Specialty retailers in Abu Dhabi's Khalidiyah Mall and Riyadh's Riyadh Park concentrate premium brand visibility, with trained staff delivering breed-specific nutritional guidance unavailable in mass retail.
- Supermarkets:Carrefour and Lulu Hypermarket chains across Saudi Arabia and UAE anchor Mars Petcare and Nestlé Purina mass-market penetration through end-cap displays and promotional pricing.
- Specialty Stores:Veterinary clinic pharmacies in Dubai's Dubai Silicon Oasis and Riyadh's King Faisal Specialist Hospital precinct distribute Hill's Prescription Diet and Royal Canin clinical formulations with professional endorsement leverage.
Supermarkets hold the volume foundation. Online retail is expanding most quickly among affluent urban cohorts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European and North American exporters dominate inbound supply corridors into Gulf Cooperation Council ports, with Rotterdam and Hamburg serving as consolidation hubs for containerized pet food shipments destined for Jeddah and Jebel Ali.
Saudi Arabia
Riyadh and Jeddah absorb the highest dry food volumes through hypermarket channels serving large-breed owners in suburban compounds. SFDA labeling mandates on ingredient provenance and nutritional adequacy statements filter substandard imports and consolidate shelf access for compliant European suppliers. The Eastern Province's Dammam corridor anchors inbound logistics for Red Sea and Arabian Sea port entries.
United Arab Emirates
Dubai Marina and Abu Dhabi's Al Reem Island concentrate demand for wet food pouches targeting small-breed ownership among high-income expatriates. MOHAP veterinary endorsement protocols for clinical diet certification create regulatory pathways that preferentially channel science-formulated products through private clinics. Dubai Silicon Oasis clusters veterinary pharmacy distribution for prescription-tier nutrition.
Qatar
Doha's Education City expatriate community sustains niche demand for ethically positioned vegetarian and plant-protein formulations. The country's national food safety regulator enforces import documentation standards that align with GCC Standardization Organization benchmarks. Lusail City's emerging retail infrastructure attracts premium pet boutique concepts from UAE-based operators.
Kuwait
Per-capita pet ownership rates lag UAE benchmarks by substantial margins, leaving veterinary partnership opportunities underexploited. The national environment authority's pet food import protocols mirror GSO frameworks but with extended registration timelines. Salmiya and Kuwait City's retail corridors remain dominated by mass-market supermarket distribution.
Bahrain
Manama's compact urban geography supports concentrated pet specialty retail serving affluent Saudi weekend visitors and resident expatriates. The national health regulator maintains streamlined import procedures for pre-registered products cleared through Saudi SFDA protocols. Seef Mall and City Centre anchor premium brand visibility with trained staff delivering breed-specific guidance.
GCC Dog Food Market Key Industry Players
Player mix skews toward multinational consumer packaged goods conglomerates with dedicated pet care divisions, creating a tiered structure where global brands control hypermarket shelf space and clinical nutrition channels. Three archetypes dominate: diversified food conglomerates leveraging cross-category procurement scale, specialized veterinary nutrition houses with prescription-tier positioning, and regional importers capturing subscription-driven urban demand. Competitive moves concentrate on veterinary channel exclusivity agreements and cold-chain infrastructure partnerships for raw format expansion.
Among diversified conglomerates, Mars Petcare and Nestlé Purina PetCare exemplify the scale-driven archetype through multi-brand portfolio breadth and hypermarket penetration. Hill's Pet Nutrition occupies a position within the clinical nutrition specialist tier, anchoring veterinary-anchored distribution with science-backed formulation credibility. Regional platforms including Petto Club and Raseen represent the emerging digital-native importer archetype, capturing recurring revenue through algorithmic replenishment models targeting Dubai and Abu Dhabi professional households.
| Leading Market Players |
|---|
| Mars Petcare |
| Nestlé Purina PetCare |
| Hill's Pet Nutrition |
| Del Monte Foods |
| Blue Buffalo Pet Products |
| Petto Club |
| Raseen |
| Bayt Al Aleefa |
| PURINA Arabia |
| Others |
Cost & Logistics Intelligence
SFDA labeling mandates and MOHAP veterinary endorsement protocols gate both supplier qualification timelines and price differentiation across the GCC dog food sector. These regulatory frameworks simultaneously filter substandard imports and stratify compliant products into premium clinical tiers unreachable by mass-market entrants.
Pricing Analysis
Format-generation pricing gaps separate extruded dry kibble from precision-fermented novel protein formulations and raw-frozen alternatives. Three-tier pricing structure across premium, standard, and economy levels anchors the market, with certification grade and veterinary channel access as primary price differentiation drivers. Pricing pressure stems from currency volatility affecting European and North American import costs. Mass-market Saudi households exhibit highest price sensitivity, while Dubai expatriate owners in veterinary-anchored channels show least elasticity.
Supply Chain Analysis
Inventory lead times for high-quality animal protein concentrates extend 12-18 weeks due to rendering facility bottlenecks with limited Gulf presence. Supply concentrates in Germany, the Netherlands, and the United States for finished formulations, with Thailand and New Zealand as secondary corridors for novel protein ingredients. Raw material dependencies center on poultry meal, fish hydrolysates, and single-cell proteins from precision fermentation. Single-source vulnerability runs through Rotterdam and Hamburg consolidation hubs for containerized shipments to Jeddah and Jebel Ali. Distribution runs through hypermarket chains for volume, veterinary clinic pharmacies for premium tiers, and Dubai-based subscription platforms for recurring replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC dog food market operates as a defensive-moat story where regulatory entrenchment through SFDA and MOHAP certification creates switching costs that lock veterinary channels and consolidate shelf access for compliant incumbents.
For Market Incumbents: Secure exclusive veterinary partnership agreements in Dubai Silicon Oasis and Riyadh's King Faisal Specialist Hospital precinct to preempt prescription-tier access for emerging competitors. Deepen backward integration into novel protein sourcing through precision fermentation pilot programs with European biotechnology suppliers, insulating margin from livestock rendering volatility. For New Entrants and Emerging Players: Lead with cold-chain infrastructure investment targeting raw and fresh-frozen distribution gaps in Abu Dhabi's Al Reem Island and Kuwait's Salmiya corridor, where temperature-controlled logistics deficiencies create whitespace. Penetrate Kuwait's underdeveloped veterinary channel before competitive positioning solidifies, deploying subscription-based algorithmic replenishment models proven in Dubai. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision fermentation ingredient sourcing and specialized last-mile refrigeration infrastructure. Long-term viability favors platforms combining digital-native customer acquisition with regulatory certification depth. Acquisition targets should demonstrate MOHAP endorsement pathways or SFDA compliance workflows. Monitor veterinary clinic pharmacy expansion rates as inflection signal for prescription-tier market share shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Exclusivity Agreement | Locks prescription-tier loyalty through MOHAP-endorsed clinical diet distribution in Dubai and Riyadh clinics. |
| Precision Fermentation Partnership | Reduces poultry meal dependency via single-cell protein sourcing from European biotechnology suppliers. |
| Cold-Chain Infrastructure Buildout | Enables raw-frozen segment viability through temperature-controlled last-mile distribution in Gulf heat. |
| Subscription Platform Integration | Captures recurring revenue via algorithmic portion sizing and automated delivery for urban professional households. |
| Regulatory Certification Acceleration | Compresses SFDA and MOHAP approval timelines through pre-submission third-party laboratory verification. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs import records, veterinary clinic procurement databases, and GCC Standardization Organization technical standards. Primary interviews engaged pet food importers, veterinary nutritionists, hypermarket category buyers, cold-chain logistics operators, and regulatory affairs specialists across Saudi Arabia and the United Arab Emirates. Secondary validation drew from SFDA registration filings, MOHAP endorsement protocols, European pet food export statistics, and subscription platform user analytics. Bottom-up demand modeling triangulated against top-down trade flow analysis.
Segmentation dimensions modeled include product format, ingredient composition, packaging type, and distribution channel across the projection horizon. The analytical framework incorporated expatriate household concentration, veterinary clinic density, and cold-chain infrastructure maturity as GCC-specific forecast inputs. CAGRs derived from trend extrapolation of premiumization rates and regulatory compliance cost trajectories.
Forecasts assume regulatory continuity in SFDA and MOHAP regimes; material policy shifts in labeling mandates or import protocols would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
North America Functional Pet Treat Market
Pet Care Products
Dog Safety Leash Market
Pet Care Products
US Pet Daycare Market
Pet Care Products
Plant-Based Pet Food Market
Pet Care Products
North America Pet Diet Market
Pet Care Products
South America Pet Diet Market
Pet Care Products
UK Pet Boarding Market
Pet Care Products
Japan Organic and Natural Pet Food Market
Pet Care Products
Outdoor Cat House Market
Pet Care Products
Organic and Natural Dog Foods Market
Pet Care Products
Saudi Arabia Dog Food Market
Pet Care Products
UAE Pet Boarding Market
Pet Care Products
Global Pet Stroller Market
Pet Care Products
Cat Litter Market
Pet Care Products
Japan Pet Food Market
Pet Care Products
Australia Pet Boarding Market