
 Frozen and Freeze-Dried Pet Food Market | 2026-2036
Frozen and Freeze-Dried Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen and Freeze-Dried Pet Food Market Intelligence
The EU Green Deal is rebalancing ingredient sourcing requirements across European supply chains, compelling manufacturers to document carbon footprints for meat inputs. Stella & Chewy's LLC leverages its Wisconsin production campus to sustain vertical integration from raw ingredient receiving through freeze-drying. Ziwi Peak anchors its position with air-dried and freeze-dried formats sourced entirely from New Zealand pastoral operations.
Frozen and freeze-dried pet food comprises minimally processed animal and plant ingredients preserved through sub-zero freezing or lyophilization to maintain cellular structure, enzymatic activity, and nutrient bioavailability without synthetic additives. Freeze-dried raw formats undergo primary freezing at minus 40 degrees Celsius followed by vacuum sublimation, yielding shelf-stable products that rehydrate to approximate fresh nutritional profiles. Raw frozen products dominate volume due to lower processing capital requirements, while freeze-dried cooked formats command premium positioning among immunocompromised pet populations. The dog end-user segment absorbs the majority of production capacity, though cat-specific freeze-dried fish formulations are gaining shelf space in specialty channels.
The FDA enforces zero-tolerance Salmonella standards under the Federal Food, Drug, and Cosmetic Act, requiring environmental monitoring and validated kill steps for raw pet food facilities. The USDA's Food Safety and Inspection Service oversees human-grade meat diversion into pet food streams, creating dual compliance obligations for manufacturers sourcing from slaughter establishments. AAFCO nutrient profiles and model feed regulations provide the baseline formulation standards adopted by most state feed control officials. Stakeholders must monitor evolving state-level raw pet food licensing requirements and determine whether captive freeze-drying capacity or toll processing partnerships better align with capital constraints and geographic market targets.
Market Dynamics
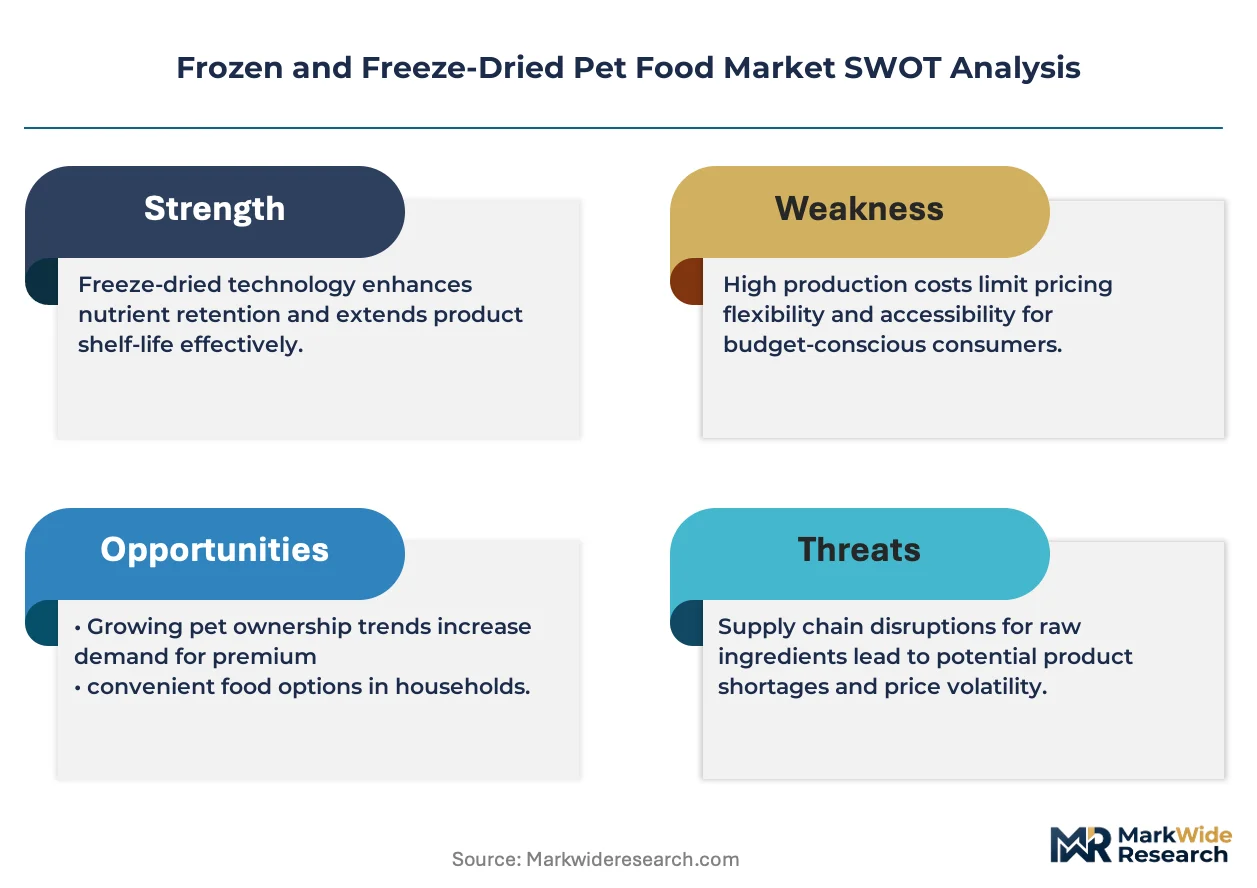
High-pressure processing (HPP) validation costs are compressing margins for raw pet food manufacturers while simultaneously erecting entry barriers against unvalidated competitors. The FDA's zero-tolerance Salmonella enforcement has transformed food safety infrastructure from a cost center into a strategic differentiator.
Growth Catalysts
- EU Green Deal carbon documentation:Mandatory footprint tracking for meat inputs is redirecting procurement toward verified low-emission suppliers, rewarding early adopters with preferential retail placement in European specialty channels.
- Urban millennial pet ownership:Dense metropolitan concentrations of companion animal households are sustaining subscription-based frozen delivery models that bypass traditional retail markup structures.
- Freeze-drying protocol advancement:Vacuum sublimation at minus 40 degrees Celsius now yields shelf-stable products that rehydrate to near-fresh nutritional profiles, expanding addressable markets beyond cold-chain limitations.
Market Restraints
- Dual USDA-FSIS and FDA compliance:Human-grade meat diversion into pet food streams creates overlapping inspection obligations that extend facility certification timelines and elevate fixed cost structures.
- Freeze-drying capital intensity:Lyophilization equipment and controlled-atmosphere infrastructure require substantial upfront investment, concentrating production capacity among established operators with captive financing access.
- Raw frozen cold-chain dependency:Sub-zero storage and transportation requirements limit distribution radius and elevate spoilage risk, constraining geographic expansion for pure-play frozen formats.
Strategic Opportunities
- Immunocompromised pet population:Freeze-dried cooked formats command premium positioning among veterinary-directed therapeutic nutrition segments currently underserved by conventional kibble alternatives.
- Cat-specific freeze-dried fish:Shelf-space expansion in specialty channels for feline formulations represents underexploited production capacity given current dog-centric capacity allocation.
- State-level raw pet food licensing harmonization:Emerging uniform standards across multiple jurisdictions would reduce regulatory fragmentation costs and enable interstate distribution scale economies.
Industry Challenges
- HPP technical talent scarcity:Validated kill-step engineering expertise remains concentrated among a limited pool of food safety specialists, constraining facility expansion timelines.
- AAFCO model regulation adoption variance:State-by-state divergence in feed control official interpretations creates formulation compliance complexity and extends product registration cycles.
- Environmental monitoring infrastructure:Continuous pathogen surveillance systems require sustained operational expenditure and specialized microbiological laboratory partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen and Freeze-Dried Pet Food Market |
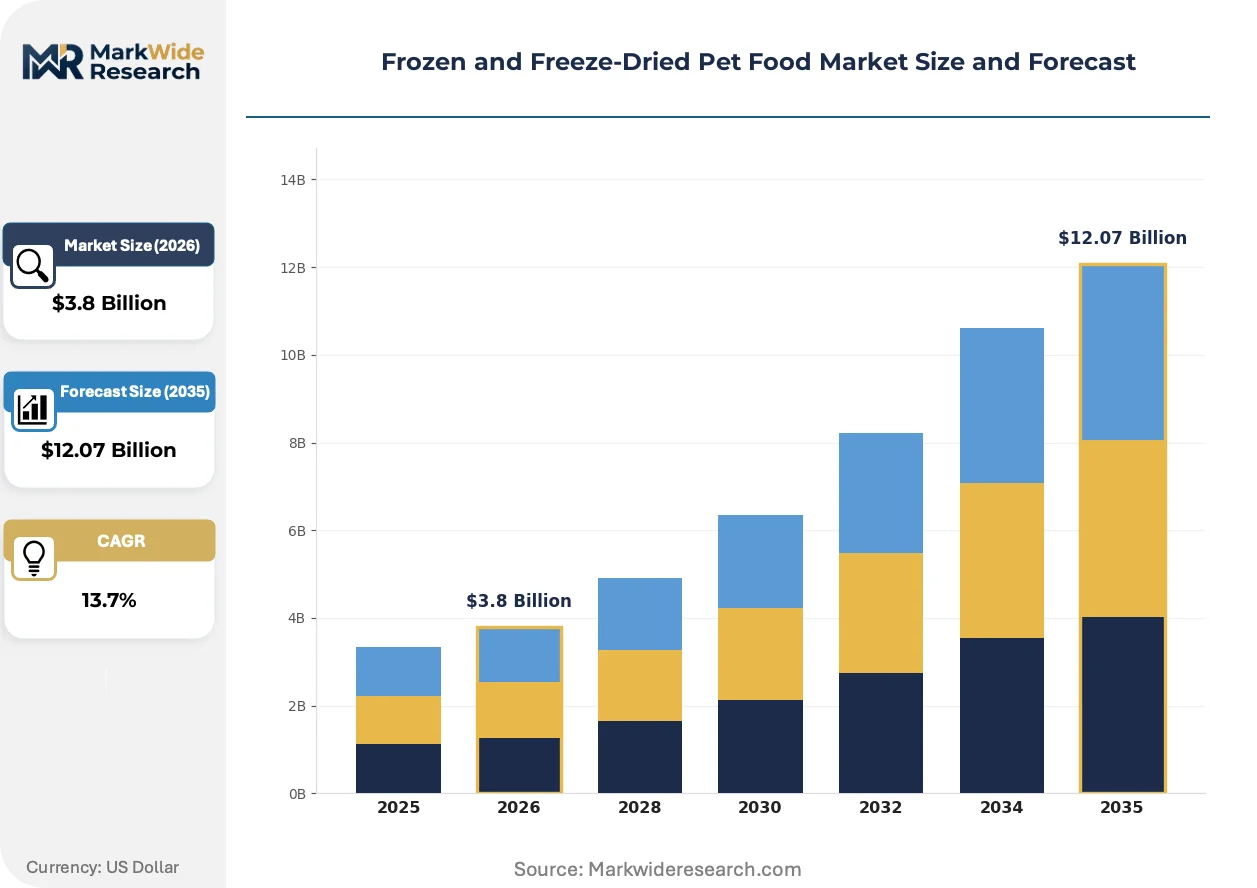
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.07 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Frozen, Freeze-Dried Raw, Freeze-Dried Cooked, Dehydrated Ingredient Type: Meat, Fish, Vegetables, Fruits End User: Dogs, Cats, Birds, Small Pets Packaging Type: Bags, Pouches, Cans, Boxes |
| Companies Covered | Merrick Pet Care, WellPet, Stella & Chewy's LLC, Northwest Naturals, Bravo Pet Foods, Primal Pet Foods Inc., Ziwi Peak, Grandma Lucy's, Mars Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen and Freeze-Dried Pet Food Market Strategic Shifts & Innovations
Processing technology convergence with veterinary nutrition science is redefining product categorization boundaries. Manufacturers now compete on bioavailability metrics rather than ingredient lists alone.
High-pressure processing equipment is modularizing across mid-scale production facilities, enabling batch-scale pathogen reduction without continuous-line capital commitment. Regional co-manufacturers in the United States are adopting HPP units to serve multiple brand clients under toll arrangements. This distributed processing architecture is compressing the minimum viable scale for validated raw pet food production.
The FDA's zero-tolerance Salmonella standard under the Federal Food, Drug, and Cosmetic Act is forcing environmental monitoring investments that favor integrated production campuses over fragmented supply chains. Facilities with in-house laboratory capabilities are capturing veterinary channel preference through documented lot-level safety verification. Raw frozen specialists face the steepest compliance cost escalation, accelerating format diversification toward freeze-dried alternatives.
Subscription-based direct delivery is displacing conventional retail stocking for frozen formats among urban millennial households. Specialty pet retail chains are responding with dedicated freezer sections and staff nutrition certification programs. This channel bifurcation is most visible in United States coastal metropolitan markets where cold-chain logistics density supports reliable fulfillment windows.
Frozen and Freeze-Dried Pet Food Market Segmentation
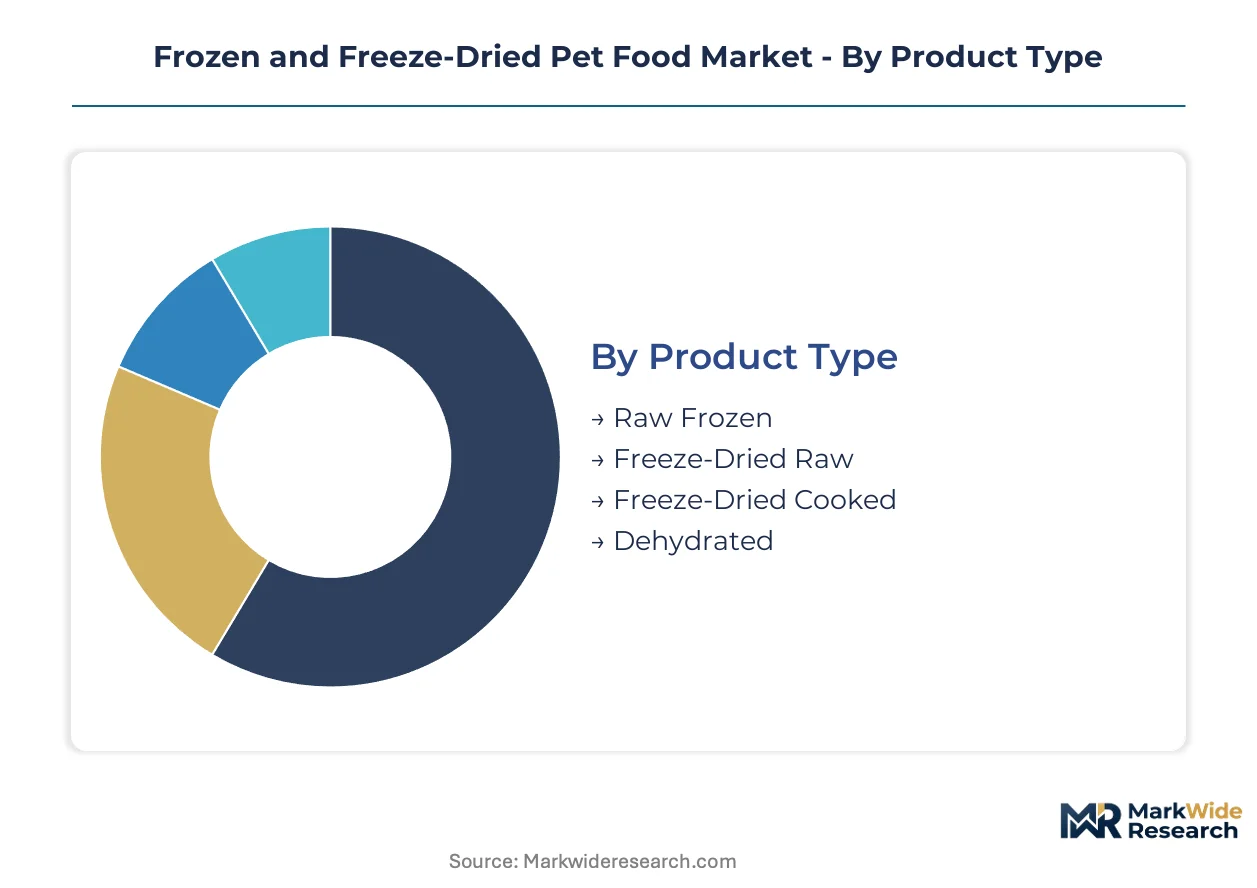
Segmentation in frozen and freeze-dried pet food reveals distinct supply chain configurations, processing capital requirements, and channel access patterns. Each category maps to different buyer priorities: food safety validation for raw formats, convenience for shelf-stable alternatives, and species-specific nutritional formulations for end-user targeting.
Product Type:
Buyers in this category trade between nutritional fidelity, storage logistics, and pathogen risk tolerance.
- Raw Frozen:Minimally processed animal tissue preserved at sub-zero temperatures maintains enzymatic activity and cellular structure without thermal degradation. Demand concentrates in United States metropolitan corridors where subscription cold-chain delivery has achieved logistical density; FDA zero-tolerance Salmonella enforcement elevates facility compliance costs as a barrier to new entrants. Volume sits with Raw Frozen; growth tilts toward Freeze-Dried Raw.
- Freeze-Dried Raw:Vacuum sublimation at minus 40 degrees Celsius removes moisture while preserving raw nutritional profiles, yielding shelf-stable products that rehydrate to approximate fresh states. Urban millennial households in coastal United States cities drive adoption through direct-to-consumer channels that bypass conventional retail freezer dependency.
- Freeze-Dried Cooked:Thermal processing prior to lyophilization eliminates pathogen risk for immunocompromised pet populations. Veterinary-directed therapeutic nutrition segments absorb premium pricing.
- Dehydrated:Low-temperature air removal achieves preservation without freeze-drying capital intensity. Mid-market positioning serves price-sensitive buyers seeking minimally processed alternatives.
Freeze-dried formats are gaining share fastest as cold-chain limitations constrain raw frozen geographic expansion.
Ingredient Type:
Procurement patterns in this category track carbon documentation requirements and species-specific nutritional science.
- Meat:Bovine, ovine, and porcine muscle tissue dominates volume throughput due to protein density and palatability. EU Green Deal carbon footprint tracking is redirecting European procurement toward verified low-emission suppliers.
- Fish:Marine and freshwater species provide omega-3 fatty acid profiles for coat and cognitive health. Cat-specific freeze-dried fish formulations are expanding shelf space in specialty United States retail channels.
- Vegetables:Root and leafy additions supply fiber and micronutrients in plant-inclusive formulations. Sweet potato and pumpkin feature prominently in digestive health positioning.
- Fruits:Berry and apple inclusions deliver antioxidant marketing claims. Low inclusion rates limit procurement scale relative to protein inputs.
Meat commands absolute volume; fish climbs fastest on feline segment expansion.
End User:
Species-specific digestive physiology and feeding behavior shape formulation complexity and packaging requirements.
- Dogs:Omnivorous capacity enables diverse ingredient inclusion from raw meat to vegetable matter. United States direct-to-consumer subscription services and specialty retail chains have built dense distribution networks around canine-centric production capacity.
- Cats:Obligate carnivore metabolism demands high protein density and taurine supplementation. Freeze-dried fish and poultry formats are gaining shelf space in specialty channels as manufacturers reallocate capacity from dog-dominant production.
- Birds:Seed and pellet alternatives in freeze-dried formats address companion parrot and songbird nutrition. Niche volume limits dedicated production lines.
- Small Pets:Rabbit, guinea pig, and rodent formulations require fiber-forward profiles distinct from carnivore-optimized products. Veterinary exotic animal practices drive prescription channel placement.
Dogs absorb majority capacity; cats represent the steepest expansion trajectory on underexploited freeze-dried fish capacity.
Packaging Type:
Material selection balances oxygen barrier performance, cold-chain compatibility, and retail presentation requirements.
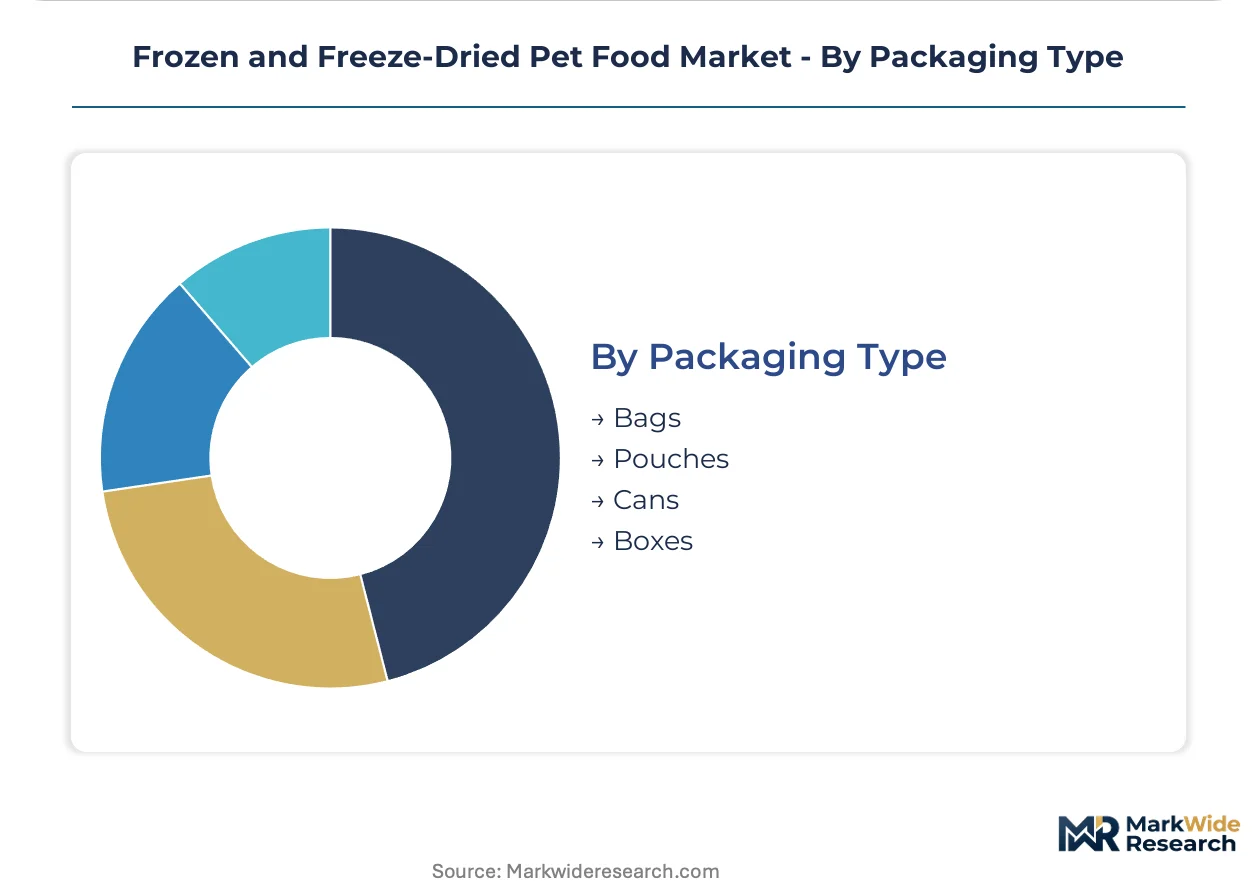
- Bags:Multi-layer polymer structures with oxygen scavengers protect freeze-dried products from moisture reabsorption. Stand-up pouch configurations dominate specialty retail shelf placement.
- Pouches:Flexible formats reduce shipping cube and enable portion-controlled resealing. Subscription services favor pouches for delivery density.
- Cans:Metal containers serve frozen raw formats requiring structural integrity at sub-zero temperatures. Retail freezer display compatibility drives specification.
- Boxes:Corrugated outer shells with insulated liners protect frozen shipments in direct-to-consumer fulfillment. United States coastal metropolitan markets with reliable cold-chain logistics support box-format subscription scale.
Bags and pouches split freeze-dried volume; cans and boxes anchor frozen distribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Milwaukee anchors North American freeze-drying capacity through vertically integrated production campuses serving subscription distribution channels. Dense urban pet ownership clusters in coastal metropolitan corridors sustain cold-chain logistics networks that bypass traditional retail infrastructure.
United States
Urban millennial households in Boston, New York, and Seattle drive subscription-based frozen delivery models that circumvent conventional retail markups. FDA zero-tolerance Salmonella enforcement under the Federal Food, Drug, and Cosmetic Act elevates environmental monitoring costs for raw pet food facilities. Wisconsin production campuses concentrate freeze-drying infrastructure with captive laboratory capabilities for lot-level safety verification.
Germany
EU Green Deal carbon documentation requirements redirect procurement toward verified low-emission meat suppliers across Bavaria and North Rhine-Westphalia. EFSA guidelines on raw pet food safety create compliance obligations overlapping with national feed control interpretations. Berlin-Brandenburg specialty retail chains are expanding dedicated freezer sections with staff nutrition certification programs.
United Kingdom
London and Southeast England metropolitan corridors sustain direct-to-consumer frozen pet food subscription density comparable to US coastal markets. UK Food Standards Agency enforcement on raw pet food pathogens mirrors FDA stringency, compressing margins for unvalidated producers. Midlands distribution hubs are consolidating cold-chain infrastructure to serve northern England and Scotland expansion.
France
Île-de-France and Auvergne-Rhône-Alpes concentrate demand for minimally processed companion animal nutrition among urban professional households. ANSM oversight of veterinary therapeutic nutrition creates regulatory pathways for freeze-dried cooked formats targeting immunocompromised pets. Lyon-area specialty pet retail clusters are gaining shelf space for cat-specific freeze-dried fish formulations.
Japan
Kanto and Tokyo metropolitan areas absorb premium freeze-dried imports from New Zealand and US West Coast suppliers. METI guidance on pet food safety standards emphasizes documented kill-step validation for raw-derived products. Osaka-Kansai veterinary channel partnerships are expanding for therapeutic nutrition segments underserved by conventional kibble alternatives.
Frozen and Freeze-Dried Pet Food Market Key Industry Players
The competitive structure tilts toward vertically integrated specialists with captive freeze-drying capacity and validated pathogen control infrastructure. Mid-scale regional operators rely on toll processing partnerships to access high-pressure processing equipment without continuous-line capital commitment. Two strategic archetypes dominate: Wisconsin-based production campus operators with backward integration into raw ingredient sourcing, and New Zealand-sourced air-dried specialists leveraging pastoral supply chains. Capacity expansion and portfolio diversification toward cat-specific formulations represent the dominant competitive moves across both archetypes.
Within the vertically integrated specialist tier, Stella & Chewy's LLC and Ziwi Peak exemplify divergent sourcing strategies anchoring premium positioning. Wisconsin-based Stella & Chewy's LLC occupies a position representing North American captive production campus models, while New Zealand-sourced Ziwi Peak anchors air-dried and freeze-dried formats from pastoral operations. Mars Inc. sits within the diversified conglomerate archetype, leveraging existing pet food infrastructure across multiple format categories. These three players collectively illustrate the spectrum from single-format specialization to portfolio breadth across frozen, freeze-dried, and conventional nutrition segments.
| Leading Market Players |
|---|
| Merrick Pet Care |
| WellPet |
| Stella & Chewy's LLC |
| Northwest Naturals |
| Bravo Pet Foods |
| Primal Pet Foods Inc. |
| Ziwi Peak |
| Grandma Lucy's |
| Mars Inc. |
| Others |
Cost & Logistics Intelligence
Urban millennial subscription preferences for direct-to-consumer frozen delivery are compressing traditional retail markups and forcing manufacturers to absorb cold-chain logistics costs within pricing structures. This demand-side pressure elevates freeze-dried formats that bypass freezer dependency while concentrating supply chain investments in Wisconsin production campuses with captive laboratory capabilities.
Pricing Analysis
Outcome-based pricing anchored to nutritional bioavailability metrics and documented pathogen safety separates premium freeze-dried formats from commodity alternatives. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with FDA-validated HPP protocols commanding substantial premiums. Pricing pressure stems from dual USDA-FSIS and FDA compliance obligations extending facility certification timelines. Raw frozen formats face acute price sensitivity among metropolitan subscription households, while freeze-dried cooked products absorb premium positioning among veterinary-directed buyers.
Supply Chain Analysis
Single-source vulnerability sits with New Zealand pastoral operations anchoring air-dried and freeze-dried ingredient flows for premium positioning. Manufacturing concentration clusters in the United States, New Zealand, and Germany, with Wisconsin production campuses and Bavarian distribution hubs serving regional demand. Raw material dependencies center on bovine muscle tissue, marine fish species, and vacuum sublimation equipment. Tariff exposure on New Zealand-sourced inputs threatens margin structures for pastoral-dependent brands. Distribution runs through direct-to-consumer subscription channels and specialty pet retail chains with dedicated freezer infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The frozen and freeze-dried pet food sector is transitioning from raw frozen cold-chain dependency toward shelf-stable freeze-dried formats, with vacuum sublimation at minus 40 degrees Celsius displacing conventional freezing infrastructure.
For Market Incumbents: Deepen backward integration into raw ingredient sourcing through Wisconsin production campus expansion, securing captive supply of human-grade meat streams against USDA-FSIS diversion competition. Invest in modular HPP equipment across mid-scale facilities to validate kill-step protocols before FDA enforcement escalates. Channel control through veterinary-direct relationships protects premium positioning against emerging freeze-dried specialists. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the most penetrable route for cat-specific freeze-dried fish formulations, exploiting underexploited production capacity currently allocated to dog-centric output. Target immunocompromised pet therapeutic nutrition segments where veterinary prescription channels remain underserved by conventional kibble alternatives. White-space expansion into state-level raw pet food licensing harmonization reduces regulatory fragmentation costs for interstate scale. For Investors and Strategic Acquirers: The window for entry favors vertically integrated specialists with captive freeze-drying capacity and validated pathogen control infrastructure over toll-dependent regional operators. Long-term viability across the analysis window rests on backward integration depth and laboratory-verified lot-level safety documentation. Monitor FDA zero-tolerance Salmonella enforcement intensity as the primary inflection signal for raw frozen margin compression accelerating format diversification.| Strategic Initiative | Industry Significance |
|---|---|
| Freeze-Drying Capacity Expansion | Captive lyophilization infrastructure at Wisconsin campuses reduces toll-processing dependency and accelerates lot-level safety verification. |
| Direct-to-Consumer Channel Development | Subscription platforms bypass specialty retail freezer markup structures and capture urban millennial household data for personalization. |
| Cat-Specific Formulation Diversification | Freeze-dried fish and poultry formats exploit underutilized production lines currently dominated by dog-centric capacity allocation. |
| HPP Validation Investment | FDA-compliant kill-step documentation transforms food safety infrastructure from cost center into veterinary channel preference driver. |
| EU Green Deal Compliance Positioning | Carbon footprint documentation for meat inputs secures preferential placement in European specialty retail channels. |
Research Approach
Trade databases, regulatory filings, and specialty pet retail audit data formed the secondary backbone, supplemented by primary interviews with freeze-drying equipment engineers, veterinary nutrition specialists, cold-chain logistics coordinators, and specialty pet retail category buyers. Bottom-up triangulation across product-format volume estimates and top-down validation against aggregate category expenditure produced convergent market sizing. SEC filings from diversified pet food conglomerates and FDA enforcement action records provided compliance cost benchmarks.
Historical trendline analysis across raw frozen and freeze-dried format trajectories informed projection modeling throughout the forecast period. Segmentation dimensions included product type, ingredient category, end-user species, and packaging format, with geographic regulatory cluster as an industry-specific overlay. CAGRs were derived from fitted growth curves adjusted for cold-chain logistics density and subscription penetration rates in metropolitan corridors.
The model holds under sustained FDA zero-tolerance enforcement and stable cold-chain infrastructure investment; deviation in EU Green Deal carbon documentation stringency or HPP equipment supply constraints would shift format adoption timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
US Pet Daycare Market
Pet Care Products
High Protein Dog Food Market
Pet Care Products
Global Flea and Tick Product Market
Pet Care Products
North America Dog Food Market
Pet Care Products
Pet Slow Feeder Bowl Market
Pet Care Products
Weight Management Dog Food Market
Pet Care Products
Pet Tag Market
Pet Care Products
Dog Bed Covers Market
Pet Care Products
Disposable Absorbent Pet Pad Market
Pet Care Products
Pet Grooming Market
Pet Care Products
Pet Clean-Up and Odor-Control Products Market
Pet Care Products
China Pet Training Services Market
Pet Care Products
UK Dog Food Market
Pet Care Products
Modern Cat Furniture Market
Pet Care Products
Automatic and Smart Pet Feeder Market
Pet Care Products
Pet Hair Care Market