
 Canada Pet Food Market | 2026-2036
Canada Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Pet Food Market Analysis
Ontario is tilting toward expanded pet food manufacturing capacity as domestic consumption outpaces legacy supply infrastructure. Mars Incorporated leverages its integrated nutrition science platform to sustain formulation leadership across therapeutic and lifestyle diets. Nestlé (Purina) anchors volume through veterinary channel partnerships and private label adjacent positioning. Petcurean Pet Nutrition Inc. differentiates through region-specific protein sourcing and smaller-batch production protocols.
Canada pet food encompasses nutritionally complete and complementary formulations for domestic companion animals, manufactured through extrusion, retorting, or cold-pressing processes with controlled moisture content, protein digestibility coefficients, and shelf-stable packaging barriers. Its commercial purpose centers on delivering species-appropriate macronutrient profiles that substitute or supplement homemade feeding regimens. Dry food occupies the dominant volume position due to logistics efficiency and extended shelf stability, while freeze-dried formats command disproportionate margin pools through ingredient transparency narratives. Wet food competes on palatability and hydration support, particularly in feline formulations where urinary health positioning drives veterinarian recommendations.
Health Canada enforces the Feed Act and Safe Food for Canadians Regulations, mandating facility licensing, ingredient traceability, and nutritional adequacy verification that elevates compliance costs for new entrants. The Canadian Food Inspection Agency conducts border inspections and label audits that restrict cross-border product flows failing bilingual packaging or guaranteed analysis standards. Stakeholders must monitor evolving AAFCO nutrient profile harmonization pressures and provincial extended producer responsibility packaging mandates that could reshape cost structures.
Market Dynamics
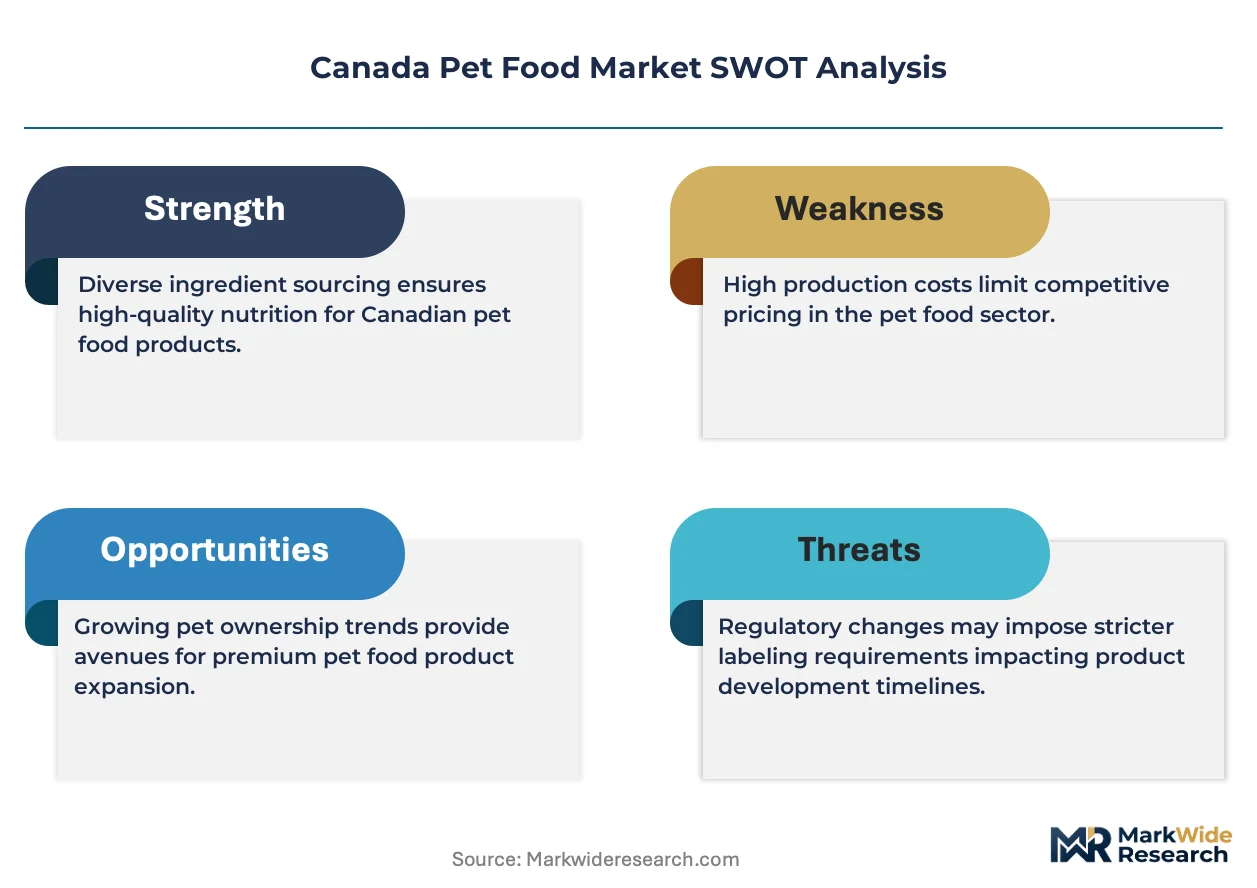
Pet humanization is compressing product development cycles as Canadian manufacturers race to match human-grade ingredient standards demanded by urban millennial households. Health Canada's Feed Act enforcement and the Canadian Food Inspection Agency's bilingual labeling mandates are elevating compliance thresholds that favor scaled operators with dedicated regulatory affairs functions.
Growth Catalysts
- Ontario manufacturing expansion:Provincial feed facility licensing reforms are accelerating production capacity additions to match domestic consumption growth.
- Safe Food for Canadians Regulations:Mandatory ingredient traceability systems are building consumer trust premiums that sustain price realization power.
- Cold-pressed protein retention:Lower-temperature processing protocols are preserving amino acid bioavailability that drives veterinary endorsement.
Market Restraints
- Atlantic salmon meal price volatility:British Columbia aquaculture supply disruptions are transmitting cost pressure through premium formulations.
- Quebec rendering facility concentration:Three provincial suppliers control the majority of animal protein meal inputs, creating single-source vulnerability.
- CFIA border inspection backlogs:Cross-border ingredient shipments face extended quarantine holds that compress formulation flexibility.
Strategic Opportunities
- Alberta prairie bison sourcing:Underexploited provincial protein supply chains offer traceability narratives that command shelf price premiums.
- Veterinary telehealth integration:Remote prescription diet authorization is opening direct-to-consumer channels bypassing traditional retail markup structures.
- Extended producer responsibility mandates:Provincial packaging recycling targets are creating first-mover advantages for mono-material pouch adopters.
Industry Challenges
- Veterinary nutritionist talent scarcity:Board-certified companion animal nutrition specialists command compensation premiums that strain mid-tier R&D budgets.
- Extrusion line retooling cycles:Legacy thermal processing equipment requires capital-intensive upgrades to achieve human-grade facility certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Pet Food Market |
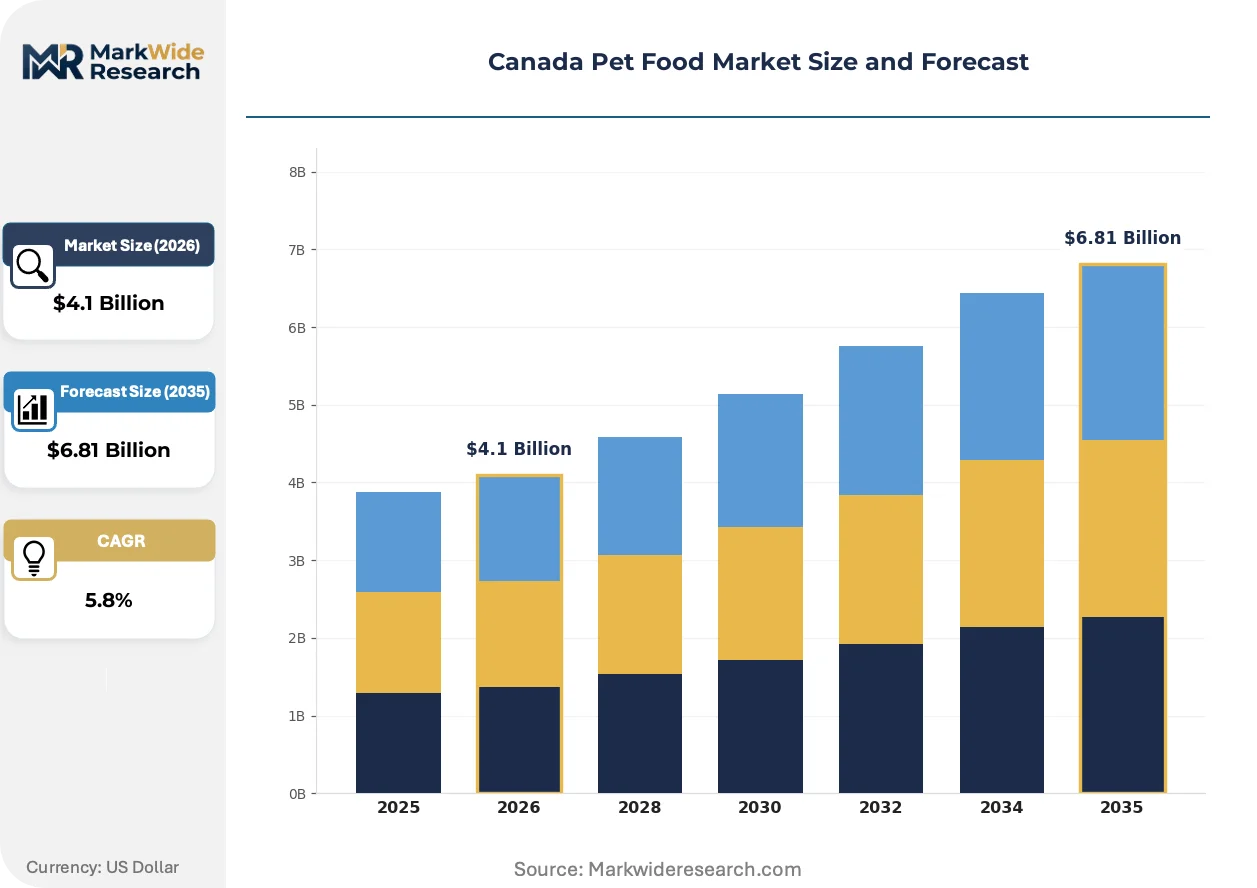
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Freeze-Dried Animal Type: Dogs, Cats, Fish, Birds Sales Channel: Online, Supermarkets, Specialty Stores, Veterinary Clinics Ingredient Quality: Natural, Organic, Grain-Free, Premium |
| Companies Covered | General Mills Inc., Schell & Kampeter Inc. (Diamond Pet Foods), Mars Incorporated, Spectrum Brands Inc., Clearlake Capital Group, L.P. (Wellness Pet Company Inc.), Nestlé (Purina), The J. M. Smucker Company, Petcurean Pet Nutrition Inc., Colgate-Palmolive Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Pet Food Market Emerging Trajectories
Formulation science is converging with digital traceability infrastructure to create ingredient-verified product architectures that command sustained price premiums. Three interconnected developments are restructuring competitive capabilities across the value chain.
High-pressure processing is hybridizing raw nutrition preservation with pathogen elimination safety margins that previously required thermal degradation. Premium freeze-dried raw manufacturers are adopting HPP tunnel systems at pilot scale, compressing the safety-versus-nutrition tradeoff that historically segmented the market. This convergence is enabling shelf-stable raw formats to displace frozen distribution dependencies.
Health Canada's Feed Act amendment consultations are signaling tightened veterinary health claim substantiation requirements that will reshape label architecture. The proposed regulatory language targets functional ingredient callouts that currently occupy front-panel positioning, forcing reformulation toward compositional superiority claims. Therapeutic diet manufacturers are pre-positioning clinical trial investments to defend prescription channel access.
Subscription-based replenishment is displacing episodic retail purchasing among multi-pet households in Vancouver and Toronto metropolitan corridors. Automated delivery platforms are capturing recurring revenue streams that reduce customer acquisition cost burdens for emerging brands. This channel migration concentrates most visibly among feline owners managing chronic urinary health conditions requiring consistent formulation adherence.
Canada Pet Food Market Segmentation
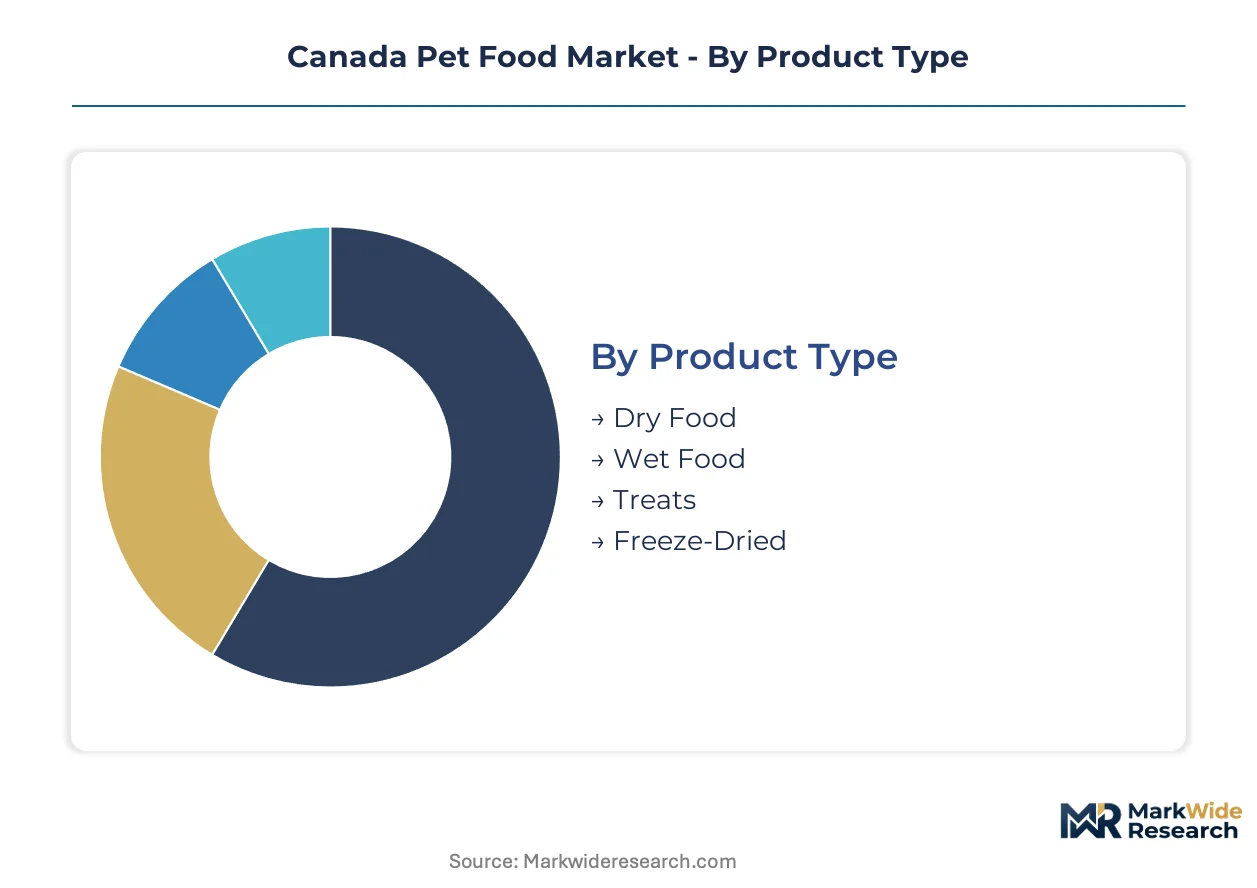
Pet food segmentation in Canada tracks purchasing velocity differences across household types. Urban millennial buyers cycle through premium formats faster than rural households stocking value-positioned dry food. Understanding these turnover patterns shapes inventory deployment and margin capture strategies.
Product Type:
Dry food turns over slowest due to bulk purchasing and extended shelf stability, while freeze-dried formats rotate fastest through specialty retail channels. Wet food occupies the middle velocity tier with predictable replenishment cycles tied to feeding schedules.
- Dry Food:Extruded kibble formulations with moisture content below 10% achieve logistics efficiency through ambient storage and extended shelf life. Demand concentrates in suburban Ontario households with multiple large-breed dogs where volume purchasing dominates. Health Canada's Feed Act labeling requirements for guaranteed analysis panels create compliance scale advantages for established manufacturers.
- Freeze-Dried:Low-temperature dehydration preserves raw protein structures without frozen distribution infrastructure. Vancouver and Toronto metropolitan corridors drive adoption among single-pet households seeking human-grade ingredient transparency. Cold-pressed alternatives compete on price while HPP-treated formats challenge on safety credentials.
- Wet Food:Retorted cans and pouches with 75-85% moisture content address feline hydration requirements and palatability preferences.
- Treats:Functional and indulgent formats with compressed feeding occasions and impulse purchase dynamics.
Dry food dominates installed base. Freeze-dried is where expansion concentrates.
Animal Type:
Canine formulations generate the highest absolute volume, yet feline nutrition commands disproportionate margin capture through veterinary-channel positioning. Avian and aquatic segments serve narrow hobbyist demographics with specialized distribution requirements.
- Dogs:Formulations span size-specific life-stage nutrition with therapeutic diet authorization through veterinary partnerships. Ontario and British Columbia households drive premiumization through humanization spending patterns.
- Cats:Obligate carnivore protein requirements and urinary health positioning create prescription diet dependencies. Vancouver metropolitan demand concentrates among apartment-dwelling owners seeking odor-control and hairball management solutions.
- Fish:Species-specific flake and pellet formats for ornamental aquarium maintenance.
- Birds:Seed blends and formulated diets for companion parrot and songbird species.
Canine nutrition anchors revenue scale. Feline therapeutic diets generate the steepest expansion trajectory.
Sales Channel:
Channel selection determines price realization and customer acquisition economics. Veterinary clinics sustain the highest margin structure through prescription authorization, while supermarkets compete on volume throughput with compressed per-unit economics.
- Veterinary Clinics:Prescription diet authorization creates captive demand with limited price elasticity. Toronto and Calgary metropolitan practice networks consolidate therapeutic nutrition recommendations.
- Online:Subscription replenishment platforms capture recurring revenue with reduced customer acquisition costs. Direct-to-consumer brands bypass retail markup structures through automated delivery scheduling.
- Supermarkets:Mass-market dry food placement with high-velocity turnover and promotional pricing pressure.
- Specialty Stores:Independent retailers curating premium and niche formulations with consultative service positioning.
Veterinary clinics defend margin structure. Online subscription models are climbing the fastest.
Ingredient Quality:
Quality tier selection correlates with household income geography and pet humanization intensity. Grain-free positioning has retreated from peak penetration amid veterinary cardiovascular concerns, while organic certification commands sustained price premiums.
- Premium:Human-grade ingredient specifications with named protein sources and excluded by-product declarations. British Columbia households demonstrate highest willingness-to-pay for transparent supply chain narratives.
- Natural:Minimal processing claims with preservative-free positioning and recognizable ingredient panels. Quebec regulatory scrutiny on natural claim substantiation elevates compliance documentation requirements.
- Organic:Certified organic ingredient sourcing with supply chain verification and price premiums reflecting input costs.
- Grain-Free:Carbohydrate substitution with legume and pulse alternatives facing veterinary scrutiny on dilated cardiomyopathy associations.
Premium positioning holds installed base concentration. Natural formulations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Health Canada anchors regulatory oversight across provincial markets where pet humanization intensity varies by urban density and household income distribution.
Ontario
Toronto and Ottawa metropolitan corridors drive premium format adoption through millennial household concentration. The province's feed facility licensing reforms under Health Canada oversight are accelerating manufacturing capacity additions. Guelph-Waterloo hosts expanding production clusters where extrusion line upgrades target human-grade certification standards.
British Columbia
Vancouver's apartment-dwelling pet owners generate concentrated demand for feline urinary health formulations and odor-control positioning. CFIA bilingual labeling enforcement at Pacific border crossings filters cross-border product flows. Lower Mainland distribution hubs are integrating cold-pressed and freeze-dried formats into specialty retail networks.
Alberta
Calgary and Edmonton households demonstrate rising willingness-to-pay for traceable protein sourcing narratives. Provincial prairie bison supply chains remain underexploited relative to premium positioning potential. Lethbridge rendering infrastructure supports regional formulation flexibility amid Quebec supplier concentration risks.
Quebec
Montreal's veterinary practice networks consolidate therapeutic diet recommendations with limited price elasticity. The province's rendering facility concentration creates single-source vulnerability for animal protein meal inputs. CFIA label audits in both official languages elevate compliance documentation requirements for market access.
Canada Pet Food Market Vendor Landscape
Capability concentration sits with mid-tier specialists; scale advantage sits with multinational nutrition platforms. The vendor base stratifies across three tiers: integrated consumer goods conglomerates with veterinary channel anchoring, regional specialists with province-specific protein sourcing relationships, and emerging direct-to-consumer brands leveraging subscription replenishment infrastructure. Dominant competitive moves include capacity expansion in Ontario manufacturing corridors and portfolio diversification toward freeze-dried and cold-pressed format hybrids.
Within the multinational tier, Mars Incorporated and Nestlé (Purina) exemplify scale-driven positioning through integrated nutrition science platforms and veterinary partnership networks. Petcurean Pet Nutrition Inc. occupies a specialist position among Canadian-origin operators with smaller-batch production protocols and region-specific ingredient traceability narratives.
| Leading Market Players |
|---|
| General Mills Inc. |
| Schell & Kampeter Inc. (Diamond Pet Foods) |
| Mars Incorporated |
| Spectrum Brands Inc. |
| Clearlake Capital Group, L.P. (Wellness Pet Company Inc.) |
| Nestlé (Purina) |
| The J. M. Smucker Company |
| Petcurean Pet Nutrition Inc. |
| Colgate-Palmolive Company |
| Others |
Supply Flow & Price Mechanics
The Trans-Canada Highway freight corridor carries Atlantic salmon meal shipments from British Columbia aquaculture operations to Ontario extrusion facilities, with fuel surcharge volatility transmitting directly into premium formulation cost structures and compressing margin pools for mid-tier producers unable to pass through logistics inflation.
Pricing Analysis
Ontario and British Columbia households face the widest price spreads, with Vancouver specialty retailers commanding shelf price premiums that Toronto supermarkets cannot sustain. Three-tier pricing structure across premium, standard, and economy levels stratifies by ingredient transparency grade and veterinary endorsement intensity. Pricing pressure stems from Quebec rendering facility concentration that limits animal protein meal sourcing alternatives. Rural multi-pet households in Alberta exhibit highest price sensitivity, while single-pet urban millennials in Vancouver demonstrate lowest elasticity.
Supply Chain Analysis
Tariff exposure between Canada and the United States dominates cross-border ingredient shipment economics, with CFIA bilingual labeling enforcement creating non-tariff barriers that extend quarantine holds. Supply concentrates in Quebec rendering infrastructure, British Columbia aquaculture operations, and Alberta prairie protein networks. Raw material dependencies include Atlantic salmon meal, prairie bison protein, and rendered poultry by-products. Single-source vulnerability in Quebec animal protein meal inputs creates systemic concentration risk. Distribution runs through veterinary clinic networks, specialty retail channels, and subscription-based direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Board-certified veterinary nutritionist scarcity constrains formulation innovation velocity, leaving mid-tier R&D budgets uncompetitive against multinational nutrition science platforms with captive specialist talent pipelines.
For Market Incumbents: Harden regulatory affairs capabilities against Health Canada's Feed Act amendment consultations targeting veterinary health claim substantiation requirements. Deepen backward integration into Alberta prairie bison supply chains to secure traceability narratives that defend shelf price premiums. Extrusion line human-grade certification investments will widen the compliance gap that strains emerging competitor capital structures. For New Entrants and Emerging Players: Mid-market freeze-dried formats in Calgary and Edmonton metropolitan corridors represent the most penetrable entry point, with underexploited prairie protein sourcing relationships offering differentiation against coastal supply chain incumbents. Subscription-based replenishment infrastructure for feline urinary health formulations opens direct-to-consumer channels that bypass veterinary clinic markup structures and capture recurring revenue with compressed customer acquisition economics. For Investors and Strategic Acquirers: Smaller-batch production specialists with region-specific protein traceability infrastructure and existing Health Canada facility licensing offer the strongest acquisition target archetype for portfolio diversification into premium pet nutrition. Long-term viability hinges on defensible regulatory compliance capabilities and captive ingredient sourcing relationships that sustain margin structure against multinational scale advantages. The signal to watch is CFIA enforcement intensity on bilingual labeling and veterinary health claim substantiation, which will accelerate consolidation toward scaled operators with dedicated compliance functions.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Pressed Format Expansion | Lower-temperature processing preserves amino acid bioavailability that drives veterinary endorsement and price premiums. |
| Alberta Bison Supply Chain Integration | Underexploited provincial protein networks offer traceability narratives that command shelf price premiums against coastal competitors. |
| Veterinary Telehealth Platform Partnership | Remote prescription diet authorization opens direct-to-consumer channels bypassing traditional retail markup structures. |
| Extended Producer Responsibility Compliance | Provincial packaging recycling targets create first-mover advantages for mono-material pouch adopters in specialty retail. |
| High-Pressure Processing Pilot Investment | HPP tunnel systems enable shelf-stable raw formats that displace frozen distribution dependencies and capture premium positioning. |
Methodological Framework
Initial hypotheses were tested against primary input from pet food formulation scientists, veterinary clinic procurement managers, specialty retail category buyers, and Health Canada regulatory affairs specialists and refined through secondary validation against CFIA enforcement bulletins, AAFCO nutrient profile documentation, provincial extended producer responsibility mandate filings, and Nielsen retail audit data across Canadian metropolitan corridors. Bottom-up demand modeling from household pet ownership surveys and veterinary prescription diet authorization rates was triangulated against top-down capacity assessments from feed facility licensing records.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, animal species, sales channel, and ingredient quality tier. CAGRs were derived from regression analysis of historical pricing and volume trajectories, incorporating industry-specific inputs including extrusion line capacity utilization rates and cold-pressed format adoption curves in Vancouver and Toronto metropolitan markets.
Practitioners should monitor Health Canada Feed Act amendment consultations, CFIA bilingual labeling enforcement intensity, and Atlantic salmon meal price volatility for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Plant-Based Pet Food Market
Pet Care Products
Pet Meal Kit Delivery Services Market
Pet Care Products
Canned Wet Cat Food Market
Pet Care Products
Canned Dog Food Market
Pet Care Products
Cat Bed Market
Pet Care Products
Outdoor Cat Houses and Furniture Market
Pet Care Products
US Pet Food Market
Pet Care Products
Inflatable Pet Collars Market
Pet Care Products
UK Pet Training Services Market
Pet Care Products
Dog Food Market
Pet Care Products
Bird Toy Market
Pet Care Products
Australia Pet Boarding Market
Pet Care Products
Indonesia Pet Care Market
Pet Care Products
Europe Pet Smart Tracker Market
Pet Care Products
Animal Bedding Products Market
Pet Care Products
Parrot Cage Market