
 Smart Cat Eye Market | 2026-2036
Smart Cat Eye Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Cat Eye Market Insights
Modular sensor-lighting bundles is pivoting buyer choice away from standalone reflective markers toward integrated smart cat eye systems with embedded connectivity. Xiaomi leverages its consumer electronics ecosystem to anchor distribution in Asia-Pacific smart city tenders. Kaadas specializes in precision optical components that differentiate its offerings for high-speed roadway applications. Philips sustains brand strength across European municipal procurement channels through established lighting infrastructure relationships.
A smart cat eye is an intelligent road marker incorporating photovoltaic cells, LED emitters, and wireless communication modules to transmit real-time traffic and environmental data to central management platforms. These devices typically operate at wavelengths between 590 and 620 nanometers for optimal visibility, with embedded piezoelectric or radar sensors detecting vehicle presence and velocity. Wi-Fi Connectivity and Sensor Technology segments lead current deployment volumes, while Solar-Powered configurations represent the fastest-growing category as municipalities seek off-grid infrastructure resilience. Advanced Lighting commands premium positioning due to integrated AI-driven adaptive brightness protocols, whereas Reflective Cat Eyes remain a mature, cost-driven segment with thinning margins.
FCC certification requirements govern wireless transmission protocols for US deployments, while CE marking and RoHS compliance shape European market access for electronic road safety equipment. India's BIS standards and China's GB certification frameworks further fragment regulatory entry pathways, compelling manufacturers to maintain multi-jurisdiction testing capabilities. Stakeholders must monitor evolving electromagnetic compatibility mandates and cybersecurity standards for connected infrastructure as regulatory scope expands beyond physical durability to data governance protocols.
Market Dynamics
Municipal procurement cycles are compressing as India's Ministry of Road Transport and Highways mandates intelligent traffic management upgrades, forcing vendors to reconfigure supply chains for accelerated deployment timelines.
Growth Catalysts
- India's BIS Standards:Certification frameworks for electronic road safety equipment create predictable compliance pathways, reducing market entry friction for qualified manufacturers.
- Photovoltaic Cell Efficiency Gains:Embedded solar harvesting extends operational autonomy, enabling off-grid installations in remote highway corridors without grid connection costs.
- China's Tier-One Urban Corridors:Integrated sensor-lighting systems replace conventional road markers at scale, concentrating demand volume in high-density deployment zones.
Market Restraints
- Lithium-Ion Battery Volatility:Energy storage component costs fluctuate with raw material availability, compressing margins on Solar-Powered configurations.
- Multi-Jurisdiction Testing Burden:FCC certification for US deployments, CE marking for Europe, and China's GB standards fragment R&D budgets across incompatible compliance regimes.
- Reflective Marker Substitution:Mature reflective cat eyes retain cost advantage in budget-constrained municipalities, limiting premium smart system penetration.
Strategic Opportunities
- Wi-Fi Connectivity Convergence:Mesh networking protocols combined with edge computing enable real-time traffic analytics without cellular dependency.
- European Municipal Procurement Channels:Established lighting infrastructure relationships create upgrade pathways for integrated smart cat eye bundles.
- India's PLI Scheme:Production-linked incentives for electronics manufacturing reduce landed costs for domestic assembly operations.
Industry Challenges
- Electromagnetic Compatibility Certification:Evolving EMC mandates for connected infrastructure extend product validation timelines before commercial release.
- Piezoelectric Sensor Calibration:Precision optical component integration requires specialized technician training unavailable in secondary highway maintenance markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Cat Eye Market |
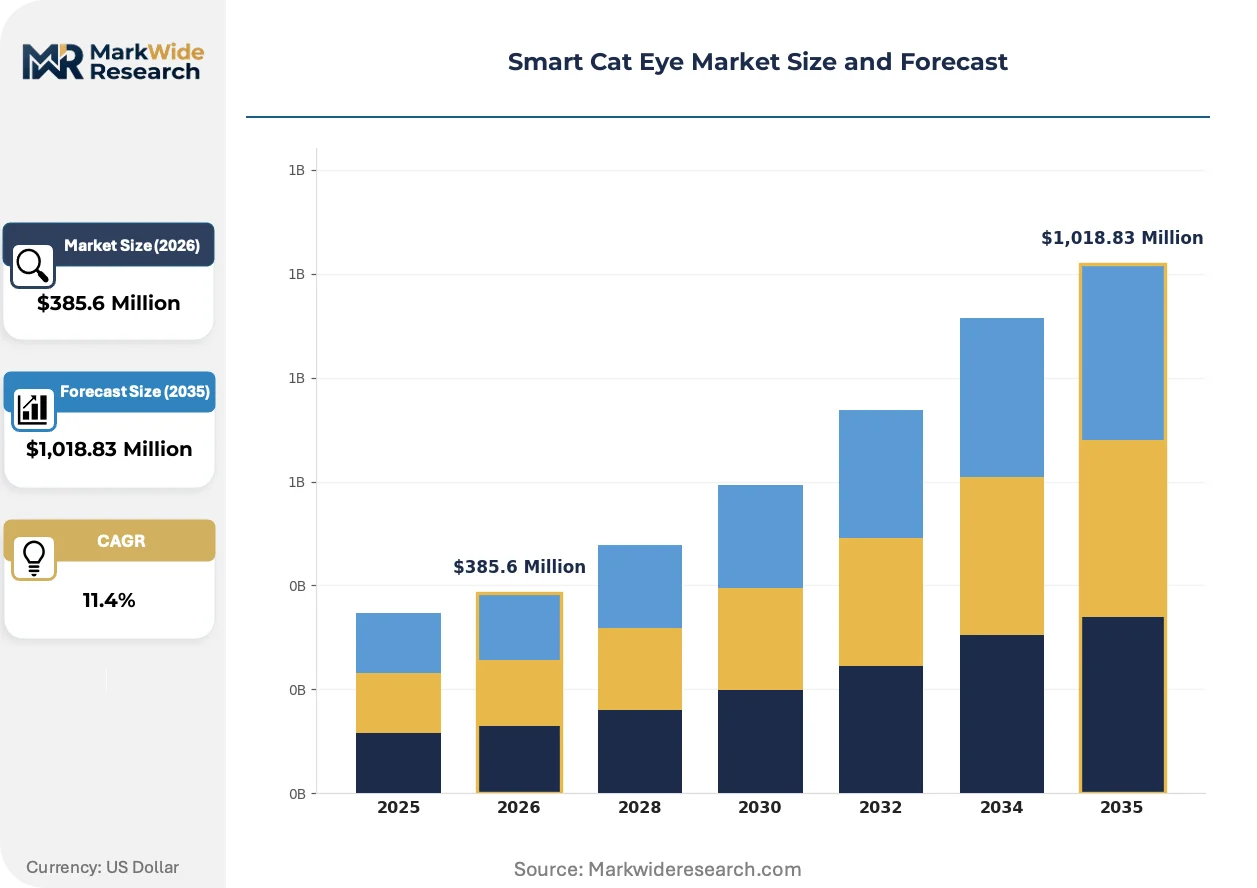
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $1,018.83 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED Cat Eyes, Reflective Cat Eyes, Smart Sensors, Advanced Lighting Technology: Wi-Fi Connectivity, Bluetooth Integration, Solar-Powered, Sensor Technology Application: Road Safety, Traffic Management, Smart City Infrastructure, Vehicle Assistance End User: Municipalities, Construction Companies, Automotive Manufacturers, Transport Agencies |
| Companies Covered | Royalstar, Danmini, Xiaomi, Tuya Smart, HiThink, Kaadas, Elock, Philips, Sengled, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Cat Eye Market Trends and Innovations
Adaptive brightness protocols and embedded connectivity modules are redefining product specifications, compressing the functional gap between road markers and full traffic management nodes.
AI-driven adaptive brightness protocols are automating luminosity adjustment based on ambient conditions and vehicle proximity. Municipal buyers in high-speed roadway applications are specifying these systems in tender documents. The technology is automating manual calibration requirements, reducing field maintenance cycles.
China's GB certification frameworks for wireless communication modules are tightening electromagnetic compatibility thresholds for roadway electronics. Manufacturers must redesign transmission architectures to meet revised spectrum allocation rules. Solar-Powered configurations face the steepest redesign burden due to integrated RF components.
Integrated sensor-lighting bundles are displacing standalone procurement of reflective markers and illumination systems. Tier-one urban corridor authorities now specify combined connectivity-visibility solutions in single-vendor contracts. China's municipal tender processes exhibit the most pronounced bundling preference.
Smart Cat Eye Market Segmentation
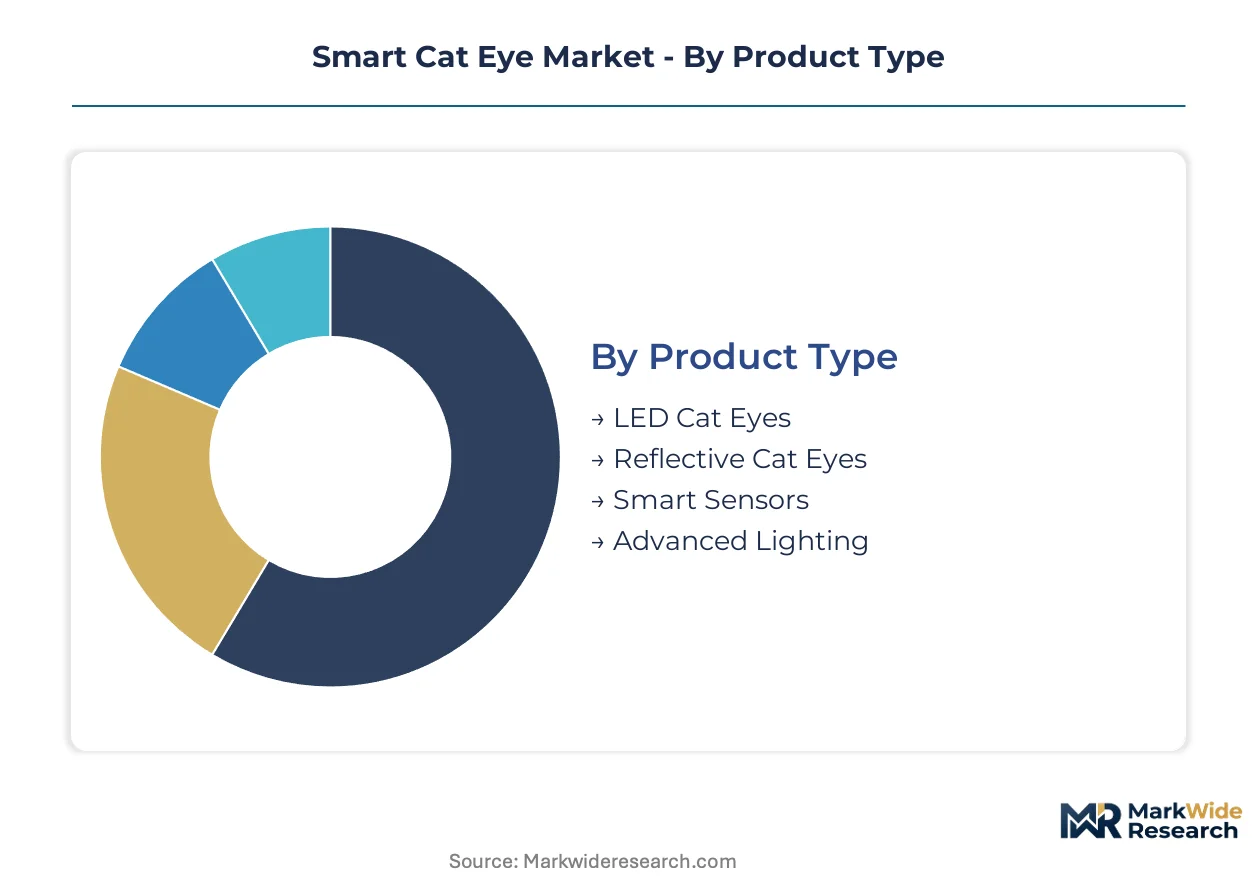
Smart cat eye manufacturers configure product portfolios across four intersecting dimensions to match procurement specifications. Municipal tender documents increasingly bundle hardware, connectivity, and analytics into unified vendor contracts. Segment positioning determines margin structure, with integrated systems commanding premium pricing against standalone reflective markers.
Product Type:
Volume concentrates in established visibility solutions while premium value shifts toward sensor-embedded systems with data transmission capabilities.
- LED Cat Eyes:Active illumination systems incorporate photovoltaic harvesting and solid-state emitters operating between 590-620 nanometers for optimal nighttime visibility. China's tier-one urban corridors specify these units for high-speed roadway replacements, driven by Ministry of Transport mandates for intelligent infrastructure upgrades.
- Smart Sensors:Embedded piezoelectric and radar modules detect vehicle presence, velocity, and axle load for real-time traffic analytics. India's Ministry of Road Transport and Highways concentrates procurement in this segment through accelerated smart city deployment timelines.
- Reflective Cat Eyes:Passive retroreflective markers using glass bead or prismatic optics retain dominance in budget-constrained secondary highway networks.
- Advanced Lighting:AI-driven adaptive brightness protocols automate luminosity adjustment based on ambient conditions and proximity detection.
Today's leader: LED Cat Eyes. Tomorrow's challenger: Smart Sensors.
Technology:
Connectivity architecture determines deployment economics, with mesh networking protocols reducing cellular dependency and recurring subscription costs.
- Wi-Fi Connectivity:Mesh-enabled transmission modules support real-time data relay to central management platforms without proprietary carrier contracts. European municipal procurement channels favor this architecture for existing lighting infrastructure integration.
- Solar-Powered:Photovoltaic cell efficiency gains extend operational autonomy in remote highway corridors lacking grid access. India's PLI scheme for electronics manufacturing reduces landed costs for domestic assembly of these configurations.
- Bluetooth Integration:Short-range protocols enable vehicle-to-infrastructure communication for localized hazard alerts.
- Sensor Technology:Multi-modal detection arrays combine environmental monitoring with traffic flow measurement.
Wi-Fi Connectivity anchors current deployment volumes. Solar-Powered configurations are climbing the fastest as off-grid resilience becomes a procurement priority.
Application:
Use case specificity shapes technical specifications, with smart city tenders demanding broader data integration than standalone road safety installations.
- Traffic Management:Integrated sensor networks feed predictive analytics platforms for congestion mitigation and incident response. China's GB certification frameworks for wireless modules concentrate compliance investment in this application segment.
- Smart City Infrastructure:Unified connectivity-visibility solutions bundle illumination, environmental sensing, and communication in single-vendor contracts. Tier-one municipal authorities in Asia-Pacific specify these systems for new urban corridor development.
- Road Safety:Conventional visibility enhancement for lane demarcation and hazard marking.
- Vehicle Assistance:Cooperative intelligent transport systems supporting automated driving functions.
Traffic Management captures the largest contract values. Smart City Infrastructure is gaining share fastest through bundled procurement mandates.
End User:
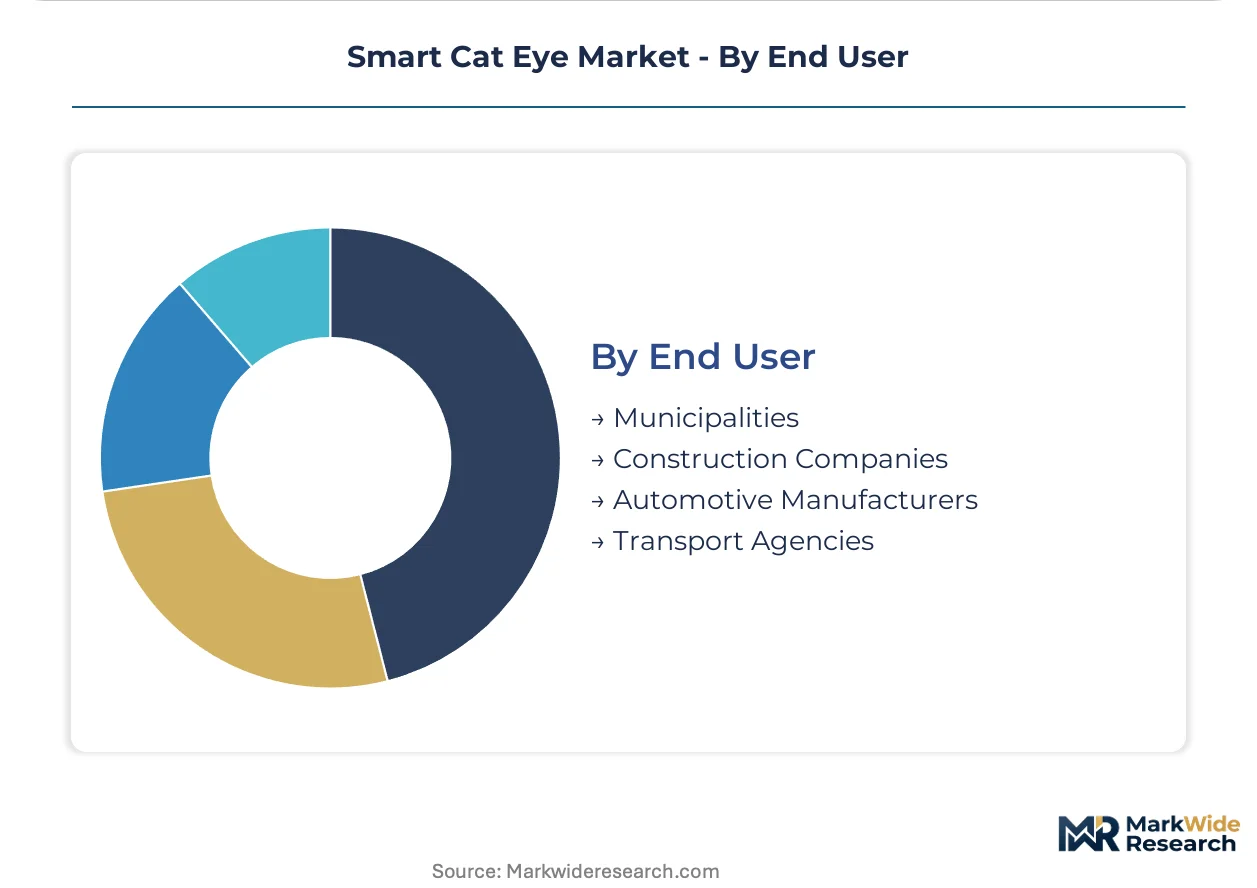
Procurement authority determines specification complexity, with centralized transport agencies consolidating demand volume against fragmented construction company purchasing.
- Municipalities:City and regional governments issue multi-year framework agreements for integrated sensor-lighting systems. India's state-level urban development authorities are compressing procurement cycles through centralized tender platforms.
- Transport Agencies:National and provincial highway operators specify high-performance systems for arterial road networks. China's Ministry of Transport directs standardization through GB certification alignment.
- Construction Companies:Temporary installation demand for work zone safety and project-specific roadway marking.
- Automotive Manufacturers:OEM integration for proving ground infrastructure and cooperative vehicle testing.
Municipalities dominate current order intake. Transport Agencies represent the steepest expansion trajectory through national highway modernization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smart cat eye technology originated in European road safety engineering before scaling through Asian manufacturing corridors. Early photovoltaic-LED integration emerged from German automotive lighting research. Deployment density now concentrates in Asia-Pacific urban corridors where smart city mandates accelerate replacement cycles.
China
Integrated sensor-lighting systems dominate procurement in tier-one urban corridors. The Ministry of Transport directs standardization through GB certification alignment for wireless communication modules. Shanghai and Beijing municipal authorities specify combined connectivity-visibility solutions in single-vendor framework agreements.
India
State-level urban development authorities compress procurement cycles through centralized tender platforms. The Ministry of Road Transport and Highways mandates intelligent traffic management upgrades under BIS certification frameworks. Maharashtra and Karnataka concentrate deployment volume through accelerated smart city infrastructure programs.
Germany
European municipal procurement channels favor Wi-Fi-enabled mesh architectures for existing lighting infrastructure integration. CE marking and RoHS compliance govern market access for electronic road safety equipment. Bavaria and North Rhine-Westphalia anchor continental demand through established highway modernization frameworks.
United States
FCC certification requirements govern wireless transmission protocols for intelligent roadway electronics. Municipal procurement cycles favor adaptive brightness protocols for high-speed roadway applications. California and Texas transport agencies specify AI-driven luminosity adjustment systems in arterial network tenders.
Japan
METI guidelines shape cooperative intelligent transport system specifications for vehicle-to-infrastructure communication. JIS standards govern electromagnetic compatibility thresholds for embedded sensor modules. Kanto and Kansai metropolitan regions concentrate pilot deployments for automated driving function support.
Smart Cat Eye Market Competitive Landscape
The competitive structure tilts toward diversified electronics conglomerates with consumer ecosystem leverage. Vendor concentration remains moderate, with tier-one municipal contracts consolidating around established lighting infrastructure relationships. Three archetypes dominate: consumer electronics platform holders, precision optical component specialists, and legacy lighting infrastructure incumbents. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with manufacturers reconfiguring supply chains to meet compressed deployment timelines.
Within the consumer electronics platform tier, Xiaomi leverages its ecosystem breadth to anchor Asia-Pacific smart city tender participation. Kaadas occupies a position among precision optical component specialists, differentiating through technical specifications for high-speed roadway applications. Philips represents the legacy lighting infrastructure archetype, sustaining municipal procurement channel relationships across European markets. These three exemplify the strategic positioning vectors that define competitive differentiation in integrated sensor-lighting bundles.
| Leading Market Players |
|---|
| Royalstar |
| Danmini |
| Xiaomi |
| Tuya Smart |
| HiThink |
| Kaadas |
| Elock |
| Philips |
| Sengled |
| Others |
Pricing and Supply Chain Analysis
Precision optical engineering talent clustering in Guangdong Province compresses production labor costs for mid-tier LED Cat Eye assemblies, widening the spread between premium AI-driven adaptive brightness systems and economy photovoltaic-LED units. Municipal procurement officers exploit this labor-cost gradient to negotiate volume discounts on standardized bundles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs municipal tender responses. Price differentiation centers on certification grade—FCC-compliant configurations for US transport agencies command premiums over BIS-certified domestic Indian alternatives—and embedded sensor density. Cost compression in Solar-Powered configurations intensifies because lithium-ion battery raw material volatility feeds through to landed costs. Budget-constrained secondary highway authorities exhibit highest price sensitivity, while tier-one smart city integrators prioritize performance specifications over unit economics.
Supply Chain Analysis
Reverse-logistics flows for photovoltaic cell refurbishment and LED emitter remanufacturing are underdeveloped, creating stranded asset risk in deployed units. Manufacturing concentrates in China, South Korea, and Vietnam, with precision optical component fabrication anchored in German and Japanese specialist facilities. Supply chains draw from polysilicon wafer suppliers, lithium carbonate processors, and RF module foundries. Single-source vulnerability in piezoelectric sensor MEMS fabrication threatens calibration consistency. Distribution runs through municipal procurement platforms and national highway authority framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Smart Cat Eye systems rests on photovoltaic cell efficiency gains reducing battery capacity requirements and shifting procurement preference toward premium-tier AI-driven adaptive brightness protocols.
For Market Incumbents: Hedge against reflective marker substitution by embedding connectivity modules as standard features rather than upsell options. Deepen backward integration into precision optical component production to defend margin position against Kaadas-style specialists. Accelerate BIS and GB certification maintenance to preempt compliance-driven vendor switching in India and China. For New Entrants and Emerging Players: Capture underserved secondary highway networks in India's state-level urban development authorities where procurement cycle compression outpaces incumbent supply chain reconfiguration. Target European municipal procurement channels through Wi-Fi-enabled mesh architectures that retrofit existing Philips lighting infrastructure. Lead with solar-powered configurations to bypass grid-connection cost barriers in remote corridor deployments. For Investors and Strategic Acquirers: Consumer electronics conglomerates with smart home ecosystems are the most active acquirer in this space, seeking traffic infrastructure entry points. Long-term viability hinges on automated driving function integration and vehicle-to-infrastructure communication standardization. Monitor METI guideline evolution and NHTSA cooperative transport system rulemaking as regulatory inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Photovoltaic Efficiency Partnership | Domestic solar cell sourcing under India's PLI scheme reduces landed costs for off-grid configurations. |
| GB Certification Pre-Positioning | Early alignment with China's revised electromagnetic compatibility thresholds accelerates municipal tender eligibility. |
| Mesh Network Platform Integration | Wi-Fi-enabled architectures bypass cellular subscription costs favored by European procurement officers. |
| Precision Optical Component Acquisition | Capturing German or Japanese MEMS fabrication capability differentiates high-speed roadway specifications. |
| Adaptive Brightness Protocol Development | AI-driven luminosity automation reduces field maintenance cycles specified in California transport tenders. |
Research Methodology
Multiple input streams—municipal procurement database analysis, highway authority tender documentation, and component supplier shipment records—were reconciled against primary interviews with smart city project directors, transport agency specification engineers, and photovoltaic module procurement leads. Secondary validation drew from FCC equipment authorization filings, BIS certification registries, China's GB standards publication notices, and EPC contractor project announcements. Bottom-up unit deployment estimates and top-down infrastructure budget allocations were cross-referenced for triangulation.
Data-stream reconciliation across product type, technology architecture, application specificity, and end-user procurement authority dimensions shaped the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against macro infrastructure investment trajectories. Forecast inputs incorporated India's Ministry of Road Transport and Highways mandate timelines, China's tier-one urban corridor replacement cycles, and European municipal lighting infrastructure upgrade schedules.
Underlying measurement precision varies by segment; LED Cat Eyes and Wi-Fi Connectivity carry tighter precision than emerging Advanced Lighting categories. Forecasts reflect documented assumptions regarding regulatory mandate adherence and photovoltaic cost curves. Practitioners should monitor lithium carbonate price indices, GB certification revision notices, and state-level smart city budget allocations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Brazil Pet Food Market
Pet Care Products
Pet Grooming Supplies Market
Pet Care Products
Robotic Pets Market
Pet Care Products
Outdoor Dog Bed Market
Pet Care Products
Germany Pet Training Services Market
Pet Care Products
Freeze Dried Dog Food Market
Pet Care Products
Dog Dental Chews Market
Pet Care Products
Dog Seat Belt Market
Pet Care Products
Pet Collar Market
Pet Care Products
UTI Cat Food Market
Pet Care Products
Canada Pet Training Services Market
Pet Care Products
Asia-Pacific Pet Clothing Market
Pet Care Products
Vegan Cat Food Market
Pet Care Products
Smart Pet Kennel Market
Pet Care Products
Pet Rugs Market
Pet Care Products
Dog Food for Small Breeds Dogs Market