
 Pet Car Seat Market | 2026-2036
Pet Car Seat Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Car Seat Market Analytics
Modular booster-to-hammock configurations is pivoting buyer choice toward adaptable single-purchase solutions that accommodate multiple vehicle types and pet sizes. Kurgo leverages its R&D intensity to develop crash-tested designs that meet independent safety certifications. Sleepypod anchors its premium positioning through aviation-grade materials originally engineered for pet carrier applications. PetSafe competes across mass retail channels with accessible price points and broad distribution coverage.
A pet car seat is a purpose-built restraint system designed to secure companion animals during vehicular transport, typically constructed with padded structural frames, tether-compatible anchor points, and materials rated for abrasion resistance and impact absorption. Its primary commercial purpose is to reduce driver distraction, minimize injury risk to occupants, and comply with emerging animal welfare transportation standards. Booster seats command the largest volume share due to their compatibility with small-to-medium breeds and straightforward installation protocols, while hammock-style configurations represent the fastest-growing category as owners of large and extra-large dogs seek full-coverage cabin protection. Waterproof fabric materials capture disproportionate margin pools because they command premium pricing and address the highest-frequency consumer pain point of post-travel cleaning and odor retention.
The National Highway Traffic Safety Administration in the United States and the European Committee for Standardization through its pet transport equipment working groups are both advancing testing protocols that would mandate independent crash certification for products marketed as safety devices. These regulatory trajectories are forcing manufacturers to invest in third-party validation infrastructure and redesign products around quantifiable performance metrics rather than aesthetic differentiation alone. Stakeholders must monitor which certification schemes achieve retail gatekeeper status and align their development roadmaps accordingly.
Market Dynamics
Crash-test certification mandates from NHTSA and parallel European standardization efforts are forcing manufacturers to redesign around quantifiable safety metrics rather than aesthetic differentiation alone. This regulatory compression is restructuring competitive advantage toward R&D-intensive players with third-party validation infrastructure.
Growth Catalysts
- Sun Belt State Car Dependency:Pet owners across Texas, Florida, and Arizona maintain vehicle-centric lifestyles that normalize pet transport accessories as routine purchases rather than discretionary items.
- EU Pet Transport Equipment Standards:Emerging harmonized testing protocols through the European Committee for Standardization are creating retail gatekeeper effects that favor certified products in mass distribution channels.
- Modular Booster-to-Hammock Systems:Adaptable single-purchase configurations accommodating multiple vehicle types and pet sizes are compressing replacement cycles and expanding average transaction values.
Market Restraints
- Aviation-Grade Material Costs:Premium positioning dependent on aerospace-sourced fabrics and impact-absorbing foams exposes margins to volatile petrochemical and specialty polymer input pricing.
- Third-Party Testing Bottlenecks:Concentration of independent crash-test facilities in Germany and the United States creates certification queue delays that extend product launch timelines.
- Uncertified Low-Cost Substitutes:Unregulated harness and barrier alternatives sold through uncontrolled e-commerce channels erode price discipline and confuse safety-conscious buyers.
Strategic Opportunities
- Suburban and Exurban Expansion:Underpenetrated communities outside major metropolitan cores in the United States represent concentrated pet ownership density with rising disposable income profiles.
- Waterproof Fabric Premium Tiers:Post-travel cleaning and odor retention remain the highest-frequency consumer pain point, creating margin expansion potential for advanced hydrophobic coating technologies.
- Veterinary Channel Integration:Partnership structures with companion animal health providers offer trust-based distribution that bypasses commoditized mass retail price competition.
Industry Challenges
- Biomechanical Engineering Talent Scarcity:The intersection of veterinary anatomy knowledge and automotive safety engineering represents a narrow labor pool that constrains product development velocity.
- Multi-Jurisdiction Certification Parallelism:Divergent NHTSA, EU, and emerging national testing timelines force redundant validation expenditures that compress development budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Car Seat Market |
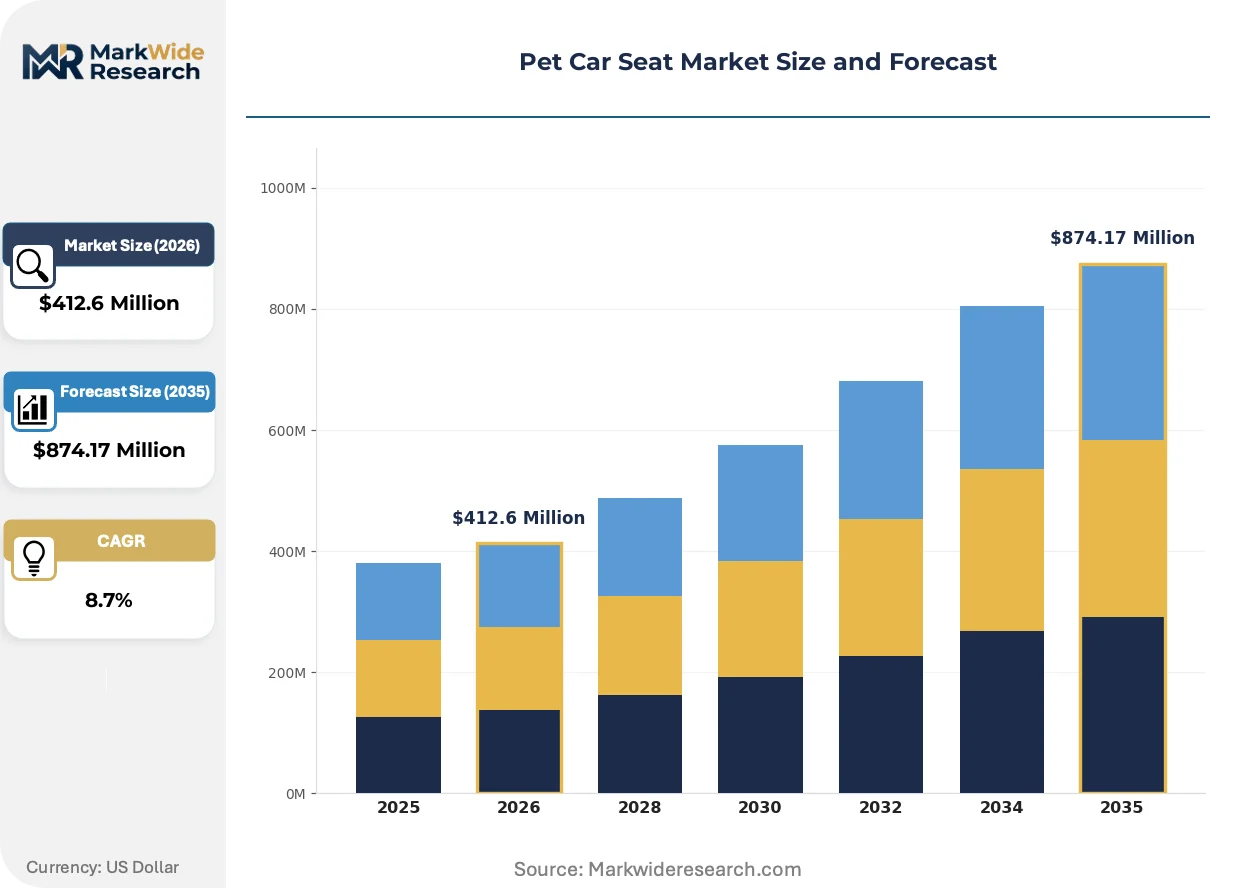
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bucket Seat Covers, Booster Seats, Hammock Style, Safety Harnesses Material: Canvas, Nylon, Waterproof Fabric, Faux Leather Size: Small, Medium, Large, Extra Large Installation Type: Seat Belt Utilization, Latch System, Clip System, Slip-on Design |
| Companies Covered | Petsfit, Snoozer Pet Products, Kong, Julibees, Tavo Pet Products, Luther Bennett, Kurgo, Sleepypod, PetSafe, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Car Seat Market Evolving Landscape
Product architecture is pivoting from fixed-format designs toward adaptive systems that accommodate variable vehicle geometries and pet morphologies without hardware replacement. This shift is compressing manufacturer SKU proliferation while expanding end-user utility per purchase.
Memory-foam core construction paired with machine-washable outer shells is decentralizing the traditional trade-off between impact protection and maintenance convenience. Suburban households with multiple vehicle types are adopting these hybrid systems at accelerated rates. The technology is decentralizing purchasing authority from specialized pet retailers toward general automotive accessory channels by reducing fit-complexity support requirements.
REACH chemical compliance and emerging EU Green Deal circularity requirements are mandating material disclosure and recyclability roadmaps for textile components. Manufacturers serving European distribution must now document supply chain chemistry and end-of-life processing protocols. Booster seat categories with synthetic-heavy construction face disproportionate reformulation pressure compared to hammock configurations with simpler material stacks.
Subscription-based accessory refresh programs are emerging as an alternative to outright ownership in premium buyer segments. Veterinary clinic partnerships and direct-to-consumer platforms are displacing traditional pet specialty retail for initial purchase and replacement cycles. This pattern concentrates most visibly in coastal United States markets where service-model consumption has normalized across adjacent categories.
Pet Car Seat Market Segmentation
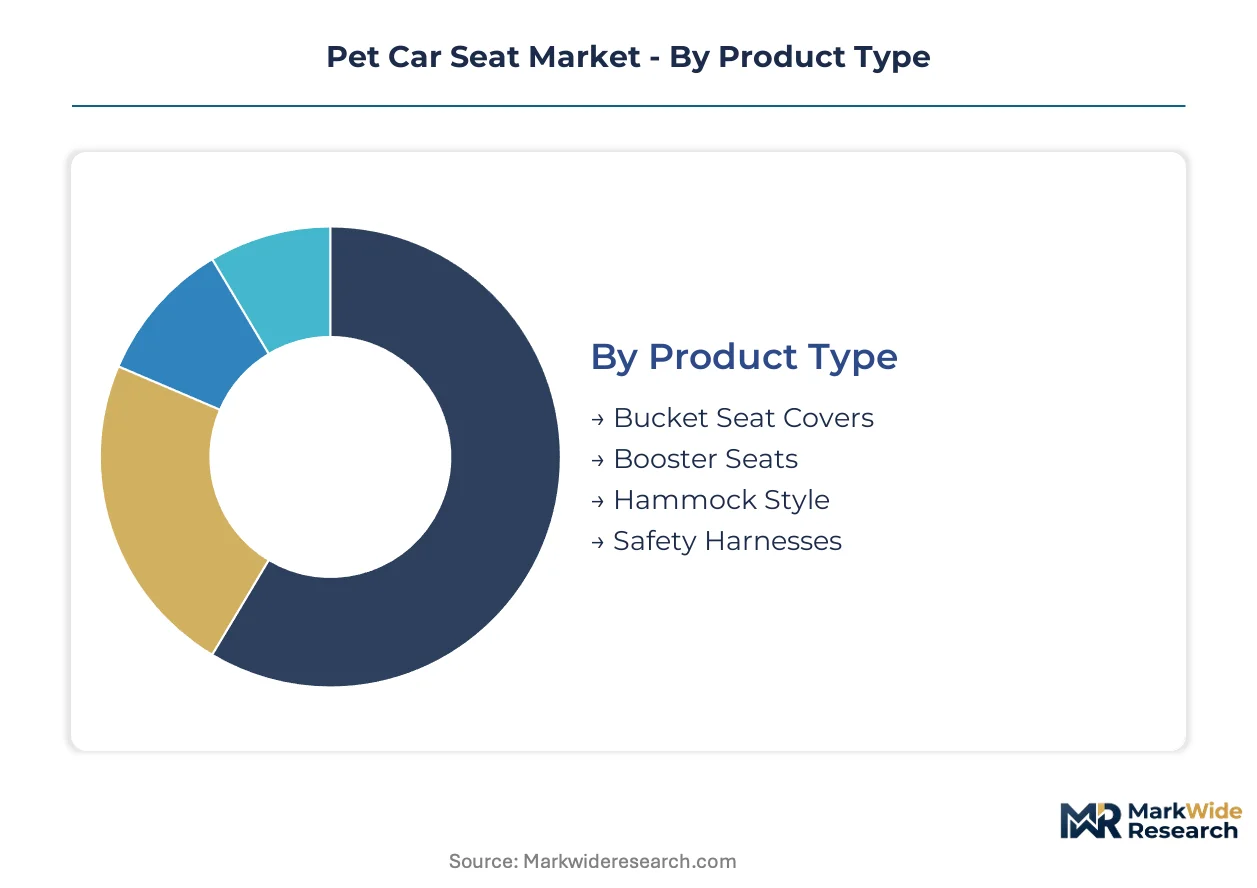
Segmentation in the pet car seat market reveals how purchase decisions cluster around vehicle compatibility, pet morphology, and maintenance expectations. Manufacturers configure their SKU strategies around these dimensions to minimize fit-related returns and maximize repeat purchase rates.
Product Type:
Upgrade cycles vary dramatically across formats, with replacement driven by either pet growth milestones or vehicle changes rather than product failure.
- Booster Seats:Elevated platforms with padded structural frames and tether-compatible anchor points designed for small-to-medium breeds. Demand concentrates most visibly in the United States, particularly across Texas, Florida, and Arizona where car-dependent lifestyles normalize pet transport accessories as routine purchases.
- Hammock Style:Full-coverage cabin protection systems spanning rear seating areas with abrasion-resistant panels and side-flap extensions. Owners of large and extra-large dogs in suburban communities outside major metropolitan cores are adopting these configurations at accelerated rates as they seek comprehensive interior protection.
- Bucket Seat Covers:Contoured single-seat protection with non-slip backing and quilted padding layers.
- Safety Harnesses:Body-conforming restraint systems with crash-test-rated webbing and vehicle anchor compatibility.
Volume placements concentrate in Booster Seats; the faster expansion belongs to Hammock Style.
Material:
Cost tier differentiation separates commodity synthetics from aerospace-derived performance fabrics, with margin pools concentrating in hydrophobic coating technologies.
- Waterproof Fabric:Hydrophobic-coated textiles with sealed seams and odor-resistant surface treatments originally engineered for marine applications. Post-travel cleaning and odor retention remain the highest-frequency consumer pain point, creating margin expansion potential for advanced coating technologies in premium buyer segments.
- Nylon:High-tenacity synthetic weave with abrasion ratings and machine-washable compatibility for maintenance convenience. REACH chemical compliance and emerging EU Green Deal circularity requirements are mandating material disclosure and recyclability roadmaps for textile components in European distribution.
- Canvas:Heavy-duty cotton-duck weave with natural fiber content and waxed finish options.
- Faux Leather:Polyurethane-coated substrates mimicking automotive interior aesthetics with wipe-clean maintenance profiles.
Volume placements concentrate in Nylon; the steepest expansion trajectory belongs to Waterproof Fabric.
Size:
Customer type stratification maps directly to breed ownership patterns, with multi-pet households driving demand for graduated size configurations.
- Small:Dimensions calibrated for toy breeds under 15 pounds with compact vehicle footprint requirements.
- Medium:Platforms accommodating breeds between 15-40 pounds with adjustable elevation settings.
- Large:Structural capacity for breeds between 40-75 pounds with reinforced frame construction.
- Extra Large:Heavy-duty configurations for breeds exceeding 75 pounds with distributed load engineering.
Volume placements concentrate in Small and Medium; the climbing demand belongs to Large as breed ownership patterns shift.
Installation Type:
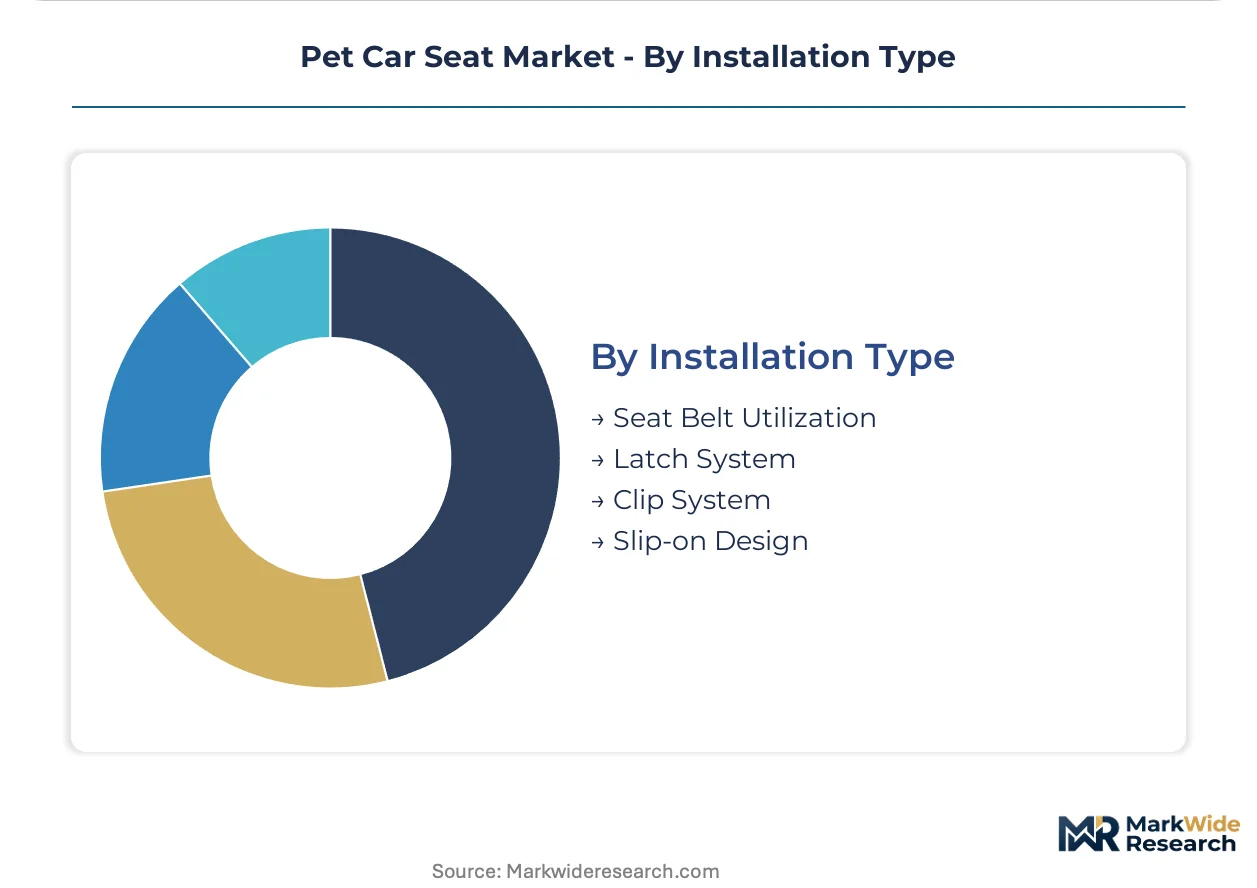
Application context determines protocol preference, with rental vehicle compatibility and multi-car households favoring transferable systems.
- Latch System:ISOFIX-compatible anchor points with rigid attachment bars and release mechanisms matching child safety seat standards. NHTSA advancing testing protocols that would mandate independent crash certification for products marketed as safety devices is elevating Latch System validation requirements.
- Seat Belt Utilization:Universal compatibility with existing vehicle restraint systems and tool-free attachment protocols. Suburban households with multiple vehicle types are adopting these hybrid systems at accelerated rates as the technology decentralizes purchasing authority from specialized pet retailers.
- Clip System:Quick-release hardware with adjustable strap lengths and swivel connectors.
- Slip-on Design:Elasticized perimeter construction for rapid deployment and removal without hardware engagement.
Volume placements concentrate in Seat Belt Utilization; the gaining share fastest belongs to Latch System as certification standards tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in China and Vietnam while consumption tilts toward the United States and European Union. This geographic split shapes certification requirements and distribution strategies across supplier networks.
United States
Sun Belt states including Texas, Florida, and Arizona normalize pet car seats as routine vehicle accessories. NHTSA testing protocol developments are elevating third-party crash certification requirements for safety-marketed products. Suburban communities outside Atlanta, Dallas, and Phoenix exhibit concentrated adoption of modular booster-to-hammock configurations.
Germany
Automotive safety engineering heritage translates into stringent consumer expectations for pet restraint validation. KBA involvement in EU harmonization efforts is accelerating independent testing facility queue congestion. Stuttgart and Munich industrial clusters host specialized polymer and textile suppliers serving premium pet transport equipment manufacturers.
China
Domestic pet ownership expansion in tier-two cities is creating parallel demand for vehicle accessories. GB standards development for pet transport equipment remains in early drafting phases, creating regulatory uncertainty for exporters. Yangtze River Delta manufacturing bases supply waterproof fabric components to global OEM networks.
United Kingdom
Urban-rural pet ownership gradients favor hammock-style configurations for countryside vehicle use. Post-Brexit divergence from EU certification timelines is forcing redundant validation expenditures for cross-channel suppliers. Midlands distribution hubs consolidate inventory for European re-export despite customs friction.
Japan
Compact vehicle fleet composition favors space-efficient booster seat formats over full-cabin hammocks. METI consumer product safety guidelines are incorporating pet transport equipment into broader vehicle accessory frameworks. Osaka-based textile processors supply abrasion-resistant fabrics to domestic and export markets.
Pet Car Seat Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered price bands. The vendor base spans mass-market retailers, veterinary channel partners, and direct-to-consumer platforms with divergent margin structures. Three archetypes dominate: R&D-intensive safety validators, mass-market distributors with broad channel coverage, and premium material specialists leveraging aerospace-derived inputs. Consolidation pressure is intensifying through strategic partnerships with third-party testing facilities and exclusive veterinary clinic distribution agreements.
Within the safety-validation archetype, Kurgo and Sleepypod occupy positions that exemplify third-party certification dependence. PetSafe anchors the mass-market tier with channel breadth rather than technical differentiation. These three companies represent the strategic poles around which competitive positioning organizes.
| Leading Market Players |
|---|
| Petsfit |
| Snoozer Pet Products |
| Kong |
| Julibees |
| Tavo Pet Products |
| Luther Bennett |
| Kurgo |
| Sleepypod |
| PetSafe |
| Others |
Value Network & Pricing Analysis
Crash-test certification mandates from NHTSA and the European Committee for Standardization are forcing manufacturers to absorb third-party validation costs and redesign products around quantifiable performance metrics, compressing margins in the mass-market tier while creating pricing power for certified premium players.
Pricing Analysis
Margin tightening in the standard tier reflects raw material cost escalation in aerospace-derived fabrics and impact-absorbing foams. Three-tier pricing structure across premium, standard, and economy levels separates crash-tested safety validators from uncertified alternatives, with certification grade and volume scale as the primary differentiation drivers. Pricing pressure intensifies in the economy tier as unregulated harness substitutes flood e-commerce channels. Veterinary channel buyers exhibit the lowest price sensitivity, while mass retail consumers demonstrate acute responsiveness to promotional discounting.
Supply Chain Analysis
Returns processing and refurbishment flows remain underdeveloped in this category, creating working capital inefficiencies for manufacturers managing fit-related exchanges across variable vehicle geometries. Manufacturing concentrates in China and Vietnam, with Yangtze River Delta facilities supplying waterproof fabric components and polymer processors serving frame and tether hardware needs. The supply chain draws from petrochemical-based specialty polymers and aviation-grade textile inputs. Single-source vulnerability concentrates in German and American third-party crash-test facilities. Distribution runs through mass retail chains, veterinary clinic partnerships, and direct-to-consumer platforms with divergent margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NHTSA and EU harmonization efforts are elevating compliance costs into a structural moat that rewards pre-certified incumbents while raising capital barriers for unvalidated entrants.
For Market Incumbents: Extend certification coverage across modular product architectures to capture replacement cycle compression from adaptable booster-to-hammock systems. Deepen backward integration into waterproof fabric coating technologies to defend margin position against petrochemical input volatility. Channel control through exclusive veterinary clinic partnerships offers defensive positioning against mass retail price erosion. For New Entrants and Emerging Players: Direct-to-consumer subscription models for accessory refresh programs represent the most penetrable white-space target in coastal United States markets where service-model consumption has normalized. Suburban and exurban communities outside Sun Belt metropolitan cores offer geographic expansion potential with concentrated pet ownership density and rising disposable income profiles. A veterinary channel integration strategy bypasses commoditized retail competition through trust-based distribution. For Investors and Strategic Acquirers: The window for entry favors R&D-intensive safety validators with established third-party testing relationships and multi-jurisdiction certification portfolios. Long-term viability hinges on regulatory trajectory alignment rather than aesthetic differentiation alone. The signal to monitor is which certification schemes achieve retail gatekeeper status in mass distribution channels.| Strategic Initiative | Industry Significance |
|---|---|
| Third-Party Certification Investment | NHTSA and EU protocol alignment secures retail distribution access in safety-marketed tiers. |
| Modular Product Architecture Development | Booster-to-hammock adaptability compresses SKU proliferation while expanding transaction values. |
| Veterinary Channel Partnership Expansion | Clinic-based distribution bypasses price competition through trust-based recommendation authority. |
| Waterproof Fabric Technology Integration | Hydrophobic coating capabilities address the highest-frequency consumer pain point in post-travel maintenance. |
| Reverse Logistics Infrastructure Buildout | Returns processing efficiency reduces working capital drag from fit-related exchanges across vehicle types. |
Research Methodology
Trade association filings, customs and import records, and automotive safety regulator documentation formed the secondary backbone of this analysis. Primary interviews with pet product R&D directors, third-party testing facility managers, veterinary clinic procurement leads, and mass retail category buyers were cross-validated against secondary sources. Bottom-up segmentation modeling and top-down market sizing approaches were triangulated to reconcile volume and value estimates.
Historical trendline analysis across pet ownership growth patterns, vehicle sales data, and accessory attachment rates informed the projection framework. Segmentation dimensions modeled include product type, material grade, installation protocol, pet size category, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to baseline penetration estimates. Industry-specific forecast inputs incorporated NHTSA protocol development timelines and EU harmonization implementation schedules.
The model holds under stable regulatory implementation timelines; deviation in certification mandate acceleration or petrochemical input cost spikes would shift manufacturer margin trajectories. Practitioners should monitor third-party testing facility queue congestion and REACH chemical compliance enforcement intensity for early signals of supply-side constraint or reformulation cost pressure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Spain Pet Boarding Market
Pet Care Products
Automatic Cat Feeder Market
Pet Care Products
DTC Pet Food Market
Pet Care Products
Dog Seat Covers Market
Pet Care Products
Pet Care Market
Pet Care Products
Small Breed Dog Food Market
Pet Care Products
Small Dog Harness Market
Pet Care Products
Fresh and Frozen Dog Food Market
Pet Care Products
Dog Clothes Market
Pet Care Products
Disposable Absorbent Pet Pad Market
Pet Care Products
UTI Cat Food Market
Pet Care Products
Germany Pet Clothing Market
Pet Care Products
Cat Accessories Market
Pet Care Products
Dog Pad Market
Pet Care Products
Pet Tick and Flea Prevention Market
Pet Care Products
Robotic Pets Market