
 North America Cat Food Market | 2026-2036
North America Cat Food Market Size, Share, and Industry Trends Forecast 2026-2036
North America Cat Food Market Insights
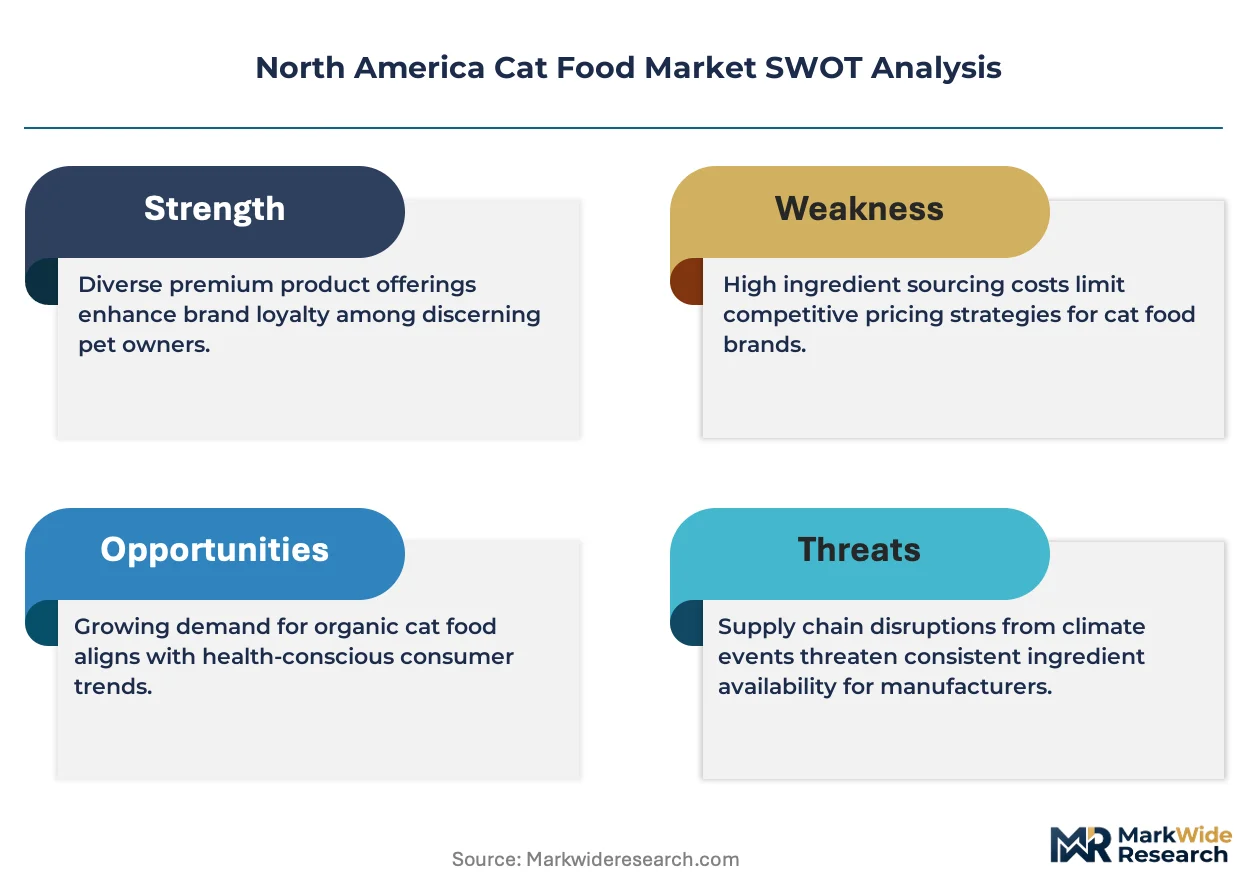
Premium wet food revenue is fragmenting across multiple price tiers and channel formats as private-label entrants and direct-to-consumer brands erode legacy margin pools. Mars Incorporated leverages its vertical integration into protein sourcing to sustain cost discipline across wet and dry portfolios. Nestle Purina PetCare anchors volume leadership through veterinary channel partnerships and prescription diet lines. Champion Petfoods differentiates via biologically appropriate formulations that command shelf space in specialty retail.
North America cat food encompasses commercially manufactured nutritional products formulated to meet the dietary requirements of domestic cats, typically comprising protein meals, fats, vitamins, and moisture content ranging from six percent in dry kibble to eighty percent in wet formulations, produced through extrusion, canning, or raw blending processes designed to deliver complete and balanced feline nutrition. Wet food commands the highest per-unit margins and fastest volume growth as humanization trends elevate palatability expectations, while dry food retains scale advantages in mass retail distribution and storage economics. Grain-free ingredient positioning has matured following FDA investigations into dilated cardiomyopathy linkages, redirecting R&D investment toward limited-ingredient and functional additive formulations.
The FDA Center for Veterinary Medicine enforces ingredient safety and labeling standards that dictate permissible additives and nutritional adequacy claims across US production facilities. The Association of American Feed Control Officials establishes nutrient profiles that manufacturers must meet for complete-diet designation, while Canadian Food Inspection Agency regulations govern cross-border product flows and import compliance. State-level inspection protocols in California and Texas add supplementary layers that multi-facility operators must navigate. Stakeholders should monitor evolving regulatory scrutiny of novel proteins and cultivated meat alternatives as these technologies approach commercial viability in companion animal nutrition.
Market Dynamics
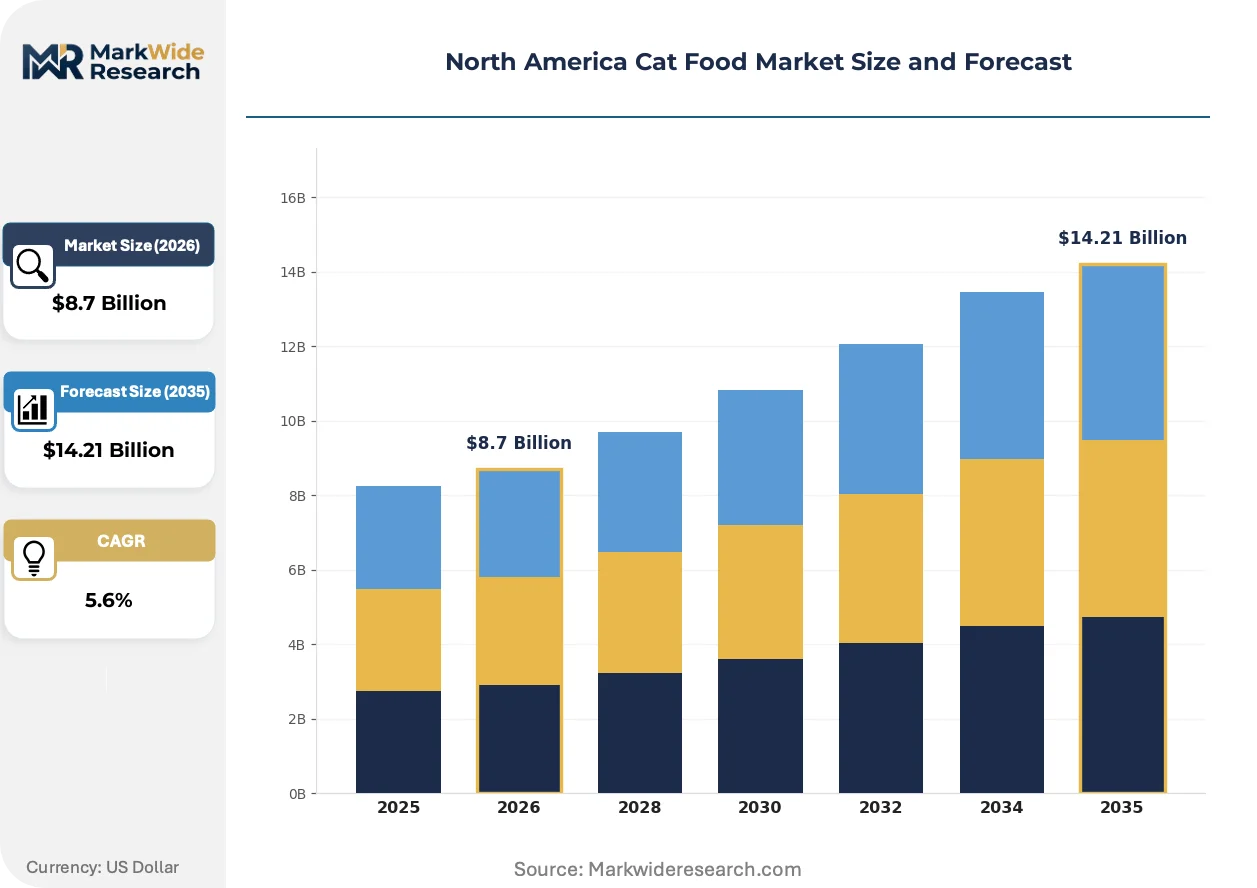
Humanization of pet ownership among urban millennials is compressing product lifecycles and fragmenting price tiers across wet, dry, and fresh formats. The FDA Center for Veterinary Medicine's evolving safety mandates are forcing reformulation investments that favor capitalized multi-brand operators over regional challengers.
Growth Catalysts
- FDA ingredient safety mandates:Stricter labeling and additive approval protocols elevate compliance barriers that filter out subscale competitors, consolidating shelf access for certified manufacturers.
- Millennial urban household formation:Density in coastal metropolitan corridors concentrates demand for premium wet formats with elevated palatability and convenience packaging.
- Veterinary channel expansion:Prescription diet lines tethered to clinical recommendations build recurring revenue streams and insulate against mass retail price erosion.
Market Restraints
- Animal protein input volatility:Chicken and fish meal prices fluctuate with commodity feed markets and aquaculture harvest cycles, compressing margin predictability for mid-tier brands.
- Midwest production concentration:Extrusion and canning capacity clusters in Kansas, Nebraska, and Iowa create geographic vulnerability to weather-related logistics disruptions.
- Novel protein regulatory friction:Insect and cultivated meat alternatives face undefined approval pathways at FDA, delaying commercialization timelines.
Strategic Opportunities
- Canadian market underpenetration:Premium fresh and raw formats hold minimal share versus the United States, offering first-mover expansion potential in Toronto and Vancouver metro areas.
- Direct-to-consumer subscription models:Portion-customized meal plans bypass retail slotting fees and capture lifetime value through automated replenishment.
- Functional additive convergence:Probiotic and omega-3 fortification addresses digestive and coat health concerns, commanding price premiums in specialty channels.
Industry Challenges
- Veterinary nutritionist scarcity:Formulation of prescription diets requires board-certified specialists, creating hiring bottlenecks for R&D expansion.
- Legacy ERP integration:Traceability mandates from FDA demand lot-level tracking that conflicts with decades-old manufacturing software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Cat Food Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Raw Food Ingredient Type: Meat-Based, Fish-Based, Grain-Free, Organic Packaging Type: Bags, Cans, Pouches, Bulk Distribution Channel: Pet Stores, Supermarkets, E-Commerce, Specialty Shops |
| Companies Covered | Mars Incorporated, Nestle Purina PetCare, Colgate-Palmolive Company, General Mills Inc., Schell & Kampeter Inc., The J.M. Smucker Company, WellPet LLC, Royal Canin SAS, Champion Petfoods, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Cat Food Market Trends and Innovations
Reformulation priorities are pivoting from grain-free positioning toward limited-ingredient and functional additive architectures. Digital tools are penetrating quality assurance and supply chain verification. Regulatory scrutiny of novel proteins is intensifying ahead of commercial viability.
Blockchain-based supply chain verification is digitizing ingredient provenance tracking from slaughterhouse to retail shelf. Premium and prescription manufacturers are adopting distributed ledger systems fastest, pressured by FDA traceability mandates and retailer liability concerns. This transparency infrastructure is digitizing competitive differentiation, compressing the advantage window for opaque sourcing practices.
The FDA's ongoing investigation into dilated cardiomyopathy linkages to grain-free formulations has forced explicit disclosure of carbohydrate sources and taurine supplementation levels. Reformulation costs have redirected R&D budgets toward legume and pulse alternatives. Wet food and veterinary diet segments are responding fastest, as these categories carry higher clinical scrutiny and recall exposure.
Subscription-based fresh food delivery is displacing mass retail purchasing among coastal urban households with single-cat and dual-cat configurations. Direct-to-consumer brands bypass slotting fees and capture recurring revenue through portion-customized meal plans. California and New York metropolitan corridors exhibit the highest conversion rates, driven by convenience prioritization and humanization of feeding rituals.
North America Cat Food Market Segmentation
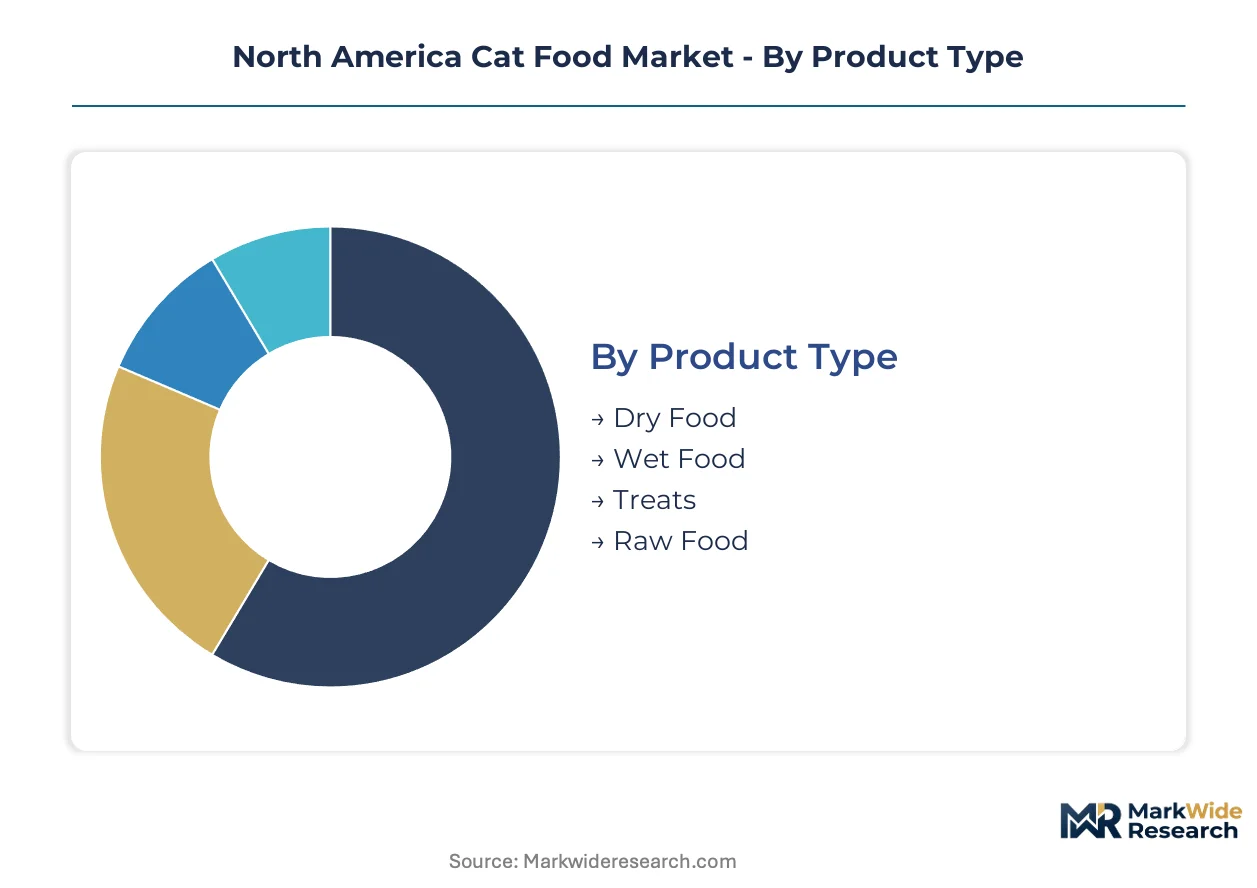
Segmentation in North American cat food reveals how formulation choices, packaging formats, and channel access stratify purchasing behavior. Manufacturers align R&D and distribution investments to capture value across these divides.
Product Type:
Mature dry formats coexist with emerging fresh and raw alternatives as palatability expectations shift.
- Dry Food:Extruded kibble with six to ten percent moisture content delivers storage stability and dental abrasion benefits. Mass retail chains in the US Midwest and South anchor volume, though growth flattens as wet alternatives gain coastal urban traction.
- Wet Food:Canned or pouched formulations with sixty to eighty percent moisture content command premium shelf positioning through elevated palatability. Veterinary recommendations and single-serve convenience drive expansion in Toronto, Vancouver, and coastal US metropolitan corridors.
- Treats:Supplementary morsels with functional additive positioning address dental health and behavioral training needs.
- Raw Food:Minimally processed frozen or freeze-dried proteins target biologically appropriate feeding philosophies in specialty retail channels.
Dry food handles the majority of throughput; raw food is the fastest mover on share.
Ingredient Type:
Cost tiers separate commodity formulations from certified specialty positioning.
- Meat-Based:Poultry and red protein meals supply amino acid profiles aligned with obligate carnivore requirements. Kansas and Nebraska slaughterhouse proximity reduces input costs for regional manufacturers serving mass-market channels.
- Fish-Based:Tuna, salmon, and whitefish meals deliver omega-3 fatty acids for coat and cognitive health. Pacific Northwest aquaculture linkages and import dependencies from Alaskan fisheries create price volatility that specialty brands absorb through premium positioning.
- Grain-Free:Legume and pulse carbohydrate substitutes replaced cereal grains following FDA cardiomyopathy investigations.
- Organic:USDA-certified ingredients with restricted pesticide and antibiotic exposure target health-conscious urban households.
Meat-based formulations dominate volume; organic certification is climbing the fastest on share.
Packaging Type:
Volume economics and convenience imperatives fragment container selection across retail formats.
- Bags:Multi-layer polymer or paperboard containers protect dry kibble from oxidation and moisture ingress. Big-box retailers and warehouse clubs in Texas and California prefer bulk bag configurations for inventory turns.
- Cans:Steel or aluminum containers with easy-open lids preserve wet food sterility and shelf stability. Veterinary clinics and independent pet stores stock single-serve cans for prescription diet dispensing.
- Pouches:Flexible film containers reduce material weight and enable portion-controlled dispensing for urban single-cat households.
- Bulk:Unpackaged dry food distributed through refill stations addresses sustainability concerns in coastal metropolitan markets.
Bags handle the majority of throughput; pouches are expanding most quickly on share.
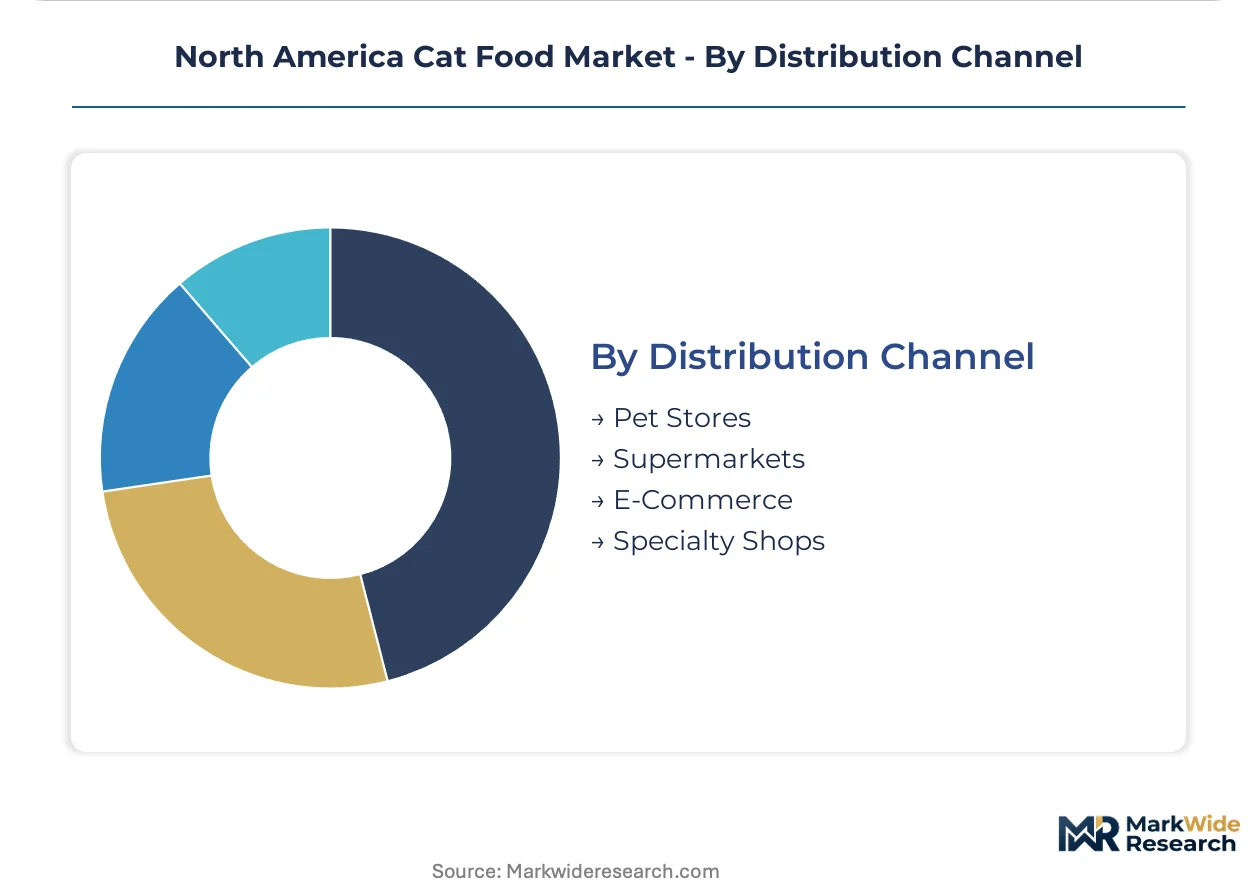
Distribution Channel:
Customer type and purchase occasion dictate channel selection and margin capture.
- Pet Stores:Dedicated retailers with trained staff guide formulation selection and loyalty program enrollment. PetSmart and Petco footprints concentrate in suburban corridors surrounding Dallas, Houston, and Atlanta.
- Supermarkets:Mass-market grocery chains stock mid-tier dry and wet portfolios for convenience purchasing. Walmart and Kroger distribution networks penetrate rural and exurban markets underserved by specialty retailers.
- E-Commerce:Direct-to-consumer platforms and marketplace listings enable subscription replenishment and novel protein access. Chewy and Amazon fulfillment centers in Pennsylvania and Nevada compress delivery windows for coastal urban subscribers.
- Specialty Shops:Independent retailers curate premium, raw, and regional brands with consultation-intensive service models.
Pet stores handle the majority of throughput; e-commerce is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extrusion and canning capacity clusters in Kansas, Nebraska, and Iowa create geographic vulnerability to weather-related logistics disruptions. FDA Center for Veterinary Medicine oversight and AAFCO nutrient standards govern cross-border product flows between the three North American markets. Each national market exhibits distinct demand concentrations and regulatory compliance requirements.
United States
Coastal metropolitan corridors in California and New York drive premium wet food demand through convenience prioritization and humanization trends. FDA ingredient safety mandates and state-level inspection protocols in California and Texas add supplementary compliance layers. Kansas and Nebraska host major extrusion facilities serving mass-market dry food distribution.
Canada
Toronto and Vancouver metro areas concentrate demand for veterinary-recommended wet formats with limited penetration of fresh and raw alternatives. Canadian Food Inspection Agency regulations govern import compliance and cross-border product flows from US production facilities. Ontario and Quebec distribution networks channel mid-tier dry portfolios through mass retail chains.
Mexico
Mexico City metropolitan area anchors volume demand for economy-tier dry formulations through supermarket and warehouse club channels. COFEPRIS oversight of pet food labeling and additive safety creates regulatory friction for premium imported brands. Northern border states facilitate maquiladora-adjacent packaging operations serving US Southwest markets.
North America Cat Food Market Competitive Landscape
Vertically integrated multinationals and specialty formulation houses split the market between scale-driven cost discipline and premium positioning. The competitive structure favors capitalized operators capable of absorbing FDA-mandated reformulation investments. Three archetypes dominate: diversified consumer goods conglomerates with captive protein sourcing, veterinary-channel specialists with prescription diet portfolios, and biologically-appropriate challengers with specialty retail access. Consolidation pressure operates through M&A absorption of regional brands and capacity expansion into underpenetrated Canadian markets.
Within the diversified conglomerate tier, Mars Incorporated and Nestle Purina PetCare represent scale-driven archetypes with integrated supply chain control. Champion Petfoods occupies a position exemplifying the biologically-appropriate specialist model. These three anchors illustrate the strategic divergence between mass-market volume capture and premium-tier margin extraction.
| Leading Market Players |
|---|
| Mars Incorporated |
| Nestle Purina PetCare |
| Colgate-Palmolive Company |
| General Mills Inc. |
| Schell & Kampeter Inc. |
| The J.M. Smucker Company |
| WellPet LLC |
| Royal Canin SAS |
| Champion Petfoods |
| Others |
Pricing and Supply Chain Analysis
Kansas-Nebraska-Iowa extrusion and canning clusters concentrate manufacturing capacity for mass-market dry formats, concentrating upstream negotiating leverage among protein meal suppliers and compressing margin pools for mid-tier brands unable to secure captive supply arrangements.
Pricing Analysis
FDA Center for Veterinary Medicine ingredient safety mandates dictate the pricing tier structure through compliance cost differentiation. Three-tier pricing separates veterinary prescription lines from premium wet formats and economy dry portfolios. Certification investment and clinical validation requirements widen price spreads between prescription and mass-market tiers. Cost compression in mid-tier dry segments is intensifying because private-label entrants erode legacy brand premiums. Economy-tier buyers in Midwest and Southern mass retail channels exhibit highest price sensitivity; prescription diet purchasers through veterinary clinics demonstrate lowest sensitivity due to clinical recommendation lock-in.
Supply Chain Analysis
Animal protein feedstock sourcing draws from Kansas and Nebraska slaughterhouse clusters for poultry meal, Pacific Northwest aquaculture operations for salmon and whitefish inputs, and Alaskan import channels for specialty fish meals. Corn and soy derivatives from Iowa and Illinois elevators supply carbohydrate fractions for extruded kibble. Commodity price volatility in chicken and fish meal markets creates margin unpredictability for non-integrated operators. Distribution runs through mass retail chains in Texas and California, veterinary clinic networks in coastal metropolitan corridors, and direct-to-consumer fulfillment centers in Pennsylvania and Nevada.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based fresh food delivery platforms are reconfiguring customer acquisition economics, creating interoperability demands between portion-customization algorithms and automated replenishment infrastructure that favor digitally native entrants over legacy ERP-constrained operators.
For Market Incumbents: Build regulatory compliance moats through preemptive FDA traceability system investments that regional challengers cannot replicate. Champion Petfoods and Nestle Purina PetCare should deepen backward integration into named protein sourcing to insulate against commodity volatility. Mars Incorporated can extend veterinary channel control through prescription diet line expansion, defending against direct-to-consumer fresh brands eroding coastal urban share. For New Entrants and Emerging Players: Canadian metropolitan underpenetration in Toronto and Vancouver offers white-space capture for premium fresh and raw formats with minimal incumbent specialization. Direct-to-consumer subscription models bypass retail slotting fee structures that concentrate mass-market access. Functional additive positioning around probiotic and omega-3 fortification provides differentiable entry angle in specialty retail channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated operators with captive protein sourcing and digital fulfillment infrastructure. Long-term viability rests on FDA compliance scalability and subscription platform economics. Acquisition target archetype: regional fresh-format brands with Toronto or Vancouver distribution footholds and portion-customization technology assets. Signal to watch: FDA approval pathway clarity for insect and cultivated meat alternatives as inflection indicator for novel protein R&D valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Expansion | Prescription diet partnerships with VCA and Banfield networks build recurring revenue insulation against mass retail price erosion. |
| Direct-to-Consumer Platform Launch | Subscription meal plans bypass PetSmart and Petco slotting fees while capturing lifetime value through automated replenishment. |
| Backward Integration into Protein Sourcing | Captive supply of Kansas and Nebraska poultry meal reduces input cost volatility for extruded kibble portfolios. |
| Functional Additive Fortification | Probiotic and omega-3 positioning commands price premiums in independent pet stores and specialty retail channels. |
| Canadian Market Entry | Toronto and Vancouver distribution buildout addresses underpenetration of fresh and raw formats versus US coastal markets. |
Research Methodology
Cross-validation between primary interviews with veterinary nutritionists, pet retail category managers, and FDA regulatory affairs specialists and secondary validation through AAFCO nutrient profile databases, FDA Center for Veterinary Medicine enforcement records, and Nielsen retail audit data anchors the qualitative findings. Bottom-up volume modeling from facility-level production capacity and top-down demand triangulation from household pet ownership surveys converge on segment-level estimates.
Calibration against historical volume trajectories and elasticity-adjusted price response patterns shapes the analytical framework across the projection horizon. Segmentation dimensions include product type, ingredient certification tier, packaging format, and distribution channel intensity. CAGRs derive from trend extrapolation moderated by regulatory event probability and capacity expansion timelines. Forecast inputs incorporate FDA reformulation cost assumptions and subscription platform adoption curves in coastal metropolitan corridors.
Practitioners should monitor FDA novel protein approval pathway developments, commodity feed price spikes, and direct-to-consumer churn rates for early signals of forecast revision. Cross-checking against AAFCO annual meeting proceedings and Canadian Food Inspection Agency import compliance bulletins is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dog Perfume Market
Pet Care Products
Pet Rugs Market
Pet Care Products
Asia Pacific Pet Diet Market
Pet Care Products
GCC Organic and Natural Pet Food Market
Pet Care Products
Dog Water Bottle Market
Pet Care Products
Pet Treats Market
Pet Care Products
Cat Diffuser Market
Pet Care Products
Pet Transport Cage Market
Pet Care Products
Dog Vitamins Market
Pet Care Products
Dog Carrier Bags Market
Pet Care Products
UK Pet Grooming Market
Pet Care Products
Indonesia Pet Care Market
Pet Care Products
Cat Mat Market
Pet Care Products
High Fiber Dog Food Market
Pet Care Products
Dog Food Market
Pet Care Products
Pet Molar Bite Toy Market