
 Dog Float Market | 2026-2036
Dog Float Market Size, Share, and Industry Trends Forecast 2026-2036
Dog Float Market Outlook
Modular sizing configurations is decoupling purchase decisions from breed-weight assumptions, letting buyers mix components across product lines. Ruffwear leverages its technical outdoor heritage to command premium positioning in backcountry water sports. Outward Hound competes through mass-channel distribution breadth and price-accessible SKUs. EzyDog anchors its presence in Australian and North American specialty retail with harness-integrated float designs.
A dog float is a buoyancy-aid device engineered to support canine weight in water, typically constructed from welded vinyl bladders, closed-cell foam, or coated fabric shells rated for specific poundage capacities, designed to prevent drowning risk during supervised aquatic activity. Inflatable floats dominate volume due to storage convenience and travel portability, while hard shell variants capture margin pools among competitive dock-diving and water rescue training segments. Fabric and mesh materials are gaining specification share in premium tiers as breathability and quick-dry performance become purchase criteria.
The US Consumer Product Safety Commission and ASTM International shape baseline flotation performance standards, while the EU's REACH regulation governs phthalate restrictions in vinyl constructions sold across European member states. California's Proposition 65 labeling requirements add compliance layers for products containing certain chemical compounds. Stakeholders must monitor evolving state-level pet product safety legislation and material disclosure mandates as these frameworks increasingly dictate market access conditions.
Market Dynamics
Modular sizing configurations are decoupling purchase decisions from breed-weight assumptions, letting buyers mix components across product lines. This structural shift is fragmenting SKU strategies and compressing inventory holding costs for specialty retailers.
Growth Catalysts
- Coastal recreation demand:California and Florida beach communities generate concentrated adoption of swim-assist flotation devices for supervised canine aquatic activity.
- REACH phthalate restrictions:The EU's chemical governance framework is pushing vinyl manufacturers toward compliant alternative formulations in European member states.
- Closed-cell foam innovation:Material science advances in buoyancy-rated foam cores are enabling lighter-weight designs without sacrificing poundage capacity ratings.
Market Restraints
- Petroleum-based input volatility:Welded vinyl bladder production faces raw material cost exposure from PVC resin and plasticizer supply chains concentrated in Gulf Coast petrochemical corridors.
- California Proposition 65 compliance:Chemical compound labeling mandates add regulatory friction and litigation exposure for products containing certain phthalates or heavy metals.
- Hard shell substitution ceiling:Inflatable designs dominate volume due to storage convenience, limiting margin expansion for rigid hull variants in recreational segments.
Strategic Opportunities
- Dock-diving competition expansion:Performance water sports segments in Texas and North Carolina present underpenetrated demand for competition-grade flotation with integrated harness points.
- Specialty retail channel integration:Independent outdoor outfitters are consolidating shelf space for technical pet gear, creating margin pools for harness-integrated float designs.
- ASTM International standardization:Emerging baseline flotation performance standards offer first-mover certification advantages for testing protocol compliance.
Industry Challenges
- Canine biomechanics expertise gap:Product development teams lack veterinary rehabilitation specialists to optimize flotation geometry for breed-specific swimming mechanics.
- Multi-jurisdiction certification timelines:Simultaneous US Consumer Product Safety Commission review and EU REACH dossier preparation extend commercialization cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dog Float Market |
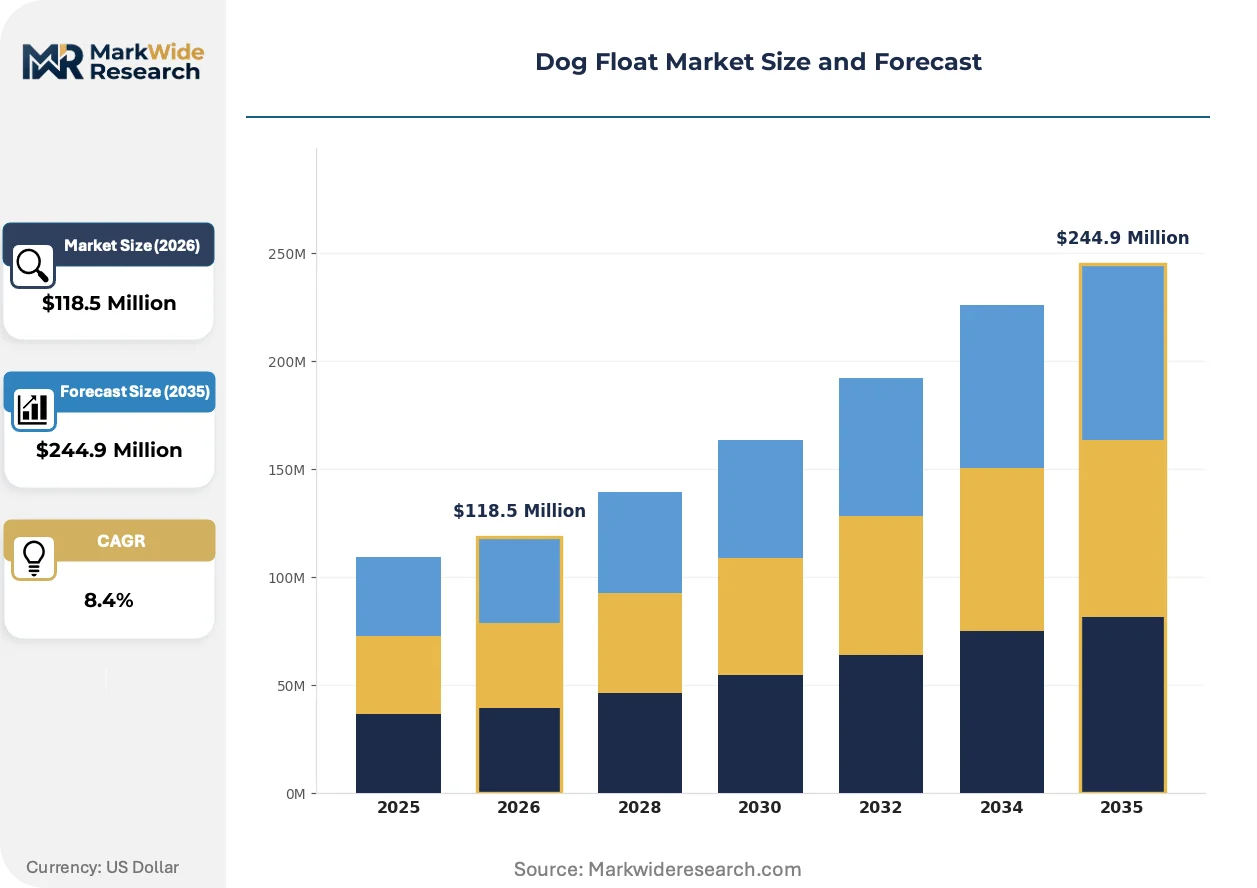
| Market Size in 2026 | $118.5 Million |
| Market Size in 2035 | $244.9 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inflatable Floats, Hard Shell Floats, Hammock Floats, Floating Beds Material: Vinyl, Fabric, Rubber, Mesh Size: Small, Medium, Large, Extra Large Feature: Swim Assistance, Safety Handle, UV Resistant, Storage Pocket |
| Companies Covered | Ruffwear, Outward Hound, EzyDog, Kurgo, Paws Aboard, PetSafe, West Paw Design, Petco Animal Supplies, Spin Master, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dog Float Market Strategic Shifts
Welded vinyl construction methods are encountering displacement pressure from advanced textile composites. Three convergent forces are reshaping material specification, regulatory compliance architecture, and channel economics across the forecast window.
Coated fabric shells with welded seam technology are absorbing specification share from traditional vinyl bladders in premium tiers. Dock-diving training facilities and water rescue programs in the Pacific Northwest are specifying these constructions for abrasion resistance. The shift is absorbing margin from commodity inflatable producers while compressing warranty claim rates for technical outdoor retailers.
ASTM International is developing baseline flotation performance standards for aquatic pet gear. The framework will mandate poundage capacity verification and material degradation testing under simulated saltwater exposure. California-based manufacturers are pre-positioning compliance documentation to capture certification-driven preference shifts in specialty channels.
Buyers are unbundling after-sales service from product purchase, treating flotation devices as disposable seasonal equipment rather than durable goods. Mass-channel distributors in the Southeast are responding with private-label SKUs priced for single-season replacement cycles. This behavioral pivot is most visible in Florida beach communities where storage constraints limit off-season inventory retention.
Dog Float Market Segmentation
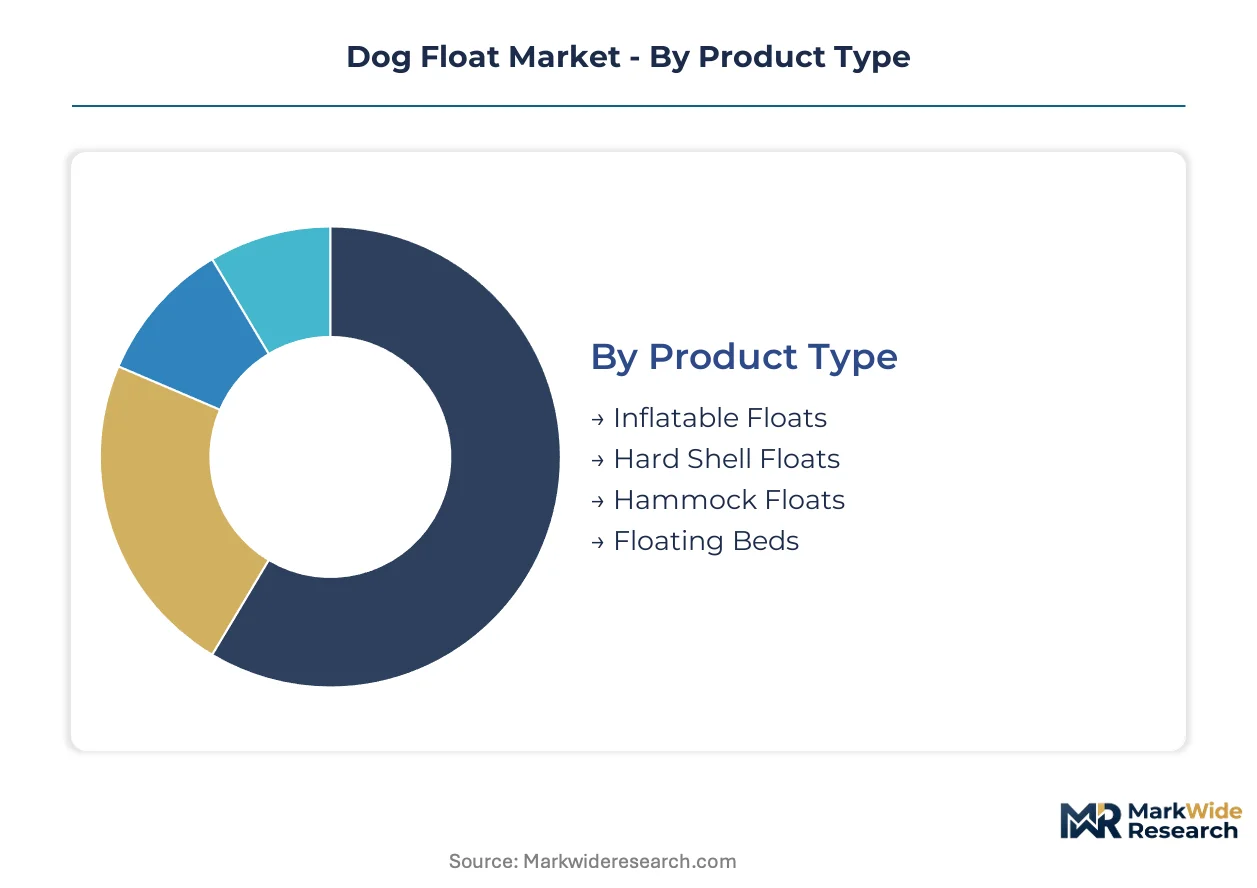
Product architecture in the dog float market fragments across construction methods, material specifications, and functional add-ons that reshape buyer calculus. Coastal recreation patterns and competitive water sports participation create divergent demand profiles that reward targeted portfolio construction.
Product Type:
Buyers in this category sort by storage constraints versus performance requirements, with recreational portability pulling toward inflatables and competition durability toward rigid constructions.
- Inflatable Floats:Welded vinyl bladder construction enables deflation for compact storage and airline travel compliance. Florida beach communities and California coastal counties generate concentrated demand where seasonal use patterns favor packable solutions.
- Hard Shell Floats:Molded polyethylene or composite hulls deliver puncture resistance and consistent buoyancy geometry for dock-diving training. Texas and North Carolina competitive circuits specify these for repeated impact tolerance.
- Hammock Floats:Suspended mesh platforms cradle dogs in partial submersion for cooling. Popular in Arizona and Nevada lake recreation zones.
- Floating Beds:Rigid foam-core platforms with elevated sleeping surfaces target houseboat and marina dwellers. Niche adoption in Pacific Northwest coastal communities.
Inflatable Floats lead volumes today; Hard Shell Floats are gaining share fastest in competitive segments.
Material:
Specification decisions here trace regulatory exposure and climate conditions, with chemical compliance mandates in European markets diverging from abrasion priorities in North American outdoor retail.
- Vinyl:PVC formulations with welded seam construction dominate mass-channel price points. REACH phthalate restrictions are forcing reformulation toward bio-based plasticizers for EU market access.
- Fabric:Coated nylon and polyester shells with welded seam technology absorb specification share in premium tiers. Dock-diving facilities in Oregon and Washington specify these for abrasion resistance.
- Rubber:Natural and synthetic rubber compounds offer puncture recovery and cold-weather flexibility. Limited adoption in Great Lakes region seasonal use.
- Mesh:Quick-dry synthetic weaves enable breathability and reduced water retention. California manufacturers are pre-positioning these for ASTM certification alignment.
Vinyl retains volume leadership; Fabric is expanding most quickly in specialty channels.
Size:
Modular sizing configurations are decoupling purchase decisions from breed-weight assumptions, letting buyers mix components across product lines rather than accepting fixed breed-based recommendations.
- Small:Rated for dogs under 25 pounds with compact bladder geometry. Urban coastal markets in San Diego and Miami show concentrated adoption for toy breeds.
- Medium:The reference specification for retrievers and shepherds in recreational water sports. Captures the broadest SKU distribution across mass and specialty channels.
- Large:Reinforced construction for dogs 60-90 pounds with expanded buoyancy chambers. Growing specification in Great Dane and Mastiff owner segments.
- Extra Large:Custom-fabricated or reinforced standard designs for giant breeds over 90 pounds. Limited production runs from specialty manufacturers.
Medium dominates unit volumes; Large is climbing the fastest as giant breed ownership expands.
Feature:
Functional add-ons are reshaping price realization and channel placement, with safety integration commanding premium positioning and convenience features driving mass-market differentiation.
- Swim Assistance:Integrated buoyancy distribution and ergonomic cutouts support dogs with limited swimming ability or post-surgical rehabilitation needs. Veterinary rehabilitation clinics in Colorado and Utah are specifying these for hydrotherapy programs.
- Safety Handle:Reinforced grab points for human retrieval of distressed dogs. Water rescue training programs in the Pacific Northwest mandate these for certification compliance.
- UV Resistant:Stabilized material formulations prevent degradation under prolonged sun exposure. Standard specification for Florida and Arizona outdoor retail.
- Storage Pocket:Integrated compartments for treats, waste bags, or retrieval toys. Mass-channel SKUs in the Southeast use these as price-tier differentiators.
Swim Assistance leads feature-driven pricing; Safety Handle is gaining specification fastest in professional training segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The dog float industry traces its commercial origins to coastal California and Florida, where recreational boating culture first created sustained demand for canine aquatic safety equipment during the 1990s. This beach-community foundation established material specifications and sizing conventions that subsequently diffused to inland lake recreation zones and competitive water sports circuits.
United States
California and Florida beach communities generate concentrated adoption of swim-assist flotation devices for supervised canine aquatic activity. The US Consumer Product Safety Commission shapes baseline material safety standards for aquatic pet gear sold across state lines. Dock-diving training facilities in Austin, Texas and Raleigh, North Carolina specify competition-grade hard shell constructions for repeated impact tolerance.
Canada
Great Lakes region seasonal use patterns favor cold-weather flexibility in rubber and synthetic compounds for abbreviated summer recreation windows. Health Canada's national product safety regulator monitors phthalate content in vinyl constructions imported from US and Asian suppliers. Vancouver Island and Gulf Islands marinas in British Columbia anchor niche demand for floating bed platforms among houseboat dwellers.
Germany
EU REACH phthalate restrictions are forcing vinyl manufacturers toward bio-based plasticizer formulations for market access across European member states. The country's central pet product safety authority enforces chemical disclosure mandates that exceed baseline EU requirements. Bavarian lake districts and North Rhine-Westphalia reservoir communities concentrate specialty retail distribution for technical outdoor pet gear.
Australia
EzyDog anchors its presence in Australian specialty retail with harness-integrated float designs targeting coastal recreation demand. The Therapeutic Goods Administration's national product safety framework governs material degradation standards for aquatic equipment. Sydney Harbour and Gold Coast marina clusters generate sustained specification for UV-resistant stabilized formulations under prolonged sun exposure.
United Kingdom
Veterinary rehabilitation clinics in Surrey and Oxfordshire specify swim-assistance features for post-surgical hydrotherapy programs. The country's national standards body participates in ASTM International protocol development for baseline flotation performance verification. Lake District national park communities and Scottish Highlands loch recreation zones concentrate adoption among retriever and shepherd owner segments.
Dog Float Market Competitive Environment
Premium-margin players sit above commodity-margin players across material specification and channel placement dimensions, with technical outdoor heritage commanding shelf space in specialty retail while mass-channel distributors compete on price-accessible SKU breadth. The vendor base organizes into three strategic archetypes: technical outdoor specialists leveraging backcountry credibility, mass-market distributors optimizing for storage convenience and travel portability, and veterinary-aligned developers targeting rehabilitation and hydrotherapy specifications. Dominant competitive moves include portfolio diversification into harness-integrated designs and geographic expansion through specialty retail channel consolidation.
Within the technical outdoor tier, Ruffwear leverages its backcountry water sports heritage to command premium positioning, while Outward Hound competes through mass-channel distribution breadth. EzyDog anchors presence in Australian and North American specialty retail. These three players exemplify the archetype spectrum from performance-grade specifications to price-accessible volume plays.
| Leading Market Players |
|---|
| Ruffwear |
| Outward Hound |
| EzyDog |
| Kurgo |
| Paws Aboard |
| PetSafe |
| West Paw Design |
| Petco Animal Supplies |
| Spin Master |
| Others |
Value Chain & Pricing Dynamics
REACH phthalate restrictions in European markets are compelling vinyl manufacturers toward bio-based plasticizer reformulations, forcing supply-side retooling that compresses margins on mass-market SKUs while creating premium capture opportunities for compliant alternative materials. This specification-driven sourcing pivot concentrates pricing power with fabric and mesh suppliers capable of certifying ASTM-aligned constructions.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Ruffwear-grade technical specifications from mass-channel inflatable volumes. Price differentiation hinges on ASTM certification alignment and harness- integration complexity, with certified constructions commanding shelf-space premiums in specialty outdoor retail. Cost compression in the economy tier is intensifying because private-label distributors in Florida and Arizona are optimizing for single-season replacement cycles. Mass-channel buyers exhibit highest price sensitivity; dock-diving training facilities show least sensitivity due to performance mandates.
Supply Chain Analysis
California Proposition 65 compliance requirements are reshaping domestic-content mandates for manufacturers serving US West Coast distribution. PVC resin and plasticizer supply concentrates in Gulf Coast petrochemical corridors, with welded bladder assembly anchored in Guangdong and Zhejiang manufacturing zones. Raw material dependencies include petroleum-based vinyl formulations, closed-cell foam cores from South Korean suppliers, and coated nylon textiles from Taiwan. Single-source vulnerability runs through Gulf Coast resin concentration exposed to hurricane disruption. Distribution runs through mass-channel pet retailers, independent outdoor outfitters, and veterinary rehabilitation clinic direct procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dog float market compounds steadily as coastal recreation participation and competitive water sports enrollment create durable replacement demand. Pet humanization trends sustain premiumization across all tiers.
For Market Incumbents: Deepen ASTM certification investment to capture first-mover advantage as baseline flotation performance standards finalize, while extending harness-integrated designs into veterinary rehabilitation channels. Defend against fabric-shell substitution by locking coated textile supply agreements with Pacific Northwest abrasion-resistant specification leaders. Prioritize backward integration into closed-cell foam core production to insulate margin from petroleum input volatility. For New Entrants and Emerging Players: Giant breed owners underserved by standard sizing configurations represent a concentrated white-space target, with custom-fabricated extra-large designs commanding 40-60% price premiums over mass-market SKUs. Texas and North Carolina dock-diving circuits offer penetrable competitive segments where hard shell durability specifications exceed current supply. Pursue specialty retail channel integration through technical outdoor outfitter consolidation rather than mass-market shelf-space competition. For Investors and Strategic Acquirers: Asymmetric upside sits with veterinary-aligned developers possessing hydrotherapy program relationships and rehabilitation specialist networks. Five-to-ten year viability rests on ASTM standardization completion and subsequent certification barrier formation. Monitor California state-level pet product safety legislation expansion as inflection signal for compliance-driven market access tightening.| Strategic Initiative | Industry Significance |
|---|---|
| ASTM Certification Investment | First-mover positioning captures specialty channel preference as baseline flotation standards finalize. |
| Harness-Integrated Design Extension | Veterinary rehabilitation clinic penetration opens premium pricing pools in hydrotherapy segments. |
| Specialty Retail Channel Consolidation | Independent outdoor outfitter shelf-space aggregation creates margin pools for technical specifications. |
| Alternative Material Formulation | Bio-based plasticizer and coated fabric pivots satisfy REACH compliance and Proposition 65 mandates. |
| Modular Sizing Platform Development | Component-mix architectures reduce inventory holding costs for specialty retailers serving diverse breeds. |
Study Parameters
Bottom-up coastal recreation demand modeling reconciled against top-down welded vinyl and coated fabric production tracking forms the analytical core of this study. Primary interviews with product development directors at technical outdoor specialists, procurement leads at mass-channel pet retailers, veterinary rehabilitation clinic managers, and dock-diving training facility operators were cross-validated against secondary sources including US Consumer Product Safety Commission guidance documents, EU REACH dossier filings, ASTM International draft standard disclosures, and California Office of Environmental Health Hazard assessment notices. Trade data from USITC and Eurostat informed import volume triangulation.
Historical trendline analysis of inflatable versus hard shell specification share informed segmentation-level growth rate derivation across the projection horizon. The forecast framework models product type, material specification, size tier, and functional feature dimensions alongside geographic adoption patterns and regulatory compliance cluster evolution. CAGRs were synthesized from replacement cycle frequency data, coastal recreation participation rates, and competitive water sports enrollment trajectories. Closed-cell foam innovation timelines and ASTM standardization completion assumptions shaped material substitution velocity inputs.
Underlying measurement precision varies by segment; inflatable float volume estimates carry tighter precision than custom extra-large fabrication given production concentration visibility. Forecasts incorporate assumptions regarding REACH enforcement consistency and state-level pet product safety legislation diffusion that could revise trajectory if regulatory timelines accelerate or delay. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
United Kingdom Cat Litter Market
Pet Care Products
South Korea Pet Food Market
Pet Care Products
Pet Lodging Market
Pet Care Products
Philippines Pet Food Market
Pet Care Products
Small Breed Dog Food Market
Pet Care Products
Japan Organic and Natural Pet Food Market
Pet Care Products
Germany Pet Clothing Market
Pet Care Products
United States Pet Care and Services Market
Pet Care Products
Pet Care Ingredients Market
Pet Care Products
Pet Hotels Market
Pet Care Products
Dehydrated Pet Food Market
Pet Care Products
Toy Dog Market
Pet Care Products
Pet GPS Tracker Market
Pet Care Products
Cat Backpacks Market
Pet Care Products
Dog Safety Leash Market
Pet Care Products
Pet Transporting Service Market