
 Automatic and Smart Pet Feeder Market | 2026-2036
Automatic and Smart Pet Feeder Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic and Smart Pet Feeder Market Intelligence
Manufacturing expansion in China's Pearl River Delta is reconfiguring the supply chain for consumer electronics used in pet feeders. PETKIT leverages its strong design and engineering capabilities to command a premium in the smart feeder segment. In contrast, PetSafe sustains its market position through an extensive distribution network in North American pet specialty stores. WOPET competes by offering a wide range of affordable, timed feeders through online retail channels.
Automatic and smart pet feeders are electromechanical devices designed to dispense a pre-set quantity of pet food at scheduled intervals. Smart variants integrate Wi-Fi or Bluetooth connectivity, allowing for remote control, monitoring via smartphone apps, and sometimes video streaming. Wi-Fi Enabled models within the technology segment are seeing the highest investment, while basic Timed Feeders still constitute a significant volume base. Online Retail remains the dominant distribution channel, though Pet Specialty Stores are critical for demonstrating premium, feature-rich smart devices to consumers.
Product safety and material standards are governed by frameworks such as CE marking in the European Union and FCC regulations for wireless devices in the United States. These regulations ensure device reliability and the safety of materials in contact with pet food, influencing component selection. Future competitive advantage will hinge on a manufacturer's ability to integrate advanced health monitoring sensors while maintaining data privacy and security for the pet owner.
Market Dynamics
The convergence of consumer IoT technology with the growing trend of pet humanization is the central force shaping the automatic and smart pet feeder market. This dynamic is creating a new product category at the intersection of home automation and pet wellness.
Growth Catalysts
- Health Data Integration:The inclusion of sensors for tracking food consumption aligns with the consumer trend toward proactive, data-driven pet wellness.
- Urban Lifestyles:Growing pet ownership among busy professionals in dense urban centers creates strong demand for automated feeding convenience.
- Component Standardization:Compliance with FCC and CE regulations for electronic components assures consumers of device reliability and electrical safety.
Market Restraints
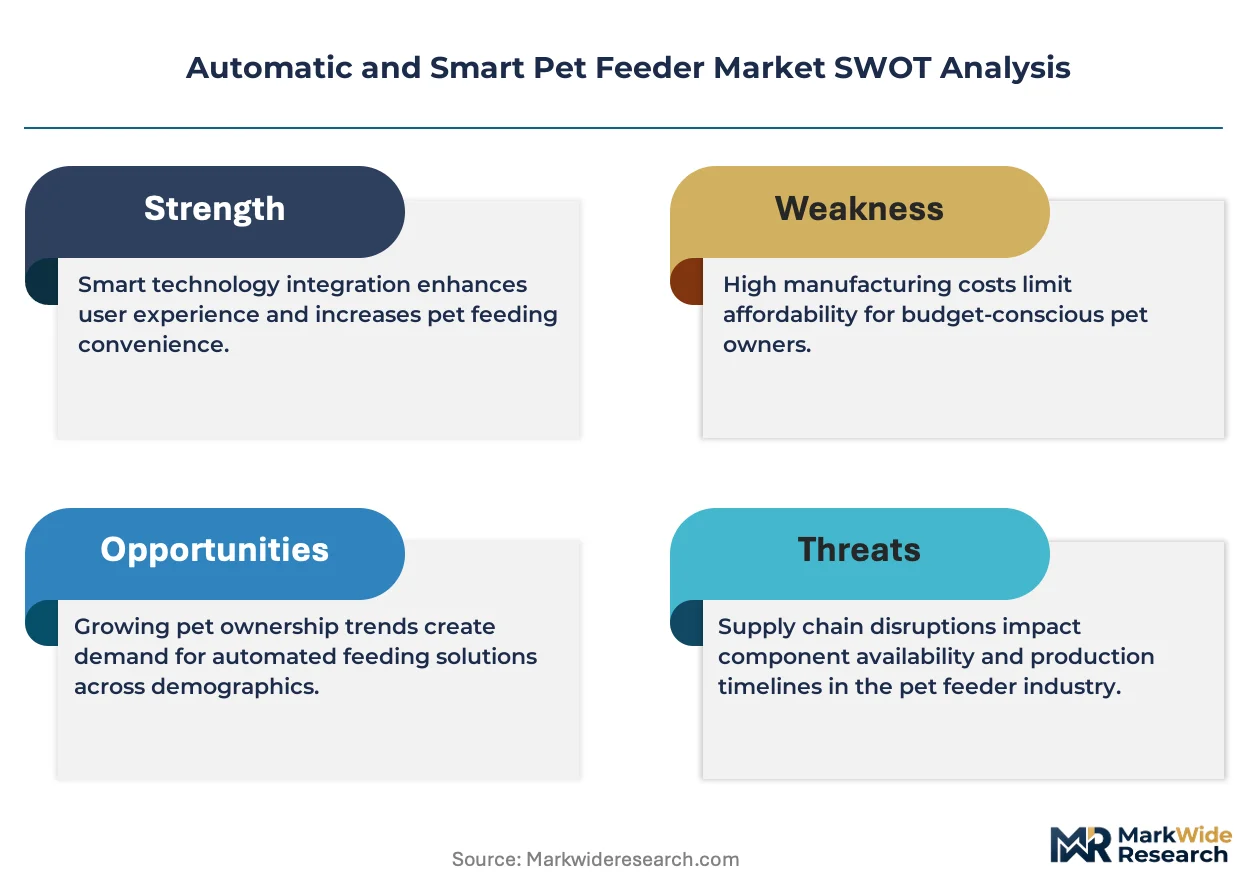
- Premium Pricing:The high initial cost of smart feeders with Wi-Fi connectivity limits adoption among price-sensitive consumers compared to basic timed models.
- Data Security Risks:Consumer concerns regarding the privacy of personal data and in-home video feeds collected by connected devices deter purchases.
- Supply Chain Concentration:Heavy reliance on electronics manufacturing within China's Pearl River Delta introduces risks of supply disruption.
Strategic Opportunities
- Veterinary Channel Integration:Linking feeder data to veterinary telehealth platforms enables remote health monitoring and prescription diet adherence.
- Specialized Medical Feeders:Developing feeders for pets with chronic conditions like diabetes addresses a key unmet need in the market.
- Expansion into East Asia:Significant growth potential exists in high-income, tech-savvy urban markets such as Tokyo and Seoul.
Industry Challenges
- Software and App Maintenance:Ensuring seamless app functionality and providing continuous security updates across diverse smartphone operating systems presents a significant operational challenge.
- Navigating Dual Compliance:Manufacturers face the complexity of simultaneously adhering to electronics standards like FCC/CE and separate food-contact material safety regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic and Smart Pet Feeder Market |
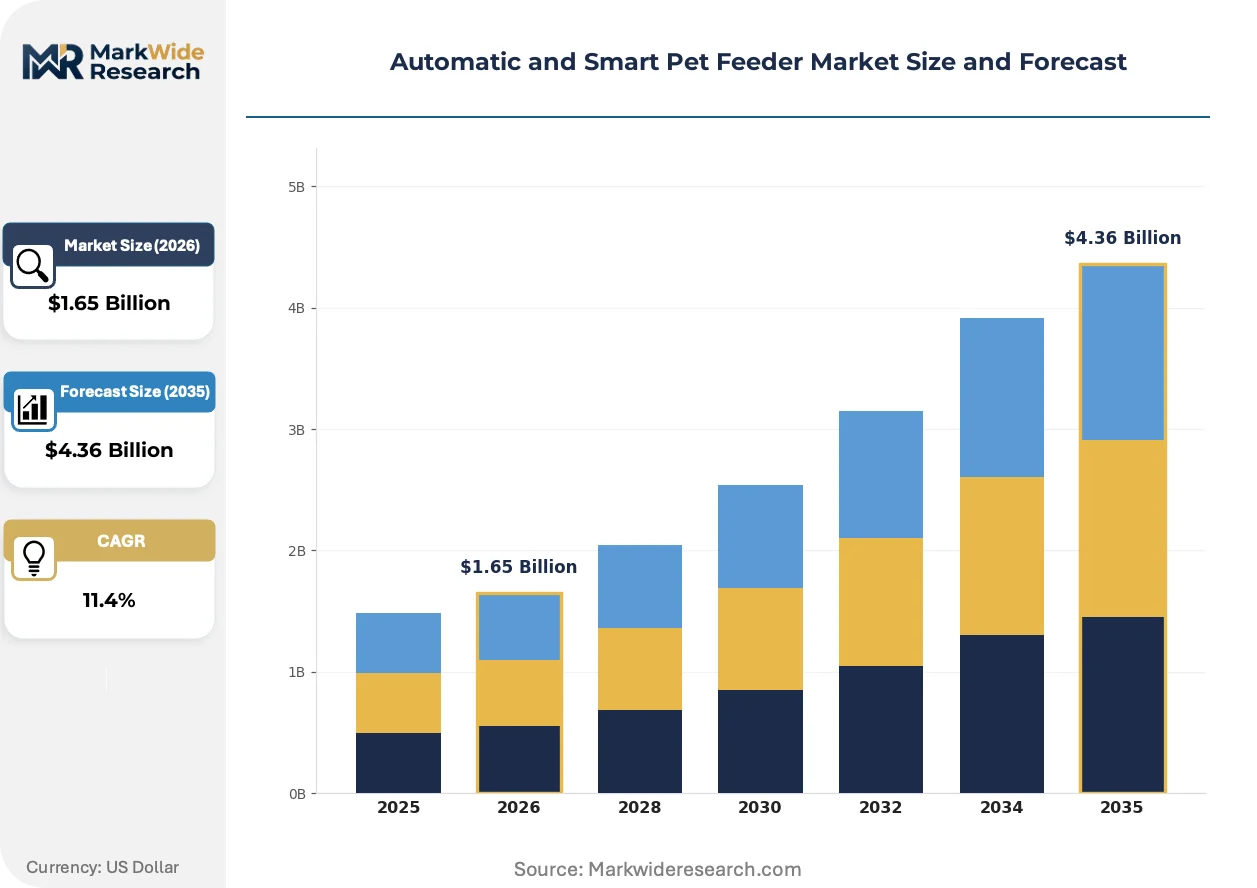
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $4.36 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Feeders, Smart Feeders, Timed Feeders, Portion Control Feeders End User: Pet Owners, Veterinary Clinics, Pet Boarding Facilities, Animal Shelters Technology: Wi-Fi Enabled, Bluetooth Enabled, Sensor-Based, Smartphone Controlled Distribution Channel: Online Retail, Pet Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Whisker, WOPET, PetSafe, Arf Pets, Catit, PETKIT, Petlibro, CATLINK, Sure Petcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic and Smart Pet Feeder Market Strategic Shifts & Innovations
Integration of artificial intelligence and data analytics is transforming smart feeders from simple dispensing tools into central hubs for pet health management. This shift creates value beyond convenience, focusing on proactive wellness monitoring for pets through connected hardware and software ecosystems.
Advanced sensor suites incorporating cameras and microphones are becoming more common in premium models. Pet owners, particularly those in high-income brackets, are adopting these features for enhanced monitoring capabilities. The integration of AI-powered analytics is digitizing the observation of pet behavior, allowing for the early detection of potential health or dietary issues from consumption patterns.
The European Union's General Data Protection Regulation (GDPR) sets a high bar for data privacy and security. This regulation directly impacts manufacturers of smart feeders that collect user information and video, forcing them to implement privacy-by-design principles. The smart feeder segment is most affected, often adopting these stringent standards globally to streamline product development.
A direct-to-consumer (DTC) sales model, amplified by social media marketing, is gaining significant traction for new market entrants. This channel shift allows brands to build a direct relationship with customers, bypassing the traditional gatekeepers of pet specialty and big-box retail. The trend is most visible in the North American market, where e-commerce for pet supplies is highly developed.
Automatic and Smart Pet Feeder Market Segmentation
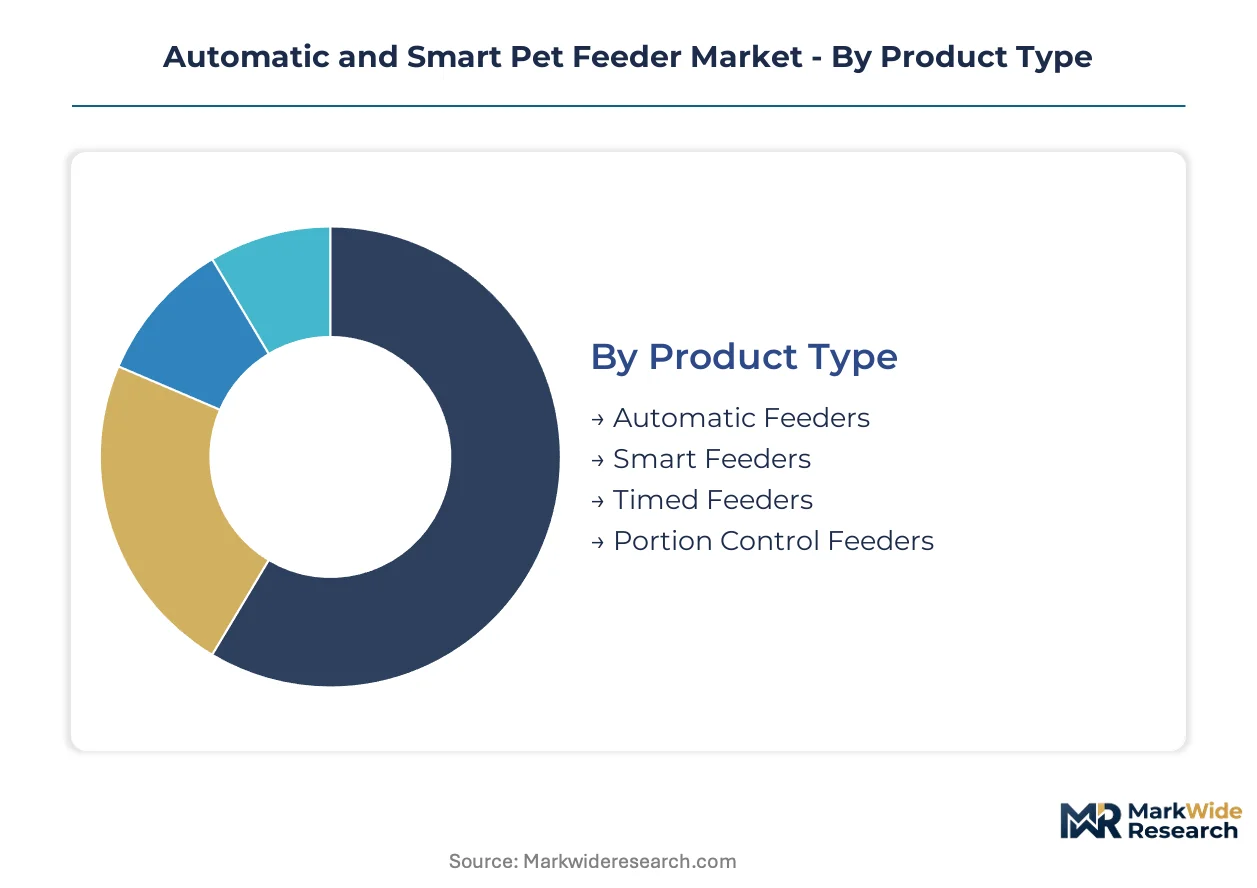
The automatic and smart pet feeder market segments highlight distinct product functionalities and end-user needs, enabling manufacturers to tailor offerings for specific consumer preferences. Understanding these divisions allows for targeted product development and optimized distribution strategies across the evolving pet care landscape.
Product Type:
Segments within product type exhibit varying innovation cycles, with advanced smart feeders experiencing rapid iteration compared to more established automatic models.
- Smart Feeders:These devices integrate Wi-Fi or Bluetooth connectivity, enabling remote control, monitoring via smartphone applications, and often video streaming. Demand concentrates in urban centers across the United States and Germany, driven by busy pet owners seeking convenience and advanced dietary management.
- Automatic Feeders:Electromechanical systems dispense pre-set food quantities at scheduled intervals, offering basic automation without advanced connectivity features. Demand is strong among pet owners prioritizing consistent feeding schedules and convenience in their daily routines.
- Timed Feeders:These basic models offer scheduled dispensing of pet food at pre-defined times, providing fundamental automation for pet owners.
- Portion Control Feeders:Devices designed to accurately dispense specific food quantities, supporting pet health management and adherence to veterinary dietary recommendations.
Timed Feeders anchor the volume base while Smart Feeders gain share at the steepest rate.
End User:
The market's end-user segmentation reveals diverse application scenarios, from individual pet households to professional animal care environments.
- Pet Owners:Individual consumers purchasing feeders for their companion animals within private residences, seeking solutions for feeding convenience, portion control, and pet monitoring. This segment represents the largest customer base, particularly in urban areas.
- Veterinary Clinics:Professional animal healthcare facilities utilizing specialized feeders for managing prescription diets, monitoring food intake for patients, or supporting remote telehealth initiatives. Integration with veterinary software platforms is a key requirement.
- Pet Boarding Facilities:Commercial establishments offering temporary accommodation for pets, where automated feeders provide consistent feeding schedules and reduce labor requirements.
- Animal Shelters:Non-profit or governmental organizations housing stray or abandoned animals, employing feeders for efficient and hygienic food distribution to multiple animals.
Demand from Pet Owners drives significant volume, while Veterinary Clinics represent a high-value niche.
Technology:
Technology segments reflect varying levels of connectivity and sensor integration, influencing device capabilities and user interaction.
- Wi-Fi Enabled:These feeders connect to home networks, allowing remote control, scheduling, and monitoring through smartphone apps from any location with internet access. This technology segment sees the highest investment due to its comprehensive remote management features.
- Sensor-Based:Feeders equipped with sensors for portion management, food level detection, or even pet presence, ensuring accurate dispensing and optimizing feeding routines. Integration of AI-powered analytics enhances their functionality for proactive wellness monitoring.
- Bluetooth Enabled:Devices using short-range wireless technology for local control and data transfer to a paired smartphone or tablet, offering a simpler connectivity option.
- Smartphone Controlled:Any feeder whose primary interface and control mechanism is a dedicated mobile application, providing a user-friendly experience for managing feeding schedules and settings.
Technological advancements in Wi-Fi Enabled devices are setting new industry benchmarks, while Bluetooth Enabled models provide foundational connectivity.
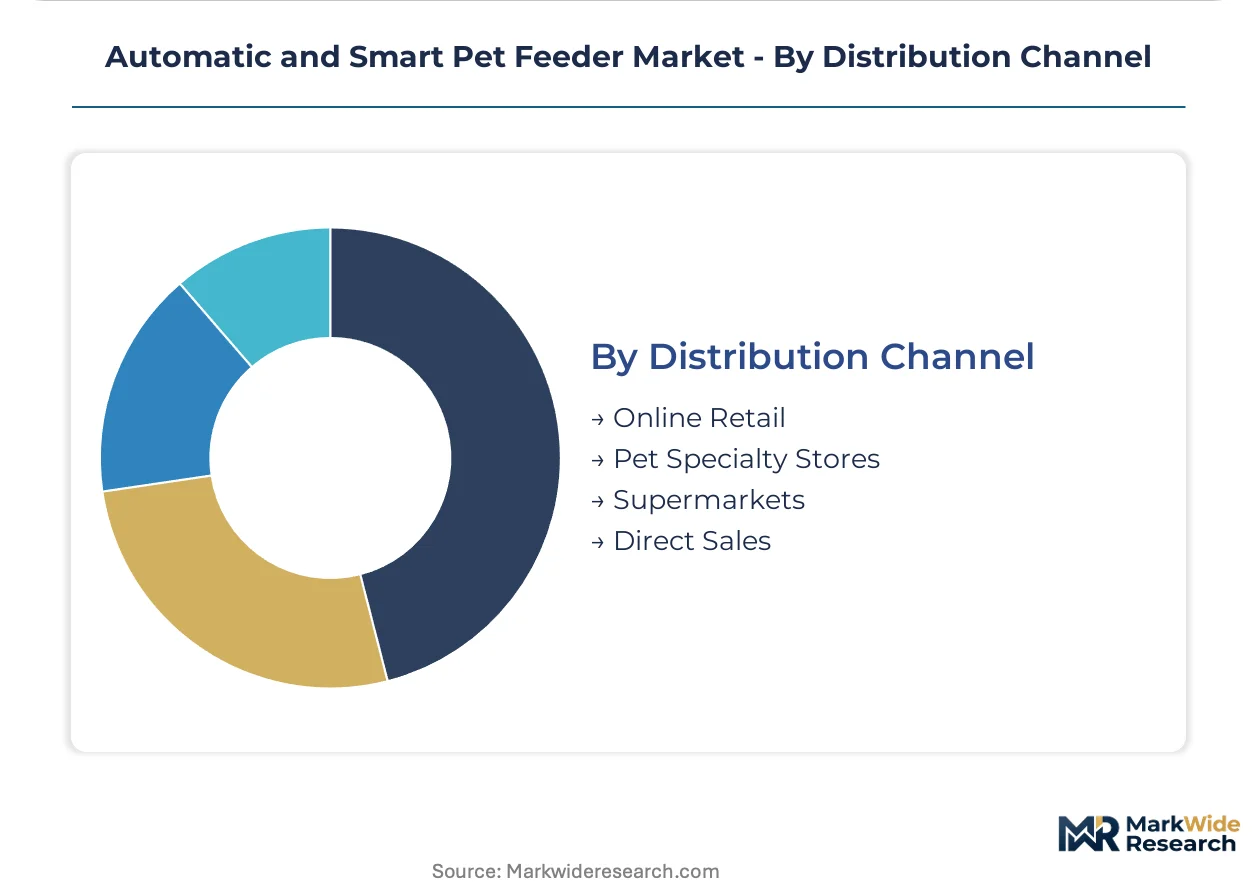
Distribution Channel:
The distribution channels highlight how products reach consumers, with online platforms dominating for accessibility and specialty stores crucial for premium offerings.
- Online Retail:E-commerce platforms and direct-to-consumer websites serve as primary sales channels, offering broad product selections, competitive pricing, and convenience for consumers. This channel is particularly developed in the North American market.
- Pet Specialty Stores:Brick-and-mortar retail outlets focused exclusively on pet products, providing expert advice, product demonstrations, and a curated selection of premium, feature-rich smart devices. PetSafe maintains its market position through this network.
- Supermarkets:Large retail chains offering a limited selection of basic automatic and timed feeders alongside other consumer goods, catering to mass-market accessibility.
- Direct Sales:Manufacturers selling directly to consumers, often through their own websites, allowing for brand-building and direct customer relationships, especially for new market entrants.
The shift towards Online Retail reflects evolving consumer purchasing habits, while Pet Specialty Stores maintain importance for specific product categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global market for automatic and smart pet feeders benefits from interconnected logistics networks that facilitate component sourcing and product distribution. These robust supply chains enable manufacturers to efficiently deliver devices to diverse consumer bases worldwide. E-commerce infrastructure further supports rapid market penetration.
United States
Demand for smart pet feeders in the United States stems from busy urban professionals seeking convenience and remote pet monitoring. FCC regulations govern wireless devices, ensuring product safety and reliable connectivity for consumers. Silicon Valley and other tech hubs drive innovation in app development and sensor integration for advanced feeder functionalities.
Germany
German consumers prioritize pet wellness and product quality, driving demand for advanced automatic and smart feeders. CE marking ensures compliance with European Union safety and material standards for electronic devices sold in the region. Cities like Munich and Berlin exhibit high pet ownership, fostering strong retail sales for premium smart pet care solutions.
China
China's extensive manufacturing infrastructure, particularly in the Pearl River Delta, supports the production of consumer electronics for pet feeders. GB standards ensure product quality and safety for devices manufactured and sold within the country. Shenzhen serves as a critical hub for electronics assembly and supply chain logistics, influencing global production costs.
Japan
Japanese pet owners, often residing in compact urban environments, value compact, technologically advanced pet care solutions. METI guidelines influence product design and energy efficiency standards for household electronics. Tokyo's high-income urban population drives demand for premium smart feeders with sophisticated features and aesthetic designs.
South Korea
South Korea's tech-savvy population and high smartphone penetration contribute to strong demand for smart pet feeders with advanced connectivity. KC certification ensures electrical safety and electromagnetic compatibility for consumer electronic products. Seoul's dense urban centers and pet-friendly culture create a significant consumer base for innovative pet tech.
Automatic and Smart Pet Feeder Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the automatic and smart pet feeder market. The competitive landscape features a blend of established players with extensive distribution and innovative new entrants, creating a tiered market structure. Strategic archetypes include premium design-focused manufacturers, volume-driven mass-market providers, and specialized developers of health monitoring solutions. Companies engage in product portfolio diversification and targeted geographic expansion to enhance their competitive positioning and capture new consumer segments.
PETKIT represents the premium design-focused archetype, leveraging strong engineering capabilities to command a premium in the smart feeder segment. PetSafe exemplifies established market presence, maintaining its position through an extensive distribution network in North American pet specialty stores. WOPET, in contrast, anchors the accessible segment, offering a wide array of affordable timed feeders primarily through online retail channels. These companies collectively illustrate the diverse strategies employed across the market, from high-end feature integration and brand building to broad accessibility and volume-driven sales.
| Leading Market Players |
|---|
| Whisker |
| WOPET |
| PetSafe |
| Arf Pets |
| Catit |
| PETKIT |
| Petlibro |
| CATLINK |
| Sure Petcare |
| Others |
Cost & Logistics Intelligence
Supply chain concentration within China's Pearl River Delta creates commodity volatility, determining both pricing tier spreads and the geographic shape of automatic pet feeder manufacturing. This reliance introduces risks for component sourcing and final product costs.
Pricing Analysis
Volume-discount tiering structures characterize the automatic and smart pet feeder market, ranging from premium-priced smart devices to affordable timed models. Price differentiation stems from advanced feature integration, such as Wi-Fi connectivity and sensor suites, and established brand equity. Pricing pressure intensifies for mid-range products due to competition from low-cost online retailers and high-end specialized devices. Price-sensitive consumers favor basic timed feeders, while tech-savvy, high-income pet owners readily adopt premium smart models.
Supply Chain Analysis
Contract manufacturing concentration in China's Pearl River Delta, particularly Shenzhen, holds significant electronics assembly capacity for pet feeders. The supply chain draws heavily from Chinese component manufacturers for electromechanical parts, sensors, and food-grade plastics. Supply disruption represents a structural risk due to this heavy reliance on a single geographic region. Distribution runs through diverse channels, including dominant online retail platforms and critical pet specialty stores.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automatic and smart pet feeder market is experiencing a cyclical recovery, driven by the sustained convergence of pet humanization trends with consumer IoT technology. This dynamic creates new product categories at the intersection of home automation and pet wellness.
For Market Incumbents: Harden intellectual property around proprietary sensor technology and AI-powered analytics to counter emerging tech-focused entrants. Expand specialized medical feeder lines to address chronic pet conditions, leveraging existing veterinary channel relationships. Invest in robust data privacy and security features, exceeding baseline GDPR and FCC compliance, to mitigate consumer concerns regarding connected devices. Control distribution in pet specialty stores remains critical for demonstrating premium, feature-rich smart devices.
For New Entrants and Emerging Players: Establish a beachhead in East Asian urban centers like Tokyo and Seoul, targeting tech-savvy pet owners with compact, advanced solutions. Focus on developing specialized medical feeders for pets with chronic conditions, integrating data with veterinary telehealth platforms. Leverage direct-to-consumer sales models and social media marketing to build brand awareness and bypass traditional retail gatekeepers. Offer affordable, feature-rich models to capture price-sensitive segments.
For Investors and Strategic Acquirers: GDPR compliance reshapes the acquisition landscape, favoring companies with robust privacy-by-design principles embedded in their smart feeder platforms. The market demonstrates long-term viability, underpinned by sustained pet humanization and technological convergence over the coming decade. Target companies with proven capabilities in software and app maintenance, advanced sensor suites, or strong penetration in East Asian markets. Increased integration of feeder data into veterinary telehealth platforms is a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate AI-powered Health Analytics | This enhances feeder value beyond dispensing, offering proactive pet wellness monitoring for owners. |
| Expand Direct-to-Consumer Channels | New market entrants can build direct relationships with customers, bypassing traditional retail gatekeepers. |
| Secure CE and FCC Certifications | Compliance ensures device reliability and safety, fostering consumer trust in electronic components. |
| Develop Specialized Medical Feeders | Addressing chronic pet conditions creates a high-value niche in the veterinary channel. |
| Target East Asian Urban Markets | High-income, tech-savvy populations in Tokyo and Seoul offer significant growth potential. |
Research Approach
Operator-level perspectives from product managers, supply chain directors, pet specialty store owners, and veterinary clinic administrators anchored the qualitative base for this analysis. These insights were validated through a comprehensive review of secondary data, including FCC filings, CE marking documentation, industry association reports, and e-commerce sales data. A rigorous bottom-up and top-down triangulation approach ensured the accuracy and consistency of all market estimations.
Scenario-bracketing framed the quantitative forecasts, establishing plausible growth trajectories across the analysis window. The market was segmented by product type, end-user, technology, distribution channel, and regional regulatory compliance for precise modeling. Compound annual growth rates were derived from historical data analysis and projected demand drivers like pet ownership rates and consumer IoT adoption. This framework ensured robust market projections.
Stress conditions across component cost volatility and regulatory shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions, though supply chain disruptions and data privacy concerns pose risks. Quarterly review of electronics component prices and regional regulatory updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Vegan Cat Food Market
Pet Care Products
Pet Grooming Supplies Market
Pet Care Products
High Protein Dog Food Market
Pet Care Products
Pet Snacks and Treats Market
Pet Care Products
Saudi Arabia Dog Food Market
Pet Care Products
Dog Clothes Market
Pet Care Products
High Fiber Dog Food Market
Pet Care Products
Pet Slow Feeder Bowl Market
Pet Care Products
Dog Shampoo Market
Pet Care Products
Japan Organic and Natural Pet Food Market
Pet Care Products
United States Pet Care and Services Market
Pet Care Products
UK Pet Grooming Market
Pet Care Products
Pet Smart Tracker Market
Pet Care Products
Vegan Dog Food Market
Pet Care Products
UK Dog Food Market
Pet Care Products
Gcc Pet Food Market