
 Pet Bathing Supplies Market | 2026-2036
Pet Bathing Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Bathing Supplies Market Analytics
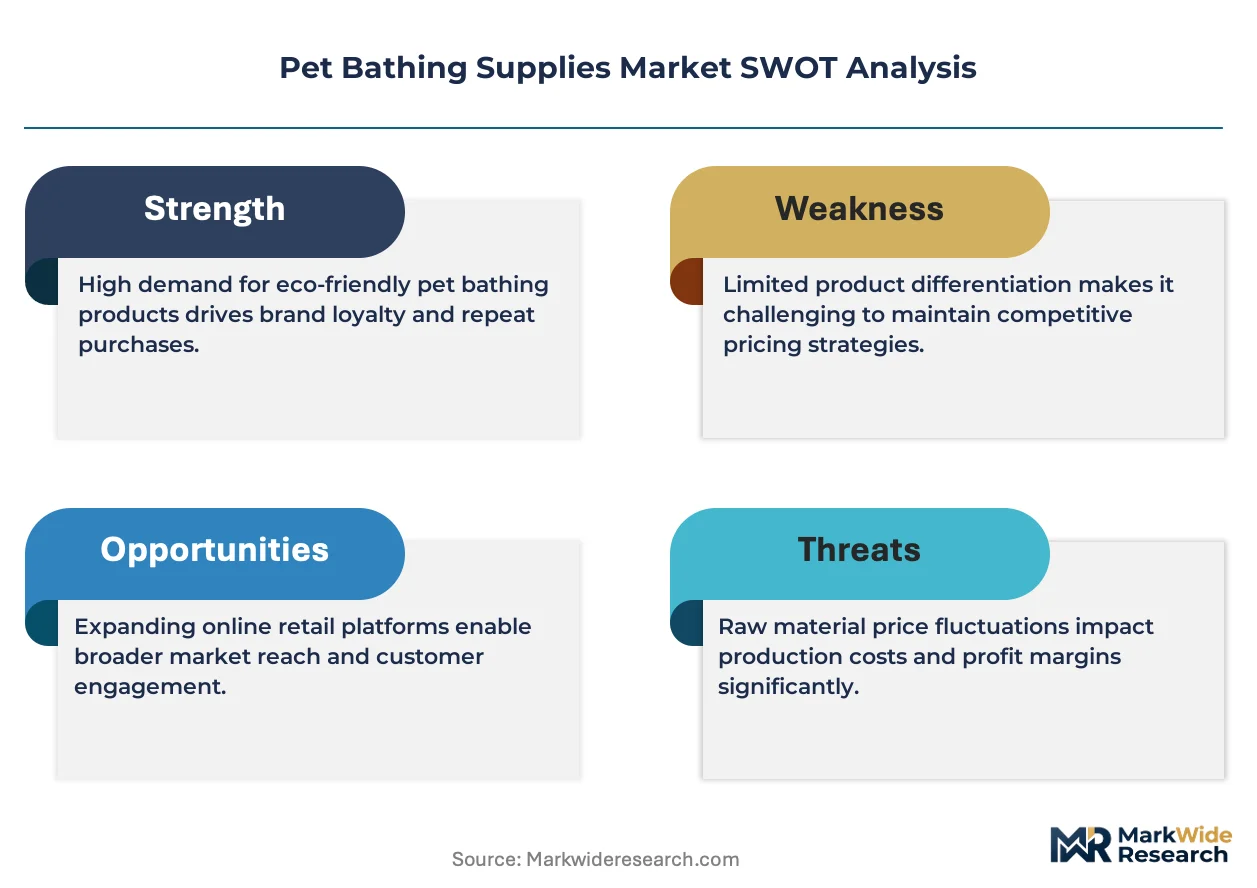
The capital-intensity divergence between automated bathing system manufacturers and manual-tool suppliers is bifurcating competitive dynamics in pet bathing supplies. Spectrum Brands leverages its vertically integrated supply chain to sustain margin control across mass-market shampoo lines. Groomer's Choice anchors its position through specialized professional-grade equipment tailored to high-volume grooming salons. Earthbath differentiates via concentrated natural-ingredient formulations that command premium positioning in specialty retail channels.
Pet bathing supplies encompass formulated cleansing and grooming products alongside mechanical tools designed for coat maintenance, skin health, and parasite control in companion animals; shampoos typically feature surfactant blends balanced to canine and feline skin pH ranges of 6.2–7.5, while brushes integrate varied bristle densities matched to coat length and shedding cycles. The product-type dimension shows shampoos occupying the dominant revenue pool due to repeat-purchase frequency, though eco-friendly feature variants are expanding fastest as ingredient transparency pressures mount across retail and professional channels. End-user segmentation reveals grooming salons capturing the highest per-unit spend through bulk professional formats, while pet owners drive absolute volume through fragmented retail purchases.
EPA oversight of pesticide-containing anti-flea formulations and FDA Center for Veterinary Medicine guidance on topical product safety shape formulation thresholds and labeling requirements for market access in the United States. REACH compliance in Europe restricts certain preservative chemistries, redirecting R&D investment toward bio-based surfactant alternatives. Stakeholders must monitor evolving state-level ingredient disclosure mandates and professional licensing requirements for salon-applied treatments to anticipate compliance cost trajectories and channel-specific product registration demands.
Market Dynamics
Professional grooming salons are driving equipment upgrade cycles as labor costs rise and throughput demands intensify, forcing suppliers to automate rinse systems and water-recirculation technology.
Growth Catalysts
- EPA registration pathways for anti-parasitic shampoos:Clearer pesticide-labeling guidance accelerates product commercialization for flea-control formulations in the United States.
- Waterless cleansing foams:Apartment-dwelling pet owners in Shanghai and Beijing adopt no-rinse formats as bathroom space constraints limit traditional bathing.
- Grooming salon consolidation:Multi-location chains in Texas and Florida standardize equipment procurement, creating volume pull for stainless-steel tub and hydraulic-lift manufacturers.
Market Restraints
- Surfactant input volatility:Coconut-derived foaming agents face price swings tied to Philippine and Indonesian agricultural output, squeezing mid-tier shampoo margins.
- REACH authorization delays:European preservative restrictions force reformulation cycles that extend time-to-market by 18-24 months for EU-bound product lines.
- DIY grooming substitution:Home-use clipper and bathing-tool sales cannibalize professional service visits during economic compression cycles.
Strategic Opportunities
- Veterinary clinic channel expansion:Therapeutic-medicated shampoo lines penetrate dermatology service menus as vets expand ancillary retail.
- India tier-two city penetration:Rising pet ownership in Pune and Hyderabad outpaces organized retail coverage, creating whitespace for direct-to-consumer distribution.
- CE-marked equipment exports:Unified EU safety standards reduce country-by-country compliance burden for bathing-system manufacturers targeting continental Europe.
Industry Challenges
- Certified groomer workforce gaps:Professional licensing requirements in California and New York outstrip training-program output, constraining salon expansion.
- Legacy tub retrofits:Existing grooming-floor plumbing configurations resist seamless integration of automated temperature-mixing valves.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Bathing Supplies Market |
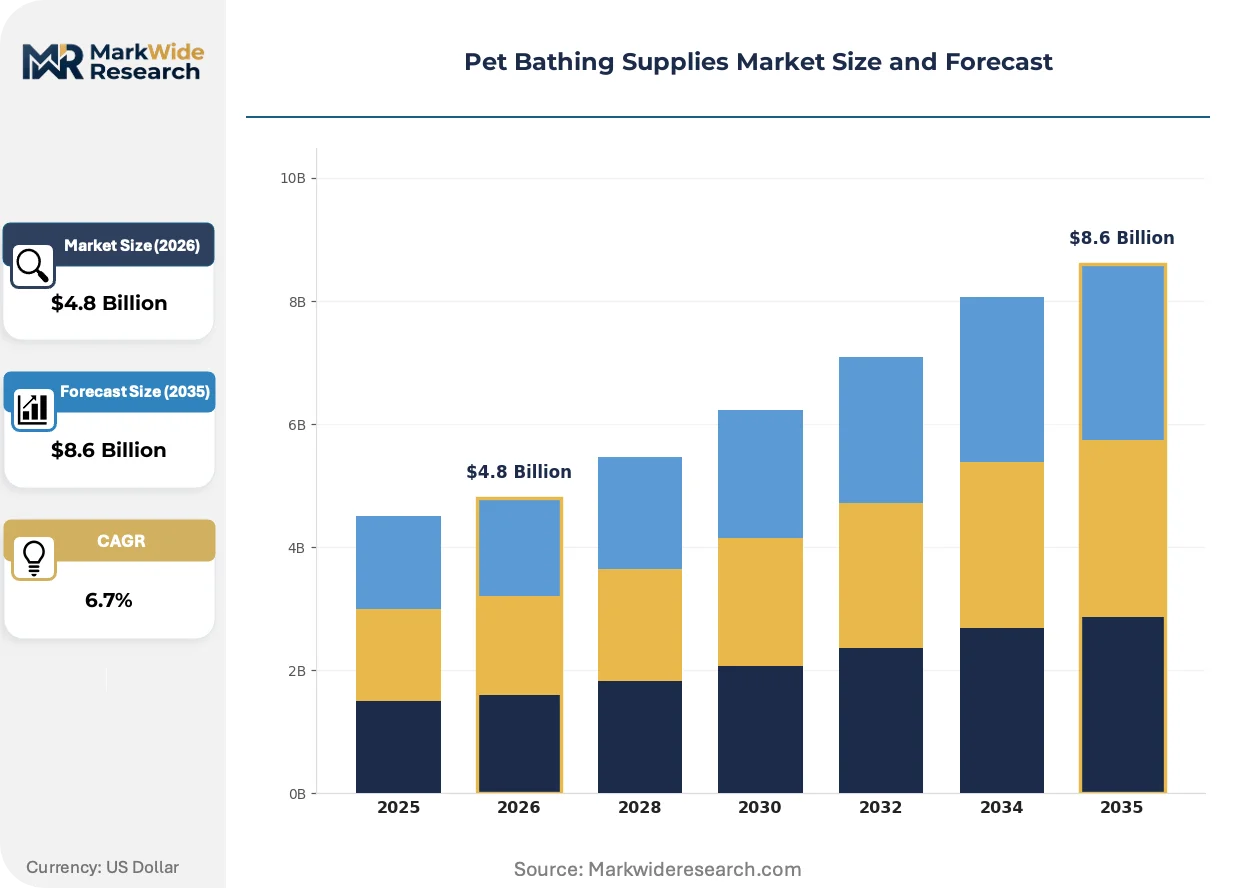
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shampoos, Conditioners, Brushes, Towels End User: Pet Owners, Grooming Salons, Veterinarians, Shelters Feature: Anti-Flea, Hypoallergenic, Moisturizing, Eco-Friendly Packaging Type: Bottles, Sachets, Jars, Bulk Containers |
| Companies Covered | Groomer's Choice, Rosewood Pet Products, Resco, Hagen Inc., Spectrum Brands, Petco Animal Supplies, Inc., Coastal Pet Products, Earthbath, SynergyLabs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Bathing Supplies Market Evolving Landscape
Ingredient transparency and automation are converging to reshape product development priorities and equipment procurement standards across retail and professional channels.
Portable ultrasonic bathing devices are miniaturizing. Mobile groomers operating van-based services in suburban Dallas and Phoenix adopt battery-powered units that eliminate generator dependency. This format compression is opening service territories previously unreachable due to power-access constraints.
REACH bio-based surfactant mandates are redirecting R&D budgets. European formulators substitute petrochemical foaming agents with sugar-derived alternatives to maintain market access. Specialty retail channels in Germany and France now demand full ingredient-chain disclosure as a listing prerequisite.
Subscription replenishment models are capturing shampoo volume. Direct-to-consumer platforms displace periodic big-box purchases with auto-ship algorithms calibrated to breed-specific coat cycles. This behavior shift concentrates most visibly among millennial pet owners in urban UK markets.
Pet Bathing Supplies Market Segmentation
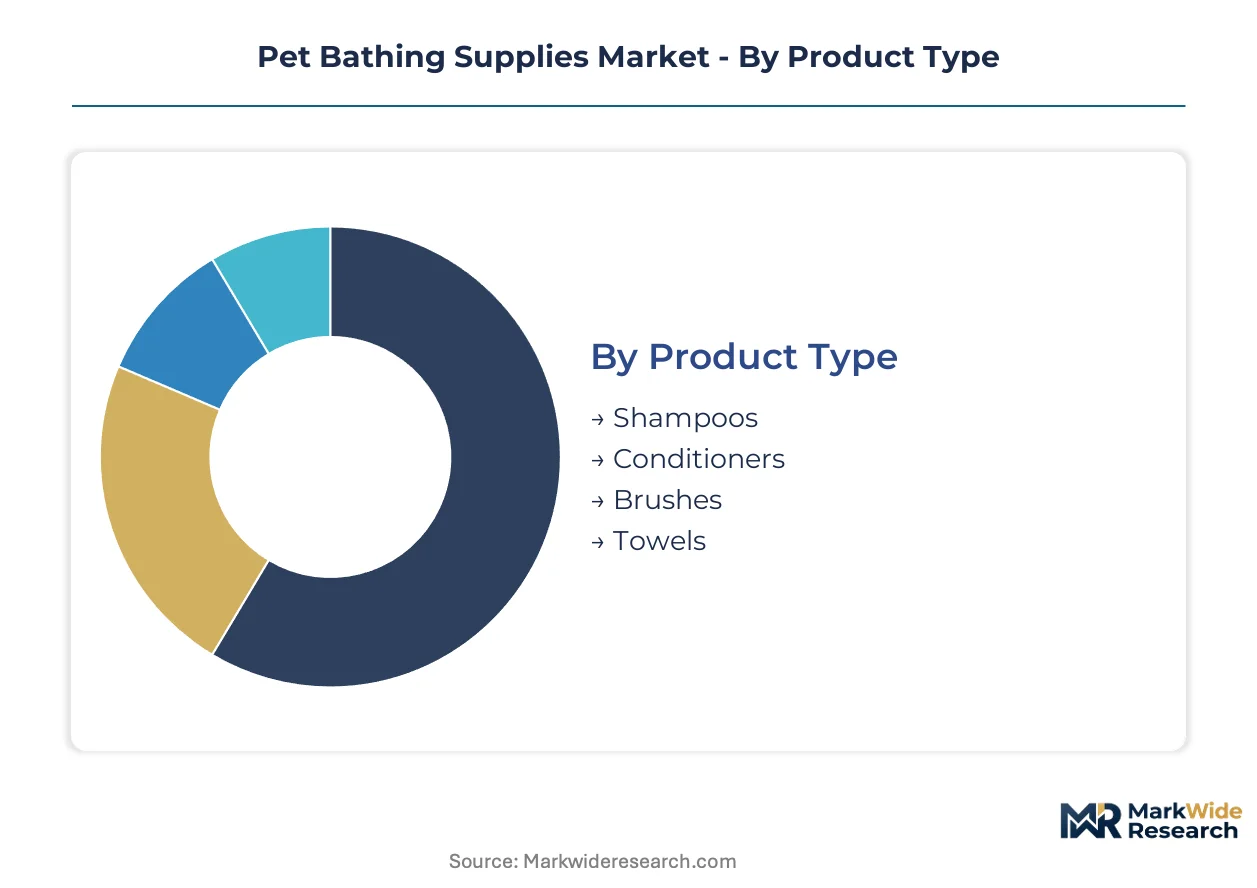
Segmentation in pet bathing supplies reveals distinct compliance burdens and procurement patterns across product formulations and professional channels. Regulatory thresholds vary sharply between retail consumer goods and clinic-grade therapeutics, reshaping how suppliers configure their SKU portfolios and geographic targeting.
Product Type:
EPA registration requirements for pesticide-containing formulations create divergent cost structures across cleansing product categories.
- Shampoos:Surfactant blends calibrated to canine and feline skin pH ranges of 6.2–7.5 dominate absolute volume through repeat-purchase frequency in both retail and professional channels. Demand concentrates in grooming salons purchasing bulk professional formats as labor costs rise and throughput demands intensify.
- Conditioners:Silicone and lipid-based detangling formulations command premium positioning in specialty retail. Adoption is climbing fastest among long-coated breed owners in tier-one Chinese cities where apartment-dwelling constraints favor coat-maintenance efficiency.
- Brushes:Bristle density configurations matched to coat length and shedding cycles serve high-volume salon equipment upgrade cycles.
- Towels:Microfiber and cotton-blend absorbency variants support mobile grooming van services expanding across suburban Dallas and Phoenix.
Established volume favors shampoos; emerging adoption favors conditioners.
End User:
Per-unit spend and procurement authority split sharply between fragmented individual purchasers and consolidated institutional buyers.
- Pet Owners:Fragmented retail purchases drive absolute volume through big-box and direct-to-consumer channels. Subscription replenishment models calibrated to breed-specific coat cycles are displacing periodic purchases among millennial owners in urban UK markets.
- Grooming Salons:Multi-location chains in Texas and Florida standardize equipment procurement, creating volume pull for stainless-steel tub and hydraulic-lift manufacturers. Labor cost pressures are forcing automation investments in rinse systems and water-recirculation technology.
- Veterinarians:Therapeutic-medicated shampoo lines penetrate dermatology service menus as clinics expand ancillary retail operations.
- Shelters:High-throughput bathing demands favor bulk container formats and simplified ingredient profiles to minimize adverse reaction risk across unknown medical histories.
Absolute volume concentrates with pet owners; margin expansion concentrates with grooming salons.
Feature:
Ingredient transparency mandates and REACH bio-based surfactant requirements are redirecting R&D investment toward disclosure-compliant formulations.
- Anti-Flea:Pesticide-containing formulations require EPA registration pathways and specific labeling claims that extend commercialization timelines. Clearer guidance is accelerating product development for United States market access.
- Hypoallergenic:Fragrance-free and limited-ingredient profiles address dermatological sensitivity in veterinary clinic channels.
- Moisturizing:Lipid-replenishing formulations target dry-skin conditions prevalent in arid climate zones.
- Eco-Friendly:Sugar-derived surfactant alternatives substitute petrochemical foaming agents to maintain European market access under REACH mandates. Specialty retail channels in Germany and France now demand full ingredient-chain disclosure as a listing prerequisite.
Regulatory compliance burden weighs heaviest on anti-flea; sustainability positioning drives fastest feature expansion in eco-friendly.
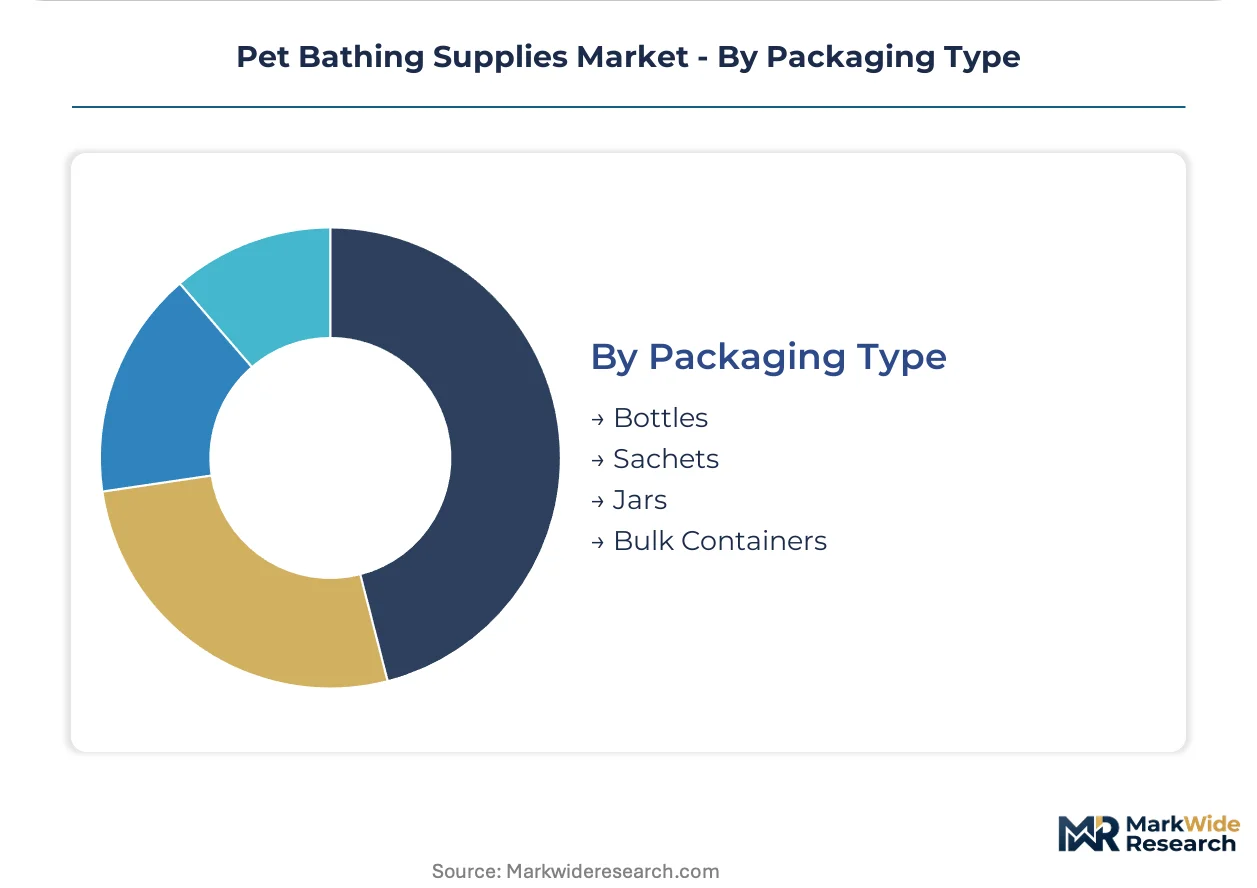
Packaging Type:
Channel economics and usage velocity determine format selection across retail, professional, and institutional procurement contexts.
- Bottles:Standard retail formats with pump and flip-cap dispensers dominate household purchase patterns.
- Sachets:Single-use portions support trial sampling and travel-oriented consumption in mobile grooming services.
- Jars:Wide-mouth containers accommodate thick conditioning masks and paw-balm formulations.
- Bulk Containers:Professional-grade volumes capture highest per-unit spend in grooming salon procurement. Consolidated multi-location chains negotiate direct supply agreements that bypass distributor markups.
Retail velocity sustains bottles; professional consolidation elevates bulk containers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pet bathing supply consumption patterns diverge sharply by geography: United States households favor high-frequency retail purchases, while Chinese demand concentrates in tier-one cities where apartment living drives waterless format adoption, and European procurement prioritizes REACH-compliant formulations with full ingredient disclosure.
United States
Pet ownership rates exceed seventy percent in suburban households, driving repeat-purchase volume through big-box and direct-to-consumer channels. EPA registration requirements for anti-parasitic shampoos shape formulation thresholds and labeling standards. Multi-location grooming chains in Texas and Florida standardize equipment procurement, creating consolidated demand for stainless-steel tubs and hydraulic lifts.
China
Apartment-dwelling pet owners in Shanghai and Beijing adopt waterless cleansing foams as bathroom space constraints limit traditional bathing. SAMR labeling standards and GB product safety codes govern cosmetic-grade pet care formulations. Tier-one cities concentrate absolute demand while tier-two markets in Chengdu and Hangzhou present whitespace for distribution expansion.
Germany
Specialty retail channels demand full ingredient-chain disclosure as a listing prerequisite, redirecting supplier R&D toward bio-based surfactants. REACH authorization protocols restrict preservative chemistries, extending reformulation cycles. Industrial clusters in North Rhine-Westphalia host formulators developing sugar-derived alternatives to petrochemical foaming agents.
United Kingdom
Millennial pet owners in urban markets subscribe to auto-ship algorithms calibrated to breed-specific coat cycles, displacing periodic big-box purchases. Veterinary Medicines Directorate guidance shapes therapeutic shampoo classifications. London-based direct-to-consumer platforms capture replenishment volume through subscription models.
India
Rising pet ownership in Pune and Hyderabad outpaces organized retail coverage, creating whitespace for direct-to-consumer distribution. BIS quality standards apply to imported pet care formulations. Metropolitan clusters in Maharashtra and Telangana concentrate demand for professional-grade grooming equipment as salon culture spreads.
Pet Bathing Supplies Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with mass-market formulators controlling retail shelf space while equipment fabricators serve consolidated grooming chains. The market structure shows Spectrum Brands leveraging vertically integrated supply chains for margin control, Earthbath occupying premium natural-ingredient positioning, and Groomer's Choice anchoring professional-grade equipment segments. Competitive moves concentrate on portfolio diversification into adjacent pet wellness categories and geographic expansion through distributor partnerships in underpenetrated Asian markets.
Within the integrated mass-market tier, Spectrum Brands exemplifies backward integration into raw material sourcing, while Earthbath occupies the specialty retail channel with concentrated natural formulations. Groomer's Choice represents the professional equipment archetype, serving high-volume salon chains with specialized bathing systems. These three anchors illustrate the vertical stratification between retail-scale formulators and professional-channel equipment suppliers.
| Leading Market Players |
|---|
| Groomer's Choice |
| Rosewood Pet Products |
| Resco |
| Hagen Inc. |
| Spectrum Brands |
| Petco Animal Supplies, Inc. |
| Coastal Pet Products |
| Earthbath |
| SynergyLabs |
| Others |
Value Network & Pricing Analysis
Sugar-derived surfactant substitution for petrochemical foaming agents is redrawing supply geography toward Philippine and Indonesian coconut processing clusters while compressing mid-tier shampoo margins through agricultural input volatility. This input shift simultaneously elevates European REACH compliance costs and fragments pricing power between bio-based formulators and legacy petrochemical suppliers.
Pricing Analysis
Long-term offtake agreements dominate professional-grade equipment procurement as multi-location grooming chains in Texas and Florida negotiate direct supply contracts that bypass distributor markups. Three-tier pricing structure across premium natural-ingredient, standard surfactant, and economy bulk formats separates Earthbath's specialty positioning from mass-market lines. Pricing pressure stems from coconut-derived input volatility squeezing mid-tier manufacturers. Pet owners through fragmented retail channels exhibit highest price sensitivity; grooming salons demonstrate lowest sensitivity due to equipment financing structures.
Supply Chain Analysis
Inventory lead times for stainless-steel bathing systems extend from fabrication clusters in China and Mexico to installation sites across the United States. Raw material dependencies center on coconut-derived surfactants from Southeast Asia, sugar-based alternatives from European industrial clusters, and hydraulic components from German engineering suppliers. Single-source vulnerability concentrates in Philippine agricultural output for premium foaming agents. Distribution runs through veterinary clinic networks, direct-to-consumer platforms, and consolidated grooming chain procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against waterless cleansing foam formats that threaten traditional shampoo volume in space-constrained urban households.
For Market Incumbents: Shield professional equipment lines through exclusive service contracts with consolidating grooming chains in Texas and Florida. Deepen captive supply of sugar-derived surfactants to preempt REACH-driven raw material access restrictions. Counter waterless format substitution by emphasizing therapeutic efficacy in veterinary clinic channels. For New Entrants and Emerging Players: Lead with direct-to-consumer subscription models targeting millennial pet owners in urban UK markets where auto-ship algorithms displace periodic retail purchases. Exploit whitespace in India's tier-two cities where organized retail coverage lags rising pet ownership in Pune and Hyderabad. Anchor go-to-market positioning through breed-specific coat cycle calibration. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated formulators with backward control over bio-based surfactant supply. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than brand equity alone. Target acquisition archetypes include REACH-certified European formulators and mobile grooming equipment fabricators. Monitor EPA registration pathway clarity for anti-parasitic shampoos as inflection indicator for flea-control formulation profitability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Surfactants | Captive supply of sugar-derived alternatives secures European market access under REACH mandates. |
| Veterinary Clinic Channel Expansion | Therapeutic-medicated lines penetrate dermatology menus as vets expand ancillary retail operations. |
| Mobile Grooming Equipment Miniaturization | Battery-powered ultrasonic units eliminate generator dependency for van-based services in suburban Dallas. |
| Subscription Replenishment Model Launch | Auto-ship algorithms calibrated to breed-specific coat cycles capture volume from periodic big-box purchases. |
| CE-Marked Equipment Export Program | Unified EU safety standards reduce country-by-country compliance burden for bathing-system manufacturers. |
Research Methodology
The analysis maps shampoo formulations, professional equipment, and waterless cleansing formats, each validated through grooming salon operators, veterinary procurement managers, retail category buyers, and surfactant R&D directors. Primary interviews with these stakeholders combined trade data from customs records, EPA registration filings, and REACH authorization databases. Secondary validation drew from pet industry association reports, grooming chain equipment procurement disclosures, and specialty retail channel audits. Bottom-up SKU-level modeling triangulated against top-down category spending estimates.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include product type, end-user channel, ingredient feature, and packaging format alongside regional regulatory cluster variations. CAGRs derived from historical trajectory analysis adjusted for documented policy shifts and channel migration patterns. Forecast inputs incorporated grooming salon automation adoption curves and REACH bio-based surfactant mandate implementation timelines.
Forecasts assume regulatory continuity in EPA pesticide-labeling guidance and REACH authorization protocols; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
United States Pet Care and Services Market
Pet Care Products
Outdoor Cat Houses and Furniture Market
Pet Care Products
China Pet Training Services Market
Pet Care Products
China Pet Clothing Market
Pet Care Products
Gcc Pet Food Market
Pet Care Products
Pet Smart Tracker Market
Pet Care Products
US and Mexico Cat Litter Market
Pet Care Products
Saudi Arabia Pet Food Market
Pet Care Products
Global Pet Stroller Market
Pet Care Products
Dog Muzzle Market
Pet Care Products
Asia Pacific Pet Diet Market
Pet Care Products
Smart Pet Leash Market
Pet Care Products
Smart Pet Kennel Market
Pet Care Products
Natural Dog Treat Market
Pet Care Products
South America Pet Treats Market
Pet Care Products
Indestructible Dog Toys Market