
 Smart Pet Supply Market | 2026-2036
Smart Pet Supply Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Pet Supply Market Insights
IEC 62368-1 safety certification for audio/video and information technology equipment is bifurcating the competitive landscape into qualified incumbents and cost-challenged entrants. PetSafe leverages its captive distribution through specialty retail chains to sustain margin capture in North America. Garmin anchors its position through backward integration into GPS chipset design, while Tractive differentiates via cloud-native firmware architecture that reduces hardware bill-of-materials.
Smart pet supply denotes connected hardware and software systems engineered for animal welfare management, typically incorporating accelerometers, temperature sensors, and RF transceivers operating in unlicensed ISM bands for real-time biometric telemetry and geolocation. The primary commercial purpose centers on translating continuous physiological data into actionable health alerts and behavioral interventions for pet owners and veterinary professionals. GPS collars and health monitors occupy the deepest margin pools as recurring subscription revenue attaches to hardware sale, while interactive toys remain structurally constrained by commoditized motor and speaker components. Machine learning-enabled diagnostic platforms represent the fastest-expanding technology segment as pattern recognition improves predictive accuracy for chronic conditions.
FCC Part 15 emissions rules in the United States, CE marking requirements under the EU Radio Equipment Directive, and Japan's TELEC certification collectively govern RF-enabled device market access and dictate testing expenditure thresholds. These frameworks shape demand by excluding uncertified imports while elevating R&D overhead that favors scaled manufacturers over garage-stage entrants. Stakeholders must monitor evolving cybersecurity mandates for IoT devices as breach liability frameworks crystallize across major economies.
Market Dynamics
Subscription revenue attachment to GPS collars and health monitors is restructuring competitive economics, forcing hardware manufacturers to build cloud infrastructure or surrender margin to platform intermediaries. This shift privileges firms with captive firmware development and direct-to-consumer distribution.
Growth Catalysts
- ISM Band Proliferation:Unlicensed 2.4 GHz and sub-GHz spectrum availability in the United States, Germany, and Japan reduces RF deployment costs for telemetry hardware.
- Veterinary Diagnostic Integration:Machine learning pattern recognition for chronic condition prediction is creating clinical referral pathways that validate consumer purchase decisions.
- FCC Part 15 Harmonization:Streamlined electromagnetic emissions testing is accelerating certification timelines for multi-band wearable devices.
Market Restraints
- Lithium-Polymer Cost Volatility:Battery cell price swings constrain margin stability in compact wearable form factors where energy density is non-negotiable.
- Taiwan Semiconductor Concentration:GPS chipset and accelerometer foundry capacity bottlenecks create single-source exposure for mid-tier hardware vendors.
- IEC 62368-1 Compliance Burden:Audio/video safety certification requirements for camera-enabled pet monitors impose testing overhead that excludes garage-stage entrants.
Strategic Opportunities
- Brazil Regulatory Opening:ANVISA framework clarity for ingestible sensors creates first-mover advantage in Latin America's largest pet population market.
- Cellular LPWAN Convergence:NB-IoT and LTE-M module integration is enabling real-time tracking beyond Bluetooth range without smartphone tethering.
- Veterinary Channel Direct:Clinic-based hardware dispensing bypasses retail margin extraction while embedding devices within professional recommendation networks.
Industry Challenges
- Firmware Security Engineering:IoT breach liability exposure requires dedicated cybersecurity talent scarce in traditional consumer electronics firms.
- Multi-Regulatory Parallel Certification:Simultaneous FCC, CE marking, and TELEC testing extends product launch timelines by eight to fourteen months.
- Legacy Home Automation Integration:Proprietary smart home protocols fragment compatibility, forcing redundant engineering for Alexa, Google Home, and Apple HomeKit certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Pet Supply Market |
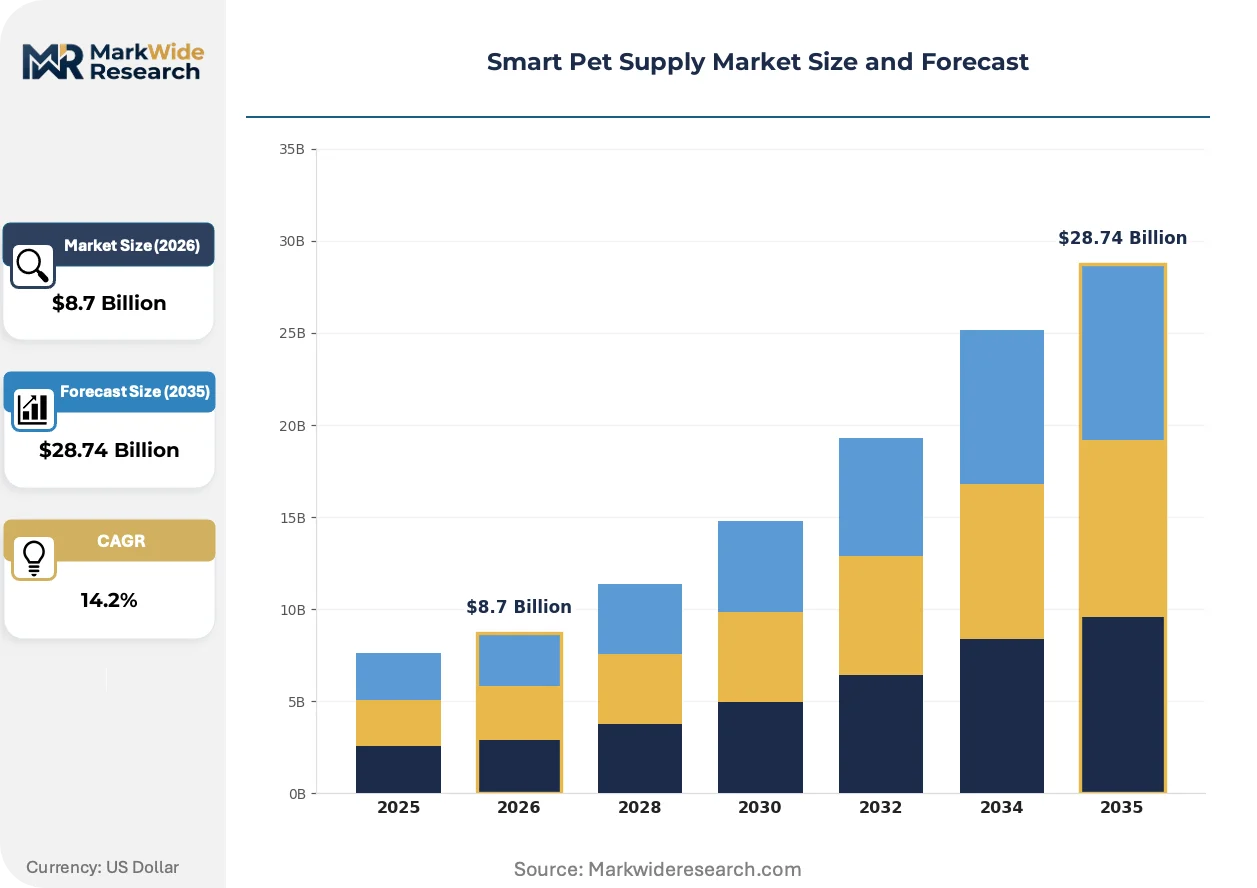
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Feeders, GPS Collars, Health Monitors, Interactive Toys End User: Pet Owners, Veterinary Clinics, Pet Retailers, Animal Shelters Technology: IOT, Bluetooth, Machine Learning, Remote Monitoring Distribution Channel: Online Retail, Specialty Stores, Pet Expos, Direct Sales |
| Companies Covered | PetSafe, Petkit, Sure Petcare, Whistle, Garmin, FitBark, Tractive, PetPace, WOpet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Pet Supply Market Trends and Innovations
Edge computing migration and predictive health algorithms are compressing the latency between biometric capture and owner notification. These capabilities are redefining value propositions from reactive tracking to preemptive intervention.
On-device machine learning inference is displacing cloud-dependent processing for anomaly detection in GPS collars and activity monitors. Premium pet owners in Germany and Japan are adopting these units fastest, prioritizing data privacy and offline functionality. This architecture shift is compressing recurring cloud infrastructure costs while enabling subscription pricing for firmware feature unlocks rather than raw data transmission.
EU Cybersecurity Resilience Act mandates for IoT device vulnerability disclosure are reshaping product lifecycle obligations. Manufacturers must now maintain security update channels for minimum five-year horizons. GPS collar and health monitor segments face the steepest compliance costs, prompting consolidation among vendors lacking dedicated firmware engineering teams.
Veterinary procurement of remote monitoring hardware for post-surgical patient management is fragmenting traditional retail-centric distribution. Specialty clinics in the United States are negotiating direct purchasing agreements that bypass pet specialty chains. This channel rotation concentrates volume with vendors offering clinical data export compatibility and veterinary practice management software integration.
Smart Pet Supply Market Segmentation
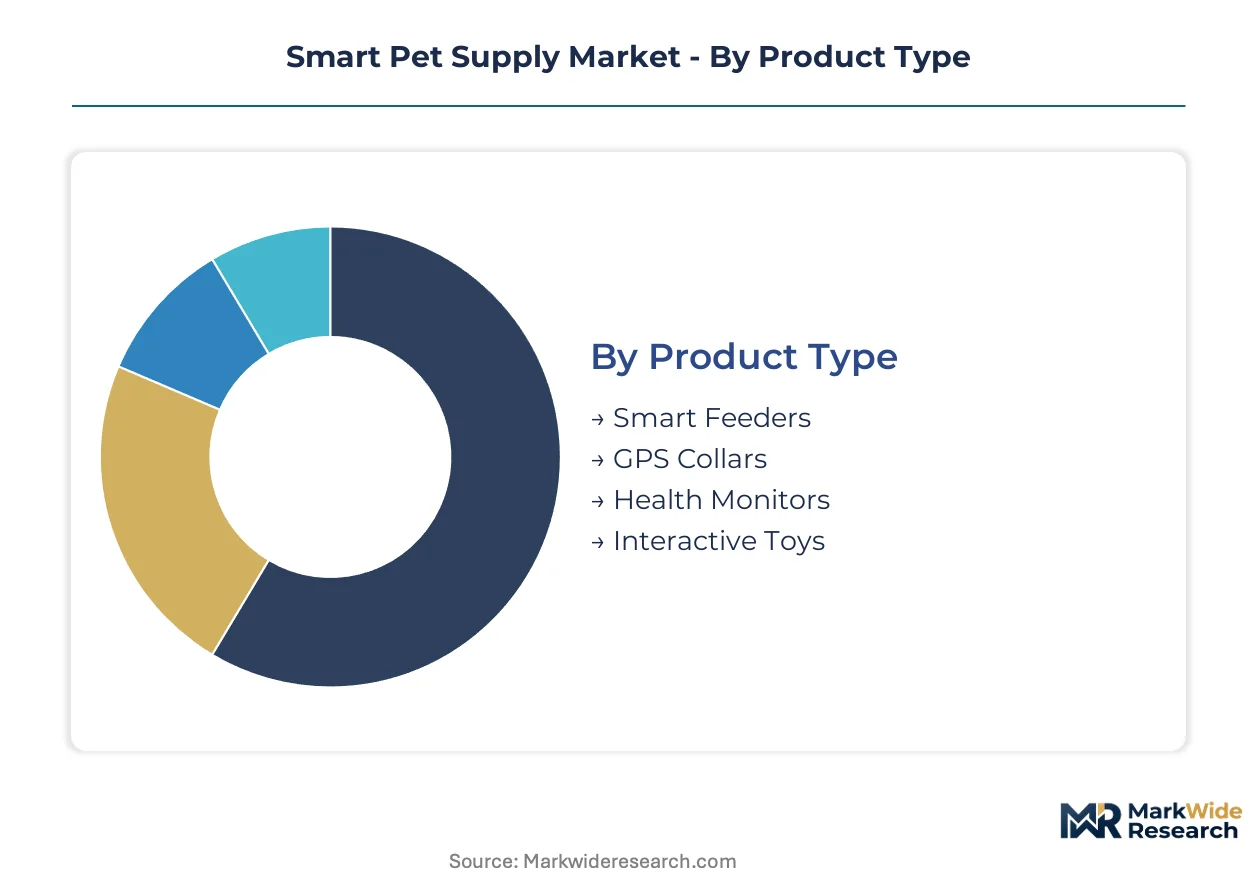
Segmentation in smart pet supplies exposes where subscription economics override hardware commoditization. GPS collars and health monitors command recurring revenue attachment, while interactive toys face substitution from unconnected alternatives.
Product Type:
Interactive toys confront the steepest substitution pressure from conventional pet products lacking RF connectivity or cloud dependency.
- GPS Collars:Units integrate GPS chipsets with cellular LPWAN modules for real-time geolocation beyond Bluetooth range. Demand concentrates in the United States and Germany where premium pet expenditure overlaps with rural off-leash recreation culture, driven by FCC Part 15 and CE marking harmonization that streamlines multi-band certification.
- Health Monitors:Wearable devices incorporate accelerometers and temperature sensors for continuous biometric telemetry with veterinary diagnostic integration. Pet owners in Japan adopt these fastest, prioritizing predictive algorithms for chronic condition detection that validate clinical referral pathways.
- Smart Feeders:Connected dispensing systems with portion control and scheduling via smartphone applications.
- Interactive Toys:Motorized and speaker-equipped devices for remote engagement, constrained by commoditized component costs.
GPS Collars retain volume leadership; Health Monitors hold the steepest expansion curve.
End User:
Cost tier stratification separates enterprise procurement with clinical data requirements from individual consumer purchases driven by convenience.
- Pet Owners:Individual consumers purchasing direct-to-consumer through online retail and specialty stores, representing the largest addressable base.
- Veterinary Clinics:Professional facilities procuring remote monitoring hardware for post-surgical patient management and chronic condition tracking. Demand concentrates in the United States where direct purchasing agreements bypass retail margin extraction.
- Pet Retailers:Specialty chains and independent stores curating connected hardware with subscription attachment.
- Animal Shelters:Non-profit and municipal facilities with budget-constrained procurement of basic tracking and monitoring equipment.
Pet Owners dominate absolute volume; Veterinary Clinics are climbing the fastest as channel rotation concentrates professional-grade procurement.
Technology:
Application maturity varies sharply between established ISM band connectivity and emerging on-device inference architectures.
- Machine Learning:Edge computing migration enables on-device anomaly detection without cloud dependency. Germany and Japan lead adoption among privacy-conscious premium owners, compressing recurring infrastructure costs while enabling firmware feature unlock subscriptions.
- Remote Monitoring:Continuous telemetry platforms with real-time alert generation for biometric thresholds and geofence breaches. Veterinary integration in the United States validates consumer purchase decisions through clinical referral pathways.
- IOT:Internet-connected device ecosystems with smartphone application control and data aggregation.
- Bluetooth:Short-range wireless connectivity for smartphone-tethered operation within limited proximity.
Remote Monitoring retains volume leadership; Machine Learning holds the steepest expansion trajectory.
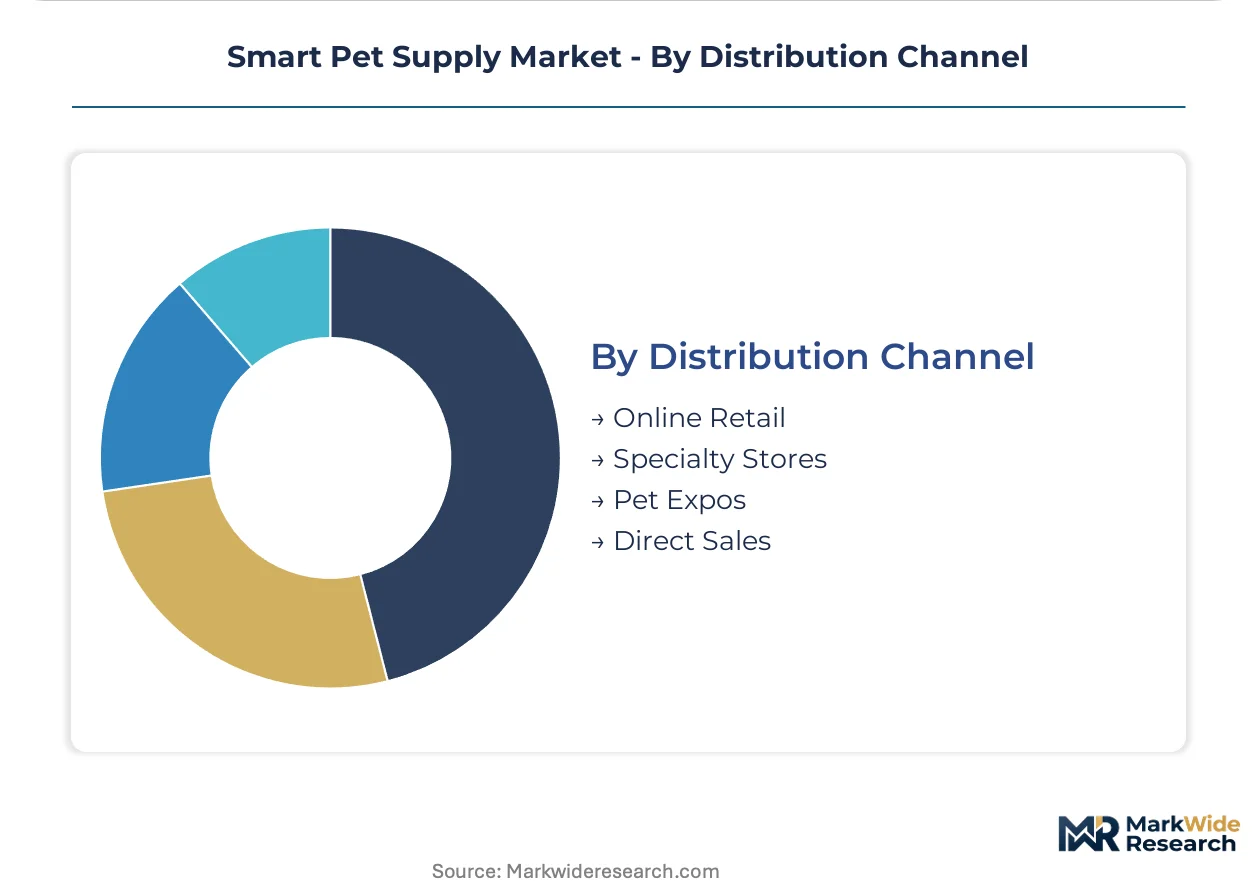
Distribution Channel:
Geography determines channel effectiveness, with online retail penetrating rural markets while specialty stores dominate urban premium corridors.
- Online Retail:E-commerce platforms with direct-to-consumer fulfillment and subscription management infrastructure. The United States and Germany show highest penetration where smart home ecosystem normalization reduces purchase friction.
- Specialty Stores:Physical pet retail chains with captive distribution and margin capture through trained staff consultation.
- Pet Expos:Trade show and exhibition channels for product demonstration and breeder network penetration.
- Direct Sales:Manufacturer-owned channels bypassing intermediary margin extraction for veterinary and enterprise accounts.
Online Retail retains volume leadership; Direct Sales gains share fastest as veterinary channel rotation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC Part 15 harmonization and the EU Cybersecurity Resilience Act are accelerating certification timelines and extending product lifecycle obligations across major economies. Premium pet expenditure overlaps with smart home penetration in specific national markets, concentrating demand where regulatory clarity reduces market access friction.
United States
Pet owners in rural corridors drive GPS collar adoption for off-leash recreation, while veterinary clinics negotiate direct procurement agreements for post-surgical monitoring. FDA device classifications for ingestible sensors and FCC emissions rules govern wearable hardware market access. Austin and San Diego clusters host firmware engineering teams serving cloud-native pet health platforms.
Germany
Privacy-conscious premium owners accelerate adoption of on-device machine learning inference for biometric anomaly detection. CE marking under the EU Radio Equipment Directive and REACH compliance for battery materials shape hardware design requirements. Munich and Stuttgart industrial zones concentrate GPS chipset integration and accelerometer calibration facilities.
Japan
TELEC certification for RF-enabled wearables and predictive health algorithm validation through veterinary referral networks sustain premium pricing. METI guidelines for IoT cybersecurity influence firmware update channel design. Tokyo and Osaka metropolitan areas anchor distribution through specialty retail chains with trained consultation staff.
United Kingdom
Smart home ecosystem normalization reduces purchase friction for connected feeders and health monitors in Greater London and Southeast England. UKCA marking transition from CE standards creates temporary certification overhead for import-dependent vendors. Cambridge technology corridor hosts edge computing development for low-latency biometric processing.
Brazil
ANVISA framework clarity for ingestible sensors creates first-mover positioning in Latin America's largest pet population market. São Paulo and Rio de Janeiro concentrate veterinary clinic networks exploring remote monitoring for chronic condition management. Import tariff structures favor local assembly of GPS-enabled collars from Asian component suppliers.
Smart Pet Supply Market Competitive Landscape
Player mix skews toward consumer electronics specialists with captive cloud infrastructure and veterinary-channel entrants with clinical data integration capabilities. Market structure concentrates around three tiers: GPS chipset designers with backward integration, cloud-native firmware architects with reduced hardware bill-of-materials, and specialty retailers with captive distribution networks. Dominant competitive moves include direct-to-consumer channel construction and veterinary practice management software integration.
Within the integrated hardware tier, Garmin exemplifies upstream control over GPS chipset design, while Tractive occupies a position as a cloud-native firmware specialist reducing transmission infrastructure costs. PetSafe anchors the specialty retail vector through trained consultation networks in North American pet chains. These three entities represent the strategic archetypes reshaping margin capture as subscription revenue attachment restructures competitive economics.
| Leading Market Players |
|---|
| PetSafe |
| Petkit |
| Sure Petcare |
| Whistle |
| Garmin |
| FitBark |
| Tractive |
| PetPace |
| WOpet |
| Others |
Pricing and Supply Chain Analysis
Cellular LPWAN module substitution for Bluetooth-tethered architectures redraws manufacturing geography toward Shenzhen and Taipei while compressing subscription pricing power as hardware margins detach from recurring revenue capture.
Pricing Analysis
Certification level under FCC Part 15, CE marking, and TELEC standards creates the primary spread between premium GPS collars and economy-tier health monitors. Three-tier pricing structure across premium, standard, and economy levels reflects firmware feature depth and veterinary data export compatibility. Cost compression in the interactive toy segment intensifies because commoditized motor and speaker components face substitution from unconnected alternatives. Veterinary clinics exhibit lowest price sensitivity due to clinical workflow integration requirements, while animal shelters operate under severe budget constraints.
Supply Chain Analysis
Inbound logistics costs from Shanghai and Busan to Los Angeles and Rotterdam fluctuate with container availability and port congestion on transpacific lanes. GPS chipset fabrication concentrates in Taiwan and South Korea, while lithium-polymer cell assembly anchors in China and Japan. Hardware bill-of-materials rests on accelerometer foundry capacity, GPS module supply, and cellular modem procurement. Single-source exposure to Taiwan Semiconductor creates vulnerability for mid-tier vendors lacking multi-source qualification. Distribution runs through direct-to-consumer online platforms and veterinary clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart pet supply market functions as a service-attach opportunity where firmware subscription revenue expands faster than hardware unit economics, rewarding cloud infrastructure investment over pure manufacturing scale.
For Market Incumbents: Compound defensive positioning through backward integration into GPS chipset design and captive cloud firmware development. Threats from cloud-native entrants with reduced hardware bill-of-materials demand accelerated veterinary practice management software integration. Priority levers include multi-regulatory parallel certification investment and direct-to-consumer channel construction.
For New Entrants and Emerging Players: ANVISA fast-track certification for ingestible sensors in Brazil creates white-space entry before incumbent footprint solidifies. Cellular LPWAN-enabled real-time tracking beyond smartphone tethering represents the most penetrable technology segment. Clinic-based hardware dispensing with clinical data export compatibility offers the strongest go-to-market angle.
For Investors and Strategic Acquirers: Capital is best deployed toward cloud-native firmware architects with reduced transmission infrastructure costs and veterinary-channel integration capabilities. Long-term viability across the analysis window favors firms with captive subscription revenue attachment and five-year cybersecurity update channel obligations. Signal to monitor: consolidation velocity among vendors lacking dedicated firmware engineering teams as EU Cybersecurity Resilience Act compliance costs escalate.
| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Practice Management Software Integration | Embeds hardware within professional recommendation networks and bypasses retail margin extraction. |
| On-Device Machine Learning Inference Development | Compresses recurring cloud infrastructure costs while enabling firmware feature unlock subscriptions. |
| Multi-Regulatory Parallel Certification Investment | Accelerates FCC Part 15, CE marking, and TELEC timelines to capture first-mover positioning. |
| Direct-to-Consumer Channel Construction | Captures subscription revenue attachment without surrendering margin to platform intermediaries. |
| Cellular LPWAN Module Integration | Enables real-time tracking beyond Bluetooth range without smartphone tethering dependency. |
Research Methodology
A standing panel of firmware engineering directors, veterinary clinic procurement managers, pet specialty retail buyers, and cloud infrastructure architects provided ongoing calibration across the analysis window. Primary interviews with these stakeholders combined with secondary validation against FCC equipment authorization databases, EU CE marking registries, TELEC certification listings, and veterinary practice management software integration documentation. Bottom-up unit economics modeling and top-down market sizing triangulated volume and value outputs.
Consistency checks validated projections against external benchmarks including smart home device adoption curves, pet expenditure elasticity studies, and connected hardware subscription attachment rates across adjacent consumer electronics categories. Segmentation dimensions modeled encompass product type, end user archetype, technology maturity tier, and distribution channel structure. CAGRs derive from regression analysis of historical premium pet expenditure growth correlated with smart home penetration indices and regulatory harmonization timelines.
Underlying assumptions cover sustained lithium-polymer cost stability, continued ISM band availability, and veterinary diagnostic integration adoption, with deviation risk concentrated in Taiwan Semiconductor capacity constraints and cybersecurity breach liability framework crystallization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Waste Removal Services Market
Pet Care Products
Dog Food and Snacks Market
Pet Care Products
Malaysia Pet Food Market
Pet Care Products
Pet Grooming Supplies Market
Pet Care Products
China Cat Litter Market
Pet Care Products
Pet Jerky Treat Market
Pet Care Products
Pet Food Pulverizer Market
Pet Care Products
Pet Slow Feeder Bowl Market
Pet Care Products
Asia-Pacific Pet Treats Market
Pet Care Products
Frozen Pet Food Market
Pet Care Products
Europe Cat Food Market
Pet Care Products
Animal-Based Pet Protein Market
Pet Care Products
Southeast Asia Pet Care Market
Pet Care Products
South Africa Pet Boarding Market
Pet Care Products
Brazil Pet Food Market
Pet Care Products
Dog Litter Boxes Market