

Pet Food Pulverizer Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Food Pulverizer Market Insights
A shortage of trained millwrights and process engineers with pulverizer-specific expertise is unwinding capacity expansion timelines across the industry. Bühler AG leverages its Swiss engineering heritage and global service network to sustain premium positioning in high-throughput installations. ANDRITZ Group anchors its competitive stance through backward integration into die and roller manufacturing for companion feed systems. Hosokawa Micron Group specializes in precision air-classification technology that differentiates its pin mill offerings for super-premium pet food applications.
Pet food pulverizers are mechanical size-reduction machines that fracture dry or semi-moist feed ingredients through impact, shear, or attrition forces, typically operating at rotor speeds between 1,800 and 3,600 RPM to achieve target particle distributions between 100 and 800 microns. Their primary commercial purpose is to create uniform particle surfaces that optimize extrusion efficiency, nutrient digestibility, and palatability in finished pet food products. Hammer mill configurations dominate volume demand due to their operational simplicity and lower capital threshold, though pin mill systems capture disproportionate margin pools in the ultra-fine particle segment where specialty and therapeutic diets require sub-200-micron consistency. Aquatic feed applications represent the fastest-growing demand vector within the application dimension, as fish meal replacement trends intensify processing complexity for sinking and floating pellet formulations.
FDA enforcement of the Food Safety Modernization Act's preventive controls for animal food mandates hazard analysis and validated kill-step documentation, directly shaping pulverizer sanitation design and material traceability requirements. The EPA's National Emission Standards for Hazardous Air Pollutants for feed manufacturing facilities constrains dust collection and ventilation configurations, influencing capital allocation toward enclosed hammer mill systems with integrated filtration. Stakeholders must monitor evolving state-level clean-air mandates and decide whether to standardize on HEPA-integrated pulverizer platforms or maintain regional equipment differentiation strategies.
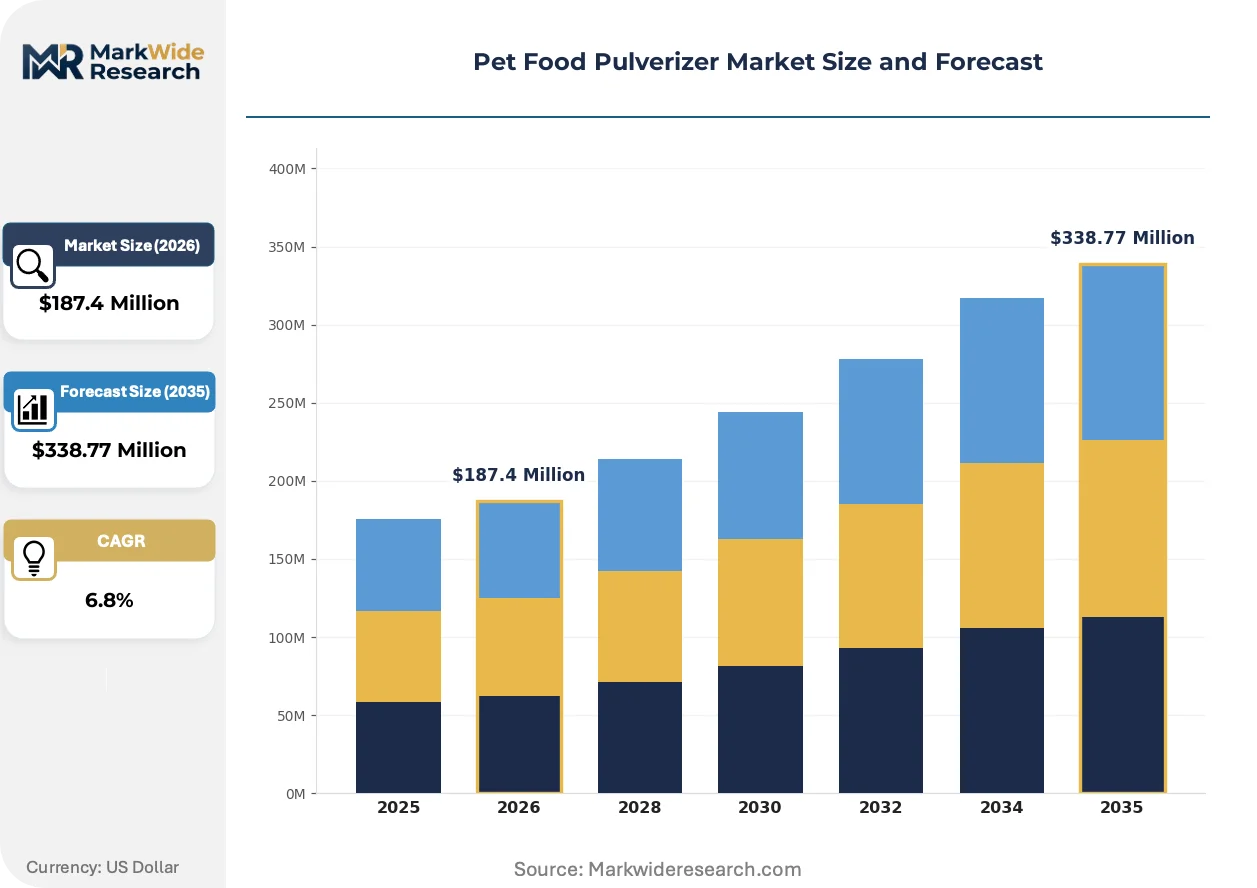
Market Dynamics
Premiumization in companion animal nutrition is compressing particle-size tolerance windows, forcing pulverizer manufacturers to engineer air-classification systems that deliver sub-200-micron consistency at industrial throughput rates. FDA enforcement of preventive controls under the Food Safety Modernization Act is simultaneously mandating validated kill-step documentation and sanitary design standards that favor enclosed systems with integrated filtration.
Growth Catalysts
- AAFCO Nutritional Density Standards:Tighter formulation requirements in the United States are compelling manufacturers to invest in precision pulverizers that ensure uniform nutrient distribution across batch volumes.
- Aquatic Feed Expansion:Fish meal replacement trends in salmon and shrimp aquaculture are intensifying demand for pulverizers capable of processing alternative protein sources at sub-300-micron specifications.
- Specialized Therapeutic Diets:Veterinary prescription foods for renal, diabetic, and gastrointestinal conditions require ultra-fine particle processing that only pin mill configurations can reliably achieve.
Market Restraints
- Stainless Steel Input Volatility:Grade 316L and 304 alloy price swings are compressing fabrication margins for sanitary-grade pulverizer housings and contact surfaces.
- Millwright Talent Concentration:Skilled technicians with pulverizer-specific commissioning expertise cluster disproportionately in Germany, Switzerland, and the United States, constraining deployment velocity elsewhere.
- EPA NESHAP Compliance Burden:The National Emission Standards for Hazardous Air Pollutants for feed manufacturing facilities is extending capital recovery timelines for hammer mill installations lacking integrated dust collection.
Strategic Opportunities
- Insect Protein Processing:Black soldier fly and mealworm meal integration into premium pet foods creates demand for pulverizers optimized for chitin-rich substrates with variable moisture content.
- Extended Producer Responsibility Schemes:EU packaging waste directives are incentivizing pulverizer retrofits that enable closed-loop processing of post-consumer pet food packaging into fiber additives.
- Telemetric Condition Monitoring:IoT-enabled vibration and temperature sensing is opening subscription-based service revenue streams for pulverizer OEMs serving large-scale manufacturers.
Industry Challenges
- Sanitary Design Certification Delays:Third-party validation of 3-A sanitary standards for pet food contact surfaces is extending new product introduction cycles by 8-14 months.
- Legacy Control System Integration:Retrofitting digital particle-size analyzers into existing hammer mill lines requires custom PLC programming that strains in-house engineering capacity.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Food Pulverizer Market Trends and Innovations
Precision air-classification technology is rewriting competitive boundaries between hammer mill and pin mill architectures, while regulatory digitization and buyer consolidation are reshaping how pulverizer capabilities are specified, procured, and serviced across the value chain.
Variable frequency drive rotor control is supplanting fixed-speed pulley configurations in mid-capacity installations. Large-scale manufacturers in the United States and Germany are adopting VFD-equipped hammer mills to enable real-time particle-size adjustment without mechanical downtime. This technology is supplanting the traditional capital-versus-flexibility tradeoff that historically segmented the market between high-volume fixed installations and lower-throughput adjustable systems.
REACH authorization requirements for cobalt and nickel compounds in wear-resistant coatings are accelerating ceramic and tungsten carbide substitution in classifier wheels and grinding elements. European pulverizer fabricators are reformulating contact surface specifications to preempt substance restrictions. Specialty diet manufacturers with EU export exposure are prioritizing equipment suppliers with demonstrated compliance documentation for SVHC-free material certifications.
Consolidated procurement by multinational pet food conglomerates is compressing vendor qualification timelines while extending contract durations. Technical specification authority is migrating from plant engineers to centralized category managers who bundle pulverizer acquisitions with extrusion and drying line investments. This concentration is most visible in North America, where three manufacturers account for the majority of greenfield capacity additions and are standardizing on preferred equipment platforms to reduce spare parts complexity.
Pet Food Pulverizer Market Segmentation
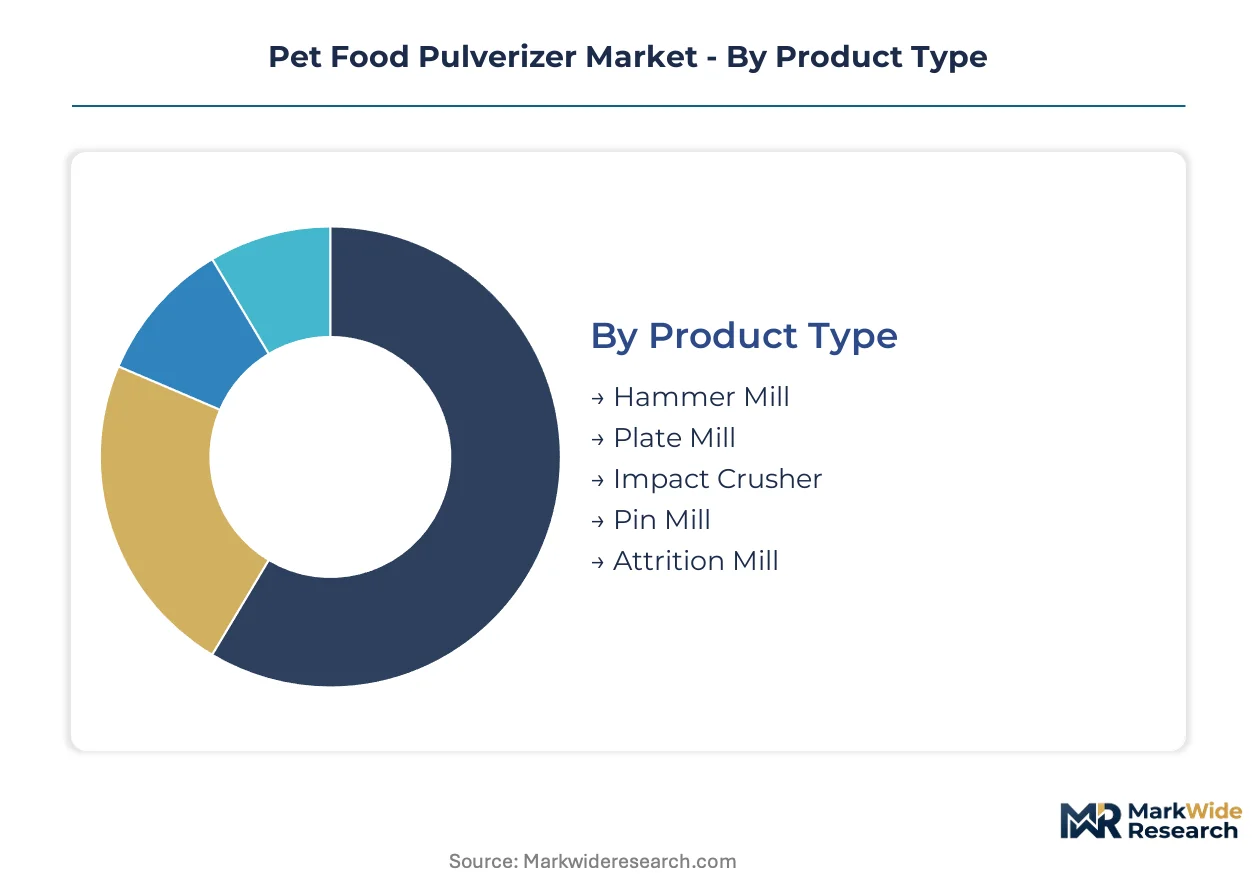
Pulverizer specification patterns diverge sharply across regulatory jurisdictions, with FDA sanitary design mandates in the United States, REACH substance restrictions in Europe, and GB standards compliance in China each favoring distinct equipment configurations. Understanding these segment boundaries enables manufacturers to align R&D pipelines with enforceable technical requirements rather than aspirational performance metrics.
Product Type:
FDA preventive controls under the Food Safety Modernization Act favor enclosed system architectures that simplify validated kill-step documentation and reduce contamination vectors during routine sanitation cycles.
- Hammer Mill:Rotor assemblies fitted with swinging hammers fracture ingredients through repeated impact against breaker plates, achieving 200-800 micron distributions at throughputs exceeding 20 tonnes per hour. Demand concentrates among large-scale pet food manufacturers in the United States and Germany where capital efficiency and operational simplicity outweigh precision requirements. EPA NESHAP compliance burdens are accelerating adoption of integrated dust collection configurations that enclose the grinding chamber.
- Pin Mill:Counter-rotating pin discs generate high-velocity particle-on-particle collisions, delivering sub-200-micron consistency essential for therapeutic diet formulations. Specialty and prescription food producers in Switzerland and the United States specify these systems for renal and diabetic pet food lines where nutrient density uniformity directly impacts veterinary efficacy claims. REACH authorization pressures on cobalt-containing wear coatings are driving tungsten carbide substitution in European installations.
- Plate Mill:Corrugated grinding plates operate at close tolerances for controlled shear reduction of oilseeds and fibrous ingredients.
- Impact Crusher:High-speed rotor assemblies with rigid hammers process tougher raw materials including bone meal and mineral premixes.
- Attrition Mill:Dual-disc configurations with adjustable gap settings excel at processing heat-sensitive ingredients where temperature control preserves nutritional value.
Established volume favors Hammer Mill; emerging adoption favors Pin Mill.
Particle Size:
Cost tier differentiation separates commodity producers seeking operational simplicity from premium manufacturers investing in precision air-classification infrastructure.
- Coarse:600-800 micron distributions suit extrusion pre-processing where subsequent cooking modifies final texture. High-volume dry dog food manufacturers in China specify coarse pulverization to minimize energy consumption and maximize line throughput.
- Ultra-Fine:Sub-100 micron specifications enable suspension stability in wet pet food emulsions and enhance palatability in senior diet formulations. Super-premium manufacturers in Germany and the United States deploy multi-stage classification systems to achieve these tolerances without thermal degradation of protein fractions.
- Medium:300-600 micron range balances processing efficiency with extruder feed consistency for mainstream formulations.
- Fine:150-300 micron distributions optimize nutrient surface area for digestive absorption in high-performance working dog diets.
- Micro:Sub-50 micron specifications serve specialized applications including pharmaceutical-grade nutritional supplements and research-grade reference materials.
Mainstream production gravitates toward Medium; margin expansion concentrates in Ultra-Fine.
Application:
Customer type stratification distinguishes commodity feed compounders from vertically integrated pet food manufacturers with captive R&D capabilities.
- Dog Food:Volume leadership across all particle size categories reflects the species' dietary diversity from economy kibble to veterinary prescription formulations. Manufacturers in the United States account for the largest installed base of precision pulverizers serving this segment.
- Aquatic Feed:Fish meal replacement trends in salmon and shrimp aquaculture demand sub-300-micron processing of insect meal, single-cell proteins, and plant concentrates to achieve target buoyancy and leaching resistance. This application is expanding most quickly within the analysis window as aquaculture capacity builds in Norway and Chile.
- Cat Food:Palatability-driven particle specifications emphasize uniform texture and minimal fines generation to prevent selective feeding behavior.
- Bird Feed:Seed and pellet hybrid formulations require gentle reduction to preserve oil integrity in oilseed components.
- Equine Feed:Larger particle tolerances accommodate the species' digestive physiology while molasses coating compatibility influences equipment selection.
Current capacity concentrates in Dog Food; steepest expansion trajectory appears in Aquatic Feed.
End User:
Supply concentration among multinational conglomerates in North America and Western Europe shapes procurement patterns toward standardized platforms with global service support.
- Pet Food Manufacturers:Integrated producers with captive extrusion and drying lines specify pulverizers as subsystem components within capital-intensive process trains. Centralized category management at three dominant North American manufacturers is compressing vendor qualification timelines.
- Feed Processors:Toll milling operations serving regional pet food brands prioritize equipment flexibility to accommodate diverse raw material specifications and batch sizes.
- Specialty Bakeries:Human-grade pet treat producers specify sanitary-design pulverizers with 3-A certification to support clean-label marketing claims.
- Nutritional Labs:Research and quality control facilities demand analytical-grade particle consistency for method validation and reference material preparation.
Procurement authority consolidates among Pet Food Manufacturers; equipment differentiation persists in Nutritional Labs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA enforcement of preventive controls under the Food Safety Modernization Act anchors demand patterns in the United States, while regulatory divergence across major manufacturing jurisdictions creates distinct equipment specification clusters.
United States
Specialized therapeutic diets for renal and diabetic conditions drive precision pulverizer procurement among vertically integrated pet food manufacturers. EPA National Emission Standards for Hazardous Air Pollutants mandate integrated dust collection configurations that extend capital recovery timelines for hammer mill installations. Three dominant manufacturers headquartered in the Midwest and Northeast are standardizing on preferred equipment platforms to reduce spare parts complexity across their production networks.
Germany
Aquatic feed expansion for salmon and shrimp aquaculture intensifies demand for sub-300-micron processing systems capable of handling alternative protein sources. REACH authorization requirements for cobalt and nickel compounds in wear-resistant coatings accelerate ceramic and tungsten carbide substitution in classifier wheel specifications. Millwright talent clusters disproportionately in Bavaria and Baden-Württemberg, constraining deployment velocity for capacity expansions elsewhere in Europe.
China
High-volume dry dog food manufacturing prioritizes coarse pulverization configurations that minimize energy consumption and maximize line throughput. GB standards compliance for feed machinery safety and sanitation shapes domestic equipment specifications distinct from Western regulatory frameworks. Yangtze River Delta and Pearl River Delta industrial corridors concentrate greenfield capacity additions for both domestic consumption and export-oriented production.
Switzerland
Super-premium pet food formulations requiring sub-200-micron consistency anchor demand for precision air-classification technology. Swissmedic-aligned quality protocols for veterinary prescription foods elevate sanitary design requirements beyond baseline EU standards. Zurich and Basel metropolitan areas host engineering-intensive suppliers leveraging Swiss manufacturing heritage to sustain premium positioning in global markets.
Norway
Fish meal replacement trends in Atlantic salmon aquaculture drive specialized pulverizer specifications for insect meal and single-cell protein processing. The Norwegian Food Safety Authority enforces strict documentation requirements for feed ingredient traceability that favor enclosed system architectures. Coastal processing clusters from Bergen to Ålesund are expanding capacity for export-oriented aquatic feed production serving European and Asian markets.
Pet Food Pulverizer Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with precision air-classification specialists commanding margin premiums while standardized hammer mill fabricators compete on capital efficiency and service network density. The vendor base stratifies across three tiers: integrated process technology conglomerates with captive grinding element manufacturing, mid-cap specialists focused on sanitary-design configurations for regulated markets, and regional fabricators serving price-sensitive toll milling operations. Dominant competitive moves include backward integration into wear-resistant component production and geographic expansion through acquisition of local service providers.
Among Swiss and German engineering conglomerates, Bühler AG and ANDRITZ Group exemplify the integrated process technology archetype, leveraging in-house manufacturing capabilities for grinding elements and die systems. Hosokawa Micron Group occupies a specialist position within the precision air-classification tier, serving super-premium and therapeutic diet manufacturers with sub-200-micron processing requirements. These three entities anchor the competitive structure by representing distinct strategic postures: full-line integration, component captive supply, and precision technology specialization.
| Leading Market Players |
|---|
| Bühler AG |
| ANDRITZ Group |
| Hosokawa Micron Group |
| Schenck Process Holding GmbH |
| Prater Industries |
| Stedman Machine Company |
| Franklin Miller |
| Bepex International |
| CPM Holdings |
| Others |
Pricing and Supply Chain Analysis
Long-term equipment supply contracts with take-or-pay provisions dominate procurement between pulverizer OEMs and multinational pet food manufacturers, locking in stainless steel alloy pricing visibility while constraining buyer flexibility to switch suppliers during capacity expansion cycles. These arrangements concentrate pricing power among Swiss and German engineering conglomerates with captive grinding element manufacturing capabilities.
Pricing Analysis
Geographic price spreads widen between North American installations subject to FDA sanitary design mandates and Chinese domestic equipment serving coarse-pulverization requirements. Three-tier pricing structure across premium pin-mill systems, standard hammer-mill configurations, and economy-grade toll-milling equipment reflects certification grade and after-sales service bundling. Cost compression in the economy tier intensifies because Grade 316L stainless steel price volatility compresses fabrication margins. Contract manufacturers and toll milling operations exhibit highest price sensitivity, while vertically integrated pet food conglomerates prioritize performance guarantees over unit economics.
Supply Chain Analysis
Inbound logistics costs from Hamburg and Rotterdam port congestion periodically strain delivery timelines for European-sourced precision air-classification components destined for North American assembly facilities. Component manufacturing concentrates in Germany, Switzerland, and China, with classifier wheels and grinding elements drawing from cobalt-substituted tungsten carbide and ceramic formulations. Single-source vulnerability persists for sub-200-micron pin mill assemblies requiring Swissmedic-aligned quality protocols. Distribution runs through OEM-direct channels for large-scale manufacturers and regional distributor networks serving toll milling operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted toward three dominant North American pet food manufacturers consolidating procurement authority through centralized category management, compressing vendor qualification timelines while extending contract durations across extrusion and drying line investments.
For Market Incumbents: Consolidate service network density in the United States and Germany to defend against emerging Asian equipment fabricators competing on capital efficiency. Backward integration into die and roller manufacturing for companion feed systems anchors margin retention as stainless steel input volatility intensifies. Prioritize 3-A sanitary certification maintenance to sustain premium positioning against mid-cap specialists.
For New Entrants and Emerging Players: FDA Food Safety Modernization Act compliance fast-tracks offer entry pathways into specialty therapeutic diet manufacturing segments where precision pulverization requirements exceed commodity equipment capabilities. Target aquatic feed processing in Norway and Chile as the most penetrable application expansion, leveraging fish meal replacement trends demanding sub-300-micron alternative protein processing. Pursue telemetric condition monitoring subscriptions as a differentiated go-to-market angle.
For Investors and Strategic Acquirers: Precision air-classification technology specialists with demonstrated SVHC-free material certifications represent compelling acquisition targets as REACH authorization pressures reshape European equipment specifications. Long-term viability hinges on exposure to super-premium pet food formulation growth and veterinary prescription diet regulatory expansion. Monitor EPA NESHAP enforcement intensity as an inflection indicator for enclosed system architecture demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wear-Resistant Components | Captive supply of tungsten carbide grinding elements insulates margin compression from cobalt price volatility. |
| Telemetric Condition Monitoring Platform Launch | IoT-enabled vibration sensing opens recurring revenue streams with large-scale manufacturers in the United States. |
| 3-A Sanitary Certification Fast-Track | Accelerated validation reduces new product introduction cycles for therapeutic diet equipment specifications. |
| Aquatic Feed Processing Capacity Expansion | Norwegian and Chilean salmon aquaculture buildout demands sub-300-micron insect meal processing systems. |
| REACH-Compliant Material Substitution Program | Ceramic classifier wheel formulations preempt European substance restrictions on cobalt-containing coatings. |
Research Methodology
Cross-validation between technical director interviews at pulverizer OEMs and regulatory filing analysis anchors the qualitative findings on FDA preventive controls and EPA NESHAP compliance requirements. Primary fieldwork engaged plant engineers at pet food manufacturing facilities, category procurement managers at multinational conglomerates, millwright technicians with pulverizer-specific commissioning expertise, and aftermarket service heads at regional distributor networks. Secondary validation drew from FDA FSMA guidance documents, EPA enforcement records, AAFCO nutritional density standards, and SEC 10-K filings from listed process technology conglomerates. Bottom-up equipment shipment analysis and top-down pet food production capacity modeling were triangulated to constrain volume estimates.
Sensitivity analysis on stainless steel alloy price trajectories and millwright labor availability stress-tested base-case assumptions across the projection horizon. Segmentation dimensions modeled include pulverizer type, particle size specification, application category, and end-user procurement structure, with geographic regulatory clusters treated as distinct demand envelopes. CAGRs were derived from fitted growth curves against historical capacity expansion patterns and forward-looking greenfield project announcements. Industry-specific forecast inputs incorporated fish meal replacement rates in aquaculture and veterinary prescription diet formulation growth.
Underlying assumptions cover sustained FDA enforcement of preventive controls, stable REACH authorization timelines for wear-resistant coatings, and continued buyer consolidation among North American pet food manufacturers, with deviation risk concentrated in EPA NESHAP rulemaking intensity and Chinese GB standards harmonization with Western sanitary design protocols. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.