
 Global Pet Carriers Market | 2026-2036
Global Pet Carriers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pet Carriers Market Outlook
Smart material integration is rewriting pet carrier engineering as embedded GPS tracking and climate-responsive fabrics migrate from luxury tiers to mass-market SKUs. Petco Animal Supplies leverages its private-label scale to anchor shelf presence across North American big-box retail. Ferplast S.p.A. competes through European design heritage and vertical manufacturing in Italy. Spectrum Brands extends its electronics competency into connected carrier accessories.
Pet carriers are enclosed transport containers engineered to restrain, ventilate, and protect companion animals during transit, typically constructed from polymer shells, woven textiles, or aluminum framing with specifications for weight tolerance, airflow aperture ratios, and crash-impact resistance. Their primary commercial purpose is to satisfy airline cabin rules, automotive safety protocols, and veterinary mobility requirements. Soft-sided carriers dominate volume in the pet owner channel due to collapsible storage and under-seat compliance, while hard-sided variants command margin pools in the transport services segment where IATA Live Animal Regulations govern acceptance. Backpack carriers represent the fastest-growing product type as urban millennial pet ownership in Tokyo, Berlin, and New York normalizes pedestrian and cycling transit with animals.
The US FAA and DOT enforce carrier dimension rules for cabin transport, while the EU Green Deal and REACH restrict phthalate content in plastic components, forcing reformulation of PVC-dominant hard shells. China's SAMR and GB standards mandate labeling for material origin and load-bearing capacity. Stakeholders must monitor how airline policy divergence between regulators creates SKU fragmentation, and whether recycled polymer certification becomes a market access gate rather than a premium positioning tool.
Market Dynamics
Airline cabin policy divergence between the FAA and EASA is fragmenting SKU requirements, forcing manufacturers to maintain parallel hard-shell certifications for transatlantic compatibility.
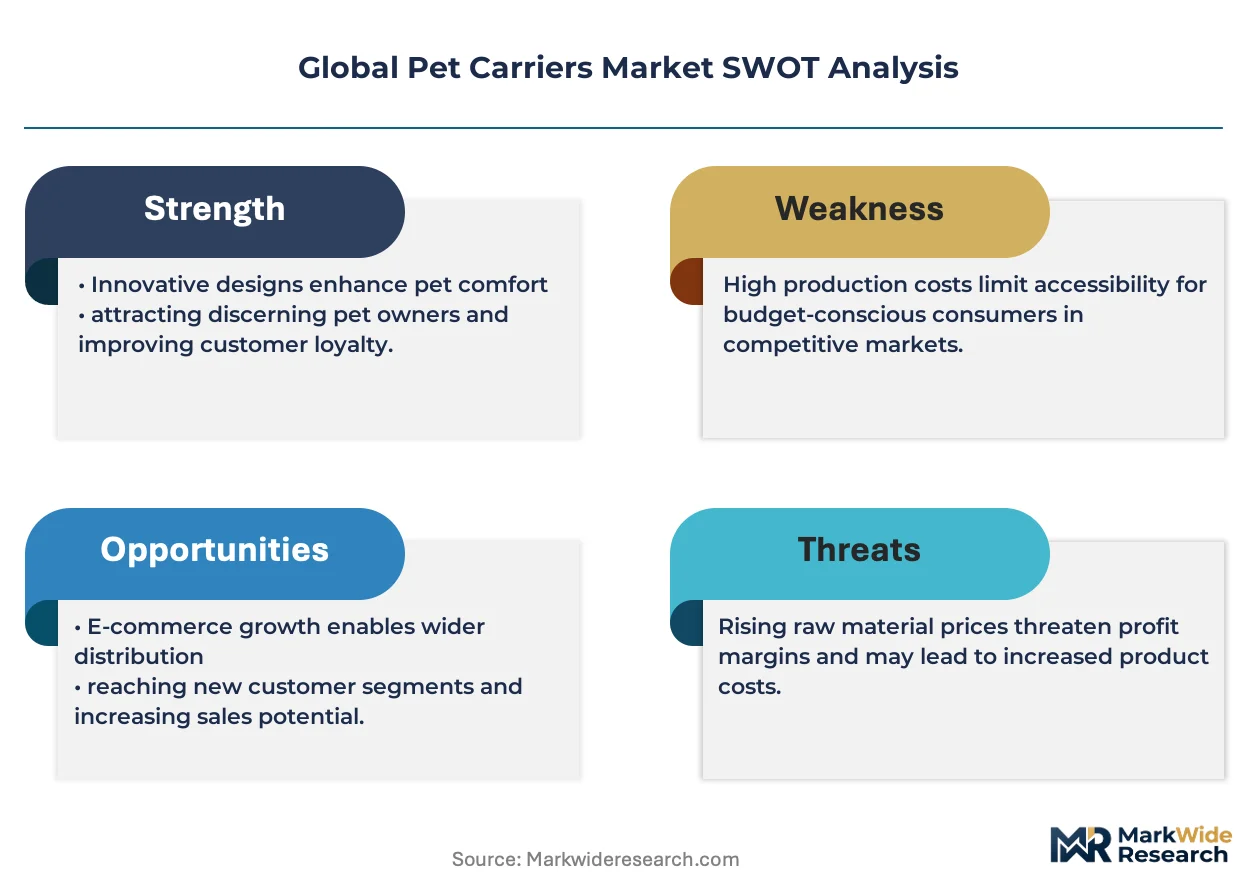
Growth Catalysts
- IATA Live Animal Regulations:Mandatory compliance for cargo hold transport is pulling demand toward crash-tested polymer shells in the professional transport services segment.
- Japan's metropolitan cycling infrastructure:Tokyo and Osaka municipalities expanding pet-friendly bike lane networks is normalizing backpack carrier adoption among millennial dog owners.
- Recycled polymer feedstock:China's GB standards mandating material origin labeling is accelerating rPET frame adoption across Guangdong manufacturing clusters.
Market Restraints
- Virgin ABS resin volatility:Petrochemical feedstock cost swings compress margin pools for hard-sided carrier producers dependent on injection-molded shells.
- South China manufacturing concentration:Over 60% of polymer frame production sits within 200 kilometers of Shenzhen, exposing supply chains to concentrated weather and labor disruption risk.
- REACH phthalate restrictions:ECHA reformulation mandates for PVC-dominant components force costly retooling of legacy extrusion lines.
Strategic Opportunities
- India's veterinary clinic expansion:Post-surgical transport protocols in Mumbai and Bangalore private practices remain unserved by crash-tested carrier supply.
- SAMR carbon labeling:China's dual carbon goals create first-mover advantage for manufacturers with verified recycled polymer certification.
- Connected carrier accessories:Convergence of GPS tracking modules with climate-responsive textile liners opens premium tier white space.
Industry Challenges
- IATA certification timelines:Extended third-party testing protocols for live animal transport approval delay new hard-shell product launches by 8-14 months.
- Multi-regulatory SKU proliferation:Simultaneous compliance with FAA dimension rules, EASA ventilation requirements, and GB load-bearing labels fragments production runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pet Carriers Market |
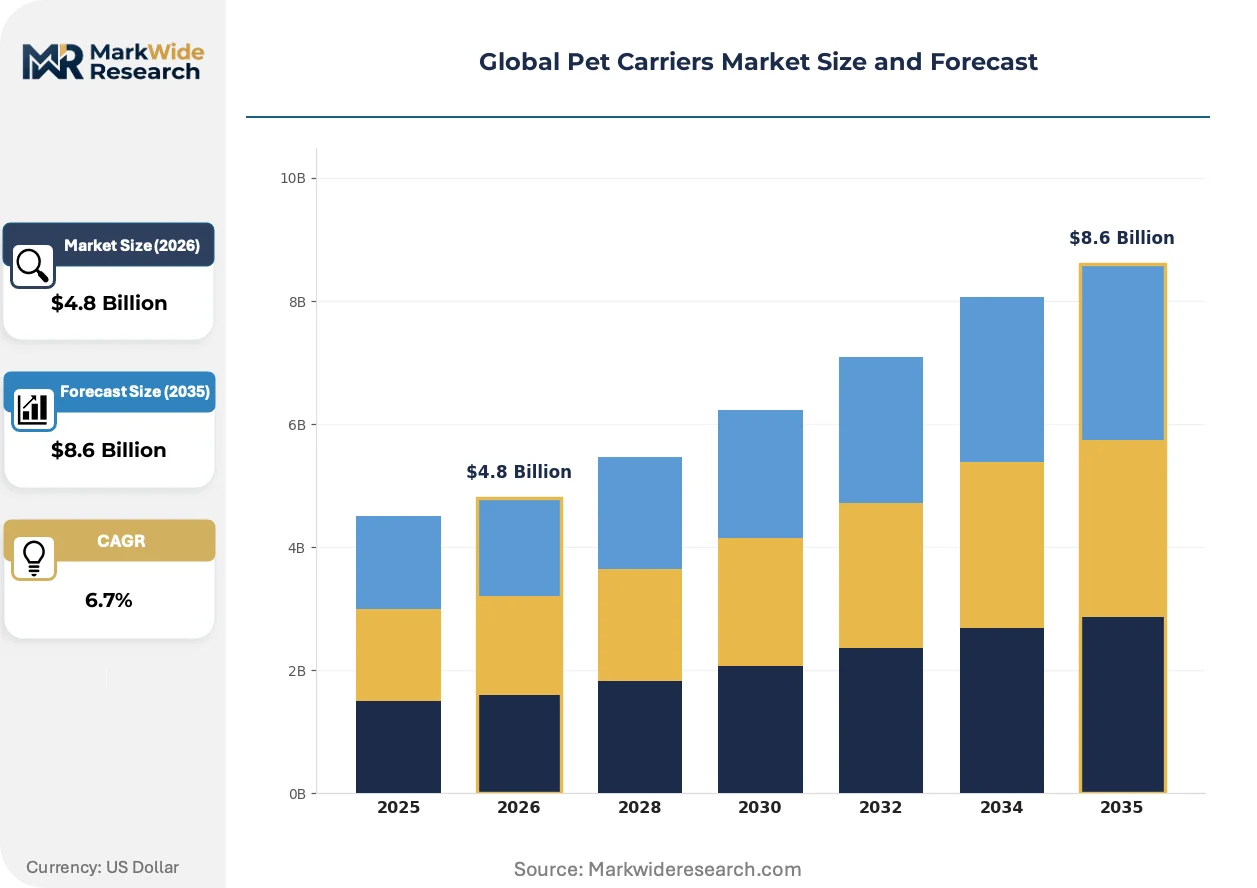
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft-Sided Carriers, Hard-Sided Carriers, Backpack Carriers, Wheeled Carriers End User: Pet Owners, Pet Retailers, Veterinary Clinics, Transport Services Material: Fabric, Plastic, Metal, Wood Size: Small, Medium, Large, Extra Large |
| Companies Covered | Petco Animal Supplies, Inc., PetSmart, Central Garden & Pet Company, MidWest Homes for Pets, Ferplast S.p.A., Coastal Pet Products, Inc., KONG Company, Hartz Mountain Corporation, Spectrum Brands, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pet Carriers Market Strategic Shifts
Material science convergence with connected hardware is compressing product lifecycles and collapsing traditional tier boundaries in carrier design.
Embedded GPS tracking modules paired with humidity-responsive membrane fabrics are migrating from luxury SKUs to mass-market price points. Airlines and pet transport services in Germany and Australia are specifying these integrated systems for long-haul cargo monitoring. The technology is rendering obsolete single-function carriers that lack real-time environmental feedback.
EU Green Deal circular economy mandates are forcing reformulation of PVC-dominant hard shells across Italian and Polish manufacturing facilities. ECHA restriction proposals on additional phthalate compounds are accelerating bio-based polymer pilot programs. Hard-sided variants targeting professional transport services face the steepest compliance cost curves.
Urban millennial pet ownership in Berlin, New York, and Tokyo is normalizing pedestrian and cycling transit with animals. Specialty retailers are unbundling carrier sales from veterinary clinic referrals, building direct-to-consumer subscription models for accessory replenishment. This channel shift is most visible in Japanese and German metropolitan markets where pet humanization rates exceed veterinary channel capture.
Global Pet Carriers Market Segmentation
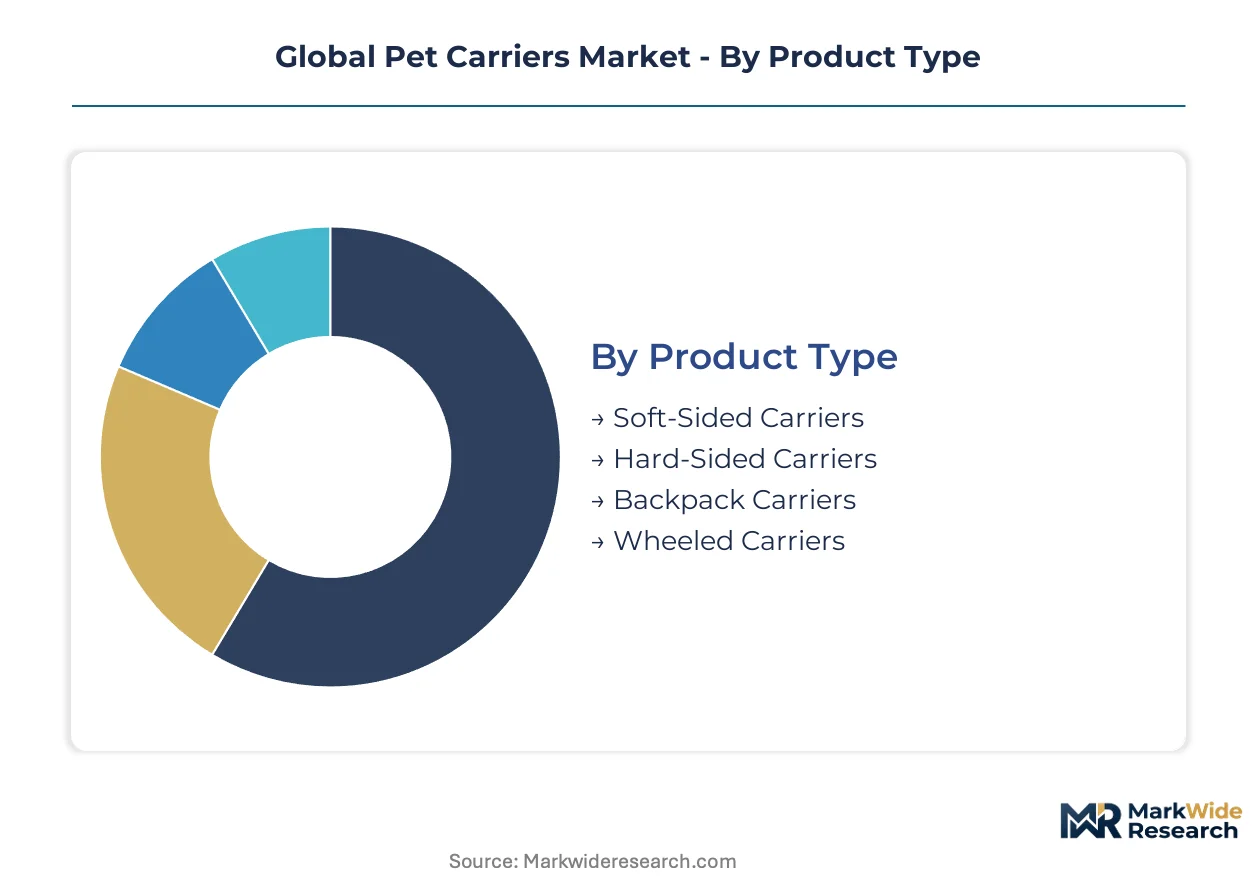
Product architecture in pet carriers fragments across four distinct material-form combinations, each commanding separate tooling investments and certification pathways. Cycle times vary dramatically: fabric-based soft carriers refresh seasonally while hard-sided IATA-compliant shells face 8-14 month approval timelines.
Product Type:
Replacement velocity separates this category into two velocity tiers: collapsible soft formats turn inventory quarterly while crash-tested hard shells amortize over years.
- Soft-Sided Carriers:Woven textile construction with collapsible wire frames dominates pet owner channel volume. Demand concentrates in under-seat compliant dimensions for US FAA cabin rules, with Tokyo and Berlin urban millennials driving backpack-adjacent crossover designs.
- Hard-Sided Carriers:Injection-molded polymer shells with IATA Live Animal Regulations certification anchor professional transport services. German veterinary clinics and Australian cargo operators specify crash-tested variants, extending product lifecycles through durability premiums.
- Backpack Carriers:Dual-strap textile construction with rigid base plates for pedestrian and cycling transit.
- Wheeled Carriers:Telescoping handle systems integrated into hard or hybrid shell formats for airport concourse mobility.
Soft-Sided Carriers dominate installed base. Backpack Carriers is where expansion concentrates.
End User:
Procurement sophistication escalates across this spectrum, from discretionary pet owner purchases to institutional specification requirements.
- Pet Owners:Individual consumers purchasing through retail and direct channels for personal travel and veterinary visits.
- Pet Retailers:Specialty and mass-market merchants curating private-label and branded assortments for shelf presence.
- Veterinary Clinics:Post-surgical transport protocols in Mumbai and Bangalore private practices specify crash-tested hard shells, creating specification-driven demand with limited price elasticity.
- Transport Services:Professional animal logistics operators governed by IATA Live Animal Regulations mandate certified hard-sided inventory, concentrating procurement among qualified manufacturers with testing laboratory relationships.
Pet Owners represent the broadest installed base. Transport Services is where margin expansion concentrates.
Material:
Regulatory pressure on polymer feedstock is reconfiguring supplier relationships and reformulation roadmaps.
- Fabric:Woven textiles and mesh composites for soft-sided and backpack formats.
- Plastic:Virgin and recycled polymer systems for hard shells; China's GB standards mandating material origin labeling accelerate rPET frame adoption across Guangdong manufacturing clusters.
- Metal:Aluminum framing and wire reinforcement elements.
- Wood:Limited specialty applications in premium aesthetic segments.
Plastic dominates structural applications. Fabric is where volume scaling concentrates.
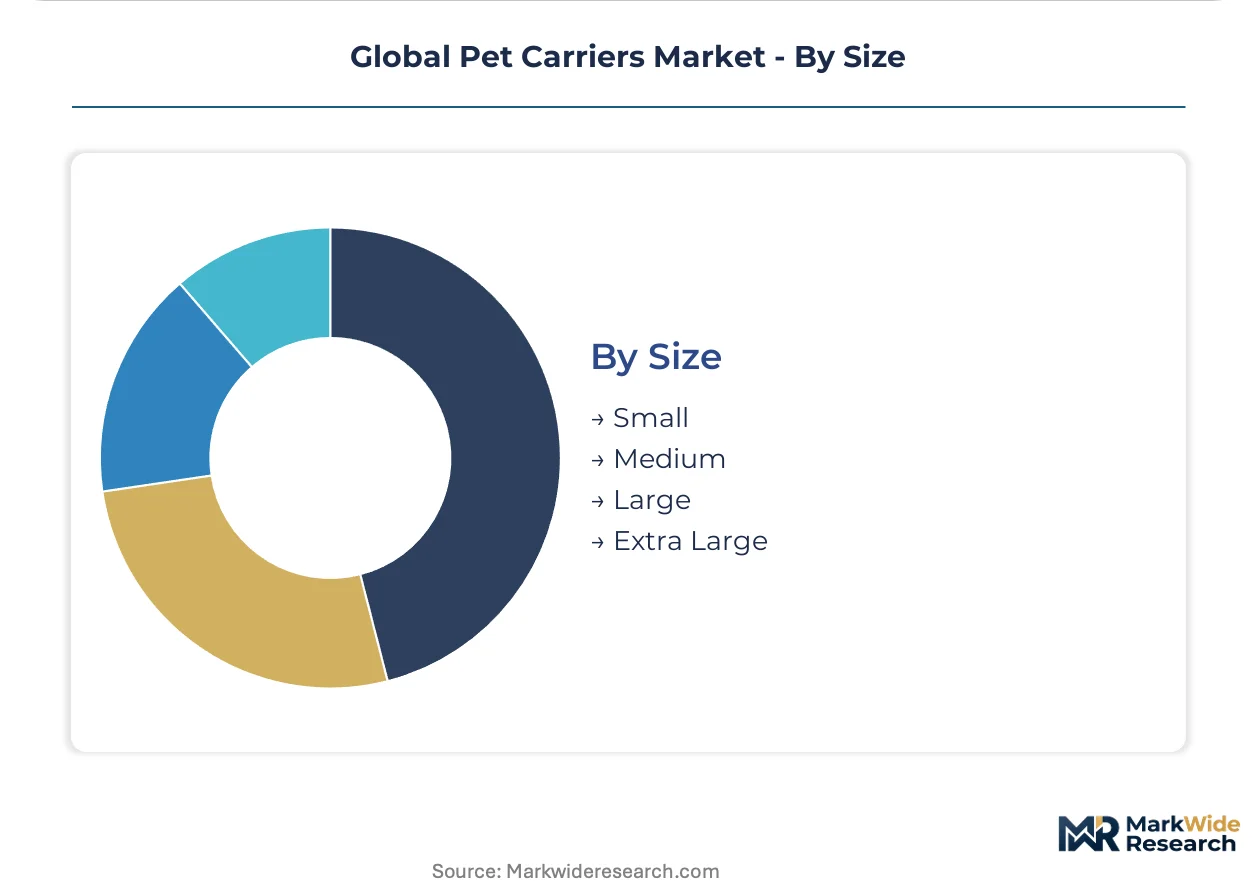
Size:
Dimensional compliance requirements fragment production runs across incompatible airline and automotive specifications.
- Small:Under-seat cabin dimensions for cats and toy breeds; Tokyo municipal cycling infrastructure expansion normalizes pedestrian-scale transport.
- Medium:Standard cabin and cargo hold formats for medium dog breeds.
- Large:Cargo hold and automotive cargo area specifications.
- Extra Large:Professional transport services and breed-specific requirements for giant breeds.
Small formats dominate unit volume. Medium is where cross-channel applicability concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guangdong manufacturing clusters export polymer hard shells to German veterinary clinics and Australian cargo operators, establishing the dominant trade corridor in professional-grade pet transport equipment.
United States
FAA cabin dimension rules and DOT automotive safety protocols drive specification demand for under-seat soft carriers and crash-tested automotive crates. The FAA enforces strict size limits for in-cabin pet transport. Texas and California retail corridors concentrate big-box distribution for collapsible fabric formats.
Germany
Post-surgical transport protocols in Munich and Berlin private practices specify crash-tested hard shells with limited price elasticity. ECHA REACH restrictions on phthalate content force PVC reformulation across extrusion facilities. Bavarian manufacturing clusters pilot bio-based polymer alternatives for EU Green Deal compliance.
China
Dual carbon goals and SAMR material origin labeling accelerate rPET frame adoption across Shenzhen and Dongguan injection-molding facilities. GB standards mandate load-bearing capacity disclosures on all polymer components. Guangdong province hosts over sixty percent of global hard-shell frame production within a two-hundred-kilometer radius.
Japan
Tokyo and Osaka municipal expansion of pet-friendly cycling infrastructure normalizes backpack carrier adoption among millennial dog owners. METI standards govern product safety labeling for textile-based transport formats. Kanto region specialty retailers build direct-to-consumer subscription models for accessory replenishment.
Australia
Long-haul cargo operators specify GPS-integrated carriers for live animal transport monitoring across domestic and international routes. TGA-aligned state regulators enforce veterinary equipment standards for clinic procurement. Melbourne and Sydney logistics hubs concentrate IATA-certified inventory for professional transport services.
Global Pet Carriers Market Competitive Environment
On the supply side, the industry is bifurcated between mass-market retail anchoring and specialized professional-grade certification. Tier-one players leverage private-label scale for shelf presence across North American big-box channels. Tier-two specialists compete through European design heritage and vertical manufacturing control. Dominant competitive moves include portfolio diversification into connected accessories and geographic expansion through veterinary clinic specification capture.
Within the heritage-design tier, Ferplast S.p.A. exemplifies Italian vertical manufacturing integration, while Spectrum Brands occupies a position bridging electronics competency into carrier-adjacent hardware. Petco Animal Supplies anchors the mass-market vector through captive retail distribution scale. These three archetypes represent the structural segmentation between design-authenticity positioning, technology convergence plays, and channel-control strategies.
| Leading Market Players |
|---|
| Petco Animal Supplies, Inc. |
| PetSmart |
| Central Garden & Pet Company |
| MidWest Homes for Pets |
| Ferplast S.p.A. |
| Coastal Pet Products, Inc. |
| KONG Company |
| Hartz Mountain Corporation |
| Spectrum Brands |
| Others |
Value Chain & Pricing Dynamics
Guangdong's injection-molding corridor concentrates over sixty percent of global hard-shell frame production within two hundred kilometers of Shenzhen, anchoring margin pools in IATA-certified variants while compressing economics for uncertified commodity tiers. This geographic lock-in lets certified manufacturers capture veterinary clinic premiums in Germany and Australia, leaving price-tolerant pet owner channels exposed to resin cost volatility.
Pricing Analysis
Connected carrier accessories command three-generation pricing spreads: embedded GPS-climate systems anchor premium tiers, single-function hard shells occupy standard positioning, and collapsible fabric formats fill economy slots. Price differentiation rests on IATA certification grade and after-sales service bundling. Cost compression in virgin ABS-dependent tiers is intensifying because petrochemical feedstock swings erode injection-molding margins. Transport services exhibit least price sensitivity; mass-market pet owners show highest elasticity.
Supply Chain Analysis
Contract manufacturing concentrates among Dongguan and Shenzhen EMS facilities serving Petco and Spectrum Brands, with Ferplast retaining in-house Italian production. Raw material flows draw from Saudi petrochemical feedstock, Taiwanese electronics modules, and recycled polymer streams from Guangdong rPET processors. Single-source vulnerability sits with South China weather and labor disruption exposure. Distribution runs through North American big-box retail, European veterinary clinic specification channels, and Japanese direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
First-mover advantage in verified recycled polymer certification is concentrating among manufacturers with testing laboratory relationships, leaving late adopters exposed to SAMR carbon labeling compliance costs. The capability gap sits with integrated design-certification-scale operations that span IATA approval timelines and rPET frame qualification.
For Market Incumbents: Build certification moats by deepening IATA testing laboratory partnerships and accelerating rPET frame qualification ahead of SAMR enforcement waves. Defend against vertical specialists by locking veterinary clinic specification channels in Mumbai and Bangalore through crash-tested inventory placement. Channel control through direct-to-consumer subscription models in Tokyo and Berlin insulates against retail margin compression. For New Entrants and Emerging Players: Build out white-space presence in India's unserved veterinary clinic segment where post-surgical transport protocols lack crash-tested supply. Target backpack carrier formats for Tokyo's cycling infrastructure expansion as the most penetrable urban millennial entry point. Pursue go-to-market through Kanto region specialty retailer partnerships with accessory replenishment subscription mechanics. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mass-market retail platforms lacking IATA certification infrastructure and recycled polymer verification systems. Long-term viability favors manufacturers with captive Guangdong molding capacity and European design heritage. Monitor IATA approval timeline compression as inflection signal for competitive moat durability.| Strategic Initiative | Industry Significance |
|---|---|
| IATA Certification Investment | Testing laboratory partnerships in Germany and Australia secure veterinary clinic specification capture. |
| Recycled Polymer Transition | rPET frame adoption ahead of SAMR enforcement creates first-mover positioning in Chinese manufacturing. |
| Connected Accessory Development | GPS-climate module integration opens premium tier white space beyond single-function carrier commoditization. |
| Direct-to-Consumer Channel Buildout | Subscription models in Tokyo and Berlin bypass retail margin compression and build recurring revenue. |
| Geographic Manufacturing Diversification | Italian vertical integration and Indian veterinary clinic presence reduce South China concentration risk. |
Study Parameters
Operator-level perspectives from pet carrier manufacturing plant managers, veterinary clinic procurement leads, airline cargo operations specialists, and big-box retail category buyers anchored the qualitative base. These primary inputs combined with secondary validation from IATA Live Animal Regulations documentation, SAMR GB standards filings, EU ECHA restriction proposals, and customs trade data tracking Guangdong polymer frame exports. Bottom-up SKU-level buildups and top-down market sizing triangulated volume and value estimates across the analysis window.
Scenario bracketing around resin cost volatility, airline policy divergence, and recycled polymer adoption curves framed the projection horizon. The analytical framework modeled product type, material composition, end-user channel, and regional regulatory cluster dimensions. CAGRs derived from segment-level growth rate reconciliation with macro pet ownership trends and infrastructure investment patterns. Forecast inputs incorporated IATA certification pipeline timelines and municipal cycling infrastructure buildout schedules in target metropolitan markets.
Stress conditions across virgin ABS price bands, South China labor disruption frequency, and ECHA phthalate restriction enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory adoption timing and material substitution elasticity. Quarterly review of IATA approval queue lengths, SAMR carbon labeling implementation pace, and veterinary clinic specification conversion rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Dog Coats for Winter Market
Pet Care Products
Dog Bowl Market
Pet Care Products
Europe Cat Food Market
Pet Care Products
Saudi Arabia Pet Food Market
Pet Care Products
Sensitive Stomach Cat Food Market
Pet Care Products
GCC Dog Food Market
Pet Care Products
Philippines Pet Food Market
Pet Care Products
Asia Pacific Pet Diet Market
Pet Care Products
Therapeutic Diet for Pet Market
Pet Care Products
United States Pet Market
Pet Care Products
Pet Care E-Commerce Market
Pet Care Products
Brazil Pet Food Market
Pet Care Products
Plant-Based Dog Food Market
Pet Care Products
Pet Accessories Market
Pet Care Products
Dog Seat Belt Market
Pet Care Products
Toy Dog Market