
 Cat Litter Product Market | 2026-2036
Cat Litter Product Market Size, Share, and Industry Trends Forecast 2026-2036
Cat Litter Product Market Intelligence
Multi-cat households is bifurcating demand away from single-pet owners toward volume-efficient, odor-control formulations. Church and Dwight Co. Inc. leverages its Arm & Hammer brand equity to dominate the clumping clay segment through retail shelf positioning. Nestlé SA (Purina) anchors its growth in specialized veterinary channels with prescription-grade litter solutions. Oil-Dri Corporation of America controls raw material costs through captive bentonite mining operations in the Western United States.
Cat litter products are granular absorbency media engineered from sodium bentonite clay, silica gel, or plant-based substrates such as pine and wheat, designed to encapsulate feline waste moisture and neutralize ammonia volatilization in confined indoor environments. Clumping clay formulations sustain the largest revenue pool due to established consumer habituation and superior liquid absorption kinetics, while silica gel competes on extended change intervals and reduced particulate dust emission. Wheat and corn substrates are capturing the fastest growth trajectory as pet owners navigate tightening municipal composting mandates and retailer sustainability scorecards.
The EPA monitors silica dust exposure thresholds in mining and manufacturing facilities, compelling producers to invest in pneumatic conveying and baghouse filtration systems that raise capital intensity for new entrants. The EU Green Deal and REACH frameworks restrict synthetic fragrance additives and mandate biodegradability disclosures on packaging sold in member states, diverting R&D expenditure toward enzymatic odor control and unbleached paper substrates. Stakeholders must monitor evolving state-level extended producer responsibility laws and pet food retail consolidation that threatens independent brand shelf access.
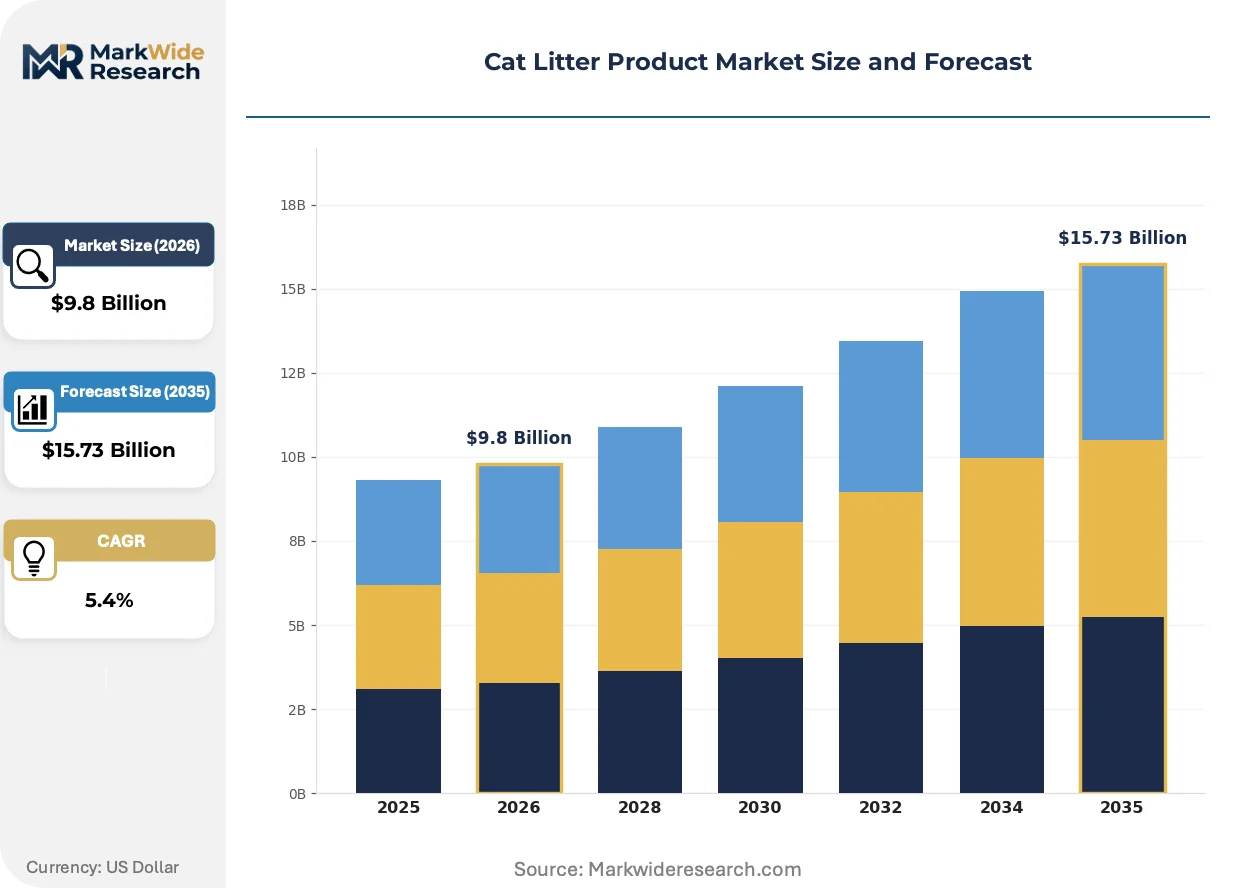
Market Dynamics
Multi-cat household formation is compressing purchase cycles and forcing manufacturers to engineer volume-efficient formulations with superior ammonia encapsulation kinetics. This demand compression is reshaping raw material sourcing priorities and retail shelf allocation strategies.
Growth Catalysts
- EU Green Deal biodegradability mandates:Municipal composting ordinances in member states are accelerating plant-based substrate adoption among urban pet owners seeking waste-stream compliance.
- Sodium bentonite mining consolidation in Wyoming and Montana:Captive clay reserves are securing supply continuity for clumping formulations amid volatile freight costs.
- Silica gel dust suppression technology:Pneumatic conveying upgrades in manufacturing facilities are expanding addressable markets for respiratory-sensitive consumers.
Market Restraints
- Bentonite clay price volatility:Energy-intensive kiln drying and diesel-dependent surface mining expose margins to fuel cost swings in the Western United States.
- REACH fragrance additive restrictions:ECHA scrutiny of synthetic odor maskers is forcing costly reformulation cycles for established scented product lines.
- Extended producer responsibility laws:California and New York packaging fee structures are elevating compliance burdens for national distribution networks.
Strategic Opportunities
- Veterinary prescription channel expansion:Therapeutic litter formulations for feline urinary syndrome are capturing margin premiums through clinic dispensing networks.
- Enzymatic odor control convergence with IoT sensors:Smart litter boxes with ammonia detection algorithms are creating bundled hardware-consumable revenue models.
- Subscription direct-to-consumer platforms:Auto-replenishment algorithms based on household pet count are disintermediating big-box retail dependence.
Industry Challenges
- Compostability certification timelines:BPI and OK Compost HOME verification processes delay plant-based product launches by 8-14 months.
- Baghouse filtration capex intensity:OSHA silica exposure limits mandate pneumatic system upgrades costing $2-4 million per production line.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cat Litter Product Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clumping Clay, Silica Gel, Pine, Wheat, Corn, Paper Application: Indoor Cats, Outdoor Cats, Multi-Cat Households, Kittens, Senior Cats Packaging Type: Bag, Box, Refill Pack, Tray, Tub, Bulk Container Customer Type: Pet Owners, Veterinary Clinics, Pet Stores, Cattery Facilities, Animal Shelters |
| Companies Covered | Church and Dwight Co. Inc., Healthy Pet L.P., Nestlé SA (Purina), Kent Pet Group, Dr. Elsey's, The Clorox Company, Oil-Dri Corporation of America, Laviosa Chimica Mineraria SpA, Mars Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cat Litter Product Market Strategic Shifts & Innovations
Wheat and corn substrate engineering is disrupting established clay economics. Three parallel developments are compressing legacy formulation advantages.
Enzymatic odor neutralization chemistry is supplanting synthetic fragrance masking in premium formulations. Pet owners with respiratory sensitivities are migrating to enzyme-treated substrates at accelerating velocity. This biological approach is compressing differentiation timelines for fragrance-dependent brands.
REACH framework restrictions on volatile organic compounds are forcing disclosure reforms across EU member state packaging. Manufacturers must now quantify biodegradability percentages and substrate sourcing geography. Small-format plant-based entrants are capturing shelf space faster than incumbents can reformulate legacy lines.
Urban apartment dwellers are compressing purchase quantities while elevating performance requirements. Subscription algorithms tied to household pet density are replacing bulk warehouse purchasing. This pattern concentrates in dense metropolitan corridors where storage constraints and delivery convenience outweigh per-unit cost optimization.
Cat Litter Product Market Segmentation
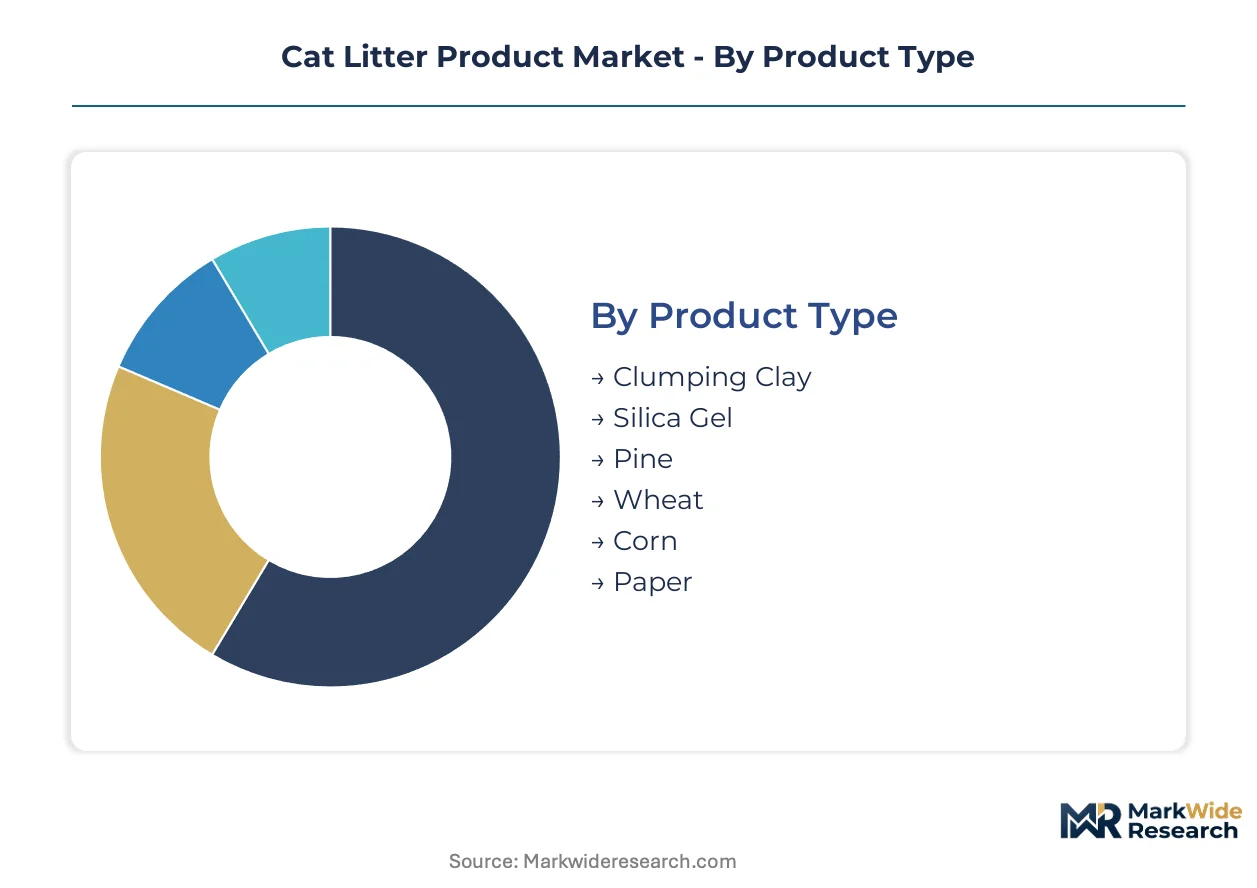
Cat litter manufacturers must navigate divergent margin structures across substrate chemistry, packaging formats, and institutional channels. Each segment carries distinct capital requirements, regulatory exposure, and pricing power that reshape portfolio allocation decisions.
Product Type:
Margin pools concentrate in clumping formulations where captive bentonite reserves create supply-side moats, while plant-based substrates command premium positioning through sustainability certifications.
- Clumping Clay:Sodium bentonite formulations deliver superior liquid absorption kinetics through particle agglomeration. Demand concentrates in suburban United States households with multiple cats, where purchase frequency and volume requirements favor established retail distribution.
- Silica Gel:Amorphous silica beads absorb moisture through capillary action, extending change intervals to 3-4 weeks. Urban apartment dwellers in Japan and South Korea prioritize dust suppression and reduced maintenance frequency over per-unit cost.
- Pine:Kiln-dried softwood pellets from southeastern United States timber operations offer natural enzymatic odor control.
- Wheat:Processed grain starch clumps through gluten activation, appealing to composting-mandate households in EU member states.
- Corn:Ground cob substrates leverage agricultural byproduct streams from Midwestern United States processing facilities.
- Paper:Recycled cellulose pellets target post-surgical cats and respiratory-sensitive owners through low-dust certification.
The dominant share belongs to Clumping Clay, while Wheat is closing the gap fastest.
Application:
Volume concentration varies sharply by feline life stage and housing density, with multi-cat formations driving the steepest consumption curves.
- Multi-Cat Households:Formulations engineered for ammonia encapsulation under high waste load conditions command 40-60% volume premiums over standard grades. United States census tracts with above-median pet density show disproportionate adoption of specialized odor-control chemistry.
- Indoor Cats:Confined-environment requirements elevate dust suppression and tracking resistance specifications. Japanese metropolitan markets prioritize space-efficient packaging and reduced particulate emission above absolute absorbency metrics.
- Outdoor Cats:Seasonal or transitional use cases favor lower-cost disposable substrates.
- Kittens:Non-clumping formulations prevent ingestion risks during litter training protocols.
- Senior Cats:Low-entry tray compatibility and soft-texture substrates address mobility limitations.
Multi-Cat Households anchor volume concentration, though Indoor Cats generate the highest per-kilogram pricing realization.
Packaging Type:
Cost-to-serve economics diverge dramatically between retail-ready units and institutional bulk formats.
- Bag:Flexible polyethylene and woven polypropylene formats dominate mass retail shelf allocation through stackability and print surface area. California extended producer responsibility fees now apply to flexible plastic packaging, elevating compliance costs for national distributors.
- Box:Corrugated retail packaging supports premium positioning through structural rigidity and graphic reproduction quality.
- Refill Pack:Lightweight pouches reduce shipping cube for direct-to-consumer replenishment channels.
- Tray:Pre-filled disposable units capture convenience-oriented purchasers in convenience store and pharmacy channels.
- Tub:Rigid plastic containers with resealable lids target bulk purchasers seeking moisture protection.
- Bulk Container:Flexible intermediate bulk bags serve cattery and shelter operations with 500-2000 kg procurement cycles.
Bag formats retain plurality share, though Refill Pack adoption accelerates most quickly in subscription commerce.
Customer Type:
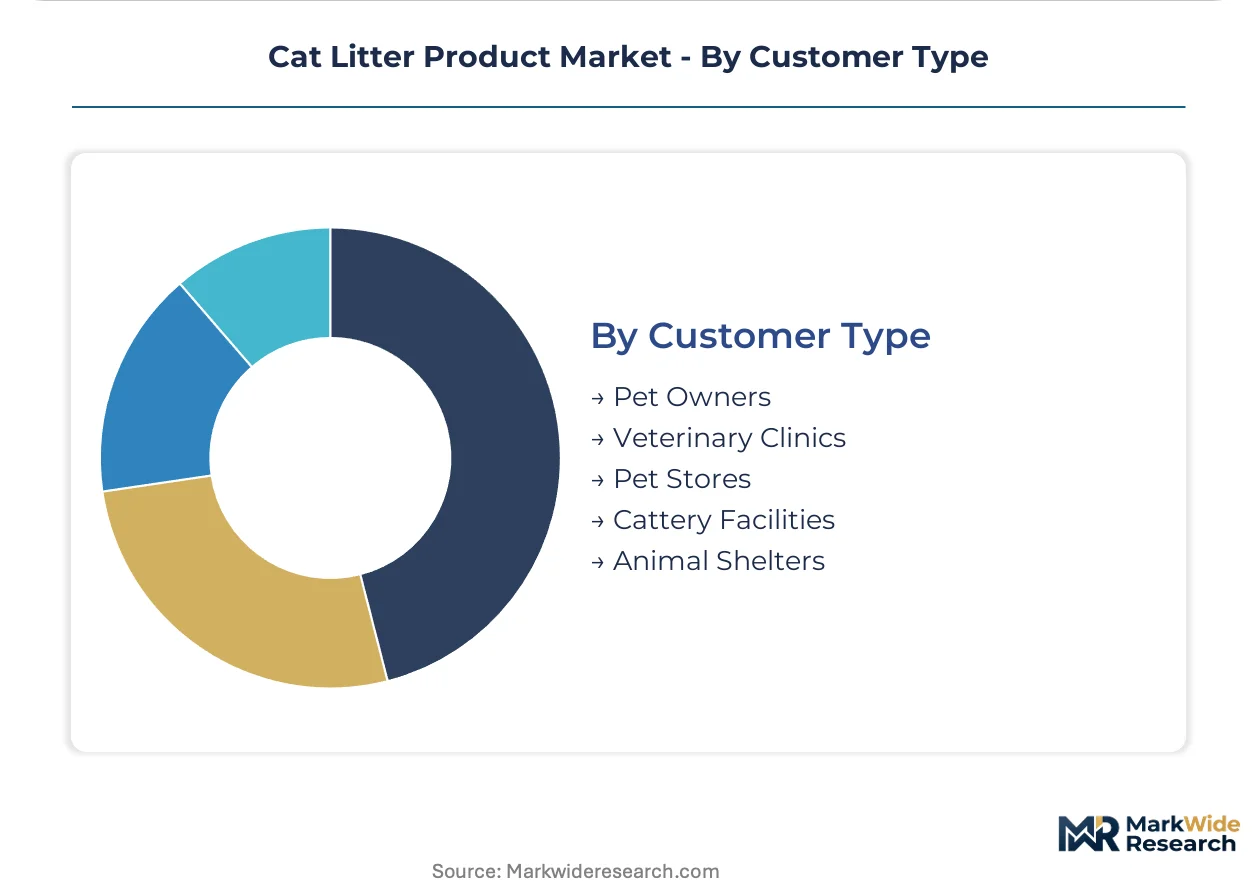
Channel-specific procurement patterns create distinct margin profiles across consumer, professional, and institutional endpoints.
- Pet Owners:Direct purchasing decisions prioritize sensory attributes—dust emission, fragrance profile, and tracking residue—over unit economics. United States big-box retail consolidation has compressed independent brand shelf access, concentrating volume with portfolio-holding conglomerates.
- Veterinary Clinics:Prescription-grade therapeutic formulations for feline lower urinary tract disease command dispensing margins through clinic-exclusive SKUs. Purina and Hill's Pet Nutrition dominate this channel through veterinary practice loyalty programs.
- Pet Stores:Specialty retailers maintain curated assortments emphasizing natural and grain-free positioning.
- Cattery Facilities:Commercial breeding operations prioritize total cost per cat-day through bulk procurement and automated litter systems.
- Animal Shelters:Municipal and nonprofit operations face budget constraints that favor donated or subsidized inventory.
Pet Owners generate absolute volume concentration, yet Veterinary Clinics deliver superior margin per transaction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multi-cat households in suburban United States census tracts drive premium formulation demand, while EU composting mandates accelerate plant-based substrate adoption in dense metropolitan zones. Veterinary prescription channels concentrate in Japan and Germany. Raw material sourcing clusters around Wyoming bentonite reserves and Midwestern agricultural processing corridors.
United States
Suburban pet-dense regions in Texas, Florida, and California compress purchase cycles for volume-efficient, odor-control formulations. EPA silica dust exposure thresholds compel pneumatic conveying investments in Wyoming and Montana mining operations. Church and Dwight Co. Inc. leverages Arm & Hammer brand equity through dominant retail shelf positioning in mass-market channels.
Germany
REACH framework restrictions on synthetic fragrance additives force enzymatic odor control reformulation across premium product lines. EU Green Deal biodegradability mandates accelerate wheat and corn substrate adoption in Berlin and Munich apartment markets. Municipal composting ordinances in Bavaria and North Rhine-Westphalia elevate plant-based packaging compliance requirements.
Japan
Urban apartment dwellers in Tokyo and Osaka prioritize silica gel formulations for extended change intervals and reduced particulate dust emission. METI indoor air quality guidelines elevate respiratory sensitivity specifications above absolute absorbency metrics. Subscription direct-to-consumer platforms displace bulk warehouse purchasing in dense metropolitan corridors.
United Kingdom
Post-Brexit regulatory divergence creates compliance fragmentation for fragrance disclosure and substrate sourcing geography. London and Southeast England concentrate demand for lightweight refill pack formats suited to storage-constrained flats. Veterinary clinic dispensing networks for therapeutic urinary formulations expand through practice loyalty programs.
France
ANSM scrutiny of volatile organic compounds in scented products accelerates migration to enzyme-treated substrates in Paris and Lyon metropolitan areas. EU Green Deal packaging requirements mandate unbleached paper substrate disclosures. Compostability certification timelines delay plant-based product launches by 8-14 months for BPI and OK Compost HOME verification.
Cat Litter Product Market Key Industry Players
Player mix skews toward diversified consumer goods conglomerates with captive raw material positions and portfolio-holding structures with veterinary channel access. Market structure concentrates volume with three strategic archetypes: mining-integrated clay specialists, brand-equity-heavy retail dominators, and prescription-grade therapeutic formulators. Competitive moves center on backward integration into bentonite reserves and subscription algorithm development to disintermediate retail dependence.
Among mining-integrated specialists, Oil-Dri Corporation of America exemplifies captive supply control through Western United States bentonite operations. Church and Dwight Co. Inc. and Nestlé SA (Purina) occupy positions spanning retail shelf dominance and veterinary channel penetration respectively. These three anchors represent the archetype spectrum from upstream raw material security through brand equity leverage to specialized clinical dispensing networks.
| Leading Market Players |
|---|
| Church and Dwight Co. Inc. |
| Healthy Pet L.P. |
| Nestlé SA (Purina) |
| Kent Pet Group |
| Dr. Elsey's |
| The Clorox Company |
| Oil-Dri Corporation of America |
| Laviosa Chimica Mineraria SpA |
| Mars Incorporated |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between Wyoming bentonite miners and clumping clay manufacturers lock in supply continuity and price visibility across volatile diesel and kiln-drying cost cycles. These contracts insulate volume commitments from spot-market swings while exposing parties to indexation clauses tied to Western United States energy benchmarks.
Pricing Analysis
Cost-plus contracts with diesel and natural gas indexation dominate raw material procurement for sodium bentonite formulations. Three-tier pricing structure across premium, standard, and economy levels separates enzymatic odor-control formulations from fragrance-masked grades from unbranded bulk substrates. Pricing pressure stems from REACH-compliant reformulation costs and California extended producer responsibility fees. Veterinary clinic dispensing channels exhibit lowest price sensitivity; municipal shelter procurement shows highest.
Supply Chain Analysis
Wyoming and Montana anchor captive bentonite mining for clumping clay formulations, while Midwestern United States agricultural processing feeds wheat and corn substrate streams. Manufacturing draws from sodium bentonite reserves, silica gel precursors, and kiln-dried softwood pellets. Single-source vulnerability concentrates in Wyoming bentonite deposits exposed to EPA silica dust compliance costs. Distribution runs through mass retail shelf allocation, veterinary clinic networks, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Cat Litter Product Market sits in early-cycle expansion as EU Green Deal biodegradability mandates and municipal composting ordinances accelerate plant-based substrate penetration beyond legacy clay habituation.
For Market Incumbents: Consolidate backward integration into Wyoming bentonite reserves to defend against mining consolidation and freight cost volatility. Secure veterinary clinic dispensing exclusives for therapeutic urinary formulations before prescription-grade channels saturate. Prioritize enzymatic odor-control R&D to offset REACH fragrance additive restrictions eroding scented product margins. For New Entrants and Emerging Players: BPI and OK Compost HOME certification fast-tracks unlock shelf access in EU member states with mandatory composting ordinances. Target wheat substrate formulations in German and French metropolitan apartment markets where disposal compliance outweighs per-kilogram cost optimization. Launch direct-to-consumer subscription platforms with auto-replenishment algorithms tied to household pet density to bypass big-box retail gatekeeping. For Investors and Strategic Acquirers: The market sits at a premium-formulation expansion phase that favors mining-integrated specialists with captive clay reserves and veterinary channel access. Five-to-ten year viability hinges on regulatory compliance infrastructure and subscription algorithm capabilities. Monitor compostability certification timeline compression as inflection signal for plant-based substrate economics crossing threshold viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bentonite Reserves | Captive Wyoming mining operations insulate clumping clay margins from diesel cost volatility and supply disruption. |
| Enzymatic Odor Control Formulation Launch | Biological neutralization chemistry captures respiratory-sensitive consumers abandoning REACH-restricted synthetic fragrances. |
| Veterinary Prescription Channel Expansion | Clinic-exclusive therapeutic SKUs for feline urinary syndrome command dispensing premiums through practice loyalty programs. |
| Subscription Platform Development | Auto-replenishment algorithms based on pet count disintermediate retail dependence in storage-constrained urban corridors. |
| Compostability Certification Investment | BPI and OK Compost HOME verification accelerates EU shelf access under Green Deal biodegradability mandates. |
Research Approach
Operator-level perspectives from bentonite mining executives, pet retail category buyers, veterinary clinic procurement managers, and plant-based substrate R&D directors anchored the qualitative base. Primary interview insights combined with secondary validation from EPA silica exposure filings, EU ECHA REACH substance registrations, USDA agricultural processing statistics, and state-level extended producer responsibility legislation. Bottom-up substrate volume modeling and top-down retail channel value triangulation cross-checked segment estimates.
Sensitivity analysis tested forecast robustness across diesel price volatility scenarios, REACH enforcement intensity variations, and composting mandate adoption rates. Segmentation dimensions modeled include substrate chemistry, packaging format, application by feline life stage, and customer channel type across the projection horizon. CAGRs derived from historical volume elasticities applied to pet ownership demographic projections and regulatory compliance cost curves.
Underlying assumptions cover sustained EU Green Deal enforcement, Wyoming mining permit continuity, and subscription commerce penetration rates, with deviation risk concentrated in state-level packaging fee expansion and silica dust threshold revisions. Recalibration cycles align with material shifts in municipal composting ordinance adoption and veterinary channel consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Raw Pet Food Market
Pet Care Products
Europe Farrier Products Market
Pet Care Products
UAE Pet Boarding Market
Pet Care Products
Global Cat Trees and Towers Market
Pet Care Products
Pet Tick and Flea Prevention Market
Pet Care Products
Dog Nail Clippers Market
Pet Care Products
South Korea Organic and Natural Pet Food Market
Pet Care Products
Dog Perfume Market
Pet Care Products
Dog Raincoats Market
Pet Care Products
Pet Beds Market
Pet Care Products
Global Flea and Tick Product Market
Pet Care Products
UAE Dog Food Market
Pet Care Products
Indonesia Pet Care Market
Pet Care Products
Pet Selfie Tools Market
Pet Care Products
North America Pet Food Nutraceuticals Market
Pet Care Products
Pet Grooming Services Market