
 US Pet Food Market | 2026-2036
US Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
US Pet Food Market Intelligence
Clean-label formulation and cold-pressed processing is tilting production economics toward fresh and minimally processed formats. Nestlé Purina PetCare leverages its veterinary prescription channel to sustain margin-rich therapeutic nutrition lines. Mars Petcare Inc. anchors broad retail distribution through mass-market brands with manufacturing scale advantages. Freshpet specializes in refrigerated fresh diets, controlling cold-chain logistics as a competitive moat against conventional shelf-stable incumbents.
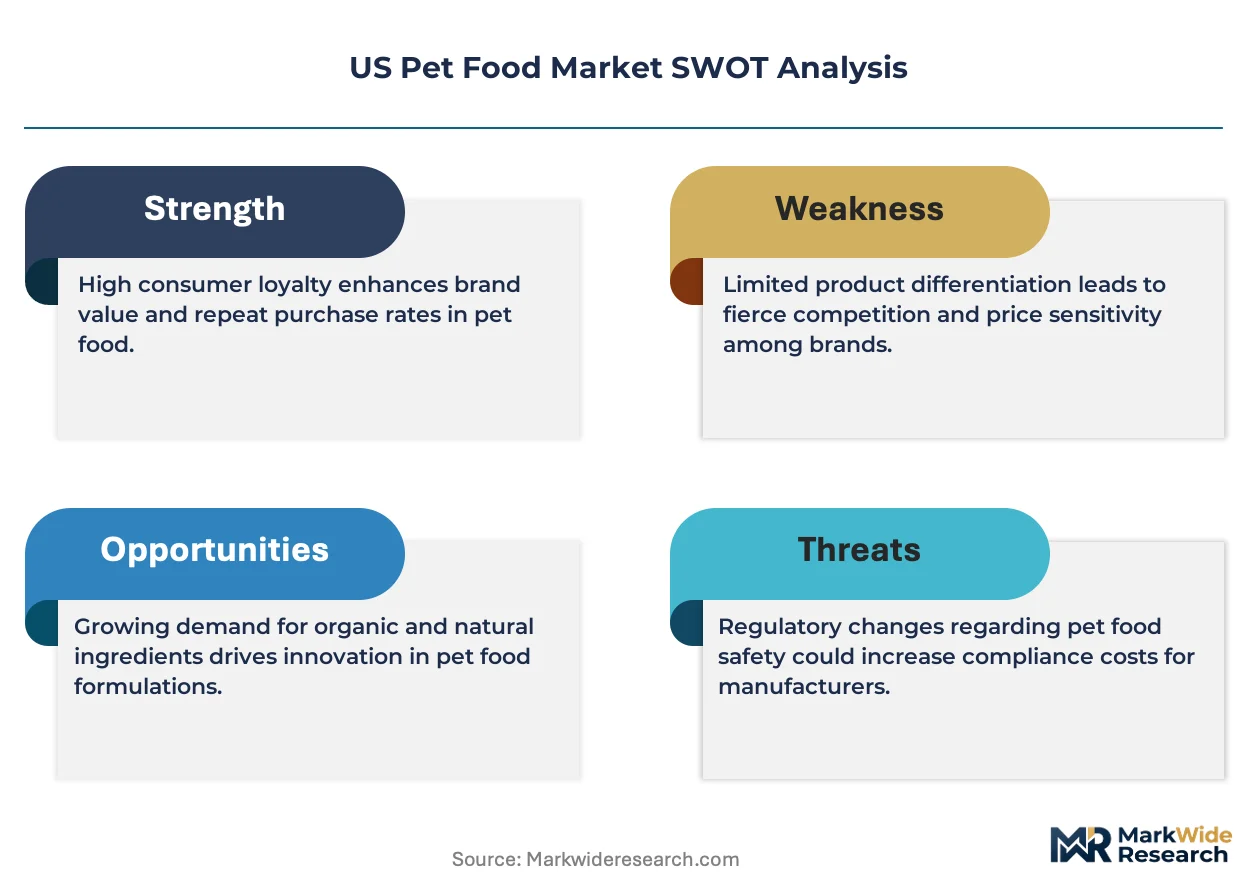
US pet food comprises formulated nutritional products for domestic companion animals, typically meeting AAFCO nutrient profiles through extrusion, canning, or minimal-processing techniques designed for species-specific digestibility and shelf stability. Dry food retains volume leadership due to cost efficiency and storage convenience, though raw food commands the fastest expansion as consumer skepticism toward synthetic additives deepens. Premium and organic price tiers capture disproportionate margin pools, while budget segments face compression from ingredient cost volatility and private-label encroachment.
The FDA's Center for Veterinary Medicine oversees feed ingredient safety, while AAFCO establishes model regulations adopted variably across states, creating compliance complexity for interstate distribution. USDA organic certification and state-level raw pet food pathogen testing requirements further stratify market access and production investment thresholds. Stakeholders must monitor evolving state laboratory testing mandates and the trajectory of FDA enforcement discretion on novel ingredients such as cultivated proteins.
Market Dynamics
Premiumization among millennial pet owners is compressing mid-tier shelf space as functional nutrition claims reshape manufacturer R&D priorities and veterinary channel partnerships.
Growth Catalysts
- AAFCO Model Regulation Adoption:State-level harmonization of nutrient profile standards reduces interstate compliance friction for multi-regional brands.
- Cold-Pressed Processing:Minimal-heat manufacturing preserves enzymatic activity in raw and fresh formats, attracting ingredient-conscious urban buyers.
- California-Texas-Florida Demand Cluster:Concentrated pet density in these three states creates efficient distribution anchor points for refrigerated logistics networks.
Market Restraints
- Protein Input Cost Volatility:Human-grade meat and poultry byproduct pricing fluctuates with commodity livestock markets, squeezing fresh-format margins.
- State Laboratory Testing Mandates:Pathogen screening requirements for raw pet food vary across jurisdictions, fragmenting production batch protocols.
- Synthetic Additive Skepticism:Consumer preference for clean-label formulations limits preservative options, shortening shelf stability windows for ambient products.
Strategic Opportunities
- Veterinary Prescription Channel Expansion:Therapeutic nutrition lines distributed through clinics capture higher price points and repeat purchase loyalty.
- USDA Organic Certification Tailwind:Federal organic seal differentiation commands retail price premiums in specialty pet retail channels.
- Direct-to-Consumer Subscription Models:Portion-customized fresh diets bypass traditional retail slotting fees and build recurring revenue streams.
Industry Challenges
- Cold-Chain Logistics Capex Intensity:Refrigerated transport and storage infrastructure demands substantial capital deployment for fresh-format entrants.
- FDA Novel Ingredient Approval Timelines:Center for Veterinary Medicine review pathways for cultivated proteins and insect meals extend product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Pet Food Market |
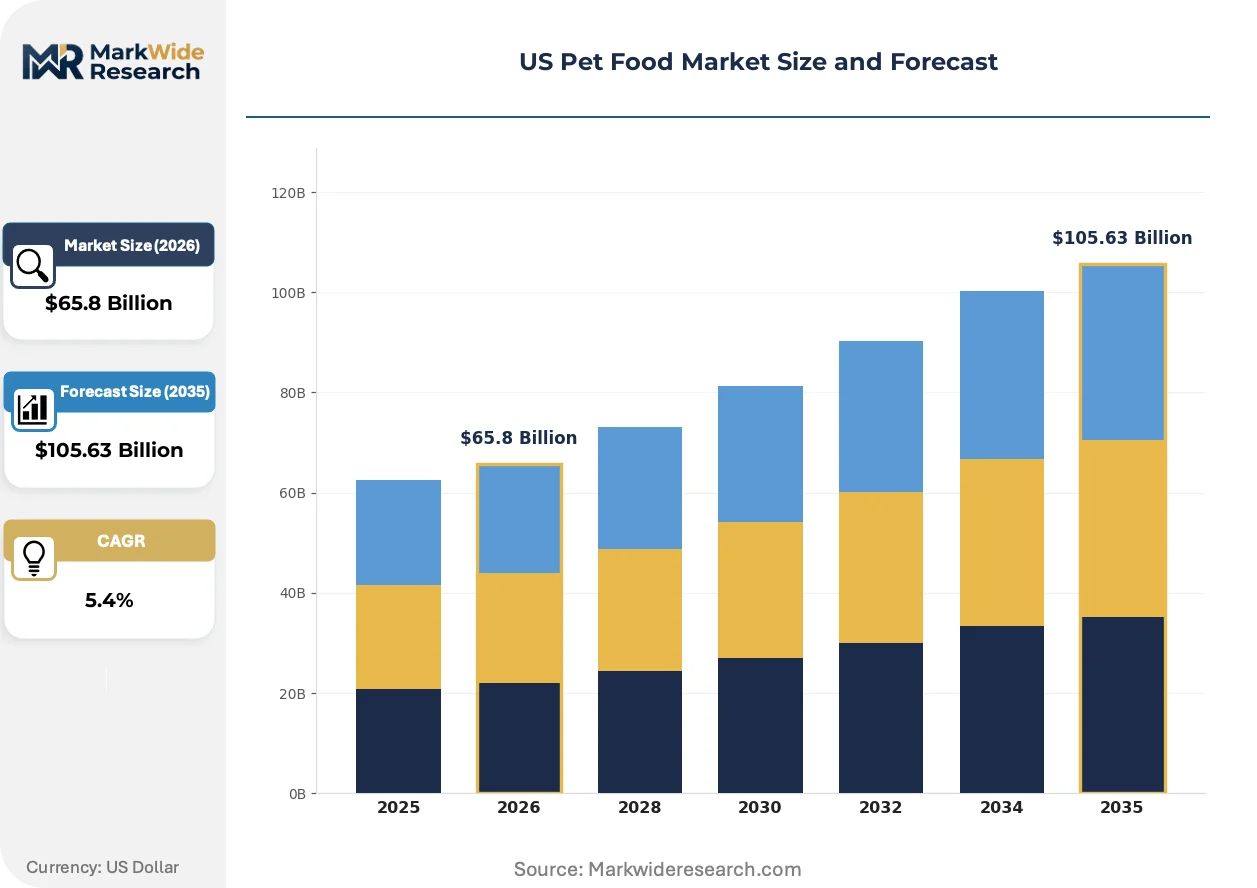
| Market Size in 2026 | $65.8 Billion |
| Market Size in 2035 | $105.63 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Raw Food Animal Type: Dogs, Cats, Fish, Birds Distribution Channel: Online Retailers, Supermarkets, Pet Shops, Wholesale Price Tier: Premium, Mid-Range, Budget, Organic |
| Companies Covered | Nestlé Purina PetCare, Mars Petcare Inc., Hill's Pet Nutrition, General Mills, Colgate-Palmolive, Blue Buffalo, Diamond Pet Foods, J.M. Smucker, Freshpet, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Pet Food Market Strategic Shifts & Innovations
Processing technology convergence with veterinary nutritional science is redefining product format boundaries, while regulatory clarity on alternative proteins accelerates investment in non-traditional ingredient supply chains.
High-pressure processing (HPP) applies isostatic pressure to eliminate pathogens without thermal degradation. Fresh-format manufacturers in Texas and Florida are scaling HPP lines to meet raw food safety mandates. This non-thermal pasteurization method is rendering obsolete conventional irradiation and chemical wash protocols for pathogen control in refrigerated diets.
FDA enforcement discretion on cultivated animal cell proteins is crystallizing into formalized Generally Recognized As Safe (GRAS) notification pathways. Pet food manufacturers face truncated ingredient approval timelines compared to human food analogs. Dry and canned segments monitor these developments most closely, as cost-competitive cultivated proteins threaten conventional rendering economics.
Subscription-based fresh diet delivery is displacing periodic retail stock-up behavior among urban millennial households. Direct-to-consumer platforms in California and New York capture recurring revenue through portion-calibrated meal plans. Veterinary clinics in metropolitan markets observe this channel shift most acutely, as clients seek convenience parity with human meal-kit services.
US Pet Food Market Segmentation
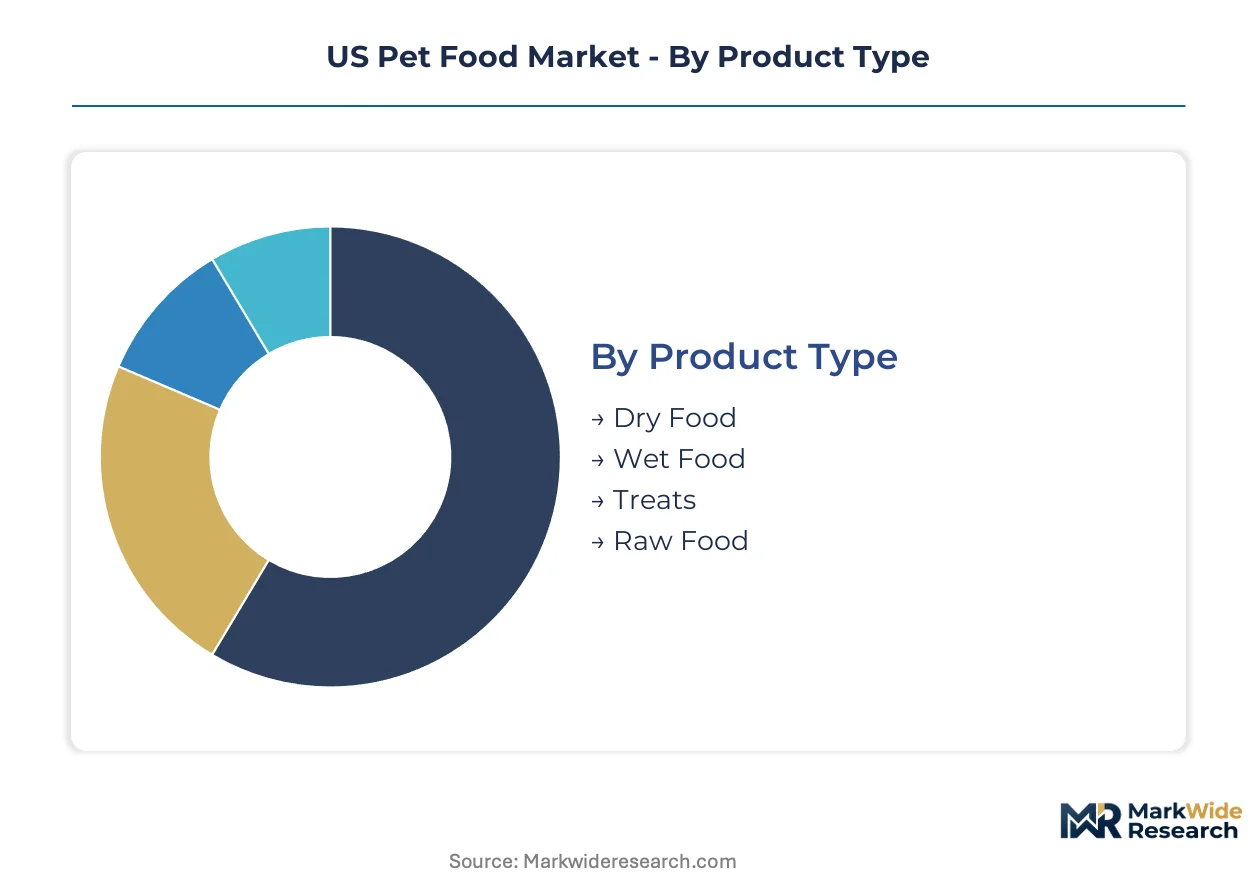
Product differentiation across the US Pet Food Market reflects divergent consumer priorities spanning convenience, nutritional philosophy, and disposable income alignment. Manufacturers calibrate formulation investments against channel-specific margin structures and state-level regulatory compliance thresholds.
Product Type:
Cost tier differentiation fundamentally separates manufacturing economics and cold-chain requirements across format categories.
- Dry Food:Extruded kibble formulations achieve shelf stability through moisture reduction below 10 percent, enabling ambient distribution without refrigeration infrastructure. Volume concentrates in California and Texas mass-market retail, where storage convenience and per-pound cost efficiency drive repeat purchase behavior among multi-pet households.
- Raw Food:Minimally processed meat, bone, and organ blends retain enzymatic activity through high-pressure processing or flash-freezing protocols. Demand clusters in Florida urban corridors, where FDA state-level pathogen testing mandates and millennial skepticism toward synthetic additives accelerate category penetration despite premium pricing.
- Wet Food:Retort-canned or tray-sealed formulations with moisture content exceeding 75 percent target palatability-sensitive pets and veterinary hydration recommendations.
- Treats:Functional and reward-based formats span dental chews, training morsels, and nutritional supplements with compressed production batch cycles.
Dry Food commands the established base. The steepest expansion runs through Raw Food.
Animal Type:
Application-specific nutritional requirements dictate divergent formulation standards and AAFCO profile compliance investments across species.
- Dogs:Omnivore-adapted formulations balance animal protein with carbohydrate digestibility, driving the largest absolute volume across therapeutic, performance, and maintenance life-stage lines. California veterinary clinics report accelerating prescription diet adoption for obesity and joint management among urban companion animals.
- Cats:Obligate carnivore specifications mandate higher protein and taurine minimums, compressing ingredient flexibility and elevating cost structures. Texas specialty retailers observe premiumization concentration in grain-free and limited-ingredient variants for feline food sensitivity cases.
- Fish:Species-specific flake, pellet, and frozen formulations address tropical and marine aquarium maintenance requirements.
- Birds:Seed blends, extruded pellets, and foraging-oriented formats target psittacine and passerine nutritional needs with regional formulation variations.
Dogs command the established base. Cats are gaining share fastest among premium tier investments.
Distribution Channel:
Customer type behavior and purchase frequency patterns fragment channel economics and inventory turnover requirements.
- Online Retailers:Direct-to-consumer platforms and marketplace aggregators bypass traditional slotting fees, enabling subscription-based fresh diet models with portion-calibrated fulfillment. Florida and New York metropolitan markets demonstrate highest penetration among millennial households seeking convenience parity with human meal-kit services.
- Supermarkets:Mass-market retail chains leverage foot traffic density for high-velocity dry and wet food replenishment, though refrigerated fresh formats face space constraints.
- Pet Shops:Specialty retail channels emphasize staff expertise and brand assortment breadth, capturing premium and therapeutic nutrition seekers.
- Wholesale:Volume-driven institutional supply serves breeding operations, shelters, and veterinary hospital group purchasing organizations.
Supermarkets command the established base. Online Retailers show the steepest expansion trajectory.
Price Tier:
Margin concentration and ingredient specification thresholds stratify competitive positioning across consumer willingness-to-pay segments.
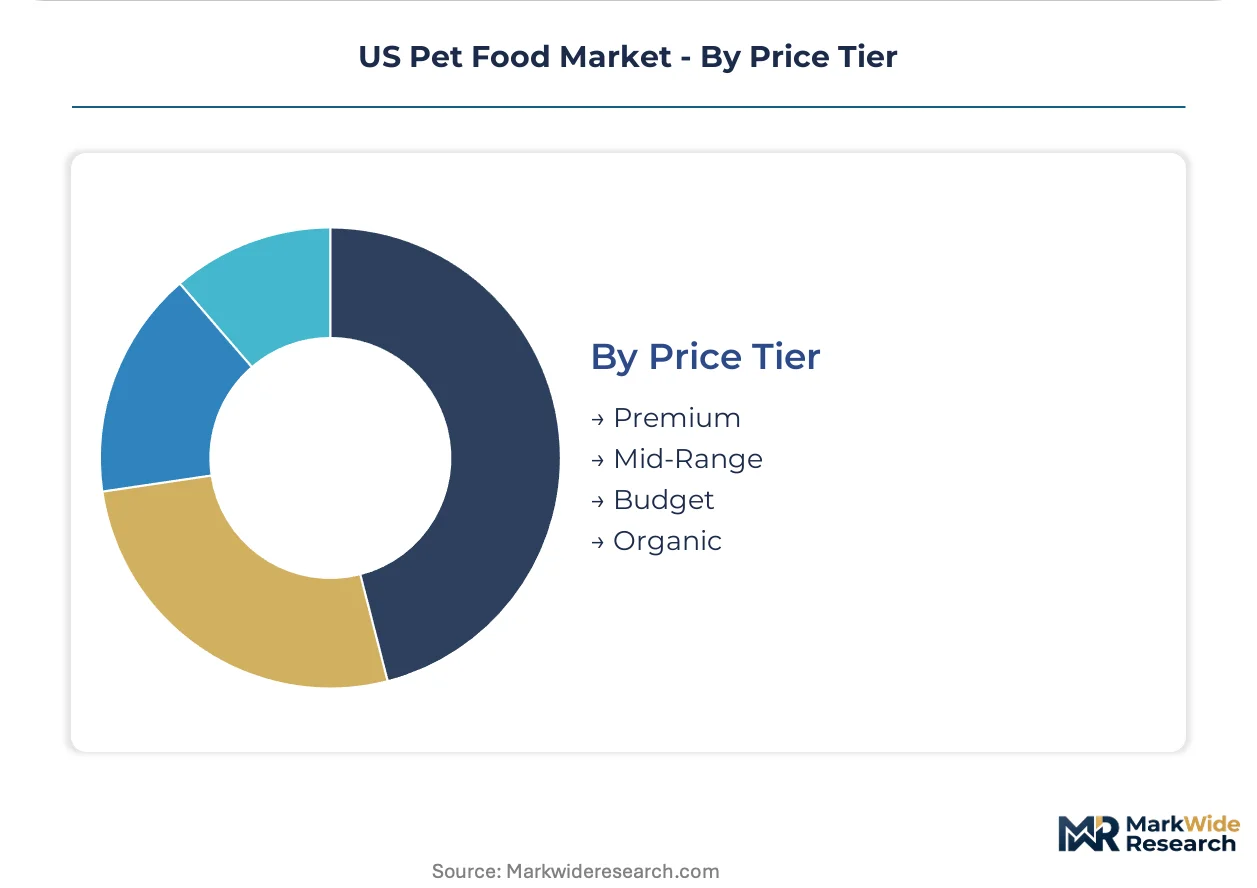
- Premium:Human-grade ingredient specifications, veterinary endorsement, and functional health claims justify price multiples above mass-market benchmarks. California and Texas urban markets demonstrate sustained elasticity for condition-specific formulations targeting dermatological, digestive, and cognitive health endpoints.
- Organic:USDA certification compliance restricts synthetic additive use and mandates non-GMO feedstock traceability, commanding retail price premiums in specialty channels. Florida consumers exhibit particular responsiveness to federal organic seal differentiation amid clean-label preference intensification.
- Mid-Range:Balanced quality-positioning targets cost-conscious owners seeking modest ingredient upgrades without specialty channel price points.
- Budget:Commodity protein inputs and simplified formulations face margin compression from ingredient cost volatility and private-label encroachment.
Premium commands the established base. Organic climbs the fastest among certification-driven differentiation strategies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Millennial pet owners in coastal metros and Sunbelt suburbs drive disproportionate spending on refrigerated fresh formats and veterinary therapeutic lines. State regulatory fragmentation around raw food pathogen testing creates compliance arbitrage opportunities for multi-regional operators.
California
Los Angeles and San Francisco Bay Area households generate the highest per-capita spending on USDA-certified organic and prescription therapeutic diets. The California Department of Public Health enforces pathogen screening protocols for raw pet food that exceed federal baselines, elevating production batch costs for regional entrants. San Diego anchors cold-chain logistics innovation, with refrigerated fulfillment centers serving direct-to-consumer subscription platforms.
Texas
Dallas-Fort Worth and Houston metropolitan areas concentrate mass-market volume for extruded dry food and high-velocity wet food replenishment. The Texas Department of State Health Services administers feed safety inspections under AAFCO-adopted standards, reducing interstate friction for national brands. Austin emerges as a testbed for high-pressure processing facilities targeting raw format safety compliance.
Florida
Miami and Tampa urban corridors exhibit accelerating penetration of minimally processed raw diets among ingredient-conscious consumers. Florida's Department of Agriculture and Consumer Services mandates state laboratory testing for Salmonella and Listeria in raw pet food, fragmenting production protocols. Orlando serves as a distribution node for refrigerated logistics networks spanning the Southeast.
New York Metro
Manhattan and Brooklyn households demonstrate highest adoption of direct-to-consumer fresh diet subscriptions with portion-calibrated fulfillment. New York State Department of Agriculture and Markets enforces labeling requirements for pet food sold through veterinary channels, shaping therapeutic nutrition marketing. Long Island specialty retailers capture premium price elasticity for limited-ingredient feline formulations.
Pacific Northwest
Seattle and Portland metropolitan areas concentrate demand for clean-label formulations and sustainable packaging claims. The Washington State Department of Agriculture coordinates with FDA field offices on novel ingredient notification pathways, including cultivated protein precursors. Portland anchors small-batch manufacturing for regional organic brands seeking differentiation from mass-market incumbents.
US Pet Food Market Key Industry Players
Channel-controlling players compete with product-specialist players across divergent margin structures and capital intensity requirements. Mass-market conglomerates leverage veterinary prescription networks and retail shelf-space dominance to sustain volume leadership. Three archetypes define competitive positioning: diversified consumer goods conglomerates with pet care divisions, pure-play pet food specialists with format-specific expertise, and refrigerated fresh entrants controlling captive cold-chain infrastructure. Dominant competitive moves include strategic partnerships with veterinary clinic networks and backward integration into protein rendering and high-pressure processing capacity.
Within the diversified conglomerate tier, Nestlé Purina PetCare and Mars Petcare Inc. exemplify scale-driven players with broad retail distribution and manufacturing footprint advantages. Freshpet occupies a distinct position as a pure-play refrigerated fresh specialist, with cold-chain logistics control representing its primary competitive moat against shelf-stable incumbents. These three companies collectively illustrate the market's structural divergence between mass-market volume efficiency and premium-format margin capture.
| Leading Market Players |
|---|
| Nestlé Purina PetCare |
| Mars Petcare Inc. |
| Hill's Pet Nutrition |
| General Mills |
| Colgate-Palmolive |
| Blue Buffalo |
| Diamond Pet Foods |
| J.M. Smucker |
| Freshpet |
| Others |
Cost & Logistics Intelligence
Midwest rendering plant concentration for human-grade meat and poultry byproducts feeds directly into margin stratification across fresh-format and shelf-stable tiers, with protein input volatility compressing economics most acutely at the premium end.
Pricing Analysis
Cost-plus contracts indexed to Chicago Mercantile Exchange livestock futures dominate protein procurement for mass-market extruded kibble, while subscription-based fresh diet platforms employ dynamic pricing calibrated to portion-customized fulfillment. Price differentiation rests on cold-chain infrastructure ownership versus third-party logistics reliance, with refrigerated format producers capturing elasticity in California and Florida urban corridors. Pricing pressure stems from commodity livestock market swings, squeezing fresh-format margins more severely than ambient shelf-stable lines. Budget-tier buyers exhibit highest price sensitivity, whereas veterinary prescription channel purchasers demonstrate lowest elasticity due to condition-specific formulation requirements.
Supply Chain Analysis
Tariff exposure between US and Canadian livestock feedstock suppliers dominates supply chain risk planning for multi-regional brands. Protein rendering draws from domestic Midwest facilities, Canadian prairie operations, and limited Australian imports for specialty organ meats. Raw material dependencies center on human-grade poultry byproducts, rendered beef meals, and novel insect protein precursors awaiting FDA GRAS determinations. Single-source vulnerability concentrates in high-pressure processing equipment, with European and Japanese machinery suppliers commanding extended lead times. Distribution runs through refrigerated fulfillment centers in Dallas-Fort Worth and San Diego anchoring direct-to-consumer subscription networks, while mass-market dry food moves through conventional trucking corridors serving Texas and California retail density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US Pet Food Market functions as a defensive-moat arena where regulatory entrenchment through FDA Center for Veterinary Medicine approval pathways and state-level pathogen testing mandates erects formidable barriers against unqualified entrants.
For Market Incumbents: Insulate prescription therapeutic nutrition lines through exclusive veterinary clinic partnerships that embed switching costs for chronic condition management. Deepen backward integration into high-pressure processing capacity in Austin and Orlando to neutralize raw food safety compliance fragmentation across state laboratory testing mandates. Cold-chain logistics ownership represents the priority defensive lever against fresh-format specialists. For New Entrants and Emerging Players: Pacific Northwest metropolitan corridors offer the most penetrable white-space for USDA-certified organic positioning, with Seattle and Portland consumers exhibiting pronounced responsiveness to sustainable packaging claims. Subscription-based portion-calibrated fulfillment in New York Metro bypasses traditional retail slotting fees while capturing recurring revenue. Direct-to-consumer platforms targeting feline limited-ingredient formulations present the clearest go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward refrigerated fresh specialists with captive cold-chain infrastructure and established FDA state-level compliance protocols. Long-term viability across the analysis window hinges on defensible logistics networks rather than brand equity alone. The signal to watch is FDA enforcement discretion crystallization on cultivated protein GRAS notifications, which would truncate approval timelines and reshape rendering economics.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | Refrigerated fulfillment centers in San Diego and Orlando anchor Southeast and West Coast subscription penetration. |
| High-Pressure Processing Capacity Buildout | Austin and Florida HPP facilities neutralize state-level Salmonella testing mandate fragmentation. |
| Veterinary Prescription Channel Deepening | Exclusive clinic partnerships embed Nestlé Purina and Hill's Pet Nutrition in chronic condition management workflows. |
| USDA Organic Certification Acceleration | Federal seal differentiation commands retail price premiums in Florida specialty retail channels. |
| Direct-to-Consumer Platform Launch | Portion-calibrated meal plans in California and New York displace periodic retail stock-up behavior. |
Research Approach
The analysis maps dry food, raw food, wet food, and treat sub-sectors, each validated through procurement directors at mass-market retailers, veterinary clinic practice managers, cold-chain logistics operators, and specialty pet retail buyers. Primary interview insights triangulated against FDA Center for Veterinary Medicine enforcement discretion memoranda, AAFCO model regulation adoption tracking across state agriculture departments, USDA organic certification databases, and Nielsen retail audit data. Bottom-up volume modeling from state-level pet density metrics and top-down value reconciliation against disclosed segment revenues ensured cross-validation integrity.
Assumptions held fixed across the projection horizon include AAFCO nutrient profile standards, FDA novel ingredient review timelines, and prevailing cold-chain logistics cost structures; variables tested encompass state laboratory testing mandate adoption rates, cultivated protein GRAS notification velocity, and millennial household pet ownership trajectories. The analytical framework segmented by product type, animal species, distribution channel, and price tier, with CAGRs derived from regression against disposable income alignment and urban pet density clustering. Forecast inputs incorporated protein commodity futures curves and refrigerated transport capacity expansion pipelines.
Practitioners should monitor FDA enforcement discretion crystallization on alternative proteins and state-level raw food pathogen testing mandate proliferation for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Thailand Pet Food Market
Pet Care Products
Pet Care Ingredients Market
Pet Care Products
Herbal Pet Shampoo Market
Pet Care Products
Natural Pet Food Market
Pet Care Products
Natural Dog Treat Market
Pet Care Products
India Pet Clothing Market
Pet Care Products
Smart Connected Pet Collar Market
Pet Care Products
Pet Tag Market
Pet Care Products
Aquarium Market
Pet Care Products
Cat Diffuser Market
Pet Care Products
Asia-Pacific Pet Treats Market
Pet Care Products
Smart Pet Leash Market
Pet Care Products
Pet Cups Market
Pet Care Products
Japan Pet Boarding Market
Pet Care Products
Mexico Pet Food Market
Pet Care Products
Fish Based Pet Food Market