
 South America Pet Food Market | 2026-2036
South America Pet Food Market Size, Share, and Industry Trends Forecast 2026-2036
South America Pet Food Market Analytics
Subscription-based replenishment services is recalibrating how manufacturers monetize pet nutrition across South America. Mars, Incorporated leverages its direct-to-consumer infrastructure to lock in recurring revenue streams. Nestlé Purina PetCare anchors its regional position through specialized veterinary diet formulations. BRF S.A. competes on cost-optimized production anchored in Brazilian poultry supply chains.
Pet food comprises formulated nutritional products manufactured through extrusion, canning, or freeze-drying processes to deliver complete diets for domestic animals, with dry kibble typically containing 6-10% moisture and wet formulations ranging 75-85% moisture to address hydration and palatability requirements. Dry Food dominates volume throughput due to logistics efficiency and shelf stability, while Wet Food captures premium margin pools in urban centers. The Ingredient Quality dimension stratifies sharply, with Natural and Grain-Free variants commanding price multiples over standard formulations.
Brazil's MAPA and Argentina's SENASA enforce ingredient labeling and facility registration standards that shape product formulation and cross-border trade eligibility. ANVISA in Brazil oversees veterinary therapeutic claims, restricting how manufacturers position functional benefits. Stakeholders must monitor evolving mercosur harmonization talks and shifting consumer willingness to pay for certified organic supply chains.
Market Dynamics
Subscription-based replenishment services are restructuring purchasing patterns among urban dog owners across Brazil and Argentina, locking in recurring revenue streams while compressing traditional retail margins and forcing distributors to reposition around logistics efficiency rather than shelf-space dominance.
Growth Catalysts
- MAPA Labeling Enforcement:Brazil's updated pet food labeling standards tighten ingredient disclosure requirements, pushing manufacturers toward premium formulations that command higher price points and justify certification investments.
- Poultry Supply Chain Density:Brazilian poultry integration creates feedstock cost advantages for domestic producers, anchoring regional competitiveness against imported alternatives.
- Veterinary Channel Expansion:Specialized therapeutic diet demand rises as ANVISA oversight restricts functional benefit claims to clinically validated formulations, channeling growth through veterinary clinics.
Market Restraints
- Feed Input Volatility:Corn and soybean price swings in Argentina's agricultural belt squeeze formulation margins, forcing producers to absorb costs or reformulate protein content.
- Import Dependency Concentration:Vitamin and mineral premix supply concentrates in Chinese manufacturing, exposing South American packers to currency and shipping disruptions.
- Mercosur Harmonization Friction:Divergent SENASA and MAPA facility registration standards create cross-border trade eligibility gaps, fragmenting production scale advantages.
Strategic Opportunities
- Colombia Urban Corridor:Bogotá and Medellín pet ownership rates trail São Paulo benchmarks by significant margins, presenting first-mover expansion potential for subscription-model entrants.
- Freeze-Dried Raw Convergence:Cold-chain logistics improvements intersect with consumer willingness to pay for minimally processed nutrition, opening premium shelf space previously dominated by imports.
- Organic Certification Tailwinds:Brazilian consumer segments demonstrate rising price tolerance for certified organic supply chains, rewarding early compliance investments with margin protection.
Industry Challenges
- Veterinary Nutritionist Scarcity:Formulation expertise for therapeutic diets concentrates in São Paulo and Buenos Aires, constraining regional product development timelines.
- Extrusion Equipment Lead Times:Capacity expansion faces 12-18 month delivery cycles for specialized high-moisture extrusion lines, throttling response to wet food demand surges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Pet Food Market |
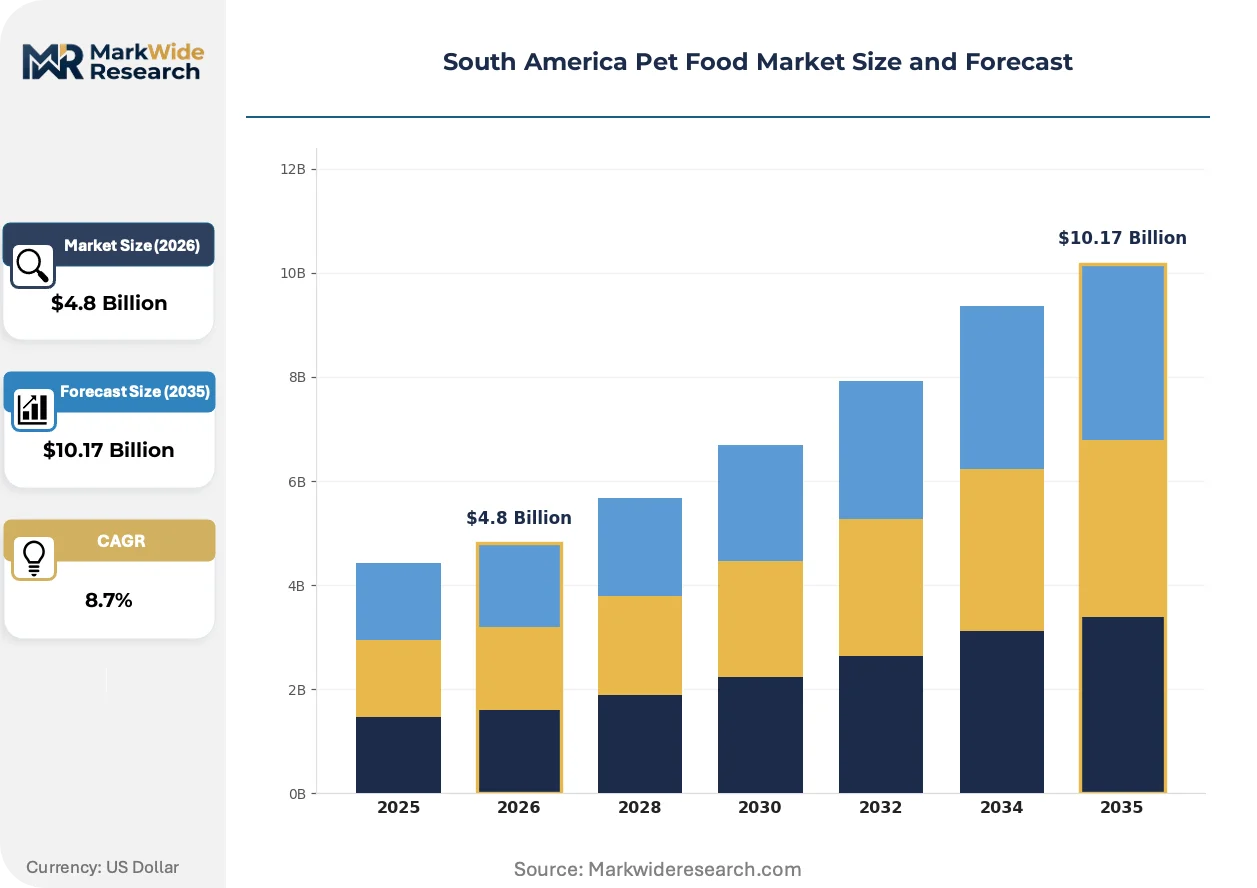
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Raw Diet Distribution Channel: Supermarkets, Pet Shops, Online Retail, Veterinary Clinics End User: Dog Owners, Cat Owners, Small Animal Enthusiasts, Bird Owners Ingredient Quality: Natural, Organic, Grain-Free, Premium, Others |
| Companies Covered | Mars, Incorporated, Nestlé Purina PetCare, BRF S.A., PremieRpet Holding, Empresas Carozzi S.A., Total Alimentação, Mogiana Alimentos SA, Agrolimen SA, Nutriara Alimentos, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Pet Food Market Evolving Landscape
Three intersecting forces are reconfiguring how pet nutrition reaches South American households: manufacturing technology is fragmenting production scale advantages, regulatory disclosure is elevating ingredient transparency as a competitive weapon, and direct-to-consumer channels are disintermediating traditional retail gatekeepers.
Cold-pressed and minimally processed formulation technology is modularizing production economics for mid-scale manufacturers. Regional packers in Minas Gerais and Rio Grande do Sul are adopting modular extrusion systems at accelerating rates. This technology is modularizing the capital barrier that previously protected large integrated producers, enabling 5,000-ton annual capacity entrants to achieve viable unit economics.
Argentina's SENASA is tightening traceability mandates for rendered protein sources, requiring batch-level documentation from slaughterhouse to finished product. This regulatory pressure is forcing reformulation toward named-meat specifications and compressing anonymous byproduct usage. Wet food producers serving Buenos Aires metropolitan demand are responding fastest, restructuring supplier contracts to secure chain-of-custody documentation.
Urban millennial pet owners are consolidating purchases through smartphone-enabled replenishment platforms, displacing monthly supermarket stocking trips. Veterinary clinics and specialty retailers in São Paulo's southeastern corridor are experiencing the most visible channel erosion, with subscription services capturing recurring dry food volumes previously secured through loyalty programs.
South America Pet Food Market Segmentation
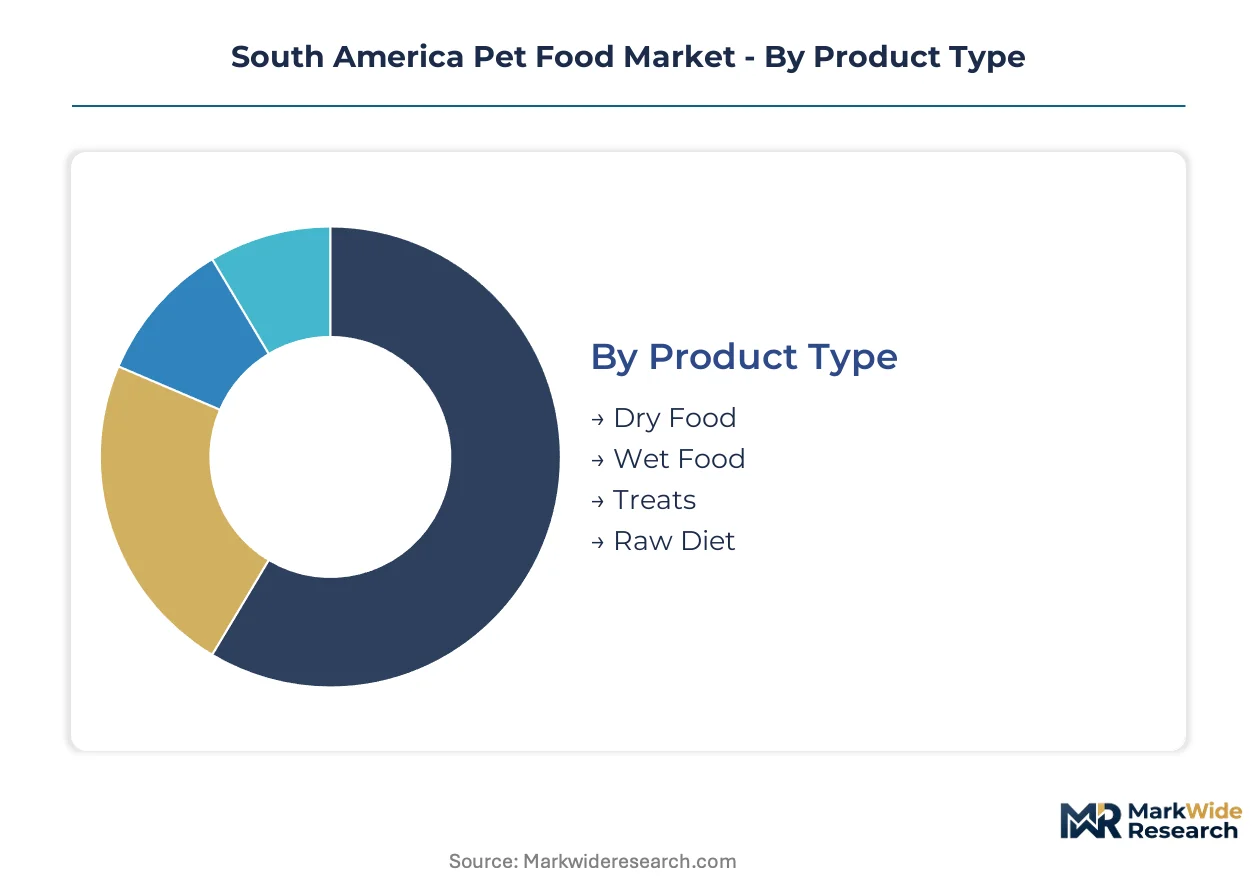
Segmentation in the South America Pet Food Market reveals how formulation choices, channel strategies, and ingredient positioning create distinct competitive battlegrounds. Manufacturers must align production capabilities with the specific margin structures and regulatory exposures of each segment cluster.
Product Type:
Standardization dominates at volume scale while customization captures premium pricing across this foundational category.
- Dry Food:Extruded kibble formulations with 6-10% moisture content deliver shelf-stable nutrition optimized for logistics efficiency. São Paulo's urban corridors concentrate demand for bulk-format dry food as subscription services consolidate recurring purchases into predictable shipment volumes.
- Wet Food:Canned and pouch formats carrying 75-85% moisture address hydration-sensitive breeds and palatability requirements. Buenos Aires metropolitan demand drives wet food premiumization as SENASA traceability mandates push producers toward named-meat specifications and documented chain-of-custody.
- Treats:Supplementary nutrition and training rewards occupy impulse-purchase occasions across Brazilian pet shops.
- Raw Diet:Minimally processed frozen and freeze-dried formats serve niche segments willing to manage cold-chain complexity.
Most installed capacity flows through Dry Food. Expansion is steepest in Raw Diet.
Distribution Channel:
Channel selection determines margin capture versus customer acquisition cost across Brazil and Argentina's diverging retail landscapes.
- Supermarkets:Mass-market shelf space delivers volume throughput for standardized formulations with established brand recognition. Minas Gerais state retailers experience margin compression as urban consumers shift replenishment toward direct channels.
- Pet Shops:Specialty retailers anchor premium positioning through trained staff consultation and exclusive brand relationships. São Paulo's southeastern corridor pet shops defend relevance through grooming service bundling and veterinary referral partnerships.
- Online Retail:Smartphone-enabled platforms displace traditional stocking trips among millennial pet owners.
- Veterinary Clinics:Therapeutic diet distribution concentrates under ANVISA oversight restricting functional claims.
Volume concentrates in Supermarkets. Margin expansion is climbing the fastest in Online Retail.
End User:
Species-specific nutritional requirements create formulation specialization that fragments production runs and elevates R&D amortization.
- Dog Owners:Canine nutrition spans breed-size variations from toy breeds through working dogs, with large-breed puppy formulations requiring controlled calcium-phosphorus ratios. Brazil's dog ownership rates in São Paulo and Rio de Janeiro metropolitan zones exceed regional benchmarks, concentrating demand for therapeutic weight management and senior formulations.
- Cat Owners:Obligate carnivore metabolism drives high-protein formulation requirements with taurine supplementation mandates. Buenos Aires shows elevated cat ownership density relative to Brazilian cities, supporting specialized urinary health and hairball control product development.
- Small Animal Enthusiasts:Rabbit, guinea pig, and rodent nutrition occupies niche formulation capacity with limited scale economies.
- Bird Owners:Psittacine and passerine diets require species-specific seed and pellet blends with vitamin A toxicity controls.
Revenue concentrates with Dog Owners. Product development velocity is expanding most quickly for Cat Owners.
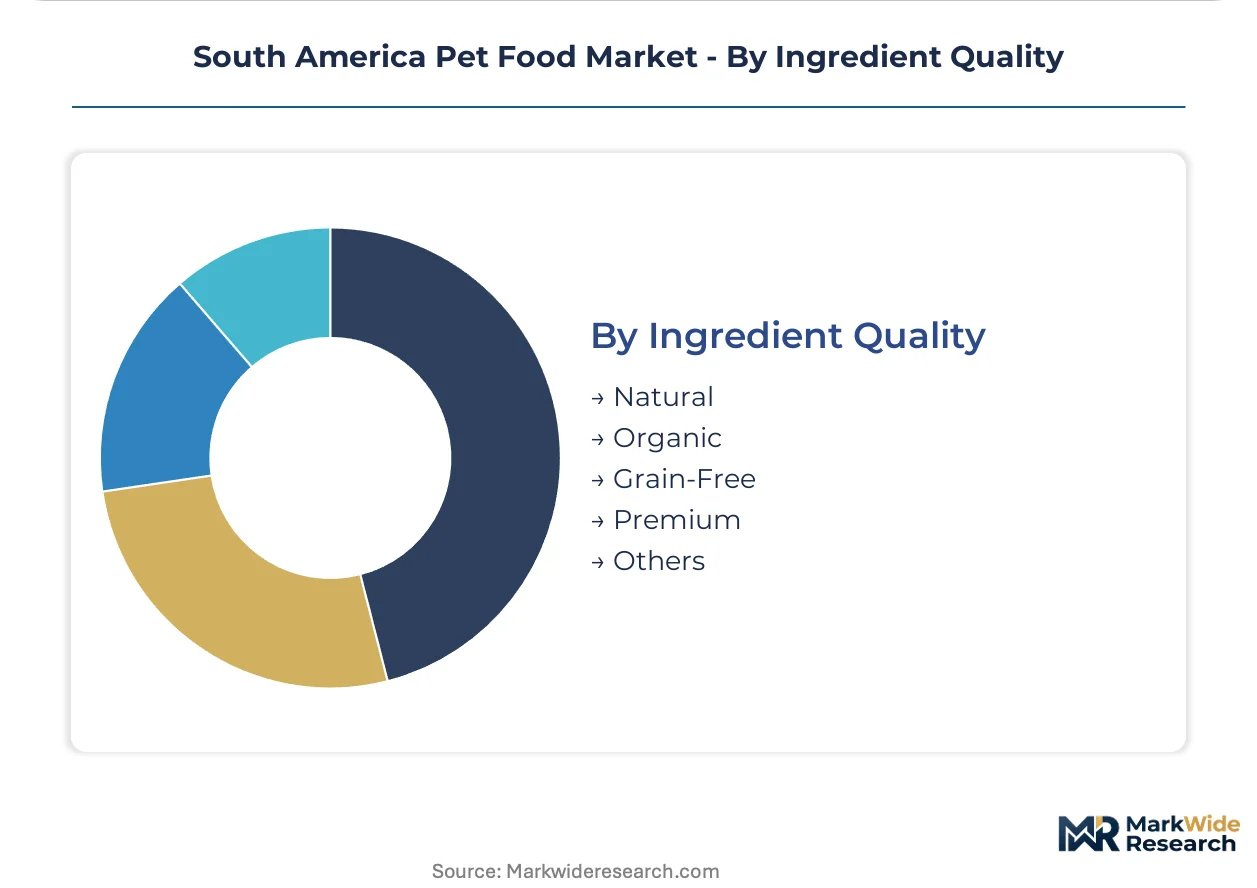
Ingredient Quality:
Certification tiering separates price-insensitive segments from cost-optimized mass market positioning.
- Natural:Formulations excluding artificial preservatives, colors, and flavors command shelf space premiums in Colombian urban centers. Bogotá retailers report rising consumer interrogation of ingredient panels, pushing manufacturers toward named-protein sourcing.
- Organic:Certified supply chains with documented pesticide and GMO exclusion attract price-tolerant segments in Brazil's affluent southeastern corridor. MAPA's evolving organic certification alignment with Mercosur standards creates compliance investment uncertainty for cross-border producers.
- Grain-Free:Carbohydrate substitution with legumes and tubers addresses perceived digestive sensitivity.
- Premium:Super-premium positioning combines multiple quality signifiers without full organic certification.
- Others:Economy and standard tiers serve price-sensitive volume segments.
Volume flows through Premium. Certification investment is gaining share fastest in Organic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's southeastern corridor generates disproportionate pet food demand relative to Argentina's metropolitan zones, while Colombia's urban centers lag both in per-capita consumption metrics. This divergence shapes where manufacturers prioritize capacity deployment and subscription-service pilot programs.
Brazil
São Paulo and Minas Gerais states concentrate dog ownership density and veterinary clinic networks. MAPA's updated labeling standards enforce ingredient disclosure thresholds that elevate compliance costs for imported formulations. Cold-chain infrastructure investments in Rio Grande do Sul are enabling freeze-dried raw production at mid-scale facilities.
Argentina
Buenos Aires metropolitan cat ownership exceeds Brazilian city benchmarks, supporting specialized urinary health product development. SENASA traceability mandates for rendered proteins are compressing anonymous byproduct usage in wet food formulations. Rosario-based packers are restructuring supplier contracts to secure chain-of-custody documentation.
Colombia
Bogotá and Medellín pet ownership rates trail São Paulo by significant margins, presenting first-mover expansion potential. The national agricultural regulator enforces facility registration standards that shape cross-border trade eligibility from Ecuador and Peru. Cali distributors are testing subscription-model logistics for premium dry food segments.
Chile
Santiago's affluent consumer segments demonstrate price tolerance for certified organic supply chains. The national agricultural service maintains import protocols that restrict vitamin premix sourcing flexibility. Valparaíso port infrastructure supports cold-chain throughput for freeze-dried raw imports from North American suppliers.
South America Pet Food Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated multinationals dominating therapeutic diet distribution while domestic packers capture cost-optimized mass-market volumes. The structure tilts toward consolidation in premium tiers and fragmentation in economy positioning. Three archetypes prevail: poultry-integrated domestic producers, multinational nutrition specialists, and subscription-enabled direct-to-consumer platforms. Competitive moves concentrate on veterinary channel partnerships and modular extrusion capacity additions.
Among Brazil-based integrated producers, BRF S.A. and Mogiana Alimentos SA exemplify poultry supply chain leverage for feedstock cost positioning. Mars, Incorporated represents the multinational archetype anchoring recurring revenue through direct-to-consumer infrastructure. These three occupy distinct competitive spaces without overlapping core segment focus.
| Leading Market Players |
|---|
| Mars, Incorporated |
| Nestlé Purina PetCare |
| BRF S.A. |
| PremieRpet Holding |
| Empresas Carozzi S.A. |
| Total Alimentação |
| Mogiana Alimentos SA |
| Agrolimen SA |
| Nutriara Alimentos |
| Others |
Value Network & Pricing Analysis
MAPA's updated organic certification alignment with Mercosur standards gates qualified supply access for premium-tier producers while compressing margin buffers for non-compliant packers. Brazilian consumers demonstrate rising price tolerance for certified organic supply chains, rewarding early compliance investments with pricing power in São Paulo's affluent southeastern corridor.
Pricing Analysis
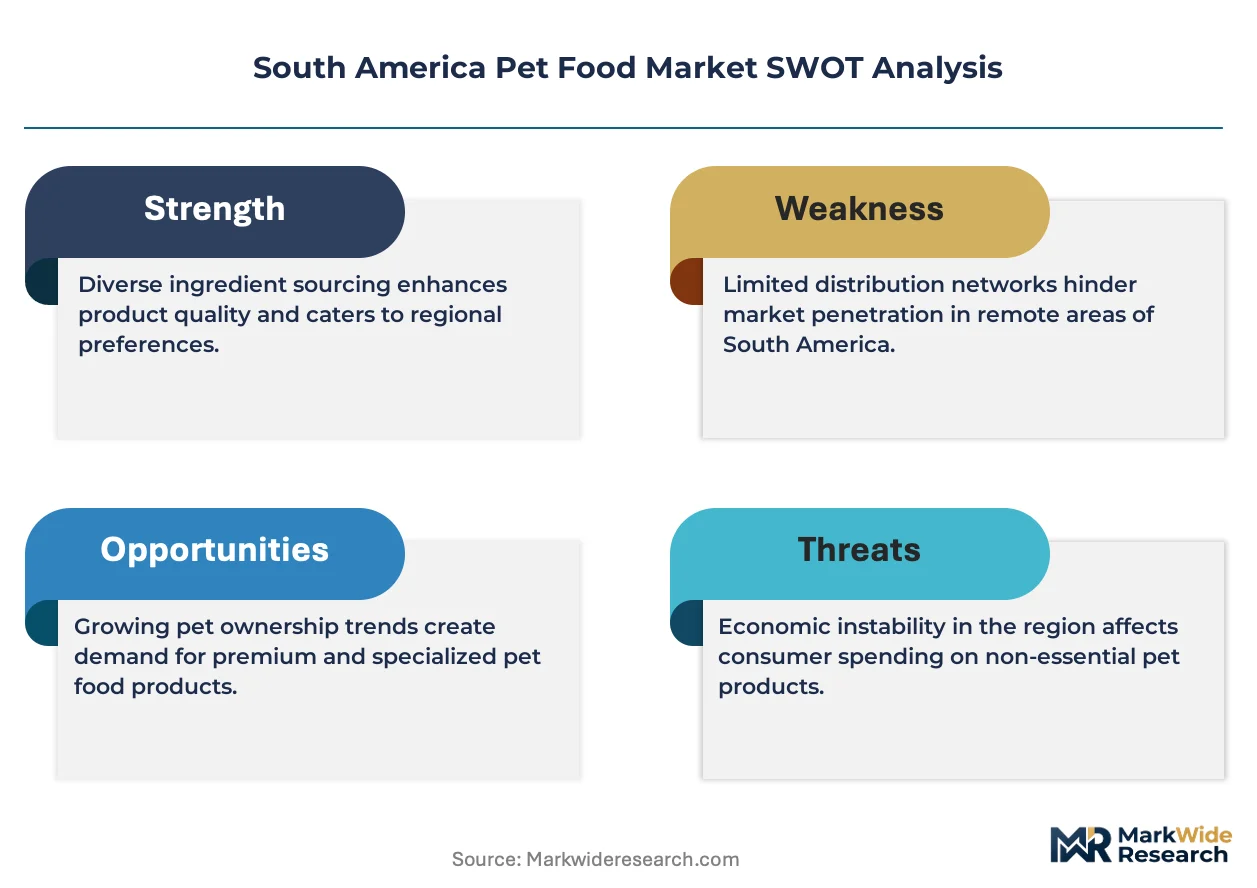
Capacity additions in Minas Gerais and Rio Grande do Sul are reshaping price floors for mid-scale dry food producers. Three-tier pricing structure across premium, standard, and economy levels stratifies by ingredient certification grade and named-meat specifications. Cost compression in economy tiers is intensifying because poultry feedstock advantages concentrate among integrated Brazilian producers. Small independent packers in Argentina's interior show highest price sensitivity; subscription-enabled urban buyers in São Paulo demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with Chinese vitamin and mineral premix manufacturing. Brazilian poultry integration and Argentine grain processing anchor regional raw material sourcing, while North American freeze-dried inputs feed Chilean cold-chain distribution. Feed input volatility in Argentina's agricultural belt creates persistent margin risk. Distribution runs through supermarket chains in volume segments and veterinary clinics for therapeutic formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through cold-pressed manufacturing technology adoption and subscription-model recurring revenue capture. Poultry supply chain density and modular extrusion economics create cost-down pathways for compliant producers.
For Market Incumbents: Extend veterinary channel partnerships to lock in therapeutic diet distribution before ANVISA restrictions tighten further. Invest in modular extrusion capacity in Rio Grande do Sul to capture freeze-dried raw convergence demand. Defend against subscription-enabled entrants by bundling loyalty programs with cold-chain logistics capabilities. For New Entrants and Emerging Players: Smartphone-enabled replenishment platforms offer the lowest customer acquisition cost route for Bogotá and Medellín first-mover expansion. Target Colombia's underpenetrated urban corridors with premium dry food subscription pilots. Secure MAPA organic certification early to justify price premiums in Brazilian southeastern markets. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale Brazilian packers lacking subscription infrastructure or cold-chain assets. Five-to-ten year viability favors poultry-integrated producers with backward feedstock control and veterinary channel relationships. Watch ANVISA harmonization progress with Mercosur standards as inflection indicator for cross-border consolidation viability.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | Subscription services capture recurring revenue previously secured through São Paulo supermarket loyalty programs. |
| Cold-Chain Infrastructure Investment | Freeze-dried raw production in Rio Grande do Sul reduces import dependency on North American suppliers. |
| MAPA Organic Certification Program | Early compliance investments reward producers with pricing power in Brazil's affluent southeastern corridor. |
| Veterinary Channel Partnership Expansion | ANVISA oversight restricts therapeutic claims to clinically validated formulations distributed through clinics. |
| Modular Extrusion Capacity Addition | Mid-scale Minas Gerais facilities achieve viable unit economics against large integrated producers. |
Research Methodology
Direct dialogue with pet food plant managers, MAPA regulatory affairs officers, veterinary clinic procurement leads, and São Paulo supermarket category buyers grounded qualitative findings. Secondary validation drew from MAPA labeling directives, ANVISA therapeutic claim registrations, SENASA traceability mandates, and Mercosur harmonization documentation. Bottom-up capacity assessments across Brazilian states triangulated against top-down consumption estimates from urban ownership rate surveys.
Segmentation outputs across product type, distribution channel, end user species, and ingredient quality tier informed volume and value projections over the analysis window. CAGRs derived from historical trajectory analysis adjusted for regulatory enforcement intensity and cold-chain infrastructure buildout pace. Modeled inputs included poultry feedstock cost indices, extrusion equipment delivery cycles, and subscription penetration rates in metropolitan corridors.
The model assumes a particular technology adoption path; alternative pathways for cold-pressed modular extrusion would alter the outlook if equipment lead times compress or capital costs decline faster than projected. Forecasts embed assumptions about MAPA enforcement consistency and Mercosur harmonization progress. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Pet Cups Market
Pet Care Products
Indestructible Dog Toys Market
Pet Care Products
Pet Treats Market
Pet Care Products
China Pet Food Market
Pet Care Products
GPS Dog Collar Market
Pet Care Products
US Pet Boarding Market
Pet Care Products
Pet Waste Removal Services Market
Pet Care Products
Pet Grooming Products Market
Pet Care Products
Cat Collar Market
Pet Care Products
South Africa Pet Food Market
Pet Care Products
Pet Oral Care Products Market
Pet Care Products
Dog Harness Market
Pet Care Products
Pet Water Dispenser Market
Pet Care Products
Europe Cat Food Market
Pet Care Products
Pet Clothing Market
Pet Care Products
Dog Water Bottle Market