
 Dog Seat Belt Market | 2026-2036
Dog Seat Belt Market Size, Share, and Industry Trends Forecast 2026-2036
Dog Seat Belt Market Analytics
The EU Green Deal is decoupling pet product sourcing from virgin petroleum feedstocks, compelling manufacturers to certify recycled-content harnesses for CE-marked entry. Kurgo leverages in-house webbing extrusion to control nylon quality from chip to finished strap. PetSafe anchors its position through exclusive distribution partnerships with Tractor Supply and Chewy. Mighty Paw differentiates via direct-to-consumer video marketing that demonstrates crash-test protocols.
A dog seat belt is a vehicle-specific restraint system comprising load-rated webbing, metal hardware meeting tensile thresholds, and a securement interface compatible with standard automotive latch points; manufacturers typically employ bar-tack stitching at stress junctions and dynamic load testing to verify occupant protection during sudden deceleration events. Standard harnesses dominate unit volume due to lower price positioning and broad retail availability, while vehicle-grade restraints command premium placement among veterinary and professional trainer channels where liability exposure drives specification rigor. Nylon retains material leadership for abrasion resistance and dye retention, though neoprene padding is gaining fastest in direct-to-consumer segments where comfort claims influence purchase decisions.
FDA guidelines for pet product labeling intersect with NHTSA consumer advisories on unrestrained animal hazards, creating a dual-compliance environment where substantiated crash-test claims carry marketing weight and legal protection. The EU AI Act and CSRD reporting requirements are beginning to reach downstream pet accessory importers, demanding supply-chain traceability documentation that smaller exporters struggle to assemble. Stakeholders must monitor whether emerging state legislation in California and New York mandates specific tensile-test certifications as a condition of retail placement, since such rules would immediately reshape supplier qualification criteria and inventory carrying costs.
Market Dynamics
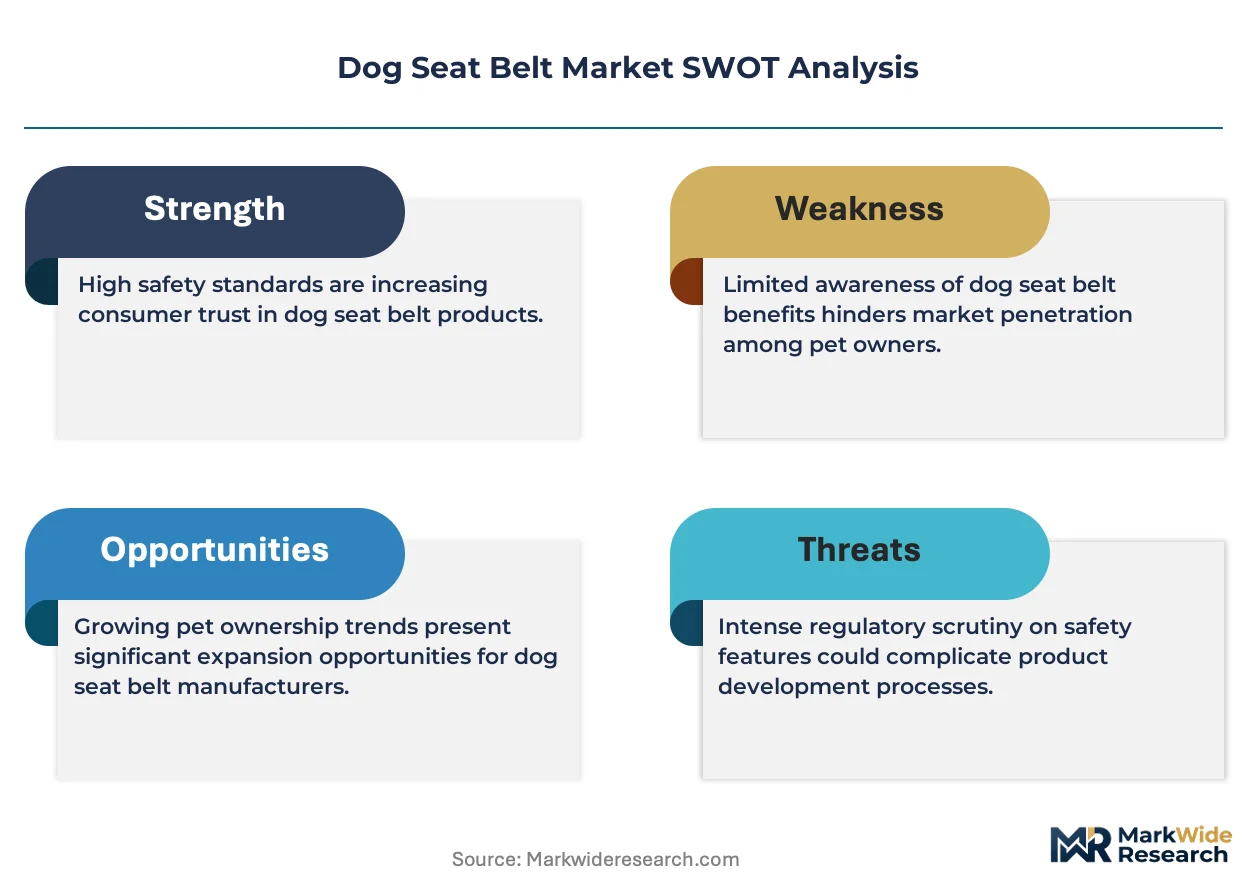
State-level distracted-driving legislation in the United States is compelling pet owners to treat crash-tested restraints as mandatory safety equipment rather than discretionary accessories, compressing purchase cycles and elevating certification requirements across the supply base.
Growth Catalysts
- NHTSA Consumer Advisories:Federal guidance on unrestrained animal hazards in vehicles is elevating crash-test claims to a decisive purchase criterion among suburban households with multiple pets.
- Veterinary Clinic Channel:Post-surgical transport protocols are mandating load-rated harnesses, converting professional endorsements into direct consumer demand for certified restraints.
- Recycled Nylon Webbing:EU Green Deal feedstock requirements are accelerating material innovation, with extrusion-grade recycled chips now meeting tensile specifications for automotive applications.
Market Restraints
- Petroleum-Derived Input Volatility:Virgin nylon 6,6 chip pricing fluctuates with benzene chain economics, compressing margin stability for non-integrated webbing producers.
- Chinese Component Concentration:Die-cast zinc hardware and snap-hook assemblies cluster in Zhejiang and Guangdong provinces, exposing importers to tariff and logistics disruption.
- Substitution by Cargo Barriers:SUV and wagon owners increasingly favor metal mesh vehicle barriers over individual harness systems for multi-dog transport scenarios.
Strategic Opportunities
- German TÜV Certification Gap:Few Asian exporters have secured the country's automotive safety testing endorsement, creating first-mover advantage for compliant entrants.
- Telematics Integration:GPS-enabled restraint systems that sync with pet-tracking apps represent unclaimed white space in the direct-to-consumer channel.
- California AB 47 Framework:The state's moving violation point system for distracted driving is expanding enforcement scope, potentially mandating specific restraint categories.
Industry Challenges
- Dynamic Load Testing Capacity:Sled-test facilities certified for pet-specific anthropomorphic dummy protocols remain scarce, creating bottlenecks for new product validation.
- Dual-Label Compliance Complexity:FDA pet product labeling intersects with NHTSA advisory language, forcing legal review cycles that delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dog Seat Belt Market |
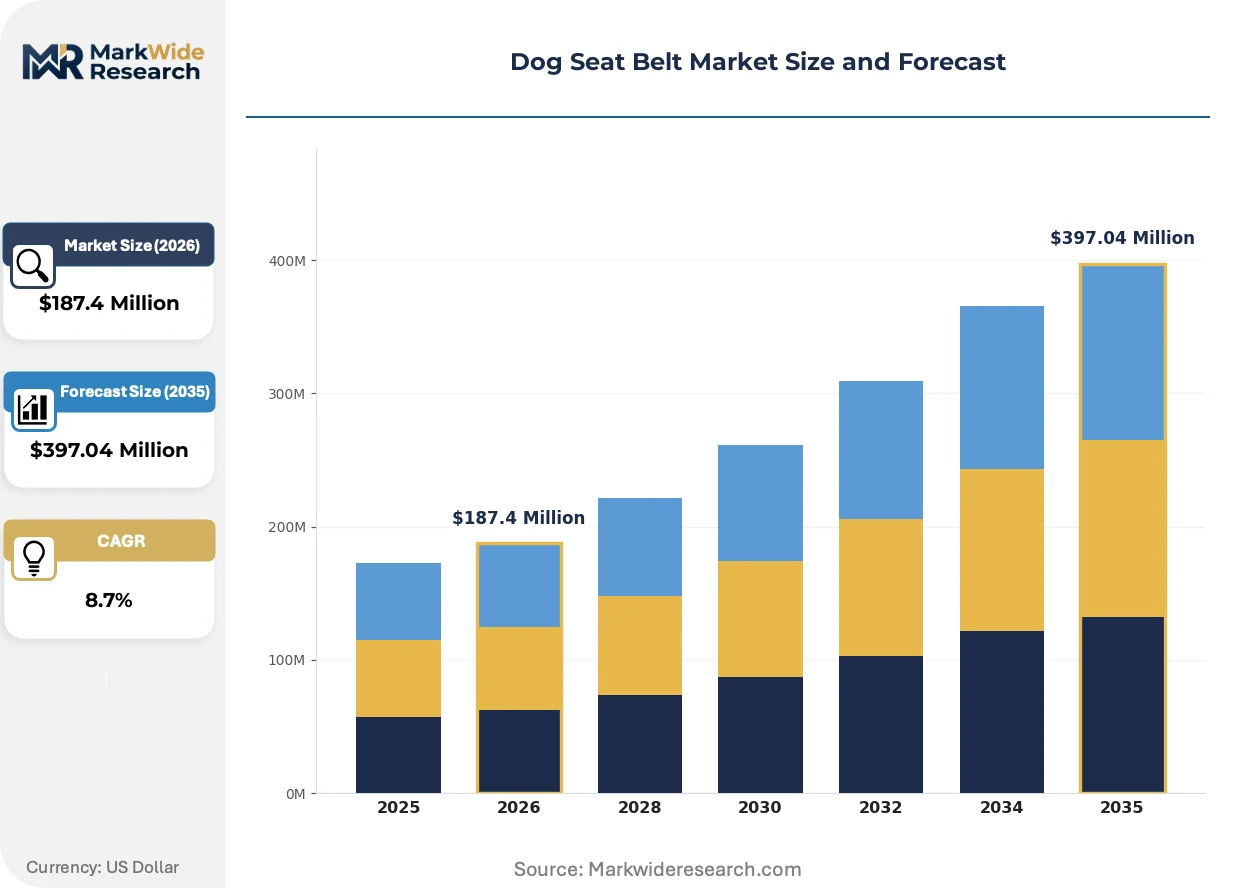
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Harness, Adjustable Harness, Seat Belt Clip, Vehicle-Grade Restraint Material: Nylon, Polyester, Metal, Neoprene End User: Pet Owners, Pet Trainers, Veterinarians, Rescues Distribution Channel: Online Retail, Pet Stores, Supermarkets, Specialty Shops |
| Companies Covered | Kurgo, PetSafe, Mighty Paw, Sleepypod, Ruffwear, EzyDog, Outward Hound, Snoozer, 4Knines, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dog Seat Belt Market Evolving Landscape
Material science advances and regulatory documentation requirements are converging to redefine product differentiation, with comfort engineering and supply-chain traceability emerging as parallel vectors of competitive separation.
Neoprene padding systems are integrating with abrasion-resistant base layers to address the tension between crash-test rigidity and extended-wear comfort. Direct-to-consumer brands are adopting these hybrid constructions fastest, using thermal-molding techniques to customize fit profiles. The technology is integrating veterinary comfort recommendations with automotive safety specifications, collapsing the traditional separation between medical and vehicle-grade product categories.
The EU AI Act and CSRD reporting requirements are extending downstream to pet accessory importers, mandating machine-readable supply-chain documentation that smaller exporters cannot assemble without third-party platform investment. This regulatory friction is filtering distributor portfolios, favoring suppliers with pre-existing textile traceability systems. Veterinary and professional trainer channels are responding by demanding batch-level polymer sourcing records as a condition of continued stocking.
Subscription-based replacement programs are displacing single-transaction retail for high-wear components like webbing and hardware. Chewy and specialty pet platforms are piloting these models, capturing lifetime value through automated replenishment of stress-fatigued straps. This pattern concentrates most visibly in coastal United States metropolitan markets where vehicle miles traveled per pet household exceed national medians.
Dog Seat Belt Market Segmentation
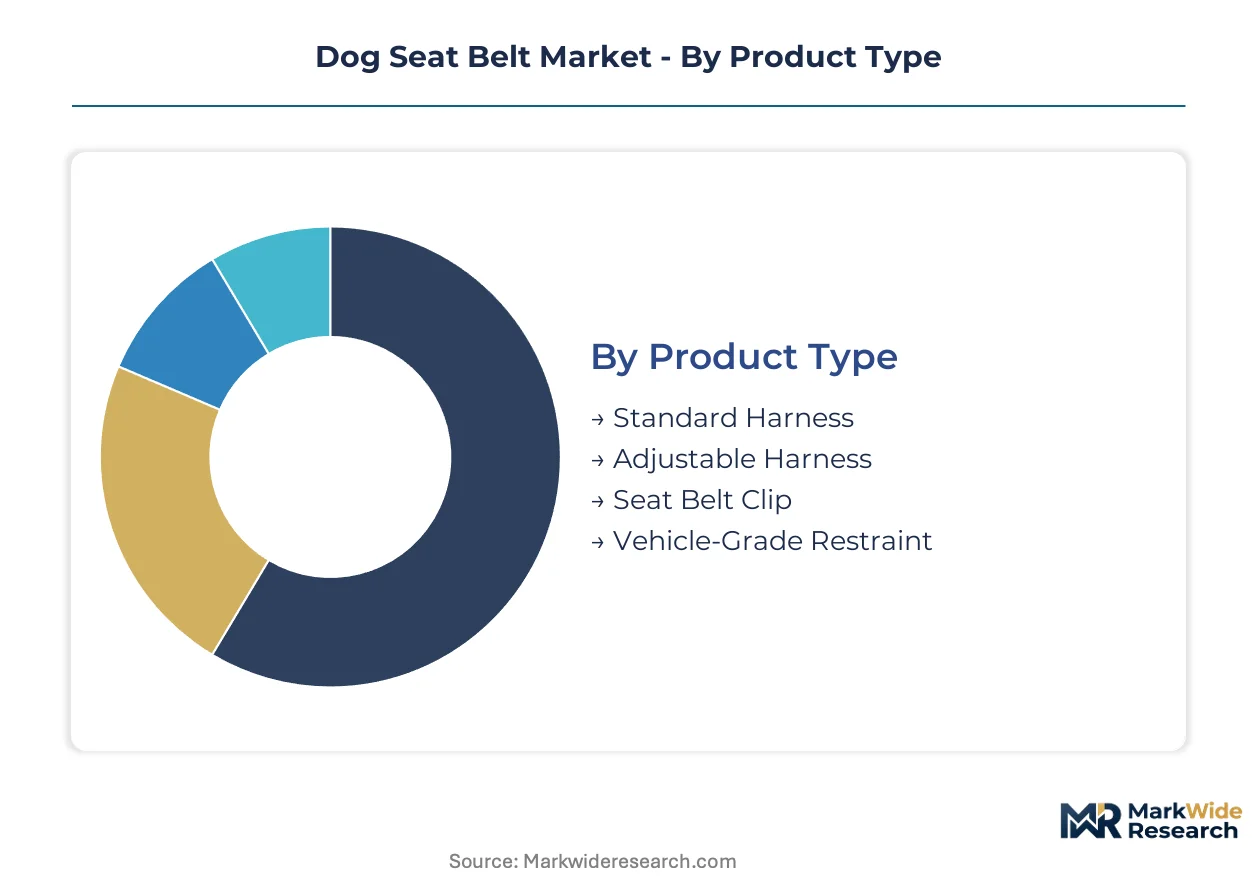
Product architecture in the dog seat belt market splits between standalone consumer accessories and professionally specified vehicle-integrated systems. Material selection, end-user certification requirements, and channel economics create divergent margin profiles across each partition.
Product Type:
Integration depth separates standalone harnesses from vehicle-anchored restraint systems, with implications for testing protocols and liability exposure.
- Standard Harness:Basic webbing construction with metal D-rings and adjustable chest straps. Demand clusters in suburban United States households with single-pet configurations where NHTSA advisories have elevated baseline safety awareness without mandating professional-grade specifications.
- Vehicle-Grade Restraint:Load-rated assemblies with certified tensile hardware and automotive latch compatibility. Veterinary clinics in California and New York are mandating these for post-surgical transport, converting professional liability requirements into direct consumer procurement.
- Adjustable Harness:Modular fit systems accommodating weight ranges across growth stages.
- Seat Belt Clip:Minimalist tether interfaces attaching existing harnesses to vehicle anchor points.
Volume placements concentrate in Standard Harness; the faster expansion belongs to Vehicle-Grade Restraint.
Material:
Cost tier alignment shapes procurement patterns, with virgin petroleum derivatives commanding premium positioning against recycled-content alternatives.
- Nylon:Extruded polyamide webbing with superior abrasion resistance and dye retention for branding visibility. Suburban North American retailers favor this for inventory turns, while EU Green Deal compliance pressures are accelerating recycled-chip substitution in export-bound production.
- Neoprene:Synthetic rubber padding laminated to base webbing for extended-wear comfort. Direct-to-consumer channels in coastal United States metros are adopting hybrid constructions fastest, collapsing the traditional separation between medical and automotive specifications.
- Polyester:Lower-cost alternative with reduced UV degradation for price-sensitive segments.
- Metal:Die-cast zinc and stainless hardware for load-bearing junctions and snap-hook assemblies.
Procurement weight sits with Nylon; steepest expansion trajectory belongs to Neoprene.
End User:
Customer type determines specification rigor, with professional channels demanding traceable certification that consumer segments often bypass.
- Veterinarians:Clinical settings requiring batch-level polymer sourcing and dynamic load documentation. Post-surgical transport protocols in licensed practices are converting professional endorsement into mandatory consumer purchase.
- Pet Owners:Discretionary purchasers responding to state-level distracted-driving enforcement. California's moving violation point system and tightening suburban enforcement scopes are compressing purchase cycles toward certified restraints.
- Pet Trainers:Behavior professionals specifying comfort-optimized configurations for extended vehicle exposure.
- Rescues:Volume purchasers prioritizing unit economics for transport logistics over individual fit precision.
Transaction volume aggregates in Pet Owners; specification escalation is concentrating in Veterinarians.
Distribution Channel:
Channel configuration dictates margin capture, with vertically integrated platforms displacing fragmented retail for replenishment-heavy categories.
- Online Retail:Direct-to-consumer platforms with video-demonstrated crash-test protocols and subscription-based webbing replacement. Coastal United States metros with elevated vehicle miles traveled per pet household are piloting automated replenishment models for stress-fatigued components.
- Pet Stores:Physical retail with immediate fit verification and returns processing. Suburban locations in states with active distracted-driving legislation are expanding certified-restraint shelf space.
- Supermarkets:Mass-merchandise placement for impulse and entry-price purchases.
- Specialty Shops:Curated selection with professional fitting services and veterinary referral relationships.
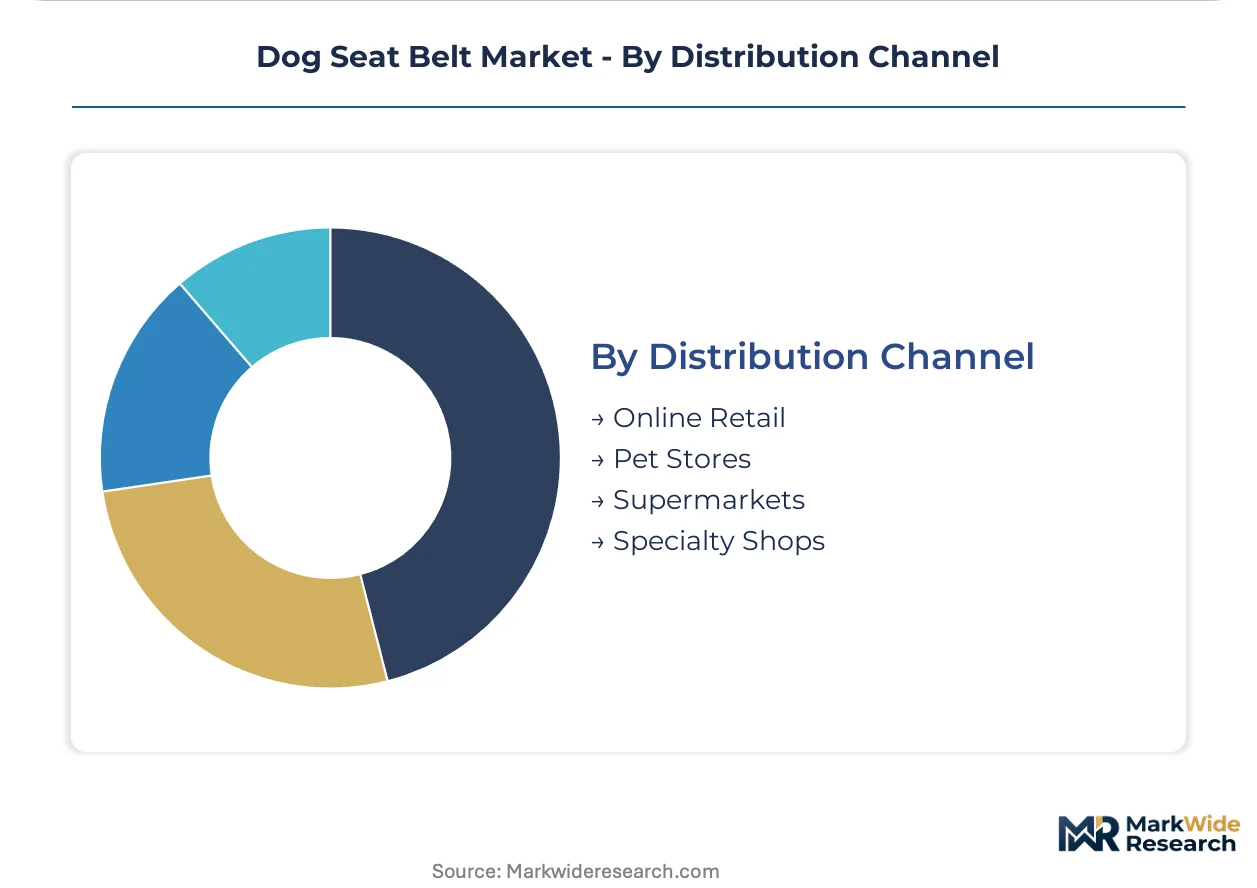
Unit velocity flows through Online Retail; margin protection is strongest in Specialty Shops.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zhejiang province anchors hardware fabrication for the sector, with die-cast zinc and snap-hook assembly clusters concentrated around Wenzhou and Ningbo port corridors.
United States
Suburban households in California and New York are accelerating purchases of certified restraints as state-level distracted-driving enforcement tightens. California's AB 47 moving violation point system for distracted driving is expanding enforcement scope beyond mobile phone use. Veterinary clinics in Los Angeles and New York City metro areas are mandating load-rated harnesses for post-surgical transport protocols.
Germany
Automotive safety certification from TÜV laboratories is becoming a decisive procurement criterion for EU-bound exporters. The EU Green Deal is decoupling pet product sourcing from virgin petroleum feedstocks, compelling recycled-content certification for CE-marked entry. Extrusion-grade recycled nylon chips from Bavarian chemical processors are now meeting tensile specifications for automotive applications.
China
Die-cast zinc hardware and snap-hook assemblies cluster in Zhejiang and Guangdong provinces, exposing importers to tariff and logistics disruption. The country's national quality regulator is tightening export documentation requirements for pet safety products. Shenzhen and Guangzhou logistics hubs are consolidating outbound freight for North American and European veterinary channels.
United Kingdom
Post-Brexit regulatory divergence is creating dual-label compliance complexity for pet accessory importers serving both UK and EU markets. The country's national veterinary regulator is aligning transport safety guidance with emerging automotive restraint standards. London and Southeast England distribution centers are filtering supplier portfolios based on batch-level polymer sourcing records.
Canada
Health Canada consumer advisories on unrestrained animal hazards are elevating crash-test claims in suburban Ontario and British Columbia households. The country's national transport safety regulator is monitoring US state-level legislation for potential harmonization. Toronto and Vancouver pet retail channels are expanding certified-restraint shelf space ahead of anticipated regulatory alignment.
Dog Seat Belt Market Competitive Landscape
The competitive structure tilts toward vertically integrated webbing producers with captive extrusion capabilities. Specialist brands and diversified pet accessory conglomerates share the remainder of the value chain. Three archetypes dominate: in-house webbing extruders controlling nylon quality from chip to finished strap; direct-to-consumer video marketers demonstrating crash-test protocols; and exclusive distribution partners with Tractor Supply and Chewy. Geographic expansion and portfolio diversification represent the dominant competitive moves, with players seeking TÜV certification gaps and telematics integration white space.
Among North American specialists, Kurgo, PetSafe, and Mighty Paw occupy distinct positioning vectors. Kurgo represents the backward-integrated archetype with captive webbing production. PetSafe anchors the exclusive distribution partnership model through mass retail and veterinary channels. Mighty Paw exemplifies direct-to-consumer video marketing approaches that demonstrate safety protocols to suburban households. Each occupies a position reflecting divergent bets on channel economics, certification investment, and consumer education intensity.
| Leading Market Players |
|---|
| Kurgo |
| PetSafe |
| Mighty Paw |
| Sleepypod |
| Ruffwear |
| EzyDog |
| Outward Hound |
| Snoozer |
| 4Knines |
| Others |
Value Network & Pricing Analysis
Recycled nylon chip extrusion for automotive-grade webbing is compressing cost differentials between virgin and reclaimed feedstocks while concentrating production among European and North American extruders with certified polymer traceability systems. This technology transition simultaneously elevates compliance costs for smaller Asian exporters and tightens supply availability for load-rated harness components.
Pricing Analysis
Crash-test certification outcomes anchor value-based pricing tiers, with TÜV-validated restraints commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels separates veterinary-specified vehicle-grade systems from suburban consumer harnesses and mass-market entry products. Price differentiation hinges on dynamic load documentation and batch-level polymer sourcing records. Margins are tightening due to EU Green Deal compliance investments in recycled-content certification. Rescue organizations and multi-dog households exhibit highest price sensitivity; veterinary clinics and professional trainers demonstrate lowest sensitivity given liability-driven procurement mandates.
Supply Chain Analysis
Ocean freight rate volatility from Shanghai and Ningbo to Los Angeles and Rotterdam is amplifying landed cost uncertainty for zinc hardware and snap-hook assemblies. Die-cast metal components concentrate in Zhejiang province; extrusion-grade nylon chips source from Bavarian chemical processors and domestic US suppliers. Raw material dependencies span virgin and recycled polyamide feedstocks, die-cast zinc alloys, and stainless steel load-bearing hardware. Single-source vulnerability runs through Wenzhou hardware clusters exposed to tariff disruption. Distribution runs through Chewy and Tractor Supply exclusive partnerships, veterinary clinic direct accounts, and direct-to-consumer video-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dynamic load testing capacity scarcity props pricing for certified restraints, as sled-test facilities with pet-specific anthropomorphic dummy protocols remain critically limited across North America and Europe.
For Market Incumbents: Lock in exclusive access to TÜV-certified testing facilities through multi-year scheduling agreements, insulating validation pipelines from emerging entrant queue competition. Deepen backward integration into recycled nylon chip extrusion to capture EU Green Deal compliance premiums and reduce virgin petroleum feedstock exposure. Secure direct veterinary clinic relationships before California and New York potentially mandate specific tensile-test certifications for retail placement eligibility. For New Entrants and Emerging Players: California AB 47 in the United States opens a window for telematics-integrated restraint systems targeting coastal metropolitan households with elevated vehicle miles traveled per pet. The German TÜV certification gap among Asian exporters creates first-mover opportunity for compliant entrants seeking EU veterinary channel access. Prioritize video-demonstrated crash-test protocols for direct-to-consumer acquisition, mirroring Mighty Paw's content marketing architecture without requiring equivalent distribution infrastructure investment. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified pet accessory conglomerates seeking crash-test certification capabilities and veterinary channel relationships. Long-term viability favors vertically integrated webbing producers with captive extrusion and established polymer traceability systems. Watch for California or New York state legislation mandating specific tensile-test certifications as retail placement conditions; such rules would immediately reshape supplier qualification criteria and concentrate market share among pre-compliant incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| TÜV Certification Investment | Secures EU veterinary channel access where automotive safety standards dominate procurement criteria. |
| Recycled Nylon Extrusion Integration | Captures EU Green Deal compliance premiums while reducing virgin petroleum feedstock cost volatility. |
| Telematics-Enabled Restraint Development | Addresses unclaimed white space in GPS-synced pet tracking applications for coastal metropolitan markets. |
| Veterinary Clinic Direct Partnership | Converts professional liability requirements into mandatory consumer procurement through post-surgical transport protocols. |
| Subscription-Based Component Replacement | Captures lifetime value through automated webbing replenishment for stress-fatigued harness systems. |
Research Methodology
Document review covered NHTSA consumer advisories, FDA pet product labeling guidelines, EU Green Deal technical documentation, and state-level distracted-driving legislation, complemented by interviews with veterinary clinic procurement managers, pet product retail category buyers, webbing extrusion plant managers, and automotive safety testing facility directors. Secondary validation drew from customs trade data, SEC filings of publicly traded pet accessory companies, and veterinary professional association transport safety guidelines. Bottom-up demand modeling from end-user segments was triangulated against top-down market sizing from production capacity estimates.
Segmentation outputs across product type, material composition, end-user category, and distribution channel were generated through the projection horizon, with CAGRs derived from regression analysis of historical adoption curves and regulatory enforcement intensity indices. Industry-specific forecast inputs included state-level distracted-driving violation rates, veterinary clinic liability insurance premium trends, and recycled nylon chip tensile specification achievement rates from European chemical processors.
The model assumes a particular technology adoption path for telematics-integrated restraint systems; alternative pathways for GPS-enabled pet tracking hardware would alter the outlook for premium product category expansion. Forecasts reflect assumptions regarding regulatory harmonization timing and testing facility capacity addition rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Europe Pet Clothing Market
Pet Care Products
China Pet Food Market
Pet Care Products
Dog Water Bottle Market
Pet Care Products
Aquarium Supplies Market
Pet Care Products
High Protein Dog Food Market
Pet Care Products
Cat Bed Market
Pet Care Products
South Africa Pet Boarding Market
Pet Care Products
Smart Cat Eye Market
Pet Care Products
Disposable Absorbent Pet Pad Market
Pet Care Products
Dog Perfume Market
Pet Care Products
Pet Corrector Spray Market
Pet Care Products
Pet Furniture Market
Pet Care Products
Natural Pet Food Market
Pet Care Products
Pet Grooming Services Market
Pet Care Products
Robotic Pets Market
Pet Care Products
Outdoor Dog Bed Market