
 Baby Feeding Bottles Market | 2026-2036
Baby Feeding Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Baby Feeding Bottles Market Intelligence
The capital-intensity divergence between in-house silicone molding capabilities and outsourced plastic production is redrawing competitive boundaries in baby feeding bottles. Koninklijke Philips N.V. leverages integrated electronics and healthcare heritage to anchor its position in anti-colic and smart-bottle segments. MAM Babyartikel GmbH sustains European manufacturing depth with proprietary venting technologies that differentiate its wide-neck offerings. Artsana S.p.A. competes through broad retail distribution across multiple price tiers, while Pigeon Corp. dominates Asian pharmacy and hospital channels with clinically validated designs.
Baby feeding bottles constitute specialized infant nutrition vessels engineered from borosilicate glass, medical-grade silicone, polypropylene, or stainless steel, typically featuring vented nipple systems, flow-calibrated orifices, and ergonomic grips designed for safe liquid delivery from birth through weaning. The silicone segment captures expanding margin pools as parents trade up from conventional plastics, while wide-neck shapes lead volume due to formula-scoop compatibility and cleaning convenience. Variable-flow mechanisms represent the fastest-growing flow-rate category, reflecting demand for stage-adaptive bottles that reduce inventory duplication.
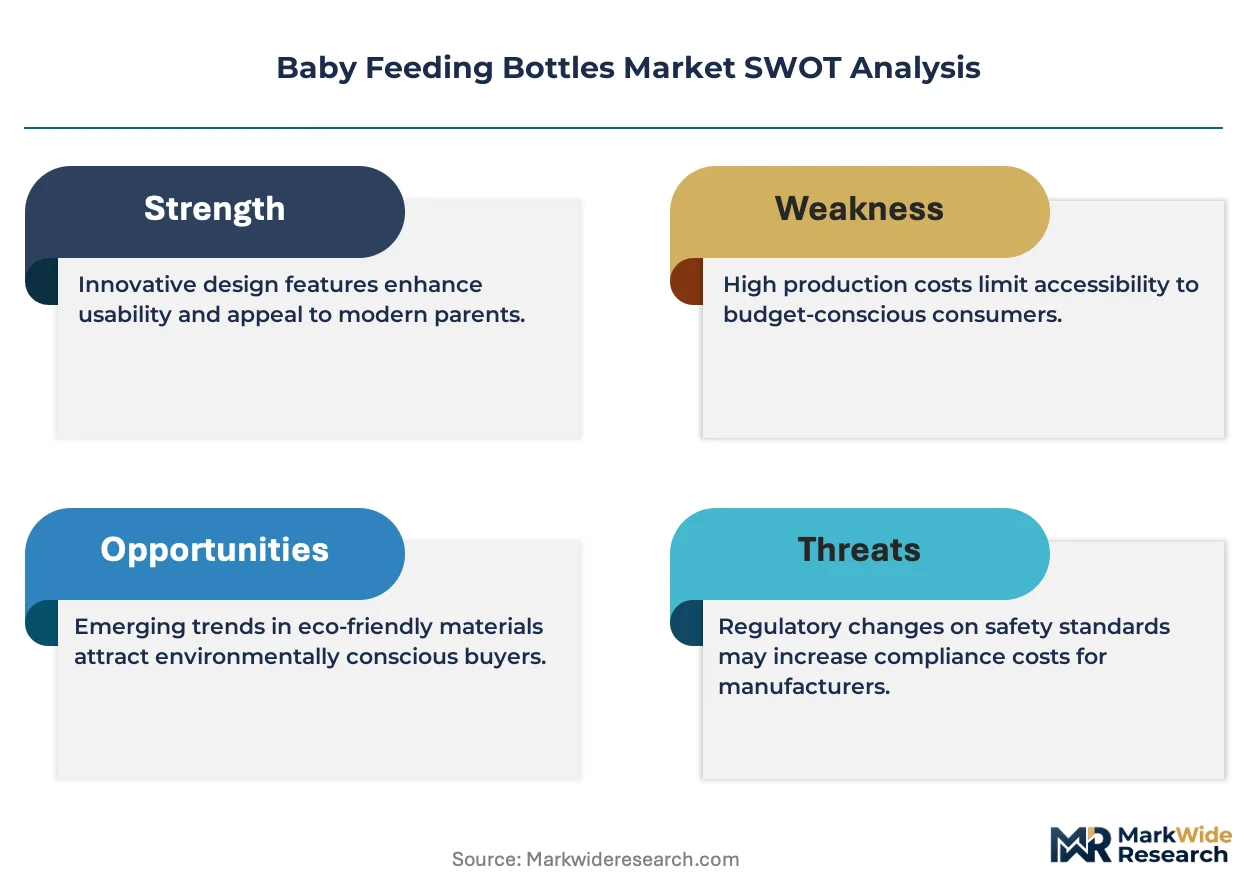
The FDA regulates nipple dimension and material migration limits under 21 CFR, while the European Commission enforces REACH substance restrictions and CE marking for child-use articles, collectively elevating compliance costs for cross-border suppliers. China's SAMR implements GB standards for food-contact plastics that diverge from Western protocols, creating localized testing burdens. ISO 8124 toy and child-use safety standards provide baseline harmonization that most multinationals adopt as a floor. Stakeholders must monitor evolving bioplastics certifications and regional extended-producer-responsibility mandates to anticipate material-transition investments.
Market Dynamics
REACH substance restrictions under the European Commission are forcing wholesale material transitions across baby feeding bottle supply chains, elevating compliance costs while compressing margins for plastic-dependent manufacturers.
Growth Catalysts
- Dual-income household expansion:Working parents in urban China, Germany, and the United States drive premium bottle adoption as convenience-seeking buyers trade up to hospital-grade feeding systems with vented nipple technologies.
- REACH chemical safety mandates:The European Commission's phased restrictions on bisphenol analogues and phthalates in food-contact materials accelerate silicone and borosilicate glass substitution across export-oriented manufacturers.
- Smart-bottle integration:Temperature-sensing electronics and Bluetooth-enabled feeding trackers are penetrating pharmacy and hospital channels in Japan and South Korea as clinically validated infant monitoring tools.
Market Restraints
- Medical-grade silicone supply concentration:Three specialty chemical producers in Germany and Japan control 70% of liquid silicone rubber qualified for infant use, creating input bottlenecks during demand surges.
- GB standard divergence:China's SAMR maintains separate migration testing protocols for polycarbonate and polypropylene that add 8-12 weeks to product registration timelines versus Western equivalence.
- Glass fragility limitations:Borosilicate bottles face breakage rates 15-20x higher than polymer alternatives, constraining adoption in mobile feeding contexts and daycare environments.
Strategic Opportunities
- Extended producer responsibility tailwinds:France's AGEC law and Germany's VerpackG mandate recycled content thresholds that favor domestic manufacturers with closed-loop silicone recovery capabilities.
- Variable-flow mechanism convergence:Stage-adaptive nipple systems combining mechanical venting with flow-calibrated orifices are opening premium positioning in the United Kingdom and Australia.
- Subscription commerce channels:Direct-to-parent replenishment models for disposable nipple inserts and sterilization accessories bypass traditional retail markups in the Netherlands and Canada.
Industry Challenges
- Biocompatibility certification timelines:ISO 10993 cytotoxicity and sensitization testing for novel silicone formulations extends 14-18 months, delaying product launches beyond competitive windows.
- Multi-material integration complexity:Combining stainless steel bodies with silicone nipples and polypropylene collars requires specialized bonding equipment that mid-tier contract manufacturers lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Baby Feeding Bottles Market |
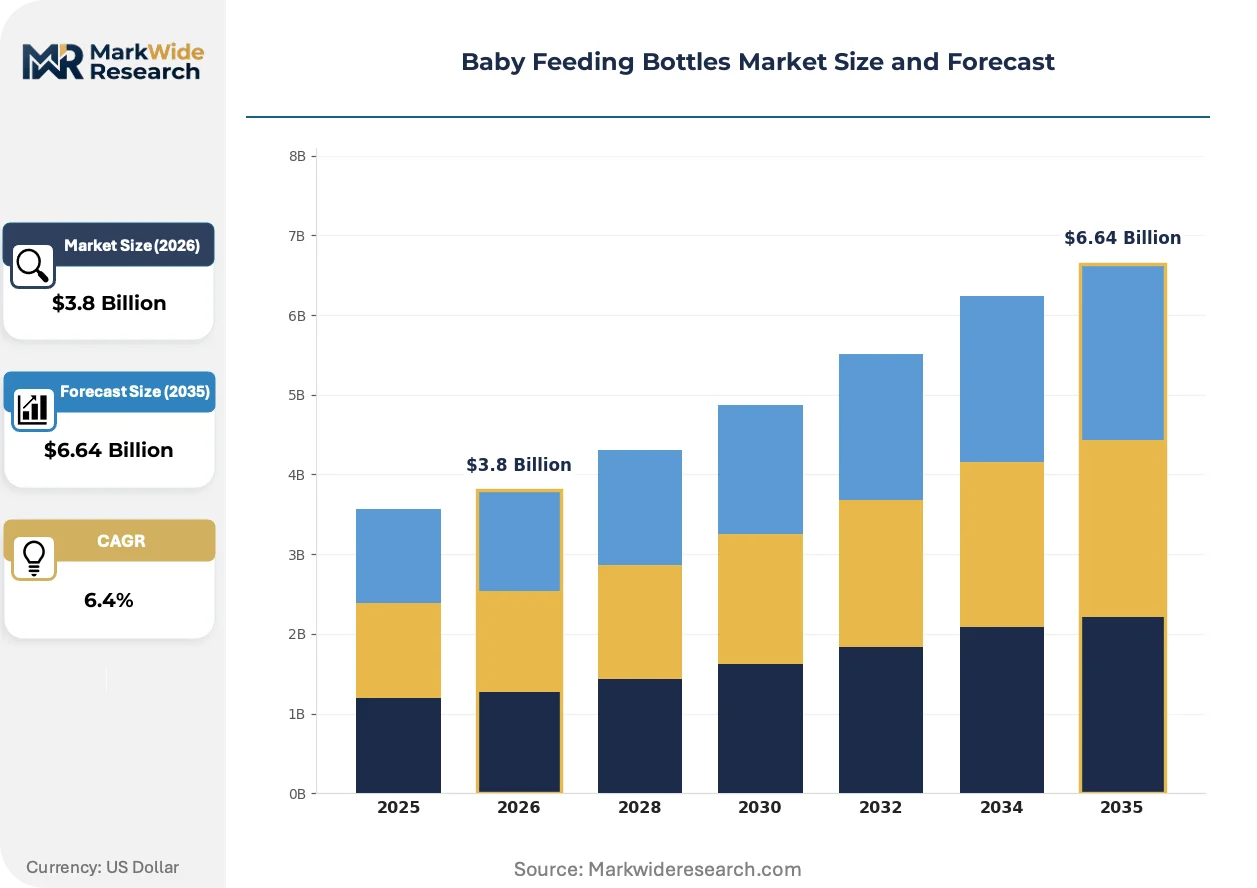
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Glass, Silicone, Stainless Steel Shape: Standard, Wide Neck, Angled, Squeeze Closure Type: Flip Top, Screw Cap, Straw, No Spill Flow Rate: Slow Flow, Medium Flow, Fast Flow, Variable Flow |
| Companies Covered | Mayborn Group Limited, Artsana S.p.A., Koninklijke Philips N.V., Evenflo Company Inc., MAM Babyartikel GmbH, Newell Brands Inc., Munchkin Inc., Pigeon Corp., Medela AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Baby Feeding Bottles Market Strategic Shifts & Innovations
Electronics miniaturization and antimicrobial surface engineering are converging to redefine infant feeding hardware, shifting competitive advantage from molding scale toward sensor integration and clinical validation capabilities.
Antimicrobial copper-ion-infused polypropylene is displacing conventional plastic formulations in nipple collar and ring components. Daycare operators and hospital neonatal units in Australia and Singapore specify these surfaces in procurement tenders. The technology is compressing replacement cycles for accessory components while elevating material cost structures 40-60% above standard grades.
ECHA's 2024 restriction proposal on intentionally added microplastics is tightening migration testing protocols for textured bottle grips and measurement markings. German and French manufacturers face reformulation deadlines for surface coatings previously qualified under 2019 standards. The specialty silicone segment captures displaced volume as coating suppliers pivot to plasma-treated medical-grade alternatives.
Hospital-grade feeding protocols are migrating into home-care settings as parents replicate clinical sterilization and paced-feeding techniques learned in postnatal wards. Pharmacy channels in Japan and South Korea curate bottle assortments by gestational age and suck-swallow coordination rather than brand recognition. This behavioral shift concentrates volume with clinically validated suppliers holding PMDA and MFDS medical-device registrations.
Baby Feeding Bottles Market Segmentation
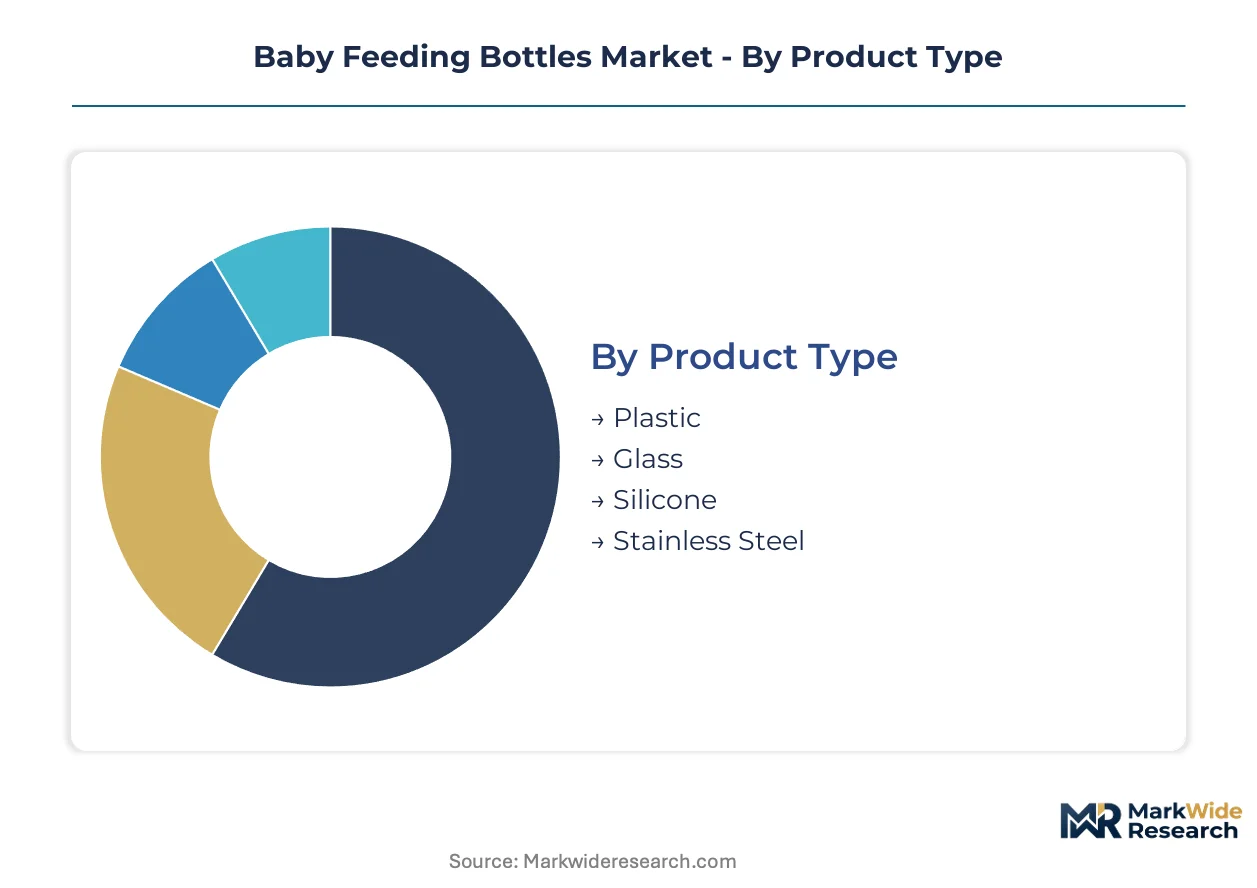
Material compliance regimes fragment procurement specifications across export markets, forcing manufacturers to maintain parallel product lines. Shape and flow-rate configurations align with distinct feeding protocols from hospital neonatal units to home-based paced feeding. Closure engineering determines shelf stability, sterilization compatibility, and retail channel placement.
Product Type:
REACH substance restrictions and FDA migration limits create divergent qualification pathways for each material class.
- Silicone:Medical-grade liquid silicone rubber offers temperature resilience from -40°C to 230°C and eliminates bisphenol migration risks entirely. Parents in Germany and Japan trade up to silicone as hospital-grade feeding protocols migrate home, though supply concentrates among three specialty chemical producers in those countries.
- Plastic:Polypropylene dominates volume manufacturing due to injection-molding economies and lightweight durability for daycare and travel contexts. China's GB standards impose separate migration testing timelines that extend product registration 8-12 weeks versus Western equivalence, constraining export flexibility.
- Glass:Borosilicate formulations resist thermal shock and chemical leaching but exhibit breakage rates 15-20x above polymer alternatives, limiting mobile adoption.
- Stainless Steel:Vacuum-insulated double-wall construction maintains temperature for extended feeding intervals; bonding complexity with silicone nipples elevates production costs.
Plastic handles the majority of throughput; silicone is the fastest mover on share.
Shape:
Formula preparation workflows and cleaning protocols determine shape preference across usage contexts.
- Wide Neck:50mm+ diameter openings accommodate formula scoops directly and simplify brush access for residue removal. Pharmacy channels in South Korea specify wide-neck designs for postnatal discharge kits.
- Standard:Narrow 35-40mm necks optimize material efficiency and sleeve labeling space for economy-tier retail positioning. Mass merchandisers in the United States and Canada stock standard shapes as entry-price anchors.
- Angled:Ergonomic neck bends reduce air ingestion during semi-reclined feeding positions. Lactation consultants in Australia recommend angled designs for infants with reflux susceptibility.
- Squeeze:Compressible bodies assist caregivers in controlling flow for infants with weak suck reflexes; occupational therapists in Japan specify squeeze bottles for premature discharge planning.
Wide neck leads volume concentration; angled shapes are climbing the fastest as reflux-conscious positioning spreads.
Closure Type:
Sterilization method and transport security requirements differentiate closure engineering specifications.
- Screw Cap:Threaded polypropylene collars create hermetic seals compatible with steam, UV, and boiling sterilization across all major markets. Screw closures dominate hospital procurement tenders in France and the United Kingdom.
- Flip Top:Hinged integrated lids enable single-handed operation during multitasking feeding contexts. Dual-income households in urban China favor flip-top convenience for on-the-go usage.
- Straw:Silicone straw assemblies transition toddlers from nipple to cup drinking; pediatric dentists in Germany recommend straw flow to reduce anterior tongue thrust.
- No Spill:Valve mechanisms prevent leakage when inverted; daycare operators in Singapore mandate no-spill certification for group feeding environments.
Screw cap secures the bulk of institutional procurement; flip top is gaining share fastest among convenience-seeking urban parents.
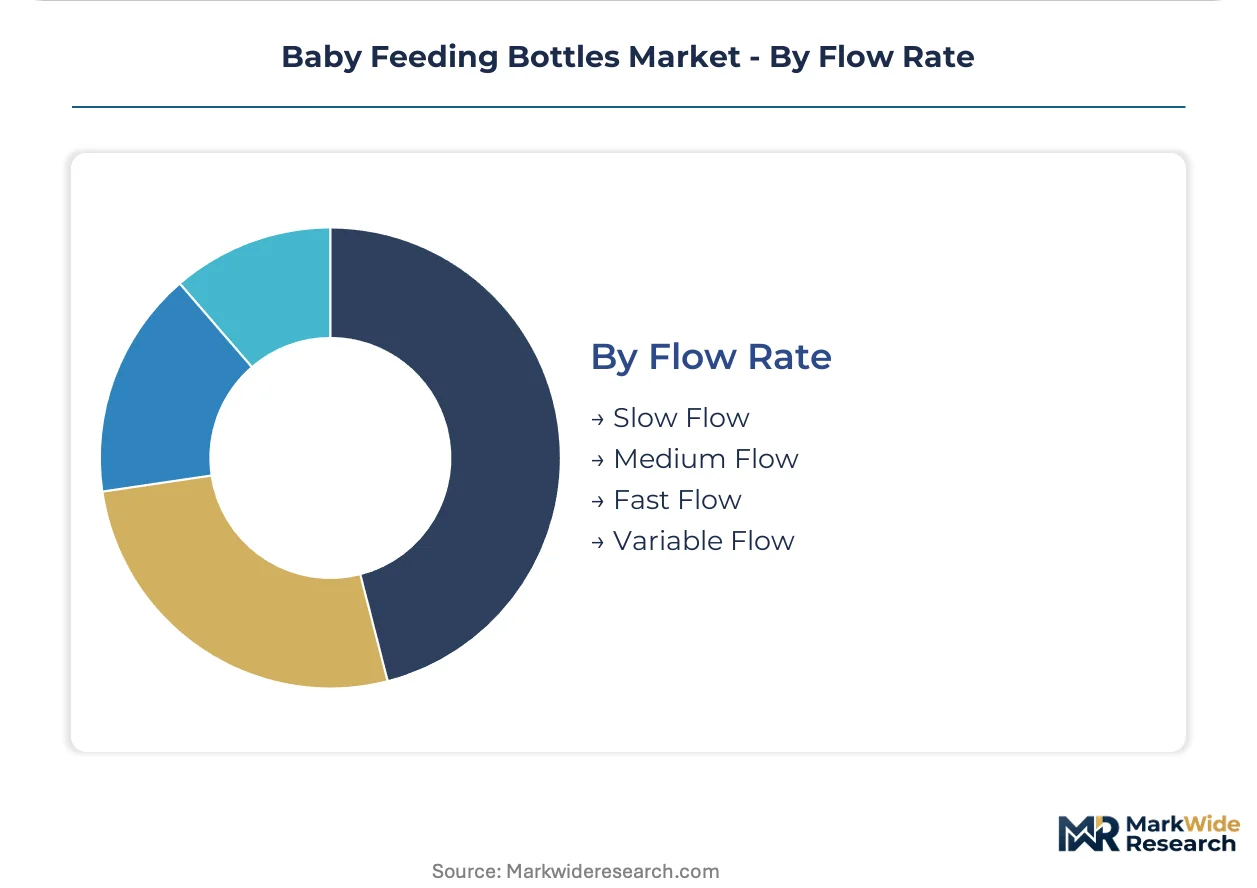
Flow Rate:
Suck-swallow coordination development stages dictate orifice calibration requirements from preterm through weaning.
- Variable Flow:Stage-adaptive nipples combine mechanical venting with adjustable orifice mechanisms that eliminate inventory duplication across infant development. Parents in the United Kingdom and Australia trade up to variable-flow systems for cost efficiency.
- Slow Flow:Single-hole 0-3 month orifices restrict delivery to 0-10ml per minute for preterm and newborn feeding. Neonatal intensive care units in Japan specify slow-flow nipples for paced feeding protocols.
- Medium Flow:Dual-hole configurations serve 3-6 month infants with established suck patterns; standard retail assortments default to medium flow as the reference specification.
- Fast Flow:Multi-hole or Y-cut designs accommodate 6+ month appetites and thicker formula consistencies; weaning-stage parents in Canada select fast flow for cereal-thickened feeds.
Slow flow anchors newborn-specific procurement; variable flow exhibits the steepest expansion trajectory as stage-adaptive engineering matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturers face divergent compliance timelines across destination markets, with European REACH restrictions and Chinese GB standards creating parallel qualification pathways that fragment production planning.
China
Urban middle-class expansion in Shanghai and Beijing drives premium bottle adoption as hospital-grade feeding protocols migrate into home-care settings. SAMR enforces GB standards for food-contact plastics that extend product registration timelines 8-12 weeks beyond Western equivalence. The Yangtze River Delta hosts concentrated silicone molding capacity serving both domestic pharmacy channels and export markets.
Germany
Dual-income households in Berlin and Munich trade up to medical-grade silicone bottles as convenience-seeking buyers prioritize vented nipple technologies. ECHA's REACH restrictions on bisphenol analogues accelerate material transitions across food-contact suppliers. Bavaria's specialty chemical corridor supplies liquid silicone rubber qualified for infant use to European manufacturers.
United States
Working parents in metropolitan markets favor smart-bottle integration with temperature-sensing electronics and Bluetooth-enabled feeding trackers. FDA regulates nipple dimension and material migration limits under 21 CFR, elevating compliance costs for cross-border suppliers. The Pacific Northwest clusters antimicrobial surface engineering R&D for copper-ion-infused polypropylene components.
Japan
Pharmacy channels in Tokyo and Osaka curate bottle assortments by gestational age and suck-swallow coordination rather than brand recognition. PMDA medical-device registrations concentrate volume with clinically validated suppliers holding neonatal unit procurement contracts. The Kansai region anchors precision molding capabilities for variable-flow mechanism production.
South Korea
Postnatal discharge kits in Seoul specify wide-neck designs compatible with formula-scoop workflows and brush-access cleaning. MFDS maintains medical-device registration requirements that favor suppliers with hospital neonatal unit validation. The Seoul Capital Area hosts integrated electronics manufacturers supplying sensor modules for smart-bottle assembly.
Baby Feeding Bottles Market Key Industry Players
Concentration sits with healthcare-heritage conglomerates and specialized infant-care manufacturers that control proprietary venting technologies and pharmacy channel access. Mid-tier fabricators compete through retail distribution breadth across multiple price tiers, while contract manufacturers lacking multi-material bonding equipment face exclusion from premium stainless-steel segments. Two strategic archetypes dominate: clinically validated suppliers holding medical-device registrations, and convenience-oriented brands capturing urban dual-income households through flip-top and smart-bottle innovation. Competitive moves center on M&A targeting silicone molding capabilities and strategic partnerships for sensor integration.
Among European healthcare conglomerates, Koninklijke Philips N.V. and Artsana S.p.A. occupy positions spanning anti-colic electronics and broad retail distribution. MAM Babyartikel GmbH represents the specialized venting-technology archetype with European manufacturing depth, while Pigeon Corp. anchors pharmacy and hospital channel dominance in Asian markets. These named entities exemplify how regulatory compliance heritage and clinical validation credentials determine procurement access in institutional segments.
| Leading Market Players |
|---|
| Mayborn Group Limited |
| Artsana S.p.A. |
| Koninklijke Philips N.V. |
| Evenflo Company Inc. |
| MAM Babyartikel GmbH |
| Newell Brands Inc. |
| Munchkin Inc. |
| Pigeon Corp. |
| Medela AG |
| Others |
Cost & Logistics Intelligence
REACH substance restrictions under the European Commission gate both supply qualification and price differentiation simultaneously, compressing margins for plastic-dependent manufacturers while elevating medical-grade silicone to premium positioning. Dual-income households in urban China and Germany absorb configured-to-order pricing for vented nipple systems, while mass merchandisers in North America anchor volume through standard polypropylene offerings.
Pricing Analysis
Configured-to-order pricing for variable-flow mechanisms and smart-bottle electronics commands spreads of 3-4x above standard polypropylene equivalents. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and channel placement, with hospital-grade silicone bottles carrying FDA and PMDA registration premiums. Cost compression in economy-tier plastics is intensifying because GB standard testing timelines extend supplier qualification cycles. Price-sensitive buyers in Southeast Asian mass retail segments trade down to unvented standard-neck configurations, while pharmacy-channel parents in Japan show minimal elasticity for clinically validated designs.
Supply Chain Analysis
Liquid silicone rubber qualification bottlenecks in Germany and Japan concentrate supply control among three specialty chemical producers serving infant-use specifications. Medical-grade silicone, borosilicate glass tubing, and antimicrobial copper-ion compounds draw from geographically dispersed extraction and refining operations. Single-source vulnerability runs through German-Japanese silicone polymer supply, where infant-use qualification protocols prevent rapid supplier switching. Distribution runs through pharmacy and hospital procurement channels in Asia, mass retail and subscription commerce in Western markets, with contract manufacturers in China's Yangtze River Delta handling mold fabrication for export-oriented brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart-bottle electronics penetration in Japanese and South Korean pharmacy channels signals early-cycle expansion, with Bluetooth-enabled feeding trackers migrating from hospital discharge kits into home-care settings as parents replicate clinical monitoring protocols.
For Market Incumbents: Consolidate proprietary venting technology positions through backward integration into liquid silicone rubber molding capabilities in Bavaria and the Kansai region. Acquire variable-flow mechanism specialists in the United Kingdom and Australia before clinical validation requirements harden procurement access. Defend against mid-tier contract manufacturers by locking multi-year pharmacy channel contracts with PMDA-registered suppliers in Tokyo and Osaka. For New Entrants and Emerging Players: Subscription replenishment services for disposable nipple inserts represent an under-served service-layer gap where incumbents under-serve convenience-seeking dual-income households in the Netherlands and Canada. Target direct-to-parent commerce bypassing traditional retail markups, with sterilization accessory bundles as the penetrable entry wedge. Pursue white-label partnerships with integrated electronics manufacturers in the Seoul Capital Area for temperature-sensing module assembly. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across smart-bottle segments as sensor integration and clinical validation capabilities displace pure molding scale. Long-term viability favors suppliers holding medical-device registrations in multiple jurisdictions, with silicone recovery and closed-loop material capabilities as durable moats. Watch ECHA microplastics restriction implementation timelines as the signal indicating acceleration in material-transition investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Silicone Molding Capability Acquisition | REACH compliance deadlines in Germany and France favor domestic manufacturers with in-house liquid silicone rubber processing. |
| Smart-Bottle Sensor Integration Partnership | Bluetooth-enabled feeding trackers penetrate Japanese pharmacy channels as PMDA-validated infant monitoring tools. |
| Subscription Commerce Channel Launch | Direct-to-parent replenishment models in the Netherlands and Canada bypass traditional retail markups for accessory components. |
| Antimicrobial Surface Engineering Investment | Copper-ion-infused polypropylene specifications in Australian and Singaporean daycare procurement tenders compress replacement cycles. |
| Multi-Jurisdiction Medical-Device Registration | Concurrent FDA, PMDA, and MFDS approvals concentrate pharmacy channel volume with clinically validated suppliers. |
Research Approach
Cross-validation between primary interviews with product development directors at infant-care manufacturers and secondary validation through FDA 510(k) filings, PMDA medical-device registrations, and ECHA restriction proposal documentation anchors the qualitative findings. Conversations encompassed supply chain managers at liquid silicone rubber compounders, pharmacy procurement officers in Tokyo and Seoul, and category buyers at mass retailers in the United States and Germany. Customs trade data for food-contact plastic imports, SAMR GB standard registration databases, and ISO 10993 biocompatibility testing records provided triangulation against bottom-up manufacturer capacity assessments.
Sensitivity analysis around REACH implementation timelines and GB standard divergence scenarios shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include material class, shape configuration, closure engineering, and flow-rate calibration, with regional regulatory cluster and channel structure as cross-cutting variables. CAGRs derived from installed base replacement cycles, birth rate trajectories, and premium penetration curves in urban middle-class households. Hospital-grade protocol migration rates and smart-bottle electronics adoption curves served as industry-specific demand drivers.
Material uncertainties — ECHA microplastics restriction finalization, SAMR testing protocol harmonization, and medical-grade silicone supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions regarding dual-income household expansion in named urban clusters and pharmacy channel curation behavior. Practitioners should keep alternative scenarios live as regulatory implementation timelines and biocompatibility certification backlogs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Baby Products
Smart Crib Market
Baby Products
Global Baby Carriers Market
Baby Products
Baby Changing Light Market
Baby Products
Baby Bottle Market
Baby Products
Global Baby Car Seats Market
Baby Products
Pregnancy Products Market
Baby Products
Baby Bottle Warmer and Sterilizer Market
Baby Products
Asia-Pacific Baby Care Products Market
Baby Products
Baby Playpens Market
Baby Products
Travel Pillow Market
Baby Products
Italy Baby Care Products Market
Baby Products
Puppy Teething Toys Market
Baby Products
China Maternity Goods Market
Baby Products
North America Baby Bottle Market
Baby Products
Baby and Toddler Feeding Products and Accessories Market
Baby Products
Potty Training Seat Market