
 Dog Food Market | 2026-2036
Dog Food Market Size, Share, and Industry Trends Forecast 2026-2036
Dog Food Market Intelligence
Subscription-based fresh meal delivery is decoupling dog food from traditional retail shelf dynamics. Mars Incorporated leverages its veterinary clinic network to sustain direct-to-consumer relationships. Nestlé Purina PetCare anchors premium positioning through prescription diet specialization. Hill's Pet Nutrition competes on clinical credibility with science-backed therapeutic formulations.
Dog food comprises commercially manufactured nutritional products formulated from proteins, carbohydrates, fats, vitamins, and minerals to meet canine dietary requirements, typically processed through extrusion for dry kibble or retort sterilization for wet formats to ensure shelf stability and digestibility. Dry food dominates volume due to cost efficiency and storage convenience, while raw and fresh segments capture expanding margin pools as health-conscious owners prioritize minimally processed ingredients. Natural and grain-free ingredient quality tiers attract disproportionate pricing power, though regulatory scrutiny on label claims intensifies compliance costs.
FDA Center for Veterinary Medicine and AAFCO model regulations govern ingredient safety and nutritional adequacy claims in the United States, while the EU's FEDIAF nutritional guidelines and national feed law implementations standardize cross-border product compliance. The EU Green Deal's sustainable packaging mandates are pressuring manufacturers to reformulate supply chains around recyclable materials. Stakeholders must monitor evolving state-level raw feeding restrictions and veterinary telehealth integrations that reshape how nutritional advice reaches owners.
Market Dynamics
Pet humanization is collapsing the distinction between companion animal nutrition and human food systems, forcing manufacturers to adopt pharmaceutical-grade traceability and clinical validation protocols previously reserved for therapeutic applications.
Growth Catalysts
- AAFCO Nutritional Adequacy Framework:Standardized feeding trial protocols in the United States eliminate formulation ambiguity, accelerating premium product commercialization.
- Retort sterilization advances:High-pressure processing and aseptic filling extend wet food shelf life without synthetic preservatives, unlocking fresh-format scalability.
- Brazilian middle-class expansion:São Paulo and Rio de Janeiro pet ownership rates now mirror developed-market penetration, creating volume anchors for South American production.
Market Restraints
- Animal protein input volatility:Chicken meal and fish oil prices fluctuate with agricultural commodity cycles, compressing margin predictability for mid-tier brands.
- Single-source supply concentration:Vitamin and mineral premix production clusters in Chinese and Indian chemical processing hubs, exposing formulators to geopolitical disruption.
- Raw feeding regulatory friction:State-level pathogen control mandates in the United States impose testing burdens that small-batch producers struggle to absorb.
Strategic Opportunities
- Veterinary telehealth integration:Remote consultation platforms in the United States and United Kingdom embed prescription diet recommendations directly into diagnostic workflows.
- EU Green Deal packaging mandates:Recyclable mono-material requirements create first-mover advantages for manufacturers with advanced flexible film capabilities.
- Senior canine metabolic health:Glucose management and cognitive support formulations address the expanding geriatric dog population in Japan and Western Europe.
Industry Challenges
- Veterinary nutritionist scarcity:Board-certified specialists remain concentrated in academic and corporate research settings, limiting independent formulation capacity.
- Cold chain infrastructure capex:Fresh and raw segment expansion requires refrigerated logistics investments that conflict with legacy dry food distribution economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dog Food Market |
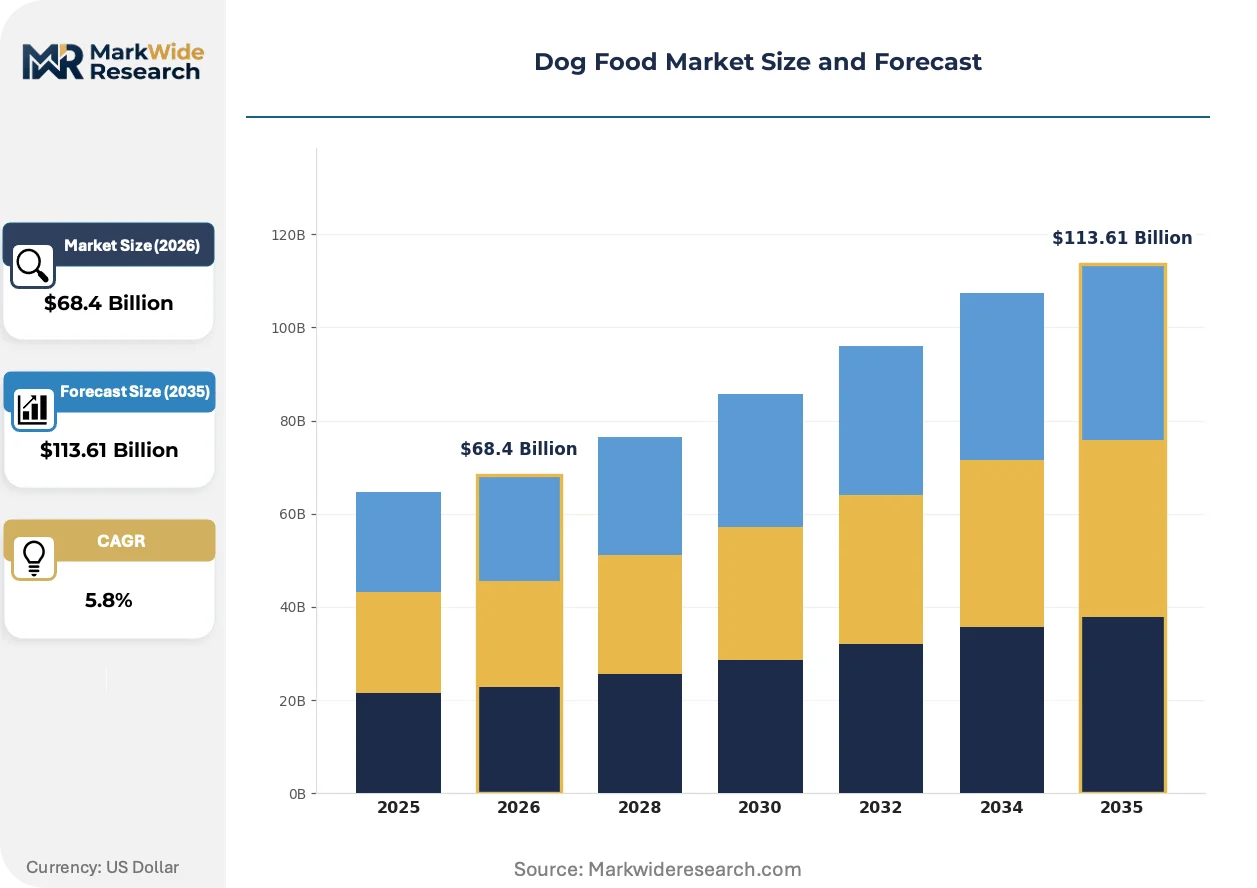
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Food, Wet Food, Treats, Raw Ingredient Quality: Natural, Organic, Grain-Free, Premium Distribution Channel: Online Retail, Pet Stores, Supermarkets, Wholesale Consumer Type: First-Time Dog Owners, Multi-Dog Households, Health-Conscious Owners, Others |
| Companies Covered | Mars Incorporated, Nestlé Purina PetCare, Colgate-Palmolive Company, The J.M. Smucker Company, General Mills, Hill's Pet Nutrition, Diamond Pet Foods, Blue Buffalo, Royal Canin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dog Food Market Strategic Shifts & Innovations
Manufacturing technology and distribution infrastructure are converging to collapse the traditional trade-off between nutritional integrity and commercial scalability that has defined the industry for decades.
Precision fermentation for alternative proteins is decentralizing supply chain risk away from conventional livestock agriculture. Cultured meat and microbial biomass startups in the Netherlands and United States achieve amino acid profiles matching poultry and fish inputs. Early adopters among sustainability-positioned brands in Germany and California integrate these ingredients at 15-30% inclusion rates, compressing reliance on commodity animal agriculture.
The EU Green Deal's sustainable packaging mandates are forcing material science investments across European manufacturing. Recyclable mono-film structures and paper-based barriers replace multi-layer laminates previously standard in wet food pouches. German and French producers face 2025 compliance deadlines, accelerating partnerships with specialty packaging converters and reshaping procurement specifications for coating and sealing technologies.
Subscription-based fresh meal delivery is fragmenting retail channel dominance in the United States and United Kingdom. Direct-to-consumer platforms capture health-conscious owners seeking portion-controlled, minimally processed diets, displacing supermarket and specialty pet store purchasing for premium segments. Urban density in London, New York, and Los Angeles enables economically viable cold-chain logistics that remain challenging in suburban and rural geographies.
Dog Food Market Segmentation
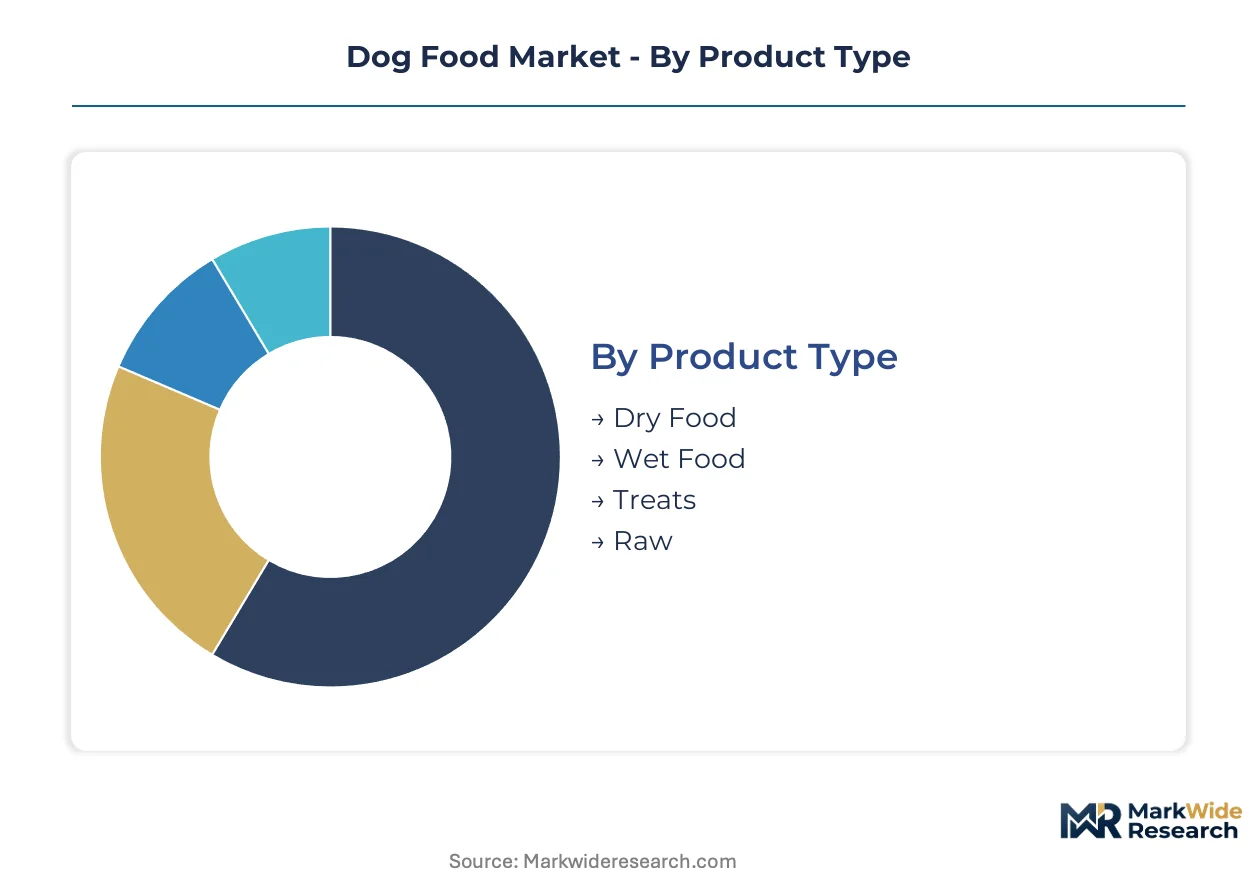
Dog food segmentation reflects divergent owner priorities across convenience, ingredient philosophy, and purchasing context. Manufacturers calibrate formulation complexity and margin architecture against distinct upgrade cycles that vary from weekly replenishment to lifestyle-driven category switching.
Product Type:
Upgrade cycles vary dramatically across physical formats, with moisture content and processing intensity determining replacement frequency and margin capture potential.
- Dry Food:Extruded kibble formulations deliver shelf-stable nutrition through high-temperature processing and fat coating. Multi-dog households in Brazil and the United States anchor volume through bulk purchasing and automatic feeder compatibility, though margin compression intensifies as private-label alternatives proliferate in supermarket channels.
- Wet Food:Retort-sterilized cans and pouches achieve higher moisture content and palatability through controlled thermal processing. Health-conscious owners in Japan and Western Europe drive premiumization as therapeutic formulations for renal and digestive conditions command veterinary endorsement.
- Treats:Functional and reward-based formats span dental chews to training rewards with compressed production cycles.
- Raw:Minimally processed frozen or freeze-dried products target owners rejecting conventional thermal processing.
Volume placements concentrate in Dry Food; the faster expansion belongs to Raw.
Ingredient Quality:
Cost tiers stratify around certification burden and supply chain traceability depth, with organic and human-grade specifications commanding disproportionate procurement investment.
- Natural:Formulations excluding artificial colors, flavors, and preservatives align with clean-label expectations in North American and European retail. AAFCO and FEDIAF labeling standards create compliance differentiation that smaller brands struggle to document.
- Organic:Certified organic ingredient chains require USDA or EU organic accreditation across farming, processing, and handling stages. German and California markets absorb price premiums as sustainability-positioned owners prioritize pesticide-free protein sourcing.
- Grain-Free:Alternative carbohydrate formulations from legumes and tubers address perceived digestive sensitivity.
- Premium:Super-premium positioning combines specified protein sources with enhanced nutrient density.
Natural captures the widest distribution footprint; Organic climbs the fastest as regulatory harmonization reduces cross-border friction.
Distribution Channel:
Channel selection determines customer data access, margin retention, and cold-chain infrastructure requirements with divergent capital intensity profiles.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators enable subscription mechanics and personalized portioning. Urban corridors in the United Kingdom and United States sustain fresh-format delivery economics through density-dependent logistics networks.
- Pet Stores:Specialty retailers provide tactile ingredient evaluation and staff consultation that online channels cannot replicate. Independent and chain pet stores in São Paulo and Tokyo maintain relevance through exclusive brand relationships and grooming service bundling.
- Supermarkets:Mass retail placement maximizes brand visibility for established dry food portfolios.
- Wholesale:Bulk distribution serves commercial kennels, breeders, and veterinary hospitals with volume pricing structures.
Supermarkets retain the highest absolute volume; Online Retail gains share fastest as cold-chain density improves.
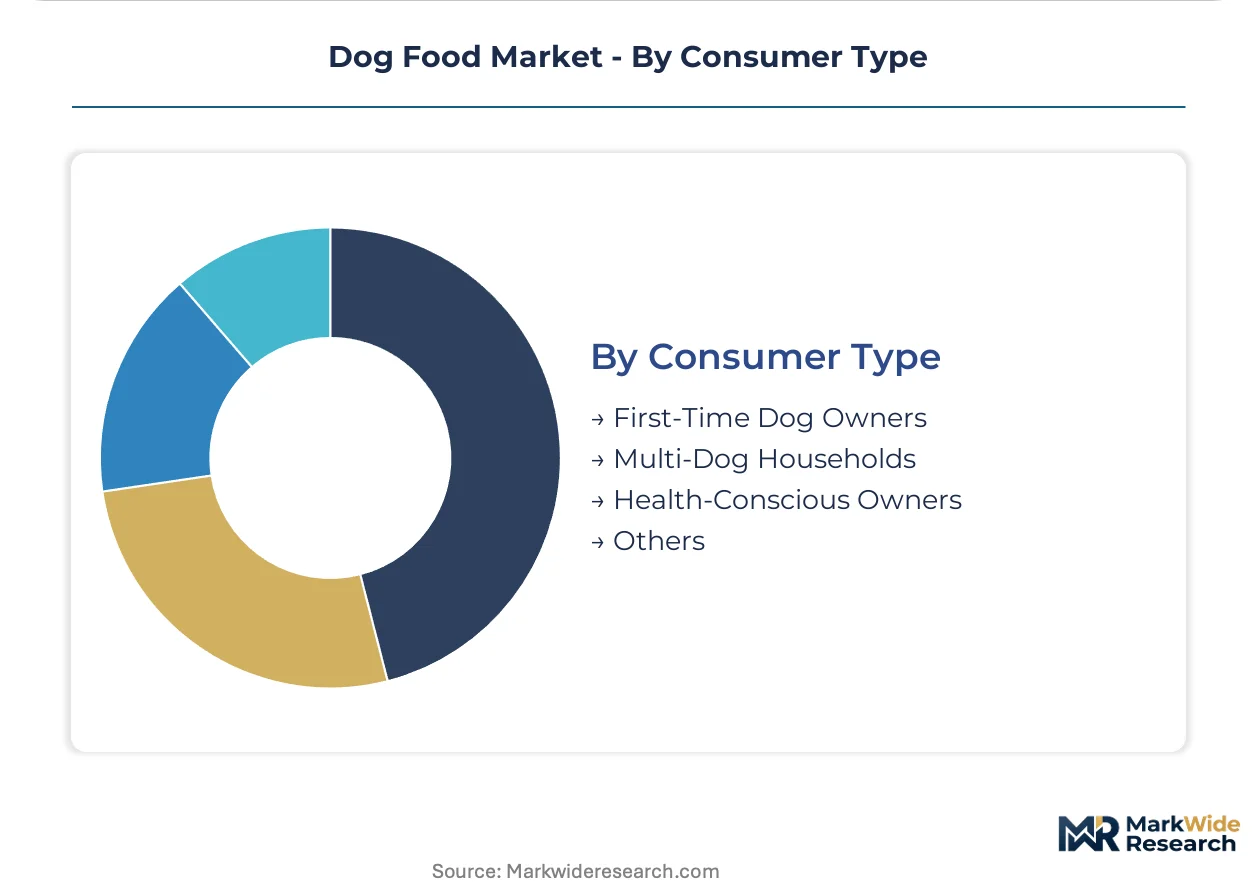
Consumer Type:
Household composition and owner sophistication determine formulation complexity tolerance and willingness to engage veterinary-guided nutrition.
- Health-Conscious Owners:Demographic segments prioritizing preventive nutrition and functional ingredients drive prescription diet adoption and fresh-format trials. Telehealth-integrated platforms in the United States embed nutritional counseling into diagnostic workflows, collapsing friction between veterinary advice and purchase execution.
- Multi-Dog Households:Volume-intensive purchasing patterns favor cost-optimized dry formulations with storage efficiency. Brazilian and Chinese middle-class expansion creates cohorts where pet ownership rates approach developed-market penetration.
- First-Time Dog Owners:Entry-level consumers rely heavily on retail staff recommendation and brand familiarity.
- Others:Breeders, foster networks, and working dog handlers represent specialized volume segments with distinct performance requirements.
Multi-Dog Households generate the largest absolute consumption; Health-Conscious Owners show the steepest expansion trajectory as humanization trends deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors Latin American volume through dense urban pet ownership and expanding veterinary infrastructure serving Brazil's emerging middle class.
United States
Subscription fresh meal delivery and telehealth-integrated prescription diets reshape purchasing patterns in New York and Los Angeles corridors. FDA Center for Veterinary Medicine and AAFCO model regulations govern nutritional adequacy claims and ingredient safety protocols. Kansas manufacturing clusters concentrate extrusion capacity for dry kibble serving North American distribution networks.
Brazil
São Paulo and Rio de Janeiro pet ownership rates now mirror developed-market penetration as middle-class expansion accelerates. ANVISA oversees feed safety standards while state-level agricultural departments monitor manufacturing facility compliance. Southern Brazilian production zones around Curitiba anchor supply chains for Mercosur export markets.
China
Pet humanization trends in Shanghai and Beijing drive premium import demand alongside domestic brand upgrading. SAMR implements national feed safety standards while provincial agricultural authorities license manufacturing facilities. Hebei and Shandong provinces concentrate contract manufacturing capacity serving both local consumption and regional export.
Germany
Sustainability-positioned owners in Berlin and Munich absorb organic certification premiums as the EU Green Deal reshapes packaging requirements. FEDIAF nutritional guidelines standardize cross-border compliance alongside national feed law implementations. Bavarian manufacturing corridors lead recyclable mono-material flexible film adoption ahead of 2025 deadlines.
Japan
Geriatric dog population growth in Tokyo and Osaka corridors fuels glucose management and cognitive support formulation demand. METI coordinates with prefectural authorities on pet food manufacturing standards and import inspection protocols. Chubu region production clusters specialize in therapeutic wet food formats for aging companion animal nutrition.
Dog Food Market Key Industry Players
Capital-heavy producers compete with asset-light designers as manufacturing scale advantages separate volume leaders from niche positioning specialists. The market consolidates around three structural tiers: multinational CPG conglomerates with veterinary network integration, mid-scale premium specialists with ingredient philosophy differentiation, and emerging fresh-format platforms with direct-to-consumer logistics. Dominant competitive moves include prescription diet specialization through veterinary channel capture and cold-chain infrastructure investment for fresh segment scalability.
Within the multinational tier, Mars Incorporated and Nestlé Purina PetCare occupy positions defined by veterinary clinic network density and prescription portfolio breadth. Hill's Pet Nutrition exemplifies the clinical credibility archetype through science-backed therapeutic formulation positioning. These three entities represent divergent strategic anchors: Mars through vertical integration into veterinary services, Nestlé Purina through premium standard-segment tiering, and Hill's through prescription-grade clinical validation protocols.
| Leading Market Players |
|---|
| Mars Incorporated |
| Nestlé Purina PetCare |
| Colgate-Palmolive Company |
| The J.M. Smucker Company |
| General Mills |
| Hill's Pet Nutrition |
| Diamond Pet Foods |
| Blue Buffalo |
| Royal Canin |
| Others |
Cost & Logistics Intelligence
Backward integration into captive vitamin and mineral premix production anchors both supply security and pricing power for multinational formulators facing commodity volatility in animal protein inputs. This upstream control over micronutrient sourcing insulates premium brands from the margin compression that mid-tier competitors absorb when Chinese and Indian chemical processing hubs experience disruption.
Pricing Analysis
Margin tightening in mid-tier dry kibble traces to private-label proliferation in supermarket channels and bulk purchasing patterns among multi-dog households. Three-tier pricing structure across premium, standard, and economy levels separates human-grade certified formulations from conventional extruded products, with organic and prescription diet tiers commanding the widest spreads. Cost-down pressure on standard-tier producers accelerates because Brazilian and Chinese contract manufacturers are scaling extrusion capacity. Health-conscious owners seeking fresh and raw formats show the least price sensitivity, while volume-intensive multi-dog households in Brazil and the United States drive the hardest negotiations.
Supply Chain Analysis
Regional distribution centers in Kansas, Curitiba, and Hebei province anchor hub-and-spoke patterns that feed veterinary clinics, specialty pet retailers, and direct-to-consumer cold-chain platforms. Manufacturing gravity draws from concentrated extrusion clusters in the United States, Brazil, and China, with vitamin premix sourcing resting on Indian and Chinese chemical processing capacity. Single-source concentration in Asian micronutrient production exposes formulators to geopolitical disruption and logistics chokepoints through Shanghai and Mumbai port complexes. Distribution runs through veterinary channel networks for prescription diets, mass retail for dry food volumes, and refrigerated last-mile logistics for fresh-format subscriptions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around veterinary channel control and cold-chain infrastructure scale, with AAFCO compliance burdens and capital-intensive fresh-format logistics forcing sub-scale players toward exit or acquisition.
For Market Incumbents: Deepen veterinary clinic network density to lock prescription diet distribution and capture telehealth-integrated nutritional counseling workflows. Invest in refrigerated logistics infrastructure in London, New York, and Los Angeles corridors to defend against fresh-format platform encroachment. Prioritize backward integration into alternative protein fermentation capacity to reduce exposure to commodity animal agriculture volatility.
For New Entrants and Emerging Players: Direct-to-consumer subscription platforms offer the lowest barrier to entry for health-conscious owner segments underserved by legacy retail. Target geriatric canine metabolic health formulations in Japan and Western Europe where veterinary guidance drives premium acceptance. Pursue precision fermentation ingredient partnerships with Dutch and California startups to differentiate on sustainability positioning without captive manufacturing investment.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational CPG conglomerates seeking veterinary channel density or fresh-format logistics capabilities. Five-to-ten-year viability hinges on cold-chain scalability and regulatory compliance infrastructure rather than brand equity alone. Watch for state-level raw feeding restriction tightening as an inflection indicator that would accelerate consolidation toward capital-compliant producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Channel Expansion | Prescription diet authorization through clinic networks locks recurring revenue and defends against retail commoditization. |
| Cold-Chain Infrastructure Investment | Refrigerated logistics density in urban corridors enables fresh-format subscription scalability that dry-food economics cannot replicate. |
| Alternative Protein Sourcing | Precision fermentation partnerships with Netherlands and California startups reduce commodity livestock input exposure. |
| Sustainable Packaging Transition | EU Green Deal mono-material compliance ahead of 2025 deadlines creates first-mover positioning in German and French markets. |
| Telehealth Platform Integration | Remote diagnostic workflows embed nutritional recommendations directly into purchase execution, collapsing friction. |
Research Approach
Independent corroboration across FDA Center for Veterinary Medicine filings, FEDIAF nutritional guideline updates, and ANVISA manufacturing facility registrations underwrites the qualitative findings. Primary interviews with veterinary nutritionists, pet food formulation scientists, specialty retail category buyers, and cold-chain logistics operators combined with secondary validation from AAFCO model regulation documents, EU feed law implementations, and customs trade data. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Rate-of-change decomposition across product type, ingredient quality tier, distribution channel, and consumer archetype dimensions drove the analytical framework. CAGRs derived from segment-level volume and value build-ups reflecting pet humanization intensity, regulatory compliance cost trajectories, and cold-chain infrastructure penetration curves. Forecast inputs incorporated Brazilian middle-class expansion patterns, Japanese geriatric dog population demographics, and EU sustainable packaging mandate compliance timelines.
The model holds under stable regulatory enforcement and continued urban density growth; deviation in raw feeding restriction severity or alternative protein cost parity would shift trajectory. Forecasts reflect documented assumptions about veterinary telehealth adoption rates and fresh-format logistics scaling economics. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Organic Dog Food Market
Pet Care Products
Frozen Pet Food Market
Pet Care Products
USA Bird Food Market
Pet Care Products
United States Pet Care and Services Market
Pet Care Products
Vegan Pet Food Market
Pet Care Products
Asia Pacific Dog Food Market
Pet Care Products
US Pet Treats Market
Pet Care Products
Dog Biscuit Market
Pet Care Products
Asia-Pacific Pet Food Market
Pet Care Products
Pet Transport Cage Market
Pet Care Products
Europe Pet Diet Market
Pet Care Products
North America Pet Diet Market
Pet Care Products
Smart Pet Kennel Market
Pet Care Products
Cat Calming Treats Market
Pet Care Products
GCC Organic and Natural Pet Food Market
Pet Care Products
Natural Cat Litter Products Market