
 Dog Collars Market | 2026-2036
Dog Collars Market Size, Share, and Industry Trends Forecast 2026-2036
Dog Collars Market Analysis
Subscription-based GPS tracking and virtual fence services is rebalancing revenue models away from one-time hardware sales toward recurring monthly fees. Halo Collar leverages its proprietary boundary training software to anchor premium positioning in the smart collar segment. Ray Allen Manufacturing specializes in tactical and working dog equipment, sustaining defense and law enforcement contracts that insulate it from consumer cyclicality. Filson dominates heritage leather craftsmanship, occupying a price tier that competes on brand narrative rather than feature density.
A dog collar constitutes a wearable restraint and identification device, typically constructed from woven nylon webbing, tanned leather, or coated metal chain with tensile ratings suited to breed-specific pull forces, designed to secure, control, or locate canines across companion, working, and sporting applications. Nylon commands volume leadership due to its cost efficiency and dye compatibility, while leather concentrates margin pools in artisan and heritage segments where full-grain construction justifies price premiums. The Martingale type is gaining fastest among sighthound owners and trainers seeking escape-resistant designs without choke mechanisms, whereas reflective design elements are becoming baseline rather than differentiating as urban safety regulations tighten.
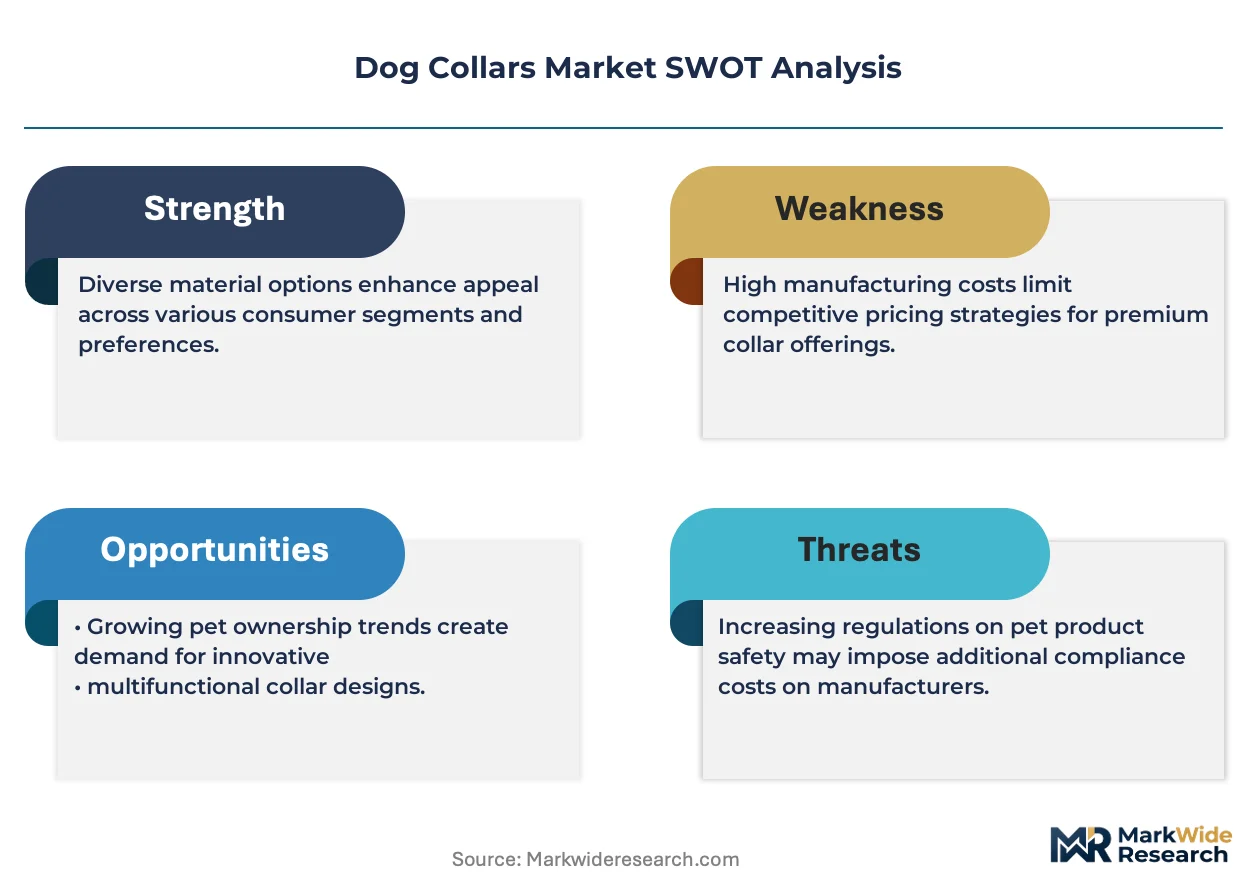
The Consumer Product Safety Commission and ASTM International shape material safety and hardware load standards in the United States, while the European Committee for Standardization governs pet accessory chemical compliance through REACH-aligned restrictions on dyes and coatings. These frameworks elevate compliance costs for import-dependent brands but simultaneously create market access barriers that protect domestic manufacturers with certified supply chains. Stakeholders must monitor whether emerging biometric sensor integration triggers medical device classification by the FDA, a development that would fundamentally alter approval timelines and liability structures for smart collar developers.
Market Dynamics
Smart collar technology with embedded biometric sensors and GPS tracking is compressing replacement cycles while elevating average selling prices, fundamentally restructuring revenue models from transactional hardware sales toward recurring software subscriptions.
Growth Catalysts
- Pet Humanization Trajectory:Millennial and Gen Z households now allocate discretionary spending toward premium companion accessories, expanding addressable wallet share for artisan leather and connected device categories.
- REACH-Aligned Chemical Standards:The European Committee for Standardization's tightened restrictions on dyes and coatings accelerate certified supply chain consolidation, advantaging domestic manufacturers with pre-compliant material sourcing.
- Biometric Sensor Miniaturization:Reduced component costs enable health monitoring features—heart rate variability, temperature tracking, activity patterns—at price points accessible to mass-market segments.
Market Restraints
- Tannery Supply Concentration:Full-grain leather sourcing depends on a limited base of North American and Italian vegetable-tanning facilities, exposing heritage brands to hide price volatility and queue delays.
- FDA Medical Device Ambiguity:Uncertainty around whether biometric smart collars trigger medical device classification creates regulatory overhang, freezing capital deployment for sensor-integrated product lines.
- Escape-Proof Fabric Substitution:High-tensile synthetic webbing and coated chain materials displace leather in working dog applications where failure tolerance approaches zero.
Strategic Opportunities
- Virtual Veterinary Integration:Smart collar data streams connect to telehealth platforms, creating subscription bundles that monetize preventive care alerts and remote consultation scheduling.
- Urban Safety Mandates:Municipal ordinances in dense metropolitan areas increasingly require reflective or illuminated collar elements, converting compliance costs into feature premiums.
- Working Dog Procurement Channels:Defense and law enforcement agencies maintain insulated budgets for tactical equipment, offering volume contracts with multi-year visibility distinct from consumer cyclicality.
Industry Challenges
- Embedded Firmware Talent Scarcity:Smart collar development requires rare combinations of low-power hardware engineering and cloud architecture expertise, inflating R&D payrolls and extending time-to-market.
- ASTM Load Testing Backlogs:Certification delays for tensile-rated hardware bottleneck product launches, particularly for Martingale and slip-chain designs targeting professional trainer segments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dog Collars Market |
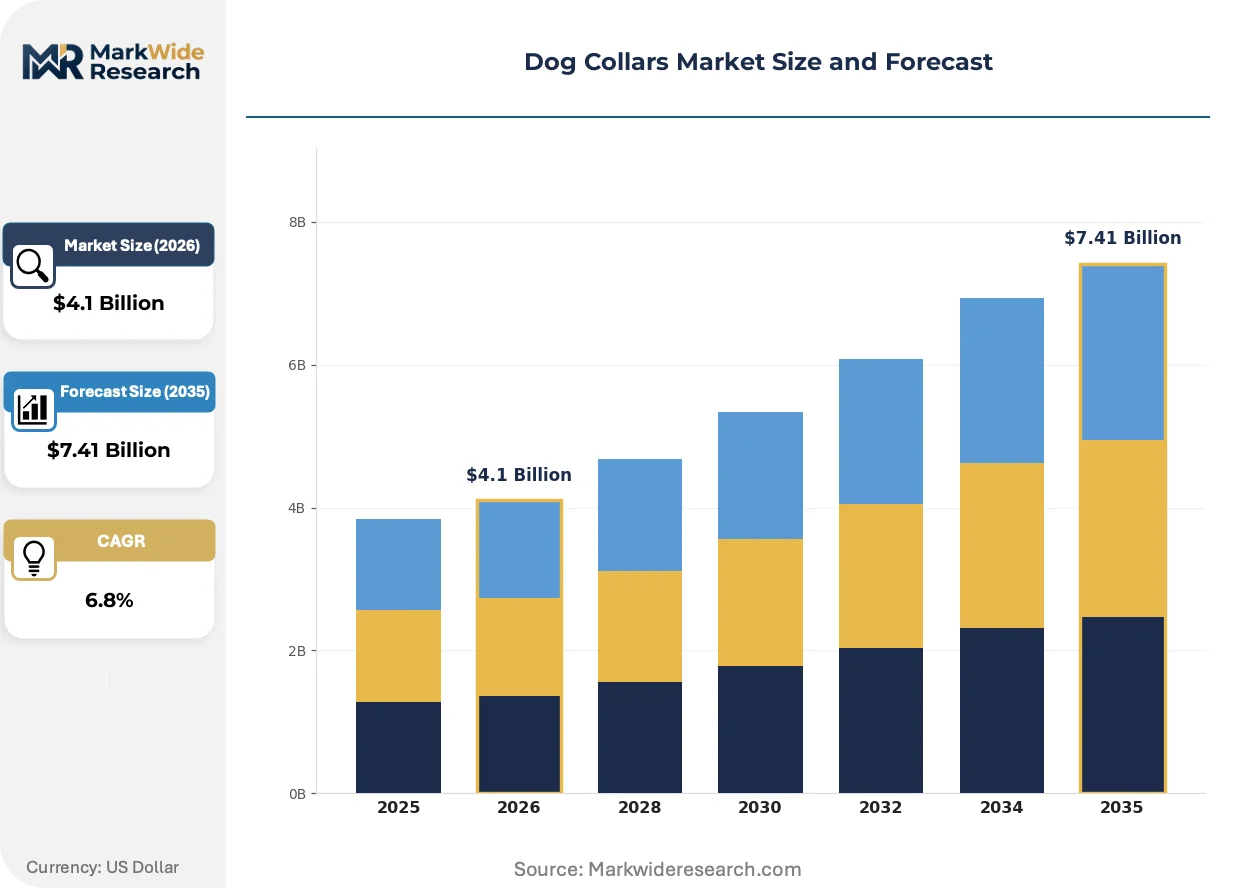
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Nylon, Leather, Metal, Polyester Type: Flat, Martingale, Harness, Headcollar Design: Reflective, Embroidered, Adjustable, Patterned Size: Small, Medium, Large, Extra Large |
| Companies Covered | Sitka, Carhartt, Ray Allen Manufacturing, Elite K-9, Halo Collar, Filson, Wolfgang GreatEscape, Viper, Orvis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dog Collars Market Emerging Trajectories
Sensor fusion and connectivity protocols are collapsing the boundary between identification accessories and health management platforms, forcing incumbents to rebuild competencies around data infrastructure and subscription retention.
Ultra-wideband (UWB) positioning chips are integrating with collar-embedded antennas to deliver centimeter-level location accuracy for virtual fence applications. Professional trainers and high-value breed owners adopt these systems fastest, replacing GPS-only units where boundary precision determines training efficacy. This capability compression is integrating hardware differentiation into software-defined boundary algorithms that vendors update over-the-air.
The Consumer Product Safety Commission's expanded jurisdiction over pet product chemical hazards is tightening phthalate and heavy metal testing protocols for imported nylon webbing and coated hardware. Domestic manufacturers with certified laboratory relationships capture shelf space as retailers demand documentation transparency. Small-batch importers without testing infrastructure face delisting pressure across mass-market channels.
Breed-specific sizing databases now power direct-to-consumer configuration tools, displacing generic small-medium-large taxonomies with neck circumference and coat density algorithms. Specialty retailers and veterinary clinics lose their fitting-table advantage as algorithmic recommendations achieve comparable accuracy. This channel compression concentrates most visible in urban markets where convenience preference overrides tactile evaluation.
Dog Collars Market Segmentation
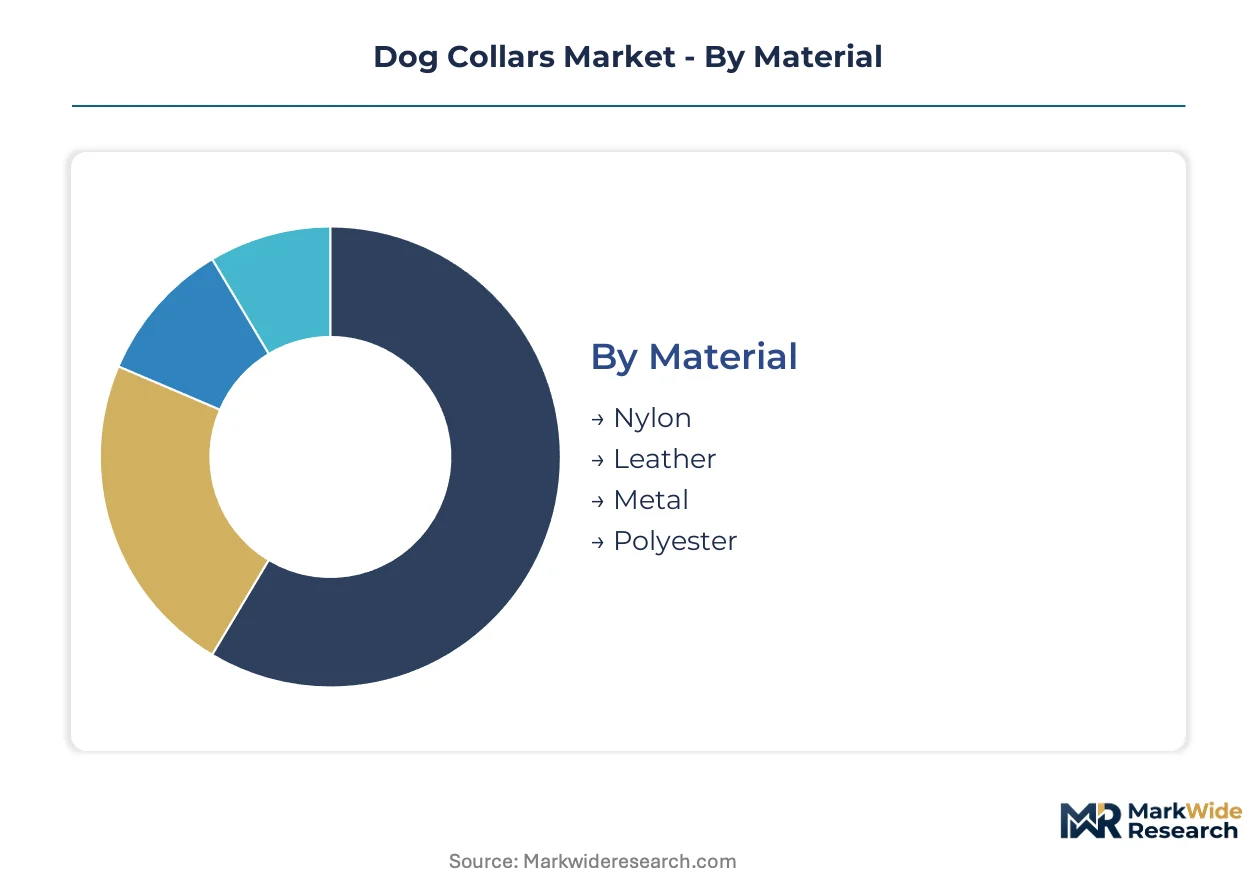
Dog collar purchasing decisions split sharply between functional utility and identity expression. Material choices dictate durability expectations and margin structures, while collar type selection reflects training philosophy and breed-specific control requirements.
Material:
Nylon dominates unit volume through cost efficiency and dye compatibility, while leather commands price premiums in artisan segments.
- Nylon:Woven polyamide webbing delivers tensile strength above 1,000 pounds with sub-ounce weight profiles. Mass-market retailers in the United States stock nylon SKUs most heavily, driven by replacement frequency and color refresh cycles.
- Leather:Full-grain vegetable-tanned hides from North American and Italian tanneries develop patina with age while maintaining structural integrity. Heritage brands concentrate margin pools here, competing on brand narrative rather than feature density.
- Metal:Coated steel chain links and slip collars serve working dog applications where failure tolerance approaches zero.
- Polyester:Recycled PET webbing addresses sustainability mandates in European markets with REACH-aligned chemical compliance.
Mature deployment sits with Nylon. Newer deployment is concentrated in Leather as pet humanization elevates accessory budgets.
Type:
Control mechanism selection reflects training methodology and escape-risk tolerance across companion and working applications.
- Flat:Standard buckle or snap-closure designs constitute the baseline category with lowest barrier to entry. Urban pet owners in dense metropolitan areas favor flat collars with integrated reflective elements as safety regulations tighten.
- Martingale:Limited-slip construction tightens under tension without choke mechanisms, making it essential for sighthound breeds with narrow heads. Professional trainers and Greyhound rescue networks drive fastest adoption here.
- Harness:Chest-attachment systems redirect pull force away from tracheal pressure for brachycephalic breeds.
- Headcollar:Gentle Leader-style designs leverage leverage points for reactive dog management in veterinary behavior programs.
Flat collar penetration peaks in mass retail channels. Martingale designs are climbing the fastest among specialty breeders and training professionals.
Design:
Visual differentiation and safety compliance now compete as primary purchase drivers rather than secondary considerations.
- Reflective:3M Scotchlite and similar retroreflective threads embed directly into webbing for 200+ meter visibility. Municipal ordinances in cities including New York and Los Angeles mandate reflective elements, converting compliance costs into feature premiums.
- Embroidered:Direct-to-webbing stitching replaces hanging tags for permanent identification, reducing noise and catch hazards. Custom embroidery services through veterinary clinics and specialty retailers capture personalization demand.
- Adjustable:Slide-lock or tri-glide hardware accommodates growth stages in large-breed puppies.
- Patterned:Sublimation printing enables photographic detail and seasonal designs for fashion-forward segments.
Reflective deployment is standardizing fastest. Patterned designs are expanding most quickly through direct-to-consumer channels with algorithmic customization tools.
Size:
Neck circumference and coat density algorithms now displace generic taxonomies in configuration tools.
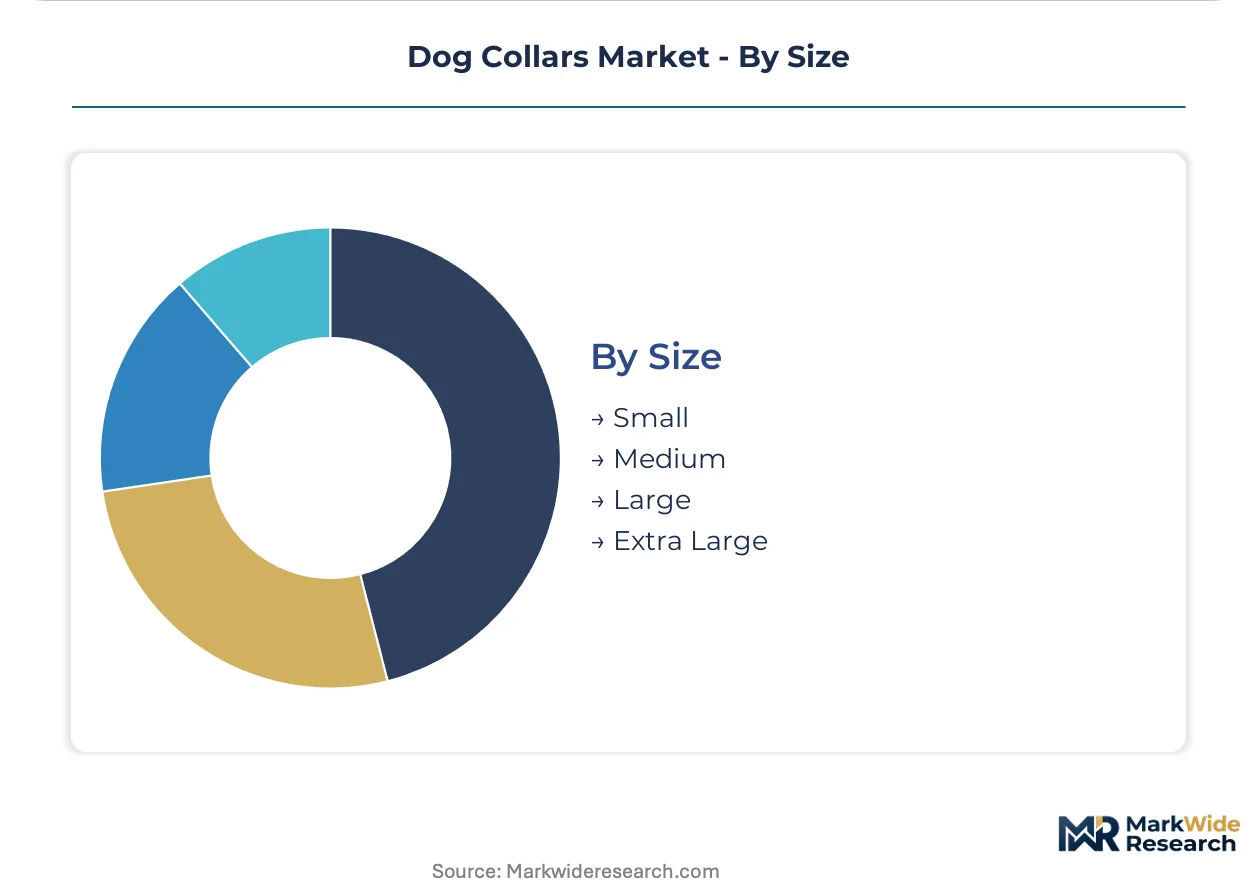
- Small:8-12 inch neck circumference targeting toy breeds and puppies under 15 pounds. Urban apartment dwellers in high-density housing stock concentrate demand here.
- Medium:12-18 inch range covering the majority of companion breeds including Labradors and Golden Retrievers.
- Large:18-26 inch specifications for working breeds and giant breeds with significant pull forces.
- Extra Large:26+ inch custom sizing for Mastiffs, Great Danes, and specialized working dog applications.
Medium sizing anchors volume production. Extra Large represents the steepest expansion trajectory as giant breed ownership climbs and working dog procurement channels demand specialized fit.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denver anchors North American smart collar development, with venture-backed startups clustering around veterinary research institutions and outdoor recreation infrastructure.
United States
Millennial household formation and premium pet accessory spending concentrate in Austin, Seattle, and Brooklyn. The Consumer Product Safety Commission enforces phthalate and heavy metal testing protocols for imported nylon webbing. Raleigh-Durham hosts veterinary telehealth platforms integrating collar biometric data streams.
Germany
REACH-aligned chemical compliance mandates reshape sourcing for dyed webbing and coated hardware. ECHA restrictions on azo dyes and chromium VI in leather tanning elevate certification costs for import-dependent distributors. Munich specialty retailers leverage full-grain vegetable-tanned construction from Italian supply chains.
United Kingdom
Post-pandemic pet acquisition rates elevated collar replacement frequency in Greater London and Manchester. The Office for Product Safety and Standards governs load-bearing hardware standards under the General Product Safety Regulations. Cotswolds-based artisans compete on heritage craftsmanship narratives.
Japan
Compact urban housing and small-breed ownership drive demand for lightweight, escape-resistant designs in Tokyo and Osaka. METI oversees product safety standards for pet accessories under the Consumer Product Safety Act. Nagoya industrial clusters supply precision-machined hardware for Martingale mechanisms.
Australia
Working dog procurement for livestock management sustains volume demand in Queensland and New South Wales. The ACCC enforces mandatory safety standards for pet restraints under the Consumer Goods (Pet Supplies) Safety Standard 2020. Melbourne direct-to-consumer brands deploy algorithmic sizing tools displacing veterinary fitting-table advantages.
Dog Collars Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across material fabrication and connected device development. The vendor base fragments between heritage leather workshops, tactical equipment fabricators, and venture-funded smart collar platforms. Three strategic archetypes dominate: artisan heritage brands competing on narrative density, defense contractors insulated from consumer cyclicality, and subscription-first hardware platforms monetizing recurring software fees. Dominant competitive moves include strategic partnerships with veterinary telehealth networks and geographic expansion through algorithmic direct-to-consumer configuration tools.
Within the tactical equipment tier, Ray Allen Manufacturing and Elite K-9 occupy positions serving defense and law enforcement procurement channels with multi-year contract visibility. Among heritage-focused platforms, Filson anchors artisan leather positioning competing on brand narrative rather than feature density. Halo Collar exemplifies the subscription-first archetype, leveraging proprietary boundary training software to capture recurring revenue streams beyond one-time hardware transactions.
| Leading Market Players |
|---|
| Sitka |
| Carhartt |
| Ray Allen Manufacturing |
| Elite K-9 |
| Halo Collar |
| Filson |
| Wolfgang GreatEscape |
| Viper |
| Orvis |
| Others |
Supply Flow & Price Mechanics
North American hide price indices cascade through vegetable-tanning queue delays into artisan leather tier premiums, while REACH-aligned chemical testing costs compress mass-market nylon margins. This bifurcation concentrates pricing power with certified domestic manufacturers holding pre-compliant supply chains.
Pricing Analysis
Margin tightening in heritage leather tiers reflects hide price volatility and Italian tannery queue delays. Three-tier pricing structure across premium, standard, and economy levels separates full-grain vegetable-tanned construction from chrome-tanned alternatives and synthetic webbing. Pricing pressure accelerates in mass-market nylon as CPSC testing mandates elevate import compliance costs. Small-breed urban owners exhibit highest price sensitivity, while working dog procurement channels show lowest elasticity due to failure-risk tolerance requirements.
Supply Chain Analysis
Full-grain leather supply rests on North American and Italian vegetable-tanning facilities with limited hide processing capacity. Component dependencies span precision-machined Martingale hardware from Nagoya industrial clusters, 3M Scotchlite retroreflective threads, and GPS-enabled biometric sensors. Single-source vulnerability concentrates in tannery consolidation and semiconductor chip allocation for smart collar platforms. Distribution runs through mass-market retailers, veterinary clinic channels, and direct-to-consumer algorithmic configuration tools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Full-grain hide availability constraints and tannery queue delays prop artisan leather pricing, creating supply-constrained conditions favoring certified domestic manufacturers.
For Market Incumbents: Acquire certified laboratory relationships and pre-compliant material sourcing contracts. Biometric sensor miniaturization threats from venture-funded platforms demand firmware talent acquisition and veterinary telehealth partnership anchoring. ASTM load testing certification investment secures professional trainer segment shelf space against import-dependent challengers. For New Entrants and Emerging Players: CPSC expanded jurisdiction over pet product chemical hazards opens a window for domestic manufacturers with testing infrastructure. White-space targets concentrate in giant breed custom sizing and defense procurement channels. Go-to-market leverage algorithmic direct-to-consumer configuration tools displacing specialty retailer fitting-table advantages. For Investors and Strategic Acquirers: Distressed-cycle entries favor heritage leather workshops with certified Italian supply chain relationships in the United States. Long-term viability frames around subscription-first smart collar platforms with recurring software revenue anchoring hardware margins. Watch FDA medical device classification ambiguity resolution as inflection signal for sensor-integrated product line capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Telehealth Partnership | Halo Collar's proprietary boundary software integrates with Raleigh-Durham platforms for preventive care monetization. |
| Certified Supply Chain Acquisition | Domestic manufacturers with REACH-aligned sourcing capture shelf space as retailers demand documentation transparency. |
| Algorithmic Direct-to-Consumer Launch | Breed-specific sizing databases displace generic taxonomies and veterinary fitting-table channel advantages. |
| Defense Procurement Channel Entry | Ray Allen Manufacturing's multi-year contract visibility offers insulation from consumer cyclicality. |
| Biometric Sensor Integration | Health monitoring features at mass-market price points compress replacement cycles and elevate average selling prices. |
Methodological Framework
Independent corroboration across primary interviews with veterinary behaviorists, specialty retailer buyers, and working dog procurement officers, alongside secondary validation through CPSC enforcement records, ASTM International standards documentation, and customs import data, underwrites the qualitative findings. Bottom-up unit economics triangulate against top-down market sizing across material, type, design, and size segmentation dimensions.
Comparable-period anchoring to historical replacement frequency and premium accessory spending patterns structures the projection horizon. Modeled segmentation spans nylon, leather, metal, and polyester materials; flat, Martingale, harness, and headcollar types; and small through extra-large size tiers. CAGRs derive from pet humanization trajectory analysis and smart collar subscription attach rate assumptions, with biometric sensor cost curves and tannery capacity utilization as industry-specific inputs.
Caveats apply where FDA medical device reclassification or ECHA chemical restriction expansion could materially shift the outlook. Forecasts embed assumptions around millennial household formation rates and REACH compliance cost trajectories. A small set of regulatory triggers and raw material price volatility indicators warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pet Care Products
Outdoor Dog Bed Market
Pet Care Products
Pet Cups Market
Pet Care Products
Dehydrated Pet Food Market
Pet Care Products
Dry Pet Food Market
Pet Care Products
Pet Furniture Market
Pet Care Products
Therapeutic Diet for Pet Market
Pet Care Products
Dog Pad Market
Pet Care Products
Dog Litter Boxes Market
Pet Care Products
Cat Massage Comb Market
Pet Care Products
Dog Float Market
Pet Care Products
Dog Bed Covers Market
Pet Care Products
Cat Calming Treats Market
Pet Care Products
Natural Pet Food Market
Pet Care Products
Dog Hoodies Market
Pet Care Products
Cat Shampoo Market
Pet Care Products
North America Pet Food Nutraceuticals Market