
 Food Service Disposables Market | 2026-2036
Food Service Disposables Market Size, Share, and Industry Trends Forecast 2026-2036
Food Service Disposables Market Intelligence
The expansion of fast food chains is recalibrating the demand profile for food service disposables, favoring products that support speed and convenience. Dart Container Corporation leverages its extensive manufacturing scale in foam and plastic products to serve this high-volume segment. Huhtamaki Oyj differentiates through its focus on fiber-based and compostable packaging alternatives. Berry Global Inc. competes with a diverse portfolio spanning multiple material types to meet varied customer requirements across the food service industry.
Food service disposables are single-use products designed for preparing, serving, or consuming food and beverages, primarily to ensure hygiene and convenience. These items are typically made from materials like paper, plastic, or biodegradable polymers such as PLA. Within the product landscape, cups and cutlery constitute major high-volume categories. The material segment is defined by a pronounced shift away from conventional plastics towards paper and biodegradable alternatives, driven by both consumer preference and regulatory pressure.
Regulatory frameworks are a primary market force, with the EU's Single-Use Plastics Directive banning certain items and the US FDA setting stringent standards for food-contact materials. In China, GB standards dictate material safety and performance for disposable products. Navigating these varied international regulations while balancing material performance, cost, and sustainability commitments remains the central challenge for manufacturers and buyers.
Market Dynamics
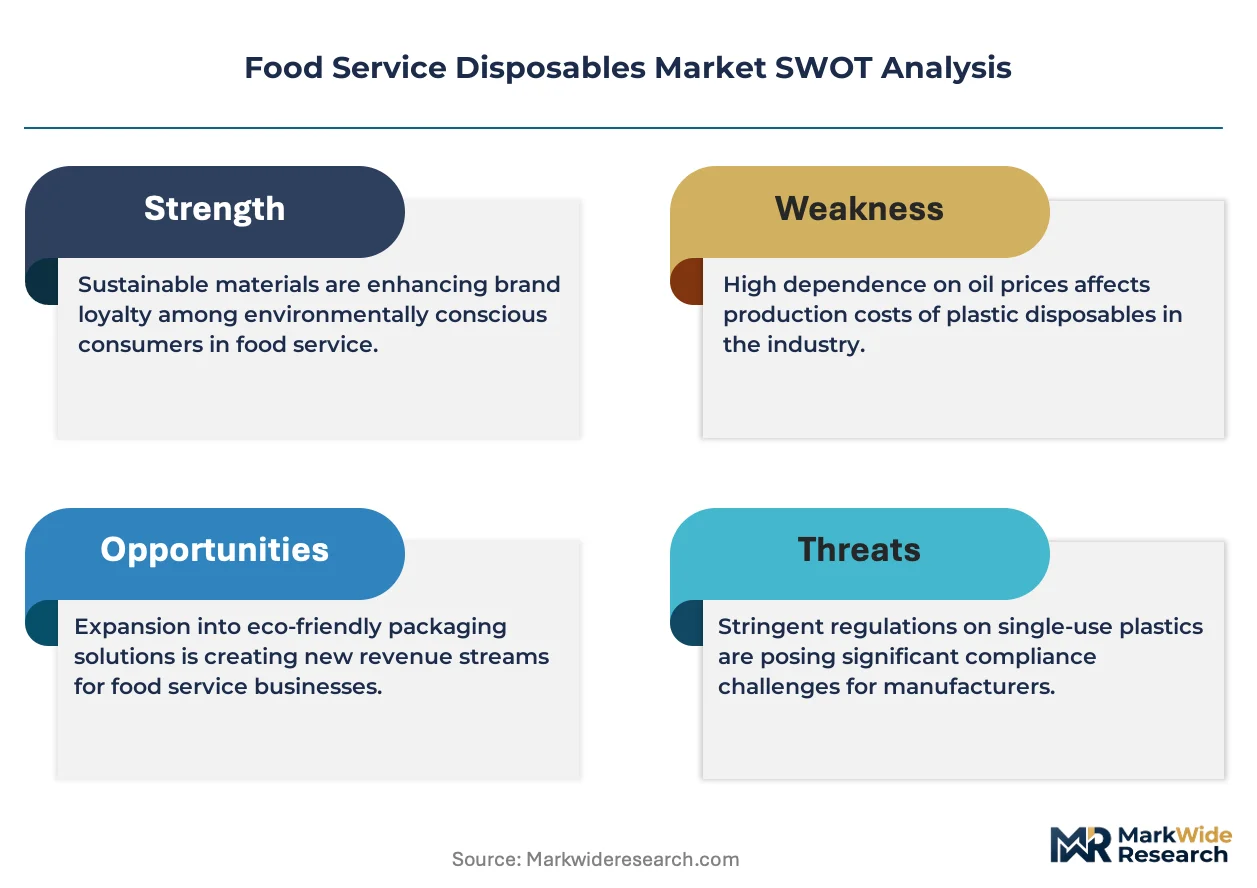
The central structural force shaping the market is the global regulatory clampdown on single-use plastics. This pressure, exemplified by the EU's directives, is compelling a fundamental and rapid realignment of material science, supply chains, and product design toward sustainable alternatives.
Growth Catalysts
- Urbanization in Emerging Economies:Rapid urbanization and the expansion of online food delivery services in countries like India are creating new, high-volume demand pools for convenient, single-use packaging solutions.
- Regulatory Mandates for Sustainability:The European Union's Single-Use Plastics Directive acts as a powerful catalyst, forcing the substitution of banned plastic items with alternatives made from paper, wood, or biodegradable polymers.
- QSR Expansion:The continued global growth of quick service restaurant (QSR) chains requires a consistent and scalable supply of disposables that prioritize speed, hygiene, and portability for on-the-go consumption models.
Market Restraints
- Higher Input Costs for Alternatives:The cost of raw materials for biodegradable polymers like PLA and PHA remains significantly higher than for conventional petroleum-based plastics, creating a price barrier for widespread adoption.
- Performance Gaps in Sustainable Materials:Certain paper and fiber-based products exhibit limitations in grease and moisture resistance compared to their plastic counterparts, restricting their use in some demanding food service applications.
- Inadequate Waste Infrastructure:A lack of widespread commercial composting facilities in many regions, including parts of North America, undermines the end-of-life benefits of compostable products, limiting their circular value proposition.
Strategic Opportunities
- Development of Barrier Coatings:Creating novel, bio-based, and compostable barrier coatings for paper and board products presents a significant opportunity to overcome performance limitations and displace plastic-lined packaging.
- Ghost Kitchen and Meal Kit Packaging:The rise of delivery-only ghost kitchens and meal kit services creates a new market for specialized, multi-compartment disposable packaging designed for transport and portion control.
- Smart Packaging Integration:Incorporating QR codes or NFC tags into disposable packaging offers opportunities for enhanced consumer engagement, traceability, and transparent communication of disposal instructions and sustainability metrics.
Industry Challenges
- Navigating Regulatory Fragmentation:Manufacturers face significant operational complexity in ensuring products comply with a patchwork of disparate international standards, such as the EU's SUPD, the US FDA's food-contact regulations, and China's GB standards.
- Capital-Intensive Production Shifts:Transitioning manufacturing capacity from traditional plastic extrusion and thermoforming to molded fiber or biopolymer processing requires substantial capital expenditure for retooling and new equipment.
- Standardization of "Compostable" Claims:A lack of harmonized global definitions and certifications for biodegradability and compostability leads to consumer confusion and greenwashing concerns, challenging brand credibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Service Disposables Market |
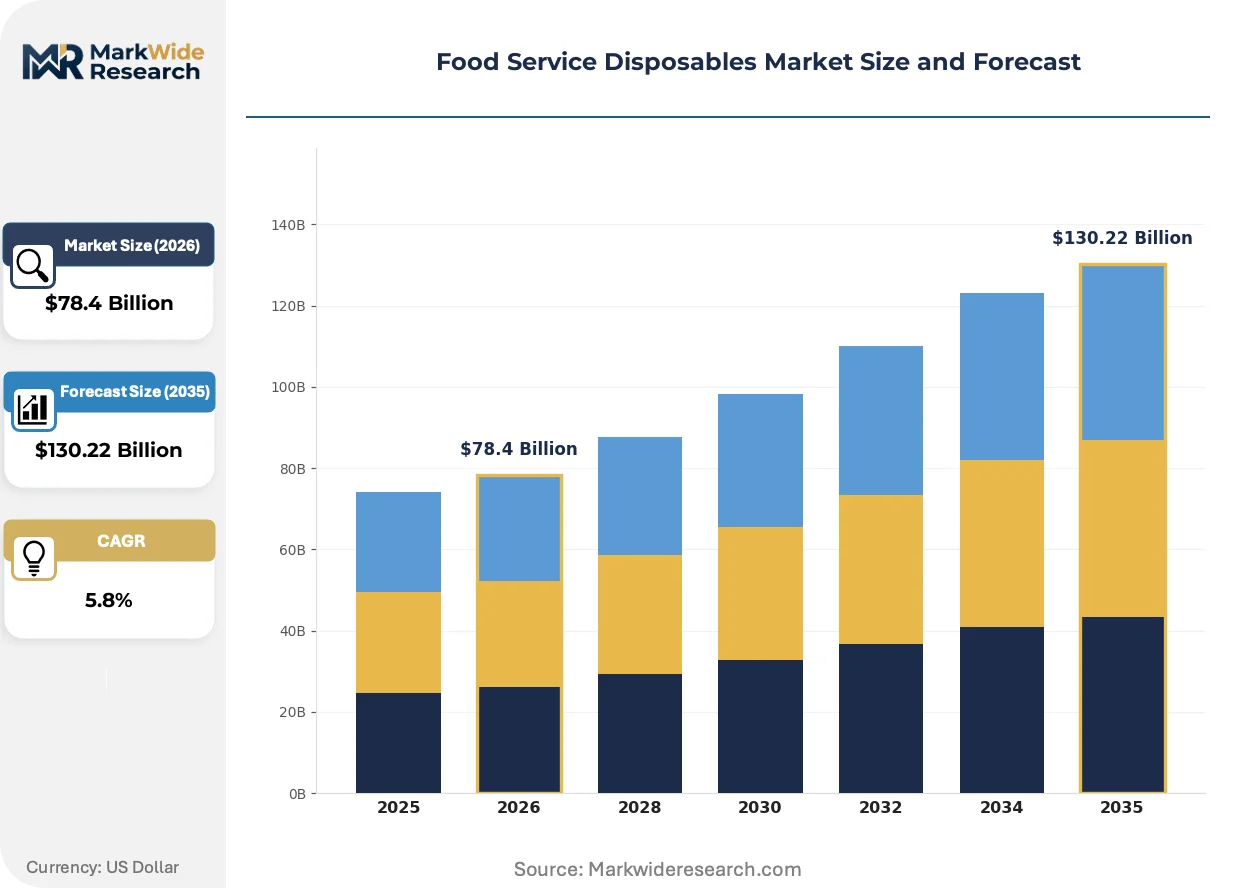
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $130.22 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plates, Cups, Cutlery, Tablecovers Material: Plastic, Paper, Biodegradable, Foam End User: Restaurants, Cafes, Fast Food Chains, Catering Services Packaging Type: Bulk Packaging, Retail Packaging, Custom Packaging, Single Use |
| Companies Covered | Dart Container Corporation, Berry Global Inc., Huhtamaki Oyj, Georgia-Pacific LLC, Pactiv LLC, Graphic Packaging International LLC, Sonoco Products Company, Sabert Corp., Genpak LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Service Disposables Market Strategic Shifts & Innovations
Material science innovation is at the forefront of market evolution, directly responding to a combination of regulatory mandates and consumer-driven pressure for environmental responsibility. This is forcing a rapid pivot from conventional polymers to functional, sustainable, and circular material solutions.
Advanced molded fiber technology produces rigid, three-dimensional packaging from pulp sources like wood or bagasse. Quick service restaurants and institutional food service providers are adopting these materials for items such as clamshells, bowls, and plates. This movement toward high-performance, plastic-free alternatives is consolidating market share away from expanded polystyrene (EPS) and other conventional plastics in the container segment.
The EU's Single-Use Plastics Directive establishes clear market restrictions on items like plastic cutlery, straws, and stirrers, compelling an industry-wide material substitution. Its implementation has an immediate effect on supply chain sourcing, creating a surge in demand for compliant alternatives across the continent. The cutlery and beverage accessory categories are most directly impacted, with producers shifting to wood, paper, and PLA-based products to retain access to the European market.
Corporate environmental, social, and governance (ESG) commitments are now a primary factor in sourcing decisions for large-scale buyers. This changes purchasing dynamics away from a singular focus on unit cost, creating a preference for suppliers who can provide certified compostable products or document a lower carbon footprint. This trend is most visible in North America and Western Europe, where major hospitality and fast-food brands link their public sustainability goals to procurement practices.
Food Service Disposables Market Segmentation
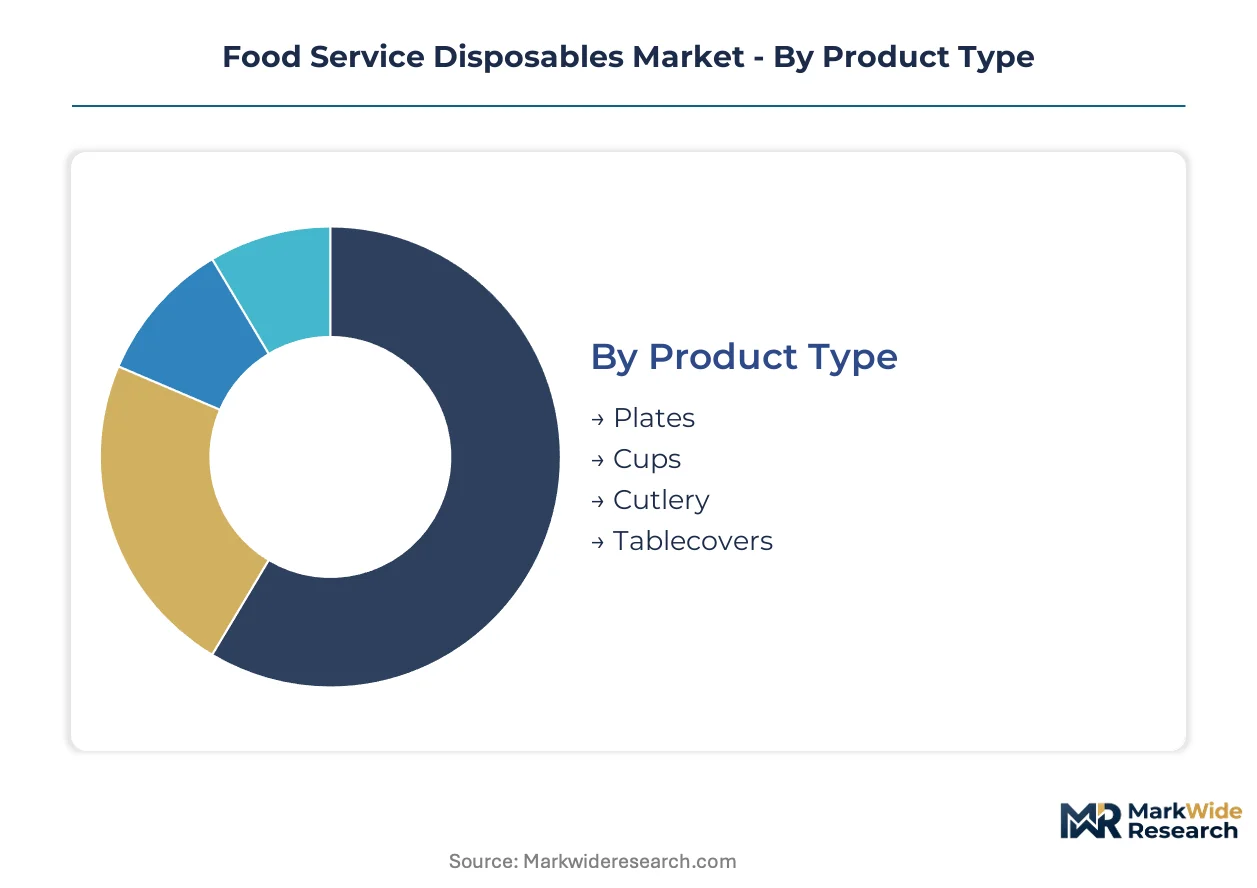
The food service disposables market is disaggregated into distinct categories, reflecting the diverse operational needs of the hospitality sector and the evolving landscape of material science. Understanding these segmentations is critical for manufacturers to align product development with specific demand profiles and regulatory pressures.
Product Type:
The capital intensity across product types varies significantly, with manufacturing infrastructure for certain items demanding substantial upfront investment in specialized molding and forming equipment.
- Cups:These items are primarily used for beverages, encompassing hot and cold applications, and are manufactured from paper, plastic, or bioplastics. Demand for paper cups is concentrating in Europe due to the EU's Single-Use Plastics Directive, driving material substitution from conventional plastics.
- Cutlery:This category includes forks, spoons, and knives, often produced from wood, CPLA (crystallized polylactic acid), or other biodegradable polymers. Quick service restaurants are a primary consumer, requiring durable yet disposable options for on-the-go meals.
- Plates:Plates are flat or shallow containers for serving solid food, typically made from paperboard, molded fiber, or plastic.
- Tablecovers:These are disposable coverings for tables, primarily used in catering and event settings to ensure hygiene and ease of cleanup.
Cups absorb the bulk of installed capacity; Cutlery is expanding most quickly.
Material:
Material segmentation reflects distinct cost tiers, directly influencing procurement decisions and end-product pricing strategies.
- Paper:Products manufactured from paperboard or pulp, often coated for moisture and grease resistance, are widely adopted across food service applications. Urbanization in countries like India is fueling demand for paper-based packaging due to its cost-effectiveness and perceived environmental benefits.
- Biodegradable:This segment includes items made from bioplastics like PLA (polylactic acid), PHA (polyhydroxyalkanoates), or other compostable polymers. Regulatory mandates for sustainability, particularly in the European Union, are accelerating the shift towards these alternatives.
- Plastic:Conventional plastic disposables, such as polypropylene and PET, offer high durability and cost efficiency.
- Foam:Expanded polystyrene (EPS) foam products provide excellent insulation and are lightweight, but face significant regulatory restrictions in many regions.
Demand for paper-based disposables is concentrating in regions with stringent plastic bans, while biodegradable options are gaining traction among environmentally conscious brands.
End User:
End-user segments are differentiated by their consumption volumes, with large-scale operators dictating production economies and supply chain configurations.
- Fast Food Chains:These establishments require high volumes of standardized, cost-effective disposables that support rapid service and on-the-go consumption. Global expansion of quick service restaurant brands drives consistent demand for hygienic and portable packaging solutions.
- Restaurants:This segment includes full-service and casual dining establishments that utilize disposables for takeout, delivery, and some in-house serving needs. Corporate ESG commitments are influencing restaurant procurement towards certified compostable products.
- Cafes:Cafes primarily use disposable cups, lids, and sleeves for hot and cold beverages.
- Catering Services:Catering operations demand a versatile range of disposables for events, often prioritizing aesthetics and ease of transport.
Fast Food Chains face the most immediate regulatory scrutiny regarding single-use plastics, driving their rapid shift towards compliant materials, while catering services adapt to diverse client sustainability mandates.
Packaging Type:
Packaging type distinctions are driven by specific application requirements, ranging from high-volume industrial supply to consumer-facing retail solutions.
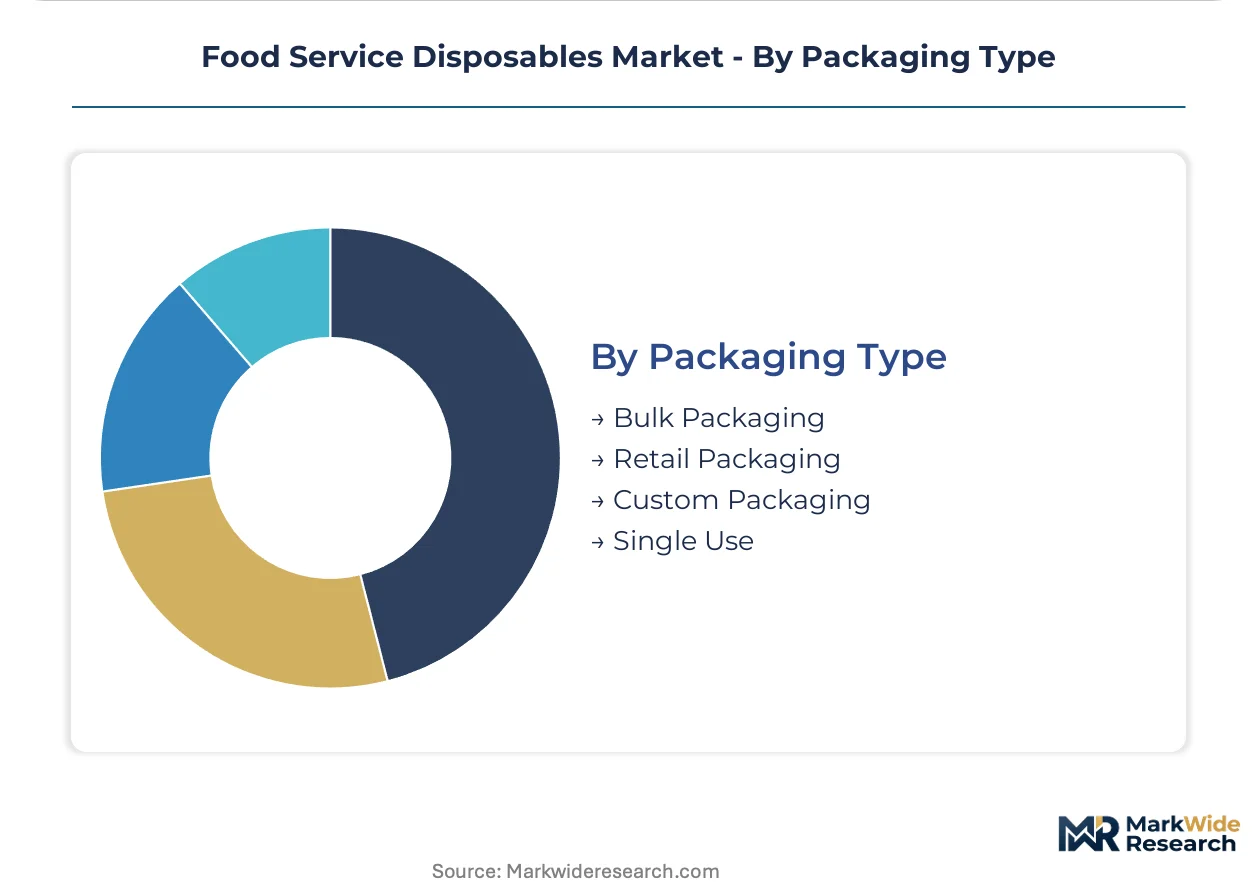
- Single Use:These disposables are designed for one-time consumption, emphasizing hygiene and convenience across all food service applications. The EU's Single-Use Plastics Directive has significantly impacted the material composition of these products across Europe.
- Custom Packaging:Tailored packaging solutions are designed to meet specific brand requirements, often incorporating unique designs, branding, or multi-compartment structures. The rise of ghost kitchens creates a market for specialized, branded custom packaging for food delivery.
- Bulk Packaging:Large quantities of disposables are supplied in bulk to high-volume end-users like institutional food service providers.
- Retail Packaging:Disposables are packaged for direct sale to consumers, typically found in supermarkets or convenience stores for home use.
Innovation in single-use packaging focuses on material science for performance improvements, whereas custom packaging drives advancements in design and functionality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The food service disposables market exhibits a clear divide between regions driving large-scale production and those primarily characterized by high consumption. Demand centers in urbanized economies propel innovation in material science and product design. Manufacturers strategically position facilities to serve these diverse consumption patterns.
United States
Demand from quick service restaurants and the growing meal delivery sector drives significant consumption. The US FDA sets stringent standards for food-contact materials, influencing product development and safety protocols. California and New York City are at the forefront of implementing local bans on certain single-use plastic items.
Germany
European demand for sustainable disposables is accelerating due to robust regulatory pressures. The EU's Single-Use Plastics Directive has banned several items, compelling a shift towards fiber-based alternatives. Industrial clusters in North Rhine-Westphalia are adapting production lines to meet the new material requirements.
India
Urbanization and the rapid expansion of online food delivery platforms create substantial demand for convenient packaging solutions. FSSAI regulations govern food safety and packaging standards for all food service products. Major metropolitan areas like Mumbai and Delhi are experiencing high growth in disposable usage.
China
High-volume consumption from fast food chains and a burgeoning takeaway culture fuel the market. GB standards dictate material safety and performance for disposable food contact articles. Manufacturing hubs in the Yangtze River Delta are innovating to produce compliant and cost-effective alternatives.
Brazil
The expanding QSR segment and increasing consumer preference for convenience drive demand for single-use items. ANVISA regulations ensure the safety and quality of food packaging materials used across the country. São Paulo, as a major economic hub, sees significant activity in food service disposable procurement.
Food Service Disposables Market Key Industry Players
Top-tier vendors anchor the global food service disposables market, while a multitude of regional and specialized players address niche segments. The market structure favors companies capable of large-scale manufacturing and those specializing in sustainable material innovation. Strategic archetypes include diversified material producers, biopolymer specialists, and integrated packaging providers. Competitive moves center on capacity expansion in sustainable materials and strategic partnerships for distribution.
At the scale-driven end, Dart Container Corporation exemplifies a major player leveraging extensive manufacturing infrastructure for high-volume foam and plastic products. Huhtamaki Oyj represents a key innovator, focusing on fiber-based and compostable packaging alternatives to meet evolving regulatory demands. Berry Global Inc. occupies a diversified position, offering a broad portfolio across multiple material types to cater to varied customer requirements within the food service industry.
| Leading Market Players |
|---|
| Dart Container Corporation |
| Berry Global Inc. |
| Huhtamaki Oyj |
| Georgia-Pacific LLC |
| Pactiv LLC |
| Graphic Packaging International LLC |
| Sonoco Products Company |
| Sabert Corp. |
| Genpak LLC |
| Others |
Cost & Logistics Intelligence
Advanced molded fiber technology's proliferation simultaneously reshapes cost economics for disposables and concentrates supply for sustainable alternatives. This transition demands significant capital investment for new production lines, impacting overall cost structures and favoring manufacturers with scale.
Pricing Analysis
Lead-time-driven pricing offers premiums for immediate availability of compliant materials, while commodity spot markets dictate lower prices for conventional plastics. Pricing structures are predominantly contract-based long-term offtakes for large fast food chains, with smaller businesses relying on transactional purchases. Price differentiation stems from volume scale, certified compostable materials, and customization for specialized packaging. Pricing softness in basic plastic alternatives reflects oversupply, but higher input costs for biopolymers like PLA create upward pressure on sustainable options. Fast food chains remain highly price-sensitive for high-volume items, while catering services prioritize aesthetics and performance, exhibiting less sensitivity.
Supply Chain Analysis
Certification and qualification gating heavily influence supply chain entry and material selection, particularly in regions with stringent regulations like the EU. Geographic supply concentrates in China and India for high-volume paper and plastic production, alongside specialized biopolymer manufacturing in Germany. Raw material dependencies center on wood pulp for paper products, biopolymer resins such as PLA and PHA, and petroleum-based plastics. Regulatory restriction, exemplified by the EU's Single-Use Plastics Directive, poses a significant structural risk for non-compliant materials. Distribution runs through direct sales channels for major QSRs and wholesale distributors serving smaller restaurants and cafes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The food service disposables market is a consolidation play, as escalating regulatory pressure on single-use plastics forces smaller, less adaptable players to exit or be acquired.
For Market Incumbents: To counter the global regulatory clampdown on single-use plastics, incumbents must accelerate capital-intensive retooling for molded fiber and biopolymer processing. Strategic partnerships with material science firms are crucial for securing access to novel barrier coatings and sustainable resins. Investment in R&D for performance-enhanced biodegradable materials will differentiate offerings and meet evolving buyer ESG commitments. Certifying products with globally recognized compostability standards builds trust and market access.
For New Entrants and Emerging Players: Ghost kitchens and meal kit services represent an underserved buyer archetype seeking specialized, multi-compartment disposable packaging. New entrants can target these tech-enabled food delivery platforms with innovative designs emphasizing transport stability, portion control, and material sustainability. Incorporating smart packaging features like QR codes for traceability and disposal instructions offers a compelling go-to-market angle. Focusing on niche applications where performance gaps in sustainable materials persist creates differentiation.
For Investors and Strategic Acquirers: Exit pathways concentrate in biopolymer specialists and advanced molded fiber technology providers poised for rapid scaling. The long-term viability of this market hinges on continued regulatory enforcement and consumer demand for circular economy solutions. Acquisition targets should possess proprietary material science, established manufacturing capacity for sustainable alternatives, or strong distribution networks in high-growth emerging economies. Widespread commercial composting infrastructure development is a critical signal to watch as an inflection indicator for compostable product adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Molded Fiber | Addresses rapidly growing demand for plastic-free alternatives in key product categories. |
| Bio-based Barrier Coating R&D | Overcomes performance limitations of paper, enabling broader displacement of plastic-lined packaging. |
| Strategic Partnerships with Biopolymer Producers | Secures stable supply chains for innovative and compliant sustainable raw materials. |
| Investment in Commercial Composting Infrastructure | Enhances the circular value proposition and end-of-life benefits of compostable products. |
| Digital Integration for Traceability and Consumer Engagement | Builds brand trust and transparency regarding product sustainability and proper disposal. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study, complemented by primary interviews with industry stakeholders. This approach combined insights from procurement managers at QSRs, material scientists, packaging engineers, and sustainability officers. Publicly available documents like EU directives, US FDA standards, and FSSAI regulations provided crucial context and validation for market trends. The methodology ensured a robust bottom-up and top-down triangulation of market data.
Data-stream reconciliation integrated diverse information to construct a comprehensive analytical framework across the analysis window. This framework modeled segmentation dimensions including product type, material, end-user, packaging type, and regional regulatory stringency. Compound annual growth rates were derived from a blend of historical performance analysis and projected market shifts influenced by material innovation. Key forecast inputs included raw material price volatility and the timelines for new material development.
Revisions become necessary when unforeseen regulatory changes or rapid material science breakthroughs materialize, impacting market dynamics. Forecasts reflect assumptions documented at the time of analysis, acknowledging inherent uncertainties. A model refresh is warranted upon material change in global waste management infrastructure or consumer preference shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Global Online Food Delivery Services Market
Food Service
GCC Online Grocery Market
Food Service
Inflight Catering Market
Food Service
United States Food Truck Market
Food Service
Food & Beverage in Asia Market
Food Service
Global Dark Store Market
Food Service
Europe Food Cold Chain Logistics Market
Food Service
Vietnam Food Service Market
Food Service
Restaurant Takeout Market
Food Service
North America Online Food Delivery Market
Food Service
Commercial Bar Supplies Market
Food Service
Europe Pizza Oven Market
Food Service
Middle East and Africa Online Grocery Delivery Market
Food Service
Undercounter Ice Makers Market
Food Service
Smart Food Logistics Market
Food Service
China Retail Bubble Tea Kits Market