
 Europe Food Cold Chain Logistics Market | 2026-2036
Europe Food Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Food Cold Chain Logistics Market Insights
Ready-to-eat meal distribution is expanding across European foodservice channels, pulling refrigerated transport capacity toward urban last-mile networks. DHL Supply Chain leverages its pan-European warehouse footprint to anchor temperature-controlled fulfillment for retail clients. STEF SA sustains dominant coverage across France and Southern Europe through specialized meat and seafood logistics infrastructure. NewCold Advanced Cold Logistics differentiates via automated high-bay frozen storage facilities that compress energy intensity per pallet position.
Food cold chain logistics encompasses the temperature-managed movement and storage of perishable food products from origin through consumption, maintaining precise thermal bands typically between minus 25 degrees Celsius and plus 8 degrees Celsius to arrest microbial proliferation and preserve nutritional integrity. The refrigerated segment leads service type deployment as dairy and fresh protein shippers prioritize uninterrupted cooling across multimodal handoffs. Frozen warehousing commands premium margin pools due to capital-intensive automation and energy hedging requirements. Meat and seafood product types concentrate demand in port-adjacent cold stores serving import-dependent European markets.
The EU F-Gas Regulation and ECHA REACH framework shape refrigerant selection and equipment replacement cycles across the European cold chain fleet. CE marking under the EU Green Deal accelerates demand for low-emission transport refrigeration units. Stakeholders must monitor refrigerant phase-down timelines and energy border adjustment mechanisms to calibrate fleet investment and warehouse location decisions.
Market Dynamics
The EU F-Gas Regulation is forcing fleet-wide refrigerant transitions across European cold chain operators, compressing equipment replacement cycles and redistributing capital toward low-emission transport refrigeration units.
Growth Catalysts
- EU Green Deal CE marking mandates:The accelerated CE marking requirements under the EU Green Deal are pulling investment into electrified transport refrigeration. Fleet operators in Germany and France are prioritizing compliant equipment to maintain cross-border operating licenses.
- Restaurant and foodservice channel expansion:Ready-to-eat meal distribution is expanding across European foodservice channels, pulling refrigerated transport capacity toward urban last-mile networks. This segment demands precise temperature bands between 0 and 4 degrees Celsius for prepared proteins.
- Port-adjacent cold store concentration:Rotterdam and Hamburg port complexes are anchoring import-dependent meat and seafood flows, creating demand for automated high-bay frozen storage facilities that compress dwell times for containerized perishables.
Market Restraints
- Refrigerant input cost volatility:Hydrofluorocarbon phase-down schedules under the EU F-Gas Regulation are creating supply squeezes for legacy refrigerants. Operators face stranded asset risk on equipment with residual cooling capacity but non-compliant chemistry.
- Energy border adjustment exposure:The EU Carbon Border Adjustment Mechanism is elevating power costs for warehouse refrigeration. Cold store operators in the Netherlands and Belgium face margin compression where grid intensity remains carbon-heavy.
- Specialized fleet substitution limits:No viable substitute exists for diesel-powered transport refrigeration in long-haul frozen distribution. Battery-electric alternatives lack the energy density for multi-day frozen runs across Southern European corridors.
Strategic Opportunities
- Polish and Romanian warehouse development:Underpenetrated cold storage capacity in Poland and Romania offers expansion corridors for frozen and chilled distribution. These markets serve as consolidation points for Black Sea grain and Eastern European protein flows.
- Automation-software convergence:Warehouse management systems integrating with automated high-bay storage are compressing labor intensity per pallet position. This convergence enables 24-hour throughput with minimal temperature excursion risk.
- CSRD-driven sustainability reporting:The Corporate Sustainability Reporting Directive is creating demand for carbon-accounted cold chain services. Operators with verified low-emission footprints can capture premium positioning from retail clients facing disclosure mandates.
Industry Challenges
- Refrigerant technician certification gaps:The compressed timeline for F-Gas compliant equipment deployment is outpacing certified technician availability. Fleet maintenance networks in Spain and Italy face scheduling bottlenecks for retrofit work.
- Legacy warehouse management system integration:Automated high-bay facilities require real-time data exchange with existing enterprise resource planning platforms. Cold store operators face integration complexity where legacy systems lack API compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Food Cold Chain Logistics Market |
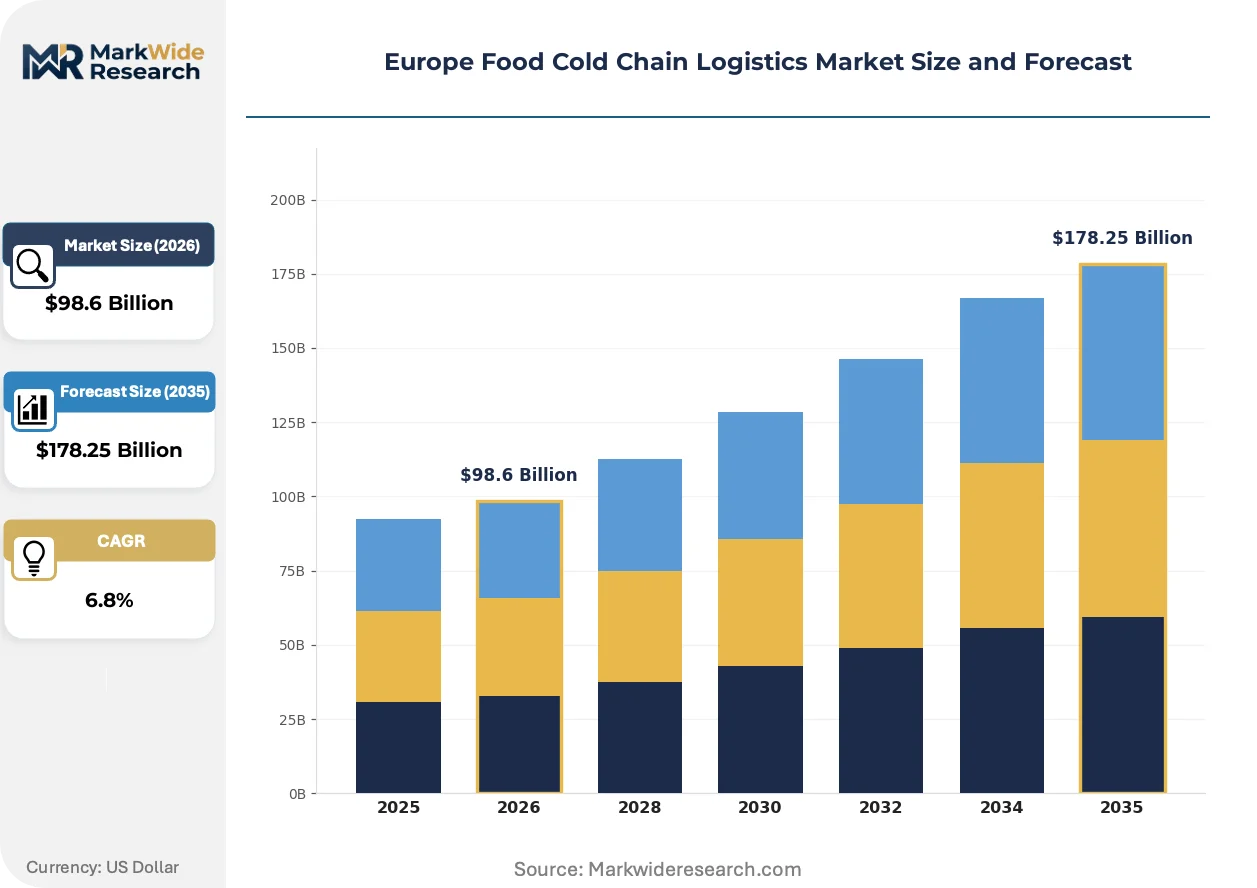
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $178.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Packaging, Distribution Temperature Range: Ambient, Refrigerated, Frozen, Cryogenic Product Type: Dairy Products, Meat, Seafood, Fruits End User: Food Manufacturers, Retailers, Wholesalers, Restaurants |
| Companies Covered | DSV AS, STEF SA, DHL Supply Chain, GEODIS, NewCold Advanced Cold Logistics, AP Moller Maersk AS, Lineage Inc., Americold Logistics, LLC, Kuehne + Nagel International AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Food Cold Chain Logistics Market Trends and Innovations
Electrification and automation are rewriting operational economics across European cold chain infrastructure, compressing energy intensity while elevating capital requirements for competitive positioning.
CO2 transcritical refrigeration systems are rewriting efficiency benchmarks for European cold storage facilities. These systems operate at higher pressure ratios than hydrofluorocarbon alternatives, delivering superior thermodynamic performance in temperate climates. Dutch and Danish cold store operators are adopting CO2 systems at accelerating pace to hedge against refrigerant phase-down exposure. The technology is rewriting facility location economics by reducing energy cost variance across climate zones.
The EU F-Gas Regulation is mandating stepped reductions in hydrofluorocarbon refrigerant volumes through 2030. Fleet operators face compressed replacement cycles for transport refrigeration units using R404A and R134a chemistries. The refrigerated road transport segment is responding with accelerated pilot programs for hydrofluoroolefin alternatives and electric compressor architectures in Germany, France, and the Netherlands.
Foodservice procurement is consolidating toward integrated temperature-controlled logistics providers capable of spanning primary distribution through last-mile delivery. Small and mid-sized restaurant chains are displacing fragmented multi-vendor arrangements with single-source contracts covering frozen, chilled, and ambient flows. This consolidation is most visible in urban UK and German markets where labor costs and delivery density favor integrated network operators.
Europe Food Cold Chain Logistics Market Segmentation
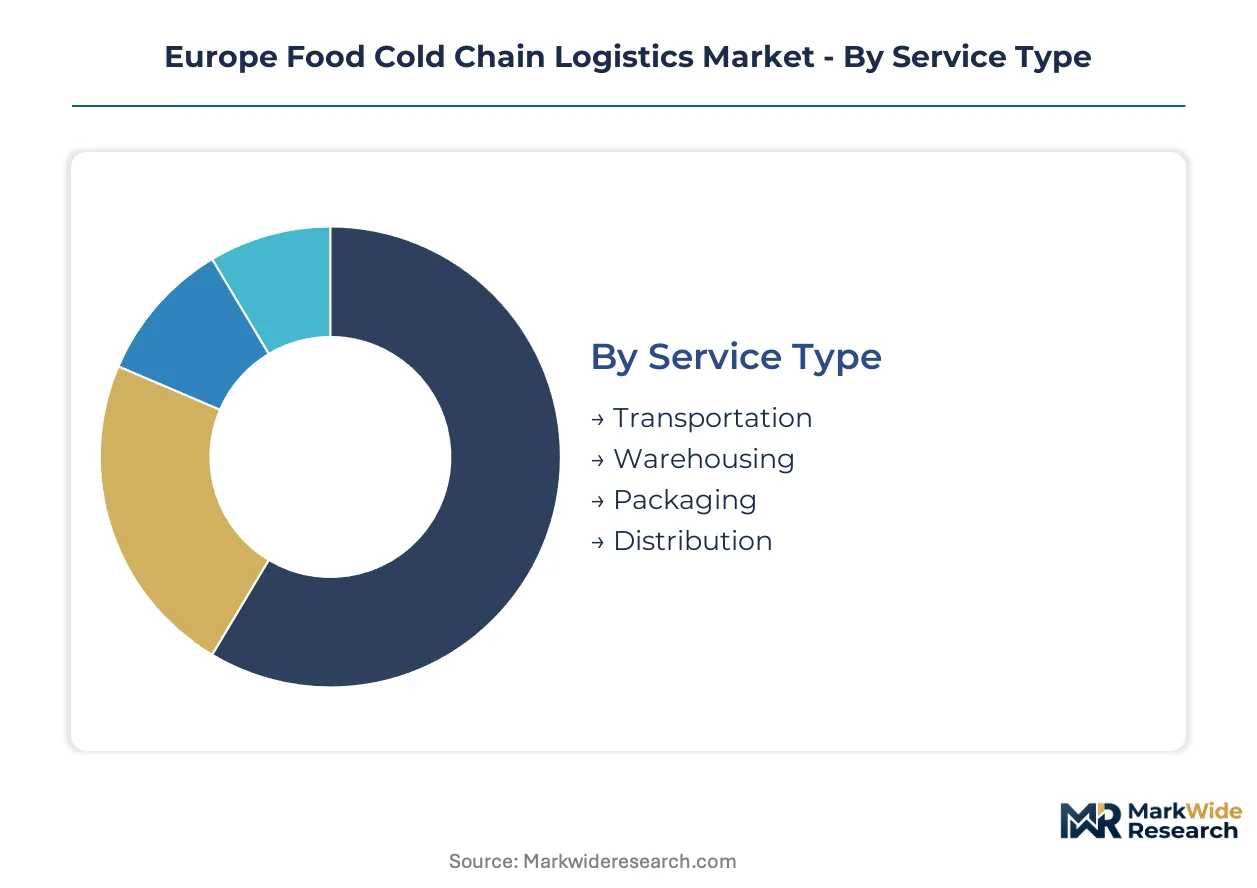
Temperature-controlled logistics demands precise segment alignment between thermal requirements and infrastructure capabilities. Service configuration, thermal bands, product sensitivity, and end-user operational rhythms each dictate distinct equipment investments and network architectures across European cold chain operations.
Service Type:
Temperature integrity depends on which operational layer controls custody of perishable goods.
- Transportation:Refrigerated road fleets and intermodal rail services maintain unbroken cooling across multimodal handoffs. German and French operators prioritize electrified transport refrigeration units to satisfy EU Green Deal CE marking mandates for cross-border licenses.
- Warehousing:Automated high-bay frozen storage facilities compress energy intensity per pallet position through CO2 transcritical refrigeration systems. Dutch cold store operators deploy these systems to hedge against F-Gas Regulation phase-down exposure.
- Packaging:Insulated containers and phase-change materials extend temperature stability during last-mile handoffs. Active thermal packaging with integrated cooling elements serves prepared meal distribution in urban UK foodservice channels.
- Distribution:Consolidated fulfillment networks span primary distribution through last-mile delivery. Integrated operators capture single-source contracts from mid-sized restaurant chains displacing fragmented multi-vendor arrangements.
Transportation leads on scale; Warehousing leads on momentum.
Temperature Range:
Capital allocation follows thermal band complexity and energy intensity gradients.
- Refrigerated:Dairy and fresh protein shippers demand precise bands between 0 and 4 degrees Celsius. This segment concentrates demand in port-adjacent cold stores serving Rotterdam and Hamburg import flows.
- Frozen:Minus 18 to minus 25 degree Celsius operations command premium margins due to automation requirements and energy hedging needs. Automated facilities in the Netherlands and Denmark exploit CO2 system efficiency in temperate climates.
- Ambient:Non-refrigerated handling applies to shelf-stable packaged goods co-loaded with temperature-sensitive cargo. Retail consolidation centers in Poland and Romania leverage ambient capacity for mixed-load efficiency.
- Cryogenic:Ultra-low minus 80 degree Celsius systems serve specialized pharmaceutical and high-value protein applications. Limited deployment concentrates at Belgian and German hub facilities with liquid nitrogen infrastructure.
Frozen commands margin concentration; Refrigerated captures volume breadth.
Product Type:
Biological decay rates determine custody transfer frequency and monitoring intensity.
- Meat:Fresh and frozen protein flows dominate containerized imports through European port complexes. Automated high-bay facilities compress dwell times for beef and pork shipments entering Rotterdam and Hamburg.
- Seafood:Rapid temperature descent requirements from harvest temperature to frozen state demand specialized blast freezing infrastructure. Nordic and Scottish processing clusters feed continental distribution through dedicated cold chains.
- Dairy:Chilled distribution networks serve just-in-time replenishment for retail private-label programs. French and German dairy processors anchor regional hub-and-spoke configurations.
- Fruits:Ripening-controlled logistics for bananas and avocados requires ethylene-managed environments. Mediterranean port facilities in Spain and Italy handle Southern Hemisphere counter-seasonal flows.
Meat anchors import volume; Seafood drives automation investment.
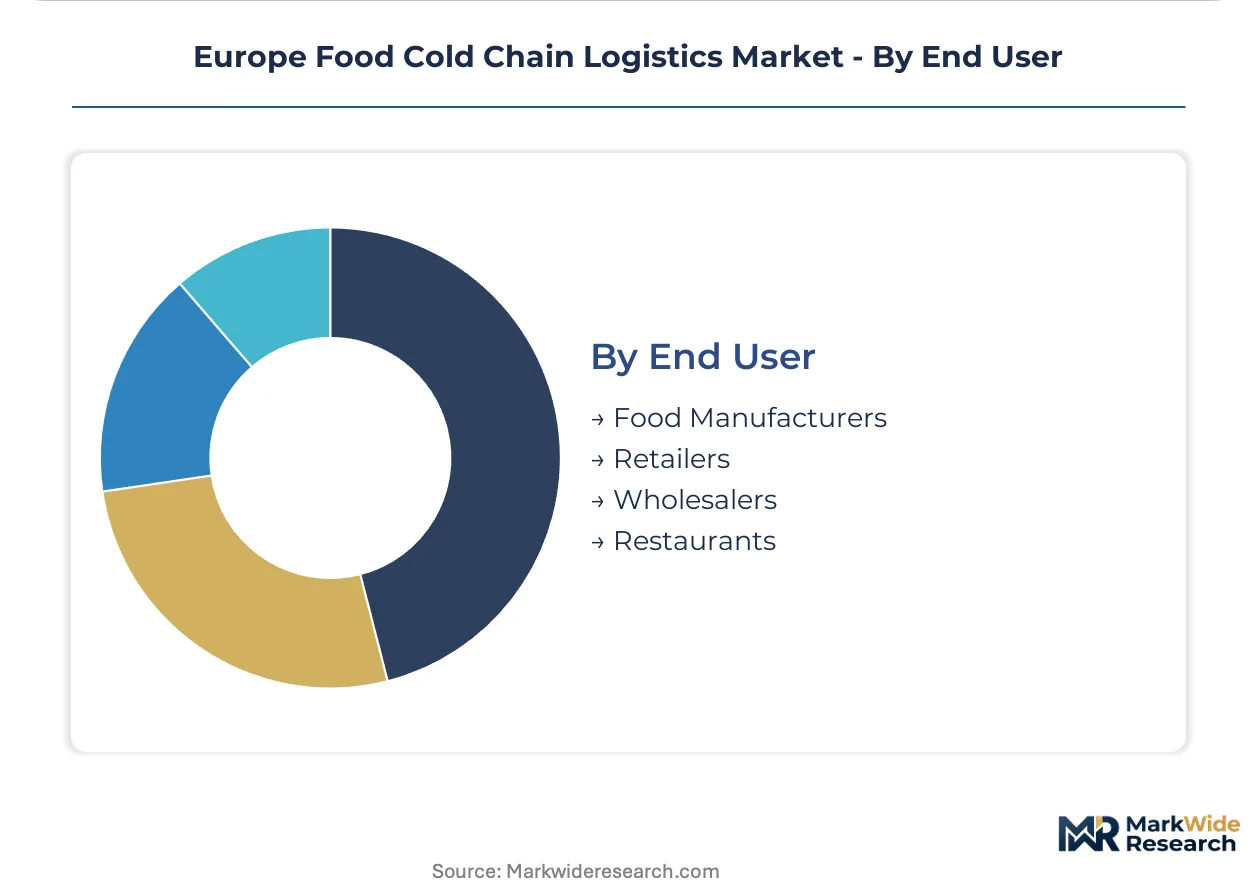
End User:
Operational tempo and order granularity shape service level requirements and pricing structures.
- Restaurants:Ready-to-eat meal distribution pulls refrigerated capacity toward urban last-mile networks. Foodservice procurement consolidation favors integrated providers spanning frozen, chilled, and ambient flows.
- Retailers:Omnichannel fulfillment demands synchronized replenishment for store and home delivery channels. DHL Supply Chain leverages pan-European warehouse footprints to anchor temperature-controlled retail fulfillment.
- Food Manufacturers:Ingredient sourcing and finished goods distribution require dedicated contract logistics arrangements. Meat and seafood processors maintain captive cold storage adjacent to production facilities.
- Wholesalers:Break-bulk operations consolidate fragmented producer volumes for downstream redistribution. Traditional merchant wholesalers in Southern Europe face margin pressure from integrated network operators.
Restaurants drive channel transformation; Retailers anchor contract value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam and Hamburg port complexes anchor European cold chain capacity, concentrating automated frozen storage and intermodal handoff infrastructure for import-dependent protein flows.
Germany
Meat and dairy processors in Lower Saxony and Bavaria drive demand for precise chilled distribution networks. The EU F-Gas Regulation accelerates fleet retrofits for cross-border transport refrigeration units. Hamburg's port-adjacent cold stores compress dwell times for containerized beef and pork shipments entering Northern European markets.
France
Foodservice procurement consolidation pulls refrigerated capacity toward urban last-mile networks in Paris and Lyon. CE marking mandates under the EU Green Deal prioritize electrified transport refrigeration for fleet operators maintaining cross-border licenses. STEF SA sustains dominant coverage across France and Southern Europe through specialized meat and seafood logistics infrastructure.
Netherlands
Rotterdam's automated high-bay frozen storage facilities serve as consolidation points for global protein imports. CO2 transcritical refrigeration systems rewrite efficiency benchmarks for Dutch cold store operators hedging against refrigerant phase-down exposure. The Randstad region concentrates temperature-controlled fulfillment capacity serving retail omnichannel replenishment.
Poland
Underpenetrated cold storage capacity offers expansion corridors for frozen and chilled distribution serving Eastern European markets. Black Sea grain and regional protein flows consolidate at Polish hub facilities. The country's central geography positions Warsaw and Łódź as redistribution points for continental supply chains.
Spain
Mediterranean port facilities in Barcelona and Valencia handle Southern Hemisphere counter-seasonal fruit flows requiring ethylene-managed ripening environments. Refrigerant technician certification gaps create scheduling bottlenecks for F-Gas compliant equipment deployment. Andalusian processing clusters feed continental distribution through dedicated seafood cold chains.
Europe Food Cold Chain Logistics Market Competitive Landscape
Capacity expansion dominates the current landscape as operators automate high-bay facilities and electrify transport fleets to satisfy regulatory mandates. The market exhibits tiered concentration with global integrators, regional specialists, and port-centric operators occupying distinct competitive positions. Three strategic archetypes define the field: pan-European network operators leveraging warehouse scale, national champions dominating specific protein verticals, and automated cold storage specialists compressing energy intensity per pallet. M&A activity and strategic partnerships represent the dominant competitive moves as players seek geographic density and technology access.
Among pan-European network operators, DHL Supply Chain and Kuehne + Nagel International AG exemplify the integrated fulfillment archetype spanning primary distribution through last-mile delivery. STEF SA occupies a position within the regional specialist tier, anchoring temperature-controlled logistics across France and adjacent markets. NewCold Advanced Cold Logistics represents the automation-focused segment, with facilities that compress labor intensity through high-bay frozen storage systems.
| Leading Market Players |
|---|
| DSV AS |
| STEF SA |
| DHL Supply Chain |
| GEODIS |
| NewCold Advanced Cold Logistics |
| AP Moller Maersk AS |
| Lineage Inc. |
| Americold Logistics, LLC |
| Kuehne + Nagel International AG |
| Others |
Pricing and Supply Chain Analysis
CO2 transcritical refrigeration adoption is compressing energy cost variance across European cold storage facilities while concentrating competitive advantage among operators with capital reserves for system conversion. This technology shift simultaneously elevates fixed-cost barriers and reshapes margin pools toward automated facilities in temperate climate zones.
Pricing Analysis
Refrigerant input-cost pass-through dominates pricing dynamics as EU F-Gas Regulation phase-down schedules squeeze legacy hydrofluorocarbon supply. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked electrified fleets from diesel-dependent long-haul operators and ambient co-load services. Pricing pressure stems from energy border adjustment exposure elevating warehouse power costs in carbon-heavy grid regions. Small restaurant chains exhibit highest price sensitivity, while omnichannel retailers prioritize carbon-accounted service premiums over unit cost.
Supply Chain Analysis
EU Green Deal local-content provisions for transport equipment manufacturing are reshaping sourcing patterns for refrigeration unit assembly. Supply concentrates in Germany, the Netherlands, and Denmark for CO2 system components and electrified transport refrigeration. Raw material dependencies span aluminum heat exchangers, steel racking systems, and specialized compressor castings. Single-source vulnerability concentrates in Danish and German CO2 component suppliers. Distribution runs through port-adjacent cold stores at Rotterdam and Hamburg anchoring import-dependent protein flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European food cold chain logistics represents a late-cycle quality story as foodservice procurement consolidation favors integrated operators capable of spanning frozen, chilled, and ambient flows with verified low-emission footprints.
For Market Incumbents: Hedge refrigerant phase-down exposure by accelerating CO2 transcritical retrofits in Dutch and Danish facilities before technician certification gaps widen. Consolidate position in Polish and Romanian warehouse development corridors to capture Black Sea grain and Eastern European protein flows. Defend against automation-software convergence threats by prioritizing API-compatible warehouse management system upgrades. For New Entrants and Emerging Players: Enter via underpenetrated cold storage capacity in Poland and Romania serving consolidation points for continental redistribution. Target mid-sized restaurant chains in urban UK and German markets displacing fragmented multi-vendor arrangements with single-source temperature-controlled contracts. Pursue CSRD-driven sustainability reporting as the primary go-to-market angle for retail clients facing disclosure mandates. For Investors and Strategic Acquirers: Valuations sit cheapest among national champions with captive protein verticals and port-adjacent real estate positions. Long-term viability favors operators with automated high-bay infrastructure and electrified fleet pathways aligned with EU Green Deal compliance timelines. Watch refrigerant technician certification expansion rates as the inflection signal for retrofit capacity constraints easing.| Strategic Initiative | Industry Significance |
|---|---|
| CO2 Transcritical Refrigeration Retrofit | Hedges against F-Gas Regulation phase-down exposure while compressing energy intensity per pallet position. |
| Polish and Romanian Warehouse Development | Captures underpenetrated capacity serving Black Sea grain and Eastern European protein redistribution. |
| Electrified Transport Refrigeration Fleet Conversion | Satisfies EU Green Deal CE marking mandates for cross-border operating licenses in Germany and France. |
| Automation-Software Convergence Investment | Enables 24-hour throughput with minimal temperature excursion risk through integrated high-bay systems. |
| CSRD-Verified Carbon Accounting Service Launch | Captures premium positioning from retail clients facing Corporate Sustainability Reporting Directive disclosure mandates. |
Research Methodology
Multiple input streams — cold chain logistics executives, fleet operations directors, warehouse automation engineers, and foodservice procurement managers — were reconciled against secondary validation from EU F-Gas Regulation filings, ECHA REACH substance registrations, customs trade data, and cold storage capacity databases. Bottom-up facility-level capacity estimates and top-down market sizing were triangulated to anchor volume and value outputs.
Data-stream reconciliation across the projection horizon applied segment-level modeling across service type, temperature range, product category, and end-user operational tempo. CAGRs were derived from equipment replacement cycle analysis, regulatory compliance timeline assumptions, and foodservice channel expansion patterns. Forecast inputs incorporated port throughput volumes for Rotterdam and Hamburg, electrified fleet adoption curves, and automation capital expenditure disclosures from Dutch and Danish operators.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time warehouse utilization rates and proprietary fleet cost structures introduce uncertainty bands around margin compression estimates. Forecasts reflect documented assumptions regarding F-Gas phase-down adherence, energy border adjustment implementation scope, and technician certification expansion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Smoker Grill Market
Food Service
Meal Kit Delivery Services Market
Food Service
South America Free from Food Market
Food Service
Virtual Kitchen Market
Food Service
Latin America Biodegradable Food Service Disposables Market
Food Service
Flat Top Grills Market
Food Service
Peer-To-Peer Dining Market
Food Service
United Arab Emirates Foodservice Market
Food Service
Workplace Service Market
Food Service
Gourmet Street Food Market
Food Service
Food Service Disposables Market
Food Service
Food Logistics Market
Food Service
Europe Airline Catering Services Market
Food Service
Commercial Tandoor Oven Market
Food Service
Commercial Sink Market
Food Service
Global Combi Ovens Market