
 Vietnam Food Service Market | 2026-2036
Vietnam Food Service Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Food Service Market Insights
HACCP certification is reorganizing competitive access for international chains entering Vietnam. Golden Gate JSC dominates the casual dining tier through backward integration into central kitchen operations. Jollibee Foods Corporation leverages its Filipino brand equity to anchor market share in the fast-food segment. Starbucks Corporation positions its premium café format in Ho Chi Minh City's District 1 and Hanoi's Ba Dinh district.
Vietnam food service encompasses commercial preparation and sale of meals through structured formats ranging from quick-service counters to full-table establishments, with operational parameters governed by kitchen throughput capacity, cold-chain integrity, and standardized recipe protocols. The sector supplies nourishment, social venue utility, and employment across urban commercial corridors. Fast food and cafés concentrate margin pools where online delivery integration lowers real estate overhead, while fine dining sustains pricing power through experiential differentiation. The distribution channel split between dine-in and online delivery reflects infrastructure maturity gaps between Ho Chi Minh City and secondary provinces.
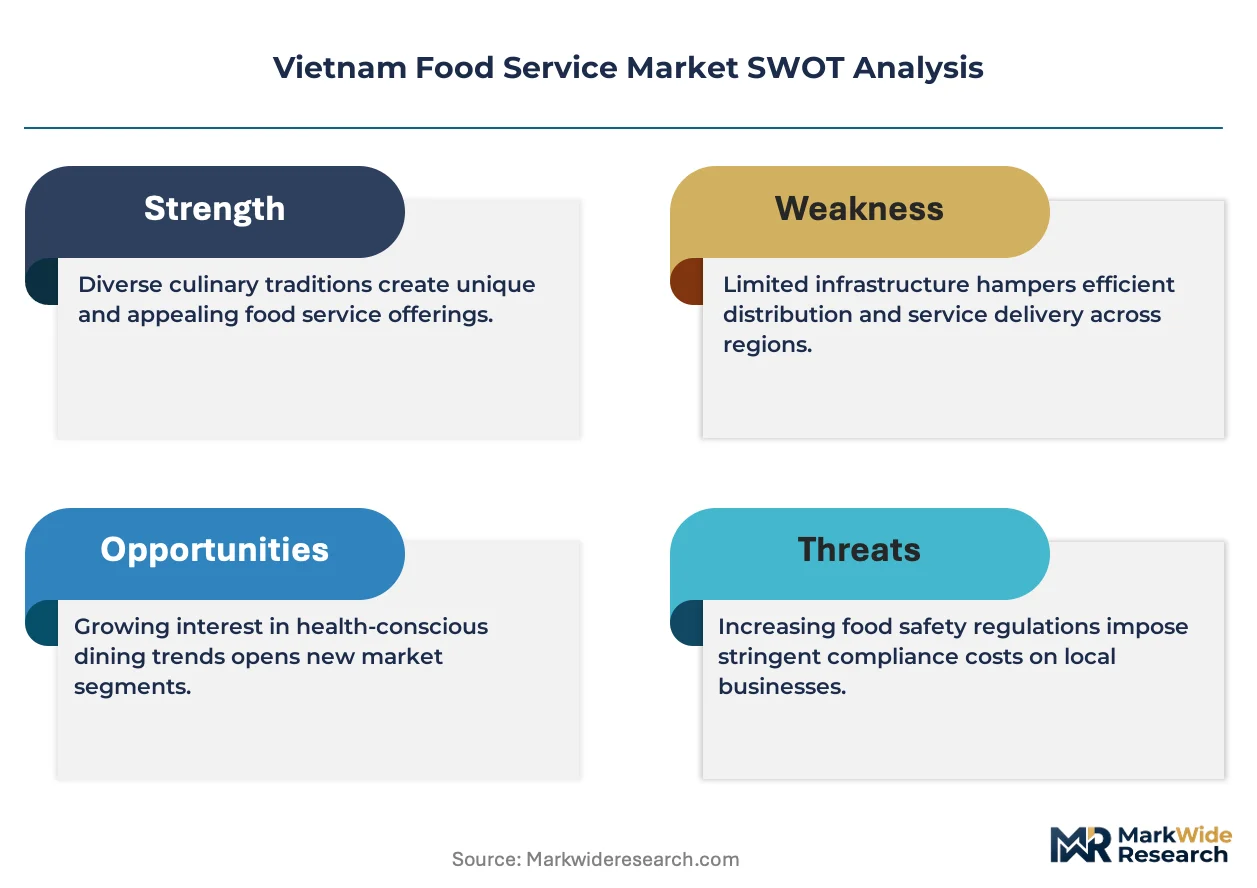
Vietnam's Ministry of Health enforces food safety protocols through periodic HACCP audits that filter substandard operators from licensing renewal. The Ministry of Industry and Trade coordinates with provincial People's Committees on street-vendor formalization programs that reshape informal sector participation. Stakeholders must monitor whether regulatory tightening on cloud kitchen licensing accelerates consolidation among unbranded digital-native entrants.
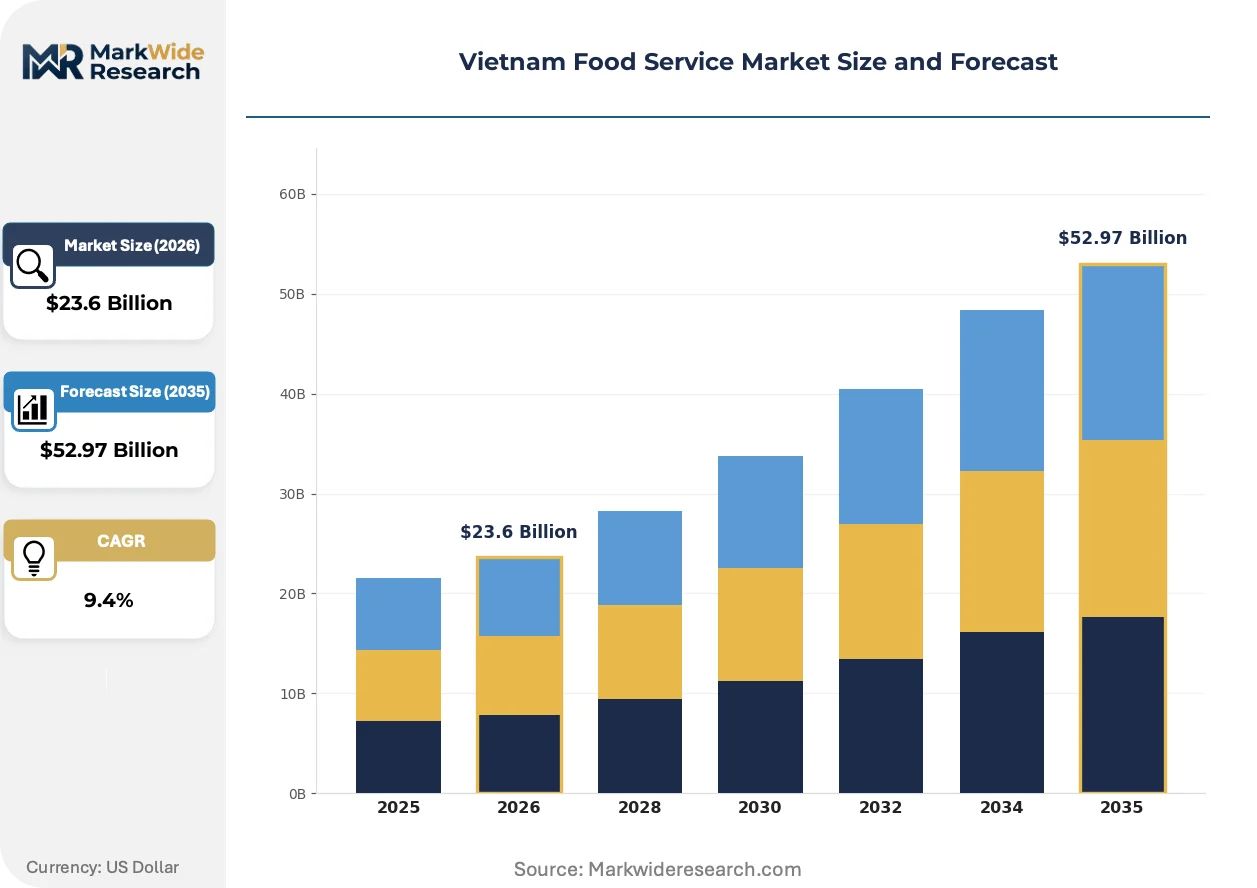
Market Dynamics
Vietnam's food service sector faces structural pressure from cloud kitchen infrastructure redirecting capital away from traditional dine-in formats, while HACCP certification requirements from the Ministry of Health filter substandard operators from licensing renewal. This dual squeeze reshapes competitive access for international chains and domestic incumbents alike.
Growth Catalysts
- Young professional demand:Quick-service restaurants targeting white-collar workers in Ho Chi Minh City and Hanoi are expanding outlet networks to capture weekday lunch and evening consumption clusters.
- Cloud kitchen infrastructure:Concentrated kitchen facilities in Da Nang and Hai Phong reduce real estate overhead for delivery-native brands, lowering barrier-to-entry for digital-first operators.
- Street vendor formalization:Provincial People's Committees coordinate with the Ministry of Industry and Trade to register informal vendors, expanding the addressable market for standardized supply chains.
Market Restraints
- Input cost volatility:Cold-chain logistics and imported protein prices fluctuate with fuel and currency movements, compressing margin pools for mid-tier operators.
- Regulatory friction:HACCP audit timelines and Ministry of Health certification renewals create licensing bottlenecks that delay market entry for foreign entrants.
- Substitution threat:Home meal preparation and informal street food retain price advantage over branded formats in secondary provinces outside Ho Chi Minh City and Hanoi.
Strategic Opportunities
- Central kitchen backward integration:Captive production of standardized sauces and prepped proteins reduces supplier dependency and quality variance across multi-outlet chains.
- Premium café format expansion:District 1 in Ho Chi Minh City and Ba Dinh district in Hanoi demonstrate pricing power for experiential beverage-led concepts with limited food menus.
- Online delivery channel maturation:Third-party platform integration enables asset-light scaling for brands avoiding prime retail rents in urban cores.
Industry Challenges
- Certification timeline compression:Ministry of Health food safety audits demand documentation systems that unbranded digital-native entrants struggle to operationalize before license expiration.
- Kitchen throughput standardization:Recipe protocol consistency across cloud kitchen nodes and dine-in outlets requires training infrastructure that fragments operational focus.
- Cold-chain integrity maintenance:Provincial gaps in refrigerated logistics force operators to self-invest in distribution assets, raising capital intensity outside major metros.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Food Service Market |
| Market Size in 2026 | $23.6 Billion |
| Market Size in 2035 | $52.97 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fast Food, Casual Dining, Fine Dining, Cafés Distribution Channel: Online Delivery, Dine-In, Takeaway, Catering Customer Type: Families, Young Professionals, Tourists, Students Service Style: Buffet, À La Carte, Food Trucks, Pop-Up Stalls |
| Companies Covered | Lotte GRS Co Ltd, Starbucks Corporation, Golden Gate JSC, Mesa Group, Restaurant Brands International Inc, Jollibee Foods Corporation, CP All PCL, Imex Pan Pacific Group, Yum! Brands Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Food Service Market Trends and Innovations
Cloud kitchen technology and delivery platform integration are actively fragmenting how food service brands access consumers, splitting operational models between asset-heavy dine-in and asset-light digital-native formats. This technological shift compresses real estate requirements while raising the bar for kitchen throughput efficiency.
Kitchen management software is bifurcating operational control between central kitchen nodes and last-mile preparation sites. Quick-service chains in Ho Chi Minh City deploy these systems to synchronize inventory across cloud facilities and flagship outlets. The technology compresses coordination costs for multi-format operators while enabling smaller brands to scale without proprietary real estate.
Vietnam's Ministry of Health enforces periodic HACCP audits that filter substandard operators from licensing renewal. The regulation compresses the viable operator base to those with documented cold-chain protocols and standardized recipe compliance. Foreign entrants and domestic chains alike redirect capital toward certification infrastructure rather than outlet expansion.
Consumption patterns among urban Vietnamese professionals rotate toward convenience-first meal solutions that prioritize speed over experiential dining. Lunch-hour demand in Hanoi's Cau Giay district and Ho Chi Minh City's District 7 shifts volume toward grab-and-go counters and pre-ordered pickup. This behavioral pivot rewards brands with streamlined menu architecture and sub-ten-minute service guarantees.
Vietnam Food Service Market Segmentation
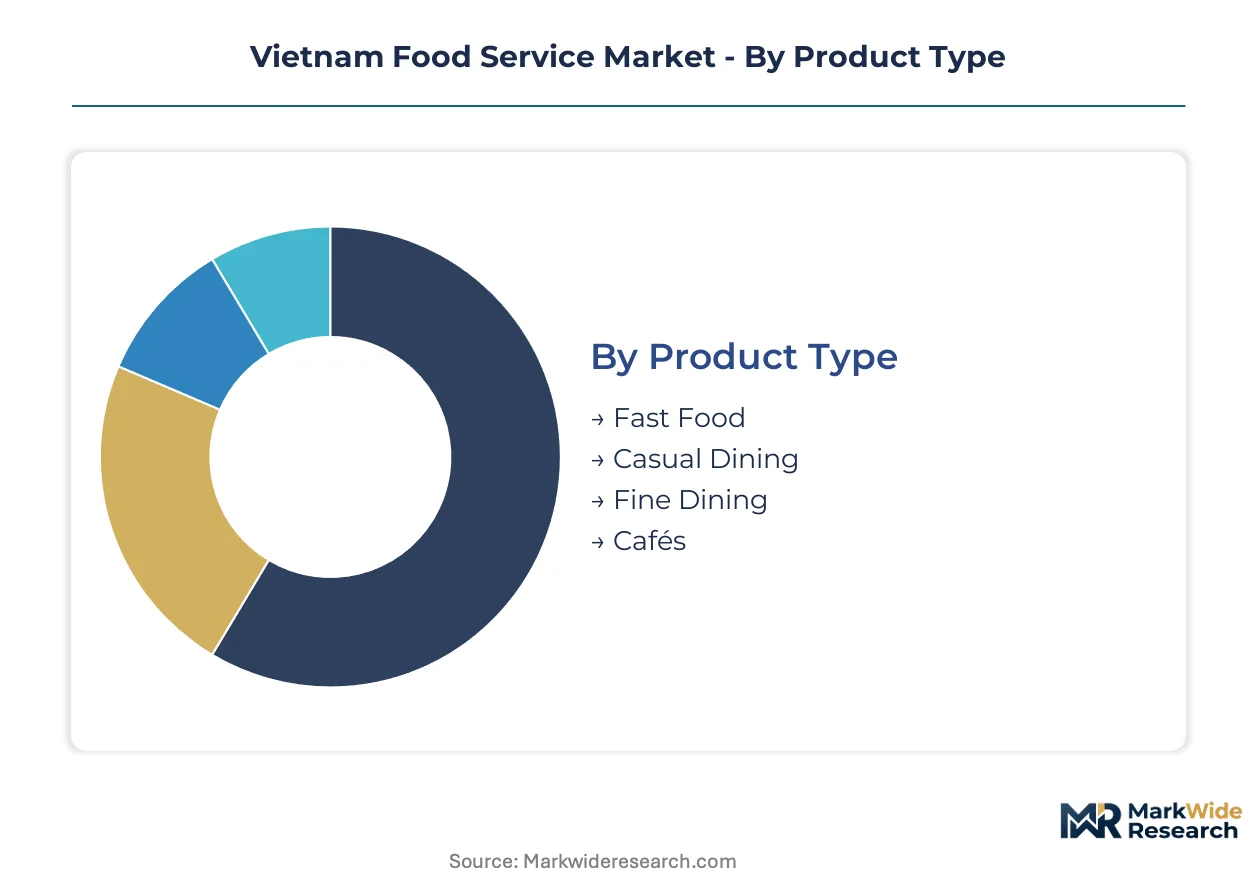
Vietnam's food service market fragments across operational formats that demand distinct regulatory compliance, capital intensity, and customer acquisition strategies. Segmentation reveals where Ministry of Health HACCP certification creates competitive moats versus where informal participation persists.
Product Type:
Regulatory differentiation through HACCP audit stringency separates licensed operators from street-level competitors across all four format tiers.
- Fast Food:Standardized menu architecture with sub-ten-minute service guarantees dominates weekday lunch clusters in Ho Chi Minh City's District 7 and Hanoi's Cau Giay. Young professional demand concentrates here, though input cost volatility from imported protein prices compresses margin pools for mid-tier chains.
- Casual Dining:Full-table service with moderate price positioning requires central kitchen backward integration to maintain quality variance control across multi-outlet networks. Golden Gate JSC anchors this tier through captive production of standardized sauces and prepped proteins.
- Fine Dining:Experiential differentiation sustains pricing power through chef-led menu curation and venue design in premium districts.
- Cafés:Beverage-led concepts with limited food menus concentrate in District 1 and Ba Dinh district where Starbucks Corporation positions its premium format.
Established volume favors Fast Food; emerging adoption favors Cafés.
Distribution Channel:
Cost tier separation between asset-heavy real estate commitments and asset-light digital infrastructure redirects capital flows across the four access modes.
- Online Delivery:Third-party platform integration enables scaling without prime retail rents, though cloud kitchen licensing timelines from the Ministry of Health create bottlenecks for unbranded digital-native entrants. Da Nang and Hai Phong infrastructure concentration lowers barrier-to-entry for delivery-native brands.
- Dine-In:Flagship outlet positioning in urban cores demands sustained rental commitments that fragment operational focus for multi-format operators. Cold-chain integrity maintenance forces self-investment in distribution assets outside major metros.
- Takeaway:Grab-and-go counters capture lunch-hour demand rotation toward convenience-first solutions.
- Catering:Volume contracts for corporate and event segments require batch production protocols distinct from individual meal service.
Margin concentration favors Online Delivery; experiential differentiation favors Dine-In.
Customer Type:
Application-specific demand patterns across four demographic clusters shape menu architecture and service speed requirements.
- Young Professionals:White-collar workers in Ho Chi Minh City and Hanoi drive expansion of quick-service outlet networks for weekday lunch and evening consumption. Speed prioritization over experiential dining rewards streamlined menu architecture.
- Families:Group dining occasions concentrate in casual dining and buffet formats where portion scalability and child-friendly options determine venue selection.
- Tourists:International visitors seek experiential differentiation through regional cuisine presentation in fine dining and premium café settings.
- Students:Price-sensitive demand in secondary provinces retains preference for informal street food and economy-tier fast food.
Volume scale favors Young Professionals; pricing power favors Tourists.
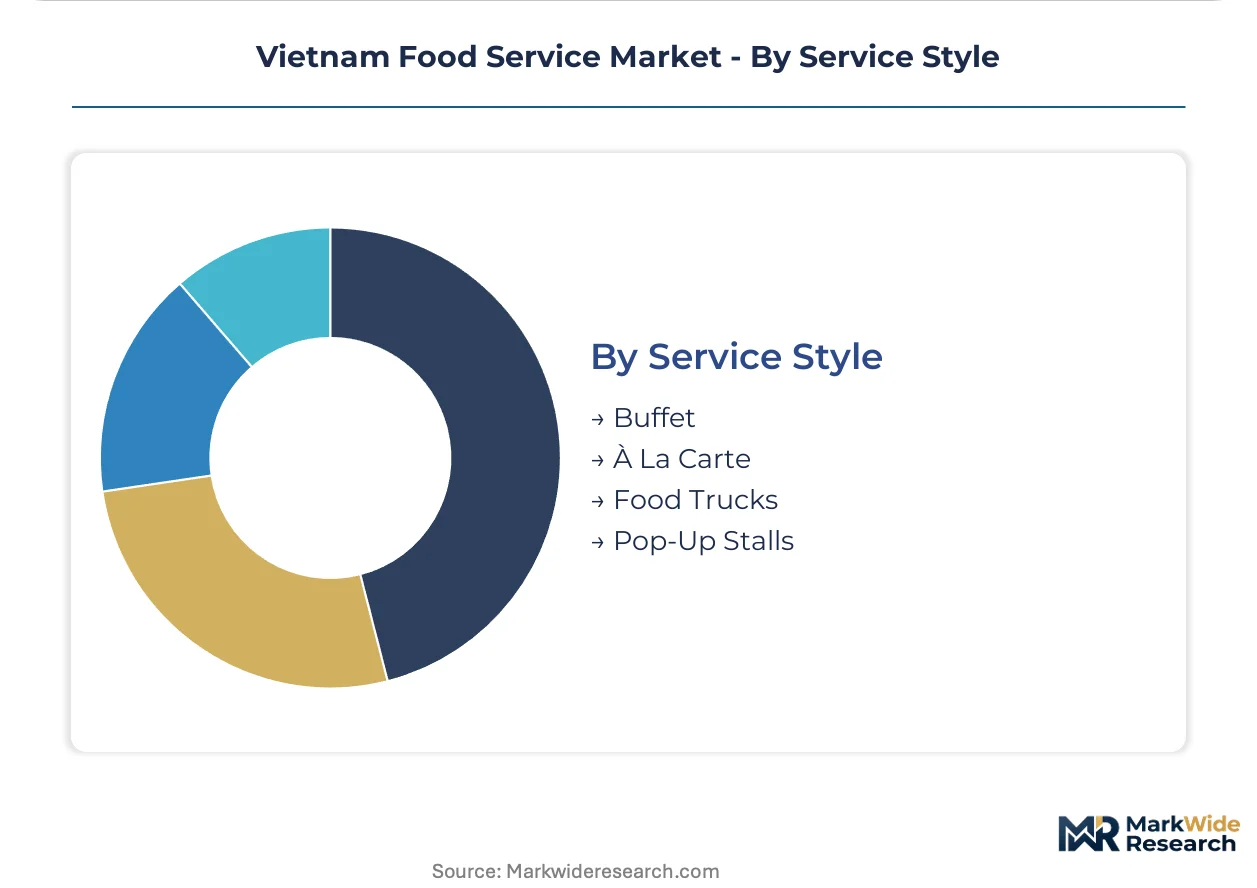
Service Style:
Maturity gaps between formalized licensed operations and informal sector participation reshape competitive access under street vendor formalization programs.
- À La Carte:Individual item ordering with kitchen throughput standardization across outlets requires training infrastructure that chains deploy through management software. Recipe protocol consistency fragments operational focus for multi-node operators.
- Buffet:Self-service formats with portion control challenges demand distinct food safety protocols for temperature maintenance and cross-contamination prevention.
- Food Trucks:Mobile units operating under provincial People's Committee registration expand addressable market for standardized supply chains.
- Pop-Up Stalls:Temporary positioning captures event-driven demand with minimal capital commitment.
Operational stability favors À La Carte; flexibility favors Pop-Up Stalls.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Young professionals in Ho Chi Minh City and Hanoi drive weekday consumption clusters, while provincial markets retain informal street-food participation. The Ministry of Health's HACCP certification requirements filter substandard operators from licensing renewal, compressing the viable base to documented cold-chain protocols.
Ho Chi Minh City
White-collar workers in District 1 and District 7 power quick-service lunch demand, with premium café formats commanding pricing power. The Ministry of Health enforces periodic HACCP audits that reshape competitive access for foreign entrants. Cloud kitchen infrastructure in peripheral zones redirects capital from traditional dine-in formats toward delivery-native scaling.
Hanoi
Government and corporate office clusters in Ba Dinh and Cau Giay districts generate concentrated weekday meal demand. Provincial People's Committees coordinate street-vendor formalization programs with the Ministry of Industry and Trade. Central kitchen backward integration by domestic chains reduces supplier dependency across multi-outlet networks in the capital corridor.
Da Nang
Tourism and port logistics create dual demand streams for experiential dining and industrial catering. The Ministry of Health food safety certifications tighten operational standards for beachfront and hotel-adjacent operators. Cloud kitchen concentration lowers real estate overhead for delivery-native brands targeting the central coast.
Hai Phong
Manufacturing zone expansion and port throughput generate working-class meal demand alongside expatriate consumption. Provincial regulators align with national HACCP timelines, creating licensing bottlenecks for unbranded entrants. Kitchen facility clustering enables third-party platform integration without prime retail rent exposure.
Can Tho
Mekong Delta agricultural trade flows support fresh-ingredient supply chains for regional cuisine formats. Street vendor formalization programs expand addressable market for standardized supply chains. Cold-chain gaps force self-investment in distribution assets, raising capital intensity for branded operators.
Vietnam Food Service Market Competitive Landscape
Player mix skews toward multi-format domestic conglomerates with central kitchen infrastructure and foreign fast-food chains with delivery platform integration. The market structure fragments across four operational tiers: premium café concepts, quick-service counters, casual dining networks, and cloud kitchen-native brands. Strategic archetypes include backward-integrated domestic operators, format-specialist foreign entrants, and asset-light digital-native challengers. Dominant competitive moves encompass central kitchen capacity expansion and third-party delivery platform partnerships.
Within the domestic integrated tier, Golden Gate JSC exemplifies backward integration into captive sauce and protein preparation. Foreign format specialists include Starbucks Corporation, occupying premium positioning in District 1 and Ba Dinh district, and Jollibee Foods Corporation, leveraging Filipino brand equity in the fast-food segment. These three anchors represent divergent strategic paths: domestic supply chain control, experiential beverage-led concepts, and ethnic brand differentiation.
| Leading Market Players |
|---|
| Lotte GRS Co Ltd |
| Starbucks Corporation |
| Golden Gate JSC |
| Mesa Group |
| Restaurant Brands International Inc |
| Jollibee Foods Corporation |
| CP All PCL |
| Imex Pan Pacific Group |
| Yum! Brands Inc |
| Others |
Pricing and Supply Chain Analysis
Seven-to-ten-day protein inventory cycles in Ho Chi Minh City and Hanoi compress margin pools for mid-tier operators while amplifying pricing power for backward-integrated chains with captive cold-chain assets. This lead-time band concentrates cost volatility exposure among unbranded entrants lacking Ministry of Health HACCP certification infrastructure.
Pricing Analysis
Cost-plus contracts indexed to imported protein and fuel benchmarks dominate procurement for mid-tier fast-food and casual dining chains. Three-tier pricing structure across premium, standard, and economy levels separates Starbucks Corporation's experiential café formats from Golden Gate JSC's central kitchen-integrated casual dining and street-level economy vendors. Pricing pressure stems from currency-driven input cost volatility compressing margins for operators without backward integration. Students and price-sensitive workers in secondary provinces exhibit highest price sensitivity; tourists and District 1 white-collar professionals demonstrate lowest.
Supply Chain Analysis
Inventory cycles of under ten days for fresh proteins and produce force rapid turnover commitments from cloud kitchen nodes and dine-in outlets alike. Vietnam draws from domestic Mekong Delta agricultural corridors for vegetables and seafood, Australia and Brazil for beef, and China for processed packaging materials. Single-source vulnerability concentrates in imported protein channels exposed to currency fluctuation. Distribution runs through third-party delivery platforms integrated with cloud kitchen clusters in Da Nang and Hai Phong, supplemented by self-invested cold-chain assets for provincial expansion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's food service sector is cycling through a recovery phase driven by young professional consumption clusters rebounding in Ho Chi Minh City and Hanoi office corridors. Cloud kitchen infrastructure buildout and street vendor formalization programs create divergent entry economics across format tiers.
For Market Incumbents: Shield core margin pools by accelerating central kitchen backward integration into sauce and protein preparation, reducing exposure to imported input volatility. Defend licensing renewal timelines by pre-positioning HACCP documentation systems ahead of Ministry of Health audit windows. Prioritize certification investment as the primary lever to filter digital-native challengers from viable competitor sets.
For New Entrants and Emerging Players: Delivery-native brand positioning in Da Nang and Hai Phong cloud kitchen clusters offers the most penetrable white-space, where real estate overhead compression enables sub-scale economics unavailable in Ho Chi Minh City or Hanoi. Target working-class demand in Hai Phong manufacturing zones and Can Tho agricultural trade corridors where branded supply chains remain underdeveloped. Pursue go-to-market angles through third-party platform exclusivity rather than proprietary outlet buildout.
For Investors and Strategic Acquirers: Carve-out targets emerge from domestic conglomerates divesting non-core food service assets amid central kitchen consolidation pressures. Long-term viability over a five-to-ten-year window favors operators with captive production infrastructure and multi-format flexibility across dine-in and delivery channels. Watch cloud kitchen licensing timeline compression by the Ministry of Health as the signal for accelerated consolidation among unbranded digital-native entrants.
| Strategic Initiative | Industry Significance |
|---|---|
| Central Kitchen Backward Integration | Captive sauce and protein production reduces supplier dependency for Golden Gate JSC-format chains. |
| Cloud Kitchen Licensing Compliance | HACCP documentation systems filter substandard operators from Ministry of Health renewal pools. |
| Third-Party Platform Partnership | Delivery-native scaling in Da Nang and Hai Phong avoids prime retail rent exposure. |
| Premium Café Format Expansion | District 1 and Ba Dinh positioning captures pricing power from experiential beverage-led demand. |
| Street Vendor Formalization Program | Ministry of Industry and Trade registration expands addressable market for standardized supply chains. |
Research Methodology
A spread of perspectives from central kitchen operations directors, third-party delivery platform strategists, provincial People's Committee licensing officers, and quick-service franchise development leads converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through Ministry of Health HACCP audit disclosures, Ministry of Industry and Trade street vendor registration data, and customs records tracking imported protein flows. Bottom-up outlet count triangulation against top-down consumption expenditure estimates anchored volume and value outputs.
Segmentation dimensions modeled encompass operational format tier, distribution channel split, customer demographic cluster, and geographic urban core versus provincial corridor classification across the projection horizon. CAGRs derive from trend extrapolation of outlet expansion rates, per-capita consumption intensity shifts, and delivery platform penetration curves. Industry-specific forecast inputs include cloud kitchen facility commissioning timelines and HACCP certification renewal velocity by provincial jurisdiction.
Forecasts assume regulatory continuity in Ministry of Health food safety audit regimes and Ministry of Industry and Trade street vendor formalization programs; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Europe Food Cold Chain Logistics Market
Food Service
Global Cafe and Bars Market
Food Service
Asia-Pacific Cloud Kitchen Market
Food Service
Air Fryer Meal Kits Market
Food Service
Retail Bubble Tea Kits Market
Food Service
United Kingdom Barbeque Grill Market
Food Service
Commercial Deep Fryer Parts and Accessories Market
Food Service
Food Service Utensils Market
Food Service
Global Vending Machine Market
Food Service
Malaysia Food Service Market
Food Service
Saudi Arabia Quick Service Restaurants Market
Food Service
Plates Market
Food Service
Beverage Vending Machine Market
Food Service
India Retail Bubble Tea Kits Market
Food Service
Philippines Foodservice Market
Food Service
Stirrers Market