
 Restaurant Takeout Market | 2026-2036
Restaurant Takeout Market Size, Share, and Industry Trends Forecast 2026-2036
Restaurant Takeout Market Analytics
FDA food safety modernization is consolidating the cost-of-entry calculus for restaurant takeout operators. Domino's leverages its captive delivery fleet and technology infrastructure to sustain national scale advantages. Wingstop anchors its growth model on digital-native ordering and specialized menu focus. Cava differentiates through Mediterranean fast-casual positioning and customizable bowl formats that travel well for off-premise consumption.
Restaurant takeout encompasses prepared food orders packaged for consumption away from the point of preparation, requiring temperature-retentive packaging engineered to maintain food safety thresholds between 140°F hot holding and 40°F cold storage over transit durations. The primary commercial purpose centers on converting fixed kitchen capacity into incremental revenue streams without proportional dining room footprint expansion. Takeaway and delivery service types now capture the dominant margin pools as labor costs shift fulfillment economics toward higher-ticket off-premise orders. Mobile app and website ordering channels are expanding fastest, displacing phone-based transactions through integrated loyalty programs and predictive reordering algorithms.
FDA food code standards, state-level health department permitting frameworks, and municipal zoning ordinances collectively shape packaging compliance requirements, driver classification rules, and ghost kitchen operating permissions. These regulatory layers determine market access costs and operational flexibility for multi-unit operators. Stakeholders must monitor evolving delivery worker classification rulings and single-use packaging bans as these forces will restructure last-mile economics and material sourcing decisions.
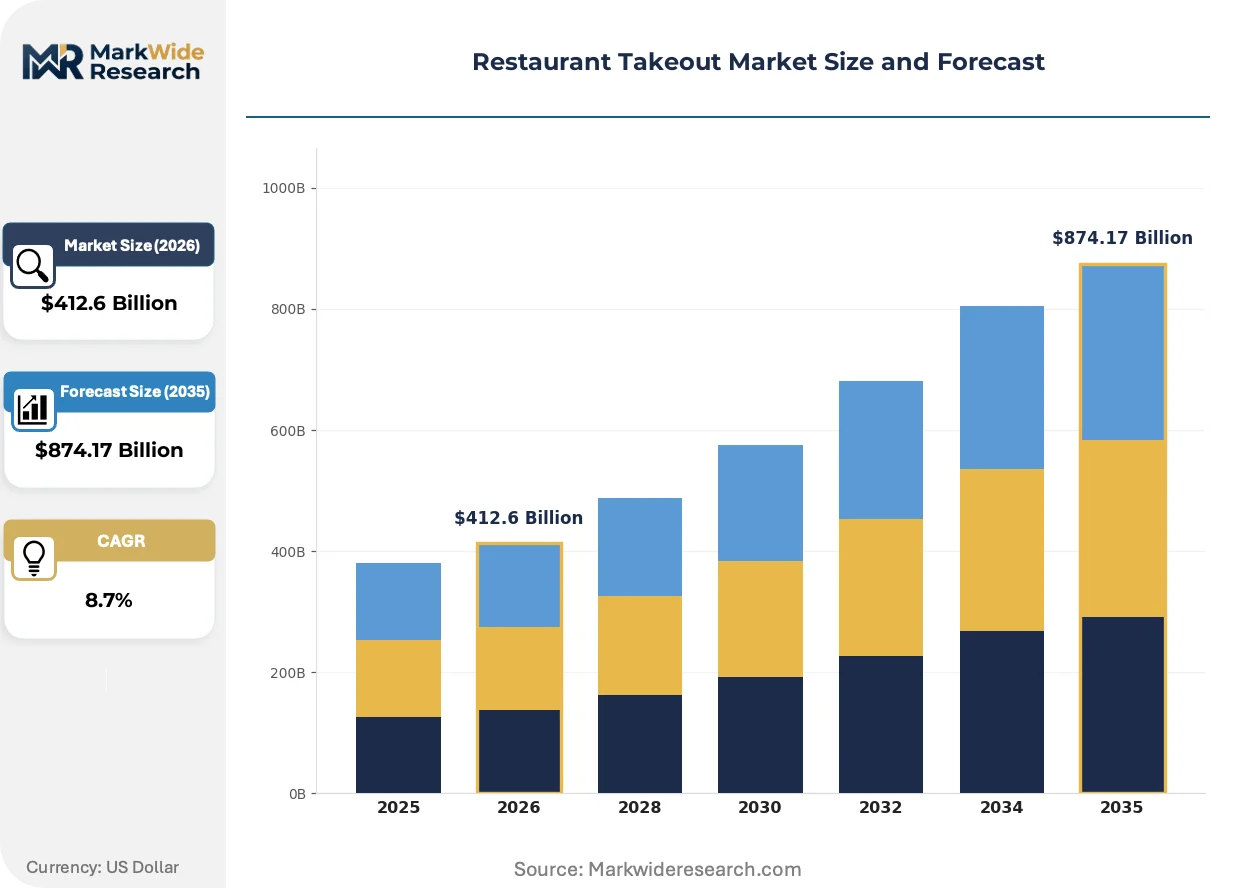
Market Dynamics
Digital ordering infrastructure and FDA food safety modernization rules are restructuring how restaurant takeout operators configure packaging, logistics, and kitchen workflows to capture off-premise revenue streams.
Growth Catalysts
- Mobile-First Ordering Platforms:Smartphone apps with predictive algorithms and loyalty integration are converting phone-based transactions into higher-ticket digital orders across urban markets.
- Food Code Modernization:FDA standards for temperature control and traceability are elevating packaging specifications that premium operators use to differentiate quality assurance.
- Ghost Kitchen Proliferation:Municipal zoning adaptations in dense metropolitan areas are enabling delivery-only facilities that expand kitchen capacity without dining room capital.
Market Restraints
- Packaging Cost Volatility:Petroleum-based container materials and compostable alternatives face input price swings that compress margin on standardized menu items.
- Driver Classification Uncertainty:State-level labor rulings on independent contractor status threaten last-mile cost structures in California, New York, and Illinois.
- Thermal Performance Limits:Current insulating materials cannot reliably maintain 140°F hot-holding thresholds beyond 45-minute delivery windows in extreme weather.
Strategic Opportunities
- Suburban Market Expansion:Households in secondary US metropolitan rings show rising takeout frequency with lower competitive density than urban cores.
- Smart Packaging Integration:RFID-enabled containers that communicate temperature status to consumers are creating premium positioning opportunities.
- Aggregation Platform Partnerships:Third-party marketplaces with embedded financing tools are opening capital-light expansion paths for regional restaurant groups.
Industry Challenges
- Cross-Contamination Protocol Gaps:Staff training on allergen separation during high-volume off-premise assembly remains inconsistent across multi-unit operations.
- Legacy POS Integration Friction:Kitchen display systems from established vendors require expensive middleware to synchronize with modern delivery dispatch software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Restaurant Takeout Market |
| Market Size in 2026 | $412.6 Billion |
| Market Size in 2035 | $874.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Dine-in, Takeaway, Delivery, Drive-thru Cuisine Type: Italian, Mexican, Chinese, American Ordering Channel: Website, Mobile App, Phone Order, In-person Customer Segment: Families, Professionals, College Students, Seniors |
| Companies Covered | Shake Shack, Marco's Pizza, Domino's, Dutch Bros, Raising Cane's, Wingstop, Cava, Paris Baguette, Jersey Mike's, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Restaurant Takeout Market Evolving Landscape
Restaurant takeout is experiencing fundamental restructuring as digital infrastructure, regulatory compliance requirements, and consumer expectations for transparency converge on operational workflows.
Reusable container programs with deposit-return mechanisms are modularizing how operators approach sustainability compliance and customer retention simultaneously. Fast-casual chains in Seattle and San Francisco are piloting these systems to preempt municipal single-use packaging bans. The modularizing architecture separates packaging logistics from food production, enabling third-party services to manage container circulation.
FDA Food Code updates regarding time-temperature abuse documentation are compelling operators to implement digital logging systems. Chain restaurants with centralized quality assurance functions are deploying Bluetooth-enabled probes that auto-upload holding data to cloud compliance dashboards. Smaller independent operators in Texas and Florida are slower to adopt due to capital constraints, creating a compliance capability gap.
Subscription-based meal planning is altering how households allocate food budgets across delivery and grocery channels. Young professional segments in Boston and Washington DC are consolidating weekly meal decisions into platform-native subscription bundles. This behavior compresses switching costs between restaurant brands and elevates loyalty program sophistication as the primary retention mechanism.
Restaurant Takeout Market Segmentation
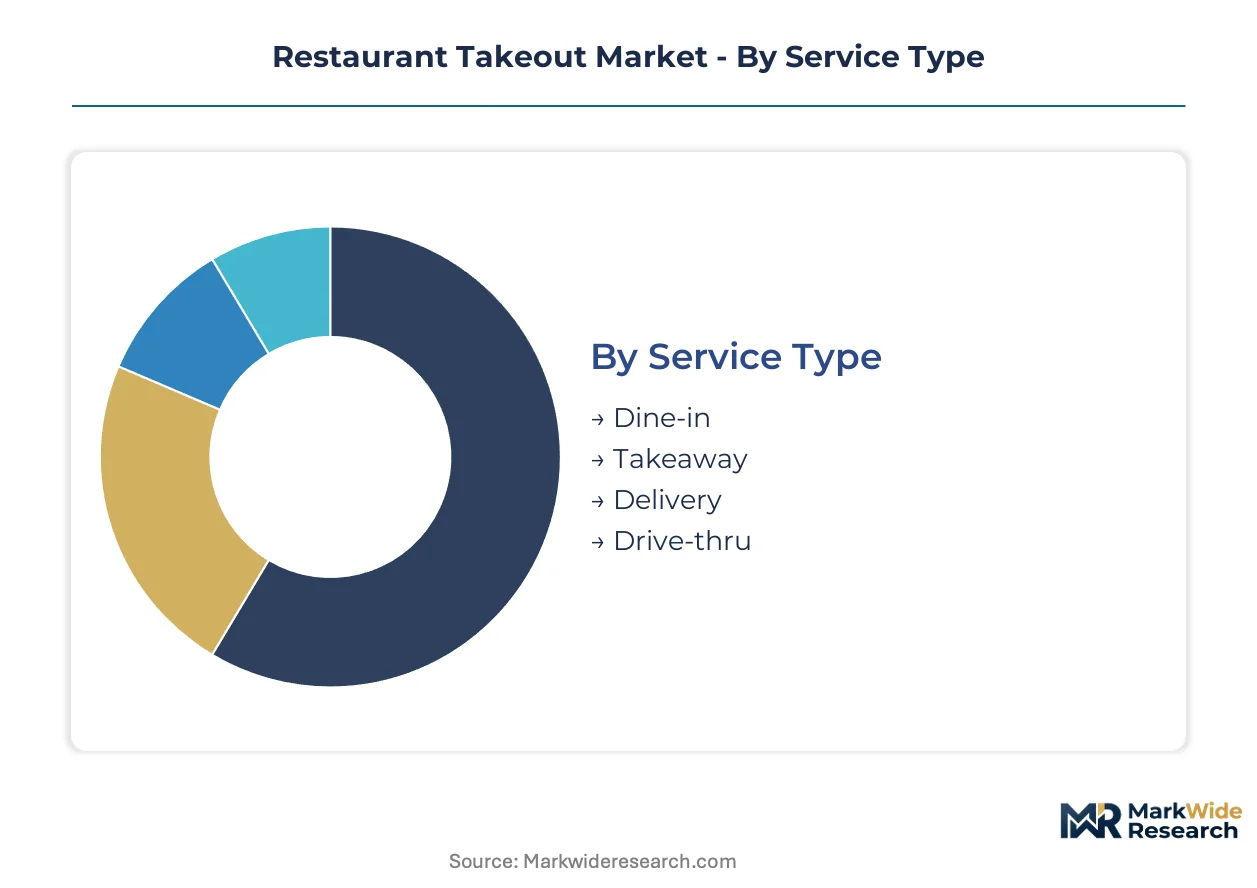
Restaurant takeout operators configure their kitchen workflows, packaging specifications, and delivery partnerships around distinct service modalities and customer profiles. Segmentation reveals where margin pools concentrate and which operational investments yield disproportionate returns across fulfillment types and ordering channels.
Service Type:
Customer urgency and labor cost exposure determine how operators prioritize service mode investments and staffing models.
- Takeaway:Counter pickup orders require minimal labor overhead while capturing full margin without platform commission fees. Demand concentrates in urban corridors where professionals integrate pickup into commute patterns, driven by time compression and parking cost avoidance.
- Delivery:Third-party and captive fleet fulfillment extends reach to suburban households but compresses margins through per-order fees and insurance costs. Growth clusters in secondary metropolitan rings where kitchen density lags residential demand, constrained by driver availability during peak windows.
- Dine-in:On-premise consumption anchors brand experience and beverage attachment but carries fixed real estate costs that dilute returns during off-peak hours.
- Drive-thru:Vehicle-based ordering captures suburban and exurban traffic flow with speed-of-service premiums that justify dedicated lane infrastructure.
Takeaway leads on scale; delivery leads on momentum.
Cuisine Type:
Menu engineering and packaging requirements vary substantially across culinary traditions, with travel tolerance and preparation speed determining off-premise viability.
- American:Burgers, sandwiches, and fried items dominate volume through standardized preparation and forgiving holding characteristics. Demand concentrates in suburban markets where family-oriented occasions drive large-ticket orders, supported by established supply chains for proteins and buns.
- Chinese:Stir-fry and noodle formats adapt well to containerization and reheat cycles, with regional variations in sauce viscosity affecting packaging seal requirements. Expansion is fastest in metropolitan areas with established Asian-American population centers.
- Italian:Pasta and pizza categories face texture degradation challenges during transit, requiring specialized vented packaging to manage moisture retention.
- Mexican:Bowl and burrito formats travel efficiently but require strict temperature separation between hot proteins and cold salsas to maintain food safety thresholds.
American cuisine leads on scale; Chinese cuisine leads on momentum.
Ordering Channel:
Technology adoption curves and customer lifetime value calculations shape where operators direct platform development resources.
- Mobile App:Native smartphone applications with stored payment and reorder history capture the highest frequency users and enable predictive personalization. Demand concentrates among professionals aged 25-40 in dense urban markets, driven by loyalty program integration and checkout friction elimination.
- Website:Browser-based ordering retains importance for first-time customers and corporate catering procurement, with desktop usage persisting in business district lunch corridors.
- Phone Order:Voice-based transactions now serve primarily senior demographics and complex customization requests that resist digital menu structuring.
- In-person:Counter ordering at pickup maintains relevance for cash-preferred segments and same-day impulse occasions.
Mobile app leads on scale; website leads on momentum.
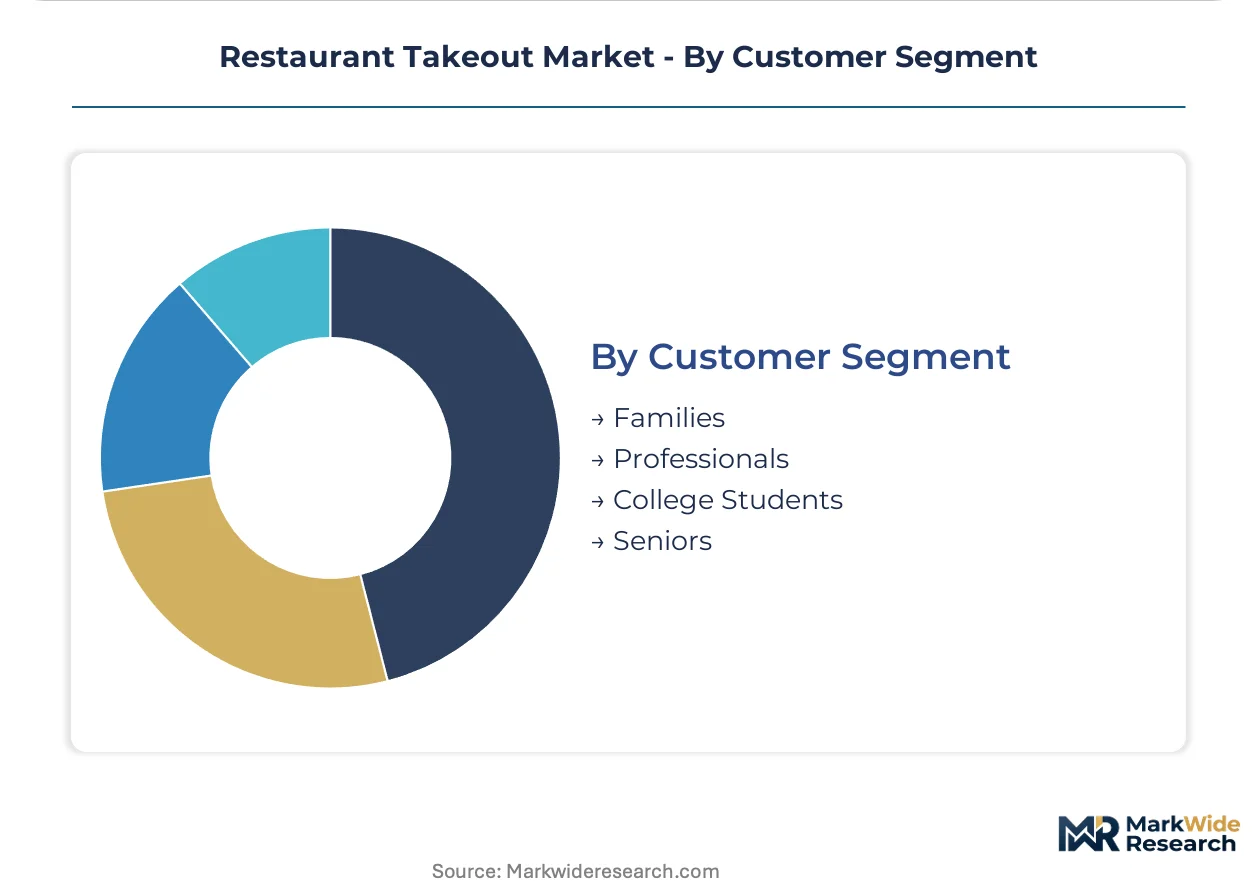
Customer Segment:
Household composition and work patterns dictate order frequency, ticket size, and sensitivity to delivery fees versus time savings.
- Professionals:Time-constrained white-collar workers generate the highest per-capita order frequency through lunch and dinner occasions, prioritizing speed and dietary customization over price minimization. Demand concentrates in central business districts and transit-adjacent residential towers.
- Families:Multi-person households drive large-ticket orders with menu variety requirements, favoring value bundles and predictable preparation times for coordinated meal occasions.
- College Students:Price-sensitive younger consumers with irregular schedules generate volume through late-night windows and promotional responsiveness, though loyalty remains transient.
- Seniors:Smaller household sizes and fixed incomes produce lower frequency but higher margin per order when health-conscious menu options are available.
Professionals lead on scale; families lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Urban kitchen labor pools and delivery driver networks concentrate demand across metropolitan corridors where density justifies infrastructure investment. Workforce availability in food preparation and last-mile logistics anchors market viability more than raw consumer demand. Regulatory frameworks governing driver classification and food safety certification shape operational economics in each jurisdiction.
United States
Professional households in coastal metros generate the highest per-capita order frequency through integrated commute-and-pickup patterns. FDA Food Code modernization elevates packaging compliance costs that national chains absorb more readily than independents. Kitchen density in Manhattan, Brooklyn, and San Francisco sustains ghost kitchen proliferation with municipal zoning adaptations enabling delivery-only facilities.
China
Meituan and Ele.me platform penetration drives mobile-first ordering behavior across tier-one and tier-two urban centers. SAMR antitrust oversight and food safety licensing under GB standards tighten operational requirements for cloud kitchen operators. Shanghai and Beijing metropolitan clusters concentrate dark kitchen infrastructure with municipal authorities streamlining commercial kitchen permitting in repurposed industrial zones.
United Kingdom
Office worker return-to-office patterns in London and Manchester reactivate midday takeaway demand following pandemic-era remote work prevalence. Food Standards Agency hygiene rating schemes and municipal trading permits structure compliance costs for delivery-only entrants. The London Borough of Camden and City of Westminster host dense kitchen clusters where rent premiums reflect last-mile proximity to residential towers.
Germany
Dual-income professional households in Berlin, Munich, and Hamburg sustain elevated delivery frequency despite higher platform fee sensitivity than Anglo markets. EFSA-aligned food contact material regulations and Bundesrat implementation of packaging waste ordinances reshape container sourcing decisions. Berlin's Kreuzberg and Neukölln districts concentrate independent operator kitchens with Lieferando platform integration driving digital order capture.
Japan
Single-person households in Tokyo and Osaka generate consistent demand for portion-optimized takeaway formats suited to compact residential units. Ministry of Health, Labour and Welfare food sanitation law amendments tighten traceability documentation for delivery intermediaries. The Shibuya and Shinjuku wards sustain high kitchen density with municipal authorities piloting streamlined permitting for shared commercial kitchen facilities.
Restaurant Takeout Market Competitive Landscape
The competitive structure tilts toward digitally native specialists with captive technology infrastructure. National pizza chains and chicken-wing specialists dominate volume through vertically integrated delivery fleets and predictive ordering algorithms. Three archetypes define positioning: platform-dependent regional brands, captive-fleet national operators, and fast-casual format innovators with travel-optimized menu architecture. Consolidation pressure operates through technology acquisition and ghost kitchen network expansion rather than traditional M&A.
Among US-based operators with national scale, Domino's, Wingstop, and Cava exemplify divergent strategic paths. Domino's anchors the captive-fleet archetype with proprietary logistics infrastructure insulating margin from third-party commission structures. Wingstop occupies a position within the delivery-native specialist tier, concentrating menu breadth to simplify kitchen workflow and packaging standardization. Cava represents the fast-casual format innovation vector, with customizable bowl configurations engineered for temperature retention and visual integrity during transit. Shake Shack, Marco's Pizza, and Raising Cane's sit within regional expansion trajectories, each pursuing density-building strategies in secondary metros before platform-dependent scaling. Paris Baguette and Jersey Mike's illustrate bakery-café and sandwich-specialist positioning respectively, with format constraints shaping their off-premise feasibility. Dutch Bros anchors beverage-forward takeaway with drive-thru infrastructure optimized for speed-of-service rather than meal-complexity.
| Leading Market Players |
|---|
| Shake Shack |
| Marco's Pizza |
| Domino's |
| Dutch Bros |
| Raising Cane's |
| Wingstop |
| Cava |
| Paris Baguette |
| Jersey Mike's |
| Others |
Value Network & Pricing Analysis
Platform commission consolidation among DoorDash and Uber Eats is forcing restaurant operators to renegotiate fulfillment economics and source packaging from lower-cost Asian manufacturers. This demand compression cascades into supply chain restructuring as operators trade premium domestic suppliers for offshore alternatives that preserve margin on standardized menu items.
Pricing Analysis
Bundled delivery-plus-platform-fee service splits from unbundled counter-pickup transactions create divergent margin structures across service modalities. Three-tier pricing separates premium temperature-assured packaging from standard compostable containers and economy petroleum-based alternatives. Pricing pressure stems from driver wage reclassification rulings in California and New York that inflate last-mile costs. Families with multi-person orders show lowest price sensitivity while college students demand promotional thresholds before conversion.
Supply Chain Analysis
Freight cost volatility on transpacific container routes is reshaping how US operators source temperature-retentive packaging from Chinese, Vietnamese, and Thai manufacturers. Raw material dependencies center on petroleum-derived insulating foams, molded fiber pulp, and RFID-enabled smart labels. Single-source vulnerability concentrates in Southeast Asian molded fiber capacity subject to monsoon season production interruptions. Distribution runs through third-party logistics providers with cold-chain capabilities rather than direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Restaurant takeout economics favor margin expansion through ghost kitchen densification and premium packaging tier adoption that captures willingness-to-pay for quality assurance. Labor cost compression in secondary metropolitan markets enables unit-level profitability improvements without ticket price escalation.
For Market Incumbents: Extend captive delivery fleet coverage into suburban rings where third-party commission avoidance preserves margin. Consolidate kitchen display system vendors to reduce middleware integration costs from legacy POS fragmentation. Defend against emerging cloud kitchen operators through exclusive real estate partnerships with municipal zoning authorities.
For New Entrants and Emerging Players: Third-party marketplace partnerships offer capital-light customer acquisition without proprietary app development burden. White-space opportunity concentrates in mid-sized metropolitan areas with household income above national median and limited fast-casual density. Target professionals aged 30-45 through subscription-native meal bundles that compress weekly decision fatigue.
For Investors and Strategic Acquirers: Asymmetric upside sits with vertically integrated delivery specialists controlling both kitchen capacity and last-mile logistics. Long-term viability favors operators with proprietary technology infrastructure insulating margin from platform dependency. Acquisition focus should target regional chains with demonstrated unit economics and scalable bowl-format menu architecture. Signal to monitor: municipal single-use packaging ban implementation velocity in coastal states.
| Strategic Initiative | Industry Significance |
|---|---|
| Ghost Kitchen Network Expansion | Delivery-only facilities in secondary metros bypass dining room capital requirements while capturing off-peak demand. |
| Smart Packaging Integration | RFID-enabled temperature monitoring creates premium positioning that justifies packaging cost pass-through to consumers. |
| Subscription Meal Bundling | Platform-native weekly commitments from Boston and Washington DC professionals compress customer acquisition costs. |
| Captive Fleet Densification | Proprietary driver networks in suburban rings eliminate DoorDash and Uber Eats commission structures. |
| Regulatory Compliance Preemption | Early adoption of FDA Food Code documentation systems creates competitive moat against slower independent operators. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged restaurant operations directors, third-party delivery platform account managers, packaging procurement leads, municipal health department officials, and ghost kitchen facility operators. Secondary validation drew from FDA Food Code guidance documents, state health department permitting databases, SEC filings from publicly traded restaurant groups, and municipal zoning ordinance repositories. Bottom-up unit economics modeling triangulated against top-down market size estimates from trade association membership data.
Segment-weighting approaches applied differential growth assumptions across service modalities, cuisine types, and ordering channels. The analytical framework modeled takeaway, delivery, dine-in, and drive-thru fulfillment types alongside American, Chinese, Italian, and Mexican cuisine categories. Mobile app, website, phone, and in-person ordering channels received distinct penetration curves across professional, family, college student, and senior customer segments. CAGRs derived from historical order frequency data and projected household formation patterns. Forecast inputs incorporated driver wage litigation trajectories and compostable packaging cost curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to driver classification rulings and municipal packaging bans. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Saudi Arabia Cloud Kitchen Market
Food Service
Pizza Oven Market
Food Service
North America Food Service Market
Food Service
Food Trays Market
Food Service
US Restaurant Point of Sale Solution Market
Food Service
Cloud Kitchen Market
Food Service
Electric Tiffin Market
Food Service
Smokeless Grill Market
Food Service
Chinese Takeout Market
Food Service
Commercial Kitchen Appliances Market
Food Service
Thailand Food Service Market
Food Service
Food Away from Home Market
Food Service
Self-Heating Hot Pot Market
Food Service
North America Food Platform-To-Consumer Delivery Market
Food Service
Foodservice Coffee Market
Food Service
United Arab Emirates Full Service Restaurants Market