
 Beverage Coaster Market | 2026-2036
Beverage Coaster Market Size, Share, and Industry Trends Forecast 2026-2036
Beverage Coaster Market Analysis
The beverage coaster market is decoupling into two distinct supply tiers: premium artisanal producers serving hospitality branding contracts versus high-volume commodity manufacturers filling institutional foodservice channels. Huhtamaki leverages its global pulp-molded packaging infrastructure to dominate disposable coaster supply for quick-service restaurants. Coaster Factory specializes in custom-printed pulpboard for North American craft breweries, sustaining margin through short-run digital printing capabilities. Thirstystone Resources anchors the premium natural stone and ceramic segment, occupying shelf space in specialty retail through licensed design partnerships.
A beverage coaster is a flat, absorbent or non-slip disc placed beneath drinking vessels to protect surfaces from condensation, heat, and abrasion; typical specifications include moisture absorption rates above 0.5 g/cm² for pulpboard variants and heat resistance to 120°C for silicone grades. Cardboard and wood variants lead volume due to cost efficiency and printability for promotional applications, though silicone is gaining traction in home segments for durability and dishwasher compatibility. The eco-friendly design subcategory is expanding fastest as hotels and restaurants replace laminated coasters with uncoated, compostable alternatives to meet procurement standards.
The US EPA regulates pulpboard manufacturing emissions under Clean Air Act guidelines, while the EU F-Gas Regulation indirectly shapes silicone coaster supply chains through fluorinated compound restrictions. FDA food-contact substance notifications govern barrier coatings on printed coasters distributed in American foodservice channels. Stakeholders must monitor evolving extended producer responsibility frameworks in Europe and North America to determine whether biodegradable material investments or closed-loop collection programs offer stronger competitive insulation against compliance cost escalation.
Market Dynamics
EU Green Deal packaging waste directives are forcing manufacturers to abandon laminated pulpboard for uncoated biodegradable substrates, compressing legacy supply chains while opening certification-driven procurement channels.
Growth Catalysts
- Boutique Hospitality Branding:Independent hotels in Germany and Austria now specify custom-printed coasters as core experiential design elements, mandating short-run digital capabilities from suppliers.
- REACH Compliance Migration:Silicone coaster producers across Europe are reformulating barrier coatings to eliminate fluorinated compounds, creating first-mover advantage for compliant molders.
- Beer Hall Culture Sustenance:German federal recycling mandates maintain per-capita coaster consumption at levels unmatched elsewhere, insulating regional pulpboard demand from global commodity cycles.
Market Restraints
- Pulp Price Volatility:Northern European softwood pulp contracts fluctuate with energy input costs, squeezing margin on disposable cardboard variants.
- Silicone Feedstock Concentration:Platinum-cured silicone precursor supply clusters in China and Germany, exposing Western molders to cross-border logistics friction.
- Absorption Rate Ceiling:Uncoated biodegradable substrates cannot achieve the 0.5 g/cm² moisture absorption standard without synthetic barriers, limiting functional parity.
Strategic Opportunities
- Indian Foodservice Penetration:Quick-service restaurant chains in Mumbai and Bangalore lack standardized coaster procurement, presenting volume openings for pulp-molded entrants.
- Extended Producer Responsibility Tailwinds:France's AGEC law mandates corporate accountability for packaging end-of-life, rewarding closed-loop coaster collection programs with preferential shelf access.
- Digital-NFC Convergence:Embedded near-field communication chips in ceramic coasters enable tap-to-order functionality, rewriting the value proposition for premium hospitality contracts.
Industry Challenges
- Composting Certification Timelines:TÜV Austria and BPI verification processes for biodegradable substrates extend 14-18 months, delaying product launches.
- Legacy Print Equipment Stranding:Rotogravure lines optimized for laminated pulpboard cannot pivot to uncoated stock without six-figure retrofit investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beverage Coaster Market |
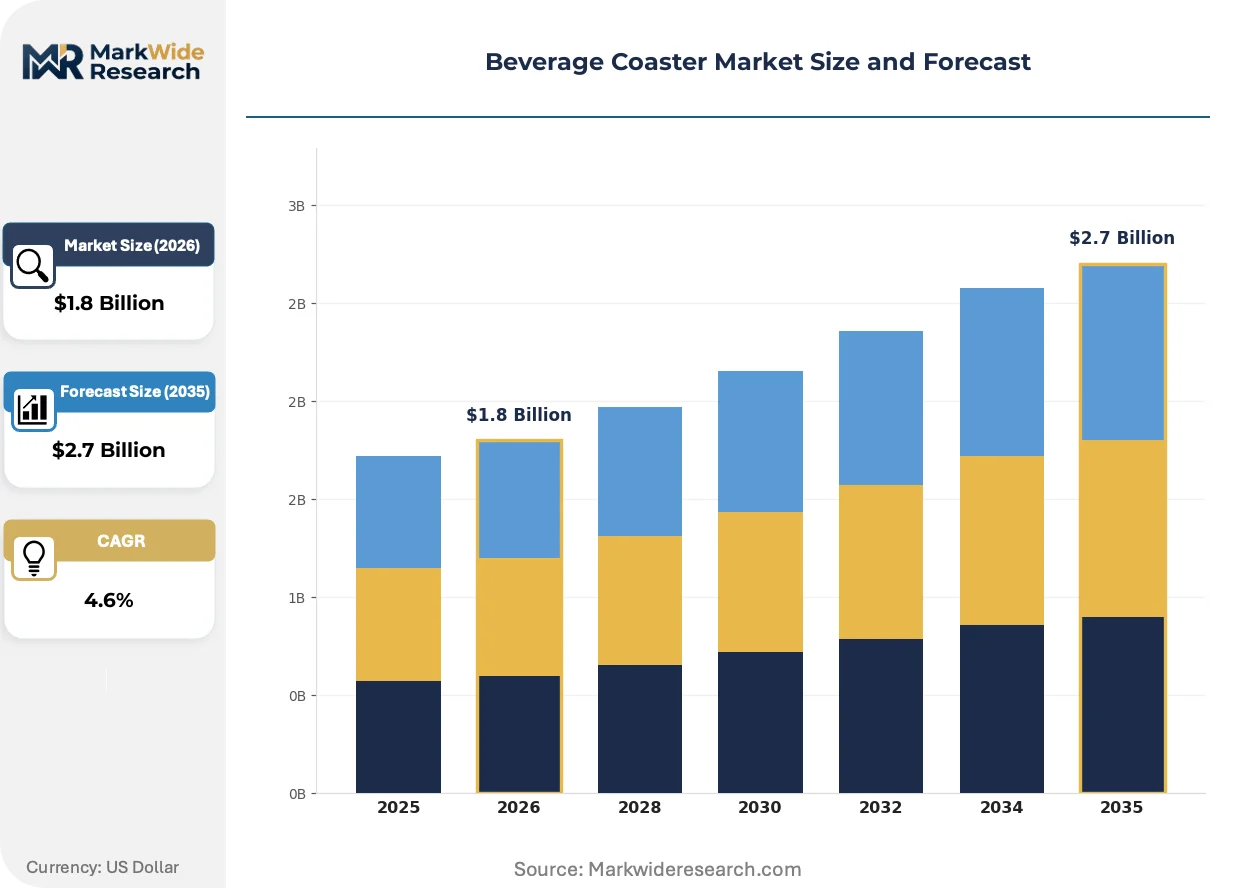
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Cardboard, Wood, Silicone, Cork Shape: Round, Square, Hexagonal, Custom Design: Printed, Plain, Textured, Eco-friendly End User: Restaurants, Bars, Homes, Hotels |
| Companies Covered | KATZ Group, Coaster Factory, Huhtamaki, Alfred Mank Inc., Dacasso Limited Inc., Coaster Company of America, Barconic, Thirstystone Resources, Inc., Hoffmaster Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beverage Coaster Market Emerging Trajectories
Active material science and embedded connectivity are compressing the traditional divide between disposable functional items and durable experiential objects.
Plant-fiber molding is rewriting substrate economics. Advanced hemp and bagasse pulps now achieve tensile strength parity with wood-based alternatives at 30% lower carbon intensity. German craft breweries and Copenhagen cocktail bars have adopted these materials for flagship locations. The technology is compressing the premium-commodity price spread that previously separated sustainable from conventional coasters.
EU F-Gas Regulation amendments are accelerating silicone formulation turnover. The 2024 restriction on hydrofluorocarbon propellants forces molders to validate water-based cure systems. Premium home goods retailers in France and Benelux now stock only F-Gas-compliant silicone coasters. Kitchenware distributors are demanding batch-level compliance documentation before listing new products.
Direct-to-venue procurement platforms are disintermediating traditional hospitality supply channels. Independent hotels in Barcelona and Lisbon now source custom coasters through specialized B2B marketplaces that aggregate digital print capacity. These platforms compress design-to-delivery cycles from six weeks to eight days. The model is most visible in Southern European markets where fragmented hotel ownership resists consolidated distributor relationships.
Beverage Coaster Market Segmentation
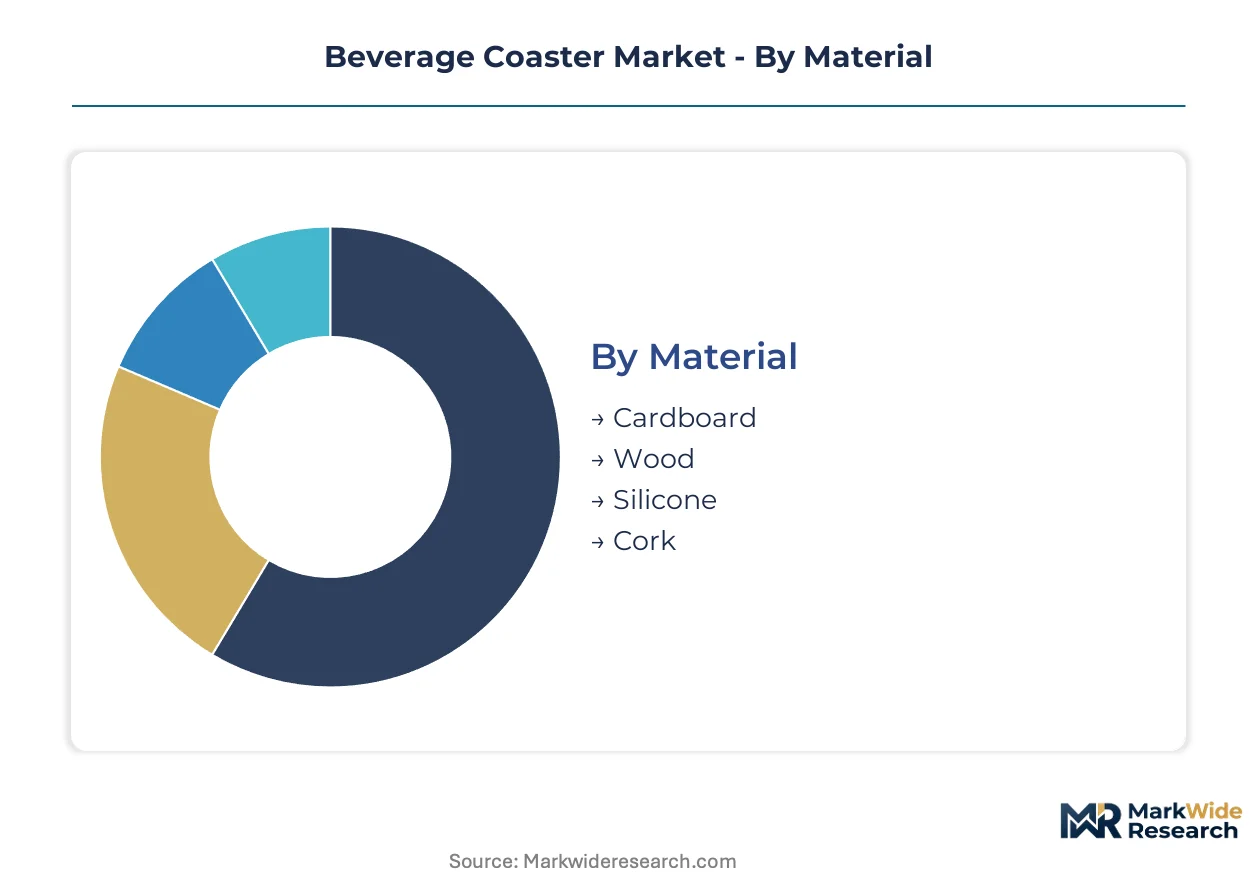
Material chemistry and end-use durability requirements split procurement into disposable promotional channels versus premium hospitality contracts. Shape and design specifications further fragment demand between standardized foodservice volumes and bespoke experiential installations.
Material:
Cost tier and functional durability dictate buyer selection across institutional and consumer channels.
- Cardboard:Pulpboard substrates achieve moisture absorption above 0.5 g/cm² through pressed fiber density. German beer halls and quick-service chains in Mumbai specify uncoated biodegradable grades to satisfy EU Green Deal procurement mandates and emerging corporate sustainability frameworks.
- Silicone:Platinum-cured formulations withstand heat to 120°C and enable dishwasher compatibility for home segments. French and Benelux kitchenware distributors now require F-Gas Regulation compliance documentation before listing, filtering non-compliant molders from premium retail channels.
- Wood:Hard maple and bamboo variants serve craft brewery tasting rooms seeking tactile warmth.
- Cork:Portuguese and Spanish harvests supply natural grip surfaces for wine-focused hospitality.
Volume sits with cardboard; growth tilts toward silicone.
Shape:
Application context determines whether standardization or customization delivers procurement economics.
- Round:90mm diameter dominates foodservice for universal glassware compatibility. Barcelona and Lisbon independent hotels source through B2B marketplaces compressing design-to-delivery cycles to eight days.
- Custom:Die-cut profiles enable branded experiential elements for boutique hospitality. Copenhagen cocktail bars specify irregular perimeters as flagship location differentiators.
- Square:Maximizes print real estate for promotional messaging in institutional channels.
- Hexagonal:Geometric novelty supports premium retail shelf differentiation.
Round captures institutional volume; custom shapes expand most quickly in hospitality branding.
Design:
Surface treatment separates commodity disposable supply from value-added experiential contracts.
- Eco-friendly:Uncoated hemp and bagasse pulps achieve tensile parity with wood-based alternatives at reduced carbon intensity. German craft breweries and Copenhagen bars have adopted these for flagship locations, compressing the historical premium-commodity price spread.
- Printed:Short-run digital capabilities enable custom branding for independent hotel chains. Rotogravure lines face stranding risk as laminated stock loses certification viability.
- Plain:Unprinted substrates serve cost-minimized institutional procurement.
- Textured:Embossed surfaces support premium home goods positioning.
Printed designs dominate current revenue; eco-friendly specifications gain share fastest.
End User:
Procurement sophistication and volume scale vary sharply across institutional and consumer channels.
- Hotels:Boutique chains specify coasters as core experiential design elements mandating short-run digital capabilities. Direct-to-venue platforms disintermediate traditional distributor relationships in Southern European markets.
- Restaurants:Quick-service chains in Bangalore and Mumbai lack standardized procurement, presenting volume openings for pulp-molded entrants.
- Bars:German federal recycling mandates sustain per-capita consumption unmatched elsewhere.
- Homes:Durability requirements favor silicone and ceramic for repeat-use scenarios.
Restaurants anchor volume scale; hotels drive margin expansion through customization premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors the industry's demand concentration through its beer hall density and federal recycling mandates that sustain unmatched per-capita coaster consumption.
Germany
Bavarian beer halls and Berlin boutique hotels drive custom-printed procurement as experiential design elements. The EU Green Deal packaging waste directives pressure manufacturers toward uncoated biodegradable substrates. Hamburg pulpboard converters face margin compression from legacy rotogravure equipment stranding.
United States
Craft brewery tasting rooms in Portland and Denver specify tactile wood and ceramic variants for brand differentiation. FDA food-contact substance notifications govern barrier coatings on printed coasters distributed through American foodservice channels. Chicago quick-service chains source high-volume disposable grades through consolidated distributor networks.
France
Parisian cocktail bars and Lyon hospitality clusters adopt F-Gas-compliant silicone coasters for premium home goods positioning. The AGEC law mandates corporate accountability for packaging end-of-life, rewarding closed-loop collection programs. Marseille kitchenware distributors demand batch-level compliance documentation before listing new products.
India
Quick-service restaurant chains in Mumbai and Bangalore lack standardized coaster procurement, presenting volume openings for pulp-molded entrants. The country's food safety regulator governs food-contact materials in commercial foodservice channels. Ahmedabad packaging converters target institutional penetration through cost-optimized uncoated grades.
China
Platinum-cured silicone precursor supply clusters in Guangdong and Jiangsu provinces, exposing Western molders to cross-border logistics friction. The country's dual carbon goals accelerate biodegradable substrate investments across packaging sectors. Shenzhen manufacturers dominate mold fabrication for ceramic and silicone variants exported to European hospitality markets.
Beverage Coaster Market Vendor Landscape
Premium-margin players sit above commodity-margin players across material sophistication and customization capability. The vendor base splits between pulp-molded volume specialists and artisanal producers serving short-run digital contracts. Three archetypes dominate: global packaging conglomerates with integrated pulp infrastructure, regional craft-focused fabricators, and specialty material specialists in stone and ceramic. Competitive moves concentrate on certification-driven procurement channel access and direct-to-venue platform disintermediation.
Within the craft-focused tier, Coaster Factory and Thirstystone Resources exemplify divergent specialization strategies. Coaster Factory occupies a position among North American short-run digital fabricators serving brewery branding contracts. Thirstystone Resources anchors the premium natural material segment through licensed design partnerships. Huhtamaki represents the scale-driven archetype, leveraging global pulp-molded packaging infrastructure to dominate disposable supply for quick-service restaurant chains.
| Leading Market Players |
|---|
| KATZ Group |
| Coaster Factory |
| Huhtamaki |
| Alfred Mank Inc. |
| Dacasso Limited Inc. |
| Coaster Company of America |
| Barconic |
| Thirstystone Resources, Inc. |
| Hoffmaster Group, Inc. |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap converters across Northern Europe anchor supply discipline through generational capital structures that resist short-term margin compression, translating pulp price volatility into selective contract repricing rather than volume wars. Their ownership model buffers pricing power against private-equity-rolled competitors chasing quarterly yield.
Pricing Analysis
Value-based pricing anchored to experiential outcomes—boutique hotels paying per-customer-impression rather than per-unit—separates premium hospitality contracts from commodity foodservice tiers. Certification grade and customization level drive price differentiation, with EU Green Deal-compliant uncoated substrates commanding premiums over laminated legacy stock. Cost compression in disposable cardboard tiers intensifies as Northern European softwood pulp contracts fluctuate with energy input costs. Quick-service chains in emerging markets exhibit highest price sensitivity; German beer halls and Copenhagen cocktail bars show lowest, prioritizing brand alignment over unit economics.
Supply Chain Analysis
Reverse-logistics infrastructure for closed-loop coaster collection programs in France and Benelux creates secondary material flows that subsidize primary production economics. Geographic supply concentrates in Germany, China, and India—Hamburg pulpboard converters, Guangdong silicone precursor clusters, and Ahmedabad packaging specialists each anchor regional procurement. Raw material dependencies span Northern European softwood pulp, platinum-cured silicone precursors, and Portuguese cork harvests. Single-source vulnerability in Chinese silicone feedstock exposes Western molders to cross-border logistics friction. Distribution runs through consolidated foodservice distributors in North America, direct-to-venue B2B platforms in Southern Europe, and fragmented dealer networks in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Composting certification bottlenecks constrain biodegradable substrate supply, propping pricing premiums for TÜV Austria and BPI-verified producers while legacy laminated stock faces procurement exclusion.
For Market Incumbents: To counter rotogravure equipment stranding from EU Green Deal mandates, accelerate six-figure digital retrofit investments and secure TÜV Austria certification pipelines before 14-18 month verification timelines strand competitors. Backward integration into hemp and bagasse pulp sourcing insulates margin from wood-based fiber volatility. For New Entrants and Emerging Players: Boutique hotel chains in Barcelona and Lisbon represent the most penetrable buyer archetype, fragmented ownership resists consolidated distributor relationships and compresses design-to-delivery tolerance to eight days. Target direct-to-venue B2B marketplace aggregation as primary go-to-market angle, bypassing legacy hospitality supply channels entirely. For Investors and Strategic Acquirers: Distressed-cycle entries favor craft-focused digital fabricators in North America with installed short-run print capacity and brewery contract backlogs. Long-term viability across the analysis window hinges on certification infrastructure ownership rather than volume scale. Watch EU F-Gas Regulation amendment timing as inflection indicator for silicone coaster supply chain restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Composting Certification Investment | TÜV Austria and BPI verification opens EU Green Deal procurement channels closed to laminated competitors. |
| Digital Print Capacity Expansion | Short-run capabilities capture boutique hospitality contracts mandating eight-day design-to-delivery cycles. |
| Hemp and Bagasse Pulp Integration | Plant-fiber molding achieves tensile parity with 30% lower carbon intensity, compressing premium-commodity spreads. |
| Direct-to-Venue Platform Launch | B2B marketplaces disintermediate traditional distributors in Southern European fragmented hotel markets. |
| Closed-Loop Collection Program | France's AGEC law rewards corporate accountability for packaging end-of-life with preferential retail access. |
Methodological Framework
Document review covered EU regulatory filings, FDA food-contact substance notifications, and hospitality procurement databases, complemented by interviews with pulpboard plant managers, boutique hotel brand directors, quick-service restaurant procurement leads, and B2B marketplace operators. Secondary validation drew from trade customs data, SEC filings of listed packaging conglomerates, and extended producer responsibility framework documentation. Bottom-up volume triangulation across material-grade segments reconciled with top-down market sizing.
Segment-level outputs across material, shape, design, and end-user dimensions were generated through structured modeling of procurement pattern shifts and regulatory compliance timelines. CAGRs were derived from elasticity-adjusted demand projections incorporating beer hall consumption baselines and boutique hospitality branding penetration curves. Industry-specific inputs included composting certification pipeline data and silicone formulation turnover schedules under F-Gas Regulation amendments.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU packaging waste directive enforcement intensity and pulp price volatility trajectories. Forecasts reflect documented assumptions regarding certification timeline stability and hospitality sector experiential spending continuity. Practitioners should monitor TÜV Austria verification queue lengths and German federal recycling mandate amendments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Global Vending Machine Market
Food Service
Global Online Food Ordering Market
Food Service
Commercial Beverage Dispenser Market
Food Service
Europe Vending Machine Market
Food Service
Onboard Rail Catering Market
Food Service
A La Carte Market
Food Service
United States Food Truck Market
Food Service
Food and Grocery Retail Market
Food Service
Commercial Deep Fryer Parts and Accessories Market
Food Service
Halal Food and Beverages Market
Food Service
United Kingdom Barbeque Grill Market
Food Service
UAE Food Service Market
Food Service
Restaurant Glassware Market
Food Service
Thailand Food Service Market
Food Service
Shaker Bottles Market
Food Service
Middle East and Africa Online Grocery Delivery Market