
 Europe Pizza Oven Market | 2026-2036
Europe Pizza Oven Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pizza Oven Market Insights
Italian kiln and refractory producers is restructuring supply chains across the Mediterranean basin to secure ceramic fiber and volcanic stone inputs. Morello Forni Italia s.r.l. leverages generational craftsmanship in Modena to dominate the artisan wood-fired segment. Cuppone s.r.l. competes on automated electric deck ovens for high-volume restaurant chains. Euro Restaurant Solutions anchors distribution through Marra Forni's network of showrooms and certified installer programs.
A pizza oven is a thermally insulated chamber engineered to sustain temperatures between 400°C and 500°C, utilizing refractory materials such as biscotto clay or cordierite decks to absorb and radiate heat for rapid dough cooking and leopard-spotted crust formation. Its primary commercial purpose is enabling restaurants to achieve two-minute bake cycles that define authentic Neapolitan pizza certification standards. Electric ovens now lead in new installations across Northern Europe where gas infrastructure restrictions and indoor air quality codes limit combustion options, while wood-fired units sustain premium positioning in Southern European markets where DOC pizza credentials command menu pricing power. Portable installations represent the fastest-growing structural category as food trucks and ghost kitchen operators prioritize mobility and reduced capital commitment.
CE marking under the EU Machinery Directive and Ecodesign regulations govern commercial oven safety and energy performance thresholds across member states, while the EU F-Gas Regulation directly shapes refrigerant-based cooling system specifications in combination oven models. ECHA REACH compliance adds material traceability requirements for imported refractory components and surface coatings. Stakeholders must monitor pending revisions to EU Ecodesign lot 23 standards for professional catering equipment and assess how Italy's national energy efficiency incentives for SME restaurant upgrades will redirect procurement timelines.
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant-based oven configurations while amplifying electric and wood-fired alternatives across European commercial kitchens. Refractory supply concentration in Italy's Emilia-Romagna cluster is forcing operators to reconfigure procurement timelines and inventory strategies.
Growth Catalysts
- Energy efficiency mandates:The EU Ecodesign lot 23 standards for professional catering equipment are accelerating replacement cycles in Germany and France as operators retrofit aging gas decks.
- Artisanal certification demand:DOC pizza credentials in Southern Europe are sustaining premium positioning for wood-fired installations among independent pizzerias in Campania and Sicily.
- Volcanic stone sourcing:Refractory producers in Italy are securing ceramic fiber inputs from Mediterranean basin suppliers to meet sustained production schedules for export markets.
Market Restraints
- Input cost volatility:Cordierite and biscotto clay prices fluctuate with energy-intensive kiln operations in Emilia-Romagna, compressing margins for mid-tier oven assemblers.
- Supply concentration risk:Artisanal oven craftsmanship concentrates in Modena and Naples, creating bottleneck vulnerability for specialized wood-fired units.
- Regulatory friction:ECHA REACH compliance adds material traceability burdens for imported refractory components from non-EU sources.
Strategic Opportunities
- Underpenetrated Northern markets:Sweden and Denmark present whitespace for electric deck ovens as indoor air quality codes restrict combustion options in urban centers.
- Ghost kitchen mobility:Portable oven installations are capturing demand from food truck operators and delivery-only kitchens seeking reduced capital commitment.
- National efficiency incentives:Italy's SME restaurant upgrade programs are redirecting procurement timelines toward certified energy-efficient models.
Industry Challenges
- Refractory craftsmanship gap:Generational kiln-building expertise in Campania is thinning as younger workers exit traditional manufacturing.
- Certification timeline compression:AVPN and other Neapolitan authenticity bodies are extending verification queues as application volumes rise.
- Legacy system integration:Automated electric ovens from Northern European suppliers require costly kitchen reconfiguration for Southern European operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pizza Oven Market |
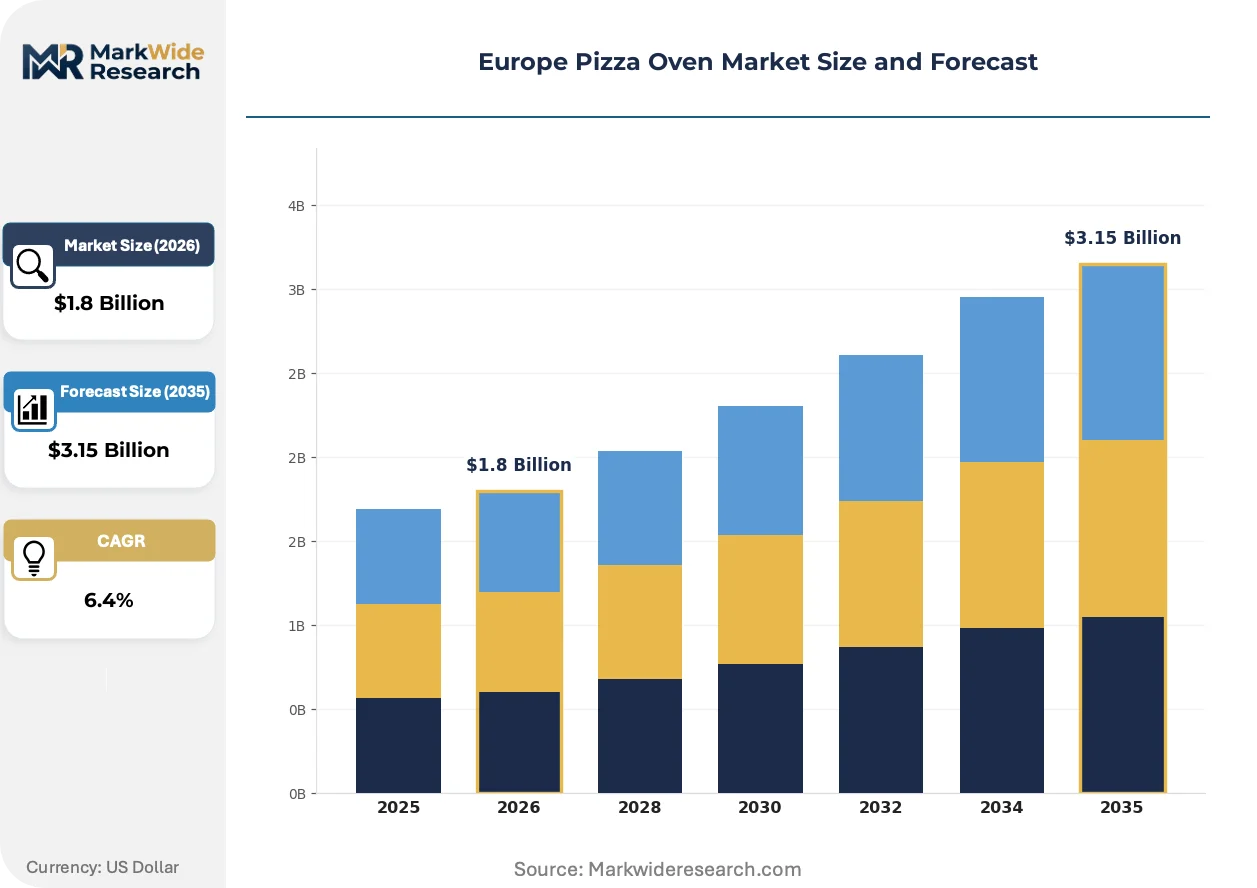
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Wood-fired, Gas, Pellet End User: Restaurants, Home Users, Catering Services, Food Trucks Installation Type: Built-in, Portable, Standalone, Countertop Size: Small, Medium, Large, Extra Large |
| Companies Covered | Morello Forni Italia s.r.l., Forno Bravo, Le Panyol (Fayol S.a.), Wood Stone Corporation, Mugnaini Imports, Inc., Californo, EarthStone Wood-Fire Ovens, Euro Restaurant Solutions (Marra Forni), Cuppone s.r.l., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pizza Oven Market Trends and Innovations
Equipment manufacturers are embedding sensor arrays and connectivity modules into deck ovens to capture operational data and enable predictive maintenance. This shift is compressing the traditional divide between artisanal craftsmanship and automated production.
Smart refractory systems with embedded thermocouples are absorbing real-time temperature data to optimize heat distribution across cooking surfaces. Fast-casual chains in Germany and the Netherlands are deploying these units to standardize output across multiple locations. The technology is absorbing variability in operator skill levels while compressing training cycles for kitchen staff.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in combination oven models with stepped reduction targets through 2030. Manufacturers are redesigning cooling architectures to eliminate refrigerant-dependent systems entirely. Northern European markets with stricter indoor air quality enforcement are experiencing the most accelerated product line transitions.
Buyer purchasing is consolidating toward certified installer networks and showroom-based specification rather than direct equipment procurement. Restaurant groups in France and Spain are routing decisions through Marra Forni's certified programs and Euro Restaurant Solutions distribution channels. Italy retains fragmented direct purchasing among independent pizzerias seeking artisanal provenance verification.
Europe Pizza Oven Market Segmentation
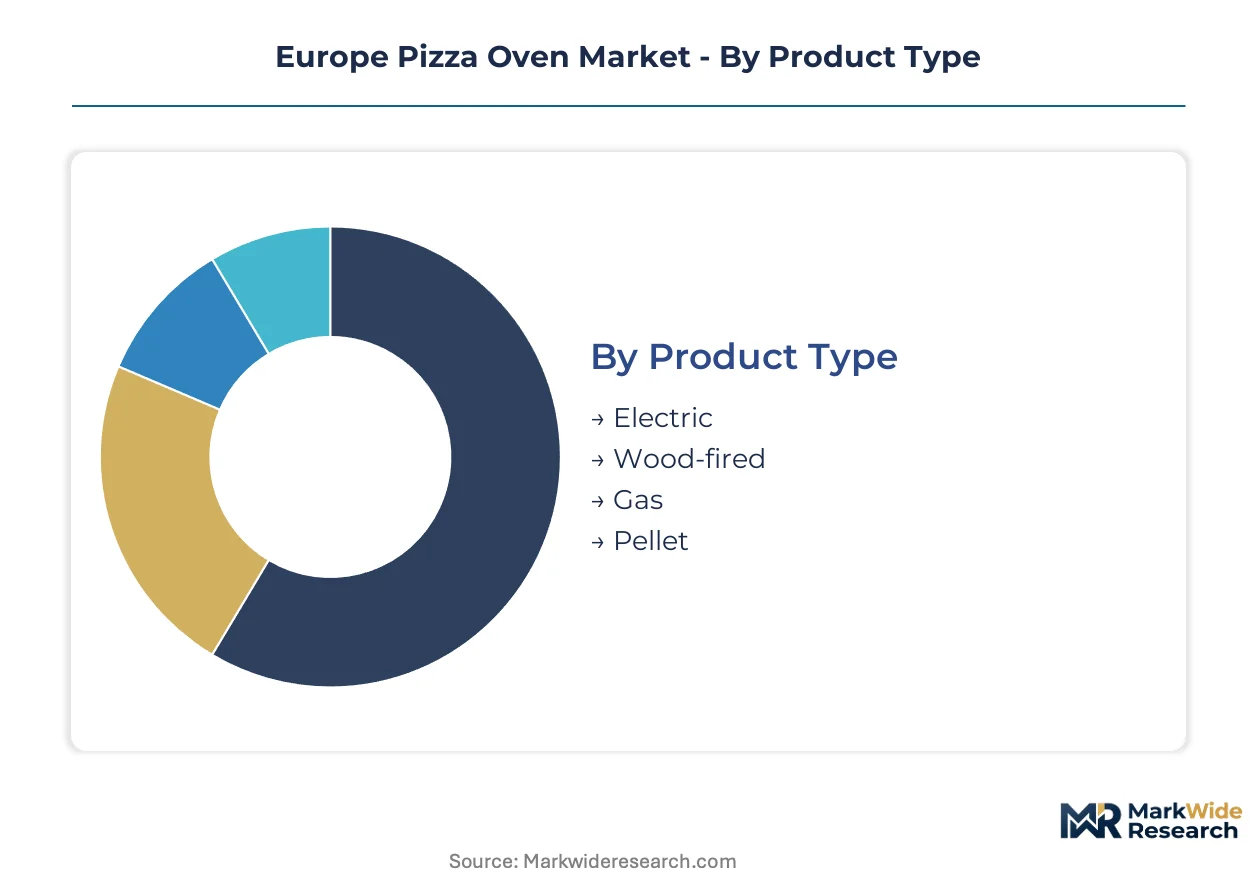
Pizza oven procurement across Europe splits across four distinct dimensions, each governing different buyer priorities from energy compliance to mobility requirements. Equipment specification varies sharply between Southern European artisanal operators and Northern European chain operators facing divergent regulatory constraints.
Product Type:
Energy infrastructure availability and indoor air quality enforcement determine fuel selection across buyer segments.
- Electric:Ceramic deck elements and infrared top heating deliver precise temperature control for standardized output. Demand concentrates in Germany and the Netherlands where municipal gas restrictions and Ecodesign lot 23 compliance accelerate retrofit cycles in fast-casual chains.
- Wood-fired:Refractory domes constructed from biscotto clay or volcanic stone sustain 450°C-plus temperatures for DOC certification. Campania and Sicily independent pizzerias anchor volume, with AVPN credential requirements sustaining premium positioning despite higher operational complexity.
- Gas:Combustion systems with modulating burners offer faster heat recovery than electric alternatives. France retains installed base concentration as operators balance speed demands against F-Gas Regulation pressures on refrigerant-based combination units.
- Pellet:Automated biomass feeding systems reduce manual stoking while retaining wood-fired flavor profiles. Emerging adoption in Northern Italian provinces where carbon reduction incentives intersect with traditional cooking expectations.
Volume sits with Electric; growth tilts toward Pellet.
End User:
Capital commitment thresholds and certification requirements segment buyer behavior across commercial and residential applications.
- Restaurants:Full-service operators and fast-casual chains deploy deck ovens with 4-6 pizza capacity for throughput optimization. AVPN certification drives specification in Naples and Rome independent pizzerias where menu pricing power depends on authenticity signaling.
- Home Users:Compact electric and pellet units with 30-40cm cooking surfaces serve residential outdoor kitchens. German and Austrian consumers lead premium residential adoption as garden entertaining culture expands post-pandemic.
- Catering Services:Mobile equipment with rapid heat-up cycles supports event-based revenue models. French traiteurs and Italian sagre operators prioritize portability for festival and wedding deployment.
- Food Trucks:Lightweight refractory or stainless steel constructions with LPG or electric hookup flexibility. Ghost kitchen operators across Madrid and Berlin ghost kitchen clusters drive specification for delivery-only pizza concepts.
Restaurants command current volume; Food Trucks are expanding most quickly.
Installation Type:
Real estate tenure and kitchen reconfiguration costs determine structural commitment levels.
- Built-in:Masonry-integrated installations with custom hood and ventilation systems. Southern European owner-operators with long-term lease security favor this category for authenticity theater and property value enhancement.
- Portable:Wheeled or modular units with quick-disconnect utilities. Food truck operators and pop-up concepts across European urban centers prioritize this category for location flexibility and reduced capital lock-in.
- Standalone:Self-supporting steel or refractory structures requiring minimal kitchen modification. Mid-size French and Spanish restaurant groups favor standalone specification for standardized rollout across multiple locations.
- Countertop:Compact electric units with ventless or minimal exhaust requirements. Small-format ghost kitchens and catering commissaries in dense Northern European urban cores adopt for space efficiency.
Standalone dominates current procurement; Portable is gaining share fastest.
Size:
Throughput requirements and kitchen footprint constraints govern dimensional selection.
- Small:1-2 pizza capacity units for residential or limited-menu commercial use. Home user segments in Alpine regions and UK suburban markets absorb this category for occasional entertaining.
- Medium:3-4 pizza decks balancing throughput and space efficiency. Independent pizzerias in secondary French and German cities standardize on this format for lunch-dinner transition flexibility.
- Large:5-8 pizza capacity for high-volume single-location operators. AVPN-certified establishments in Naples and Rome require this scale to manage tourist peak demand without quality degradation.
- Extra Large:10-plus pizza throughput for central commissary or stadium concession deployment. Limited adoption concentrated in Italian airport concessions and large-format catering operations.
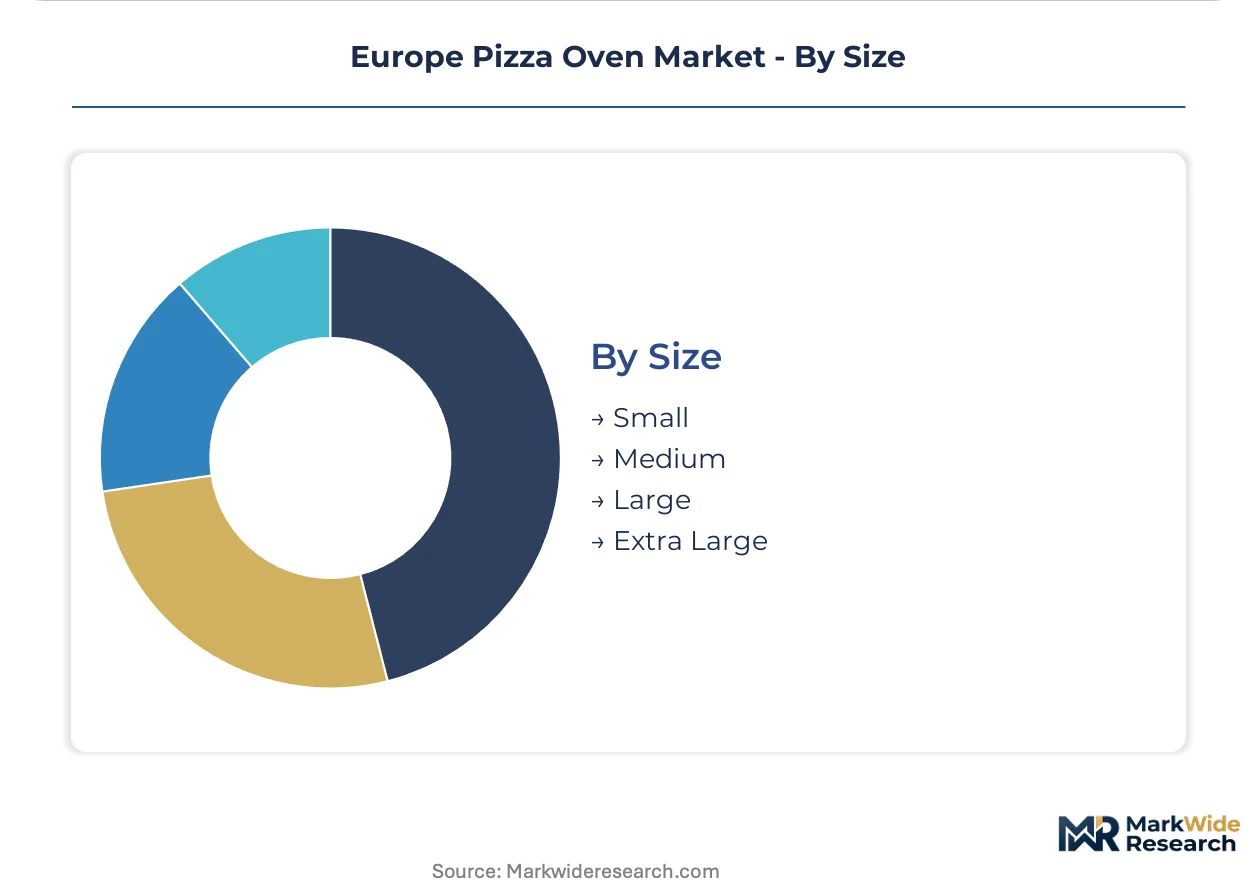
Medium commands volume concentration; Large shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Volcanic stone deposits in Italy's Campania region anchor artisanal oven production across Southern Europe. Refractory clay extraction in Emilia-Romagna feeds manufacturing clusters in Modena and Bologna. These material localities shape equipment procurement patterns from Naples to Berlin.
Italy
AVPN certification requirements drive specification for wood-fired domes among Naples and Rome independent operators. Italy's national energy efficiency incentives for SME restaurant upgrades redirect procurement toward certified electric models. The Emilia-Romagna manufacturing cluster around Modena sustains generational kiln-building expertise for export markets.
Germany
Municipal gas infrastructure restrictions and Ecodesign lot 23 compliance accelerate electric deck oven retrofits in fast-casual chains. The EU F-Gas Regulation pressures refrigerant-based combination oven configurations in commercial kitchens. Berlin and Hamburg ghost kitchen operators specify portable installations for delivery-only concepts.
France
Traiteurs and festival catering operators in Provence prioritize mobile equipment for wedding and event deployment. CE marking under the EU Machinery Directive governs safety thresholds for imported refractory components. The Auvergne-Rhône-Alpes region hosts distribution consolidation through certified installer networks.
Spain
Madrid and Barcelona food truck clusters drive lightweight portable oven specification with LPG flexibility. Indoor air quality codes in dense urban centers restrict combustion options for new installations. Andalusian independent pizzerias maintain direct purchasing patterns for artisanal provenance verification.
Netherlands
Fast-casual chains standardize on sensor-embedded electric decks for multi-location output consistency. REACH compliance adds material traceability burdens for imported ceramic fiber inputs. The Randstad urban corridor concentrates demand for countertop ventless units in compact ghost kitchen formats.
Europe Pizza Oven Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue smart connectivity and predictive maintenance modules. The vendor base splits between artisanal heritage fabricators and automated equipment specialists. Three archetypes dominate: generational craft houses anchored in Italian refractory clusters, Northern European automation-focused manufacturers, and distribution-anchored solution providers. Competitive moves center on certified installer network expansion and sensor-embedded product line diversification.
Within the heritage craft tier, Morello Forni Italia s.r.l. and Le Panyol exemplify generational expertise concentrated in Modena and Provence respectively. Cuppone s.r.l. occupies a position among automated specialists serving high-volume chain operators. Euro Restaurant Solutions anchors distribution integration through showroom and certified installer programs across Southern Europe.
| Leading Market Players |
|---|
| Morello Forni Italia s.r.l. |
| Forno Bravo |
| Le Panyol (Fayol S.a.) |
| Wood Stone Corporation |
| Mugnaini Imports, Inc. |
| Californo |
| EarthStone Wood-Fire Ovens |
| Euro Restaurant Solutions (Marra Forni) |
| Cuppone s.r.l. |
| Others |
Pricing and Supply Chain Analysis
Fast-casual chain procurement teams in Germany and the Netherlands dominate volume purchasing and enforce standardized contract terms that unbundle installation and warranty services from equipment base prices. This buyer concentration rewards certified installer networks with recurring service revenue while pressuring mid-tier assemblers to absorb refractory input volatility.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium Italian heritage brands from economy-tier competitors in this market. Three-tier pricing structure across premium, standard, and economy levels tracks AVPN certification status and refractory material grade. Pricing pressure stems from cordierite and biscotto clay cost swings tied to Emilia-Romagna kiln energy expenses. Independent pizzerias in Southern Europe show lowest price sensitivity due to authenticity signaling requirements, while Northern European ghost kitchen operators prioritize capital minimization.
Supply Chain Analysis
Single-source vulnerability sits with volcanic stone extraction in Italy's Campania region and ceramic fiber processing in Emilia-Romagna. Manufacturing draws from refractory clay deposits in Modena, volcanic tuff in Naples, and imported alumina-silicate from Turkey. Tariff exposure on Turkish ceramic fiber inputs threatens margin stability for mid-volume producers. Distribution runs through Marra Forni's certified installer network and Euro Restaurant Solutions showroom channels across France, Spain, and Italy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as players pursue captive supply of biscotto clay and volcanic stone to secure margin control against input volatility.
For Market Incumbents: Hedge refractory supply exposure through long-term quarry leases in Campania or backward integration into ceramic fiber processing. AVPN certification backlog compression threatens artisanal positioning for heritage brands unable to accelerate verification timelines. Defensive capacity expansion into automated electric deck production addresses fast-casual chain standardization demands in Northern Europe. For New Entrants and Emerging Players: Direct-to-ghost-kitchen digital sales channels bypass entrenched distributor relationships and capture portable oven demand in Berlin and Madrid delivery-only clusters. Underpenetrated Swedish and Danish urban markets present whitespace for ventless electric countertop specification. Target catering services in French festival circuits with rapid-deployment LPG-compatible units. For Investors and Strategic Acquirers: The window for entry favors automated equipment specialists with sensor-embedded product lines and established CE marking pathways. Long-term viability hinges on regulatory compliance architecture rather than craft heritage alone. Monitor EU Ecodesign lot 23 revision timing as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Installer Network Expansion | Marra Forni's showroom program locks in recurring service revenue across Southern European restaurant groups. |
| Smart Refractory System Development | Embedded thermocouple arrays from Cuppone standardize output consistency for multi-location fast-casual operators. |
| Volcanic Stone Quarry Integration | Morello Forni's Campania sourcing control insulates margins against Turkish ceramic fiber tariff exposure. |
| Portable Product Line Diversification | Lightweight LPG-electric hybrid units capture food truck demand in Madrid and Berlin ghost kitchen clusters. |
| EU Ecodesign Compliance Certification | Energy-efficient model qualification unlocks Italy's SME restaurant upgrade incentive program procurement. |
Research Methodology
Multi-period observation of AVPN certification queue lengths, refractory material import flows, and fast-casual chain capex cycles anchored the trend analysis, supplemented by interviews with equipment procurement directors at restaurant groups, plant managers at Emilia-Romagna kiln operations, certified installer network heads, and ghost kitchen operators. Secondary validation drew from EU F-Gas Regulation implementation reports, ECHA REACH compliance filings, Italian national energy efficiency incentive program disclosures, and customs data on ceramic fiber imports. Bottom-up unit demand estimates triangulated against top-down market sizing from refractory producer output volumes.
Segment-weighting approaches applied differential growth assumptions across fuel type, installation format, and end-user category throughout the forecast period. The analytical framework modeled electric, wood-fired, gas, and pellet product types alongside portable, built-in, standalone, and countertop installation configurations. CAGRs derived from regression analysis of historical replacement cycles against regulatory compliance deadlines and incentive program windows. Industry-specific inputs included AVPN certification throughput rates and EU Ecodesign lot 23 enforcement timelines.
The model holds under steady EU regulatory implementation and stable refractory supply conditions; deviation in Turkish ceramic fiber trade policy or accelerated F-Gas phase-down schedules would shift replacement cycle timing. Forecasts reflect documented assumptions about incentive program continuity and certification body capacity expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Kamado Grill Market
Food Service
Commercial Rice Cooker Market
Food Service
Global Food Retail Market
Food Service
North America Food Service Market
Food Service
Peer-To-Peer Dining Market
Food Service
Inflight Catering Market
Food Service
Latin America Online Grocery Delivery Market
Food Service
India Quick Service Restaurant Market
Food Service
Commercial Tableware Services Market
Food Service
United States Full Service Restaurants Market
Food Service
US Restaurant Point of Sale Solution Market
Food Service
Netherlands Food Service Market
Food Service
North America Food Platform-To-Consumer Delivery Market
Food Service
India Full Service Restaurants Market
Food Service
Europe Food Service Market
Food Service
Food Contract Manufacturing Market