
 Online Catering Market | 2026-2036
Online Catering Market Size, Share, and Industry Trends Forecast 2026-2036
Online Catering Market Outlook
Corporate event spending is consolidating around platforms that unify ordering, billing, and dietary compliance across distributed teams. ezCater leverages its national vendor network to sustain enterprise account stickiness. ZeroCater anchors its position through curated chef partnerships that differentiate menu quality. Grubbo competes on real-time availability dashboards that reduce booking friction for recurring office meals.
Online catering encompasses digitally coordinated food service procurement, menu customization, and logistics management for group dining occasions, typically involving minimum order thresholds of 10 to 500 servings and delivery windows synchronized to event schedules. The primary commercial purpose is replacing fragmented phone-and-email procurement with transparent pricing, vendor verification, and consolidated invoicing. Corporate catering dominates transaction volume as procurement departments mandate spend visibility, while drop-off delivery mode captures the fastest expansion by eliminating on-site staffing costs. Custom menus command premium positioning through allergen accommodation and brand-aligned presentation, whereas buffet style retains volume leadership in price-sensitive institutional segments.
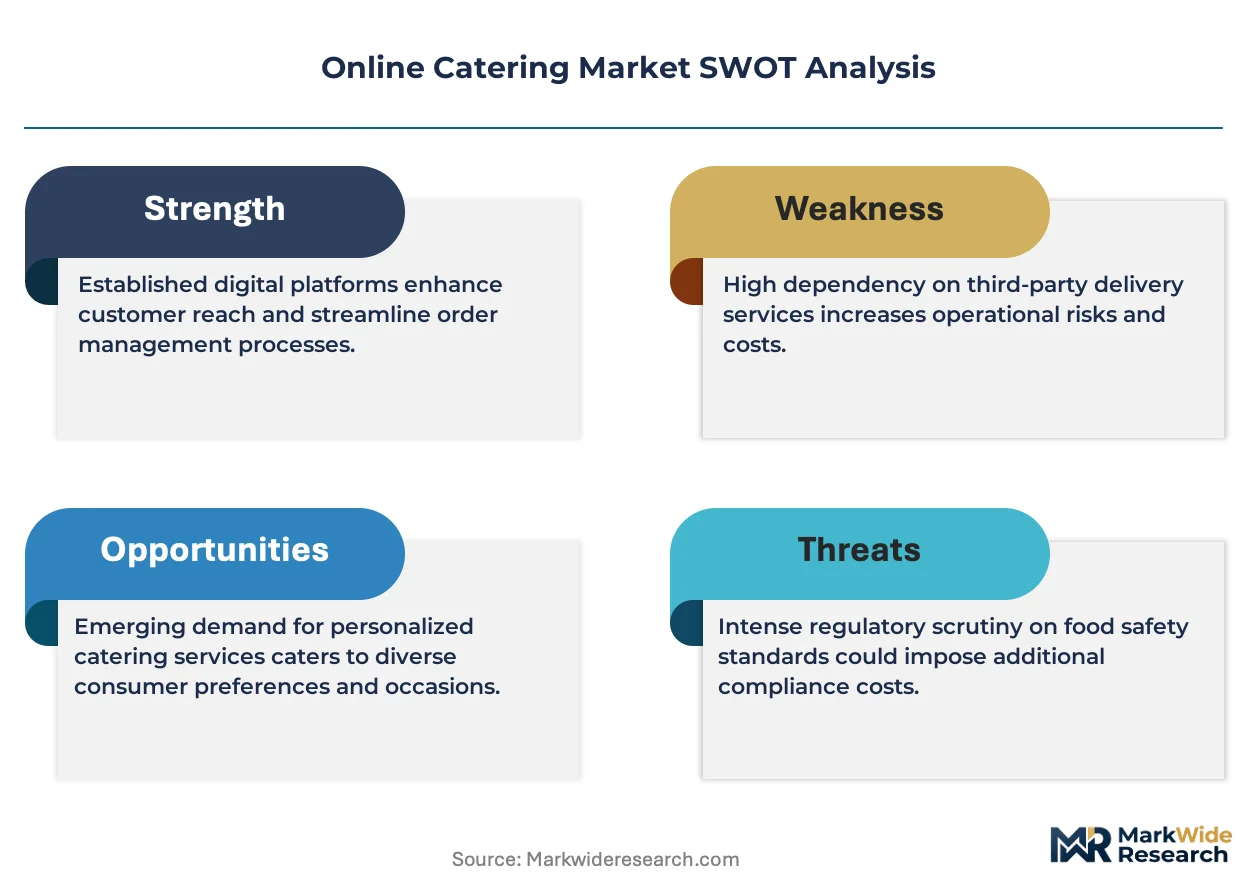
FDA Food Code provisions, state-level cottage food laws, and local health department permitting frameworks collectively elevate compliance costs for platform onboarding and vendor recertification cycles. OSHA workplace safety guidelines and municipal commercial kitchen inspection protocols further shape liability structures and insurance requirements for catering intermediaries. Stakeholders must monitor evolving patchworks of ghost kitchen regulations and third-party delivery fee caps that could restructure platform economics and vendor participation terms.
Market Dynamics
Enterprise procurement teams are consolidating vendor relationships around integrated platforms that unify ordering, billing, and dietary compliance, compressing the addressable market for standalone caterers and fragmenting volume across fewer intermediaries.
Growth Catalysts
- FDA Food Code Modernization:Digitized HACCP-aligned traceability requirements are accelerating vendor qualification upgrades and platform onboarding investments.
- Hybrid Work Normalization:Distributed team meal coordination is creating recurring demand spikes for synchronized multi-location delivery windows.
- Drop-off Delivery Infrastructure:Elimination of on-site staffing costs is expanding addressable event types into smaller recurring office meals.
Market Restraints
- Input Cost Volatility:Protein and packaging material price swings compress platform margins during contract renegotiation cycles.
- Vendor Concentration Risk:Metropolitan kitchen capacity limits create fulfillment bottlenecks during peak corporate event seasons.
- Regulatory Friction:Municipal ghost kitchen inspection protocols extend vendor recertification timelines and elevate compliance overhead.
Strategic Opportunities
- Underpenetrated Institutional Segments:Healthcare and education facilities remain underserved by integrated catering management systems.
- Allergen Accommodation Technology:AI-driven menu customization is converging with nutrition database APIs to capture premium positioning.
- State Cottage Food Law Expansion:Relaxed home kitchen commercialization rules in select US states are broadening supplier bases.
Industry Challenges
- Food Safety Certification Timelines:ServSafe and state-level manager certification backlogs delay platform vendor expansion.
- Legacy ERP Integration Complexity:Enterprise procurement systems require custom API development for consolidated invoicing workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Online Catering Market |
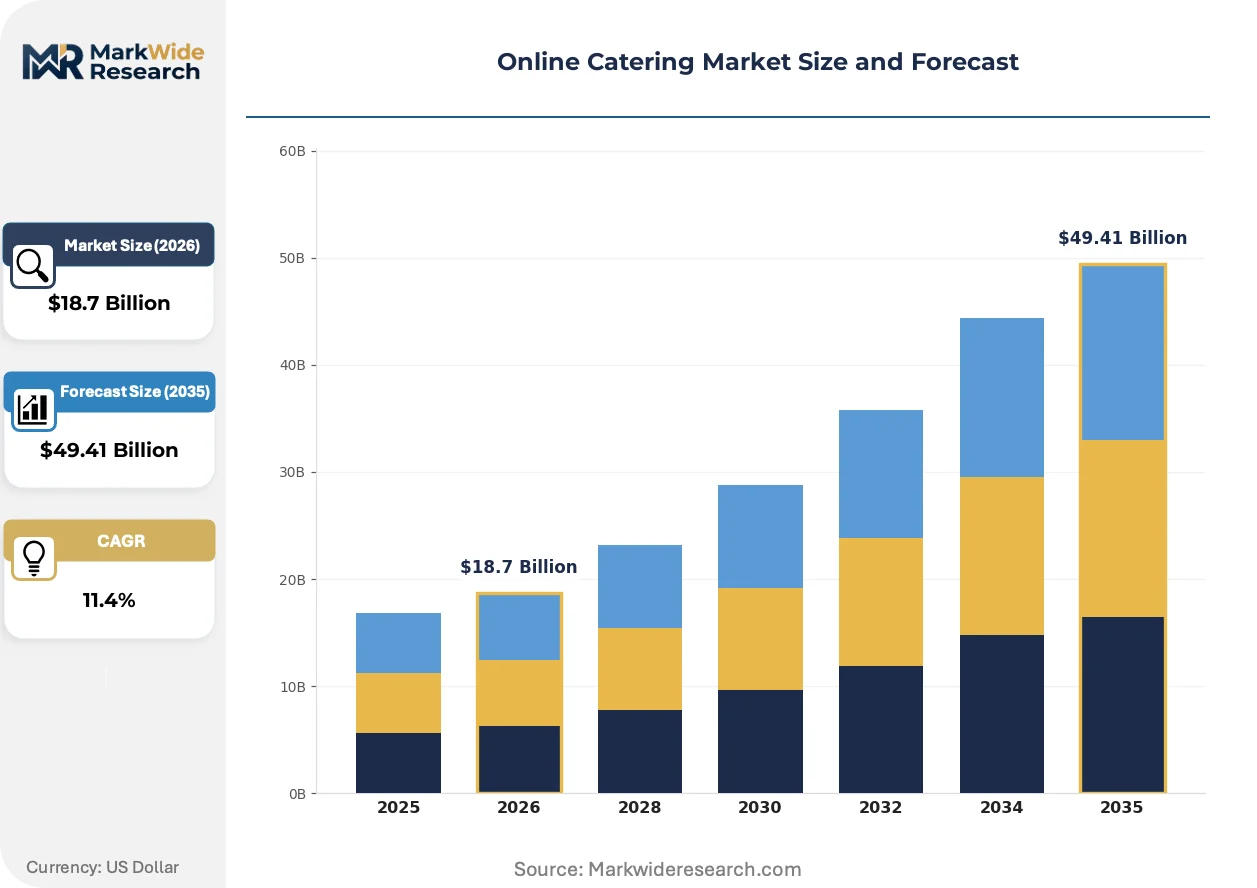
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Event Catering, Corporate Catering, Wedding Catering, Party Catering Customer Type: Individual Consumers, Corporate Clients, Institutions, Non-Profit Organizations Delivery Mode: Home Delivery, Pick-Up, On-Site Service, Drop-Off Menu Type: Buffet Style, Plated Dinner, Themed Menus, Custom Menus |
| Companies Covered | Grubbo, Sizzle, ezCater, Ordercube, Qnips, Hungry Marketplace, Ziti, ZeroCater, Sharedine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Online Catering Market Strategic Shifts
Operational digitization is compressing booking friction and reshaping how corporate buyers evaluate vendor reliability, with transparency tools displacing relationship-based procurement.
Predictive logistics engines are converging with real-time kitchen capacity APIs to optimize delivery routing. Enterprise account teams are adopting these systems fastest, demanding sub-15-minute booking completion. This convergence is compressing vendor selection cycles from days to hours and elevating platform stickiness through embedded workflow integration.
OSHA workplace safety guidelines and municipal commercial kitchen inspection protocols are tightening liability structures for catering intermediaries. Insurance carriers are mandating documented temperature logging and driver certification. Drop-off delivery operators in dense urban corridors face the steepest compliance cost escalation.
Corporate event coordinators are consolidating spend around subscription-based ordering models that guarantee volume commitments. Preferred vendor lists are narrowing to platforms offering consolidated billing and dietary audit trails. This pattern is most visible among technology sector employers with distributed workforces exceeding 500 employees.
Online Catering Market Segmentation
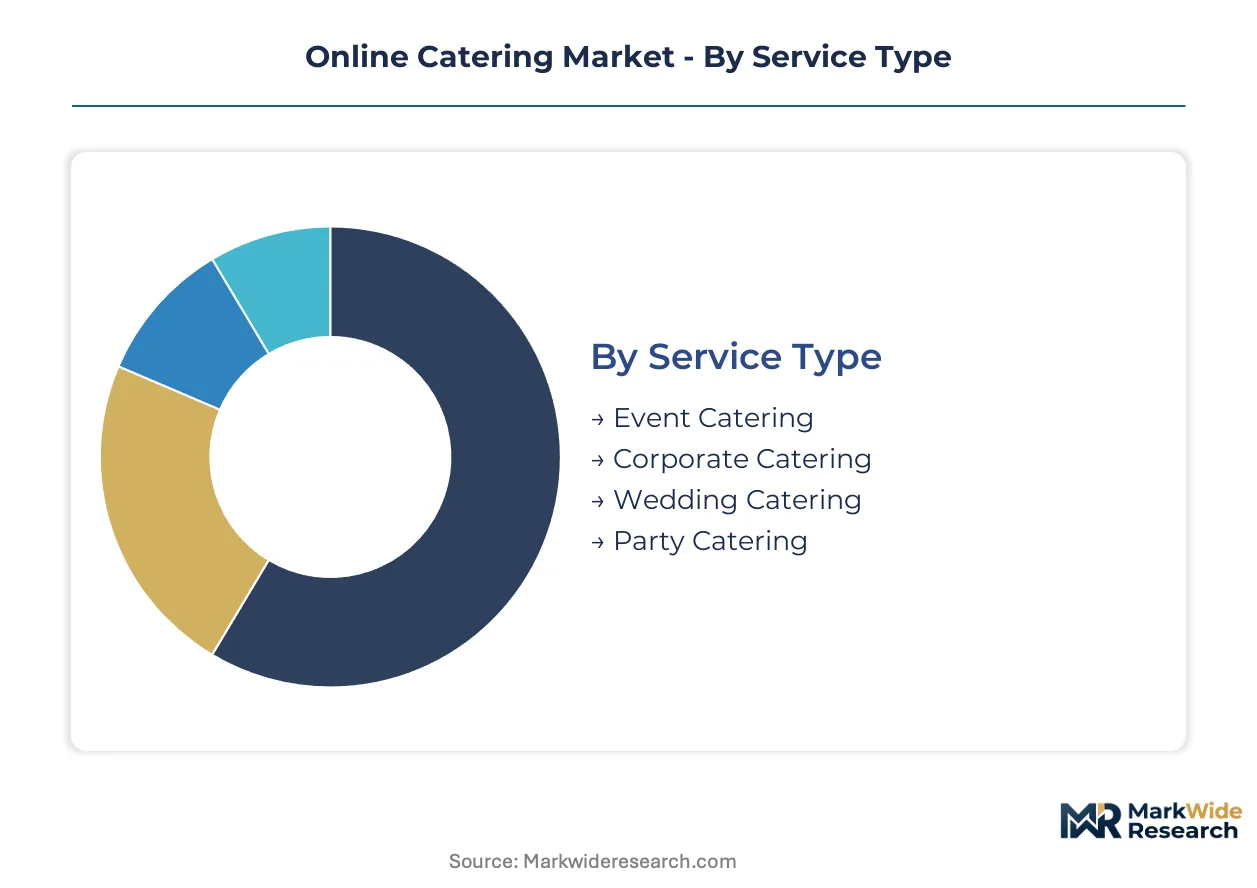
Segmentation in online catering reveals how procurement complexity varies across occasion types and buyer sophistication. Service configuration, customer organization, fulfillment method, and menu format each create distinct operational requirements that shape platform technology investments and vendor qualification standards.
Service Type:
Event scale and coordination intensity define the technical architecture required for each service category.
- Event Catering:Large-scale coordination involving multi-course sequencing, rental equipment logistics, and synchronized service windows for galas and conferences. Demand concentrates in metropolitan convention centers where procurement teams mandate consolidated billing across fragmented vendor pools.
- Corporate Catering:Recurring meal programs with standardized dietary compliance protocols and ERP-integrated invoicing. Technology sector employers with distributed workforces exceeding 500 employees are compressing vendor selection cycles from days to hours through embedded workflow integration.
- Wedding Catering:Highly customized presentation requirements with tiered service structures and seasonal booking peaks. Regional hospitality clusters in destination markets experience capacity constraints during spring and fall ceremony seasons.
- Party Catering:Flexible-portion formats designed for social gatherings with variable headcounts and informal service expectations. Home-based entertaining recovery is expanding addressable occasions beyond traditional commercial venues.
Corporate Catering leads on scale; Event Catering leads on momentum.
Customer Type:
Procurement sophistication and compliance burden vary sharply across organizational buyer categories.
- Individual Consumers:Transactional purchasers prioritizing real-time availability dashboards and transparent pricing for social occasions. Mobile-first booking interfaces are displacing phone-and-email coordination in suburban markets.
- Corporate Clients:Enterprise procurement departments mandating spend visibility, dietary audit trails, and consolidated invoicing across distributed locations. FDA Food Code-aligned vendor verification is becoming a non-negotiable qualification threshold.
- Institutions:Healthcare and education facilities with rigid nutrition standards and recurring volume commitments. Underpenetration in these segments creates expansion opportunity for integrated catering management systems.
- Non-Profit Organizations:Budget-constrained buyers requiring donation documentation and tax-exempt billing workflows. Grant-funded programming drives seasonal demand spikes aligned with fiscal year cycles.
Corporate Clients dominate transaction value; Institutions represent the steepest expansion trajectory.
Delivery Mode:
Fulfillment configuration determines staffing economics and addressable event scale.
- Home Delivery:Residential-address logistics with variable parking constraints and building access protocols. Last-mile density challenges in suburban corridors elevate delivery cost structures.
- Pick-Up:Customer-retrieved orders eliminating driver requirements and expanding service radius. Ghost kitchen clusters in urban cores optimize production proximity to residential demand.
- On-Site Service:Staffed events requiring trained personnel for setup, service, and breakdown. Labor availability constraints in peak seasons create fulfillment bottlenecks for large-format occasions.
- Drop-Off:Unstaffed delivery eliminating on-site personnel costs and expanding addressable event types into smaller recurring office meals. OSHA workplace safety guidelines and municipal commercial kitchen inspection protocols are tightening liability structures for this mode.
Drop-Off gains share fastest; On-Site Service retains premium positioning.
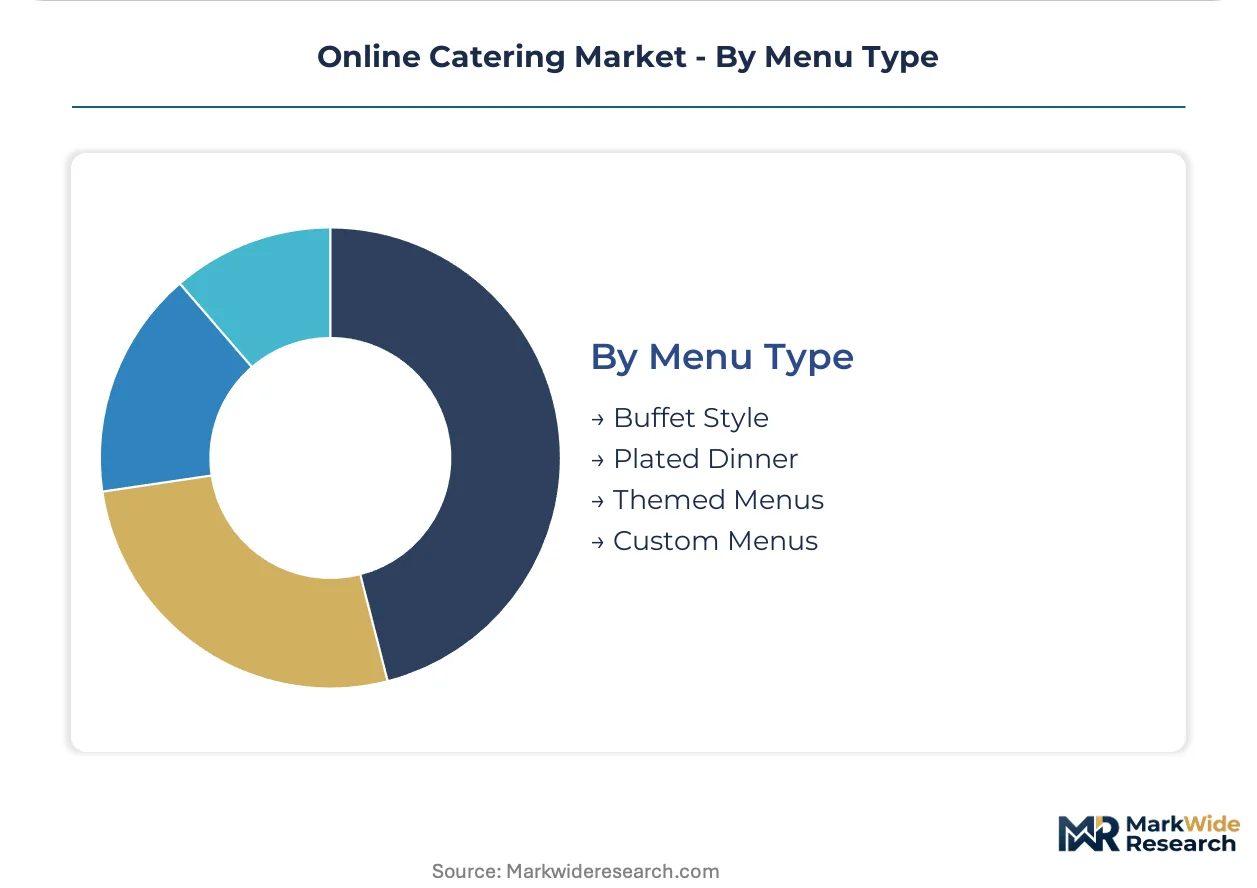
Menu Type:
Presentation format shapes kitchen capacity allocation and per-serving margin structure.
- Buffet Style:Self-service formats with batch production efficiency and minimal staffing requirements. Price-sensitive institutional segments retain volume leadership in this configuration.
- Plated Dinner:Individual service with precise portion control and elevated presentation standards. Corporate milestone events and formal galas concentrate demand for synchronized table-side delivery.
- Themed Menus:Curated culinary narratives aligned with cultural celebrations, seasonal occasions, or brand activations. Marketing and public relations departments prioritize these formats for experiential programming.
- Custom Menus:Fully bespoke offerings with allergen accommodation and brand-aligned presentation. AI-driven menu customization converging with nutrition database APIs is capturing premium positioning in enterprise accounts.
Buffet Style leads on volume; Custom Menus command margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping vendor onboarding investments as platforms migrate compliance infrastructure toward jurisdictions with streamlined food safety digitization frameworks and lower cottage food law barriers.
United States
Enterprise procurement consolidation around integrated catering management systems is concentrating demand in metropolitan clusters. FDA Food Code modernization mandates digitized HACCP-aligned traceability for vendor qualification. The San Francisco Bay Area and New York Metro anchor platform development activity, with technology sector employers exceeding 500 employees driving embedded workflow integration.
Germany
Corporate event coordinators are adopting subscription-based ordering models with consolidated billing requirements. EFSA nutrition database alignment and EU Green Deal packaging sustainability rules elevate compliance thresholds. The Rhine-Ruhr industrial corridor and Munich metropolitan region host dense concentrations of mid-market catering intermediaries upgrading ERP integration capabilities.
United Kingdom
Hybrid work normalization is generating recurring demand for synchronized multi-location delivery windows across distributed teams. Food Standards Agency digitization and post-Brexit import documentation requirements reshape vendor onboarding timelines. London and the Southeast corridor dominate transaction volume, with Manchester and Birmingham emerging as secondary platform expansion targets.
India
Institutional catering in healthcare and education facilities remains underserved by integrated management systems, creating expansion opportunity. FSSAI food safety licensing and state-level commercial kitchen registration protocols extend vendor recertification cycles. Maharashtra and Karnataka lead platform development, with Bangalore and Mumbai hosting emerging ghost kitchen clusters optimizing production proximity to corporate demand.
Japan
Drop-off delivery infrastructure is expanding addressable event types into smaller recurring office meals as on-site staffing costs escalate. PMDA-aligned food traceability standards and METI workplace safety guidelines tighten liability structures for catering intermediaries. The Tokyo-Osaka corridor concentrates platform investment, with Nagoya emerging as a secondary logistics optimization hub.
Online Catering Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with enterprise-facing platforms consolidating around integrated ordering-billing-compliance workflows while standalone caterers retain fragmentation in social occasion markets. The vendor base clusters into three archetypes: national vendor network operators, curated chef partnership platforms, and real-time availability dashboard providers. M&A activity concentrates on acquiring captive kitchen capacity, while strategic partnerships focus on ERP integration API development.
Within the enterprise platform tier, ezCater and ZeroCater exemplify divergent positioning strategies, with the former anchoring national vendor network scale and the latter occupying curated partnership differentiation. Grubbo represents the real-time availability archetype, reducing booking friction through dashboard-centric interfaces. These three entities collectively illustrate how platform economics are compressing vendor selection cycles from days to hours across technology sector accounts.
| Leading Market Players |
|---|
| Grubbo |
| Sizzle |
| ezCater |
| Ordercube |
| Qnips |
| Hungry Marketplace |
| Ziti |
| ZeroCater |
| Sharedine |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between FDA Food Code-aligned vendors and unverified kitchen operators manifests in both margin structures and procurement workflows, with enterprise accounts paying premiums for digitized HACCP traceability while price-sensitive institutional buyers tolerate longer vendor onboarding cycles.
Pricing Analysis
Platform commission layers absorb 15-25% of transaction value before kitchen payouts, compressing vendor margins during protein and packaging cost spikes. Three-tier pricing structure across premium, standard, and economy levels separates custom allergen-accommodated menus from buffet formats, with corporate accounts least sensitive and non-profit organizations most price-elastic. Cost compression in drop-off delivery is intensifying as municipal ghost kitchen inspection protocols extend compliance timelines.
Supply Chain Analysis
Single-source vulnerability sits with metropolitan kitchen capacity during Q4 corporate event peaks, when fulfillment bottlenecks trigger surge pricing. Production concentrates in the United States, Germany, and the United Kingdom, with raw material dependencies spanning proteins, sustainable packaging, and refrigerated logistics fleets. Tariff exposure on imported specialty ingredients elevates input cost volatility. Distribution runs through platform-mediated vendor networks rather than direct kitchen-to-buyer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Online catering functions as a late-cycle quality story where enterprise procurement teams are consolidating spend around integrated compliance-auditing capabilities, with FDA Food Code modernization accelerating vendor qualification investments as a premium specification.
For Market Incumbents: Anchor enterprise account stickiness through embedded ERP integration APIs that compress procurement cycles, while defending against curated chef partnership platforms by accelerating captive kitchen acquisitions in undersupplied metropolitan corridors. Certification investment in ServSafe-aligned manager training programs creates defensible vendor network scale. For New Entrants and Emerging Players: AI-driven allergen accommodation technology offers entry into healthcare and education facilities where integrated catering management systems remain underpenetrated. Target institutional segments with nutrition database API partnerships as the go-to-market angle, bypassing saturated technology sector accounts. For Investors and Strategic Acquirers: Consolidation pressure builds where vendor concentration risk in peak seasons creates fulfillment arbitrage opportunities for platforms with distributed kitchen networks. Mid-cap catering intermediaries with captive production capacity in FDA-aligned jurisdictions represent the optimal acquisition archetype. Watch ServSafe certification backlog resolution as the inflection signal for vendor expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| ERP Integration API Development | Embedded workflow integration compresses enterprise procurement cycles from days to hours. |
| Captive Kitchen Acquisition | Metropolitan production capacity secures fulfillment reliability during peak corporate event seasons. |
| AI-Driven Allergen Customization | Nutrition database convergence captures premium positioning in healthcare and education accounts. |
| FDA Food Code Compliance Investment | Digitized HACCP traceability qualifies vendors for enterprise preferred vendor lists. |
| Subscription-Based Ordering Model | Volume commitment guarantees stabilize platform revenue against input cost volatility. |
Study Parameters
Direct dialogue with enterprise procurement managers, catering operations directors, ghost kitchen facility operators, and food safety compliance officers grounded the qualitative framework, cross-referenced against FDA Food Code documentation, state cottage food law filings, municipal health department inspection records, and SEC disclosures from publicly traded food service platforms. Bottom-up vendor network analysis and top-down enterprise spend estimation were triangulated.
Segment-level outputs across service type, customer organization, delivery mode, and menu format were generated through the projection horizon, with CAGRs derived from regression analysis of historical platform transaction growth and forward-looking hybrid work normalization curves. Modeled inputs included enterprise headcount distribution patterns, commercial kitchen permit issuance rates, and protein commodity price indices.
The model holds under stable regulatory digitization timelines; deviation in FDA enforcement intensity or municipal ghost kitchen moratoriums would shift vendor onboarding velocity assumptions. Forecasts reflect documented assumptions about hybrid work persistence and enterprise procurement consolidation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Cutting Boards Market
Food Service
Instant Noodle Vending Machine Market
Food Service
Rotisseries Market
Food Service
South Korea Foodservice Market
Food Service
Takeout Dinner Market
Food Service
United States Cafes & Bars Market
Food Service
North America Online Food Delivery Market
Food Service
Portable Buffet and Drop-In Ranges Market
Food Service
Commercial Rice Cooker Market
Food Service
Commercial Sink Market
Food Service
Europe Barbeque Grill Market
Food Service
Onboard Rail Catering Market
Food Service
Electric Tiffin Market
Food Service
Turkey Food Service Market
Food Service
Netherlands Food Service Market
Food Service
Food & Beverage in Asia Market