
 Portable Cooler Market | 2026-2036
Portable Cooler Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Cooler Market Analysis
A capital-intensity divergence between premium rotational molders and low-cost injection molders is rotating competitive dynamics across the portable cooler landscape. YETI Holdings Inc. leverages proprietary rotomolding and brand equity to command price premiums in the hard-sided segment. Dometic Group AB anchors its position through deep integration into RV and marine OEM channels with compressor-based electric units. Igloo Products Corp. competes on volume scale and mass retail distribution, sustaining share in entry-level ice boxes.
Portable coolers are insulated thermal containers designed to preserve perishable goods, beverages, and temperature-sensitive materials through passive ice retention, thermoelectric Peltier modules, or compressor-driven refrigeration cycles with polyurethane foam insulation cores and UV-stabilized polyethylene shells. Their primary commercial purpose spans outdoor recreation, commercial food transport, medical specimen logistics, and mobile workforce hydration. Hard-sided coolers still occupy the dominant margin pool due to durability premiums and replacement cycles, while electric coolers with compressor technology represent the fastest-expanding segment as vanlife and overlanding enthusiasts demand off-grid refrigeration. Soft-sided formats lead in unit volume through impulse beach and picnic purchases where portability trumps ice retention duration.
EPA refrigerant regulations under SNAP and evolving DOE appliance efficiency standards are tightening compressor specifications and thermoelectric power-draw thresholds, pushing manufacturers toward R600a hydrocarbon alternatives and variable-speed drive systems. The EU F-Gas Regulation and REACH chemical compliance add parallel certification burdens for brands exporting to European outdoor retail channels. Stakeholders must monitor how state-level extended producer responsibility laws in California and Oregon reshape material recovery obligations for insulated shell disposal.
Market Dynamics
Thermoelectric and compressor cooling technologies are forcing a split between passive ice-retention products and active refrigeration systems, reshaping R&D allocation and manufacturing footprints across the portable cooler landscape.
Growth Catalysts
- EPA SNAP refrigerant rules:The program's phase-down of hydrofluorocarbons is accelerating manufacturer migration to R600a hydrocarbon alternatives, opening design windows for variable-speed compressor architectures.
- Vanlife and overlanding communities:These outdoor recreation segments are pulling compressor-based electric units into off-grid applications previously served by passive coolers, expanding addressable use cases.
- Rotational molding scale economies:Concentrated production clusters in Texas and Wisconsin are reducing per-unit insulation shell costs for premium hard-sided formats.
Market Restraints
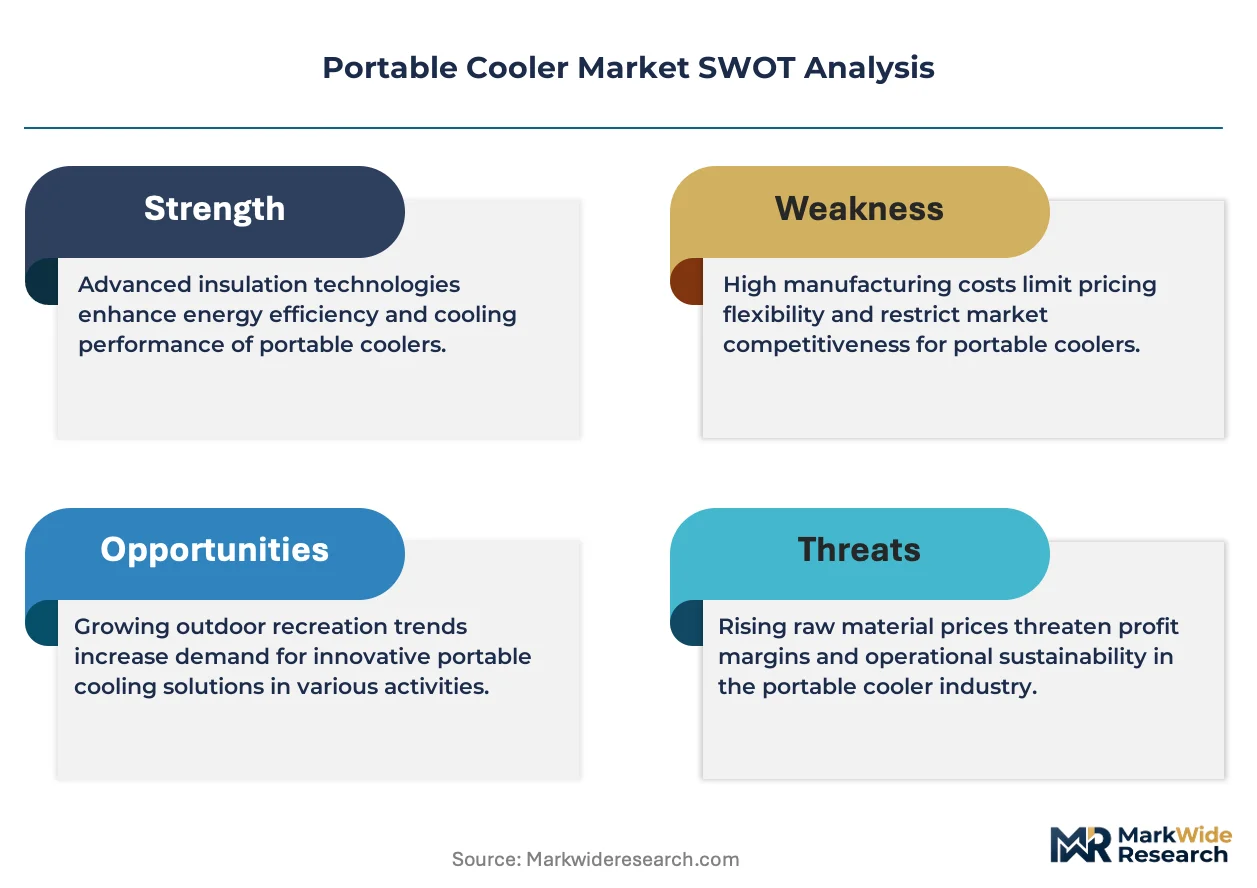
- Polyurethane foam feedstock volatility:MDI and polyol price swings compress margin predictability for insulated shell manufacturers locked into annual retail pricing contracts.
- Single-source compressor dependency:Secop and Danfoss dominate small-format refrigeration compressor supply, creating concentration risk for electric cooler assemblers.
- Thermoelectric efficiency ceiling:Peltier module COP limitations restrict cooling differential to 40°F below ambient, constraining performance in desert climates.
Strategic Opportunities
- Medical cold-chain logistics:Vaccine transport protocols are creating demand for validated temperature-tracking electric coolers with data-logging capabilities.
- California extended producer responsibility laws:SB 54 mandates are forcing material recovery infrastructure investment that first-mover brands can leverage for circular economy positioning.
- Bluetooth-enabled inventory management:Convergence of IoT sensors and mobile apps is enabling premium coolers to integrate with meal-planning and provisioning software ecosystems.
Industry Challenges
- Dual-chemistry certification timelines:Validating R600a systems for UL and CSA safety standards extends product development cycles by 8-14 months.
- Rotomold tooling amortization:Custom aluminum mold costs for proprietary shell geometries require 50,000+ unit production runs to achieve competitive unit economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Cooler Market |
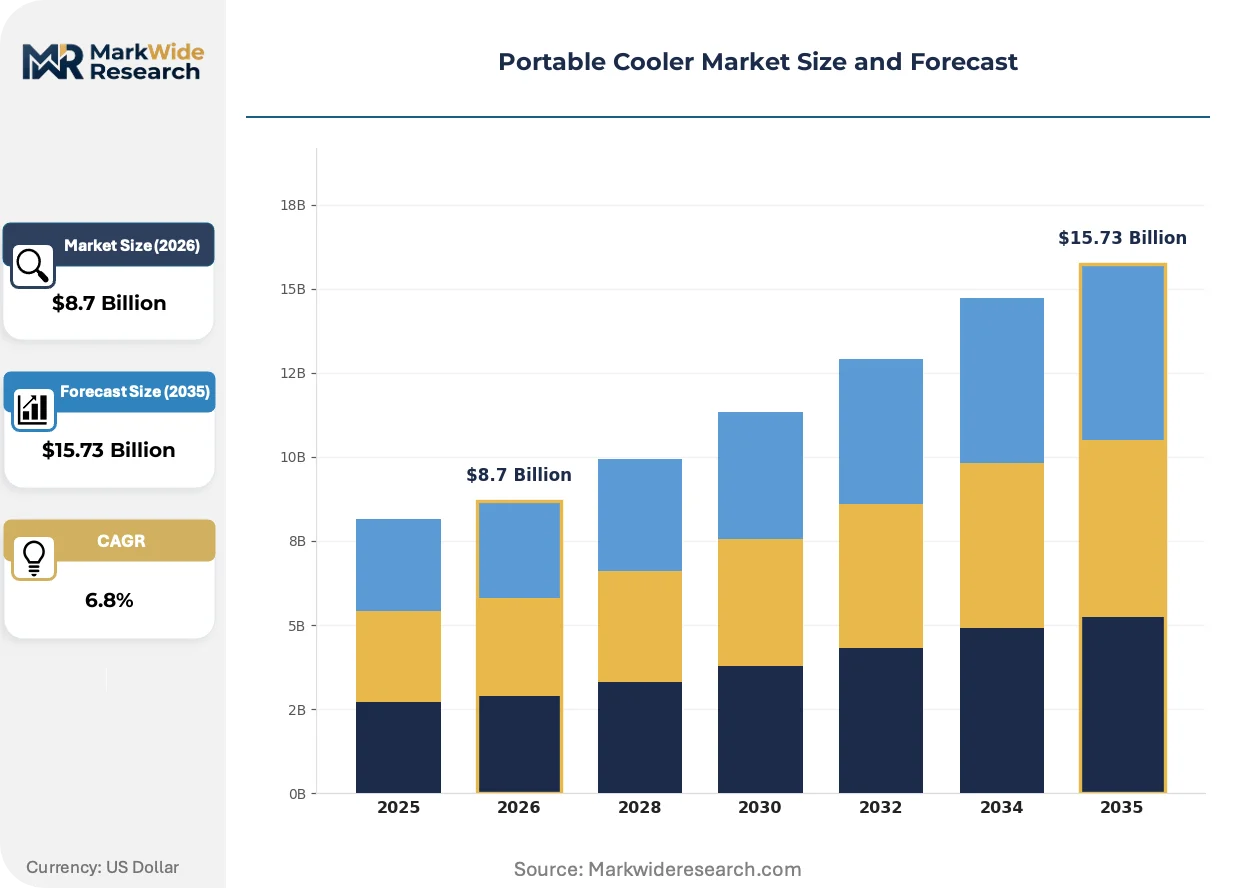
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Coolers, Hard-Sided Coolers, Soft-Sided Coolers, Ice Boxes End User: Outdoor Enthusiasts, Campers, Picnickers, Beachgoers Cooling Technology: Compressor, Thermoelectric, Passive, Refrigeration Capacity: 20-30 Liters, 31-50 Liters, 51-70 Liters, Above 70 Liters |
| Companies Covered | YETI Holdings Inc., Dometic Group AB, Newell Brands Inc., Pelican Products Inc., RTIC Outdoors LLC, Engel Coolers, Igloo Products Corp., Otter Products LLC, ORCA Coolers LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Cooler Market Emerging Trajectories
Active cooling architectures are fragmenting the market into distinct performance tiers while regulatory pressure on refrigerants and materials accelerates design obsolescence cycles.
Compressor miniaturization is bifurcating the electric cooler segment into portable 12V/24V DC units for vehicle integration and larger AC-powered formats for stationary outdoor kitchens. Overlanding enthusiasts are adopting the former at rates exceeding traditional camping gear replacement cycles. This technology split is compressing development timelines for thermoelectric products into commodity positioning.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are compelling exporters to redesign compressor systems for hydrocarbon refrigerants. The industrial consequence is a wave of platform consolidation as manufacturers sunset HFC-dependent product lines. Marine and RV OEM channels face the steepest compliance burden due to integrated system certification requirements.
Direct-to-consumer subscription models for seasonal cooler rentals are disrupting traditional retail purchase patterns among younger outdoor recreation participants. Specialty retailers in mountain west states are piloting these programs to capture recurring revenue from transient adventure travelers. This behavioral shift is most visible in Colorado and Utah, where gear ownership rates lag national averages.
Portable Cooler Market Segmentation
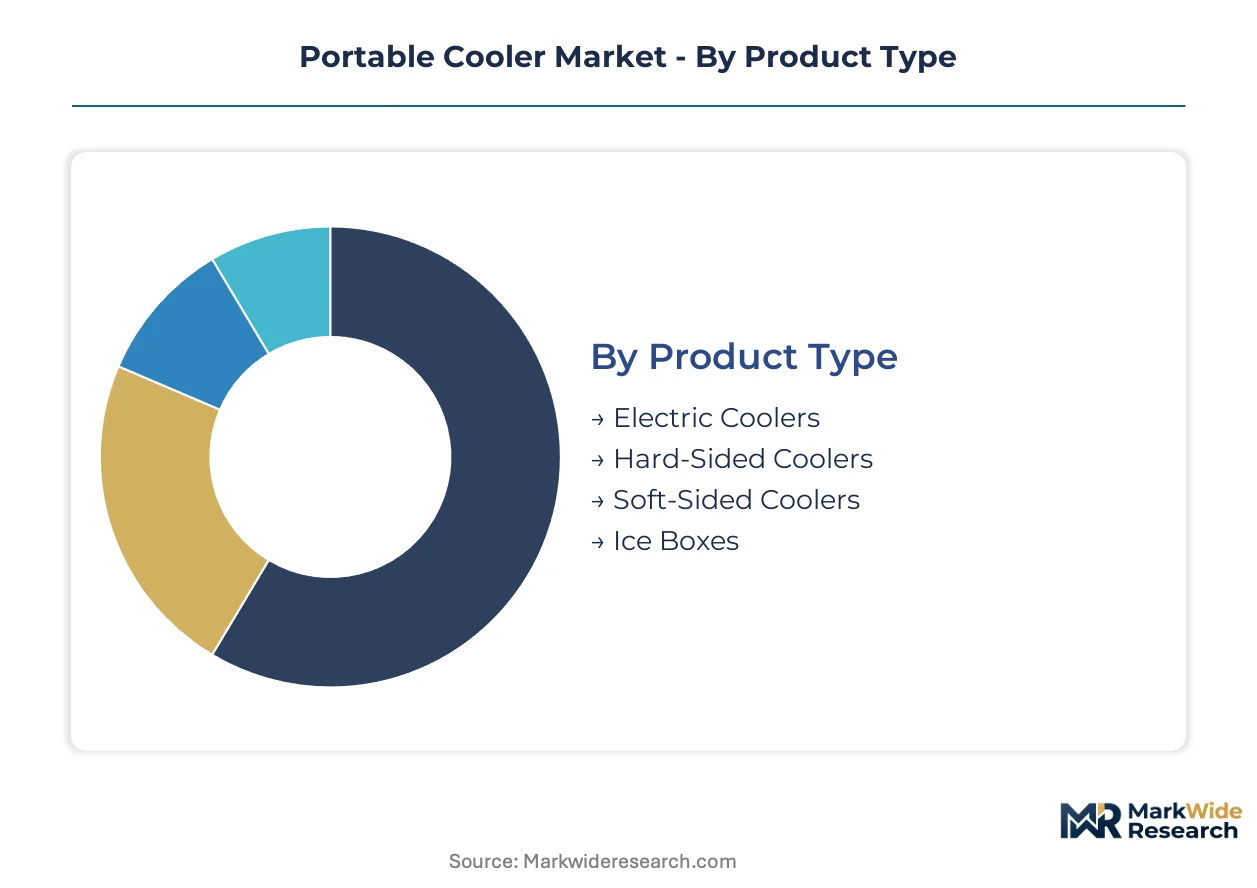
Portable cooler segmentation reveals divergent margin structures across passive and active cooling architectures. Product type and cooling technology splits determine manufacturing footprint decisions, while capacity tiers align with distinct use-case economics from day-trips to extended overlanding expeditions.
Product Type:
Domestic production concentrates rotomolded hard-sided units in Texas and Wisconsin manufacturing clusters, while electric cooler assembly draws heavily on imported compressor modules from Denmark and China. Soft-sided formats originate primarily from Asian contract manufacturers serving mass retail channels.
- Electric Coolers:Active refrigeration systems integrating 12V/24V DC compressors or thermoelectric Peltier modules with polyurethane-insulated shells. Demand clusters with vanlife and overlanding communities in Colorado and Utah seeking off-grid refrigeration capability without ice dependency.
- Hard-Sided Coolers:Rotomolded polyethylene shells with injected polyurethane foam cores delivering multi-day ice retention. Premium recreational spending in the United States sustains price premiums for durability-focused outdoor enthusiasts.
- Soft-Sided Coolers:Fabric-based insulated bags prioritizing portability over thermal performance. Impulse beach and picnic purchases drive volume through mass retail distribution.
- Ice Boxes:Basic passive containers without active cooling elements. Entry-level camping and commercial food transport applications in price-sensitive segments.
Hard-Sided Coolers hold the largest share; momentum sits with Electric Coolers.
End User:
Customer archetypes map directly to product tier selection, with expedition-grade buyers accepting compressor price premiums and casual users prioritizing portability and immediate availability.
- Outdoor Enthusiasts:Dedicated adventure travelers investing in premium equipment for repeated multi-day excursions. This segment drives fastest adoption of compressor-based electric units and rotomolded hard-sided formats.
- Campers:Recreational vehicle and tent-based overnight travelers requiring reliable food preservation across variable trip durations. Demand splits between passive coolers for short trips and electric units for basecamp setups.
- Picnickers:Day-use consumers seeking lightweight, affordable solutions for meal transport. Soft-sided formats dominate this occasional-use segment.
- Beachgoers:Coastal recreational users prioritizing sand resistance and easy carrying capacity. Regional concentration in Florida, California, and Gulf Coast states shapes seasonal demand patterns.
Outdoor Enthusiasts command the highest per-unit spending; Picnickers generate the steepest volume trajectory.
Cooling Technology:
Technology selection determines regulatory compliance burden, with compressor systems facing EPA SNAP refrigerant phase-down requirements and thermoelectric units constrained by efficiency physics.
- Compressor:Vapor-compression refrigeration using R600a hydrocarbon or legacy HFC refrigerants with variable-speed drive architectures. Vanlife adoption in the United States and EU overlanding markets accelerates platform development.
- Thermoelectric:Solid-state Peltier modules creating temperature differentials through electrical current. COP limitations restrict performance in desert climates, relegating this technology to beverage cooling applications.
- Passive:Insulated containers relying solely on ice or gel packs for thermal mass. Lowest cost entry point with zero power dependency appeals to emergency preparedness and developing market applications.
- Refrigeration:Stationary AC-powered units for outdoor kitchen and marine galley installations. Marine OEM channels in Florida and Pacific Northwest drive specification requirements.
Passive technology retains volume leadership; compressor architectures are climbing the fastest.
Capacity:
Volume tiers correlate with trip duration and group size, creating distinct competitive arenas where premium brands defend large-capacity segments and value players contest mid-range portability.
- 20-30 Liters:Personal-scale units for individual beverage and meal transport. Soft-sided formats and compact electric coolers compete in this impulse-purchase tier.
- 31-50 Liters:Couple and small-group configurations balancing portability with multi-day provisioning. Rotomolded hard-sided units from Texas manufacturing clusters dominate this core recreational segment.
- 51-70 Liters:Family and expedition-grade capacity requiring wheeled transport or vehicle integration. Electric compressor units gain traction for extended off-grid use.
- Above 70 Liters:Commercial food transport, hunting, and basecamp applications demanding maximum thermal mass. Premium pricing and replacement cycle economics concentrate margin capture here.
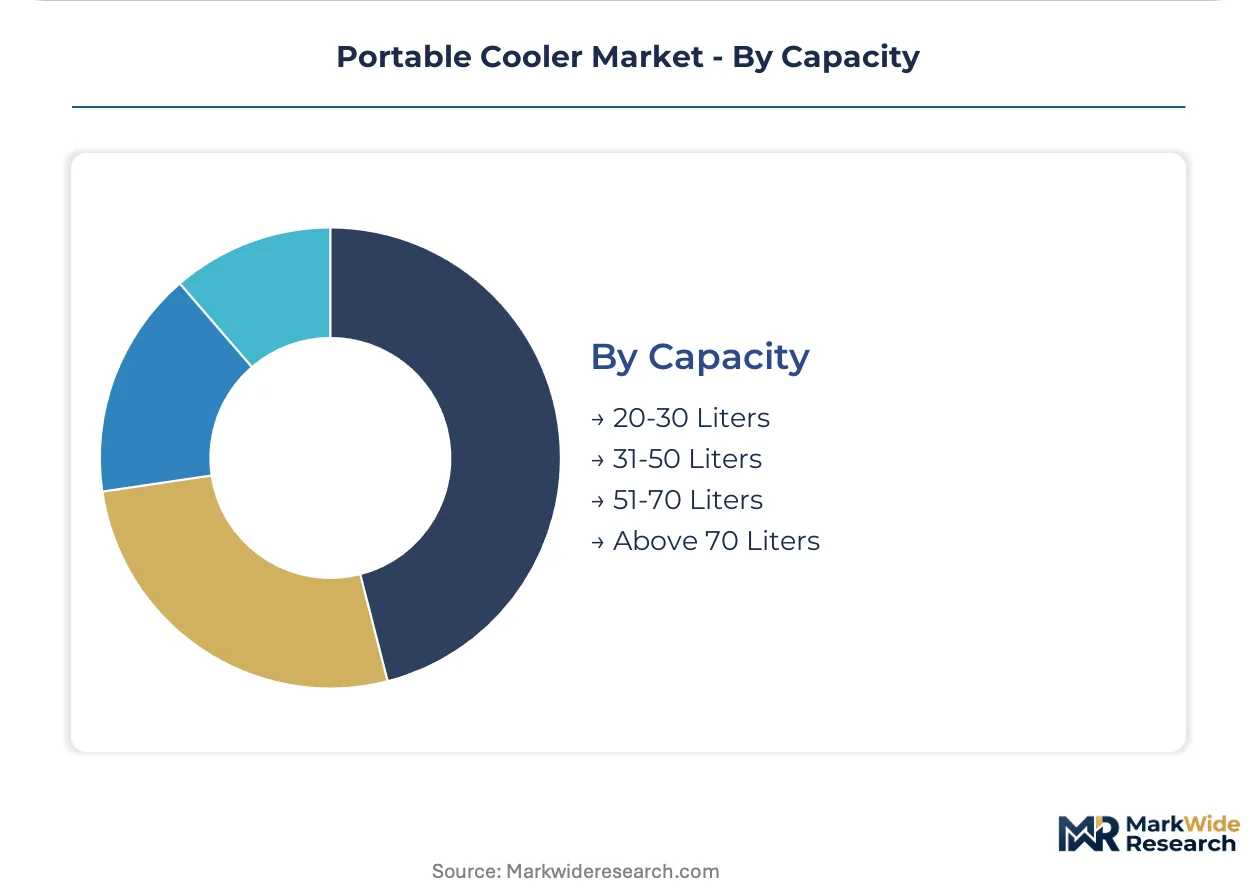
31-50 Liters captures the deepest volume; Above 70 Liters shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. United States buyers absorb premium durability premiums, while emerging market consumers prioritize entry-level passive units. European purchasers weigh regulatory compliance costs against efficiency gains.
United States
Tailgating culture and vanlife communities drive compressor cooler adoption in Colorado and Utah. EPA SNAP refrigerant phase-down rules accelerate manufacturer migration to R600a hydrocarbon systems. Austin and Houston manufacturing clusters concentrate rotomolded shell production for premium hard-sided formats.
Germany
Overlanding tourism across Alpine corridors sustains demand for electric compressor units with vehicle integration. EU F-Gas Regulation restrictions on fluorinated greenhouse gases force redesign of legacy HFC-dependent product lines. Bavarian industrial zones host assembly operations serving marine OEM channels.
China
Domestic outdoor recreation participation climbs alongside disposable income growth in tier-one cities. MIIT appliance efficiency standards tighten thermoelectric power-draw thresholds for export-bound manufacturers. Pearl River Delta contract fabricators dominate soft-sided cooler volume production.
Australia
Remote camping and 4WD expedition culture creates sustained demand for large-capacity passive coolers. TGA medical device regulations open pathways for validated cold-chain units in vaccine transport applications. Melbourne and Sydney distribution hubs coordinate seasonal inventory flows across coastal population centers.
Japan
Compact urban living shapes preference for personal-scale 20-30 liter formats with minimal footprint. METI energy conservation standards drive variable-speed compressor adoption in premium electric segments. Osaka manufacturing facilities specialize in precision thermoelectric module assembly.
Portable Cooler Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier that competes on manufacturing scale or channel access. The market structure concentrates margin capture among rotomolding specialists with proprietary shell geometries, while mass-market players contest volume through retail distribution partnerships. Three archetypes dominate: premium durability brands, RV/marine OEM integrators, and mass-market ice box manufacturers. Competitive moves center on refrigerant platform consolidation and direct-to-consumer channel expansion.
Among North American premium specialists, YETI Holdings Inc. and ORCA Coolers LLC occupy positions defined by rotational molding expertise and price-premium capture. Dometic Group AB anchors the European OEM integration tier with compressor-based electric systems. Igloo Products Corp. exemplifies the mass-market archetype through volume scale and mass retail penetration.
| Leading Market Players |
|---|
| YETI Holdings Inc. |
| Dometic Group AB |
| Newell Brands Inc. |
| Pelican Products Inc. |
| RTIC Outdoors LLC |
| Engel Coolers |
| Igloo Products Corp. |
| Otter Products LLC |
| ORCA Coolers LLC |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between rotomolding manufacturers and MDI suppliers lock in insulation foam feedstock access while anchoring cost visibility across multi-year retail pricing cycles. These arrangements concentrate margin predictability in Texas and Wisconsin production clusters where premium hard-sided units command durability premiums.
Pricing Analysis
After-sales revenue from replacement gaskets, drain plugs, and warranty extensions drives lifetime value capture in the premium tier. Three-tier pricing structure across premium, standard, and economy levels separates rotomolded hard-sided formats from injection-molded commodity ice boxes. Cost compression in thermoelectric segments is intensifying because Peltier module commoditization erodes differentiation. Picnickers and casual beachgoers exhibit highest price sensitivity, while overlanding enthusiasts absorb compressor premiums for off-grid capability.
Supply Chain Analysis
China and Vietnam anchor soft-sided cooler fabrication through Pearl River Delta contract manufacturers serving mass retail channels. Rotomolded shell production draws from Texas and Wisconsin clusters, while compressor modules feed from Denmark and Chinese assembly operations. Single-source dependency on Secop and Danfoss for small-format refrigeration compressors creates concentration risk for electric cooler assemblers. Distribution runs through big-box outdoor retailers, marine OEM channels, and direct-to-consumer platforms with seasonal inventory pre-positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The portable cooler market functions as a defensive-moat story where regulatory entrenchment around EPA SNAP refrigerant compliance and UL safety certification creates sticky barriers against unqualified entrants.
For Market Incumbents: Compound brand equity through proprietary rotomolding geometries that resist price erosion from injection-molded substitutes. Deepen upstream control over MDI supply contracts to buffer margin compression from polyurethane feedstock volatility. Prioritize R600a hydrocarbon platform consolidation ahead of state-level extended producer responsibility mandates in California and Oregon.
For New Entrants and Emerging Players: Differentiate on medical cold-chain validation protocols where vaccine transport specifications create specification gaps incumbent recreational brands have not addressed. Target the 51-70 liter electric compressor segment where vanlife demand outpaces established supply. Pursue direct-to-consumer rental subscription models piloted in Colorado and Utah mountain markets.
For Investors and Strategic Acquirers: Capital is best deployed toward rotomolding specialists with captive shell geometries and established marine OEM channel relationships rather than thermoelectric commodity assemblers. Monitor EPA refrigerant rulemaking timelines as inflection signals for platform consolidation windows and stranded asset risk in HFC-dependent product lines.
| Strategic Initiative | Industry Significance |
|---|---|
| R600a Hydrocarbon Platform Migration | EPA SNAP compliance deadlines force redesign of legacy compressor architectures ahead of phase-down enforcement. |
| Direct-to-Consumer Rental Subscription Launch | Colorado and Utah specialty retailers pilot recurring revenue models capturing transient adventure travelers. |
| Medical Cold-Chain Certification Investment | TGA and FDA validation pathways open vaccine transport applications with data-logging capability requirements. |
| Rotomolding Capacity Expansion | Texas manufacturing clusters reduce per-unit insulation shell costs through concentrated production scale. |
| Bluetooth-Enabled Inventory Integration | IoT sensor convergence with meal-planning software ecosystems creates premium cooler differentiation. |
Methodological Framework
Operator-level perspectives from rotomolding plant managers, marine OEM procurement leads, outdoor retailer category buyers, and thermoelectric module engineers anchored the qualitative base. Secondary validation drew from EPA SNAP regulatory filings, DOE appliance efficiency standards, EU F-Gas Regulation documentation, and customs trade records for polyurethane feedstock flows. Bottom-up unit economics modeling triangulated against top-down spending pattern analysis across the analysis window.
Sensitivity analysis tested demand elasticity across compressor adoption scenarios and refrigerant transition timelines. Segmentation dimensions modeled include product type, cooling technology, capacity tier, end-user archetype, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and penetration rate assumptions. Forecast inputs incorporated vanlife participation trends and MDI price volatility bands.
Decision-makers should treat outputs as directional under stable outdoor recreation participation and current EPA refrigerant phase-down schedules; material deviation would warrant model refresh. Recalibration cycles align with material shifts in regulatory enforcement timelines and compressor technology substitution rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Used Restaurant Equipment Market
Food Service Equipment
Multi-Deck Refrigerated Display Cases Market
Food Service Equipment
Commercial Refrigerator Market
Food Service Equipment
Beverage Refrigeration Market
Food Service Equipment
Global Glass Door Cooler Market
Food Service Equipment
Remote Cooled Cube Ice Machines Market
Food Service Equipment
Saudi Arabia Foodservice Disposable Packaging Market
Food Service Equipment
Smart Food Scale Market
Food Service Equipment
Commercial Kitchen Knife Market
Food Service Equipment
Commercial Foodservice Equipment Market
Food Service Equipment
Automatic Popcorn Machine Market
Food Service Equipment
Smart Cooker Market
Food Service Equipment
Freestanding Large Cooking Appliance Market
Food Service Equipment
Draught Beer Chiller Market
Food Service Equipment
Commercial Gas Restaurant Ranges Market
Food Service Equipment
Asia-Pacific Commercial Dishwashers Market