
 United States Food Truck Market | 2026-2036
United States Food Truck Market Size, Share, and Industry Trends Forecast 2026-2036
United States Food Truck Market Insights
The United States food truck landscape is consolidating around a stark split between premium custom builds and commodity trailer conversions. Prestige Food Trucks anchors the high end with stainless-steel fabrication and bespoke kitchen layouts. Sizemore Ultimate Food Trucks competes on volume throughput for budget-conscious operators. Titan Trucks Manufacturing dominates the middle tier with modular equipment packages.
A food truck is a motorized or towable commercial kitchen built on a vehicle chassis, typically featuring propane or electric cooking surfaces, refrigeration, ventilation hoods, and potable water systems designed for mobile food preparation and retail service. Gourmet street food configurations command the widest margin pools due to specialized equipment density. Mobile catering sustains the largest contract volume from corporate and institutional buyers. Dessert trucks occupy a narrower but defensible niche with lower per-unit build costs and faster turnaround cycles.
FDA Food Code compliance, state health department licensing, and local fire safety inspections collectively determine where trucks operate and what equipment they must carry. The USDA and OSHA frameworks add layers for meat-handling operations and worker safety in confined kitchen spaces. Stakeholders must monitor how municipal zoning boards and commissary regulations in target metros constrain or enable fleet deployment strategies.
Market Dynamics
State-level commissary kitchen mandates and municipal zoning board rulings are fragmenting operational permissions across metropolitan corridors, forcing fleet operators to maintain redundant compliance infrastructure for multi-city deployment.
Growth Catalysts
- Corporate Campus Catering:Austin and Nashville metropolitan employers are expanding mobile food service contracts for employee lunch programs, creating predictable revenue streams for fleet operators with health-department pre-certification.
- FDA Food Code Harmonization:Updated national standards for mobile food units are reducing interstate operational friction, enabling commissary kitchen networks to serve multi-state fleets under unified inspection protocols.
- Electric Propulsion Retrofits:Battery-electric drivetrain conversions for existing chassis are opening zero-emission zones in California and New York metros previously restricted to diesel-powered units.
Market Restraints
- Stainless Steel Input Volatility:Custom fabrication shops face margin compression from nickel and chromium price swings, forcing build-quote validity windows as narrow as 14 days.
- Commissary Kitchen Concentration:Houston and Dallas-Fort Worth operators depend on a limited pool of licensed prep facilities, creating bottlenecks during peak festival seasons.
- Propane System Certification Delays:NFPA 58 compliance inspections for onboard LPG storage are extending equipment commissioning timelines by 3-6 weeks in oversubmitted jurisdictions.
Strategic Opportunities
- Secondary Metro Expansion:San Antonio and Oklahoma City corridors show underpenetrated demand relative to permit issuance rates, offering first-mover positioning before saturation.
- USDA Meat-Handling Integration:Onboard HACCP-compliant cold-chain modules are opening federal contract eligibility for disaster relief and military base catering previously restricted to brick-and-mortar commissaries.
- Cloud Kitchen Convergence:Partnership models with ghost kitchen operators are unifying prep capacity across stationary and mobile assets, reducing per-unit capital intensity for new market entrants.
Industry Challenges
- Certified Food Protection Manager Scarcity:ServSafe-level credential holders command premium wages in Texas metros, constraining fleet scaling for operators without in-house training pipelines.
- Multi-Jurisdictional Fire Suppression Standards:Ansul system specifications vary between Austin, Dallas, and Houston fire marshals, forcing redundant equipment configurations or costly mid-route modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Food Truck Market |
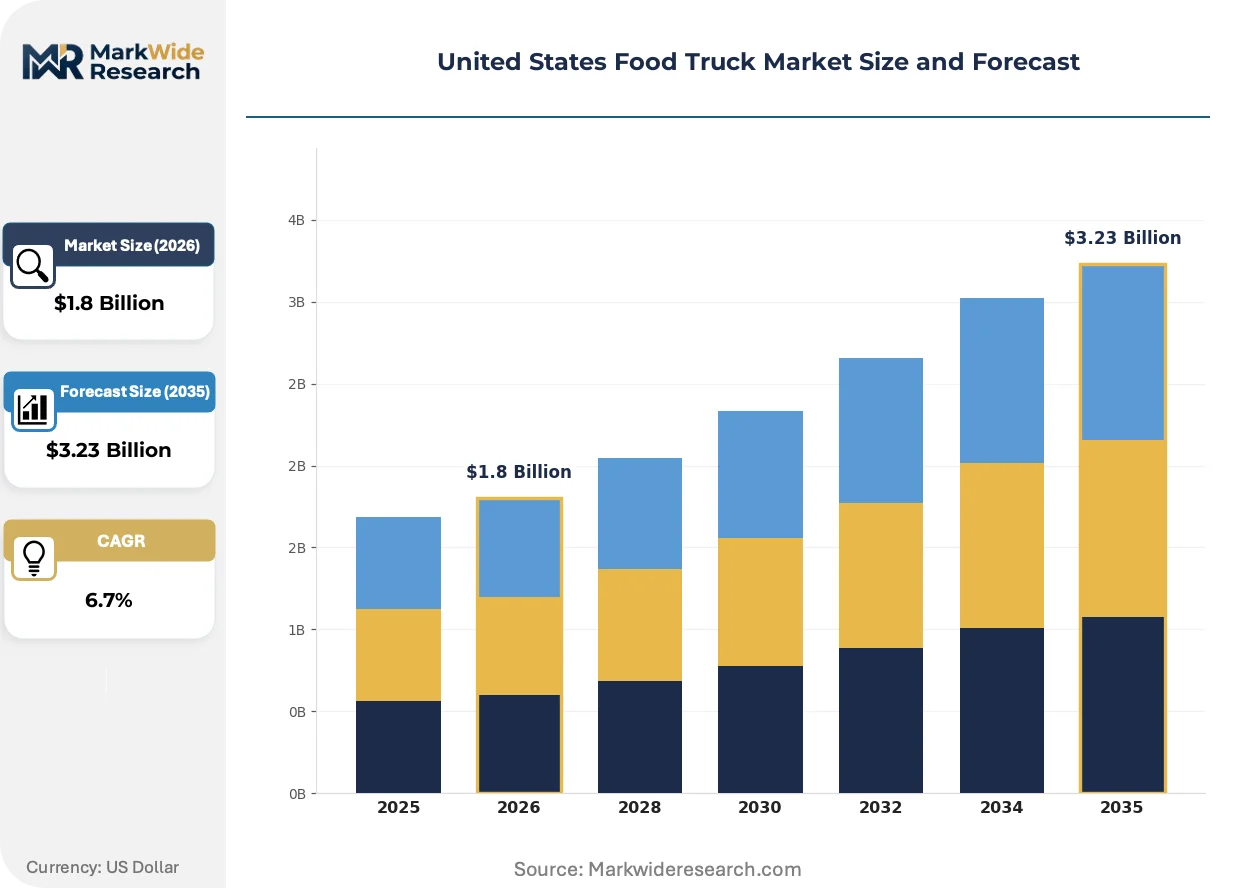
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile Catering, Gourmet Street Food, Festival Vendors, Dessert Trucks Food Type: Tacos, Burgers, Vegan Options, Barbecue Customer Type: Office Workers, Event Attendees, College Students, Tourists Pricing Model: Premium Pricing, Value Meals, Combo Offers, Daily Specials |
| Companies Covered | Titan Trucks Manufacturing, Sizemore Ultimate Food Trucks, Prestige Food Trucks, MSM Catering Trucks Mfg. Inc., Golden State Trailers, United Food Truck LLC, Cruising Kitchens, Food Trucks USA, M&R Specialty Trailers and Trucks, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Food Truck Market Trends and Innovations
Equipment manufacturers and fleet operators are converging on modular kitchen architectures that compress build-to-deployment cycles while accommodating divergent municipal inspection regimes.
Integrated battery-electric cooking suites with induction ranges and onboard solar augmentation are unifying power architecture across gourmet and catering configurations. Operators in California and Pacific Northwest metros are adopting these systems to access zero-emission zones and reduce generator fuel logistics. This convergence is compressing the traditional split between premium custom builds and commodity trailer conversions into a single configurable platform tier.
OSHA confined-space worker safety enforcement for food truck kitchen environments is tightening ventilation hood and egress requirements nationwide. The agency's updated guidance on propane inhalation risk is forcing retrofits of existing fleets with enhanced exhaust monitoring. Gourmet segment operators with specialized equipment density face disproportionate compliance costs relative to simpler mobile coffee or dessert configurations.
Corporate procurement departments are consolidating vendor relationships through multi-year mobile catering contracts with volume guarantees and performance clauses. Festival and event promoters in Texas corridors are responding by offering preferred placement and reduced site fees to pre-qualified fleet operators with corporate safety credentials. This channel consolidation favors mid-tier fleet owners with standardized equipment packages over single-unit artisan operators.
United States Food Truck Market Segmentation
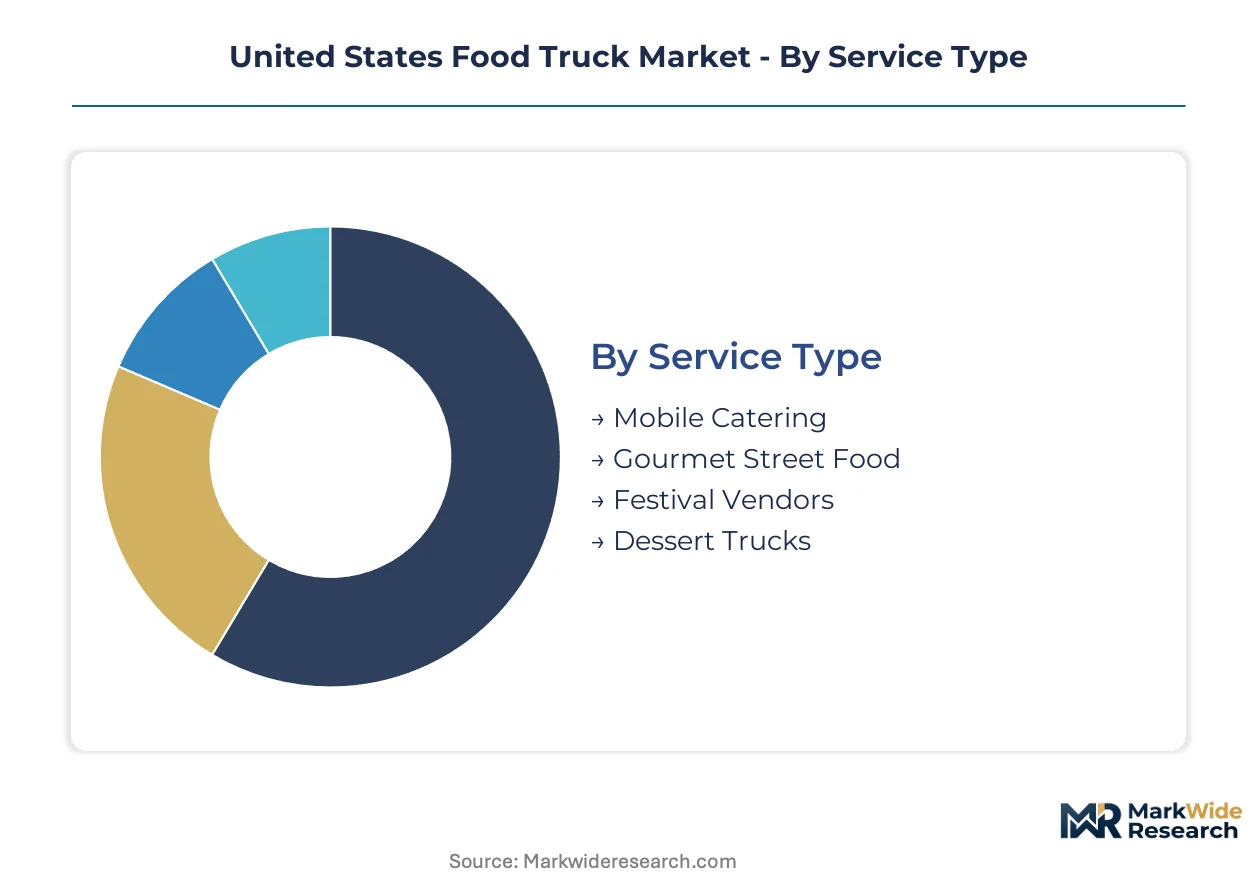
Segmentation in the United States food truck market reveals how operators align equipment configurations, menu engineering, and route planning with distinct revenue models. Each category exposes different margin structures and regulatory exposure, from high-volume corporate catering to premium gourmet builds with specialized ventilation systems.
Service Type:
The customization-vs-standardization spectrum across service types runs from bespoke stainless-steel fabrications for gourmet operators to commodity trailer conversions for festival circuits.
- Mobile Catering:Purpose-built units with modular serving lines and bulk holding capacity designed for corporate campus lunch programs and institutional contracts. Demand concentrates in Austin and Nashville metropolitan corridors where employers are expanding pre-qualified vendor rosters for predictable employee meal service.
- Gourmet Street Food:High-density kitchen configurations featuring specialized equipment such as plancha grills, tandoor ovens, or sous-vide immersion circulators. Houston and Dallas-Fort Worth operators command widest margin pools through differentiated menu offerings requiring complex ventilation hood systems and enhanced fire suppression.
- Festival Vendors:Streamlined builds optimized for rapid deployment and high throughput at seasonal events.
- Dessert Trucks:Lower capital intensity with reduced refrigeration loads and faster equipment commissioning cycles.
Leading the category by volume: Mobile Catering. Growing fastest: Gourmet Street Food.
Food Type:
Menu specialization across food types maps directly to equipment density requirements and supply chain complexity, with protein-handling operations triggering additional USDA compliance layers.
- Tacos:Compact griddle-and-steam table configurations enabling high-volume protein and vegetable preparation with minimal footprint. Texas metropolitan corridors show concentrated demand where regional palate preferences support premium tortilla and salsa sourcing.
- Burgers:Flattop griddle dominance with integrated holding cabinets and high-BTU burner arrays for patty production speed. FDA Food Code meat-handling protocols and HACCP cold-chain requirements add operational complexity relative to plant-based alternatives.
- Vegan Options:Reduced refrigeration infrastructure with emphasis on produce washing systems and allergen-segregated prep zones.
- Barbecue:Onboard smoker integration or commissary-based finishing models with specialized exhaust management.
Volume leader: Tacos. Steepest expansion trajectory: Vegan Options.
Customer Type:
Customer segmentation reveals divergent price elasticity and frequency patterns, with corporate procurement departments imposing performance clauses unavailable to transient tourist demand.
- Office Workers:Recurring weekday demand concentrated in downtown Austin and Nashville business districts with preference for mobile catering contracts offering nutritional transparency and speed-of-service guarantees. Corporate campus programs are consolidating vendor relationships around multi-year agreements with volume minimums.
- Event Attendees:Spiky weekend and seasonal demand tied to festival calendars and sporting events across Texas corridors. Pre-qualification requirements from event promoters are favoring fleet operators with standardized safety credentials over single-unit artisan vendors.
- College Students:Price-sensitive demand with high social media amplification potential and late-night service windows.
- Tourists:Experience-driven purchasing with willingness to pay premium for localized or Instagram-differentiated offerings.
Dominant by contract value: Office Workers. Expanding most quickly: Event Attendees.
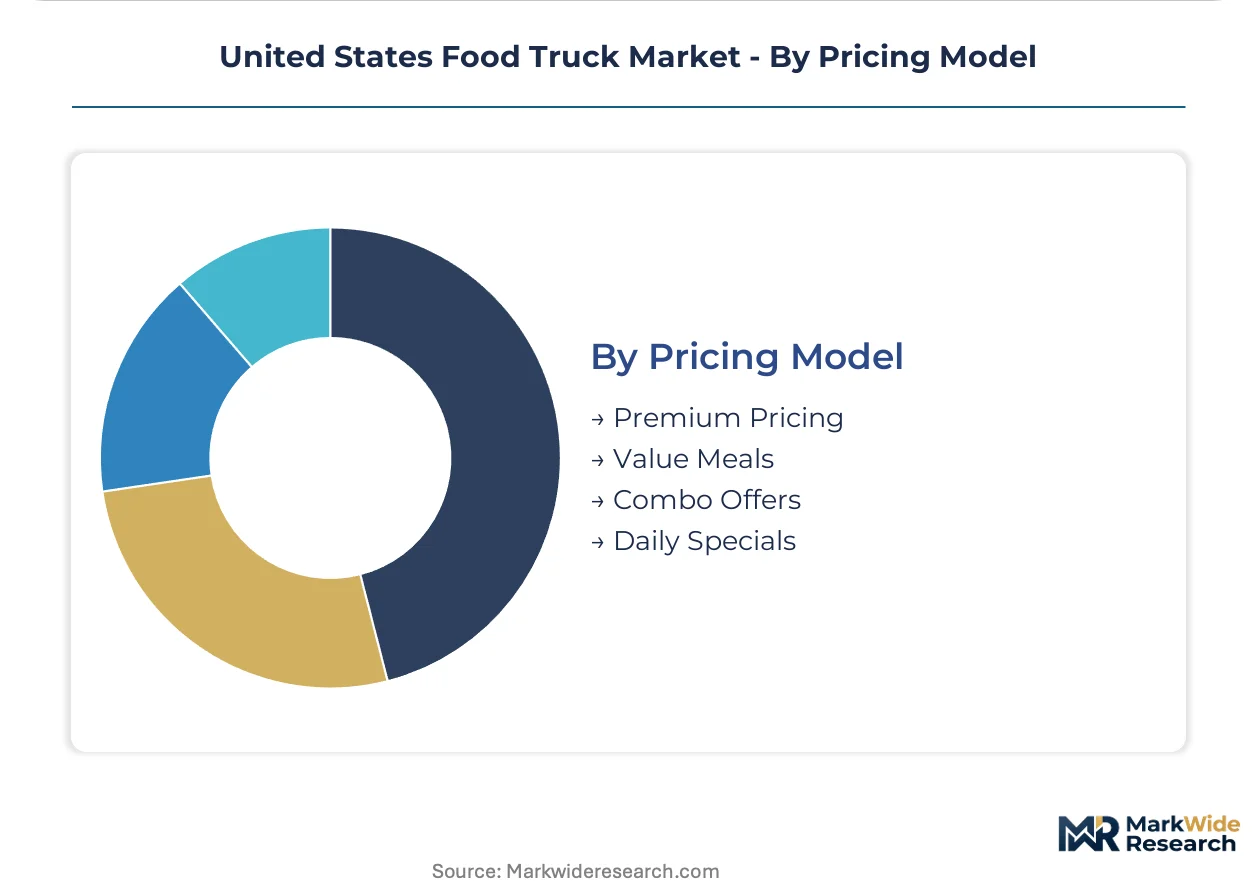
Pricing Model:
Pricing architecture reflects the tension between per-transaction revenue maximization and customer lifetime value cultivation through loyalty mechanics.
- Premium Pricing:Ingredient-forward positioning with transparent sourcing narratives and limited-menu depth enabling operational focus. Gourmet segment operators in Houston and Dallas-Fort Worth deploy this model to justify specialized equipment density and higher commissary kitchen costs.
- Value Meals:Bundled protein-starch-beverage combinations engineered for throughput speed and ticket average elevation. Mobile catering contracts for corporate campuses rely on this structure to meet per-employee meal allowances while preserving operator margin.
- Combo Offers:Cross-category bundling strategies combining entree and dessert purchases.
- Daily Specials:Inventory-driven pricing to manage perishable throughput and create urgency.
Highest revenue concentration: Premium Pricing. Gaining share fastest: Value Meals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston and Dallas-Fort Worth anchor the national food truck manufacturing and deployment activity, with Texas metropolitan corridors generating concentrated demand for both custom fabrication and mobile catering services.
Texas Gulf Coast
Houston's energy sector workforce drives corporate campus lunch contracts requiring health-department pre-certification. The Texas Department of State Health Services enforces commissary kitchen mandates that constrain fleet scaling during peak festival seasons. Fabrication shops in the Houston metro face stainless steel input volatility from nickel price swings.
North Texas
Dallas-Fort Worth operators depend on a limited pool of licensed prep facilities, creating bottlenecks for mobile catering expansion. FDA Food Code harmonization efforts are reducing interstate friction for multi-city fleet deployment. The metro's corporate procurement departments are consolidating vendor relationships through multi-year mobile catering agreements.
Central Texas
Austin's technology employers are expanding pre-qualified vendor rosters for predictable employee meal service. Municipal zoning board rulings fragment operational permissions, forcing redundant compliance infrastructure. The city's festival promoters offer preferred placement to fleet operators with corporate safety credentials.
Tennessee Corridor
Nashville metropolitan employers are expanding mobile food service contracts for employee lunch programs. State health department licensing requirements determine equipment specifications for interstate operators. The corridor shows underpenetrated demand relative to permit issuance rates, offering first-mover positioning.
California Metros
Los Angeles and San Francisco operators adopt battery-electric cooking suites to access zero-emission zones previously restricted to diesel-powered units. CARB regulations accelerate drivetrain conversion timelines. Pacific Northwest metros follow similar electrification patterns to reduce generator fuel logistics.
United States Food Truck Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a fragmented vendor base where custom fabrication shops face margin compression from raw material volatility. The market structure splits between premium stainless-steel fabricators, volume-oriented trailer converters, and modular equipment packagers. Strategic archetypes include bespoke kitchen layout specialists, budget throughput maximizers, and middle-tier configurable platform providers. Competitive moves center on electric propulsion retrofit partnerships and cloud kitchen convergence models.
Among Texas-based fabricators, Titan Trucks Manufacturing, Prestige Food Trucks, and Cruising Kitchens exemplify distinct positioning archetypes. Titan Trucks Manufacturing occupies the middle tier with modular equipment packages. Prestige Food Trucks anchors the premium vector with bespoke stainless-steel fabrication. Cruising Kitchens represents the custom build specialist segment serving gourmet operators with specialized ventilation requirements. These three entities collectively illustrate how geographic clustering around Houston and Dallas-Fort Worth manufacturing corridors shapes competitive differentiation through proximity to commissary kitchen networks and corporate catering demand.
| Leading Market Players |
|---|
| Titan Trucks Manufacturing |
| Sizemore Ultimate Food Trucks |
| Prestige Food Trucks |
| MSM Catering Trucks Mfg. Inc. |
| Golden State Trailers |
| United Food Truck LLC |
| Cruising Kitchens |
| Food Trucks USA |
| M&R Specialty Trailers and Trucks |
| Others |
Pricing and Supply Chain Analysis
Bespoke stainless-steel fabrication versus commodity trailer conversion splits the United States food truck market into divergent cost structures, with premium builds commanding threefold capital outlays that flow through to lease-rate premiums and residual value retention, while commodity converters compete on throughput-per-dollar and rapid fleet turnover cycles that compress supplier payment windows.
Pricing Analysis
Throughput-based pricing anchors mobile catering contracts, where corporate campus agreements in Austin and Nashville tie operator compensation to meals-served-per-hour guarantees rather than equipment specifications. Price differentiation separates health-department pre-certified fleets from uncertified competitors, with FDA Food Code compliance tiering access to institutional buyers. Pricing pressure stems from stainless steel input volatility, as nickel and chromium price swings force fabrication shops to narrow quote validity to fourteen-day windows. Budget-conscious festival operators exhibit highest price sensitivity, while corporate procurement departments prioritize uptime guarantees over per-unit cost.
Supply Chain Analysis
Stainless steel sheet supply rests on domestic mills in Pennsylvania and Indiana, with specialty-grade nickel alloys drawing from Canadian and Australian mining operations. Chassis fabrication depends on Ford and Chevrolet commercial vehicle platforms, while propane system components source from Mexican and Canadian valve manufacturers. Supply chain risk concentrates in NFPA 58 certification delays, where oversubmitted jurisdictions extend equipment commissioning timelines by three to six weeks. Distribution runs through regional fabrication clusters in Houston and Dallas-Fort Worth, with finished units deploying via direct-to-operator delivery or dealer networks serving secondary metros.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States food truck market is becoming a vertical-integration race, with fleet operators pursuing captive commissary kitchen capacity to escape licensed-prep-facility bottlenecks during peak festival seasons.
For Market Incumbents: Deploy modular equipment standardization to compress build-to-deployment cycles and reduce per-unit customization labor. Titan Trucks Manufacturing and Prestige Food Trucks should consolidate supplier relationships with Pennsylvania stainless mills to hedge nickel price exposure, while expanding corporate catering pre-certification pipelines to defend against cloud kitchen convergence models. Channel control through multi-year mobile catering agreements with Austin and Nashville technology employers provides defensive moats against commodity trailer converters. For New Entrants and Emerging Players: Digital-native fleet management platforms offer the lowest-friction entry vector, enabling real-time route optimization and corporate client dashboards that legacy operators lack. San Antonio and Oklahoma City corridors present underpenetrated demand relative to permit issuance rates, with first-mover positioning available before saturation. USDA meat-handling integration for disaster relief and military base catering opens federal contract eligibility previously restricted to brick-and-mortar commissaries. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-tier configurable platform providers with standardized equipment packages and multi-state commissary networks. Long-term viability over the coming decade hinges on electric propulsion retrofit capabilities and zero-emission zone access in California and New York metros. Watch for FDA Food Code harmonization progress as the inflection signal enabling interstate fleet scaling without redundant compliance infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Commissary Kitchen Backward Integration | Captive prep capacity eliminates Houston and Dallas-Fort Worth bottlenecks during festival peaks. |
| Electric Propulsion Retrofit Partnership | Battery-electric drivetrain conversions unlock California and New York zero-emission zones. |
| Corporate Catering Pre-Certification Pipeline | Health-department pre-qualification secures Austin and Nashville multi-year contract volume. |
| Cloud Kitchen Convergence Model | Ghost kitchen partnerships unify stationary and mobile prep capacity for new entrants. |
| USDA Meat-Handling Module Integration | Onboard HACCP-compliant cold-chain opens federal disaster relief and military base eligibility. |
Research Methodology
Multi-period observation of permit issuance rates, commissary kitchen licensing, and corporate catering contract awards anchored the trend analysis, supplemented by interviews with Texas-based fabrication shop owners, fleet operators in Houston and Dallas-Fort Worth, municipal health department inspectors, and corporate procurement managers at Austin technology employers. Secondary validation drew from FDA Food Code update dockets, Texas Department of State Health Services licensing records, NFPA 58 inspection backlogs, and SEC filings of publicly traded food service equipment manufacturers. Bottom-up unit economics modeling triangulated against top-down market sizing from fabrication capacity and deployment velocity.
Segment-weighting across service type, food type, customer type, and pricing model dimensions structured the analytical framework, with each category assigned proportional contribution based on revenue concentration and growth trajectory over the projection horizon. CAGRs were derived from fitted trend lines applied to historical deployment data and forward-looking contract pipeline visibility. Industry-specific forecast inputs included stainless steel price indices, electric vehicle conversion subsidy schedules, and municipal zoning board ruling patterns across target metropolitan corridors.
Inputs from health department licensing databases and corporate catering procurement disclosures were available through the study window; gaps in real-time commissary kitchen utilization rates introduce uncertainty bands around peak-season capacity constraint assumptions. Forecasts reflect documented assumptions regarding FDA Food Code harmonization timing and electric propulsion retrofit adoption curves. A small set of triggers—nickel price volatility spikes, NFPA 58 inspection backlog clearance rates, and zero-emission zone expansion announcements—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Commercial Air Fryer Oven Market
Food Service
Europe Inflight Catering Market
Food Service
Latin America Inflight Catering Market
Food Service
India Inflight Catering Market
Food Service
Commercial Ice Dispenser Market
Food Service
Sandwich Toasters Market
Food Service
Global Food Retail Market
Food Service
Food and Grocery Retail Market
Food Service
Steam Tables and Food Well Market
Food Service
Clear Ice Maker Market
Food Service
United Kingdom Quick Service Restaurant Market
Food Service
Gas Fryers Market
Food Service
Food Trays Market
Food Service
Commercial Cutlery Market
Food Service
South Korea Foodservice Market
Food Service
GCC Food Service Market