
 Inflight Catering Market | 2026-2036
Inflight Catering Market Size, Share, and Industry Trends Forecast 2026-2036
Inflight Catering Market Intelligence
Low-cost carrier procurement is rebalancing toward buy-on-board and retail-style snack programs. SATS Ltd leverages its Singapore hub infrastructure to dominate Asia-Pacific turnaround operations. Newrest specializes in remote-site and charter aviation catering, sustaining margin pools outside mainstream airline contracts. Emirates Flight Catering controls one of the world's largest centralized airline kitchens, anchoring Dubai's position as a catering logistics node.
Inflight catering encompasses the commercial preparation, assembly, and delivery of food and beverage items to aircraft operators for consumption during flight, with specifications governed by HACCP protocols, weight restrictions, and galley equipment dimensions including standard ATLAS and KSSU container formats. The client type dimension shows airlines commanding the largest volume base while private jets generate the highest per-passenger revenue. Ready-to-eat meals lead the delivery mode category in frequency, though on-demand custom catering is expanding fastest among premium cabin segments. Special requests within service type, including allergen-specific and religious-diet meals, represent a concentrated margin pool due to premium pricing and lower competitive intensity.
FDA food safety regulations and EU 852/2004 hygiene standards govern cross-border catering operations, while EASA and FAA impose specific galley fire-safety and equipment certification requirements that shape product format and packaging material selection. The EU Green Deal's packaging waste directives are pressuring single-use plastic elimination across European catering supply chains. Stakeholders must monitor evolving national biosecurity protocols and their impact on centralized kitchen versus local station sourcing decisions.
Market Dynamics
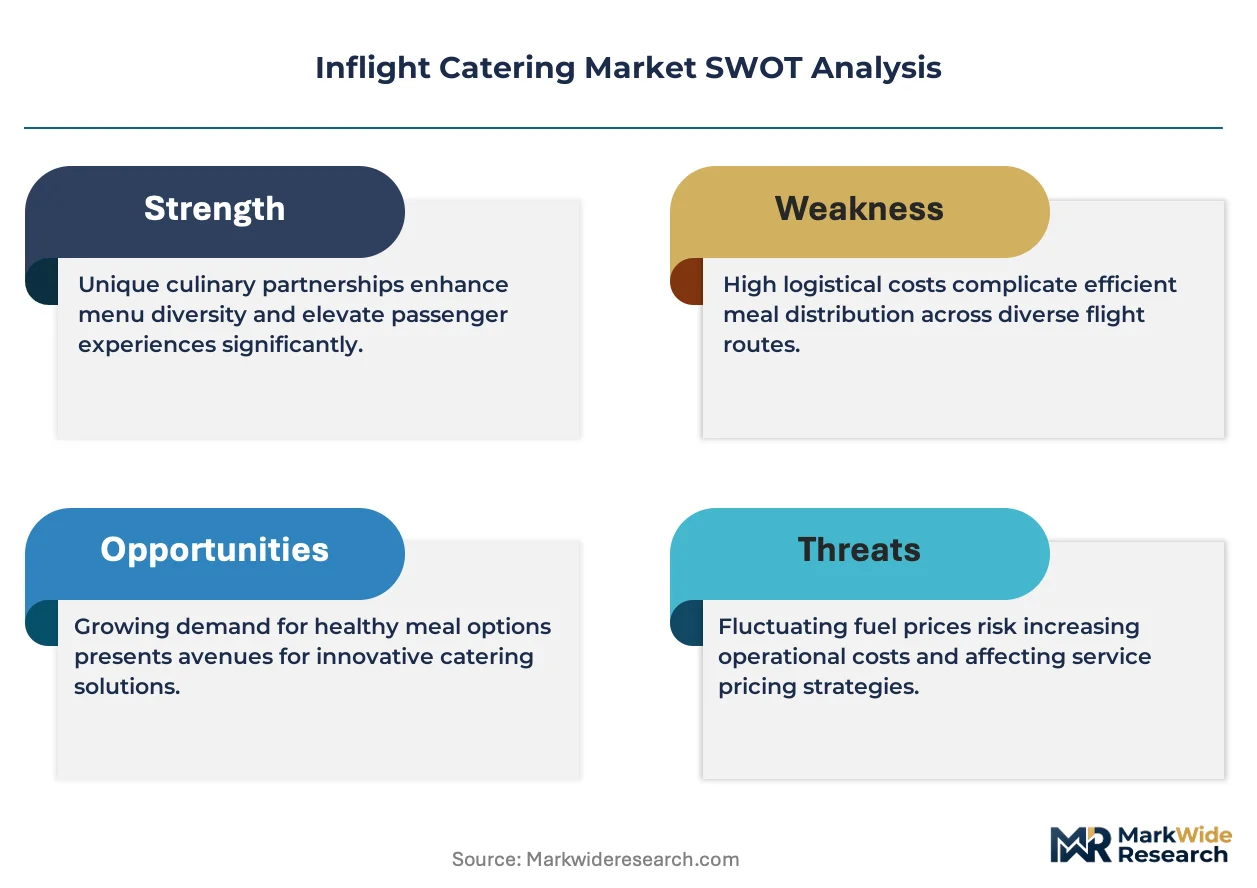
The EU F-Gas Regulation and parallel sustainability mandates are compressing cold-chain logistics architectures, forcing operators to abandon conventional refrigerants and redesign galley loading protocols across hub airports.
Growth Catalysts
- Full-service carrier premiumization:Long-haul carriers are expanding lie-flat cabin dining programs with chef-curated menus and wine pairings, lifting per-passenger catering spend.
- UAE hub concentration:Dubai's position as a long-haul transfer node concentrates high-volume catering demand, driving centralized kitchen infrastructure investment.
- HACCP protocol digitization:Real-time temperature monitoring and blockchain traceability are reducing food safety incident rates and insurance premiums.
Market Restraints
- Aviation fuel cost volatility:Jet fuel price swings compress airline operating margins, triggering procurement freezes and meal standardization mandates.
- Galley equipment lock-in:ATLAS and KSSU container format standards create path dependency, slowing packaging innovation adoption.
- Labor cost escalation:24/7 kitchen operations at hub airports face union wage pressure and night-shift premium requirements.
Strategic Opportunities
- Sustainable packaging transition:EU Green Deal packaging waste directives create first-mover advantage for compostable tray and cutlery suppliers.
- Private aviation expansion:Ultra-high-net-worth charter demand generates 8-12x per-passenger revenue multiples versus commercial airline contracts.
- AI-driven demand forecasting:Machine learning models analyzing booking patterns and seasonal routes are reducing overproduction waste by double-digit percentages.
Industry Challenges
- Biosecurity protocol fragmentation:Post-pandemic national health regulations vary on centralized kitchen versus local station sourcing, complicating network design.
- Cross-border certification timelines:FDA and EASA dual approvals for new galley equipment extend product launch cycles by 18-24 months.
- Specialized cold-chain workforce scarcity:Refrigeration technicians with aviation security clearances command premium wages and limited availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inflight Catering Market |
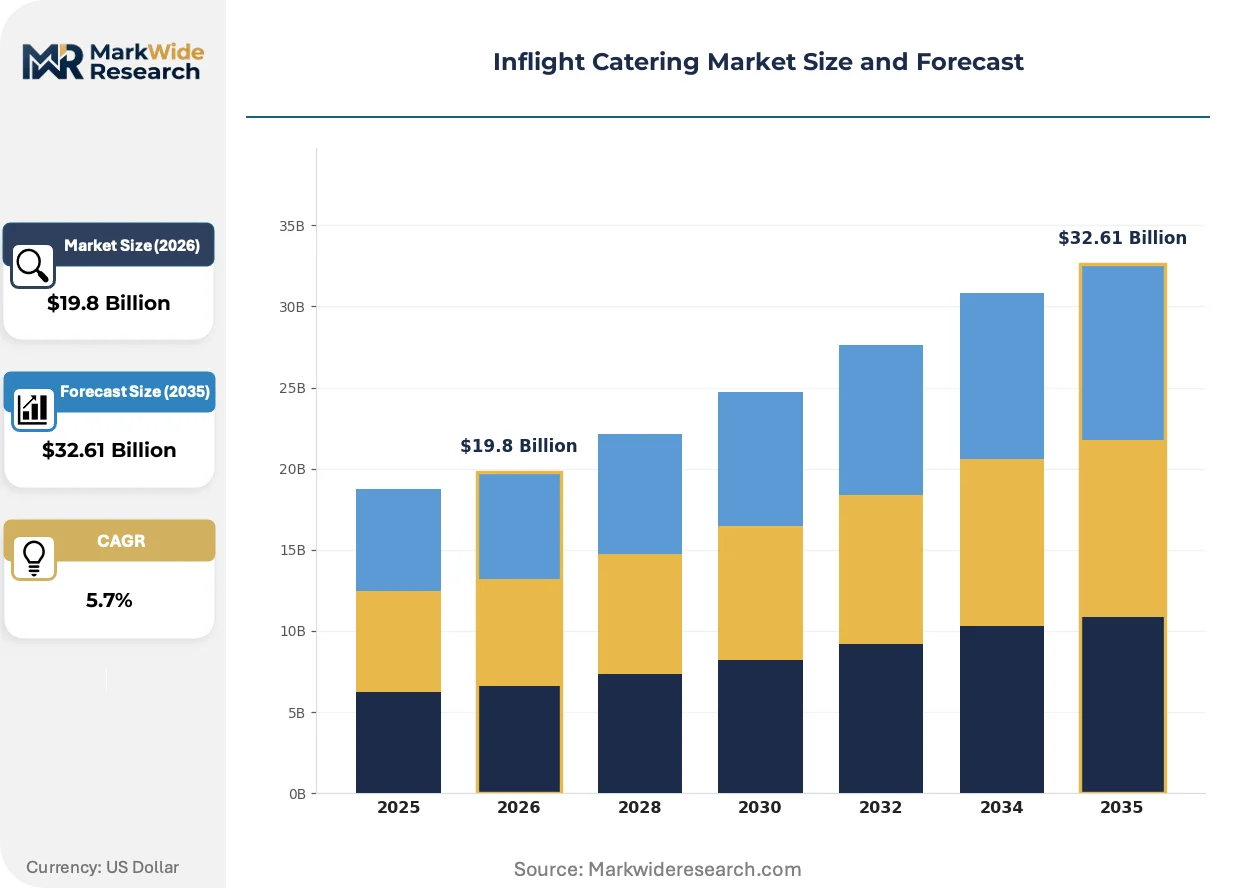
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $32.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Meals, Beverages, Snacks, Special Requests Client Type: Airlines, Private Jets, Charter Services, Cargo Carriers Delivery Mode: Ready-to-Eat, Pre-Packaged, On-Demand, Custom Catering Food Category: Vegetarian, Vegan, Gluten-Free, Halal |
| Companies Covered | SATS Ltd, Newrest, LSG Group, Cathay Pacific Catering Services, DO & CO, gategroup, Emirates Flight Catering, Flying Food Group, Dnata, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inflight Catering Market Strategic Shifts & Innovations
Automation and sustainability imperatives are restructuring kitchen operations and supplier relationships, with digital traceability and alternative proteins emerging as distinct innovation vectors.
Robotic meal assembly systems are converging with computer vision quality control in high-volume hubs. Emirates Flight Catering and SATS Ltd have deployed automated tray-setting lines that reduce labor hours per unit while maintaining HACCP compliance. This convergence is compressing the cost gap between premium and standard meal production, enabling tiered service at scale.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants across cold-chain logistics. Industrial consequence includes accelerated adoption of CO2 transcritical systems and magnetic refrigeration prototypes in centralized airline kitchens. European catering operators face 2027 compliance deadlines, driving equipment replacement cycles ahead of typical amortization schedules.
Airline procurement departments are unbundling catering contracts from ground handling agreements, creating direct supplier relationships. Low-cost carriers pioneered this separation; full-service carriers now follow, negotiating meal-unit pricing separately from ramp services. This pattern is most visible in Asia-Pacific hub markets where SATS and Newrest compete for standalone catering contracts.
Inflight Catering Market Segmentation
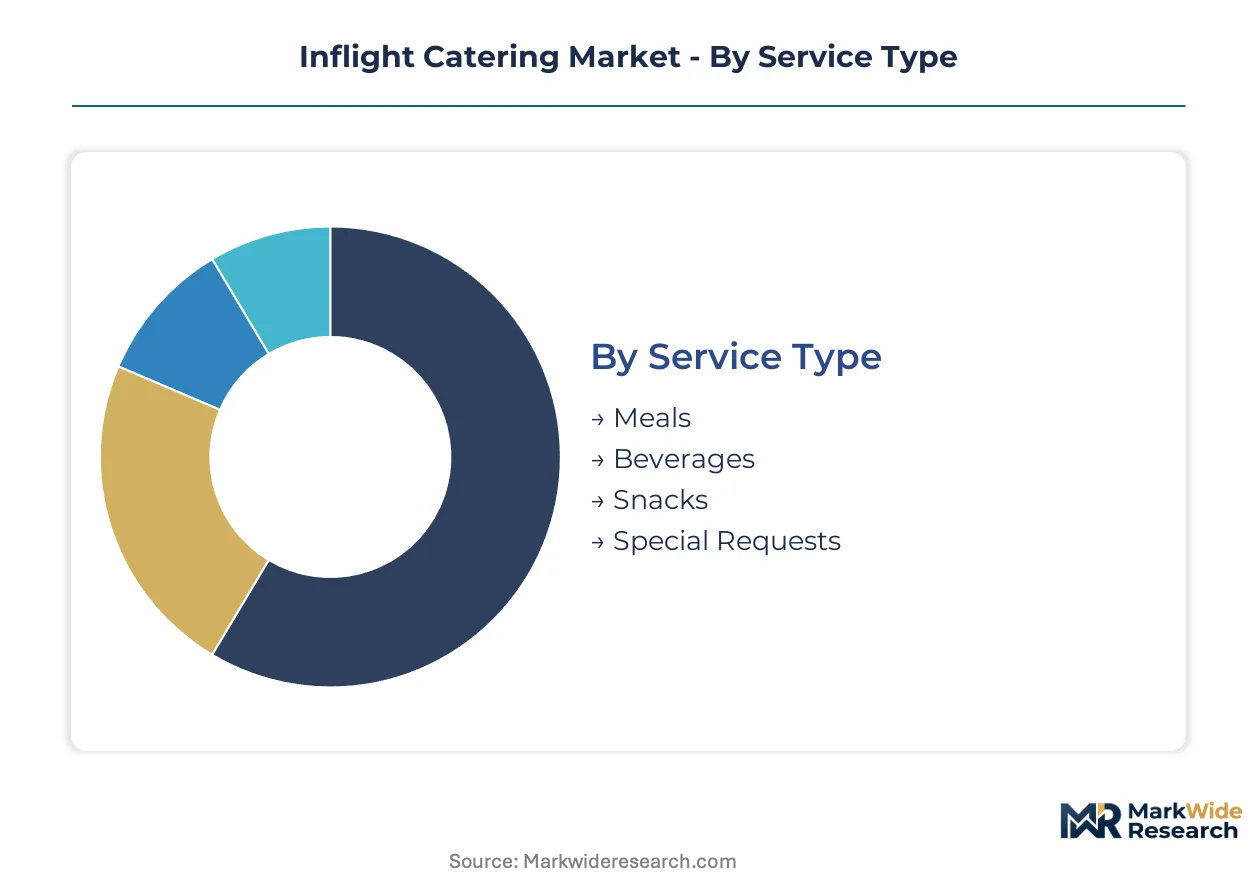
Segmentation in inflight catering reveals how procurement economics diverge across operational models. Airlines prioritize volume scalability and HACCP compliance, while private aviation segments extract premium margins through customization intensity. Understanding these fault lines exposes where technology investments and regulatory adaptation concentrate.
Service Type:
Customization intensity varies sharply across this category, from mass-produced meal trays to individually specified dietary accommodations.
- Meals:Multi-course tray assemblies governed by weight restrictions and ATLAS container dimensions. Full-service carriers in the United Arab Emirates drive demand concentration through lie-flat cabin programs requiring synchronized plating and galley loading protocols.
- Beverages:Wine pairings, premium spirits, and specialty coffee programs. Private jet operators in Dubai generate the highest per-passenger spend, with sommelier-curated selections commanding substantial markup over standard airline procurement.
- Snacks:Buy-on-board retail formats and short-haul provisioning. Low-cost carriers standardize SKUs to minimize loading complexity.
- Special Requests:Allergen-specific, religious-diet, and medical-meal preparations. Concentrated margin pool due to premium pricing and lower supplier competition.
Leading the category by volume: Meals. Expanding most quickly: Special Requests.
Client Type:
Contract structures separate this category into scheduled-service volume plays and ad-hoc premium engagements.
- Airlines:Scheduled carriers with recurring multi-year agreements. Hub airports in Singapore and Dubai concentrate procurement volume through centralized kitchen infrastructure.
- Private Jets:Ultra-high-net-worth charter and fractional ownership fleets. Per-passenger revenue multiples exceed commercial contracts significantly, with on-demand flexibility requirements.
- Charter Services:Irregular operations including sports team and government transport. Newrest specializes in this segment, sustaining margins outside mainstream airline pricing pressure.
- Cargo Carriers:Crew meal provisioning for freighter operations. Standardized requirements with limited customization scope.
Airlines dominate contract volume. Private Jets deliver the steepest revenue-per-unit trajectory.
Delivery Mode:
Production-to-consumption timing determines cold-chain architecture and inventory risk allocation across this category.
- Ready-to-Eat:Pre-plated meals held at controlled temperatures until loading. Emirates Flight Catering operates the world's largest centralized facility for this format, processing thousands of units daily through automated assembly lines.
- Pre-Packaged:Retail-style items with extended shelf stability. Low-cost carriers favor this mode for buy-on-board programs with minimal galley equipment requirements.
- On-Demand:Real-time preparation triggered by passenger booking data. AI-driven forecasting is reducing overproduction waste in premium cabin applications.
- Custom Catering:Bespoke menus for VIP and private aviation. SATS Ltd and specialized operators compete on chef network access and last-mile flexibility.
Ready-to-Eat commands the highest shipment frequency. Custom Catering gains share fastest in premium segments.
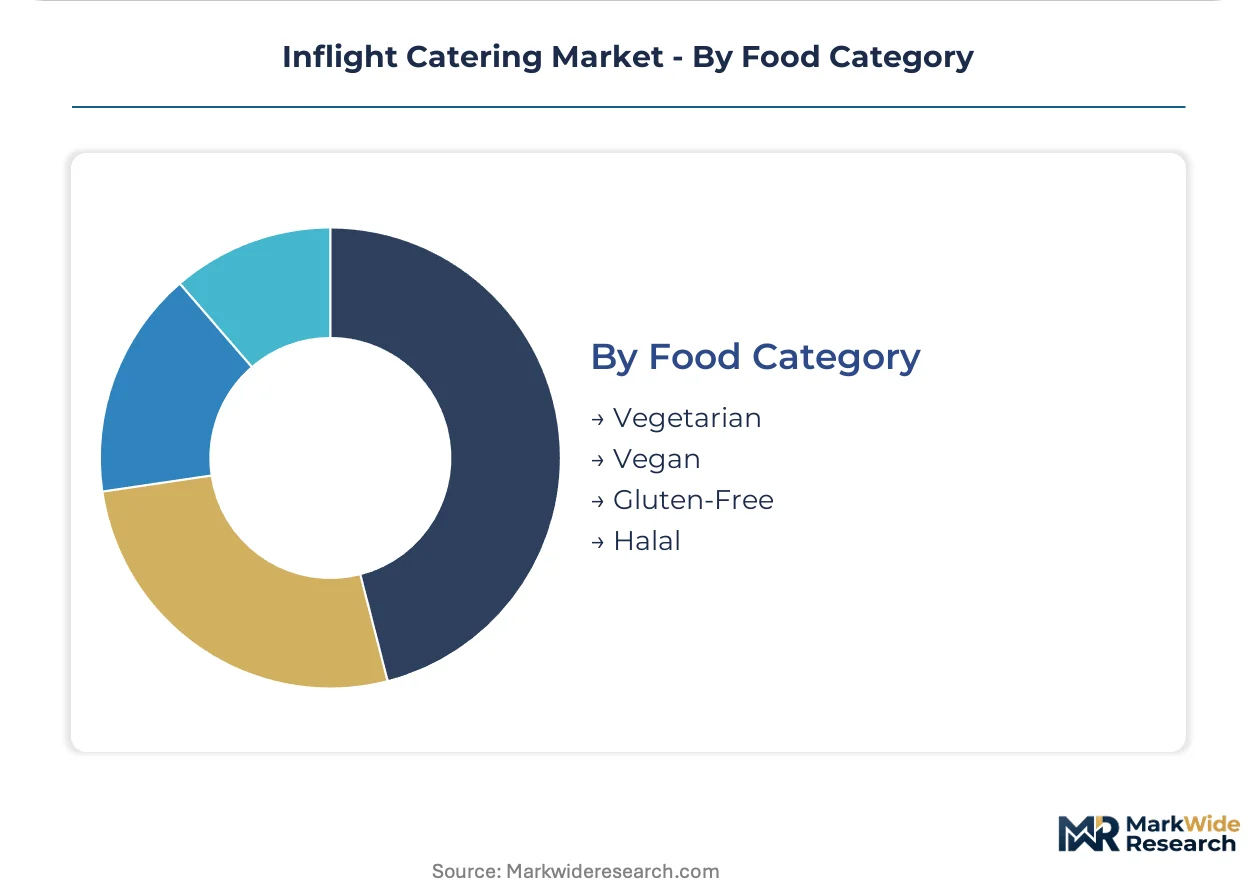
Food Category:
Religious compliance and allergen management create certification-driven tiering across dietary specifications.
- Vegetarian:Lacto-ovo and plant-forward meal options. Indian full-service carriers generate concentrated demand due to passenger demographic composition.
- Vegan:Exclusion of all animal derivatives. European carriers face accelerating requirements under EU Green Deal sustainability mandates.
- Gluten-Free:Celiac-safe preparation protocols with cross-contamination controls. Premium pricing reflects specialized supply chain segregation.
- Halal:Islamic dietary law compliance with certified slaughter and preparation. UAE-based kitchens anchor supply for Middle East-originating flights.
Halal leads by passenger volume served. Vegan climbs fastest on sustainability-aligned carrier commitments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's Jebel Ali Free Zone and Singapore's Changi Airport Free Enterprise Zone concentrate catering infrastructure investment through tax-exempt equipment import and duty-free supply chain corridors. These zones anchor cold-chain logistics networks serving long-haul transfer traffic.
United Arab Emirates
Emirates Flight Catering processes thousands of meal units daily through automated assembly lines at Dubai International Airport. MOHAP enforces HACCP digitization mandates requiring real-time temperature monitoring across centralized kitchens. Dubai anchors the Gulf's largest catering logistics node, with equipment replacement cycles accelerating ahead of EU F-Gas Regulation parallel adoption timelines.
Singapore
SATS Ltd dominates Asia-Pacific turnaround operations through Changi's integrated cargo and catering zones. The country's national food regulator mandates blockchain traceability for cross-border cold-chain shipments. Seletar Aerospace Park clusters galley equipment maintenance and refrigeration technician training facilities serving regional carriers.
Germany
Frankfurt and Munich hubs drive premium cabin catering procurement for Lufthansa's long-haul network. EASA galley fire-safety certifications and EU 852/2004 hygiene standards govern equipment selection and kitchen design. Cologne-Bonn Airport concentrates specialized cold-chain logistics providers serving cargo carrier crew meal contracts.
United States
FAA equipment certification requirements and FDA food safety regulations shape galley container formats and cross-border sourcing protocols. Chicago O'Hare and Dallas-Fort Worth anchor domestic catering networks for full-service carrier premium programs. Flying Food Group operates from multiple US airport locations serving airline and private aviation segments.
United Kingdom
Heathrow's Terminal 5 clusters high-volume catering facilities serving British Airways' long-haul fleet. The Food Standards Agency enforces allergen segregation protocols that increase production complexity for special-diet meals. London City Airport concentrates private aviation catering specialists extracting premium margins from ultra-high-net-worth charter demand.
Inflight Catering Market Key Industry Players
Top-tier vendors anchor hub-airport infrastructure plays, while mid-scale operators compete on remote-site flexibility and specialized dietary accommodation. The market structures around three distinct competitive tiers: integrated airport service conglomerates, standalone catering specialists, and private aviation boutique providers. Consolidation pressure concentrates among Asia-Pacific and Middle Eastern operators seeking network density. Dominant competitive moves include strategic partnerships with airline procurement departments and backward integration into sustainable packaging supply chains.
Within the hub-infrastructure tier, SATS Ltd and Emirates Flight Catering exemplify scale-driven positioning through captive airport real estate and automated production lines. Newrest occupies a distinct archetype serving remote-site and charter aviation operations outside mainstream airline contract pricing pressure. These three entities represent the structural segmentation between volume-scale hub operators and flexibility-oriented specialists.
| Leading Market Players |
|---|
| SATS Ltd |
| Newrest |
| LSG Group |
| Cathay Pacific Catering Services |
| DO & CO |
| gategroup |
| Emirates Flight Catering |
| Flying Food Group |
| Dnata |
| Others |
Cost & Logistics Intelligence
Backward integration into sustainable packaging supply anchors pricing power for tier-one catering operators while compressing margins for non-integrated competitors serving price-sensitive low-cost carrier segments. This structural divide concentrates margin capture among Emirates Flight Catering and SATS Ltd, which leverage captive tray and cutlery production to offset jet fuel cost pass-through pressure from airline procurement departments.
Pricing Analysis
Short lead-time premiums dominate contract negotiations, with on-demand custom catering for private aviation commanding substantial markups over standard meal-unit pricing for scheduled carriers. Three-tier pricing structure across premium, standard, and economy levels reflects galley equipment certification tiers and HACCP digitization investment levels. Cost compression in standard meal production is intensifying because low-cost carriers unbundle catering from ground handling agreements. Charter services exhibit lowest price sensitivity due to irregular volume patterns and remote-site logistics complexity.
Supply Chain Analysis
Direct-to-airline channels handle hyperscale demand from full-service carriers, while specialized distributors serve private aviation and charter segments through chef-network relationships. Supply concentrates in the United Arab Emirates, Singapore, and Germany, where hub-airport infrastructure and regulatory clustering support centralized kitchen economics. Raw material dependencies include halal-certified proteins, temperature-sensitive dairy, and compostable packaging substrates. Single-source vulnerability runs through specialized cold-chain workforce pools with aviation security clearances. Distribution runs through bonded free zones at Dubai's Jebel Ali and Singapore's Changi to minimize duty exposure and equipment import friction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing backward control over sustainable packaging supply chains to defend margin pools as EU Green Deal mandates eliminate single-use plastic alternatives.
For Market Incumbents: Hedge against procurement unbundling by securing standalone catering contracts separate from ground handling agreements. Invest in CO2 transcritical refrigeration ahead of EU F-Gas Regulation parallel adoption timelines in the Middle East. Consolidate position through automated tray-setting line deployment at secondary hub airports where SATS and Emirates Flight Catering lack presence.
For New Entrants and Emerging Players: Enter via private aviation catering specialization where per-passenger revenue multiples exceed commercial contracts and incumbent footprint remains sparse. Target London City Airport and Dubai's Al Maktoum International for ultra-high-net-worth charter demand concentration. Differentiate through chef-network partnerships and last-mile flexibility rather than competing on meal-unit scale.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by airport service conglomerates seeking catering network density across Asia-Pacific and Middle Eastern hubs. Long-term viability favors operators with integrated sustainable packaging supply and HACCP digitization compliance. Watch AI-driven demand forecasting adoption rates as inflection indicator for operational efficiency gaps between tier-one and mid-scale competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sustainable Packaging | Captures margin pools as EU Green Deal eliminates plastic alternatives across European supply chains. |
| HACCP Digitization Investment | Reduces insurance premiums and satisfies MOHAP real-time temperature monitoring mandates in UAE kitchens. |
| AI-Driven Demand Forecasting Deployment | Compresses overproduction waste in premium cabin applications through machine learning booking pattern analysis. |
| Standalone Catering Contract Negotiation | Separates meal-unit pricing from ground handling agreements as full-service carriers follow low-cost carrier procurement patterns. |
| CO2 Transcritical Refrigeration Adoption | Accelerates equipment replacement cycles ahead of EU F-Gas Regulation compliance deadlines across European operations. |
Research Approach
Document review covered regulatory filings from EASA and FAA, EU F-Gas Regulation implementation guidance, and airline procurement contract structures, complemented by interviews with catering operations directors, airline procurement executives, cold-chain logistics specialists, and sustainable packaging suppliers. Secondary validation drew from customs trade data, airport authority infrastructure disclosures, and HACCP certification body records. Bottom-up meal-unit volume estimates triangulated against top-down airline passenger traffic projections.
Segment-level outputs across the projection horizon reflect modeled interactions between service type, client type, delivery mode, and food category dimensions. CAGRs were derived from trend extrapolation of premium cabin program expansion, low-cost carrier buy-on-board penetration, and private aviation fleet growth. Forecast inputs incorporated EU Green Deal packaging waste directive timelines, biosecurity protocol fragmentation scenarios, and galley equipment certification backlog estimates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under aviation fuel price volatility and labor cost escalation at 24/7 hub airport operations. Periodic stress-testing of base assumptions is recommended, particularly regarding centralized kitchen versus local station sourcing decisions under divergent national health regulations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Kamado Grill Market
Food Service
Africa Foodservice Market
Food Service
Europe Cloud Kitchen Market
Food Service
United States Smokeless Indoor Grills Market
Food Service
Supermarkets Market
Food Service
Food Truck Services Market
Food Service
Global Vending Machine Market
Food Service
Undercounter Ice Makers Market
Food Service
United States Biodegradable Food Service Disposables Market
Food Service
Restaurant Glassware Market
Food Service
Plates Market
Food Service
International Food Subscription Box Service Market
Food Service
Bar Refrigeration Market
Food Service
Rotisseries Market
Food Service
Saudi Arabia Full- Service Restaurants Market
Food Service
United States Foodservice Market