
 North America Online Food Delivery Market | 2026-2036
North America Online Food Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
North America Online Food Delivery Market Intelligence
Corporate catering procurement is realigning toward platform-based ordering as hybrid work patterns stabilize. DoorDash leverages its merchant-plus-enterprise dual infrastructure to capture institutional accounts. Uber Eats sustains rider density through cross-subsidy from its mobility network. Grubhub competes on subscription loyalty mechanics in legacy urban markets.
North America online food delivery encompasses digitally intermediated meal and grocery logistics connecting restaurants, retailers, and consumers through algorithmic dispatch and mobile interfaces. The system relies on real-time GPS tracking, dynamic batching engines, and thermal packaging standards to preserve food safety during last-mile transport. Quick Service Restaurants and grocery delivery anchor transaction volume, while subscription services capture the highest retention economics. Third-party delivery models dominate urban deployment, though click-and-collect gains traction where parking friction and labor costs favor consumer pickup.
FDA food safety rules, state-level ABC (alcohol beverage control) statutes, and municipal ghost-kitchen zoning codes shape operational permits and facility requirements across the region. California's Proposition 22 framework and similar gig-labor statutes in other states directly influence platform cost structures and pricing flexibility. Stakeholders must monitor regulatory fragmentation in labor classification, packaging waste mandates, and alcohol delivery permissions as these determine market access and margin sustainability.
Market Dynamics
Hybrid work stabilization is forcing enterprise catering procurement onto platform-based ordering systems, compressing traditional contract-catering margins while expanding addressable volume for algorithmic dispatch networks across California, Texas, and New York metro corridors.
Growth Catalysts
- Proposition 22 frameworks:California's gig-labor classification statute and similar state-level statutes create regulatory clarity that stabilizes platform cost structures and enables pricing predictability for multi-state operators.
- Ghost kitchen zoning liberalization:Municipal codes in Dallas, Houston, and Phoenix are permitting high-density delivery-only facilities that expand restaurant supply without traditional real estate overhead.
- Thermal packaging standards:Advances in phase-change materials and insulated pouch engineering extend safe holding times for prepared foods, expanding delivery radius economics for Quick Service Restaurant chains.
Market Restraints
- Driver supply volatility:Fuel cost fluctuations and vehicle maintenance burdens create input cost instability that platforms cannot fully pass through to consumers or merchants.
- ABC statute fragmentation:State-level alcohol beverage control permissions vary widely, blocking alcohol delivery expansion in Pennsylvania, Utah, and Mississippi despite consumer demand.
- Substitution from click-and-collect:Parking-abundant suburban locations favor consumer pickup over delivery fees, capping third-party penetration in exurban markets.
Strategic Opportunities
- Mexico cross-border corridor:Underpenetrated digital restaurant supply in Monterrey and Tijuana offers expansion potential for US-platform infrastructure adapted to local payment systems.
- Subscription bundling convergence:Grocery-plus-meal membership models that combine Instacart-style retail with DoorDash-style restaurant access capture higher retention economics than single-vertical subscriptions.
- Enterprise account APIs:Direct integration with corporate expense management systems creates channel bypass of traditional catering brokers for Fortune 500 headquarters clusters.
Industry Challenges
- Food safety certification timelines:FDA Food Safety Modernization Act compliance for multi-jurisdiction ghost kitchen networks requires extended audit cycles that delay facility launches.
- Legacy POS integration friction:Independent restaurants operate on fragmented point-of-sale systems that resist standardized order-routing protocols, forcing costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Online Food Delivery Market |
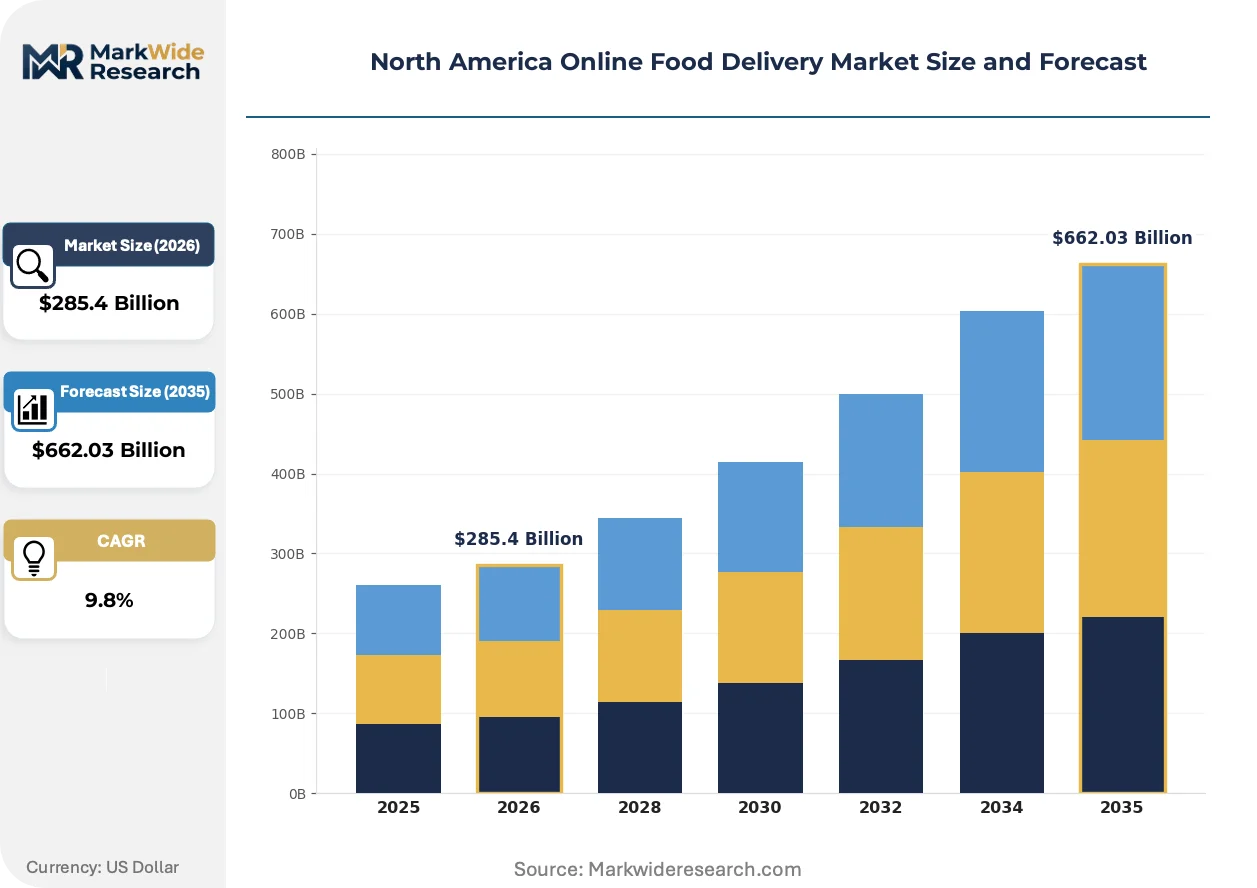
| Market Size in 2026 | $285.4 Billion |
| Market Size in 2035 | $662.03 Billion |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Quick Service Restaurants, Full-Service Restaurants, Grocery Delivery, Meal Kits Delivery Model: Third-Party Delivery, In-House Delivery, Click-and-Collect, Subscription Services Customer Type: Food Enthusiasts, Busy Professionals, Families, Students Cuisine Type: Italian, Chinese, Mexican, American |
| Companies Covered | Just Eat Takeaway.com, Deliveroo, DoorDash, Postmates, OLO, Uber Eats, Delivery Hero, Caviar, Grubhub, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Online Food Delivery Market Strategic Shifts & Innovations
Algorithmic batching and dynamic pricing engines are compressing delivery time windows while expanding per-rider throughput, reshaping unit economics across platform networks. Three developments merit particular attention.
Dynamic batching engines that cluster multiple orders into single driver routes is unifying previously separate meal and grocery delivery pools. Quick Service Restaurant chains and supermarket partners are adopting these systems simultaneously. The technology is unifying dispatch infrastructure that historically separated foodservice from retail logistics, collapsing the distinction between restaurant and grocery platform competitors.
FDA's Food Safety Modernization Act traceability rules and state-level packaging waste mandates are imposing new data-collection burdens on delivery intermediaries. Platforms must now maintain temperature logs and packaging provenance records across their contractor networks. California's SB 54 plastic packaging regulations are most affecting grocery delivery verticals, where operators are responding with deposit-return pilot programs and reusable container partnerships.
Corporate meal allowances are consolidating onto centralized platform accounts that displace individual reimbursement workflows. Human resources departments in technology and professional services verticals are mandating preferred vendor relationships with DoorDash and Uber Eats for business meal programs. This concentration is most visible in Seattle, San Francisco, and Austin, where hybrid office attendance patterns have stabilized at three-days-weekly and predictable catering volumes support contracted pricing tiers.
North America Online Food Delivery Market Segmentation
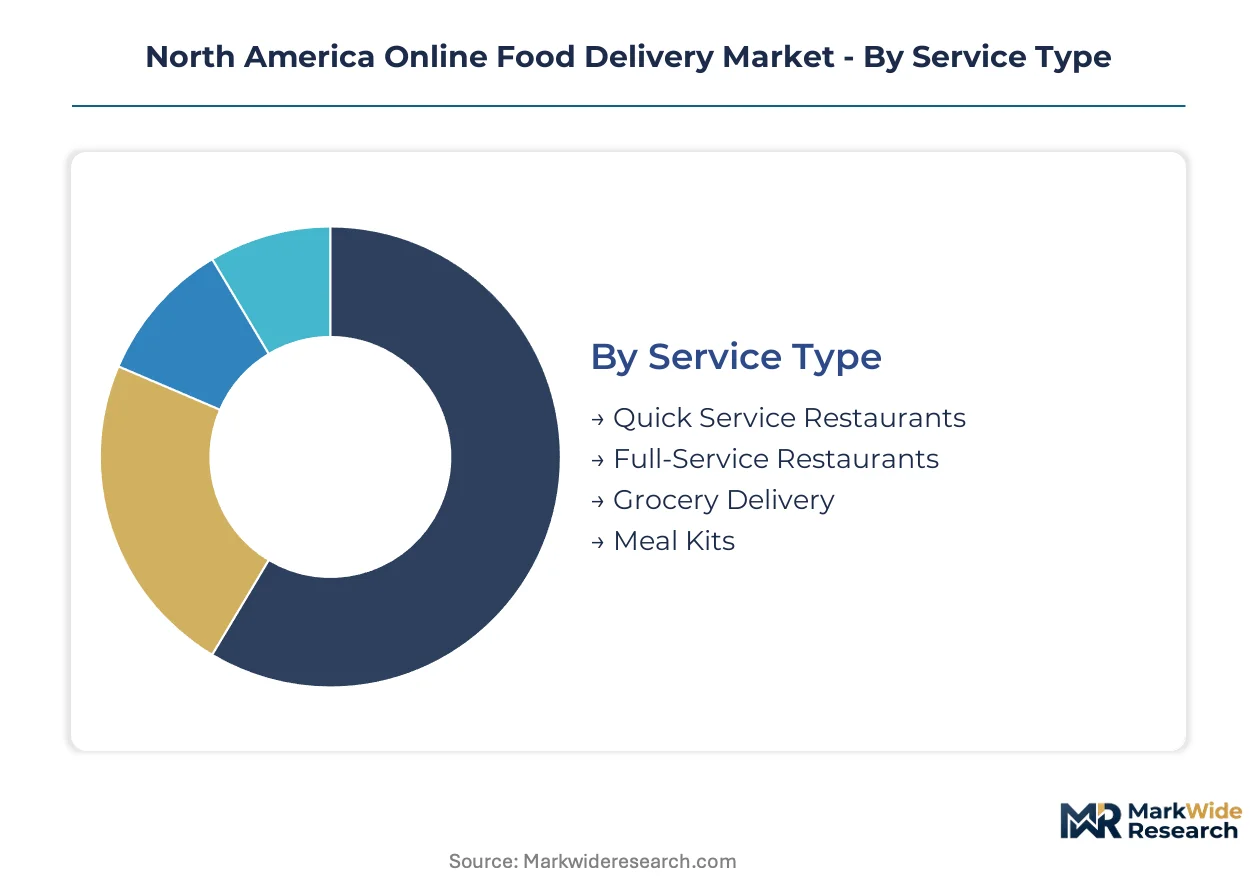
Platform operators configure dispatch algorithms and merchant onboarding protocols around service-type distinctions. Delivery-model segmentation determines capital intensity and labor classification exposure. Customer-type and cuisine-type splits guide marketing spend allocation and restaurant supply acquisition.
Service Type:
Standalone platforms dominate Quick Service Restaurant and grocery verticals, while embedded delivery modules integrate with Full-Service Restaurant reservation systems and meal kit subscription backends.
- Quick Service Restaurants:High-frequency, low-ticket transactions with standardized preparation windows. Demand clusters in Texas and California suburban corridors where drive-thru density overlaps with residential sprawl; thermal packaging standardization enables extended delivery radii for burger and pizza chains.
- Grocery Delivery:Complex SKU logistics requiring real-time inventory synchronization with supermarket POS systems. Expansion concentrates in New York metro and Pacific Northwest urban cores where parking scarcity and transit-oriented development suppress personal vehicle ownership.
- Full-Service Restaurants:Premium ticket sizes with variable preparation times. Embedded delivery modules integrate with reservation platforms; alcohol attach rates depend on state ABC statute permissions.
- Meal Kits:Pre-portioned ingredient bundles with weekly subscription cadence. Supply chains source through dedicated fulfillment centers rather than restaurant kitchens; customer acquisition costs exceed prepared meal verticals.
Volume placements concentrate in Quick Service Restaurants; the faster expansion belongs to Grocery Delivery.
Delivery Model:
Cost tier stratification separates capital-light third-party platforms from asset-heavy in-house fleets, with subscription services capturing retention premiums and click-and-collect minimizing last-mile labor exposure.
- Third-Party Delivery:Marketplace platforms connecting independent restaurants with gig-contracted drivers. California's Proposition 22 framework and similar state statutes govern labor classification costs; municipal ghost-kitchen zoning in Dallas and Houston expands addressable restaurant supply without traditional real estate overhead.
- Subscription Services:Membership models bundling delivery fee waivers with priority dispatch algorithms. Retention economics outperform per-transaction models; corporate meal allowance consolidation in Seattle and San Francisco accelerates enterprise adoption.
- In-House Delivery:Captive driver fleets employed directly by restaurant chains or grocery retailers. Vertical labor integration elevates fixed costs while insulating operators from gig-economy regulatory volatility.
- Click-and-Collect:Consumer pickup from designated staging areas or parking-lot handoff points. Parking-abundant suburban locations favor this model; substitution effects cap third-party penetration in exurban markets.
Transaction density peaks with Third-Party Delivery; Subscription Services climb the fastest as enterprise accounts consolidate procurement.
Customer Type:
Application context distinguishes occasion-based ordering patterns, with workplace and household meal occasions driving divergent platform feature requirements.
- Busy Professionals:Time-constrained ordering with corporate expense integration. Hybrid work stabilization in Austin and San Francisco metro areas concentrates midday and evening demand; HR-mandated preferred vendor relationships compress individual reimbursement workflows.
- Families:Multi-person order values with dietary restriction filtering and scheduled delivery windows. Weekend volume spikes contrast with professional weekday concentration; meal kit subscriptions align with household cooking occasion preferences.
- Food Enthusiasts:Discovery-oriented users prioritizing cuisine variety and restaurant ratings. Platform engagement centers on browse-and-search functionality rather than reorder velocity.
- Students:Price-sensitive demand concentrated in campus-adjacent geographies with late-night ordering peaks. Discount code redemption rates exceed other segments; loyalty program mechanics emphasize frequency rewards over spend thresholds.
Revenue concentration sits with Busy Professionals; Families gain share fastest as household penetration deepens in secondary metro corridors.
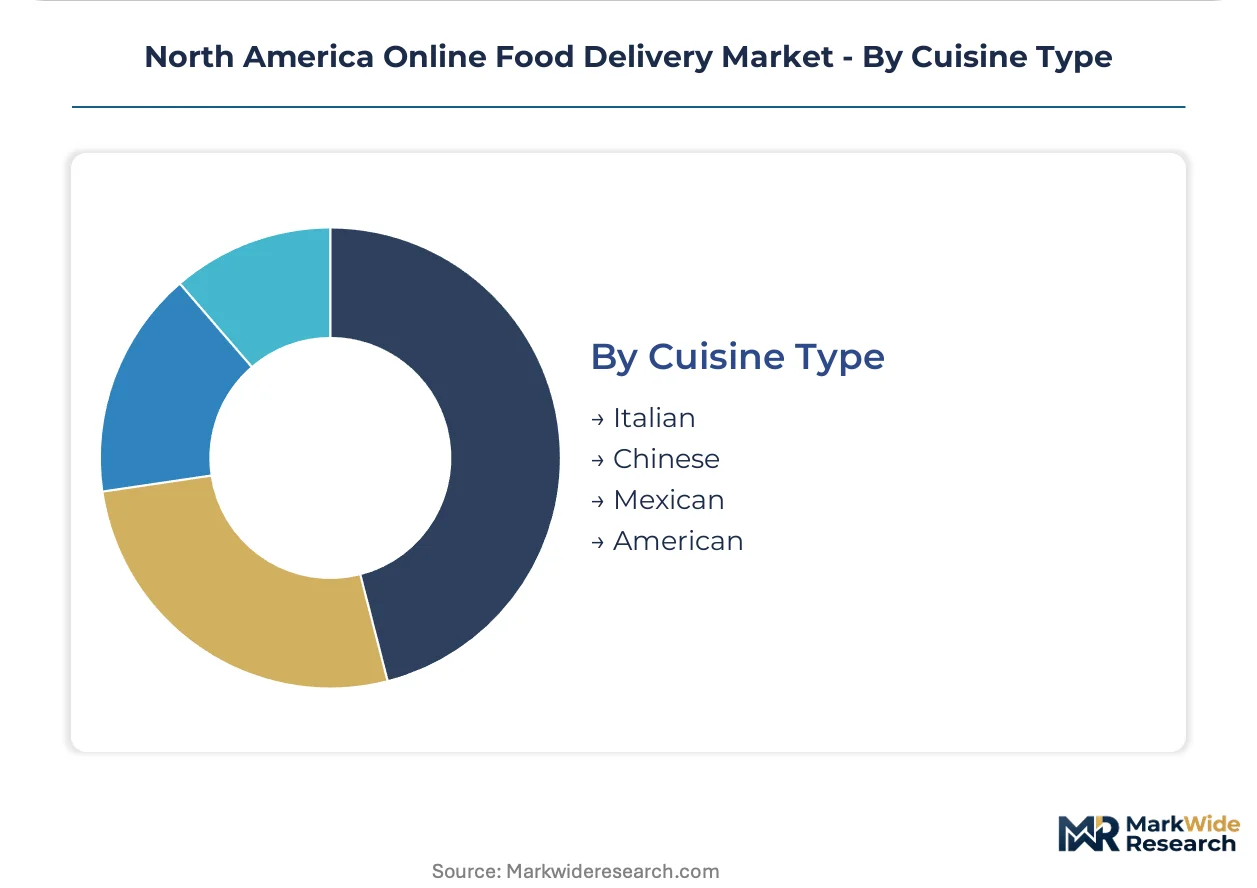
Cuisine Type:
Geographic origin of menu offerings segments supply acquisition and kitchen equipment requirements, with Italian and American cuisines dominating standardized delivery infrastructure.
- American:Burger, sandwich, and fried chicken categories optimized for thermal holding and travel durability. Quick Service Restaurant chains anchor transaction volume; packaging standardization supports batching algorithm efficiency.
- Mexican:Burrito and taco formats with high customization velocity. Demand concentrates in California and Texas where demographic density supports authentic supply; tortilla texture degradation limits delivery radius without specialized packaging.
- Italian:Pizza and pasta categories with established delivery heritage. Full-Service Restaurant white-tablecloth segments struggle with sauce separation and temperature maintenance; pizzeria verticals dominate platform placement.
- Chinese:Wok-fired dishes requiring precise timing coordination between kitchen completion and driver arrival. Steam retention packaging adds per-order cost; demand clusters in urban Chinatowns and suburban Asian population corridors.
Order frequency leadership belongs to American cuisine; Mexican cuisine expands most quickly as platform supply acquisition targets demographic growth corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qualified Opportunity Zones in Texas and Opportunity Zones across California's inland empire are concentrating third-party logistics investment and ghost kitchen permitting activity.
United States
Hybrid work stabilization in Austin, San Francisco, and Seattle metro corridors is consolidating corporate meal procurement onto platform-based ordering systems. FDA Food Safety Modernization Act traceability rules impose temperature-logging requirements across multi-state contractor networks. Dallas-Fort Worth and Houston anchor the fastest facility deployment, where municipal zoning liberalization permits high-density delivery-only kitchens without traditional restaurant real estate overhead.
Canada
Parking-scarce urban cores in Toronto and Vancouver are accelerating grocery delivery adoption among transit-oriented households. Health Canada food safety regulations align with FDA traceability standards while permitting provincial alcohol delivery pilots in Ontario and British Columbia. The Greater Toronto Area concentrates platform infrastructure investment, where subscription bundling models capture higher retention economics than per-transaction alternatives.
Mexico
Underpenetrated digital restaurant supply in Monterrey and Tijuana offers expansion potential for US-platform infrastructure adapted to local payment systems. Mexico's Federal Consumer Protection Law governs platform-merchant contractual transparency while central bank regulations shape digital wallet integration. Mexico City Metro anchors transaction volume, though northern border states present cross-border logistics synergies for US-based dispatch networks.
California
Proposition 22's gig-labor classification framework creates regulatory clarity that stabilizes platform cost structures and enables multi-state pricing predictability. SB 54 plastic packaging regulations are forcing deposit-return pilot programs and reusable container partnerships in grocery delivery verticals. Los Angeles and San Diego metro corridors concentrate demand density, where digital-native consumer overlap with restaurant supply depth produces the highest per-capita order frequency.
Texas
Suburban sprawl patterns in Houston and Dallas suburbs favor drive-thru Quick Service Restaurant delivery over grocery verticals. State-level ABC statute liberalization permits alcohol delivery expansion that remains blocked in northeastern and mountain west jurisdictions. The Austin-San Antonio corridor anchors enterprise account growth, where technology sector hybrid office attendance stabilizes at three-days-weekly and supports contracted corporate catering tiers.
North America Online Food Delivery Market Key Industry Players
Top-tier vendors anchor the platform-aggregator tier, while regional specialists and ghost kitchen operators occupy lower-margin infrastructure positions. The market exhibits consolidated dispatch network control alongside fragmented restaurant supply acquisition. Three archetypes dominate: mobility-network cross-subsidizers, merchant-plus-enterprise dual infrastructure builders, and subscription-loyalty mechanics specialists. Competitive positioning hinges on enterprise API integration and municipal ghost kitchen zoning capture.
Within the mobility-network tier, Uber Technologies Inc. exemplifies cross-subsidy architecture that sustains rider density through integration with established transportation infrastructure. DoorDash Inc. occupies the merchant-plus-enterprise dual infrastructure position, leveraging algorithmic dispatch to capture both independent restaurant supply and institutional catering accounts. Grubhub Holdings Inc. sits within the subscription-loyalty archetype, competing on frequency-based retention mechanics in legacy urban markets where customer acquisition costs have stabilized.
| Leading Market Players |
|---|
| Just Eat Takeaway.com |
| Deliveroo |
| DoorDash |
| Postmates |
| OLO |
| Uber Eats |
| Delivery Hero |
| Caviar |
| Grubhub |
| Others |
Cost & Logistics Intelligence
Diesel fuel price indices cascade through third-party delivery networks into consumer-facing pricing tiers, with fuel cost volatility compressing margins at the gig-contractor level before platforms adjust service fees and subscription rates to restore equilibrium.
Pricing Analysis
Short-lead-time orders command premium dispatch fees while scheduled windows and subscription memberships unlock discounted per-delivery rates. Pricing stratifies across premium, standard, and economy tiers based on delivery speed guarantees and order batching priority. Cost compression in the standard tier is intensifying because driver supply volatility prevents full fuel cost pass-through. Students and price-sensitive suburban households exhibit highest price elasticity, while corporate enterprise accounts locked into HR-mandated vendor relationships show lowest sensitivity.
Supply Chain Analysis
Thermal packaging supply rests on Chinese and Vietnamese manufacturers of phase-change materials and insulated pouch engineering, with domestic North American converters handling final assembly and branding. Key inputs include food-grade aluminum foil laminates, bio-based insulating foams, and GPS-enabled temperature loggers. Single-source vulnerability concentrates in specialty cold-chain materials subject to tariff exposure under shifting trade frameworks. Distribution runs through platform-controlled merchant fulfillment centers and municipal ghost kitchen clusters before final-mile gig contractor handoff.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around platform-aggregator dominance as Proposition 22 compliance costs and ghost kitchen zoning capture requirements force subscale regional operators toward exit or acquisition.
For Market Incumbents: Deepen enterprise API integration with corporate expense management systems to entrench preferred vendor status before hybrid work patterns fully stabilize. Expand captive ghost kitchen infrastructure in Dallas and Houston municipal zones to lock in restaurant supply density. Driver supply volatility represents the critical margin threat; vertical integration into in-house fleet pilots in Austin and San Francisco corridors offers insulation from gig-economy regulatory shifts. For New Entrants and Emerging Players: Enter via underpenetrated Mexico cross-border corridors in Monterrey and Tijuana, adapting US dispatch algorithms to local OXXO cash-payment and digital wallet infrastructure. White-space concentration sits with grocery-plus-meal subscription bundling models that merge Instacart-style retail access with restaurant delivery. Corporate catering procurement displacement offers the most penetrable entry vector, targeting mid-market technology firms below Fortune 500 scale with flexible API integration and contracted pricing tiers absent from incumbent enterprise programs. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional ghost kitchen operators with municipal zoning permits in Texas Opportunity Zones and California inland empire corridors, where qualified facility status accelerates capital deployment timelines. Long-term viability hinges on regulatory arbitrage durability across state-level gig-labor classification statutes and alcohol delivery permission fragmentation. The signal to watch is municipal ghost kitchen moratorium activity in Dallas, Houston, and Phoenix, where zoning liberalization reversal would strand facility investments and compress acquisition multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Enterprise API Integration | Direct corporate expense system linkage displaces traditional catering brokers in Austin and Seattle headquarters clusters. |
| Ghost Kitchen Zoning Capture | Municipal permit accumulation in Dallas-Fort Worth and Houston creates supply density moats against competitor facility entry. |
| Subscription Bundling Convergence | Grocery-plus-meal membership models capture higher retention economics than single-vertical alternatives in Toronto and Vancouver. |
| Cross-Border Infrastructure Adaptation | US platform dispatch networks localized for Mexico payment systems unlock Monterrey and Tijuana demand penetration. |
| Thermal Packaging Standardization | Phase-change material advances extend safe holding times and expand Quick Service Restaurant delivery radii in California suburban corridors. |
Research Approach
Document review covered SEC 10-K filings of platform operators, FDA Food Safety Modernization Act guidance documents, and state-level ABC statute compilations, complemented by interviews with restaurant supply chain managers, municipal zoning officers in Dallas and Houston, corporate HR procurement leads, and gig-economy driver coordinators. Secondary validation drew from Proposition 22 regulatory filings, ghost kitchen permitting databases, and fuel price index series. Bottom-up transaction volume estimates triangulated against top-down market size benchmarks.
Historical platform order data cross-referenced against panel input from restaurant operators and enterprise catering managers shaped projection trajectories across the analysis window. Segmentation modeling incorporated service type, delivery model, customer archetype, and cuisine origin dimensions. CAGRs derived from algorithmic batching efficiency curves, subscription retention rate trajectories, and enterprise account penetration slopes. Forecast inputs included hybrid work attendance stabilization patterns and municipal zoning liberalization timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Proposition 22 copycat statute adoption in additional states or federal preemption of gig-labor classification frameworks. Forecasts reflect assumptions around driver supply elasticity, ghost kitchen permitting velocity, and corporate meal allowance consolidation rates. A small set of named triggers warrants ongoing watch: FDA traceability rule enforcement intensity, SB 54 packaging regulation expansion beyond California, and ABC statute liberalization in Pennsylvania and Utah.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
India Online Grocery Market
Food Service
Europe Food Service Market
Food Service
Food Service Dairy Products Market
Food Service
Europe Online Grocery Market
Food Service
North America Smokeless Indoor Grills Market
Food Service
Catering Food Warmers Market
Food Service
Peer-To-Peer Dining Market
Food Service
Mobile Food Services Market
Food Service
Thailand Food Service Market
Food Service
Onboard Rail Catering Market
Food Service
Online Grocery Market
Food Service
Vietnam Food Service Market
Food Service
Commercial Air Fryer Market
Food Service
Charbroiler Market
Food Service
Chile Food Delivery Market
Food Service
Halal Food and Beverages Market