
 Edible Cutlery Market | 2026-2036
Edible Cutlery Market Size, Share, and Industry Trends Forecast 2026-2036
Edible Cutlery Market Intelligence
The capital-intensity divergence between automated baking lines and hand-pressed cottage operations is unwinding competitive stability in edible cutlery manufacturing. Biotrem Sp. z o.o. leverages proprietary wheat-bran extrusion systems to sustain cost leadership across European food-service contracts. Wisefood anchors its position through tight control over German retail distribution and institutional catering channels. Bakeys differentiates via localized rice-flour production networks spanning South Indian urban markets.
Edible cutlery denotes utensils manufactured from cereal flours, starches, or vegetable pulps that withstand brief liquid exposure before intentional consumption or biodegradation, typically achieving structural integrity for 15–20 minutes in hot foods. These products serve commercial food-service operators and event organizers seeking compliance with single-use plastic prohibitions while eliminating post-consumer waste streams. Spoon formulations currently dominate volume owing to universal applicability across cuisines, while straw variants represent the fastest-expanding category as beverage chains retrofit cold-drink service protocols. Wheat-based material grades command premium positioning in European markets due to established gluten-content labeling frameworks, whereas corn-derived alternatives occupy mid-tier price bands in North American institutional procurement.
The EU Single-Use Plastics Directive and FDA food-contact substance regulations jointly determine permissible ingredient matrices and migration limits for edible utensil manufacturers seeking cross-border market access. BIS certification requirements in India and state-level plastic bans across Maharashtra and Karnataka further fragment compliance obligations for exporters. Stakeholders must monitor evolving compostability certifications and allergen disclosure mandates as procurement specifications tighten across institutional buyers.
Market Dynamics
Automated baking lines are consolidating production economics in edible cutlery manufacturing, compressing unit costs below hand-pressed cottage operations and forcing capital upgrades across the supplier base.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandates material transitions across European food-service contracts, creating guaranteed procurement pipelines for wheat-based and rice-based alternatives.
- Quick-service restaurant retrofitting:North American and European chains are embedding edible utensils into cold-drink and fast-casual service protocols, normalizing bulk purchasing at scale.
- Wheat-bran extrusion systems:Proprietary automation technology is lowering per-unit production costs while extending structural integrity windows to 20 minutes in hot foods.
Market Restraints
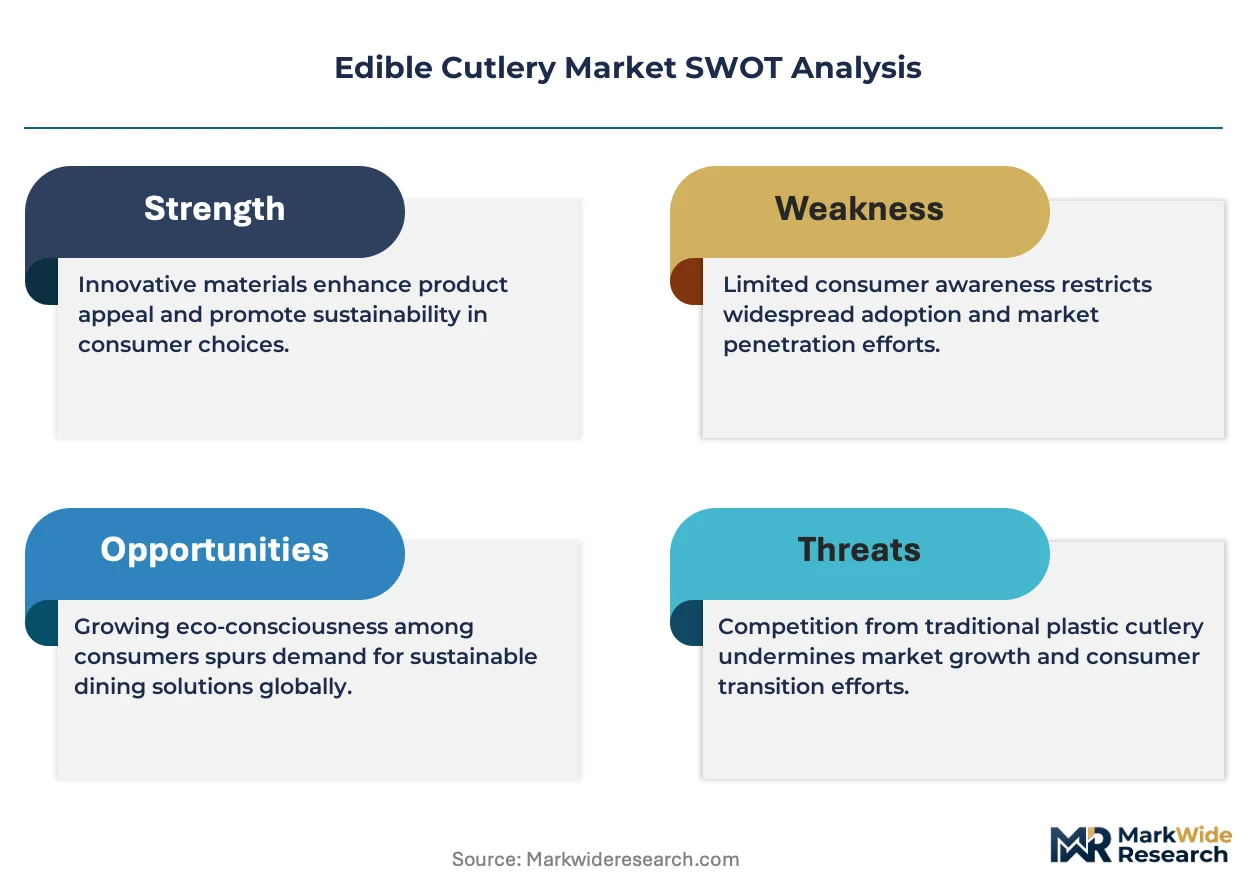
- Input cost volatility:Wheat and rice flour prices fluctuate with agricultural commodity cycles, compressing margin stability for manufacturers without long-term grain contracts.
- Supply concentration risk:European production clusters dominate automated line capacity, creating geographic vulnerability for buyers seeking diversified sourcing.
- Technical shelf-life limitation:Edible formulations absorb ambient moisture within 6-12 months, constraining inventory management and distribution radius.
Strategic Opportunities
- India institutional catering:State-level plastic bans across Maharashtra and Karnataka are opening municipal procurement channels for localized rice-flour production networks.
- Beverage straw retrofitting:Cold-drink chains are replacing petroleum-derived straws with edible variants, creating the fastest-expanding product category in the sector.
- Compostability certification alignment:Industrial buyers are tightening procurement specifications around verified biodegradation standards, favoring suppliers with pre-certified ingredient matrices.
Industry Challenges
- Allergen disclosure complexity:Gluten-content labeling frameworks vary across EU member states and US jurisdictions, fragmenting compliance obligations for cross-border exporters.
- Capital intensity for automation:Continuous baking lines require seven-figure equipment investments, excluding small-scale producers from institutional contract bidding.
- Migration limit testing:FDA food-contact substance regulations demand extended laboratory validation timelines, delaying product launches by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edible Cutlery Market |
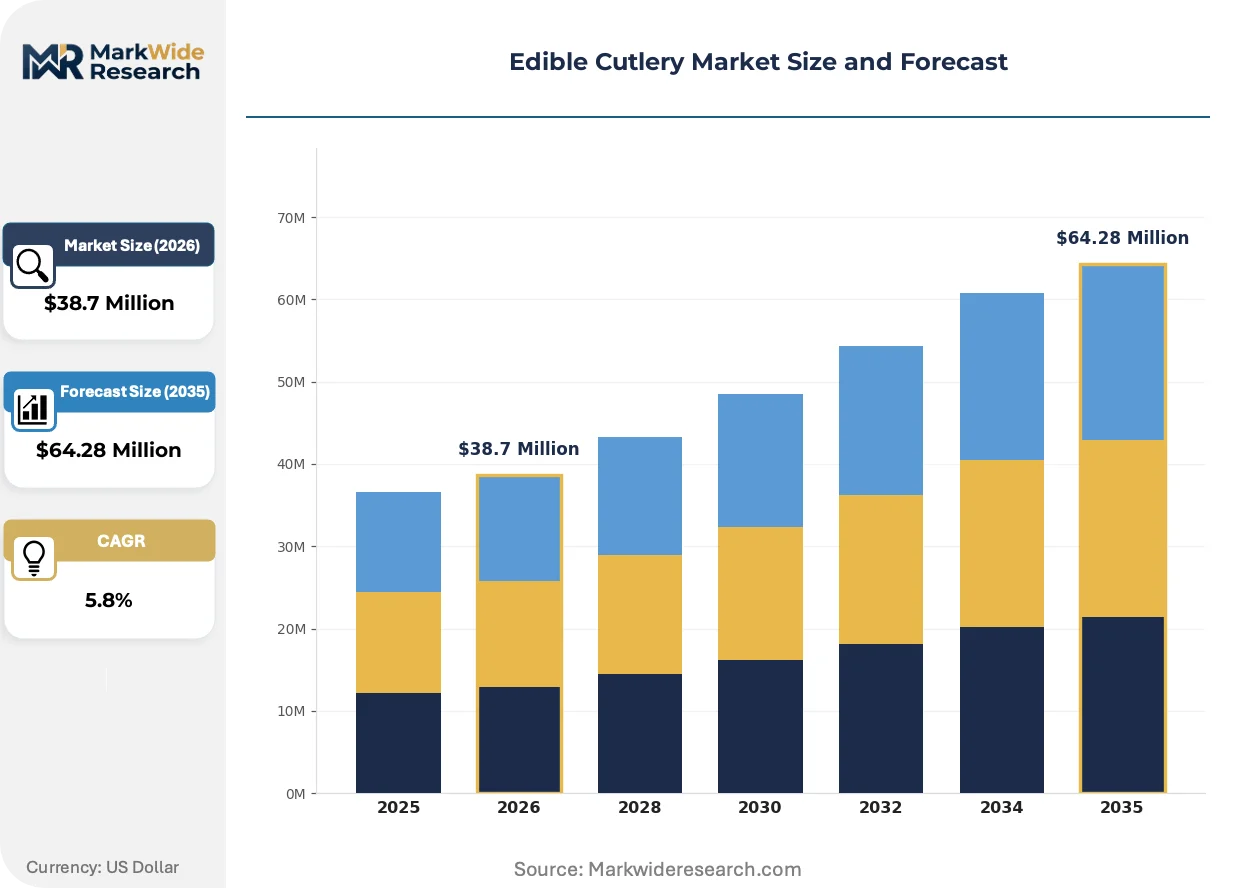
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $64.28 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spoons, Forks, Knives, Straws Material: Wheat, Rice, Corn, Potato Application: Household, Restaurants, Catering, Events Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Festivals |
| Companies Covered | Biotrem Sp. z o.o., BrightVibes B.V., EdiblePRO, Edibles by Jack, Frenvi Private Limited, Wisefood, Mede Cutlery Company, KOOVEE, Bakeys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edible Cutlery Market Strategic Shifts & Innovations
Extrusion-based manufacturing is rewriting cost structures across edible cutlery production, while regulatory alignment and procurement specification tightening are reshaping competitive access.
Continuous wheat-bran extrusion systems are supplanting batch-pressed cottage operations across European supply chains. German and Polish food-service distributors are consolidating contracts around automated suppliers capable of 500,000-unit daily output. This technology compression is eliminating price-competitive hand-pressed alternatives from institutional procurement shortlists.
REACH compliance frameworks and EU Green Deal procurement guidelines are mandating full material traceability for single-use alternatives. Manufacturers must now document agricultural sourcing, processing additives, and biodegradation pathways across batch records. Wheat-based grades face the strictest scrutiny due to established gluten-content thresholds, pushing some suppliers toward corn-derived matrices with simpler allergen profiles.
Institutional buyers are unbundling after-sales service from product supply, demanding direct certification documentation rather than distributor intermediation. University and corporate cafeteria operators in France and the Netherlands now require ISO-compliant biodegradation certificates before contract execution. This specification-driven purchasing is compressing distributor margins while rewarding manufacturers with in-house laboratory validation capabilities.
Edible Cutlery Market Segmentation
Edible cutlery procurement specifications diverge sharply across institutional buyers, with regulatory frameworks dictating permissible material matrices and allergen disclosure requirements. Manufacturers must align production configurations against these compliance tiers to secure contract eligibility.
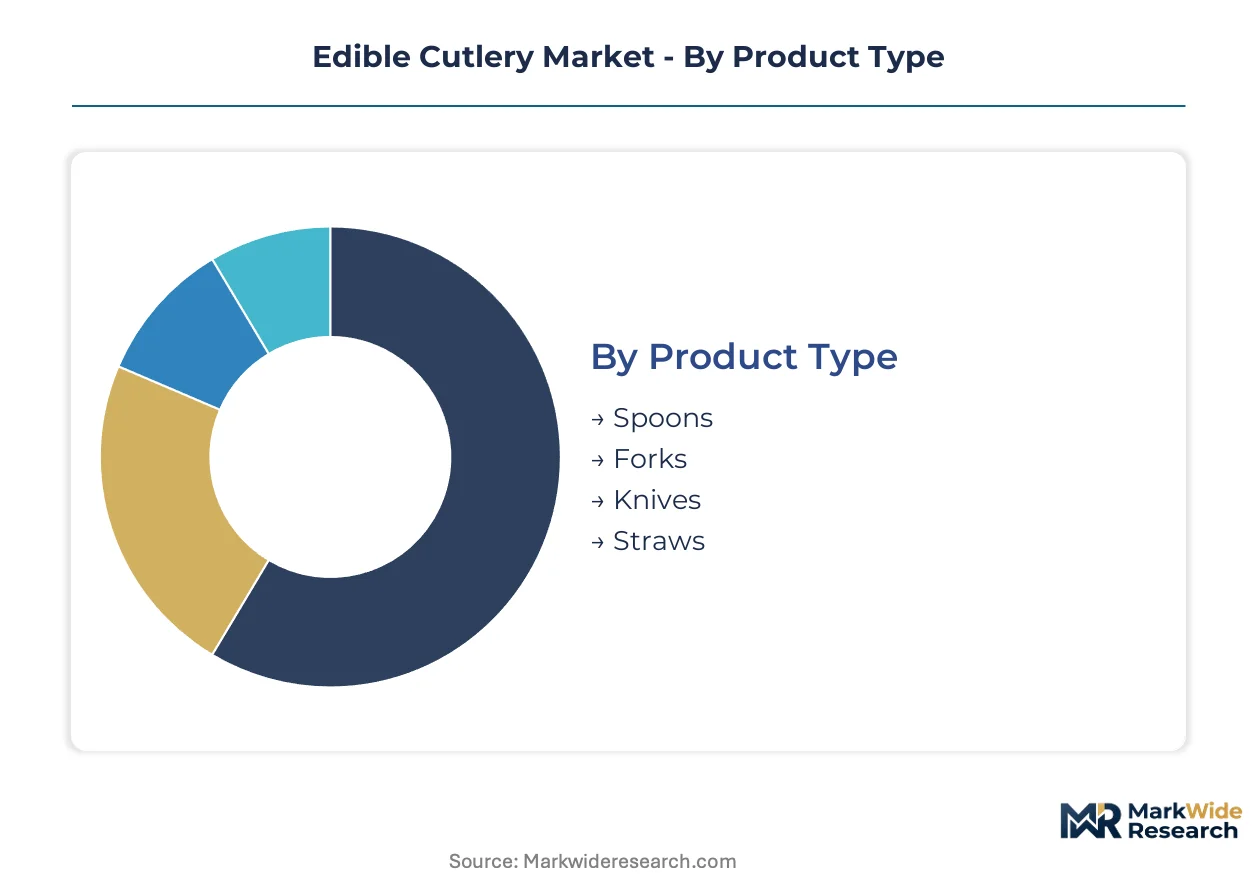
Product Type:
REACH compliance and FDA food-contact regulations impose divergent structural integrity testing protocols across utensil formats, shaping manufacturing investments.
- Spoons:Universal bowl-and-handle geometry suits liquid and semi-solid foods across all cuisines. Quick-service chains in France and Germany embed these into fast-casual service protocols as default utensils, driven by EU Single-Use Plastics Directive procurement mandates.
- Straws:Hollow cylindrical extrusions with reinforced wall thickness for cold-drink suction. Beverage retrofitting programs across US coastal states and Scandinavian markets are absorbing volume fastest as petroleum-derived straw bans proliferate.
- Forks:Tined configurations with torsional resistance for solid food piercing. Institutional catering contracts in India specify these for rice-based meal service.
- Knives:Serrated or straight-edge profiles with compressive strength for cutting. Limited adoption outside premium event catering due to structural complexity.
Established volume favors spoons; emerging adoption favors straws.
Material:
Input cost tiers separate automated extrusion-grade feedstocks from hand-pressed cottage alternatives, compressing supplier margins differentially.
- Wheat:Gluten-network binding creates superior tensile strength in hot-food applications. European markets command premium positioning through established gluten-content labeling frameworks, with German and Polish distributors consolidating contracts around certified suppliers.
- Corn:Starch gelatinization yields neutral flavor profiles and simpler allergen matrices. North American institutional procurement channels favor these mid-tier price bands for K-12 and university cafeteria contracts.
- Rice:Amylopectin-rich flour enables localized production networks with minimal equipment scale. Maharashtra and Karnataka state-level plastic bans are opening municipal procurement channels across South Indian urban clusters.
- Potato:High-amylose starch provides extended structural integrity windows. Limited commercial penetration outside experimental European formulations.
Price premiums concentrate in wheat grades; volume expansion concentrates in corn and rice alternatives.
Application:
Customer procurement scale determines automation compatibility and certification documentation requirements.
- Restaurants:Quick-service and fast-casual chains purchase through centralized procurement with ISO-compliant biodegradation certificate requirements. North American and European chains are embedding edible utensils into cold-drink and meal service protocols.
- Catering:Event and institutional operators demand direct certification documentation rather than distributor intermediation. University and corporate cafeteria operators in the Netherlands require batch-level traceability.
- Household:Retail-packaged formats through supermarkets and online channels with shorter shelf-life tolerance. Consumer awareness campaigns in urban India are driving trial purchases.
- Events:Single-use bulk procurement for festivals and outdoor gatherings with minimal compliance documentation. Food festival distribution channels in Germany and Poland test novel formulations.
Contract value concentrates in restaurant procurement; specification tightening concentrates in catering channels.
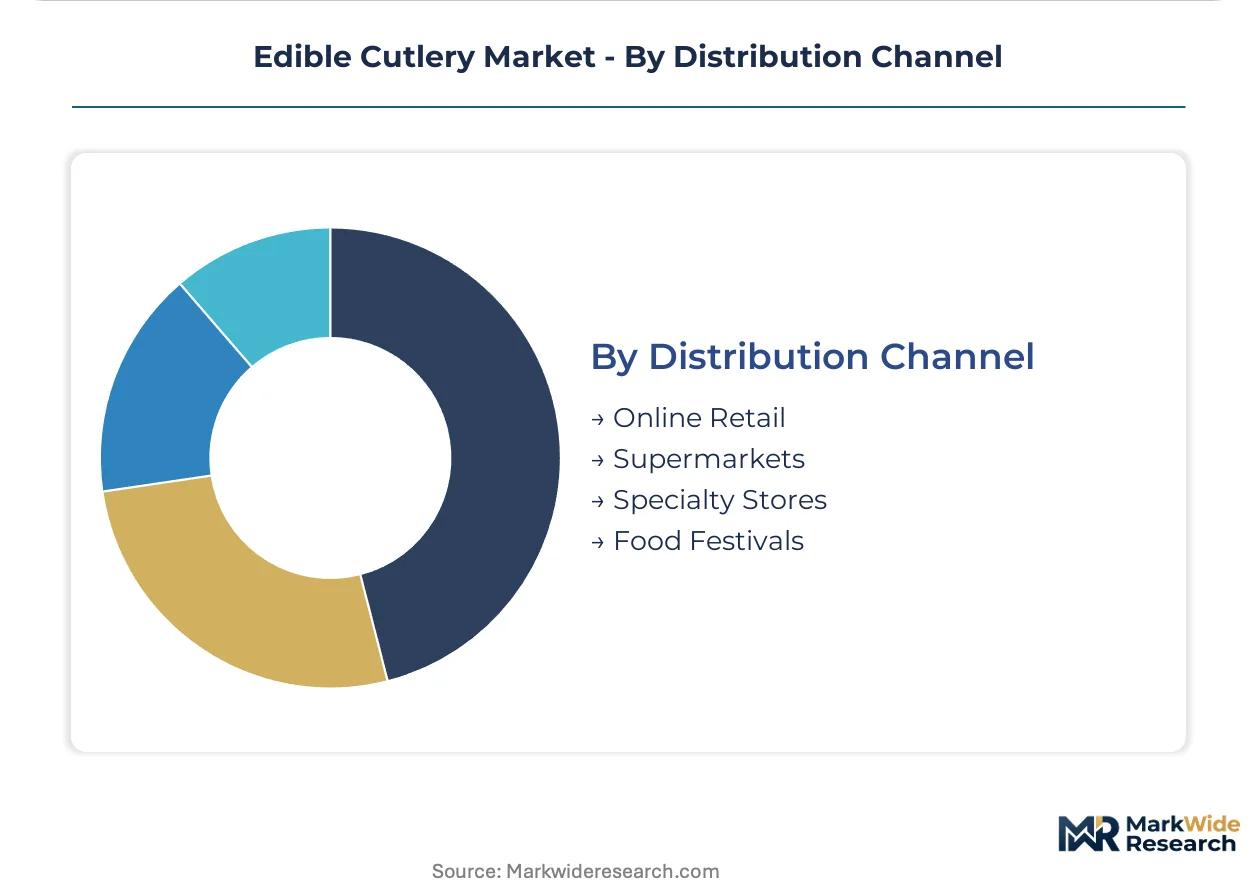
Distribution Channel:
Channel control determines margin capture and certification burden placement between manufacturer and end-user.
- Supermarkets:Mass retail placement requires extended shelf-life packaging and national distribution logistics. German retail consolidation around Wisefood demonstrates channel control value.
- Online Retail:Direct-to-consumer platforms enable niche flavor variants and subscription models with minimal inventory risk. Urban Indian markets show emerging traction for localized rice-flour products.
- Specialty Stores:Curated placement in zero-waste and organic retailers with premium pricing and educational marketing requirements. French and Dutch markets favor these for certified biodegradable grades.
- Food Festivals:Temporary activation channels for product testing and consumer education with minimal regulatory documentation. European summer festival circuits serve as formulation proving grounds.
Volume scale favors supermarket consolidation; margin capture favors online and specialty channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in edible cutlery procurement varies sharply by geography. European buyers absorb wheat-based premiums through regulatory compliance budgets, while Indian municipal purchasers prioritize rice-flour cost efficiency over certification documentation.
Germany
Quick-service chains in Berlin and Munich embed edible utensils into fast-casual protocols under EU Single-Use Plastics Directive mandates. ECHA REACH frameworks enforce full material traceability across batch records. The Ruhr industrial corridor hosts automated extrusion facilities supplying food-service distributors with 500,000-unit daily capacity.
United States
K-12 and university cafeteria operators in California and New York procure corn-based alternatives through centralized institutional channels. FDA food-contact substance regulations demand extended laboratory validation timelines for cross-border suppliers. Chicago and Dallas metropolitan clusters concentrate cold-drink chain retrofitting programs for edible straw adoption.
India
Municipal catering contracts in Maharashtra and Karnataka specify rice-flour utensils for compliance with state-level plastic prohibitions. FSSAI labeling requirements intersect with BIS certification for food-contact materials. Hyderabad and Bangalore urban clusters anchor localized production networks serving South Indian institutional buyers.
Netherlands
University and corporate cafeteria operators in Amsterdam and Rotterdam require ISO-compliant biodegradation certificates before contract execution. EU Green Deal procurement guidelines mandate documented agricultural sourcing and processing additive disclosure. The Randstad logistics hub enables distribution radius extension despite six-month shelf-life constraints.
Poland
Food-service distributors consolidate contracts around automated suppliers capable of sustained high-volume output. EFSA migration limit standards apply to wheat-bran extrusion formulations exported westward. Warsaw and Krakow industrial zones concentrate proprietary baking line investments displacing hand-pressed cottage competitors.
Edible Cutlery Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in edible cutlery manufacturing. Automated baking line operators command institutional procurement shortlists through cost compression below hand-pressed alternatives. Three archetypes populate the competitive map: proprietary extrusion technology holders, regional distribution channel controllers, and localized material network builders. Capacity expansion and certification documentation capabilities constitute the dominant competitive moves as buyers tighten procurement specifications.
Among European technology-integrated manufacturers, Biotrem Sp. z o.o. and Wisefood occupy positions reflecting divergent strategic emphases. Biotrem exemplifies the proprietary systems archetype through its Polish corporate structure. Wisefood represents channel control specialization within the German GmbH format. Bakeys anchors the localized network tier through its South Indian operational footprint. These three entities collectively illustrate how geographic origin and corporate structure map to competitive positioning in a compliance-intensive procurement environment.
| Leading Market Players |
|---|
| Biotrem Sp. z o.o. |
| BrightVibes B.V. |
| EdiblePRO |
| Edibles by Jack |
| Frenvi Private Limited |
| Wisefood |
| Mede Cutlery Company |
| KOOVEE |
| Bakeys |
| Others |
Cost & Logistics Intelligence
Automated extrusion lines achieving 500,000-unit daily capacity in Poland and Germany compress unit economics below hand-pressed cottage alternatives, concentrating pricing power among capital-intensive operators while fragmenting margin structures across geographic supply clusters.
Pricing Analysis
After-sales service bundling with direct certification documentation commands lifetime value premiums from institutional catering contracts. Three-tier pricing structure across premium wheat-based, standard corn-based, and economy rice-based levels separates buyers by compliance grade and volume scale. Pricing pressure stems from agricultural commodity volatility in wheat and rice flour inputs, with K-12 cafeteria operators in North America exhibiting highest price sensitivity versus EU quick-service chains absorbing premiums through regulatory compliance budgets.
Supply Chain Analysis
Six-to-twelve-month shelf-life constraints compress inventory turnover and limit distribution radius extension from production hubs. Supply concentrates in Poland, Germany, and India, with wheat bran, rice flour, and corn starch constituting primary feedstocks. Single-source vulnerability runs through European automated line manufacturers, while distribution feeds through food-service distributors consolidating around certified suppliers with ISO-compliant biodegradation documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement specification tightening across institutional buyers fragments contract eligibility, creating white-space opportunities for specialized operators capable of rapid certification alignment against diverging national mandates.
For Market Incumbents: Fortify cost leadership through proprietary wheat-bran extrusion technology investments and captive supply agreements with Polish grain elevators. Biotrem's automated baking line architecture demonstrates how seven-figure capital deployment displaces hand-pressed competitors from institutional shortlists. Channel control through direct certification documentation capabilities—bypassing distributor intermediation—secures university and corporate cafeteria contracts in France and the Netherlands.
For New Entrants and Emerging Players: BIS certification fast-track programs for Maharashtra and Karnataka municipal procurement channels unlock immediate revenue traction against established European exporters. Rice-flour production networks anchored in Hyderabad and Bangalore offer the most penetrable entry point, with localized manufacturing avoiding FDA migration limit testing delays that stretch product launches. Direct-to-consumer online retail enables niche flavor variants with minimal inventory risk before scaling toward institutional certification.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automated extrusion operators with in-house laboratory validation capabilities over hand-pressed cottage competitors facing capital exclusion. Long-term viability across the analysis window rests on compostability certification alignment as industrial buyers tighten procurement specifications. The signal to monitor is EU Green Deal procurement guideline expansion into additional member state municipal contracts, indicating inflection toward documented agricultural traceability requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Extrusion Technology Investment | Polish and German automated line operators compress unit costs below hand-pressed alternatives. |
| Compostability Certification Alignment | ISO-compliant biodegradation documentation satisfies Netherlands university procurement mandates. |
| Localized Rice-Flour Production Network | Hyderabad and Bangalore clusters serve Maharashtra state-level plastic ban compliance. |
| Direct Certification Documentation Capability | In-house laboratory validation bypasses distributor intermediation for institutional contracts. |
| Channel Control Through Retail Consolidation | German supermarket placement demonstrates margin capture in consumer-facing distribution. |
Research Approach
A spread of perspectives from food-service procurement directors, regulatory affairs specialists at edible cutlery manufacturers, agricultural commodity traders, and institutional catering operators converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through ECHA REACH guidance documents, FDA food-contact substance regulations, FSSAI labeling requirements, EU Single-Use Plastics Directive implementation reports, and BIS certification standards. Bottom-up production capacity estimates from automated extrusion facilities triangulated against top-down procurement volume data from quick-service restaurant chains.
Segmentation dimensions modeled include product type, material matrix, application channel, and geographic regulatory cluster across the projection horizon. CAGRs were derived from production capacity expansion trajectories and procurement mandate implementation timelines. Wheat flour price indices and migration limit testing duration assumptions constituted industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained EU regulatory enforcement and stable agricultural commodity supply; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Foods
Low Calorie Vegetable Dip Market
Specialty Foods
Low Calorie Chocolate Desserts Market
Specialty Foods
Vegan Dressing Market
Specialty Foods
Poke Food Market
Specialty Foods
Asia-Pacific Free from Food Market
Specialty Foods
Europe Halal Food and Beverage Market
Specialty Foods
Cat and Dog Food Toppers Market
Specialty Foods
Low Calorie Popsicles Market
Specialty Foods
Dill Juice Market
Specialty Foods
Halal Foods Market
Specialty Foods
Yeast-Based Spreads Market
Specialty Foods
Mediterranean Kimchi-Style Vegetable Culture Starters Market
Specialty Foods
Europe Gluten-Free Breakfast Cereals Market
Specialty Foods
United States Tofu Market
Specialty Foods
Global Truffle Market
Specialty Foods
Brahmi Market