
 Middle East and Africa Online Grocery Delivery Market | 2026-2036
Middle East and Africa Online Grocery Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Online Grocery Delivery Market Foresight
The capital-intensity divergence between dark-store operators and marketplace aggregators is collapsing as fulfillment costs normalize across the Middle East and Africa. Talabat Holding plc leverages its integrated logistics network to sustain same-day delivery promises in Gulf markets. Jahez anchors its position in Saudi Arabia through specialized quick-commerce infrastructure. Kibsons International LLC differentiates via vertical control over fresh-produce sourcing in the UAE.
Online grocery delivery denotes a digitally intermediated fulfillment service where perishable and packaged food items are ordered through web or mobile platforms and distributed via temperature-controlled last-mile networks to residential or commercial addresses. Cold-chain integrity, typically maintained at zero to four degrees Celsius for dairy and produce categories, determines product quality upon arrival. The delivery model dimension reveals structural variation: on-demand services capture premium convenience spending in dense Gulf cities, while subscription models build recurring revenue pools among Saudi households. Scheduled delivery occupies the efficiency-driven segment where route optimization minimizes per-order fulfillment costs.
Saudi Arabia's SAMR enforces e-commerce vendor registration and product-labeling standards that shape market access for cross-border grocery platforms. The UAE's central bank digital-wallet regulations and Egypt's consumer protection frameworks govern payment authentication and refund protocols across the region. Stakeholders must monitor how Nigeria's national data protection authority and South Africa's financial sector conduct authority tighten platform liability rules for customer data handling.
Market Dynamics
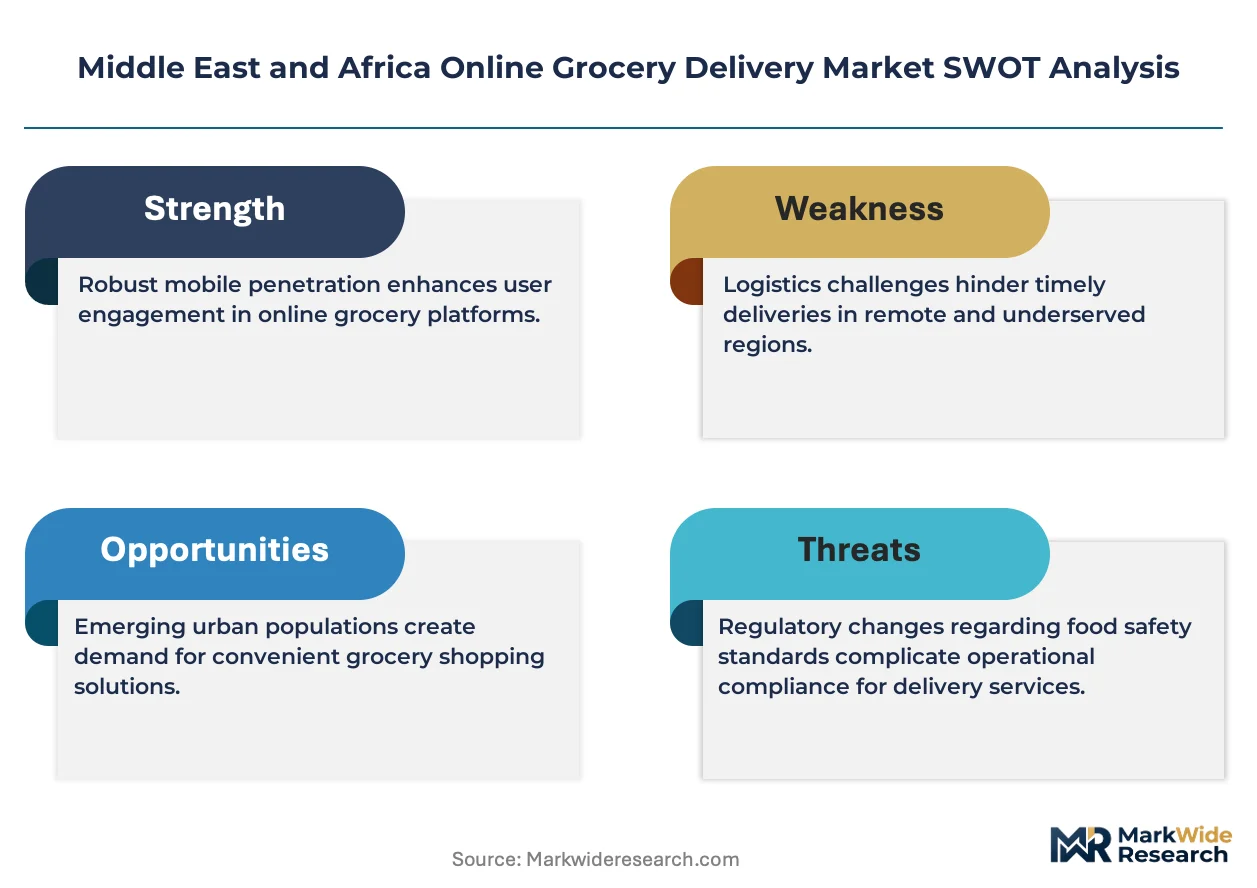
Dark-store fulfillment networks are compressing delivery windows across Gulf Cooperation Council cities while Nigeria's national data protection authority tightens platform liability for customer data handling.
Growth Catalysts
- Smartphone penetration deepening:Young urban households in Lagos and Nairobi are adopting scheduled delivery models as mobile-first ordering becomes the default interface for grocery procurement.
- UAE digital payment frameworks:The central bank's wallet regulations are accelerating cashless transaction adoption, reducing payment friction for recurring grocery purchases.
- Fulfillment infrastructure investments:Temperature-controlled last-mile networks are expanding across Dubai and Riyadh, enabling same-day delivery promises for perishable categories.
Market Restraints
- Cold-chain energy costs:Diesel-powered refrigeration units face input cost volatility as fuel subsidies contract across Saudi Arabia and Egypt.
- Cross-border vendor licensing:Saudi Arabia's SAMR e-commerce registration requirements create regulatory friction for foreign grocery platforms seeking market entry.
- Fresh-produce sourcing concentration:UAE-based vertical integrators control limited regional agricultural supply, constraining inventory depth for marketplace aggregators.
Strategic Opportunities
- Subscription model expansion:Recurring revenue pools among Saudi households remain underdeveloped relative to on-demand penetration in dense Gulf cities.
- Quick-commerce infrastructure:Specialized micro-fulfillment centers can capture premium convenience spending in secondary Saudi cities beyond Riyadh and Jeddah.
- South Africa financial sector conduct authority alignment:Proactive compliance with tightening platform liability rules creates first-mover advantage in data governance.
Industry Challenges
- Route optimization talent scarcity:Last-mile logistics engineers with expertise in dynamic scheduling algorithms command premium compensation across the region.
- Legacy ERP integration:Established retailers face friction connecting proprietary inventory systems with third-party delivery platform APIs.
- Zero-to-four-degree certification timelines:Cold-chain compliance documentation for dairy and produce categories extends vendor onboarding cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Online Grocery Delivery Market |
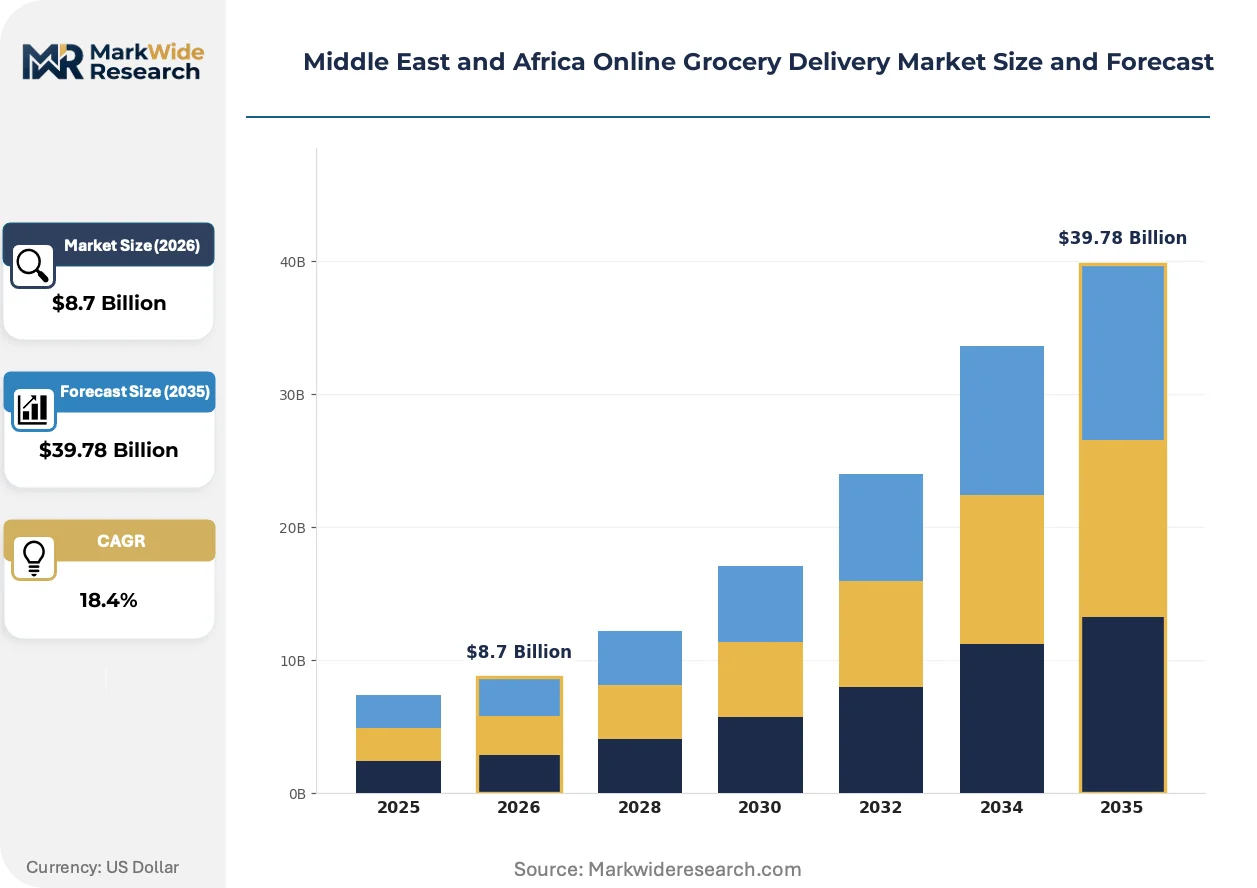
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruits, Vegetables, Dairy, Beverages Delivery Model: On-Demand, Subscription, Scheduled, Hybrid Customer Type: Households, Offices, Restaurants, Retailers Payment Method: Credit Card, Digital Wallet, Cash on Delivery, Bank Transfer |
| Companies Covered | HungerStation Company LLC, Deliveroo, Talabat Holding plc, Keeta, Jahez, Noon AD Holdings One Person Company LLC, Careem, Kibsons International LLC, InstaShop Ltd., Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Online Grocery Delivery Market Shifts & Advancements
Temperature-controlled packaging technology is actively reshaping how perishables move through last-mile networks, with implications for capital deployment and operational scale across the region.
Phase-change material cooling systems are miniaturizing. These gel-based inserts maintain zero-to-four-degree Celsius integrity for 4-6 hours without active refrigeration. Quick-commerce operators in Dubai are adopting them for motorcycle-based delivery fleets. The technology is miniaturizing fulfillment footprints, enabling dark-store proliferation in dense urban cores where mechanical refrigeration space is prohibitively expensive.
Saudi Arabia's SAMR e-commerce vendor registration and product-labeling standards are reshaping market access protocols. Cross-border grocery platforms must now maintain in-country legal entities and Arabic-language labeling compliance. International marketplace aggregators are responding by licensing local fulfillment partners rather than operating direct-to-consumer models.
Scheduled delivery windows are displacing on-demand as the preferred interface for household grocery planning. Young families in Nairobi and Lagos are selecting 2-hour arrival slots 24-48 hours in advance. This pattern compresses route density for fulfillment networks and reduces per-order logistics costs compared to instant delivery promises.
Middle East and Africa Online Grocery Delivery Market Segmentation
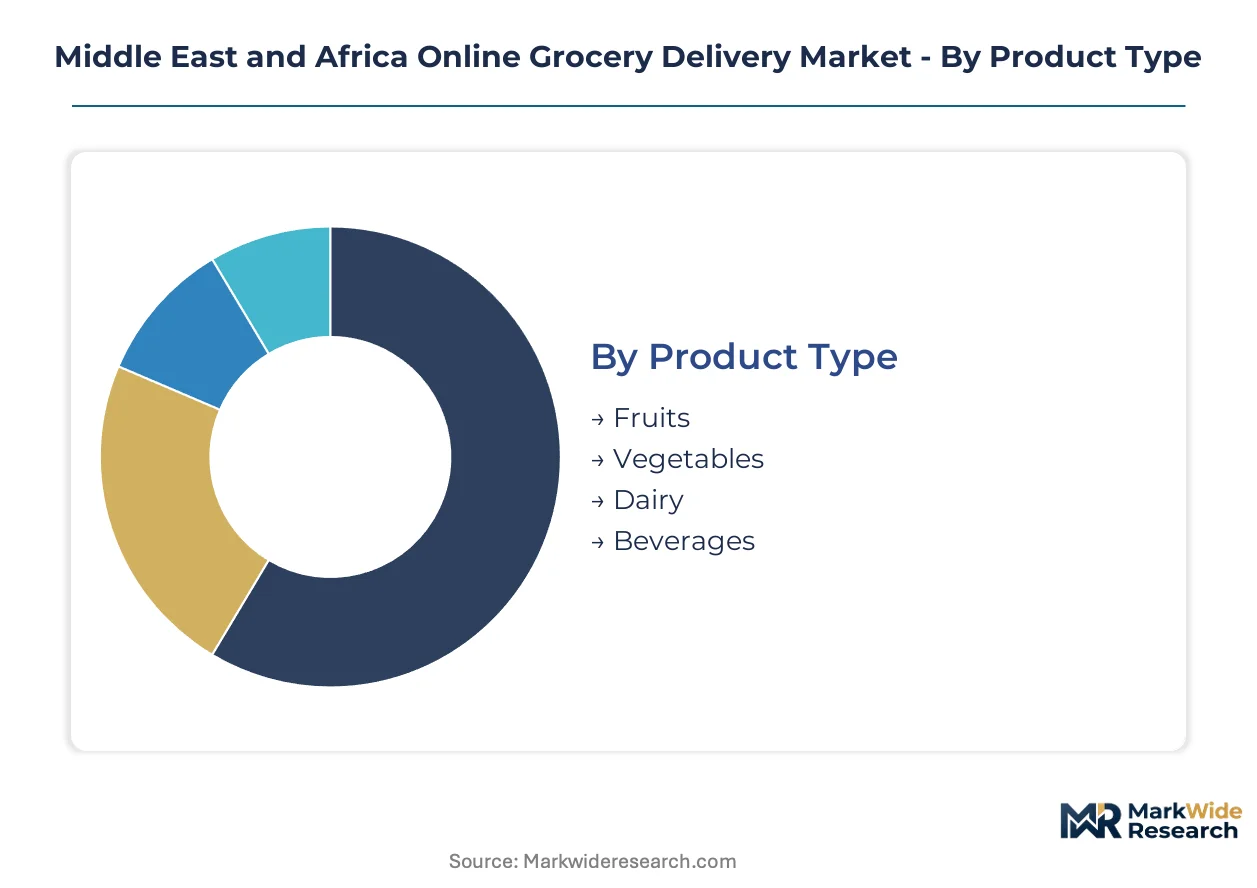
Segmentation in Middle East and Africa online grocery delivery reveals how fulfillment economics and regulatory exposure vary across product perishability, delivery cadence, and payment infrastructure. Each dimension carries distinct margin profiles and compliance burdens that reshape vendor strategy.
Product Type:
Temperature thresholds and shelf-life constraints segment regulatory scrutiny across Saudi Arabia's SAMR labeling standards and UAE import certification protocols.
- Fruits:Seasonal sourcing from East African highlands and Egyptian Nile Delta concentrates procurement in temperature-controlled consolidation hubs. Dubai-based vertical integrators maintain zero-to-four-degree cold chains from farm gate to dark-store, with SAMR Arabic-labeling requirements extending vendor onboarding timelines for cross-border suppliers.
- Vegetables:Leafy greens demand the strictest humidity controls within mechanical refrigeration units, driving diesel-powered cold-chain energy costs upward as fuel subsidies contract across Saudi Arabia and Egypt. Nairobi and Lagos households select scheduled delivery windows 24-48 hours ahead to align harvest cycles with consumption patterns.
- Dairy:Ultra-high-temperature processing extends distribution radius for ambient milk, though fresh yogurt and cheese categories remain captive to Gulf Cooperation Council fulfillment infrastructure.
- Beverages:Ambient-stable categories tolerate longer last-mile distances, enabling marketplace aggregators to compete without vertical integration into refrigeration assets.
Fruits and vegetables handle the majority of throughput; dairy is expanding most quickly as subscription models penetrate Saudi households.
Delivery Model:
Capital deployment intensity separates operators building captive logistics from those aggregating third-party fulfillment capacity.
- On-Demand:Promises under 60 minutes require micro-fulfillment centers within five kilometers of dense urban cores. Dubai and Riyadh operators deploy phase-change material cooling systems on motorcycle fleets to miniaturize refrigeration footprints where real estate costs prohibit mechanical cold rooms.
- Scheduled:2-4 hour arrival windows selected 24-48 hours in advance compress route density and reduce per-order logistics costs. Young urban households in Lagos and Nairobi favor this interface for weekly grocery planning, enabling batch fulfillment that amortizes driver wages across multiple drops.
- Subscription:Recurring revenue pools remain underdeveloped relative to on-demand penetration in Gulf cities, though Saudi Arabia's young families show rising adoption for staple replenishment.
- Hybrid:Combines scheduled base-load fulfillment with on-demand top-up capacity, requiring dual infrastructure investment that favors scaled operators.
Scheduled delivery handles the majority of throughput; on-demand is gaining share fastest among premium convenience spenders in Dubai and Riyadh.
Customer Type:
Order frequency and basket composition determine last-mile unit economics across residential and commercial endpoints.
- Households:Weekly basket sizes averaging 15-25 items sustain route density for scheduled delivery networks, with young urban families in Nairobi and Lagos driving mobile-first adoption.
- Offices:Midday delivery windows concentrate demand in central business districts, enabling drop consolidation that reduces per-order fulfillment costs compared to dispersed residential routing.
- Restaurants:Require pre-dawn delivery slots to align with kitchen prep schedules, demanding specialized fleet scheduling algorithms that command premium talent compensation across the region.
- Retailers:Small-format convenience stores source replenishment stock through B2B channels with longer lead times, tolerating next-day delivery promises.
Households handle the majority of throughput; restaurants are climbing the fastest as food-service digitization accelerates in Gulf Cooperation Council cities.
Payment Method:
Authentication protocols and refund liability frameworks segment platform risk exposure across UAE central bank regulations and Egypt's consumer protection authority.
- Credit Card:Chargeback liability concentrates with platforms under UAE central bank digital-wallet regulations, favoring established operators with fraud detection infrastructure.
- Digital Wallet:UAE central bank frameworks accelerate cashless adoption, reducing payment friction for recurring grocery purchases while tightening know-your-customer compliance burdens.
- Cash on Delivery:Dominates Lagos and Nairobi where banking penetration lags smartphone adoption, imposing working capital constraints and driver security protocols on fulfillment networks.
- Bank Transfer:Preferred for large B2B restaurant orders, with settlement delays that extend platform receivables cycles.
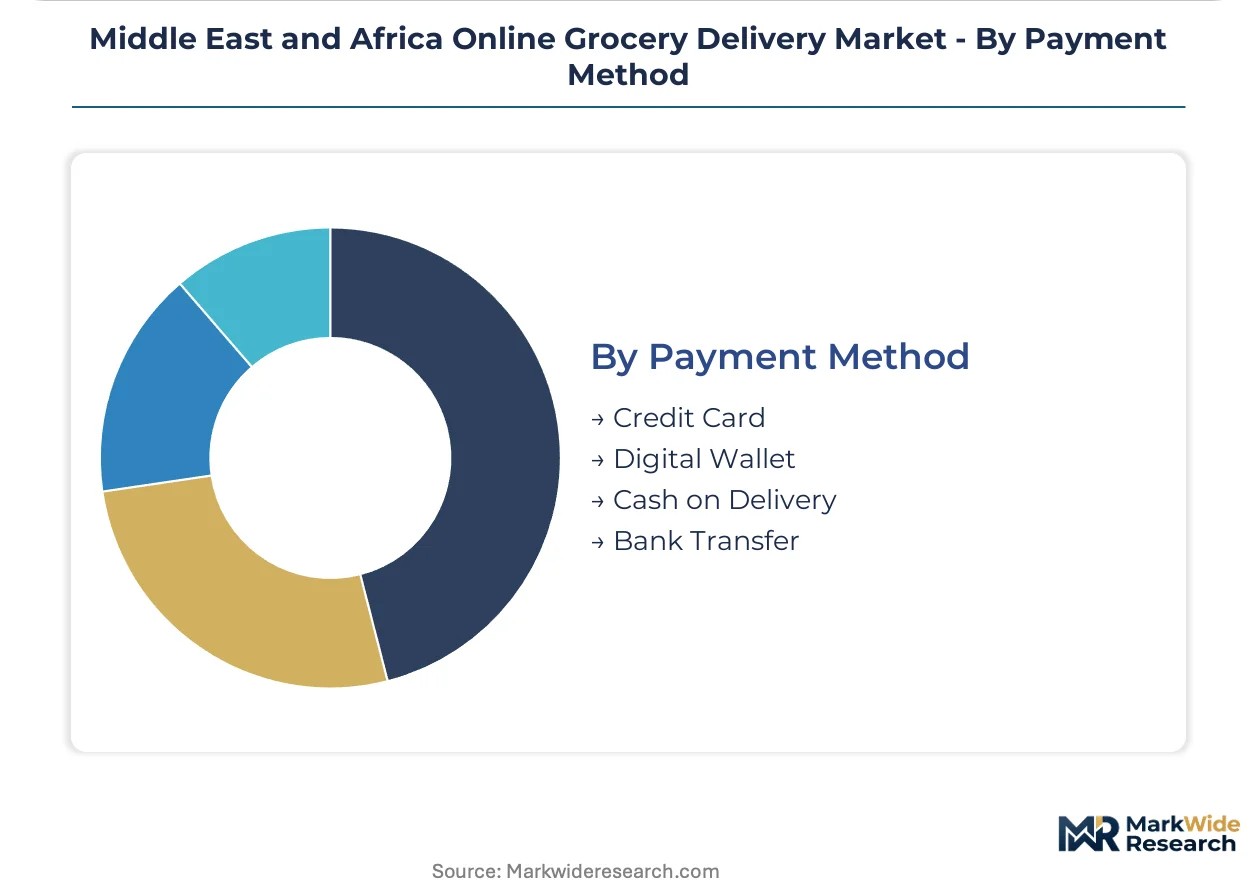
Cash on delivery handles the majority of throughput; digital wallet is gaining share fastest as UAE regulatory frameworks normalize authentication standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Gulf Cooperation Council corridors while Nigerian and Kenyan markets compete on volume throughput. Dubai and Riyadh command premium delivery fees through temperature-controlled infrastructure. Lagos and Nairobi operators absorb higher fulfillment costs to build mobile-first customer bases.
United Arab Emirates
Young urban households in Dubai drive scheduled delivery adoption for weekly grocery planning. The central bank's digital-wallet regulations accelerate cashless transaction normalization across fulfillment platforms. Temperature-controlled last-mile networks expand through Abu Dhabi and Sharjah, enabling same-day promises for perishable categories.
Saudi Arabia
Subscription models penetrate Riyadh and Jeddah households for staple replenishment cycles. SAMR e-commerce vendor registration requirements reshape market access protocols for cross-border grocery platforms. Micro-fulfillment infrastructure proliferates in secondary cities beyond the primary metropolitan corridor.
Nigeria
Lagos young urban households adopt mobile-first ordering as the default procurement interface. The national data protection authority tightens platform liability rules for customer data handling across fulfillment networks. Route density concentrates in Lagos-Ibadan corridor where scheduled delivery windows compress logistics costs.
Kenya
Nairobi households select 2-hour arrival slots 24-48 hours in advance for harvest-to-consumption alignment. Consumer protection frameworks govern payment authentication and refund protocols for digital grocery transactions. Last-mile networks prioritize dense urban cores where batch fulfillment amortizes driver wages.
South Africa
Financial sector conduct authority alignment creates compliance differentiation for proactive platform operators. Johannesburg and Cape Town concentrate B2B restaurant delivery demand through pre-dawn scheduling algorithms. Cold-chain certification timelines extend vendor onboarding for dairy and produce categories.
Middle East and Africa Online Grocery Delivery Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Middle East and Africa online grocery delivery market. Dark-store operators with captive logistics networks command premium positioning in Gulf Cooperation Council cities. Marketplace aggregators compete on selection breadth and partnership density. Quick-commerce specialists and vertical integrators represent the third archetype. Capacity expansion and strategic partnerships constitute the dominant competitive moves reshaping market structure.
Among Gulf-based integrated operators, Talabat Holding plc and Jahez exemplify the dark-store fulfillment archetype with captive last-mile infrastructure. Kibsons International LLC occupies a position within the vertical integration tier, representing fresh-produce sourcing concentration in UAE markets. These three entities anchor distinct strategic positions without overlapping core competitive vectors.
| Leading Market Players |
|---|
| HungerStation Company LLC |
| Deliveroo |
| Talabat Holding plc |
| Keeta |
| Jahez |
| Noon AD Holdings One Person Company LLC |
| Careem |
| Kibsons International LLC |
| InstaShop Ltd. |
| Others |
Supply & Pricing Matrix
Capacity reservation agreements with UAE-based vertical integrators lock in cold-chain access and price visibility for dark-store operators expanding across Gulf Cooperation Council corridors. These contracts tie fulfillment network investments to guaranteed produce volumes, insulating procurement costs from spot-market volatility in East African highlands.
Pricing Analysis
The customization-premium spread separates scheduled delivery slots configured 24-48 hours ahead from on-demand promises under 60 minutes. Three-tier pricing structure across premium, standard, and economy levels stratifies by delivery cadence and temperature certification, with SAMR Arabic-labeling compliance adding cost layers for cross-border suppliers. Price compression runs through the on-demand tier as phase-change material cooling systems reduce refrigeration capital barriers. Cash-on-delivery households in Lagos and Nairobi exhibit highest price sensitivity; subscription-model Saudi households show lowest elasticity for staple replenishment cycles.
Supply Chain Analysis
Inventory lead times for leafy greens stretch 48-72 hours from East African highland harvest to Dubai dark-store receipt, constraining just-in-time fulfillment promises. Supply concentrates in Kenya, Egypt, and the UAE for fresh produce, with Saudi Arabia and Nigeria dependent on cross-border consolidation hubs. Diesel-powered refrigeration units draw from volatile fuel markets as subsidies contract. Single-source vulnerability sits with UAE-based vertical integrators controlling limited regional agricultural supply. Distribution runs through temperature-controlled consolidation hubs to last-mile dark-stores and micro-fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market sits at a platform-economics inflection where interoperability between digital-wallet frameworks and fulfillment APIs determines competitive survival, accelerated by UAE central bank authentication standardization.
For Market Incumbents: Shield route density advantages in dense Gulf urban cores through exclusive dark-store real estate locking. Consolidate procurement relationships with East African highland farms before SAMR labeling requirements extend to cross-border suppliers. Vertical integration into phase-change material cooling manufacturing reduces exposure to refrigeration equipment import tariffs.
For New Entrants and Emerging Players: Differentiate on specialized quick-commerce infrastructure for secondary Saudi cities beyond Riyadh and Jeddah where micro-fulfillment penetration lags. Target scheduled delivery white space in Nairobi and Lagos where young urban households favor harvest-aligned 2-hour windows. Pursue partnership-first go-to-market with legacy retailers facing legacy ERP integration friction.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated operators with captive cold-chain assets over marketplace aggregators. Long-term viability hinges on fulfillment network density rather than customer acquisition spend. Watch SAMR vendor registration enforcement timelines as inflection signal for cross-border platform market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Micro-Fulfillment Center Buildout | Phase-change cooling systems enable dark-store proliferation in dense Dubai and Riyadh urban cores. |
| Backward Integration into Produce Sourcing | Vertical control over East African highland harvest cycles reduces SAMR onboarding timeline exposure. |
| Digital Wallet Platform Integration | UAE central bank authentication frameworks reduce cash-on-delivery working capital constraints. |
| Subscription Model Expansion | Recurring revenue pools among Saudi households remain underdeveloped relative to on-demand penetration. |
| Quick-Commerce Infrastructure Licensing | Specialized fleet scheduling algorithms command premium talent compensation across secondary Gulf cities. |
Research Methodology
Cross-validation between executive interviews at dark-store operators and customs data on temperature-controlled equipment imports anchors the qualitative findings. Primary fieldwork engaged fulfillment network directors, SAMR regulatory affairs leads, UAE central bank payment specialists, and East African agricultural procurement managers. Secondary validation drew from SAMR e-commerce filings, UAE central bank digital-wallet circulars, Kenya horticultural export statistics, and Saudi customs cold-chain equipment records. Bottom-up route-density modeling triangulated against top-down grocery retail digitization indices.
Sensitivity analysis tested forecast outputs against diesel price volatility scenarios and SAMR enforcement acceleration timelines. The analytical framework segments by delivery model, product perishability tier, customer endpoint type, and payment infrastructure maturity across the projection horizon. CAGRs derived from logistic diffusion curves fitted to smartphone penetration and fulfillment infrastructure investment cycles. Industry-specific inputs included cold-chain energy cost trajectories and digital-wallet adoption elasticities.
The analysis sits within stated boundaries; outcomes outside sustained UAE-Saudi regulatory alignment or East African harvest stability would require recalibration. Forecasts reflect documented assumptions on fuel subsidy contraction pace and SAMR vendor registration expansion. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Asia Pacific Food Platform-To-Consumer Delivery Market
Food Service
Africa Foodservice Market
Food Service
US Food Service Market
Food Service
Europe Barbeque Grill Market
Food Service
Haute Cuisine Market
Food Service
Egypt Food Service Market
Food Service
Smart Food Logistics Market
Food Service
Supermarkets Market
Food Service
Vacuum Flask Market
Food Service
Catering Food Warmers Market
Food Service
South Africa Fast Food Market
Food Service
Commercial Tableware Services Market
Food Service
Aquarium Protein Skimmers Market
Food Service
Switzerland Food Service Market
Food Service
Global Food Platform-To-Consumer Delivery Market
Food Service
India Full Service Restaurants Market