
 Food and Beverage Additives Market | 2026-2036
Food and Beverage Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Food and Beverage Additives Market Analysis
Asset-light contract manufacturing and third-party tolling arrangements is reconfiguring capital requirements for mid-scale additive producers. Cargill, Incorporated leverages its integrated agricultural supply chain to control input costs for emulsifier production. Kerry Group plc sustains competitive position through specialized taste and nutrition solutions across beverage and dairy channels.
Food and beverage additives comprise functional substances—typically at inclusion rates below one percent by weight—that modify texture, extend shelf stability, or enhance sensory profiles through controlled chemical interaction with base matrices. These compounds serve primarily to standardize product performance across variable raw material inputs and processing conditions. Preservatives and flavor enhancers command the largest current revenue pools, though clean-label emulsifiers represent the fastest-expanding margin segment as formulators replace synthetic alternatives. Thickeners occupy a mature, volume-driven position in sauces and bakery applications where cost optimization outweighs premium positioning.
The FDA's GRAS program and the EPA's chemical safety assessments jointly determine market access timelines for novel additive introductions in the United States. EFSA's re-evaluation mandates under the EU Food Improvement Agent Package continue reshaping acceptable preservative chemistries for European formulators. Stakeholders must monitor evolving regulatory divergence between jurisdictions to anticipate reformulation costs and compliance-driven portfolio rationalization.
Market Dynamics
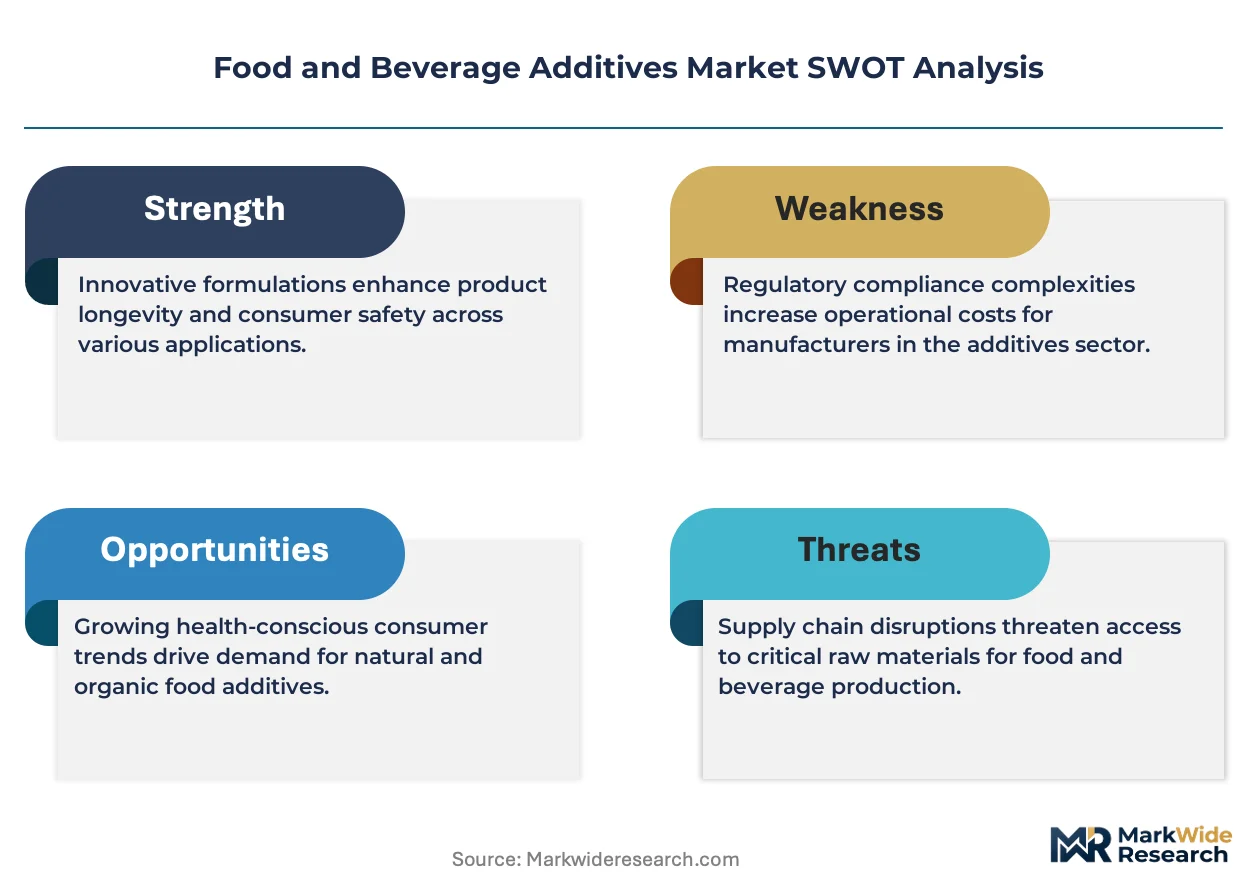
Clean-label reformulation pressure from Western European retailers and China's tier-one dairy innovators is compressing synthetic additive demand while pulling natural alternatives into scale production.
Growth Catalysts
- EFSA Re-evaluation Mandates:The EU Food Improvement Agent Package is accelerating preservative chemistry turnover, forcing formulators toward clean-label alternatives that command premium positioning in bakery and beverage channels.
- China Tier-One Dairy Innovation:Shanghai and Beijing beverage manufacturers are expanding functional dairy SKUs, creating concentrated pull for texture-modifying hydrocolloids and natural emulsifiers at inclusion rates below one percent.
- FDA GRAS Notification Tightening:The updated self-affirmation framework is extending market access timelines for novel additives, advantaging incumbents with established safety dossiers and documented consumption histories.
Market Restraints
- Natural Extract Input Volatility:Rosemary-derived antioxidants and citrus-based preservatives face agricultural yield fluctuations that compress margin stability for clean-label producers.
- Specialty Chemical Supply Concentration:China dominates citric acid and sorbitol refining capacity, creating geographic concentration risk for Western formulators dependent on Asian feedstock.
- Clean-Label Performance Ceiling:Natural emulsifiers currently fail to match synthetic lecithin functionality in high-fat bakery applications, limiting complete substitution.
Strategic Opportunities
- India Processed Food Expansion:FSSAI harmonization with Codex standards is opening formulation pathways for multinational additive suppliers in nascent ready-to-eat and convenience dairy segments.
- Fermentation-Derived Ingredient Platforms:Precision fermentation for natural flavor modulators and alternative proteins is converging with traditional additive manufacturing, enabling novel clean-label positioning.
- Direct-to-Formulator Digital Channels:B2B ingredient marketplaces are disintermediating traditional distributor networks, allowing mid-scale producers to access regional bakery and beverage manufacturers without national distribution partnerships.
Industry Challenges
- Toxicology Data Generation Timelines:EFSA and FDA safety dossier requirements demand 18-36 month chronic exposure studies, compressing product development cycles against accelerating clean-label demand.
- Legacy ERP Integration:Batch-level traceability mandates under EU General Food Law and US FSMA are forcing additive producers to reconfigure manufacturing execution systems for granular ingredient genealogy tracking.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food and Beverage Additives Market |
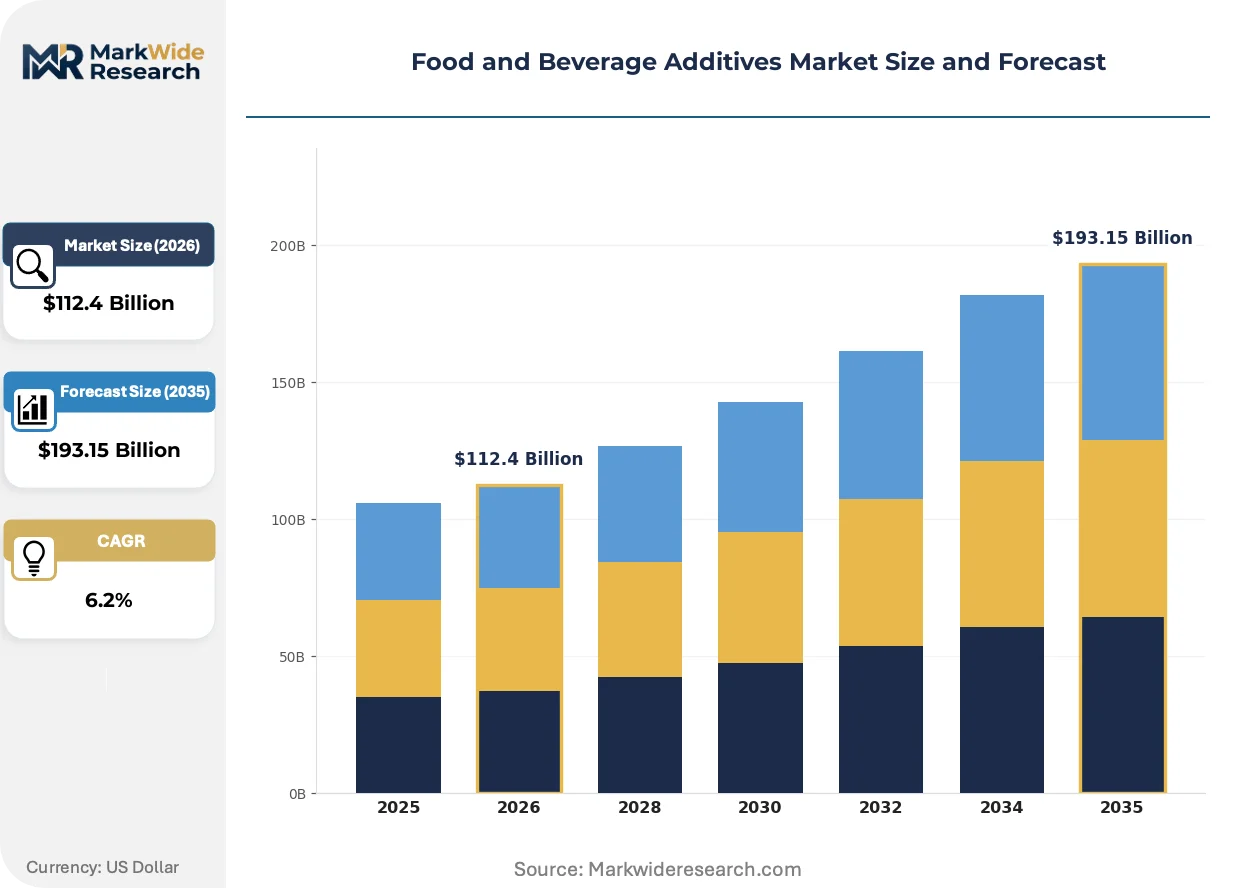
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $193.15 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsifiers, Thickeners, Preservatives, Flavor Enhancers Application: Beverages, Bakery, Dairy, Sauces Form: Liquid, Powder, Granule, Paste Grade: Food Grade, Technical Grade, Organic, Customized |
| Companies Covered | Ingredion Incorporated, International Flavors and Fragrances Inc., Cargill, Incorporated, Givaudan, Kerry Group plc, BASF SE, Tate & Lyle Plc, Chr. Hansen Holding A/S, Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food and Beverage Additives Market Emerging Trajectories
Bioprocessing advances and regulatory chemistry reclassification are restructuring how functional ingredients achieve clean-label positioning without sacrificing shelf stability or texture performance.
Plant-derived antimicrobial peptides are migrating from niche organic applications into mainstream processed meat preservation. European sausage and deli manufacturers are adopting these extracts at commercial scale following EFSA positive opinions on specific peptide fractions. The technology is migrating from premium positioning into cost-competitive standard formulations as extraction yields improve and unit economics approach synthetic benzoate parity.
REACH authorization sunset dates for certain synthetic colorants are forcing confectionery and beverage formulators toward anthocyanin and carotenoid alternatives. The industrial consequence is expanded contract cultivation partnerships between additive suppliers and European agricultural cooperatives for pigment-rich crop varieties. Gummy and hard candy segments in Germany and France are most affected, with manufacturers accelerating reformulation timelines to avoid stock-out risk during authorization windows.
Consolidated retail buying power in Western Europe is compressing additive supplier margins through specification standardization and volume commitment requirements. Aldi and Lidl central procurement offices are unbundling technical service from ingredient supply, treating emulsifiers and stabilizers as commodity inputs. This pattern is most visible in German and Benelux private-label bakery, where regional producers have lost negotiating leverage against standardized ingredient decks.
Food and Beverage Additives Market Segmentation
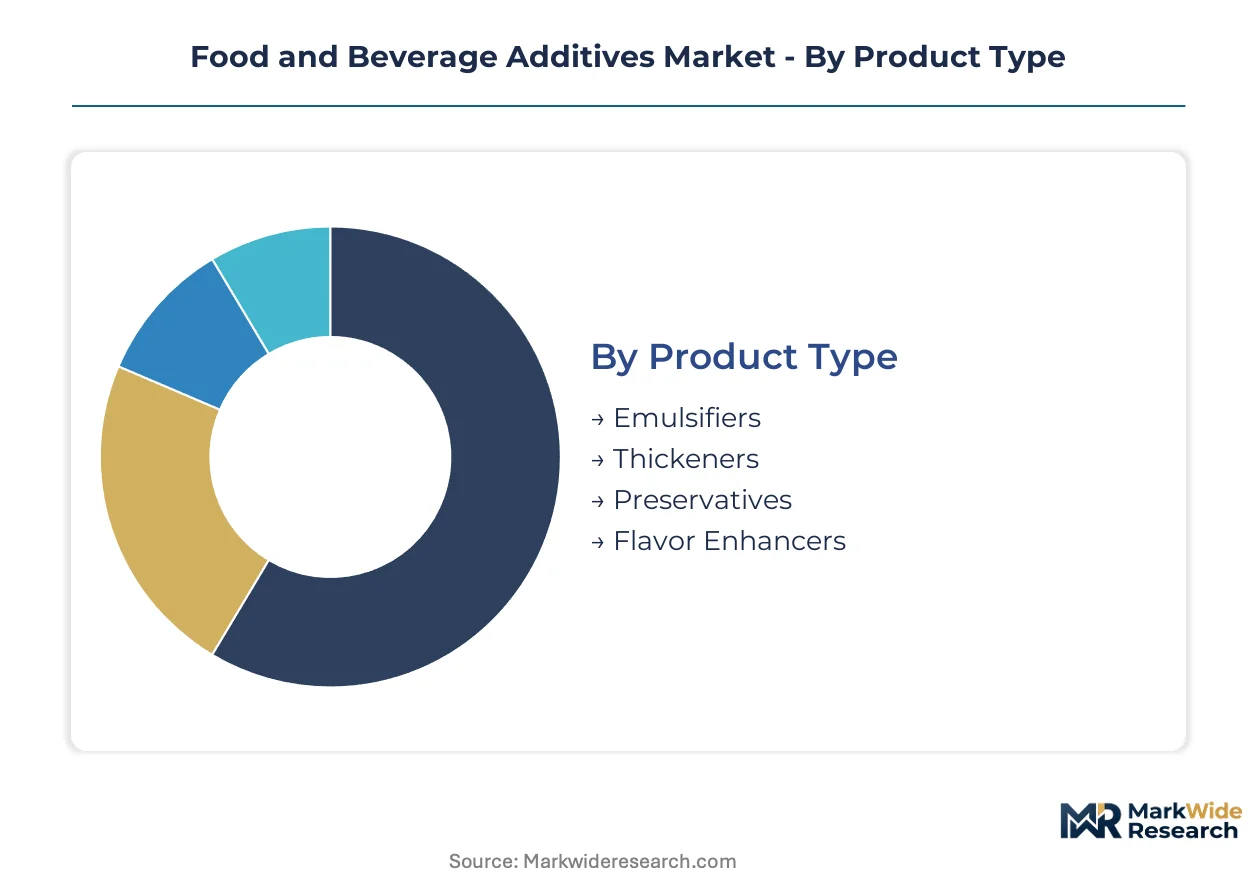
Segmentation in food and beverage additives reveals how functional requirements, regulatory thresholds, and processing constraints fragment demand across incompatible specification tiers. Manufacturers configure production assets around these divisions because reformulation cycles and margin profiles vary dramatically by segment.
Product Type:
Cycle times diverge sharply: preservatives face 18-36 month safety dossier renewals under EFSA mandates, while emulsifiers turn over faster as clean-label alternatives displace legacy chemistries.
- Emulsifiers:Surface-active agents stabilize oil-water interfaces in high-fat matrices. Clean-label lecithin alternatives from sunflower and rapeseed sources are gaining formulation share in German and French bakery channels as REACH sunset dates approach for synthetic variants.
- Preservatives:Antimicrobial compounds extend shelf stability through pH modulation or oxidative interruption. Rosemary extract and cultured dextrose alternatives are scaling in Western European private-label meat and dairy applications where retailers mandate EFSA-compliant clean-label positioning.
- Thickeners:Hydrocolloids modify viscosity through water-binding or gel network formation. Xanthan and guar gum dominate mature sauce and dressing applications where cost optimization outweighs premium positioning.
- Flavor Enhancers:Taste modulators amplify perceived sweetness or umami without caloric contribution. Yeast extract and natural glutamate alternatives are penetrating Chinese tier-one city beverage formulations as sodium reduction targets tighten.
Thickeners anchor the volume base while emulsifiers gain share at the steepest rate.
Application:
Cost tier stratification separates commodity-scale sauce manufacturing from premium beverage formulation where inclusion rates below one percent justify specialized technical service.
- Beverages:Functional drinks and flavored waters require clarity-stable emulsifiers and natural colorants. Shanghai and Beijing manufacturers are accelerating SKU expansion in protein-fortified dairy beverages, pulling demand for texture-modifying hydrocolloids.
- Bakery:Shelf-stable cakes and pastries depend on emulsifier-starch interactions for crumb structure. Western European clean-label reformulation is compressing synthetic additive demand while expanding natural preservative volumes in artisan-positioned products.
- Dairy:Fermented and processed milk applications need pH-tolerant stabilizers. India's FSSAI-harmonized standards are opening formulation pathways for multinational suppliers in nascent ready-to-eat yogurt segments.
- Sauces:Viscosity control and emulsion stability define performance in condiment and dressing matrices. Cost-driven procurement in foodservice channels favors standardized hydrocolloid blends over customized solutions.
Bakery commands the largest current revenue pool while beverage applications expand most quickly.
Form:
Volume economics favor powder processing for bulk ingredients, whereas liquid and paste forms command premium positioning in continuous-manufacturing beverage lines.
- Powder:Dried particulates enable extended shelf stability and simplified logistics. Bulk emulsifier and thickener shipments to sauce manufacturers run predominantly through this form factor.
- Liquid:Pumpable concentrates suit automated dosing in high-throughput beverage plants. Chinese dairy innovators in tier-one cities prefer liquid hydrocolloid delivery for reduced hydration time.
- Granule:Free-flowing intermediate particle sizes bridge dust control and dissolution speed. Selected for bakery premix applications where uniform dispersion matters.
- Paste:High-viscosity semisolids concentrate functional actives for minimal inclusion rates. Premium positioning in customized flavor enhancer delivery for confectionery channels.
Powder dominates tonnage shipments while liquid forms climb fastest in value terms.
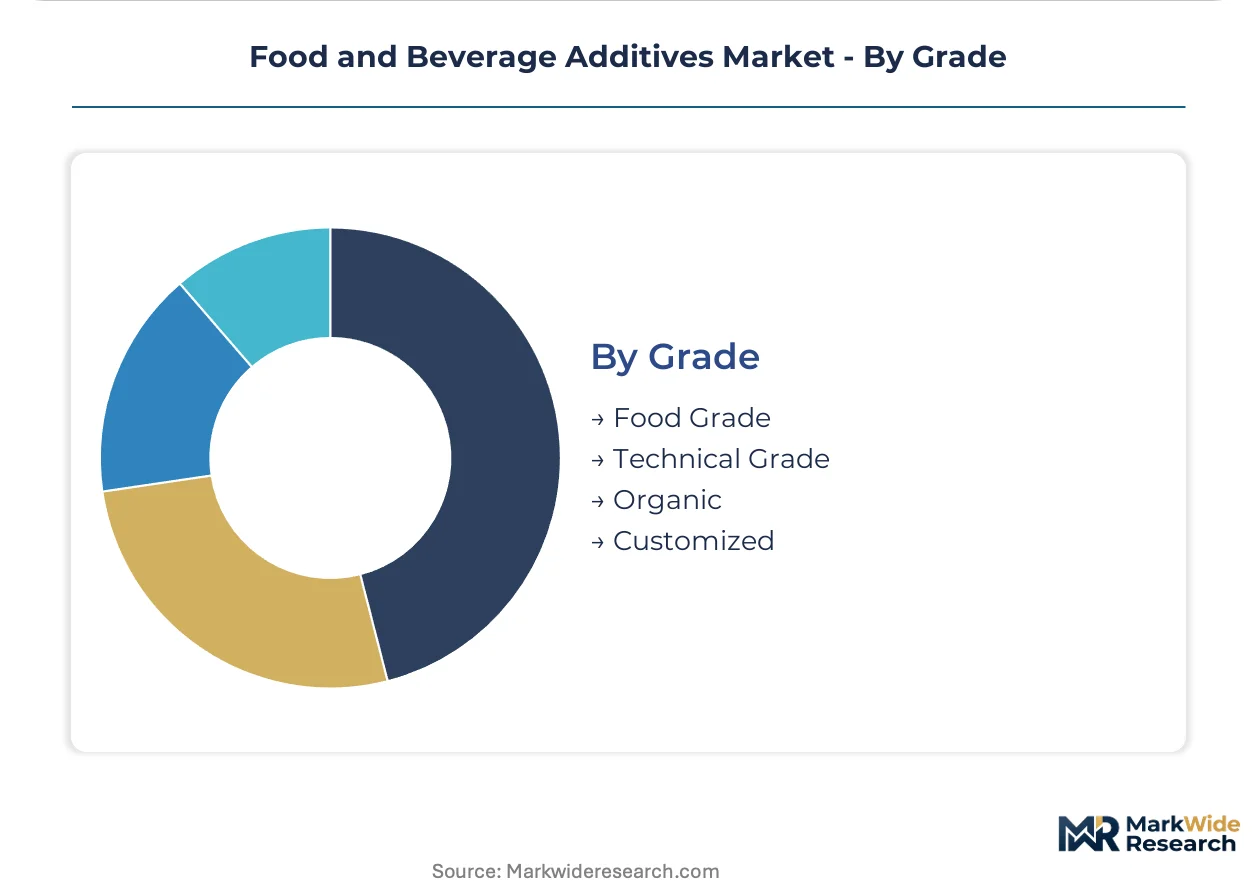
Grade:
Customer type splits procurement: multinational formulators specify food grade with full certification packages, while regional processors trade specification depth for cost in technical grade sourcing.
- Food Grade:Meets Codex and national pharmacopeia purity standards for direct human consumption. Mandatory for EU and US commercial food manufacturing under FDA and EFSA enforcement frameworks.
- Organic:Certified to USDA National Organic Program or EU Organic Regulation inputs standards. Western European retailer specifications are mandating organic-grade preservatives and emulsifiers in premium private-label lines.
- Technical Grade:Reduced purity specifications for industrial or non-food applications. Limited food sector penetration restricted to specific processing aids with no carryover.
- Customized:Blended or modified specifications for proprietary formulation requirements. Emerging in direct-to-formulator digital channels where mid-scale producers bypass distributor standard portfolios.
Food grade underpins commercial volume while organic certification gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing leverage concentrates in Western Europe where retailer consolidation squeezes supplier margins, while Chinese tier-one cities generate premium-pull demand that outpaces cost-driven procurement elsewhere.
United States
Clean-label beverage reformulation and functional dairy expansion drive demand for natural emulsifiers and texture modifiers. The FDA's updated GRAS notification framework extends market access timelines for novel additives, advantaging incumbents with established safety dossiers. Chicago and Minneapolis-St. Paul host concentrated food manufacturing clusters where mid-scale additive producers compete through direct-to-formulator digital channels.
Germany
Aldi and Lidl central procurement offices compress additive margins through specification standardization in private-label bakery. EFSA re-evaluation mandates under the EU Food Improvement Agent Package accelerate preservative chemistry turnover. The Rhineland and Bavaria concentrate meat processing and confectionery manufacturing where plant-derived antimicrobial peptides scale into standard formulations.
China
Shanghai and Beijing beverage manufacturers expand protein-fortified dairy SKUs, pulling demand for hydrocolloids and natural emulsifiers at sub-one-percent inclusion rates. SAMR's evolving food additive standards create compliance complexity for multinational suppliers. The Yangtze River Delta anchors dairy innovation clusters where domestic and international additive firms compete for formulation partnerships.
India
FSSAI harmonization with Codex standards opens pathways for multinational suppliers in nascent ready-to-eat and convenience dairy segments. Processed food expansion in urban centers accelerates demand for shelf-stable emulsifier systems. Maharashtra and Gujarat concentrate contract manufacturing capacity where regional processors trade specification depth for cost in technical-grade sourcing.
Brazil
ANVISA's food additive regulatory updates reshape import and local production requirements for preservative and flavor systems. Processed meat and beverage manufacturing expansion drives demand for clean-label alternatives. São Paulo state anchors national food processing capacity where domestic additive producers defend position through backward integration into agricultural feedstocks.
Food and Beverage Additives Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream where formulation expertise and regulatory dossiers create defensive moats. The vendor base stratifies across three tiers: multinational agricultural processors with captive raw material access, mid-scale specialty chemical houses with regional formulation service capabilities, and emerging fermentation-derived ingredient platforms. Structural consolidation favors incumbents with integrated supply chains and documented consumption histories. Competitive moves concentrate on portfolio diversification into clean-label alternatives and geographic expansion through tolling partnerships.
Within the integrated agricultural processor tier, Cargill, Incorporated and Archer Daniels Midland Company exemplify backward integration strategies that control input costs for emulsifier production. Kerry Group plc occupies a position bridging taste technology and nutrition solutions across beverage and dairy channels. These three anchors demonstrate how scale and service integration separate system-tier competitors from component suppliers.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| International Flavors and Fragrances Inc. |
| Cargill, Incorporated |
| Givaudan |
| Kerry Group plc |
| BASF SE |
| Tate & Lyle Plc |
| Chr. Hansen Holding A/S |
| Archer Daniels Midland Company |
| Others |
Supply Flow & Price Mechanics
China's citric acid and sorbitol refining concentration determines both pricing tier spreads and supply chain shape for Western formulators dependent on Asian feedstock. Natural extract input volatility from rosemary and citrus agricultural yields compresses margin stability while forcing procurement diversification into contract cultivation partnerships.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in food and beverage additives. Price differentiation rests on certification grade—organic versus conventional—and volume scale commitments that unlock contract-based long-term offtake terms. Pricing pressure stems from Aldi and Lidl central procurement offices unbundling technical service from ingredient supply. Regional bakery processors exhibit highest price sensitivity, while multinational beverage formulators prioritize performance consistency over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Chinese citric acid refiners and Indian guar gum processors shape working capital requirements for mid-scale additive producers. Geographic supply concentration centers on China for acid and polyol refining, India for hydrocolloid extraction, and Western Europe for fermentation-derived specialty ingredients. Raw material dependencies draw from agricultural feedstocks—sunflower lecithin, rosemary biomass, citrus peels—and petroleum-derived chemical precursors. Single-source vulnerability from China's dominance in citric acid creates tariff exposure risk. Distribution runs through B2B ingredient marketplaces disintermediating traditional national distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of documented EFSA and FDA safety dossiers for novel clean-label chemistries constrains competitive entry and consolidates advantage among incumbents with established consumption histories.
For Market Incumbents: Entrench regulatory moats by accelerating chronic exposure study investments ahead of EFSA re-evaluation mandates, and deepen backward integration into agricultural feedstocks to buffer natural extract input volatility from rosemary and citrus yield fluctuations. For New Entrants and Emerging Players: Establish a beachhead in India's FSSAI-harmonized ready-to-eat dairy segments where multinational supplier penetration remains nascent, and leverage direct-to-formulator digital channels to bypass entrenched distributor relationships in Chinese tier-one city beverage markets. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors fermentation-derived ingredient platforms with precision capabilities for natural flavor modulators, where acquisition targets should demonstrate viable clean-label positioning without synthetic functionality sacrifice; watch EFSA positive opinion issuance rates on plant-derived antimicrobial peptides as inflection indicator for mainstream adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Feedstocks | Cargill and ADM control input costs for emulsifier production through captive supply of sunflower and rapeseed. |
| Fermentation-Derived Ingredient Platform Development | Precision fermentation for natural flavor modulators converges with traditional additive manufacturing at Chr. Hansen. |
| Direct-to-Formulator Digital Channel Launch | B2B marketplaces disintermediate distributor networks for mid-scale producers accessing regional bakery manufacturers. |
| EFSA Safety Dossier Investment Acceleration | Chronic exposure studies compress product development cycles against clean-label demand timelines at Kerry Group. |
| Contract Cultivation Partnership Expansion | Anthocyanin and carotenoid suppliers partner with European agricultural cooperatives for pigment-rich crop varieties. |
Methodological Framework
Initial hypotheses were tested against primary input from R&D directors at multinational additive suppliers, procurement leads at tier-one dairy and beverage manufacturers, regulatory affairs specialists navigating FDA GRAS and EFSA re-evaluation pathways, and technical service managers at regional bakery processors, then refined through secondary validation against FDA GRAS notifications, EFSA scientific opinions, customs and trade data from major importing jurisdictions, and SEC 10-K filings from publicly traded ingredient suppliers. Bottom-up volume modeling across emulsifier, preservative, thickener, and flavor enhancer categories triangulated against top-down market sizing.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product type, application channel, form factor, and grade certification tier. CAGRs were derived from modeled volume trajectories adjusted for regulatory chemistry turnover rates and clean-label substitution elasticities. Industry-specific forecast inputs incorporated EFSA re-evaluation timelines and SAMR food additive standard evolution in China.
Stress conditions across agricultural yield volatility, regulatory approval delays, and raw material price spikes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about clean-label penetration rates and fermentation technology cost curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Egypt Food Emulsifiers Market
Food Additives and Ingredients
Chocolate Wax Market
Food Additives and Ingredients
Asia-Pacific Anti-Caking Market
Food Additives and Ingredients
Synthetic Food Preservatives Market
Food Additives and Ingredients
South Africa Food Enzymes Market
Food Additives and Ingredients
Food Humectants Market
Food Additives and Ingredients
Starch-Based Edible Coatings Market
Food Additives and Ingredients
Alpha-Amylase Baking Enzyme Market
Food Additives and Ingredients
Australia Food Emulsifiers Market
Food Additives and Ingredients
Africa Feed Additives Market
Food Additives and Ingredients
Excipients Market
Food Additives and Ingredients
Natural Solubilizers Market
Food Additives and Ingredients
Germany Food Acidulants Market
Food Additives and Ingredients
Lactylated Monoglyceride Market
Food Additives and Ingredients
Japan Food Acidulants Market
Food Additives and Ingredients
South America Food Acidulants Market