
 Middle East Food Premix Market | 2026-2036
Middle East Food Premix Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Food Premix Market Foresight
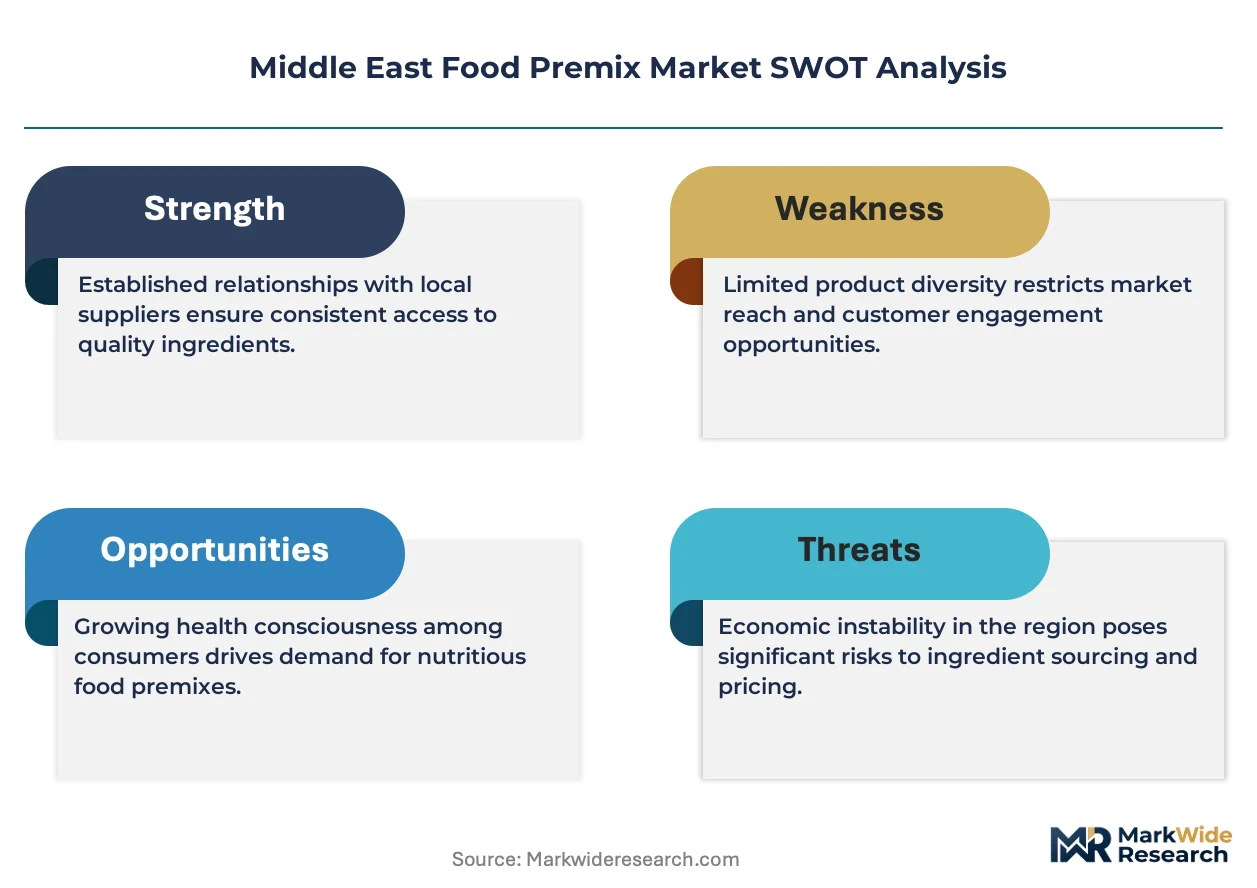
Premium micronutrient specification tiers is unwinding upward price elasticity across Middle East food premix procurement. Archer Daniels Midland Company leverages backward integration into vitamin and mineral raw material streams to sustain cost discipline across Gulf distribution networks. Koninklijke DSM N.V. anchors its regional position through R&D intensity in encapsulated nutrient delivery systems. Glanbia PLC differentiates via dairy-protein premix specialization that aligns with Saudi and UAE dairy fortification programs.
Food premix denotes a blended concentrate of vitamins, minerals, amino acids, and functional ingredients dosed at 0.5-5% inclusion rates into finished food matrices, manufactured through precision dry-mixing or spray-drying to achieve homogeneous particle distribution and shelf-stable bioactivity. Its primary commercial purpose is to standardize nutrient delivery across industrial-scale food production while simplifying quality control for manufacturers lacking in-house micronutrient formulation capability. Baking Mixes occupy the mature volume base, with margin pools concentrating in Beverage Premixes where hydration and functional drink trends in UAE and Saudi Arabia drive premiumization. Food Processing channels represent the fastest-growing application vector, as centralized production in Saudi industrial food zones displaces artisanal batch preparation.
Saudi Food and Drug Authority fortification rules and UAE Ministry of Industry and Advanced Technology standardization protocols are tightening premix documentation requirements, pushing suppliers toward third-party certification and traceability systems. Gulf Standards Organization harmonization across GCC member states is reducing cross-border formulation friction but elevating compliance costs for non-certified imports. Stakeholders must monitor evolving micronutrient maximum-level thresholds and halal-certification integration timelines to preserve market access across divergent national enforcement calendars.
Market Dynamics
Saudi Food and Drug Authority fortification mandates are compressing formulation timelines across Gulf premix procurement, forcing suppliers to synchronize R&D cycles with tightening micronutrient labeling enforcement calendars.
Growth Catalysts
- SFDA Mandatory Fortification:Saudi Arabia's wheat flour and edible oil fortification rules are pulling specification-grade premix volumes into centralized industrial food zones.
- UAE Hospitality Procurement Standards:Dubai's hotel and catering supply chains are elevating third-party certified premix sourcing requirements above commodity-grade alternatives.
- Encapsulation Technology:Heat-stable vitamin microencapsulation is extending shelf life in high-temperature Gulf distribution environments.
Market Restraints
- Vitamin Raw Material Concentration:Chinese feedstock dominance in ascorbic acid and B-vitamin precursors exposes Gulf blenders to input cost volatility and currency fluctuation risk.
- Halal Certification Friction:Divergent national enforcement timelines between Saudi Arabia's SFDA and UAE's ESMA are elevating compliance documentation burdens for cross-border premix shipments.
- Artisanal Substitution:Small-scale UAE bakeries and Saudi dairy processors continue manual fortification practices that bypass standardized premix procurement.
Strategic Opportunities
- Kuwait Underpenetration:Limited domestic premix manufacturing capacity creates import dependency that specialized Gulf distributors can capture.
- Sports Nutrition Applications:Protein-fortified recovery beverages in UAE fitness channels represent a white space beyond traditional infant and dairy segments.
- GSO Harmonization:Gulf Standards Organization micronutrient maximum-level alignment is reducing cross-border formulation friction for certified suppliers.
Industry Challenges
- Traceability System Integration:Blockchain-enabled batch tracking requirements from Saudi and UAE regulators are forcing legacy ERP upgrades at mid-size blending facilities.
- Specialized Formulation Talent:Scarcity of food science PhDs with halal biochemistry expertise is elongating product development cycles in Dubai and Riyadh.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Food Premix Market |
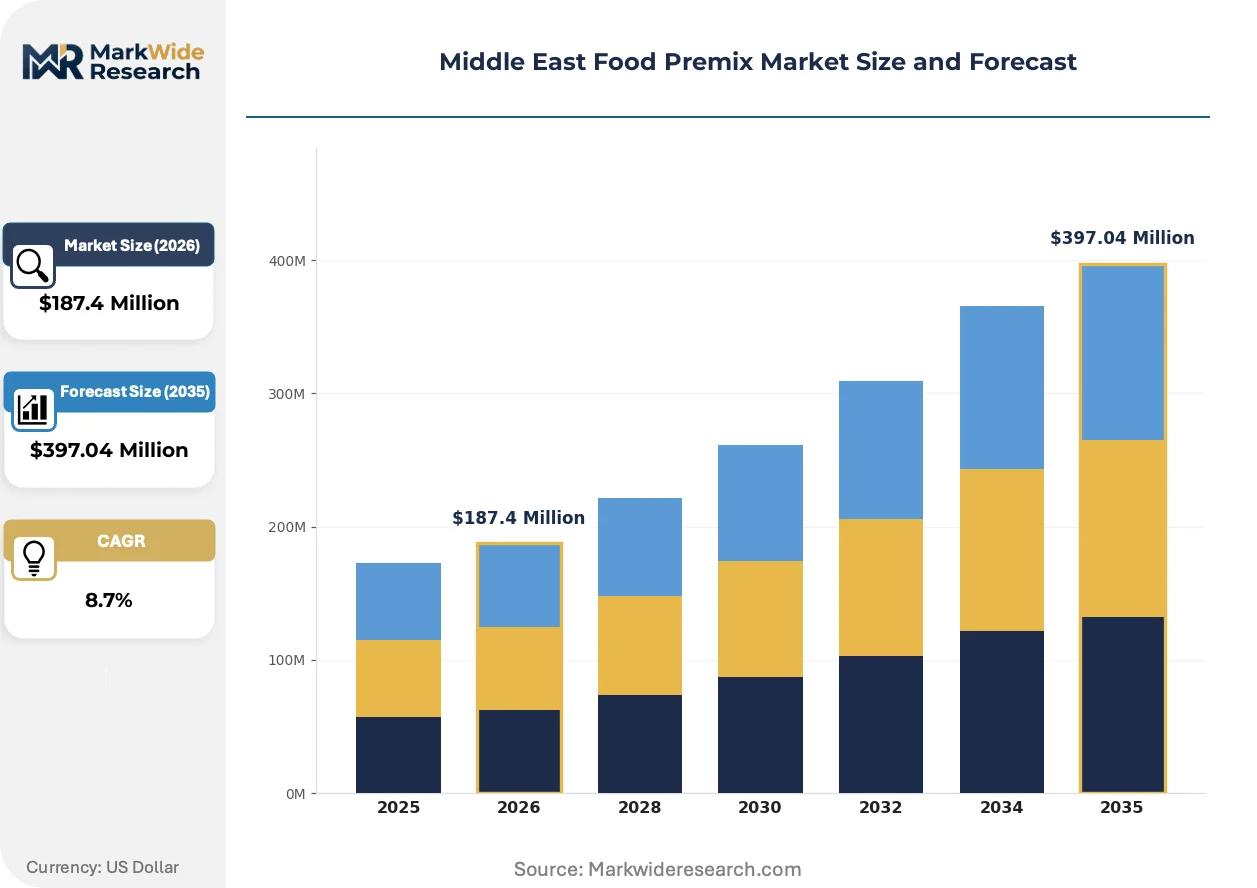
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Baking Mixes, Beverage Premixes, Sauces, Seasonings Application: Bakeries, Restaurants, Catering Services, Food Processing Packaging Type: Bags, Tubs, Pouches, Bottles Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Foodservice Channels |
| Companies Covered | Archer Daniels Midland Company, Koninklijke DSM N.V., Glanbia PLC, Prinova Group LLC, Hexagon Nutrition Pvt. Ltd, Lycored, Barentz, Fenchem, SternVitamin GmbH & Co., Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Food Premix Market Shifts & Advancements
Precision nutrient delivery systems are compressing the gap between pharmaceutical-grade bioavailability and food-grade cost structures across Middle East premix manufacturing.
Microencapsulation via spray-drying and fluidized bed coating is decomposing the traditional tradeoff between thermal stability and intestinal absorption rates. Saudi dairy processors and UAE beverage manufacturers are adopting double-shell lipid-polymer matrices at accelerated procurement cycles. This technology is decomposing price premiums previously commanded by pharmaceutical-origin vitamin suppliers.
SFDA's 2024 micronutrient maximum-level threshold revisions are forcing reformulation of iron and folic acid premixes destined for wheat flour applications. Industrial millers in Jeddah and Dammam are submitting revised stability documentation ahead of enforcement deadlines. Infant nutrition specialists face the steepest compliance burden due to stricter bioavailability demonstration requirements.
Centralized procurement consortia among UAE hospitality groups are consolidating specification-setting authority away from individual hotel purchasing departments. Dubai-based food service distributors are capturing margin pools by offering inventory-managed premix programs with guaranteed halal certification continuity. This concentration is most visible in premium hotel chains where chef-driven menu differentiation previously fragmented sourcing decisions.
Middle East Food Premix Market Segmentation
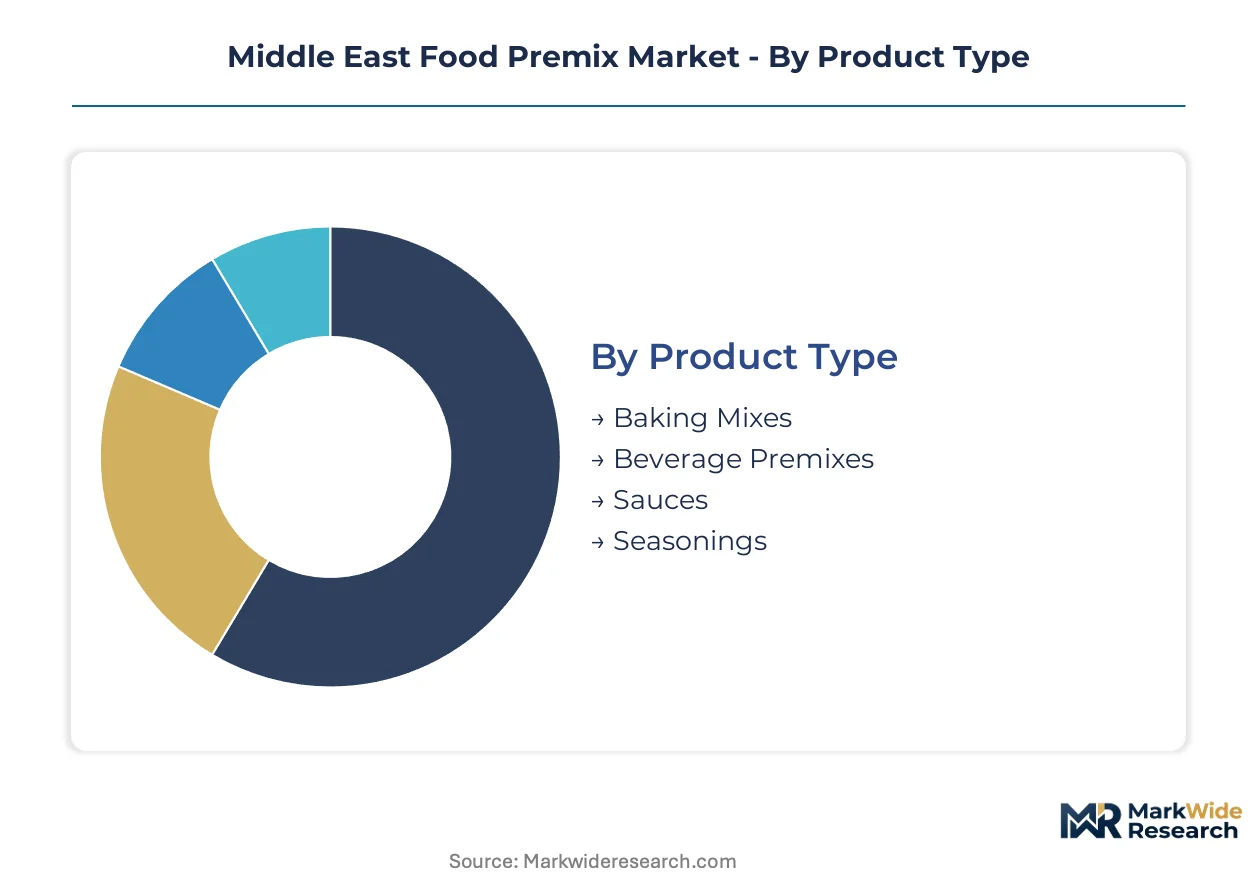
Food premix procurement patterns across Gulf markets fragment sharply across product categories and end-use channels. Substitution pressures from artisanal fortification and manual blending create uneven competitive intensity that reshapes supplier positioning.
Product Type:
Substitution from commodity vitamin powders and in-house blending operations concentrates most acutely in mature categories where specification gaps have narrowed.
- Baking Mixes:Mature vitamin-mineral concentrates for industrial bread and pastry production, standardized at 0.5-2% inclusion rates. Saudi industrial millers in Jeddah and Dammam dominate procurement volumes under SFDA wheat flour fortification mandates, though small UAE bakeries bypass premix sourcing through manual additive scaling.
- Beverage Premixes:Hydration-focused micronutrient matrices with electrolyte and vitamin complexes, requiring heat-stable encapsulation for Gulf distribution temperatures. Dubai fitness channels and UAE hospitality procurement consortia are elevating specification-grade sourcing above commodity alternatives.
- Sauces:Viscosity-compatible nutrient suspensions for industrial dressing and condiment lines.
- Seasonings:Salt-carrier micronutrient blends for processed meat and snack applications.
Baking Mixes retains volume leadership; Beverage Premixes holds the steepest expansion curve.
Application:
Channel concentration dynamics split between centralized industrial zones and fragmented artisanal endpoints, with margin capture favoring scale-aligned suppliers.
- Bakeries:Artisanal UAE operations and Saudi industrial millers present divergent procurement profiles, with the latter consolidating under SFDA compliance deadlines while the former resists standardized premix adoption.
- Food Processing:Centralized production in Saudi industrial food zones displaces batch preparation, with Jeddah and Riyadh facilities driving specification-grade premix volumes under tightening traceability mandates.
- Restaurants:Menu-driven nutrient customization creates fragmented demand across independent operators.
- Catering Services:Dubai hotel and institutional procurement standards elevate third-party certification requirements above commodity sourcing.
Food Processing commands the deepest margin pools; Bakeries faces the steepest substitution pressure from manual fortification.
Packaging Type:
Packaging selection tracks directly against humidity exposure and batch-size economics across Gulf distribution corridors.
- Bags:Multi-layer laminated bulk formats for industrial millers and food processing facilities, optimized for 25-50kg dosing efficiency in Saudi centralized production zones.
- Pouches:Flexible single-serve and small-batch formats gaining traction in UAE hospitality channels where inventory turnover and halal certification continuity dominate procurement criteria.
- Tubs:Rigid plastic containers for moisture-sensitive vitamin matrices.
- Bottles:Dispensing formats for liquid premix concentrates in beverage manufacturing.
Bags retains industrial volume leadership; Pouches gains share fastest in premium hospitality channels.
Distribution Channel:
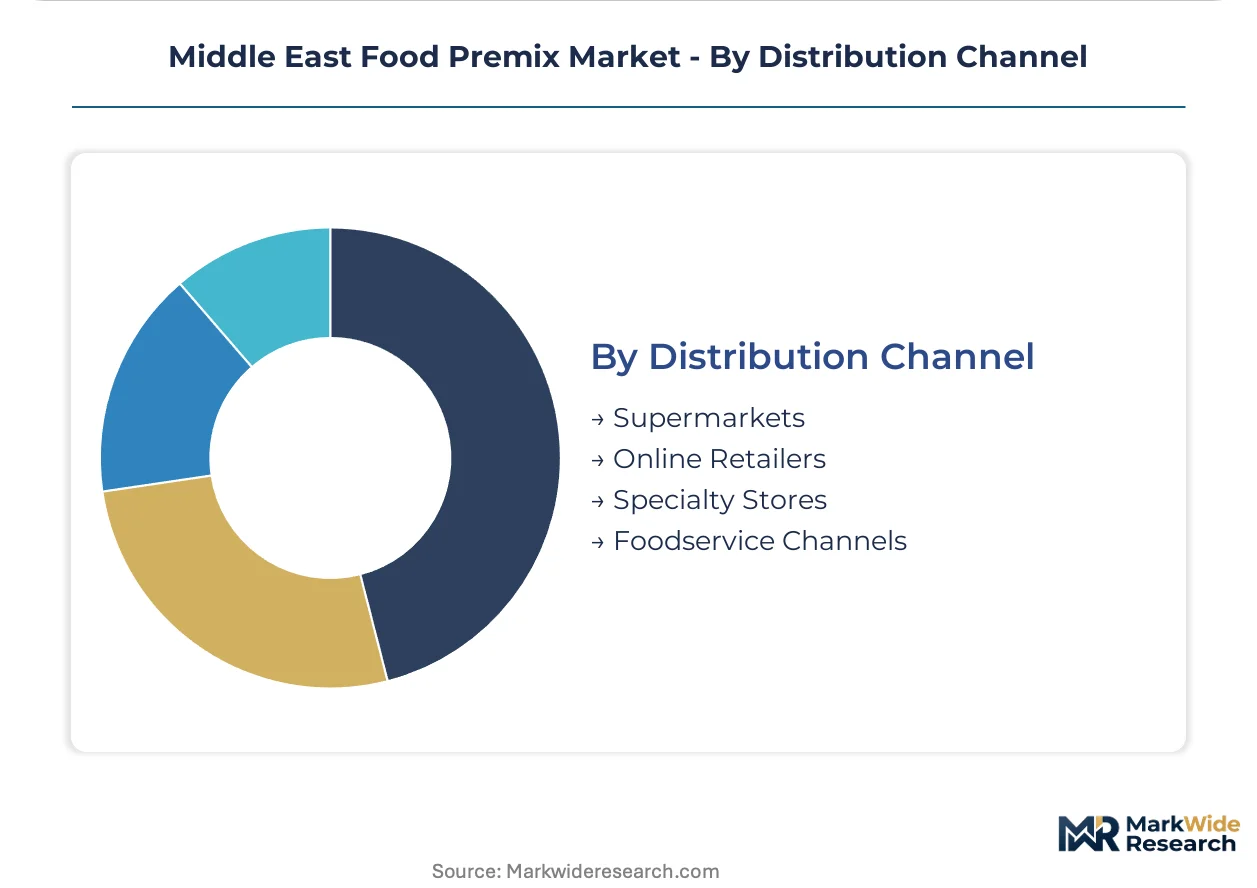
Channel control is concentrating among Dubai-based distributors offering inventory-managed programs with guaranteed certification continuity.
- Foodservice Channels:Consolidated procurement consortia among UAE hospitality groups are capturing specification-setting authority, with inventory-managed premix programs displacing fragmented hotel purchasing departments.
- Specialty Stores:Technical sales support and formulation consulting for mid-size Saudi dairy processors lacking in-house micronutrient capability.
- Supermarkets:Retail-accessible formats for small-scale bakery and restaurant operators.
- Online Retailers:Emerging procurement path for standardized premix SKUs with documented halal certification.
Foodservice Channels deepens its grip on premium specification volumes; Specialty Stores anchors technical consultative sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premix manufacturing capacity clusters around Jeddah and Dubai, with raw material sourcing dependencies stretching to Chinese vitamin feedstock suppliers. SFDA enforcement timelines and UAE certification protocols are diverging, creating compliance complexity for cross-border Gulf distributors. Industrial food zones in Saudi Arabia and hospitality procurement hubs in the Emirates anchor regional demand patterns.
Saudi Arabia
Wheat flour and edible oil fortification mandates are pulling specification-grade premix volumes into Jeddah and Dammam industrial millers. SFDA's 2024 micronutrient maximum-level threshold revisions are forcing reformulation of iron and folic acid premixes ahead of enforcement deadlines. Centralized production in Riyadh's food processing zones is displacing artisanal batch preparation under tightening traceability mandates.
United Arab Emirates
Dubai's hotel and catering supply chains are elevating third-party certified premix sourcing requirements above commodity-grade alternatives. MOHAP and ESMA standardization protocols are tightening documentation requirements for hospitality procurement consortia. Industrial food parks in Abu Dhabi are attracting specification-grade premix distributors with inventory-managed certification continuity programs.
Kuwait
Limited domestic premix manufacturing capacity creates import dependency that specialized Gulf distributors are positioning to capture. The country's national food safety regulator is aligning with Gulf Standards Organization harmonization timelines for cross-border formulation acceptance. Centralized retail and foodservice procurement in Kuwait City is consolidating specification-setting authority away from fragmented independent operators.
Qatar
Hospitality-driven demand from FIFA legacy infrastructure and premium hotel development is elevating specification-grade premix procurement standards. The national health authority is tightening micronutrient labeling requirements for imported fortified food matrices. Industrial food production clusters in Doha are consolidating under centralized procurement models that favor certified premix suppliers with guaranteed halal documentation.
Oman
Food processing industrial zones in Sohar and Salalah are attracting premix distributors serving dairy and bakery fortification programs. The country's standards and metrology organization is implementing GCC-aligned micronutrient maximum-level protocols with phased enforcement calendars. Centralized retail consolidation in Muscat is shifting procurement authority toward distributors offering technical formulation support.
Middle East Food Premix Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Middle East food premix market. Multinational nutrition specialists with encapsulated delivery capabilities occupy premium specification tiers, while regional blenders compete on cost efficiency for commodity-grade volumes. Three archetypes dominate: backward-integrated raw material suppliers, R&D-intensive nutrient delivery specialists, and dairy-protein premix pure-plays. Competitive moves concentrate on halal certification continuity guarantees and inventory-managed distribution partnerships with hospitality procurement consortia.
Among global nutrition specialists, Archer Daniels Midland Company, Koninklijke DSM N.V., and Glanbia PLC exemplify divergent strategic positioning. Archer Daniels Midland represents the backward-integrated archetype with captive vitamin and mineral raw material streams. Koninklijke DSM N.V. anchors the R&D-intensive tier through encapsulated nutrient delivery specialization. Glanbia PLC occupies the dairy-protein premix position aligned with Saudi and UAE fortification programs. These three companies illustrate how technology differentiation, cost discipline, and segment focus create non-overlapping competitive space in Gulf procurement channels.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Koninklijke DSM N.V. |
| Glanbia PLC |
| Prinova Group LLC |
| Hexagon Nutrition Pvt. Ltd |
| Lycored |
| Barentz |
| Fenchem |
| SternVitamin GmbH & Co. |
| Others |
Supply & Pricing Matrix
Manual vitamin scaling in small UAE bakeries and Saudi dairy operations draws procurement away from specification-grade premix suppliers, simultaneously fragmenting demand geography and compressing margin capture for standardized blenders serving artisanal endpoints. This substitution dynamic forces industrial-grade suppliers to defend pricing power through certification bundling while regional blenders absorb volume loss in commodity tiers.
Pricing Analysis
SFDA fortification mandates dictate the pricing tier structure across Gulf premix procurement, separating pharmaceutical-grade encapsulated matrices from commodity vitamin-mineral concentrates. Three-tier pricing stratifies across premium certification-continuous inventory programs, standard halal-compliant bulk formats, and economy-grade manual-blend alternatives. Cost compression in economy tiers intensifies because Chinese feedstock volatility transmits directly into ascorbic acid and B-vitamin precursor costs. Small-scale UAE bakeries exhibit highest price sensitivity; Dubai hospitality procurement consortia demonstrate lowest sensitivity due to specification-locked supply agreements.
Supply Chain Analysis
Strait of Hormuz transit underwrites raw material security for vitamin precursors flowing from Chinese chemical manufacturers to Jeddah and Dubai blending facilities. Concentrated supply rests on feedstock dominance from China for ascorbic acid and B-vitamins, regional blending capacity in Saudi Arabia and UAE, and specialized encapsulation inputs from European technology licensors. Single-source vulnerability concentrates in Chinese vitamin precursor suppliers exposed to export licensing shifts. Distribution runs through Dubai-based inventory-managed programs serving hospitality consortia and direct technical sales channels for Saudi industrial food zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Inventory-managed certification continuity programs represent a service-attach layer expanding faster than premix hardware volumes, as Dubai hospitality groups outsource specification compliance and halal documentation burdens to distributor partners.
For Market Incumbents: Shield margin pools in premium specification tiers by deepening captive supply relationships with Chinese vitamin precursor suppliers and accelerating blockchain traceability system deployment ahead of SFDA enforcement timelines. Channel control through exclusive inventory-managed partnerships with UAE hospitality procurement consortia defends against regional blender price aggression in commodity segments. For New Entrants and Emerging Players: Technical formulation consulting for mid-size Saudi dairy processors lacking in-house micronutrient capability offers a service-layer gap where incumbents under-serve with standardized product catalogs. Kuwait's import-dependent market structure presents the most penetrable geography for specialized Gulf distributors offering GSO-harmonized certification packages. A go-to-market angle anchored in halal biochemistry expertise and rapid stability documentation accelerates customer acquisition against legacy blender response times. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors R&D-intensive nutrient delivery specialists with encapsulated technology platforms and established SFDA compliance track records. Long-term viability over the next decade hinges on regulatory alignment capabilities across divergent Gulf enforcement calendars rather than commodity volume scale. The signal to watch as inflection indicator is GSO harmonization completion timelines and subsequent cross-border formulation friction reduction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Vitamin Precursors | Captive supply of Chinese ascorbic acid and B-vitamin feedstock insulates Gulf blenders from currency fluctuation risk. |
| Encapsulation Technology Licensing | Heat-stable microencapsulation platforms extend shelf life in high-temperature Saudi distribution corridors. |
| Halal Certification Continuity Programs | Inventory-managed documentation bundles capture Dubai hospitality procurement consortium specifications. |
| Blockchain Traceability System Deployment | Batch tracking compliance satisfies tightening SFDA and UAE Ministry documentation mandates. |
| Sports Nutrition Application Development | Protein-fortified recovery beverages target white-space demand beyond traditional infant and dairy segments. |
Research Methodology
A spread of perspectives from premix formulation scientists, Saudi industrial food zone procurement directors, UAE hospitality supply chain managers, and Chinese vitamin precursor trading desks converged on the working assumptions shaping this analysis. Primary interviews with these stakeholders combined with secondary validation against SFDA regulatory filings, GSO harmonization protocols, customs trade data, and SEC disclosures from listed nutrition specialists. Bottom-up volume triangulation across product categories and top-down value reconciliation anchored the market sizing framework.
Segmentation dimensions modeled include product type matrices, application channels, packaging formats, and distribution structures across the projection horizon. CAGRs derived from regression analysis of historical premix procurement patterns and forward elasticity estimates tied to fortification mandate expansion. Industry-specific forecast inputs incorporated SFDA enforcement calendar phasing and UAE hospitality procurement standard evolution.
Forecasts assume regulatory continuity in Saudi SFDA and UAE ESMA regimes; material policy shifts around micronutrient maximum-level thresholds or halal certification integration timelines would require re-modeling. Practitioners should keep alternative scenarios live as GSO harmonization implementation and Chinese export licensing conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Canola Lecithin Market
Flavorings and Food Additives
Shelf-Stable Mezze Fermentation Ingredient Systems Market
Flavorings and Food Additives
Vanilla Extract Market
Flavorings and Food Additives
Italy Food Colorants Market
Flavorings and Food Additives
Chicory Extract Market
Flavorings and Food Additives
Natural Flavors and Fragrances Market
Flavorings and Food Additives
Asia-Pacific Food Colorants Market
Flavorings and Food Additives
Keto Friendly Flavors Market
Flavorings and Food Additives
Lecithin Oleoresin Market
Flavorings and Food Additives
Natural Food Colors and Flavors Market
Flavorings and Food Additives
Orange Terpenes Market
Flavorings and Food Additives
Flavoring Oil Market
Flavorings and Food Additives
Global Natural Food Flavors Market
Flavorings and Food Additives
Russia Food Colorants Market
Flavorings and Food Additives
Liquid Flavors Market
Flavorings and Food Additives
Food Colorants Market