
 Brazil Food Flavor and Enhancer Market | 2026-2036
Brazil Food Flavor and Enhancer Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Food Flavor and Enhancer Market Outlook
Direct procurement from flavor houses to Brazilian food manufacturers is tilting away from traditional distributor intermediaries. Givaudan SA leverages its captive biotechnology labs in Campinas to supply yeast-extract enhancers directly to meat processors. Kerry Group anchors its position through backward integration into dairy-derived flavor precursors at its Minas Gerais facility. International Flavors and Fragrances competes by controlling regional citrus terpene extraction, a raw material bottleneck for natural flavors.
Food flavors and enhancers comprise aromatic compounds, nucleotides, amino acids, and botanical extracts formulated to impart, intensify, or modify taste perception in processed foods, typically dosed at parts-per-million to percent-level concentrations depending on application heat stability requirements. Natural flavors, the largest product type by volume, command premium positioning as ANVISA-aligned clean-label mandates spread through retail channels. Flavor enhancers, led by monosodium glutamate and yeast-derived ribonucleotides, sustain faster growth in instant noodle and savory snack applications where umami intensity reduces sodium dependency. Liquid form dominates beverage applications, while powder form occupies bakery and seasoning blends where shelf stability and dry blending compatibility matter.
ANVISA governs flavor additive approvals through its updated positive list system, while the Ministry of Agriculture's MAPA inspectors enforce Good Manufacturing Practices at production sites, creating dual compliance layers for both domestic and imported formulations. The General Food Law framework and Mercosur harmonization protocols further shape cross-border ingredient trade and labeling obligations. Stakeholders must monitor ANVISA's pending novel food consultation pathways, as accelerated approval mechanisms for fermentation-derived flavors will reshape supplier qualification timelines and capital deployment priorities.
Market Dynamics
ANVISA's compressed approval timelines for fermentation-derived flavor compounds are accelerating supplier qualification cycles and forcing capital redeployment toward biotech-enabled production assets.
Growth Catalysts
- Clean-label mandates:ANVISA-aligned retail labeling requirements are pulling natural flavor volumes into processed meat and poultry applications.
- São Paulo industrial corridor:Multinational processor clustering near Campinas-based ingredient suppliers is shortening formulation-to-production lead times.
- Yeast-extract technology:Ribonucleotide production advances are enabling sodium reduction in instant noodles without taste compromise.
Market Restraints
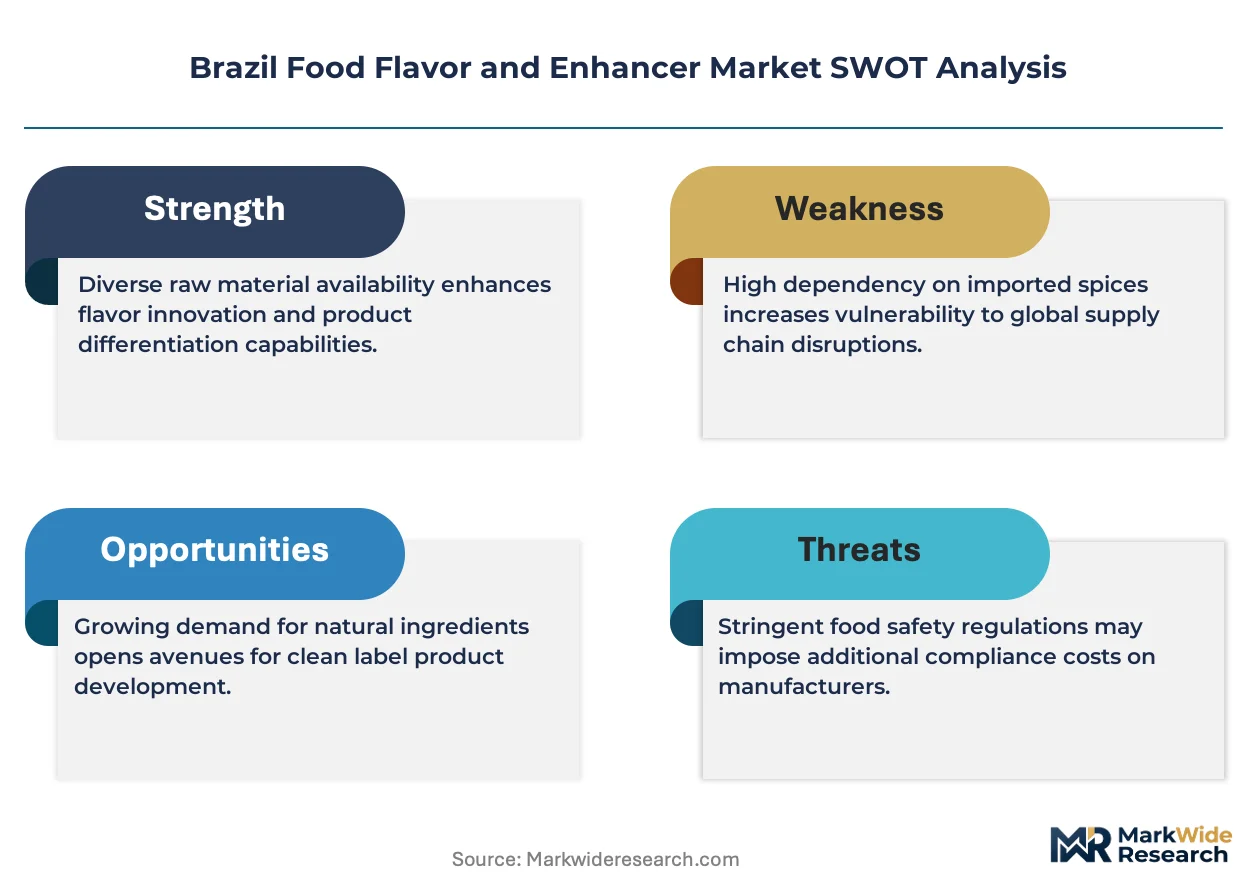
- Citrus terpene supply concentration:Regional extraction bottlenecks for natural flavor precursors create raw material vulnerability.
- Dual compliance burden:ANVISA additive registry alignment with MAPA Good Manufacturing Practice enforcement raises qualification costs for imported formulations.
- Heat stability limitations:Natural flavor volatility under high-temperature processing constrains bakery application expansion.
Strategic Opportunities
- Minas Gerais dairy precursor integration:Backward integration into whey and milk protein hydrolysates offers captive supply security for dairy-derived flavors.
- Mercosur harmonization:Cross-border ingredient trade protocol alignment opens Argentine and Paraguayan processor markets to Brazilian-formulated enhancers.
- Fermentation-derived flavor pathway:ANVISA's pending novel food consultation acceleration creates first-mover advantage for biotech-enabled suppliers.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in heat-stable natural flavor encapsulation remains concentrated among multinational R&D centers.
- Legacy equipment retrofit costs:Powder-to-liquid flexibility requirements in seasoning blend operations demand capital-intensive production line reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Food Flavor and Enhancer Market |
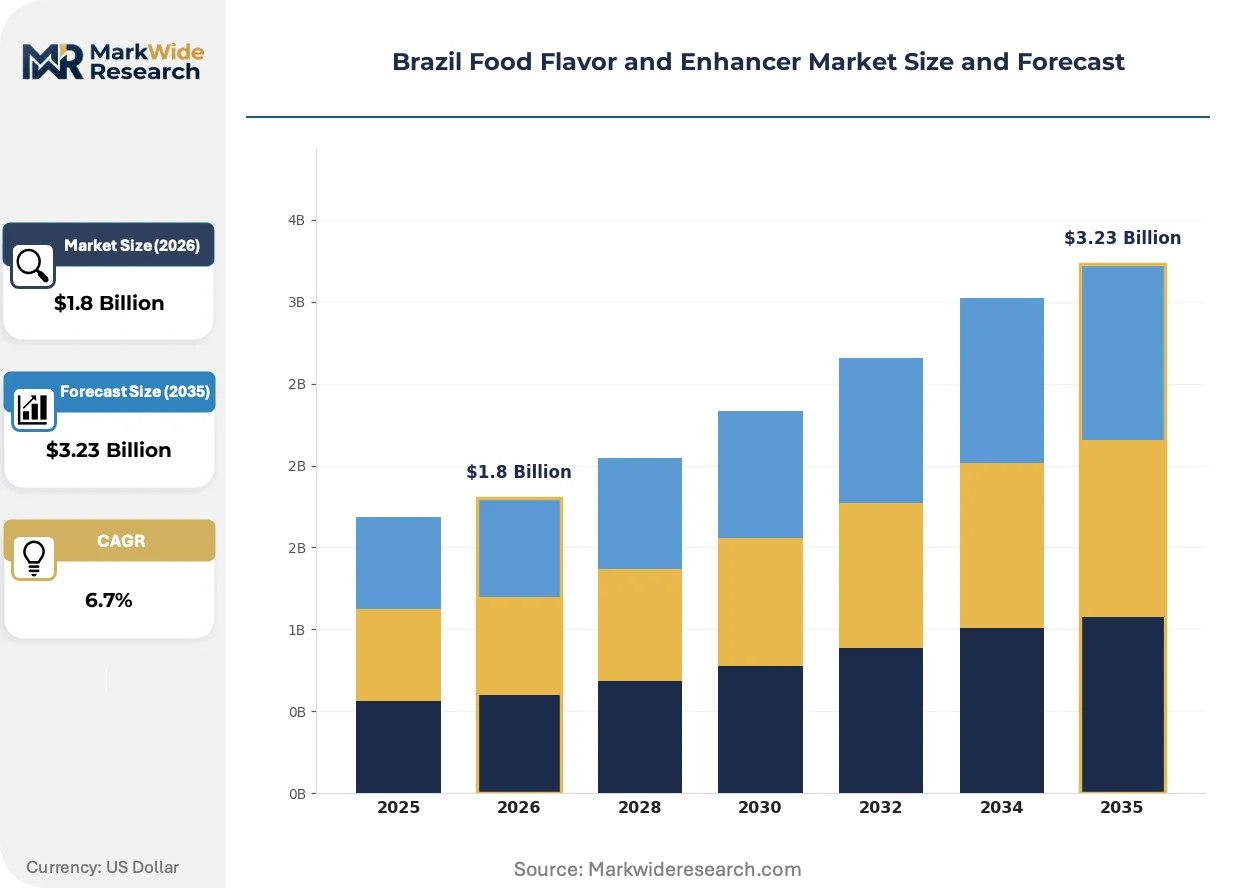
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Flavors, Artificial Flavors, Flavor Enhancers, Seasonings Form: Liquid, Powder, Granular, Paste Application: Bakery, Beverages, Snacks, Sauces Distribution Channel: Online, Retail, Foodservice, Wholesalers |
| Companies Covered | Givaudan SA, Kerry Group, Sensient Technologies Corporation, Firmenich SA, International Flavors and Fragrances, Archer Daniels Midland Company, Corbion NV, BASF SE, Ajinomoto Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Food Flavor and Enhancer Market Strategic Shifts
Biotechnology-enabled flavor production and direct procurement restructuring are compressing traditional supply chain layers while reshaping competitive qualification requirements.
Precision fermentation for terpene and pyrazine production is rendering obsolete conventional solvent extraction methods for citrus and roasted notes. Mid-sized meat processors in São Paulo state's industrial corridor are adopting these biosynthesized alternatives at pilot scale. The technology is rendering obsolete long-standing dependencies on seasonal raw material harvests and volatile commodity pricing.
ANVISA's updated positive list system for food additives is compressing novel compound approval timelines from multi-year cycles to expedited pathways for fermentation-derived substances. This regulatory acceleration is forcing reformulation roadmaps among importers reliant on legacy synthetic flavor portfolios. Clean-label retail mandates are spreading fastest through São Paulo's supermarket channels, pulling compliance investment toward natural certification stacks.
Direct procurement contracts between flavor houses and Brazilian food manufacturers are displacing traditional distributor intermediaries in savory snack and processed meat segments. Givaudan's captive Campinas biotechnology labs exemplify this disintermediation, supplying yeast-extract enhancers straight to processor formulation teams. The pattern is most visible in São Paulo state's industrial corridor, where multinational processors cluster within logistics radius of ingredient innovation centers.
Brazil Food Flavor and Enhancer Market Segmentation
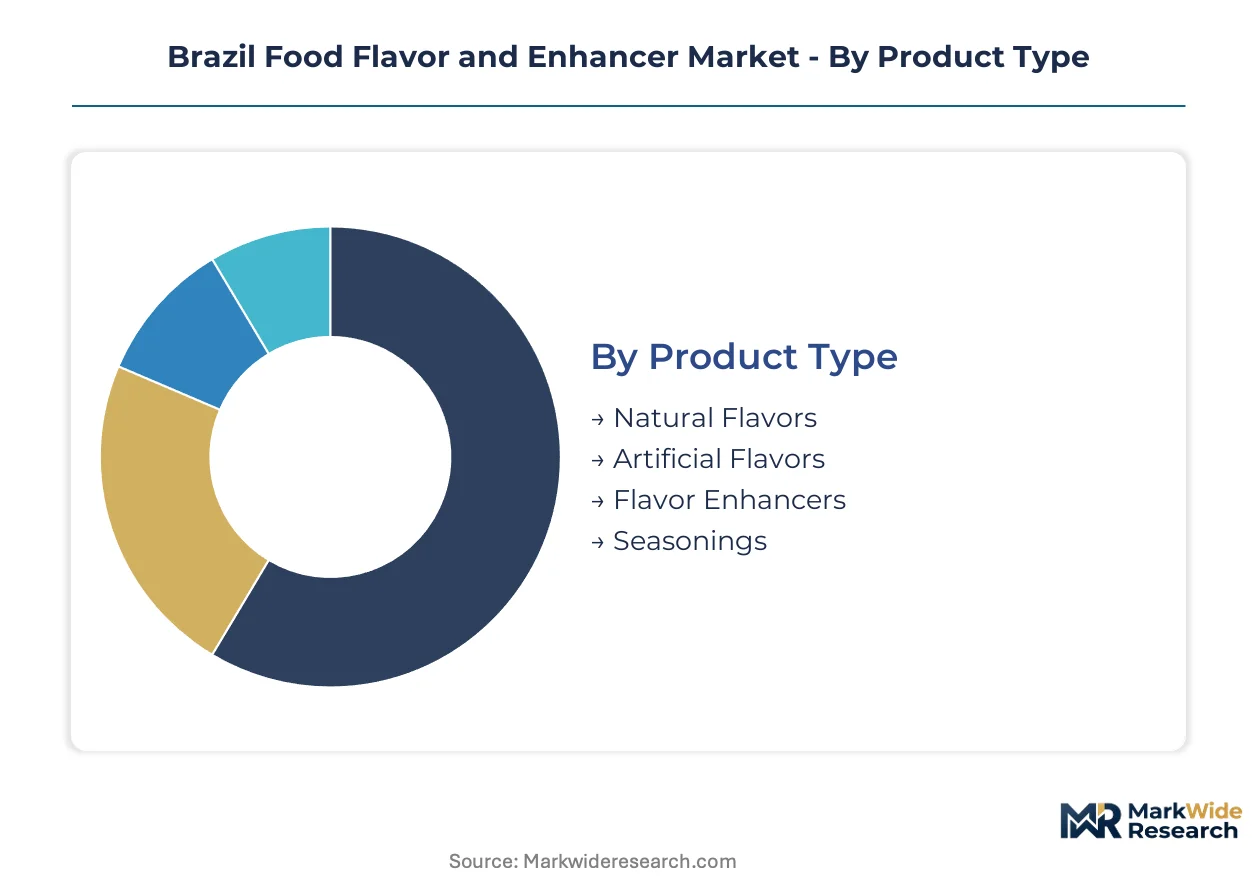
Segmentation in Brazil's food flavor and enhancer market reveals how ANVISA compliance requirements, São Paulo's industrial clustering, and clean-label procurement patterns reshape supplier targeting across product tiers and channel structures. Distinct formulation specifications, heat stability demands, and direct procurement preferences fragment addressable opportunities.
Product Type:
Cost tier stratification separates premium natural certifications from commodity synthetic alternatives, with ANVISA's positive list system determining qualification economics for each tier.
- Natural Flavors:Botanical extracts and essential oils derived from citrus, vanilla, and tropical fruits command premium positioning. São Paulo supermarket chains are pulling these volumes into processed meat applications as clean-label mandates tighten.
- Artificial Flavors:Synthetic aromatic compounds including esters, aldehydes, and ketones offer cost-efficient taste replication. Heat stability advantages sustain bakery application share despite retail labeling headwinds.
- Flavor Enhancers:Monosodium glutamate, disodium inosinate, and yeast-derived ribonucleotides intensify umami perception. Instant noodle processors in Minas Gerais deploy these for sodium reduction without taste compromise.
- Seasonings:Blended spice and herb formulations incorporating both flavor and enhancer functions. Direct procurement contracts are displacing distributor intermediaries for these composite products.
Natural Flavors holds installed capacity. Flavor Enhancers is rotating up the share rankings.
Form:
Application heat requirements and blending compatibility determine form selection, with beverage, bakery, and savory snack processors each demanding distinct physical specifications.
- Liquid:Solvent-based or emulsion formulations optimized for homogeneous dispersion in aqueous systems. Beverage applications concentrate demand in São Paulo state's industrial corridor where multinational processors cluster.
- Powder:Spray-dried or plated carriers ensuring shelf stability and dry blend compatibility. Seasoning blend operations in Brazil's interior states favor this form for logistics efficiency.
- Granular:Agglomerated particles balancing flowability with controlled dissolution. Meat processing applications adopt these for uniform distribution in brine and marinade systems.
- Paste:High-viscosity concentrates delivering intense flavor load in minimal volume. Sauces and condiments segment pulls these formulations for clean-label positioning without synthetic carriers.
Powder maintains the broadest installed base. Liquid is climbing fastest as beverage innovation accelerates.
Application:
End-use heat processing intensity and consumer label scrutiny create divergent formulation requirements across Brazil's major food manufacturing segments.
- Bakery:Heat-stable encapsulated flavors resisting degradation during oven temperatures. Natural volatility constraints limit clean-label penetration in this segment.
- Beverages:Water-soluble profiles with clarity and microbiological stability. São Paulo-based processors drive demand for tropical fruit and citrus terpene formulations.
- Snacks:Surface-applied seasonings with rapid flavor release and adhesion. Yeast-extract enhancers reduce sodium dependency in savory snack portfolios.
- Sauces:Acid-stable and retort-resistant profiles for shelf-stable condiments. Paste form concentrates serve this segment's clean-label reformulation priorities.
Bakery holds legacy volume concentration. Snacks is gaining share fastest on processed food demand expansion.
Distribution Channel:
Customer scale and procurement sophistication determine channel selection, with multinational processors bypassing traditional intermediaries.
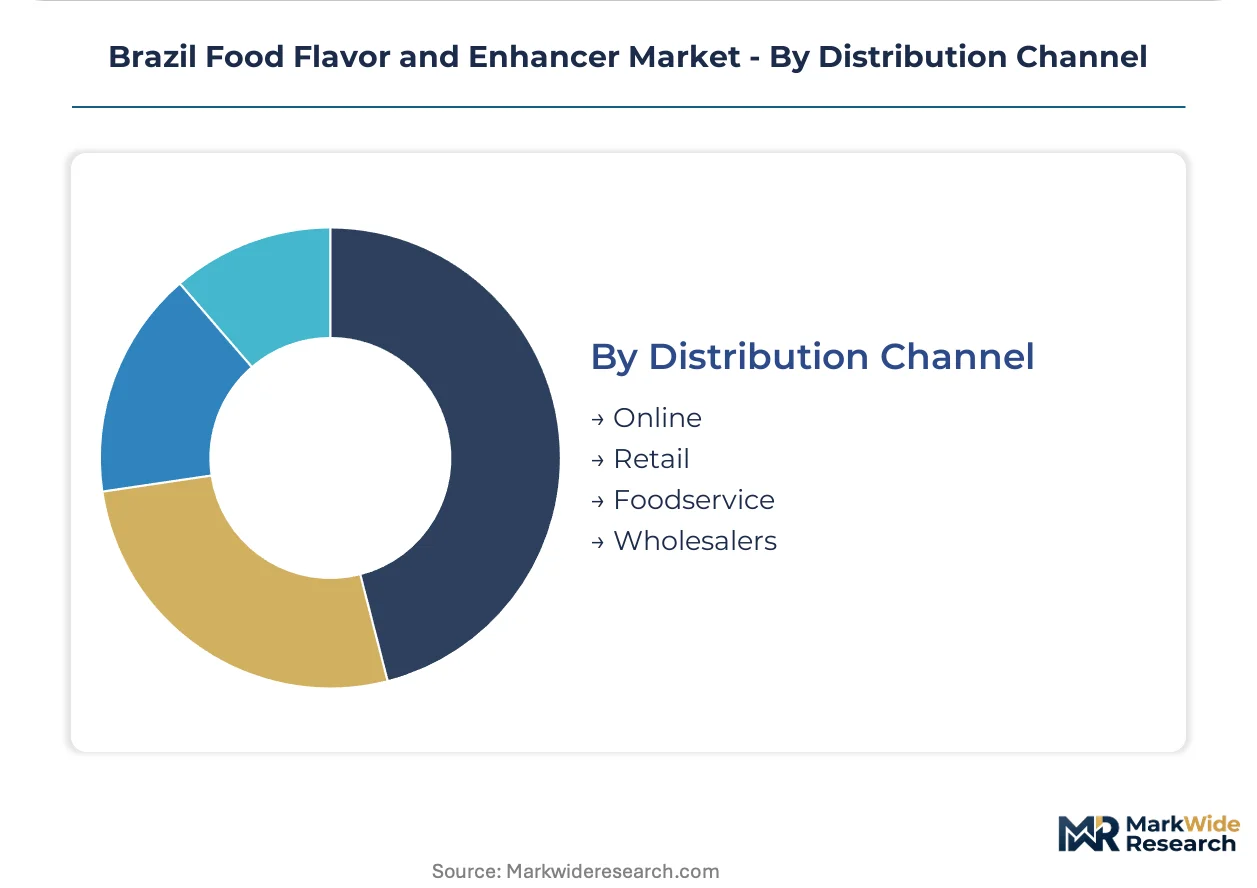
- Online:Digital procurement platforms serving small and mid-sized manufacturers with sample access and technical documentation. Direct-to-formulator relationships are emerging through these channels.
- Retail:Supermarket and hypermarket channels for consumer-facing seasoning and flavor kit products. Clean-label certification visibility drives shelf placement decisions.
- Foodservice:Supply to restaurant chains, institutional caterers, and ready-meal producers. São Paulo's foodservice density concentrates regional demand.
- Wholesalers:Traditional distributor intermediaries serving interior states and smaller processors. Share compression is accelerating as direct procurement expands.
Wholesalers retain interior state coverage. Foodservice is rotating up on chain restaurant expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos, Latin America's largest container gateway, underwrites São Paulo state's dominance in Brazilian food flavor logistics, processing over one-third of national agribulk exports while anchoring ingredient import flows for multinational processors.
São Paulo
Campinas-based biotechnology labs supply yeast-extract enhancers directly to meat processors in the state's industrial corridor. ANVISA's updated positive list system accelerates novel compound approvals for fermentation-derived flavors manufactured here. Multinational processors cluster within logistics radius of these innovation centers, compressing formulation-to-production lead times.
Minas Gerais
Dairy-derived flavor precursor production concentrates at whey and milk protein hydrolysate facilities serving clean-label sauce applications. MAPA inspectors enforce Good Manufacturing Practices at these production sites alongside ANVISA additive registry compliance. Instant noodle processors deploy ribonucleotide enhancers from regional suppliers to achieve sodium reduction targets.
Rio Grande do Sul
Poultry processing volumes pull natural flavor volumes into brine and marinade systems across the state's integrated meat complexes. State environmental regulations govern wastewater discharge from flavor extraction operations. Porto Alegre's food manufacturing base sources encapsulated heat-stable formulations for ready-meal portfolios.
Paraná
Citrus terpene extraction for beverage flavor precursors operates near the state's orange processing belt. MAPA certification requirements apply to botanical extract facilities supplying São Paulo-based beverage manufacturers. Curitiba's logistics hub coordinates cross-border ingredient flows toward Mercosur markets.
Brazil Food Flavor and Enhancer Market Competitive Environment
On the supply side, the industry is consolidating around direct procurement relationships that displace traditional distributor intermediaries. Tiered competitive dynamics separate captive biotechnology operators from commodity synthetic flavor traders. Strategic archetypes include fermentation-enabled specialists, dairy-precursor integrators, and citrus terpene controllers. Dominant competitive moves encompass backward integration into raw material precursors and geographic co-location with processor clusters.
Within the biotechnology-specialist tier, Givaudan SA and Firmenich SA exemplify European-origin flavor houses leveraging regional lab assets for direct supply relationships. Kerry Group represents the integrated nutrition-additive model with captive dairy precursor production. International Flavors and Fragrances occupies a position among terpene supply controllers. These anchors illustrate how qualification timelines and co-location strategies reshape competitive positioning under ANVISA's accelerated approval pathways.
| Leading Market Players |
|---|
| Givaudan SA |
| Kerry Group |
| Sensient Technologies Corporation |
| Firmenich SA |
| International Flavors and Fragrances |
| Archer Daniels Midland Company |
| Corbion NV |
| BASF SE |
| Ajinomoto Group |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in São Paulo state's Campinas biotechnology corridor is concentrating supplier pricing power among fermentation-enabled flavor houses while compressing margins for synthetic compound traders dependent on imported formulations. ANVISA's accelerated approval timelines for novel compounds are reshaping procurement premiums, with direct-contract manufacturers capturing value previously absorbed by distributor intermediaries.
Pricing Analysis
Three-tier pricing structure across premium natural certification, standard clean-label compliance, and economy synthetic grades dominates Brazilian food flavor transactions. Premium tiers command spreads tied to ANVISA-aligned organic and non-GMO verification stacks, while economy synthetic volumes face compression from MAPA enforcement cost pass-throughs. Price differentiation hinges on certification grade and backward integration into dairy or citrus precursor supply. Pricing pressure stems from yeast-extract technology commoditization in instant noodle applications. Mid-sized meat processors exhibit highest price sensitivity; multinational beverage manufacturers demonstrate lowest.
Supply Chain Analysis
Contract-manufacturing concentration rests with Givaudan's Campinas biotechnology labs, Kerry Group's Minas Gerais dairy precursor facilities, and IFF's regional citrus terpene extraction operations. Geographic supply concentration draws from Brazil's São Paulo industrial corridor, Minas Gerais dairy belt, and Paraná citrus processing regions. Raw material dependencies center on citrus terpenes, whey protein hydrolysates, and yeast-derived ribonucleotides. Single-source vulnerability concentrates in regional citrus terpene extraction. Distribution runs through direct procurement contracts displacing traditional wholesaler intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. ANVISA's compressed approval timelines and MAPA dual compliance layers create switching costs that lock processors into qualified supplier relationships.
For Market Incumbents: Pre-empt emerging biotech-enabled entrants by deepening backward integration into Minas Gerais dairy precursor supply and securing captive citrus terpene extraction capacity in Paraná. Accelerate fermentation-derived flavor pipeline submissions through ANVISA's expedited pathways before novel consultation mechanisms mature. Defensive priority rests on locking direct procurement contracts with São Paulo's multinational processor cluster. For New Entrants and Emerging Players: Brazil's interior wholesale-dependent states present the most penetrable white-space for digital procurement platform entry. Target mid-sized seasoning blend operators in Goiás and Mato Grosso lacking direct flavor house relationships. Second white-space target: paste-form clean-label sauce applications underserved by liquid-focused multinational portfolios. Go-to-market angle: sample-access platforms with embedded ANVISA technical documentation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across fermentation-derived flavor manufacturing as precision biotech equipment deployment accelerates. Long-term viability favors suppliers with captive precursor integration and ANVISA pre-qualified compound libraries. Acquisition target archetype: mid-sized Brazilian flavor houses with MAPA-certified facilities and underutilized biotechnology R&D capacity. Signal to watch: ANVISA novel food consultation pathway finalization timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Dairy Precursors | Kerry Group's Minas Gerais whey hydrolysate facility secures captive supply for clean-label sauce applications. |
| Fermentation-Derived Flavor Pipeline Submission | Givaudan's Campinas lab leverages ANVISA expedited pathways to compress novel compound qualification cycles. |
| Direct Procurement Contract Expansion | Multinational processors in São Paulo's industrial corridor bypass wholesaler intermediaries for yeast-extract supply. |
| Citrus Terpene Extraction Capacity Lock | IFF's Paraná operations control regional beverage flavor precursor supply against seasonal commodity volatility. |
| Digital Procurement Platform Launch | Online channels penetrate interior state mid-sized manufacturers lacking direct flavor house technical relationships. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of ANVISA additive registry filings, MAPA Good Manufacturing Practice inspection records, and Mercosur harmonization protocol documentation. Primary interviews engaged formulation chemists at multinational processors, procurement directors at Brazilian meat and snack manufacturers, regulatory affairs specialists navigating ANVISA consultation pathways, and distribution channel managers in São Paulo's industrial corridor. Secondary validation drew from customs trade data, sectoral production statistics, and facility certification databases. Bottom-up volume modeling triangulated against top-down value estimates across natural flavor, synthetic compound, and enhancer product tiers.
Forecast inputs encompass application heat stability requirements, clean-label certification penetration rates, and direct procurement contract adoption curves. Segmentation dimensions modeled include product type tier, physical form specification, end-use application intensity, and distribution channel structure. CAGRs derived from regression analysis of historical volume trajectories adjusted for ANVISA regulatory acceleration effects and São Paulo industrial corridor clustering dynamics. Industry-specific inputs incorporate fermentation technology adoption curves and citrus terpene supply seasonal patterns.
Practitioners should monitor ANVISA novel food consultation pathway finalization, MAPA enforcement intensity shifts, and Mercosur cross-border protocol alignment for early signals requiring forecast revision. Assumptions underlying projections reflect current regulatory trajectories and supplier qualification timelines. Quarterly review of ANVISA approval velocity metrics and Campinas biotechnology corridor capacity utilization indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
China Food Flavor and Enhancer Market
Flavorings and Food Additives
Natural and Organic Flavors Market
Flavorings and Food Additives
Citrus-Based Sugar-Reduction Flavor Modulators Market
Flavorings and Food Additives
France Food Flavor and Enhancer Market
Flavorings and Food Additives
Italy Food Flavor and Enhancer Market
Flavorings and Food Additives
Flavor Compounds Market
Flavorings and Food Additives
North America Flavors and Fragrances Market
Flavorings and Food Additives
Natural Extracts Market
Flavorings and Food Additives
Fiber Syrup Market
Flavorings and Food Additives
Food Flavors & Flavor Enhancers Market
Flavorings and Food Additives
Neotame Market
Flavorings and Food Additives
Salts and Flavored Salts Market
Flavorings and Food Additives
Chicory Extract Market
Flavorings and Food Additives
Citrus Extract Market
Flavorings and Food Additives
Middle East Food Premix Market
Flavorings and Food Additives
Oryzanol Market