
 Asia-Pacific Anti-Caking Market | 2026-2036
Asia-Pacific Anti-Caking Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Anti-Caking Market Outlook
Multi-source procurement among Asian salt and fertilizer processors is recalibrating supplier relationships across the region. BASF SE leverages its integrated silica and silicate production network to secure long-term contracts with Japanese food manufacturers. Evonik Industries AG sustains technology leadership through precipitated silica innovations tailored to tropical humidity conditions. Huber Engineered Materials anchors its position via dedicated mining and processing assets in Southeast Asia.
Anti-caking agents are powdered or granulated additives, typically composed of silica-based compounds, silicates, or carbonate salts, that absorb moisture and reduce interparticle adhesion to preserve free-flowing properties in bulk solids. Manufacturers apply these materials through dry blending, spray coating, or direct compaction at loadings between 0.5% and 2.0% by weight to prevent caking during storage and transport. Among product types, calcium silicate occupies the dominant volume position due to its cost efficiency in fertilizer and salt applications, while sodium bicarbonate is gaining fastest in food industry formulations where pH buffering adds functional value. The application split reveals agriculture as the mature revenue base, whereas pharmaceuticals commands the thickest margin pool because of certification and documentation burdens.
Japan's Ministry of Health, Labour and Welfare enforces stringent specifications under the Food Sanitation Act that limit permissible heavy metal traces in anti-caking additives, directly shaping reformulation priorities for suppliers serving Japanese food manufacturers. China's National Health Commission and India's FSSAI have each issued updated food additive positive lists that restrict unapproved silicate variants, tightening market access for non-compliant imports. Australia's TGA and South Korea's MFDS maintain parallel pharmaceutical-grade standards that drive dual-certification investments among exporters. Stakeholders must monitor divergent national purity thresholds and pre-approval requirements as regulatory fragmentation intensifies compliance costs across the region.
Market Dynamics
India's FSSAI purity tightening for fortified staples is forcing simultaneous reformulation across salt, flour, and milk powder processors, compressing supplier qualification timelines and reshaping procurement hierarchies throughout the region.
Growth Catalysts
- FSSAI Fortification Mandates:India's tightened purity specifications for anti-caking agents in iodized salt and wheat flour are compelling nationwide reformulation, expanding addressable volume for certified-grade suppliers.
- Tropical Humidity Adaptation:Precipitated silica innovations engineered for high-moisture storage conditions are penetrating Southeast Asian fertilizer compounding facilities where seasonal monsoons degrade conventional formulations.
- China's Eastern Coastal Clustering:Salt processing and fertilizer manufacturing concentration across Jiangsu, Shandong, and Zhejiang provinces generates consolidated demand pools that reward scale-capable suppliers with multi-year contract security.
Market Restraints
- Silicate Raw Material Volatility:Diatomaceous earth and sodium silicate feedstock costs fluctuate with energy pricing in China, compressing margin stability for precipitated silica manufacturers serving price-sensitive agricultural buyers.
- Japanese Regulatory Friction:The Ministry of Health, Labour and Welfare's Food Sanitation Act imposes heavy metal trace limits that exclude non-compliant imports, creating a protected domestic supply base resistant to regional price competition.
- Organic Salt Substitution:Premium sea salt and Himalayan rock salt products marketed as additive-free are capturing shelf space in Australian and South Korean retail channels, constraining volume growth in conventional iodized salt anti-caking demand.
Strategic Opportunities
- Vietnam's Fertilizer Expansion:The country's state-led push for domestic urea and NPK capacity is creating first-mover advantage for anti-caking suppliers establishing technical service presence in the Mekong Delta processing corridor.
- Pharmaceutical-Grade Certification Arbitrage:Australia's TGA and South Korea's MFDS parallel standards enable dual-certified producers to command premium pricing across both markets without separate production runs.
- Spray-Drying Integration:Convergence between anti-caking application equipment and continuous spray-drying lines is opening retrofit contracts among ASEAN dairy powder processors seeking single-source equipment-additive packages.
Industry Challenges
- Cross-Border Formulation Harmonization:Divergent national positive lists between China's National Health Commission, India's FSSAI, and Japan's MHLW force multi-SKU inventory strategies that inflate working capital requirements and complicate regional distribution.
- Legacy Salt Facility Retrofit Costs:Mechanized blending and coating equipment upgrades at decades-old government salt works in India and Bangladesh demand capital commitments that strain public-sector procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Anti-Caking Market |
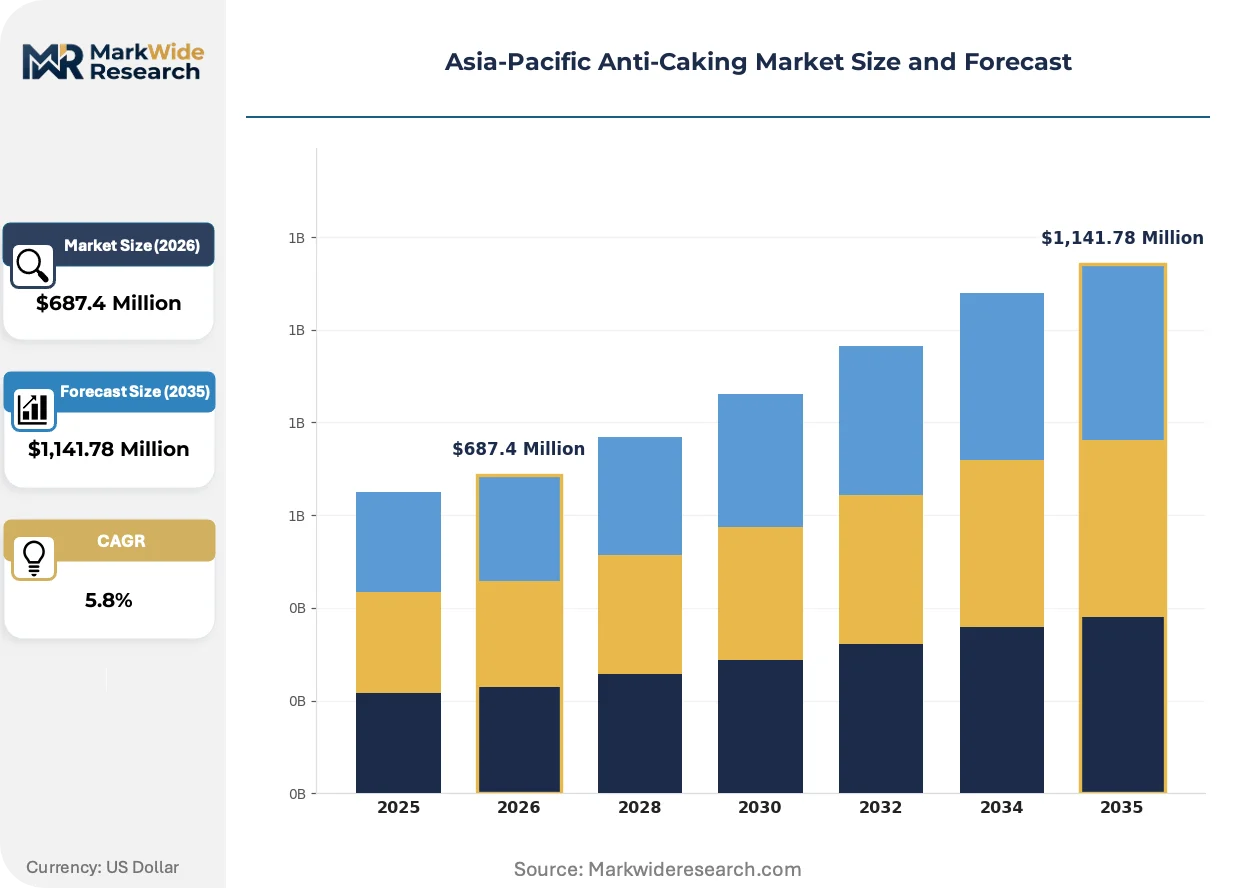
| Market Size in 2026 | $687.4 Million |
| Market Size in 2035 | $1,141.78 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Bicarbonate, Calcium Silicate, Magnesium Carbonate, Talcum Powder Application: Food Industry, Agriculture, Pharmaceuticals, Chemicals End User: Food Manufacturers, Animal Feed Producers, Cosmetic Companies, Chemical Processors Distribution Channel: Direct Sales, Online Retail, Wholesalers, Distributors |
| Companies Covered | BASF SE, Evonik Industries AG, PPG Industries Inc., Huber Engineered Materials, Kao Corporation, Solvay S.A., Cabot Corporation, Brenntag SE, Univar Solutions Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Anti-Caking Market Strategic Shifts
Moisture-responsive formulation technologies and regulatory convergence pressures are compressing product development cycles while elevating documentation burdens across the Asia-Pacific anti-caking supply base.
Encapsulated nano-silica delivery systems are automating precision dosing in high-throughput fertilizer compounding operations. Japanese and South Korean compounders are adopting these systems at pilot scale ahead of ASEAN rollout. The technology is automating quality consistency previously requiring manual batch adjustment, reducing labor intensity in 24-hour production environments.
China's National Health Commission updated food additive positive lists now restrict unapproved silicate variants previously tolerated in gray-market imports. Industrial consequence includes accelerated supplier audits and disqualification of non-compliant Southeast Asian traders. Japanese food manufacturers are responding by tightening incoming inspection protocols and demanding third-party certificates for every silicate lot.
Direct mill-to-processor contracting is displacing traditional distributor intermediaries in Australian salt and fertilizer channels. Bulk end-users in Western Australia's wheat belt and Queensland's cane regions are negotiating additive supply as embedded clauses in primary material purchase agreements. This pattern is most visible where procurement consolidation among cooperative buying groups has achieved sufficient volume leverage to warrant dedicated supplier account management.
Asia-Pacific Anti-Caking Market Segmentation
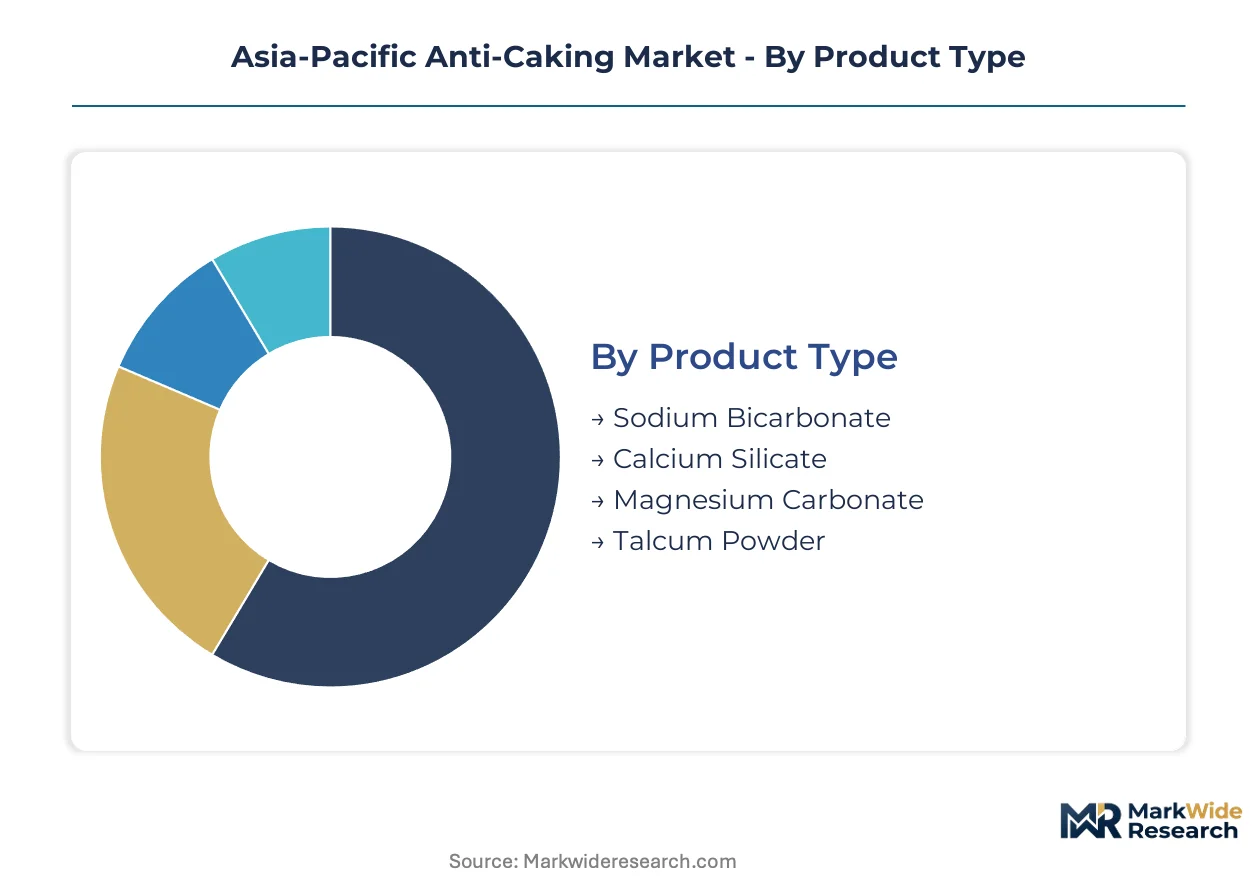
Anti-caking procurement patterns across Asia-Pacific diverge sharply by buyer sophistication and regulatory exposure. Food manufacturers prioritize certification grade over unit cost, while agricultural buyers optimize for moisture absorption performance under tropical storage conditions.
Product Type:
Cost tier determines supplier qualification depth and contract structure across the region.
- Calcium Silicate:A porous, synthetic silicate compound manufactured through controlled reaction of lime and silica. Demand concentrates in China's Jiangsu and Shandong fertilizer compounding corridors where bulk urea processors require cost-efficient flow assurance for monsoon-season distribution.
- Sodium Bicarbonate:A water-soluble alkali salt with inherent pH buffering capacity. India's FSSAI-mandated reformulation of iodized salt and wheat flour is accelerating procurement of food-grade material from certified domestic producers.
- Magnesium Carbonate:Lightweight carbonate salt with high oil absorption capacity, serving niche cosmetic and pharmaceutical applications in Japan and South Korea.
- Talcum Powder:Naturally occurring hydrated magnesium silicate, deployed primarily in animal feed pelleting operations across Vietnam and Thailand.
Volume sits with calcium silicate; growth tilts toward sodium bicarbonate.
Application:
Margin structure varies dramatically by documentation burden and certification pathway complexity.
- Food Industry:Salt, milk powder, and seasoning manufacturers across China and India absorb premium pricing for FSSAI- and National Health Commission-compliant grades. Reformulation timelines compress supplier switching costs.
- Agriculture:Fertilizer compounders in Indonesia and Malaysia prioritize moisture-responsive silica formulations for high-humidity storage resilience.
- Pharmaceuticals:Australia's TGA and South Korea's MFDS impose parallel heavy metal and microbial specifications, enabling dual-certified producers to extract premium positioning.
- Chemicals:Industrial salt and detergent intermediate processors in Thailand and Philippines drive commoditized bulk demand with price-sensitive tender structures.
Revenue concentrates in agriculture; steepest expansion trajectory emerges in pharmaceuticals.
End User:
Procurement centralization levels determine channel strategy and account management intensity.
- Food Manufacturers:National salt works and dairy cooperatives in India and Bangladesh consolidate additive purchasing through multi-year framework agreements.
- Animal Feed Producers:Southeast Asian integrated livestock operations embed anti-caking supply within vitamin and mineral premix procurement bundles.
- Cosmetic Companies:Japanese and South Korean personal care formulators demand sub-micron particle specifications with batch-level heavy metal certificates.
- Chemical Processors:Chlor-alkali and soda ash manufacturers in China negotiate silicate supply as captive inputs within integrated production economics.
Transaction volume dominates food manufacturing; cosmetic segment commands highest unit margin realization.
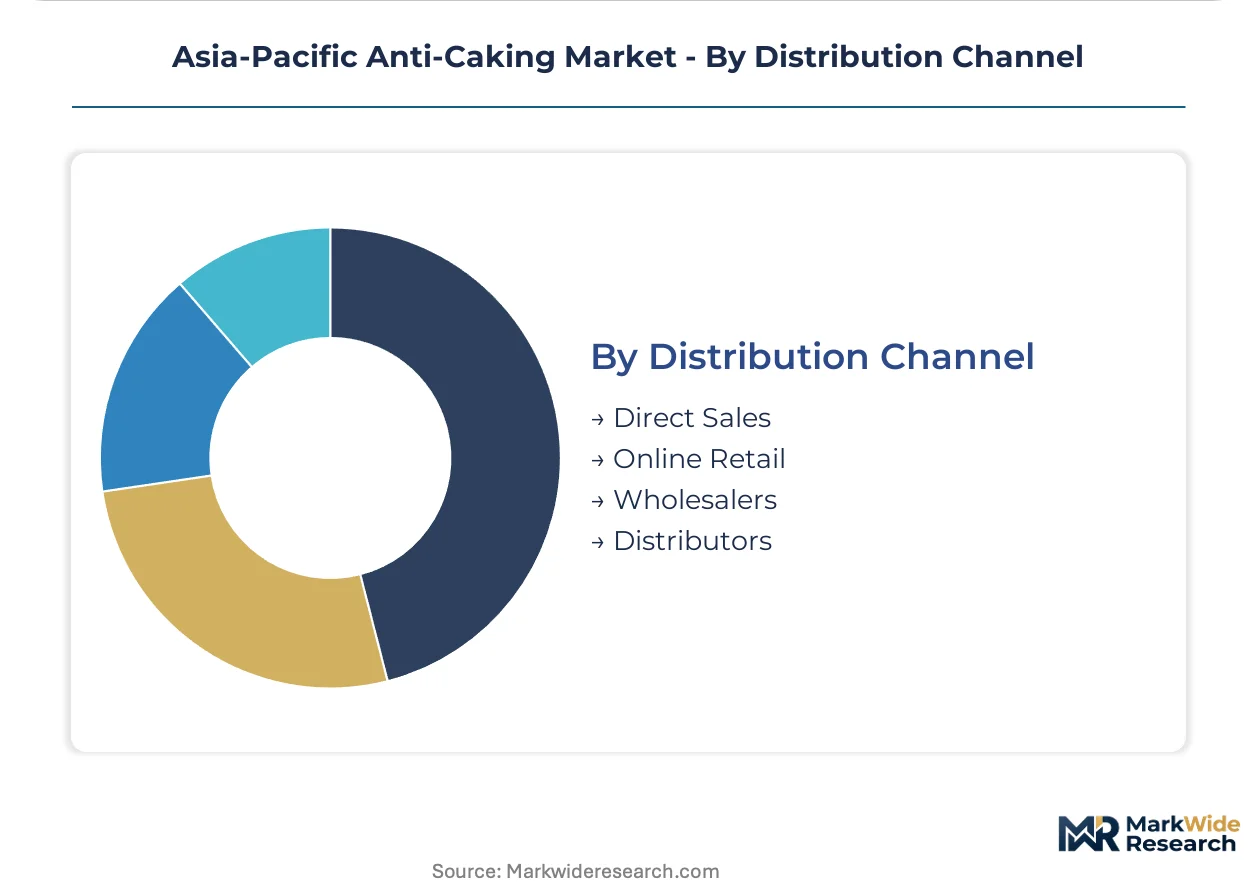
Distribution Channel:
Supply chain configuration determines working capital requirements and technical service proximity.
- Direct Sales:BASF SE and Evonik Industries AG deploy technical sales teams to anchor multi-year contracts with Japanese food manufacturers and Australian fertilizer cooperatives.
- Distributors:Regional chemical traders across Southeast Asia maintain inventory positions for mid-tier agricultural compounders requiring rapid delivery flexibility.
- Wholesalers:Bulk salt processors in India's Gujarat and Tamil Nadu source through government-mandated procurement channels with price-controlled tender mechanisms.
- Online Retail:Specialty chemical platforms serve small-scale cosmetic and pharmaceutical formulators in South Korea with certified-grade material in sub-ton quantities.
Contract value concentrates in direct sales; channel expansion accelerates through distributor technical service investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diatomaceous earth deposits in China's Shandong and Jilin provinces anchor regional silicate feedstock supply, while sodium silicate manufacturing clusters across the Yangtze River Delta feed downstream anti-caking production. Procurement patterns diverge sharply between tropical Southeast Asian fertilizer processors and East Asian food manufacturers facing stringent metal-trace regulations.
China
Jiangsu and Shandong provinces host concentrated salt processing and fertilizer compounding facilities demanding calcium silicate at bulk scale. The National Health Commission's updated food additive positive lists now exclude unapproved silicate variants, accelerating supplier audits and disqualifying non-compliant traders. Qingdao and Tianjin ports serve as primary import gateways for certified-grade material serving eastern coastal manufacturing clusters.
India
FSSAI-mandated reformulation of iodized salt and wheat flour is expanding procurement of certified sodium bicarbonate from domestic producers. Gujarat and Tamil Nadu salt works consolidate additive purchasing through government-mandated tender mechanisms with price-controlled structures. Mumbai and Ahmedabad serve as distribution hubs connecting certified suppliers with national food manufacturers.
Japan
The Ministry of Health, Labour and Welfare enforces heavy metal trace limits under the Food Sanitation Act that exclude non-compliant imports. Kanto region food manufacturers prioritize certification grade over unit cost, contracting directly with technical service-equipped suppliers. Osaka-based compounders demand batch-level documentation for every silicate lot entering production.
Australia
TGA pharmaceutical-grade standards drive dual-certification investments among exporters serving both Australian and South Korean markets. Western Australia's wheat belt and Queensland's cane regions negotiate additive supply as embedded clauses in primary material purchase agreements. Direct mill-to-processor contracting is displacing traditional distributor intermediaries in bulk agricultural channels.
Vietnam
State-led expansion of domestic urea and NPK capacity is creating first-mover opportunity for suppliers establishing technical service presence in the Mekong Delta processing corridor. Seasonal monsoons degrade conventional formulations, driving demand for moisture-responsive silica innovations. Ho Chi Minh City serves as the commercial gateway for fertilizer additive distribution throughout the delta region.
Asia-Pacific Anti-Caking Market Competitive Environment
Global majors compete with regional champions across certification depth and tropical formulation expertise. Market structure tilts toward consolidated supply at the certified-grade tier while fragmenting across agricultural commodity segments. Three archetypes dominate: integrated chemical conglomerates with captive silicate networks, specialty silica innovators with humidity-responsive portfolios, and mining-anchored processors with Southeast Asian asset bases. Competitive moves center on multi-year contract security with Japanese food manufacturers and technical service investments in Vietnamese fertilizer corridors.
Within the integrated chemical tier, BASF SE and Evonik Industries AG exemplify divergent strategic positioning. BASF leverages its production network to anchor long-term contracts with certification-demanding buyers. Evonik occupies a position emphasizing precipitated silica innovations engineered for tropical storage conditions. Huber Engineered Materials represents the mining-anchored archetype through dedicated Southeast Asian processing assets.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| PPG Industries Inc. |
| Huber Engineered Materials |
| Kao Corporation |
| Solvay S.A. |
| Cabot Corporation |
| Brenntag SE |
| Univar Solutions Inc. |
| Others |
Value Chain & Pricing Dynamics
Diatomaceous earth feedstock indices from China's Shandong and Jilin provinces cascade through sodium silicate manufacturing clusters across the Yangtze River Delta, compressing margin buffers for precipitated silica producers and forcing three-tier pricing stratification across premium pharmaceutical-grade, standard food-grade, and economy agricultural-grade tiers.
Pricing Analysis
Technical service bundling separates contract structures in this market, with Japanese food manufacturers paying premiums for batch-level documentation and on-site formulation support while Southeast Asian fertilizer compounders negotiate unbundled material-only terms. Certification grade and volume scale drive price differentiation, with FSSAI-compliant sodium bicarbonate commanding substantial premiums over standard agricultural calcium silicate. Cost compression in the economy tier is intensifying because of energy-linked raw material volatility in Chinese silicate feedstock. Agricultural buyers in Indonesia and Vietnam exhibit highest price sensitivity, whereas Japanese pharmaceutical formulators demonstrate least sensitivity due to regulatory substitution constraints.
Supply Chain Analysis
Direct-to-processor channels handle hyperscale demand from China's Jiangsu and Shandong salt processing clusters, while distributor networks serve mid-tier ASEAN agricultural compounders requiring rapid delivery flexibility. Supply concentration rests on China for diatomaceous earth and sodium silicate feedstock, India for domestic sodium bicarbonate production, and Japan for specialized pharmaceutical-grade silica processing. Raw material dependencies include diatomaceous earth deposits, sodium silicate manufacturing output, and lime derivatives for calcium silicate synthesis. Single-source vulnerability from China's Shandong-Jilin deposit concentration creates structural exposure to regional energy pricing shocks. Distribution runs through Qingdao and Tianjin port gateways for certified-grade imports, with Ho Chi Minh City anchoring Mekong Delta fertilizer additive flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where India's FSSAI purity tightening for fortified staples constructs a formidable barrier-to-entry moat, advantaging certified-grade suppliers with established domestic production footprints over import-dependent traders facing disqualification risk.
For Market Incumbents: Extend certification depth through dual TGA-MFDS pharmaceutical-grade positioning to capture premium pricing arbitrage across Australia and South Korea. Deepen captive silicate supply through backward integration into Southeast Asian diatomaceous earth processing assets, defending against margin compression from Chinese feedstock volatility. Channel control investments in Vietnamese technical service infrastructure preempt state-led fertilizer capacity expansion. For New Entrants and Emerging Players: Begin with Vietnam's Mekong Delta fertilizer corridor, where state-led urea and NPK expansion creates first-mover whitespace for moisture-responsive silica formulations ahead of incumbent technical service deployment. Target spray-drying integration packages among ASEAN dairy powder processors seeking single-source equipment-additive procurement consolidation. Go-to-market leverage rests on embedded equipment retrofit contracts rather than standalone additive supply. For Investors and Strategic Acquirers: Distressed-cycle entries favor mining-anchored processors with Southeast Asian asset bases and established National Health Commission supplier qualifications, positioned to consolidate fragmented agricultural-grade supply as Chinese feedstock volatility strains pure-play precipitated silica manufacturers. Long-term viability hinges on regulatory certification durability rather than commodity volume scale. Watch FSSAI enforcement intensity against gray-market silicate imports as inflection signal for certified-grade margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicate Feedstock | Captive diatomaceous earth supply from Shandong-Jilin deposits insulates margin stability against energy-linked raw material volatility. |
| Dual Pharmaceutical-Grade Certification | TGA-MFDS parallel standards enable premium pricing extraction across Australian and South Korean markets without separate production runs. |
| Technical Service Presence in Vietnamese Fertilizer Corridor | State-led Mekong Delta capacity expansion rewards first-mover suppliers with multi-year contract anchoring before competitor infrastructure deployment. |
| Spray-Drying Equipment Integration | Convergence with continuous processing lines opens retrofit contracts among ASEAN dairy powder manufacturers seeking consolidated procurement. |
| Moisture-Responsive Formulation Development | Tropical humidity adaptation penetrates Southeast Asian fertilizer compounding facilities where seasonal monsoons degrade conventional silica formulations. |
Study Parameters
Multi-period observation of FSSAI enforcement patterns, National Health Commission positive list updates, and Japanese Food Sanitation Act compliance audit frequencies anchored the trend analysis, supplemented by interviews with plant managers at Chinese fertilizer compounding facilities, procurement leads at Indian salt works, regulatory affairs directors at Japanese food manufacturers, and distribution channel partners across Southeast Asia. Secondary validation drew from customs and trade data, China GB standards filings, FSSAI gazette notifications, and SEC 10-K disclosures from listed chemical conglomerates. Bottom-up volume triangulation across grade-tier and application segments converged with top-down macroeconomic elasticity modeling.
Input-output matrices mapped silicate feedstock availability through sodium silicate manufacturing capacity to downstream anti-caking formulation output across the projection horizon. Segmentation dimensions modeled include product type tier, application industry, certification grade, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand projections and supply-side capacity expansion schedules. Industry-specific forecast inputs incorporated monsoon seasonality patterns affecting Southeast Asian fertilizer storage conditions and FSSAI reformulation timeline compliance rates.
Underlying measurement precision varies by segment; pharmaceutical-grade certification data carries tighter precision than agricultural commodity flows where gray-market activity distorts reported volumes. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and feedstock energy pricing correlation. Periodic stress-testing of base assumptions against FSSAI audit intensity and Chinese environmental policy shifts is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Flavophospholipol Market
Food Additives and Ingredients
Fruit Ripening Agents Market
Food Additives and Ingredients
Alcohol Additives Market
Food Additives and Ingredients
UK Food Enzymes Market
Food Additives and Ingredients
Africa Microbial Food Culture Market
Food Additives and Ingredients
Europe Food Enzymes Market
Food Additives and Ingredients
Global Food Bulking Agents Market
Food Additives and Ingredients
Resistant Dextrin Market
Food Additives and Ingredients
Sodium Propionate Market
Food Additives and Ingredients
Filling Fat Market
Food Additives and Ingredients
India Food Color Industry Market
Food Additives and Ingredients
Natural Ferulic Acid Market
Food Additives and Ingredients
Beverage Clouding Agent Market
Food Additives and Ingredients
Africa Food Emulsifiers Market
Food Additives and Ingredients
Argentina Food Emulsifiers Market
Food Additives and Ingredients
Tapioca Starch Market