
 Taste Modulators Market | 2026-2036
Taste Modulators Market Size, Share, and Industry Trends Forecast 2026-2036
Taste Modulators Market Intelligence
Ingredient distribution through flavor houses is fragmenting as direct procurement links between modulator suppliers and finished goods manufacturers multiply. DSM-Firmenich leverages its integrated biotechnology platform to sustain captive yeast-derived sweetener output. Givaudan anchors European demand through specialized bitterness blocker portfolios for reduced-sugar confectionery. Cargill Incorporated competes on agricultural input control, extending its corn-derived polyol chain into modulator precursors.
Taste modulators comprise functional ingredients that interact with human gustatory receptors to amplify, suppress, or modify perceived flavor intensity without contributing substantial caloric or nutritional load; these compounds typically operate at parts-per-million thresholds through receptor agonism, antagonism, or allosteric modulation mechanisms. Their primary commercial purpose centers on enabling reformulation of processed foods, beverages, and nutraceuticals to meet clean-label, reduced-sodium, or sugar-reduction objectives while preserving consumer acceptability. Sweeteners and bitterness blockers command the dominant share of current formulation spend, reflecting mature beverage and confectionery demand, while umami enhancers represent the fastest-expanding category as plant-based protein applications multiply. Powder and granule forms occupy the bulk of industrial procurement channels due to handling efficiency, though liquid formats are gaining traction in high-speed beverage lines where dosing precision governs batch consistency.
FDA's GRAS notification framework and EFSA's novel food ingredient assessments jointly govern market access timelines for new modulator chemistries, with compliance costs diverging sharply across Atlantic filing pathways. The EU Green Deal's Farm to Fork strategy is tightening permissible additive thresholds, while India's FSSAI is accelerating local safety reviews for imported bitterness blockers under revised food additive schedules. Stakeholders must monitor evolving receptor-targeting claims language, as regulatory bodies on both sides of the Atlantic are scrutinizing structure-function positioning that borders on therapeutic indication territory.
Market Dynamics
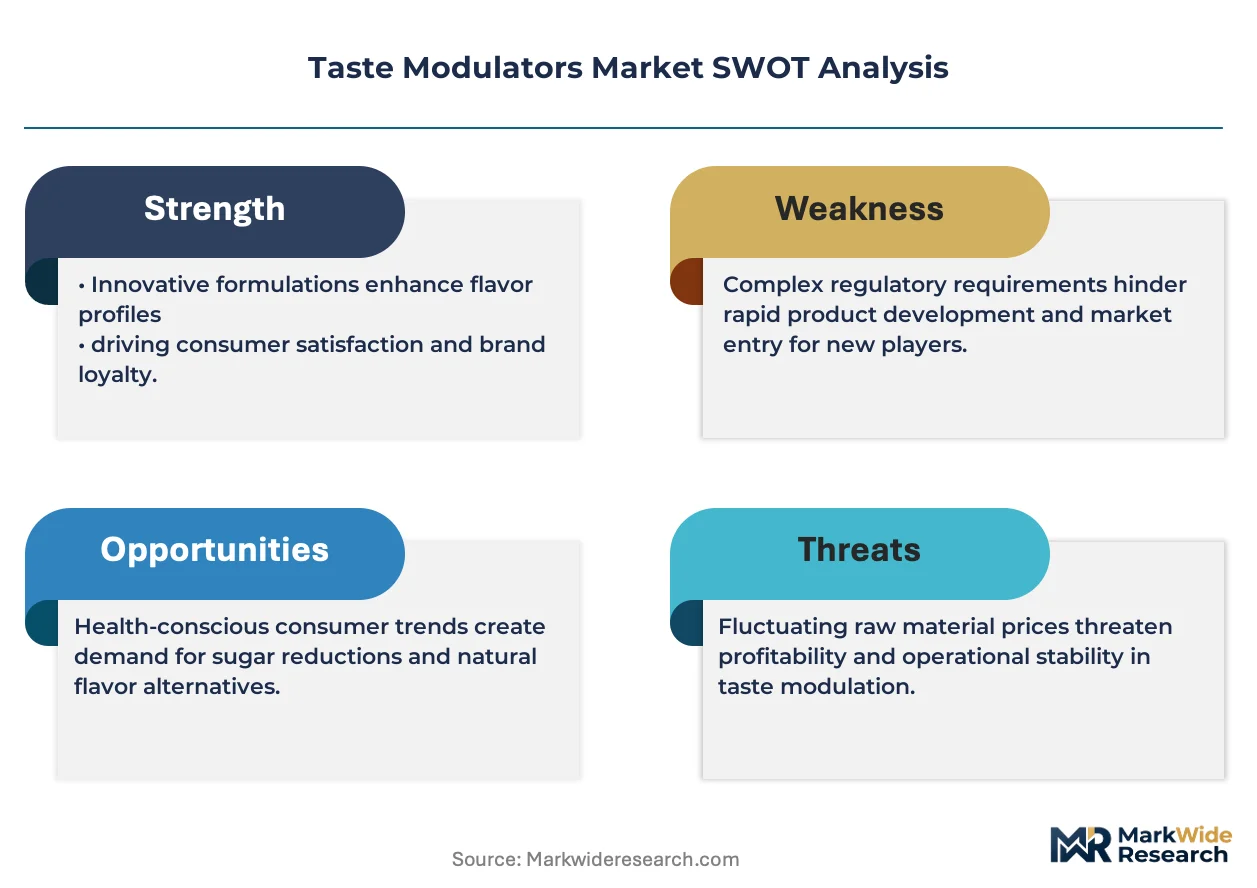
The FDA's updated guidance on novel food ingredients is compressing approval timelines for new modulator chemistries while simultaneously elevating compliance burdens, forcing suppliers to restructure their regulatory filing strategies and regional market entry sequencing.
Growth Catalysts
- EFSA clean-label mandates:European Food Safety Authority formulation requirements are accelerating bitterness blocker trials across German beverage manufacturing facilities.
- Yeast-derived sweetener biotechnology:Precision fermentation platforms are expanding output volumes of high-potency sweetness modulators without agricultural feedstock dependency.
- Plant-based protein proliferation:Umami enhancer demand is multiplying as meat alternative formulations require flavor masking and mouthfeel restoration.
Market Restraints
- Corn price volatility:Agricultural input fluctuations compress margins for polyol-derived modulator precursors sourced from Midwestern US supply basins.
- Receptor specificity limitations:Current bitterness blockers exhibit incomplete target selectivity, leaving residual off-notes in high-cocoa confectionery applications.
- GRAS notification friction:FDA's expanded safety data requirements for novel chemistries are extending US market access timelines by 18-24 months.
Strategic Opportunities
- India FSSAI schedule expansion:Revised food additive classifications are opening import pathways for bitterness blockers previously excluded from domestic formulation.
- Liquid format beverage integration:High-speed dosing systems are creating technical specifications that favor precision liquid modulator delivery over powder handling.
- EU Green Deal additive thresholds:Tightening permissible limits are mandating reformulation across existing product portfolios, generating replacement demand.
Industry Challenges
- Gustatory receptor pharmacology expertise scarcity:Formulation teams lack sufficient molecular biology depth to optimize allosteric modulation mechanisms.
- Multi-jurisdiction filing complexity:Divergent EFSA and FDA evidentiary standards force parallel track development, duplicating toxicology study expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taste Modulators Market |
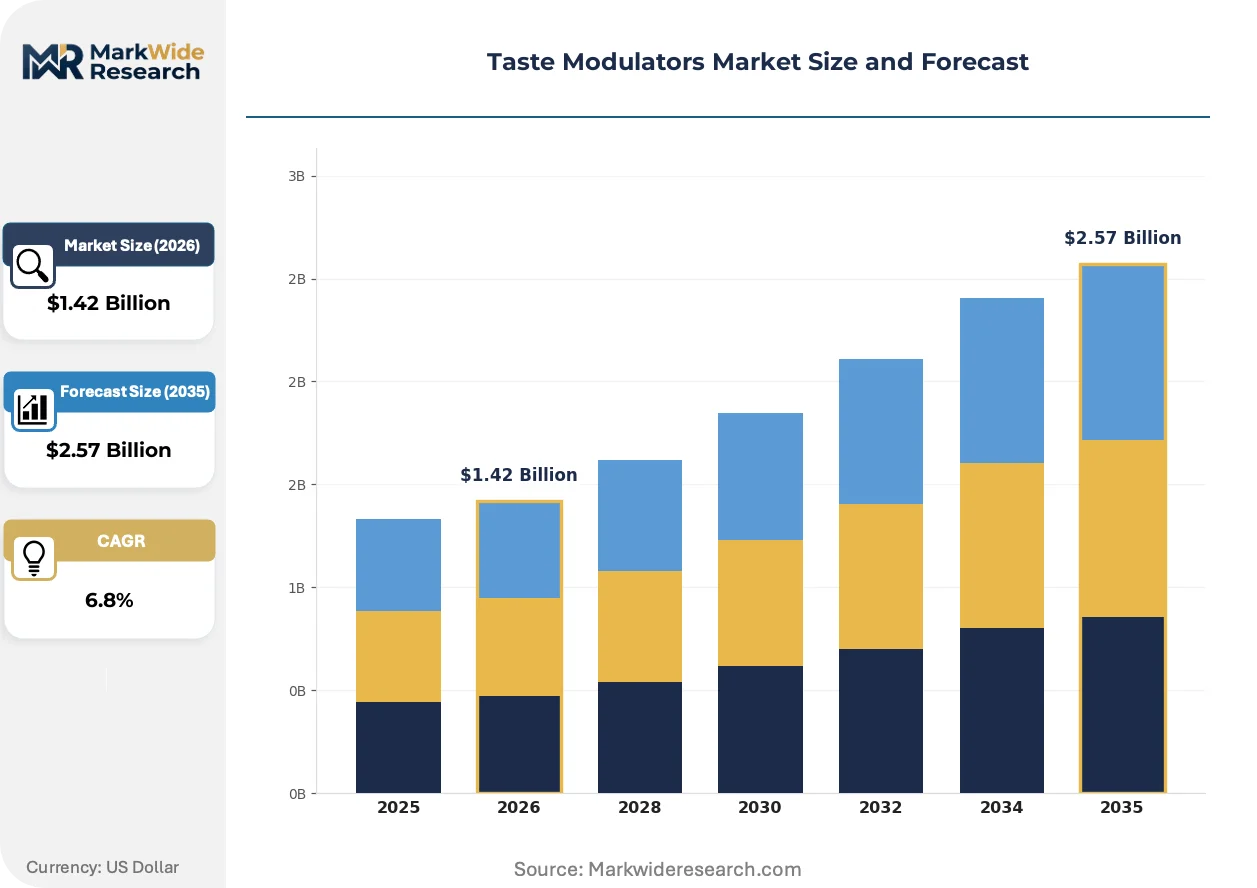
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sweeteners, Bitterness Blockers, Salt Enhancers, Sour Maskers, Umami Enhancers Form: Liquid, Powder, Granules, Tablets, Capsules Application: Beverages, Confectionery, Dairy Alternatives, Functional Foods, Personal Care End User: Food & Beverage Manufacturers, Nutraceutical Firms, Flavor Houses, Cosmetic Producers |
| Companies Covered | DSM-Firmenich, Symrise AG, Givaudan, Sensient Technologies Corporation, Cargill Incorporated, International Flavors & Fragrances Inc., Ingredion Incorporated, Tate & Lyle PLC, Kerry Group plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taste Modulators Market Strategic Shifts & Innovations
Biotechnology platforms are displacing traditional extraction-based production, while regulatory bodies on both sides of the Atlantic are tightening structure-function claim scrutiny. These forces are compressing the competitive set toward integrated discovery-to-delivery capabilities.
Precision fermentation of yeast-derived sweeteners is rendering obsolete agricultural cultivation dependencies for high-potency modulators. Beverage manufacturers in Germany and the Netherlands are adopting these biotech inputs at accelerating rates. This shift is compressing price premiums for traditionally sourced sweetness modulators while elevating technical barriers to entry.
EFSA's novel food ingredient assessment framework is tightening evidentiary requirements for receptor-targeting claims. Industrial consequence includes mandatory pre-market safety dossiers that extend European launch timelines. Bitterness blocker portfolios face the highest scrutiny, with suppliers restructuring clinical endpoints to avoid therapeutic indication territory.
Direct procurement links between modulator suppliers and finished goods manufacturers are fragmenting traditional flavor house distribution channels. Large beverage and confectionery producers are establishing captive supply relationships, displacing intermediary markup structures. This pattern concentrates most visibly in German and US formulation facilities where volume scale justifies dedicated technical service teams.
Taste Modulators Market Segmentation
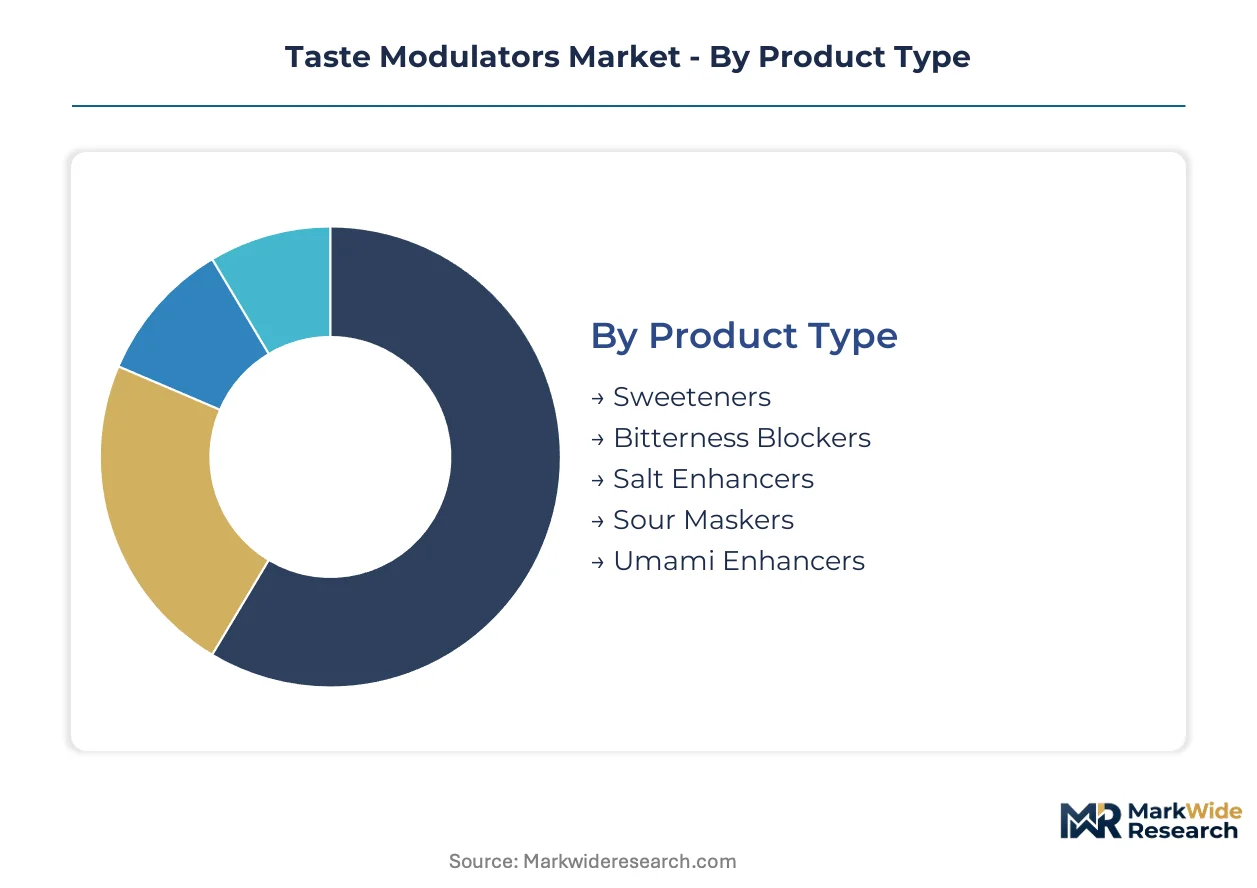
Taste modulators serve divergent technical requirements across formulation contexts. Segmentation reveals how receptor-targeting specificity, physical handling constraints, and end-use performance standards shape procurement decisions and supplier positioning.
Product Type:
Mature sweetener platforms coexist with emerging umami technologies across the functional spectrum.
- Sweeteners:High-potency compounds interact with T1R2/T1R3 heterodimer receptors to amplify perceived sweetness without caloric contribution. Beverage manufacturers in Germany and the Netherlands are adopting yeast-derived variants at accelerating rates as precision fermentation displaces agricultural extraction.
- Bitterness Blockers:T2R receptor antagonists suppress aversive taste responses in reduced-sugar confectionery and high-cocoa applications. EFSA's novel food ingredient assessments are extending European launch timelines for new chemistries as regulators scrutinize structure-function claims.
- Salt Enhancers:ENaC channel modulators amplify sodium perception to enable sodium reduction in savory formulations.
- Sour Maskers:Proton-sensitive receptor blockers reduce acidic bite in low-pH beverage systems.
- Umami Enhancers:T1R1/T1R3 agonists restore savory depth in plant-based protein matrices where fermentation-derived off-notes dominate.
Sweeteners retain volume leadership; umami enhancers hold the steepest expansion curve.
Form:
Physical format selection hinges on dosing precision requirements and line speed constraints.
- Powder:Free-flowing particulate systems dominate industrial procurement channels due to handling efficiency and extended shelf stability. Dry-blend compatibility makes this the default specification for bakery and confectionery compounders.
- Liquid:Aqueous or solvent-based solutions enable micro-dosing accuracy in high-speed beverage lines where batch consistency governs quality control. German and Dutch facilities are retrofitting liquid dosing systems at accelerating rates.
- Granules:Agglomerated particles reduce dust generation and improve flowability for manual addition processes.
- Tablets:Compressed unit doses serve nutraceutical applications requiring precise single-serving measurement.
- Capsules:Encapsulated formats protect volatile actives from moisture and oxidation in extended distribution chains.
Powder retains volume leadership; liquid holds the steepest expansion curve.
Application:
End-use diversification reflects divergent sensory performance thresholds and label positioning strategies.
- Beverages:Carbonated and still drink formulations demand rapid dissolution and clean taste profiles without lingering aftertaste. Sugar-reduction mandates from EFSA and FDA are concentrating procurement spend on sweetness modulators and bitterness blockers.
- Confectionery:Chocolate and sugar-based applications require thermal stability and compatibility with cocoa butter matrices. Incomplete receptor selectivity in current bitterness blockers leaves residual off-notes in high-cocoa formulations.
- Dairy Alternatives:Oat, soy, and almond bases mask beany or grassy off-notes while restoring creamy mouthfeel.
- Functional Foods:Nutraceutical delivery systems balance active ingredient masking with health-positioning requirements.
- Personal Care:Oral care and cosmetic applications leverage taste modulation for palatability without ingestion safety concerns.
Beverages retain volume leadership; dairy alternatives hold the steepest expansion curve.
End User:
Customer type determines technical service intensity and supply relationship structure.
- Food & Beverage Manufacturers:Large-scale producers are establishing direct procurement links with modulator suppliers, displacing traditional flavor house intermediaries. German and US facilities with sufficient volume scale now demand dedicated technical service teams.
- Flavor Houses:Traditional distribution channels face fragmentation as captive supply relationships multiply. Remaining intermediary roles concentrate on formulation integration and regulatory dossier management.
- Nutraceutical Firms:Supplement manufacturers prioritize masking of bitter actives in tablet and capsule delivery systems.
- Cosmetic Producers:Oral care and topical applications require non-toxic taste modulation for sensory acceptance.
Food & beverage manufacturers retain volume leadership; nutraceutical firms hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German beverage manufacturers command premium pricing for bitterness blockers, while Indian processors absorb compressed margins on imported sweetener precursors. This asymmetry reflects divergent regulatory sophistication and formulation scale across Atlantic and Asian procurement basins.
United States
Midwest corn-belt processors supply polyol-derived modulator precursors to beverage compounders in Chicago and St. Louis. FDA's expanded GRAS notification requirements are extending novel chemistry launch timelines by 18-24 months. DSM-Firmenich operates integrated biotechnology platforms in the region, sustaining captive yeast-derived sweetener output for direct procurement relationships.
Germany
Clean-label mandates from EFSA are accelerating bitterness blocker trials across beverage manufacturing facilities in Bavaria and North Rhine-Westphalia. The EU Green Deal's Farm to Fork strategy is tightening permissible additive thresholds, mandating reformulation across existing portfolios. Givaudan anchors European demand through specialized bitterness blocker portfolios for reduced-sugar confectionery applications.
Netherlands
High-speed beverage lines in Rotterdam and Amsterdam are retrofitting liquid dosing systems to enable precision modulator delivery. EFSA's novel food ingredient assessments are scrutinizing receptor-targeting claims that border on therapeutic indication territory. Precision fermentation platforms are expanding output volumes of high-potency sweetness modulators without agricultural feedstock dependency.
India
FSSAI's revised food additive schedules are accelerating local safety reviews for imported bitterness blockers previously excluded from domestic formulation. Mumbai and Ahmedabad processing clusters are absorbing margin compression on sweetener precursors sourced from Midwestern US supply basins. Direct procurement links between modulator suppliers and finished goods manufacturers are displacing traditional flavor house distribution channels.
China
SAMR's evolving food additive classifications are creating compliance friction for imported umami enhancers targeting plant-based protein applications. Yangtze River Delta formulation facilities in Shanghai and Suzhou are multiplying umami enhancer trials as meat alternative production scales. Yeast-derived sweetener biotechnology is rendering obsolete agricultural cultivation dependencies for regional high-potency modulator supply.
Taste Modulators Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in precursor and fermentation feedstock supply. The vendor base compresses toward biotechnology-enabled players with captive regulatory dossier capabilities, while agricultural-derivatives processors defend position through input cost control. Two archetypes dominate: integrated flavor-nutrition conglomerates with end-to-end receptor pharmacology platforms, and specialized modulator houses focused on single-mechanism bitterness or sweetness solutions. Competitive moves concentrate on direct procurement relationship formation and precision fermentation capacity expansion.
Within the integrated platform tier, DSM-Firmenich and Givaudan exemplify archetypes of biotechnology-enabled supply control and specialized European bitterness blocker positioning respectively. Cargill Incorporated represents agricultural-input-anchored competition, extending corn-derived polyol chains into modulator precursor supply. These three occupy positions spanning the technology spectrum from precision fermentation to agricultural extraction, reflecting the market's bifurcated sourcing logic.
| Leading Market Players |
|---|
| DSM-Firmenich |
| Symrise AG |
| Givaudan |
| Sensient Technologies Corporation |
| Cargill Incorporated |
| International Flavors & Fragrances Inc. |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Kerry Group plc |
| Others |
Cost & Logistics Intelligence
Rotterdam's precision fermentation capacity expansion is compressing price premiums for yeast-derived sweetness modulators while elevating technical barriers for agricultural-extraction competitors downstream.
Pricing Analysis
The customization-premium spread between configured-to-order bitterness blockers and standard sweetener platforms spans roughly three performance tiers. Contract-based long-term offtake dominates procurement relationships, with price differentiation driven by EFSA certification tier and volume scale. Pricing pressure stems from corn price volatility in Midwestern US supply basins, squeezing polyol-derived precursor margins. Small-scale nutraceutical formulators exhibit highest price sensitivity, while large beverage manufacturers in Germany absorb premiums for dedicated technical service.
Supply Chain Analysis
Contract manufacturing concentration rests with integrated flavor-nutrition conglomerates operating captive biotechnology platforms in the Netherlands, Germany, and United States. Raw material dependencies draw from corn-derived polyol feedstocks, precision fermentation yeast strains, and T2R receptor antagonist precursors. Single-source vulnerability concentrates in agricultural-extraction supply basins exposed to climate volatility. Distribution runs through direct procurement links that fragment traditional flavor house intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in bitterness blocker applications where EFSA's tightening novel food assessments create formulation expertise niches for specialized suppliers.
For Market Incumbents: Insulate receptor pharmacology capabilities through backward integration into precision fermentation capacity in Rotterdam and Amsterdam clusters. Patent thickets around T1R2/T1R3 heterodimer modulation mechanisms defend against emerging biotech entrants with CRISPR-enabled strain development. Certification investment in EFSA's expanded safety dossier requirements preserves European market access timelines. For New Entrants and Emerging Players: India's underpenetration in umami enhancer applications offers white-space expansion as FSSAI accelerates local safety reviews for imported receptor-targeting compounds. Plant-based protein trials in Mumbai and Ahmedabad processing clusters represent the most penetrable demand segment. Technical partnership with German beverage manufacturers seeking bitterness blocker alternatives to incumbent portfolios provides credible go-to-market positioning. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated biotechnology platforms with captive regulatory dossier capabilities and direct procurement relationships. Long-term viability over the coming decade hinges on precision fermentation scale economics displacing agricultural extraction. Acquisition target archetype: specialized modulator houses with single-mechanism bitterness solutions and pending EFSA novel food approvals. Signal to watch: liquid dosing system retrofit rates across high-speed beverage lines as inflection indicator for format-shift demand.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Yeast-derived sweetener output in Rotterdam displaces agricultural feedstock dependency for DSM-Firmenich. |
| Direct Procurement Relationship Formation | German beverage manufacturers bypass flavor house intermediaries to secure dedicated technical service teams. |
| EFSA Novel Food Dossier Investment | Bitterness blocker suppliers restructure clinical endpoints to avoid therapeutic indication territory scrutiny. |
| Liquid Dosing System Retrofit | High-speed beverage lines in Amsterdam enable micro-dosing accuracy for precision modulator delivery. |
| Backward Integration into Corn-Derived Polyols | Cargill extends agricultural input control from Midwestern supply basins into modulator precursor supply. |
Research Approach
A spread of perspectives from formulation scientists at beverage manufacturers, regulatory affairs leads at flavor houses, procurement directors at confectionery producers, and biotechnology platform engineers converged on the working assumptions. Primary interviews combined with secondary validation from EFSA novel food assessments, FDA GRAS notifications, FSSAI additive schedules, and customs trade data. Bottom-up volume modeling and top-down value triangulation anchored projections.
Demand-supply-balance framing shaped the analytical framework across the analysis window, with segmentation dimensions spanning receptor mechanism, physical format, end-use application, and customer archetype. CAGRs derived from intensity-of-use modeling and substitution elasticity estimates for sugar-reduction formulations. Industry-specific inputs included precision fermentation yield curves and EFSA approval timeline distributions.
Practitioners should monitor regulatory dossier rejection rates, corn futures volatility, and liquid dosing system adoption curves for early signals. Forecasts reflect assumptions on biotechnology scale economics and clean-label mandate enforcement trajectories. Quarterly review of EFSA novel food assessment backlogs and FSSAI schedule expansion announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Natural Acerola Cherry Extract Market
Flavorings and Food Additives
Orange Terpenes Market
Flavorings and Food Additives
Italy Food Colorants Market
Flavorings and Food Additives
Tangerine Extract Market
Flavorings and Food Additives
Flavor Compounds Market
Flavorings and Food Additives
Valencene Market
Flavorings and Food Additives
Lecithin Oleoresin Market
Flavorings and Food Additives
Mexico Food Colorants Market
Flavorings and Food Additives
Oryzanol Market
Flavorings and Food Additives
Natural Extracts Market
Flavorings and Food Additives
Bergamot Extract Market
Flavorings and Food Additives
Natural Food Colors and Flavors Market
Flavorings and Food Additives
Flavored Butter and Oils Market
Flavorings and Food Additives
Egypt Food Colorants Market
Flavorings and Food Additives
Middle East and Africa Flavors and Fragrances Market
Flavorings and Food Additives
Chicory Products Market